
 Robot Gearboxes Market | 2026-2036
Robot Gearboxes Market Size, Share, and Industry Trends Forecast 2026-2036
Robot Gearboxes Market Insights
Japanese precision gear manufacturers is expanding harmonic drive output to serve surging cobot arm production. Nabtesco Corporation dominates cycloidal reducer supply for heavy-payload industrial robots. Harmonic Drive LLC leverages decades of strain-wave expertise to anchor premium medical robotics positioning. Wittenstein SE differentiates through integrated servo-actuator systems that compress axial length for collaborative applications.
Robot gearboxes transmit torque from servo motors to articulated joints with positioning accuracy below one arc-minute and backlash under one arc-minute in precision grades. These reducers enable repeatable path control in six-axis arms, SCARA systems, and delta robots across factory floors and surgical suites. Harmonic drive units lead in collaborative and medical segments where zero-backlash and compact form factors command margin premiums. Planetary gearbox architectures sustain volume leadership in material handling and automotive welding lines where torque density and cost efficiency outweigh absolute precision. Cycloidal designs are gaining share in autonomous vehicle steering and exoskeleton joints where shock resistance and compact torque multiplication matter.
ISO 9409-1 mechanical interface standards and IEC 61508 functional safety frameworks govern robot joint interchangeability and fail-safe operation in automated cells. CE marking under the EU Machinery Directive and MDR requirements for surgical systems shape product certification pathways and vendor qualification timelines. Stakeholders must monitor how China's GB standards evolution and dual carbon goals recalibrate domestic robot supply chain localization requirements.
Market Dynamics
Precision motion control requirements in surgical robotics and collaborative automation are compressing backlash tolerances below one arc-minute across all gearbox architectures, forcing manufacturers to recalibrate strain-wave and cycloidal production lines.
Growth Catalysts
- EU Machinery Directive CE marking:Mandatory functional safety compliance under IEC 61508 frameworks is compelling automotive OEMs to source certified high-precision reducers for welding and assembly cells.
- Harmonic drive technology:Zero-backlash strain-wave architectures are displacing planetary systems in medical robotics where sub-millimeter positioning accuracy commands premium placement.
- South Korea robot density leadership:Manufacturing automation intensity per employee exceeds global benchmarks, sustaining concentrated demand for compact torque-dense joint actuators.
Market Restraints
- Specialized alloy input volatility:High-grade bearing steel and specialty alloys face price instability from concentrated smelter capacity in East Asian supply chains.
- Japanese cycloidal reducer concentration:Nabtesco Corporation's dominance in heavy-payload industrial segments creates single-source vulnerability for six-axis arm manufacturers.
- Strain-wave fatigue limitations:Harmonic drive flexspline durability constraints restrict deployment in high-cycle material handling applications exceeding twenty million annual rotations.
Strategic Opportunities
- India manufacturing automation underinvestment:Robot density per industrial worker remains below ten units, creating whitespace for cost-optimized planetary gearbox penetration in automotive tier-one suppliers.
- Exoskeleton joint actuation:Cycloidal architectures with shock-resistant torque multiplication are capturing placement in rehabilitation and logistics augmentation systems.
- China GB standards localization:Evolving national robot safety protocols and dual carbon goals are redirecting foreign joint-venture sourcing toward domestic-certified drivetrain producers.
Industry Challenges
- Functional safety engineer scarcity:IEC 61508 SIL certification expertise remains concentrated in German and Japanese engineering centers, extending qualification timelines for new market entrants.
- ISO 9409-1 mechanical interface compliance:Interchangeability testing for multi-vendor robot joint procurement demands capital-intensive metrology infrastructure and third-party validation cycles.
- Legacy servo motor integration:Retrofitting precision reducers into existing automation cells requires custom adapter engineering that fragments production economics for small-batch orders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robot Gearboxes Market |
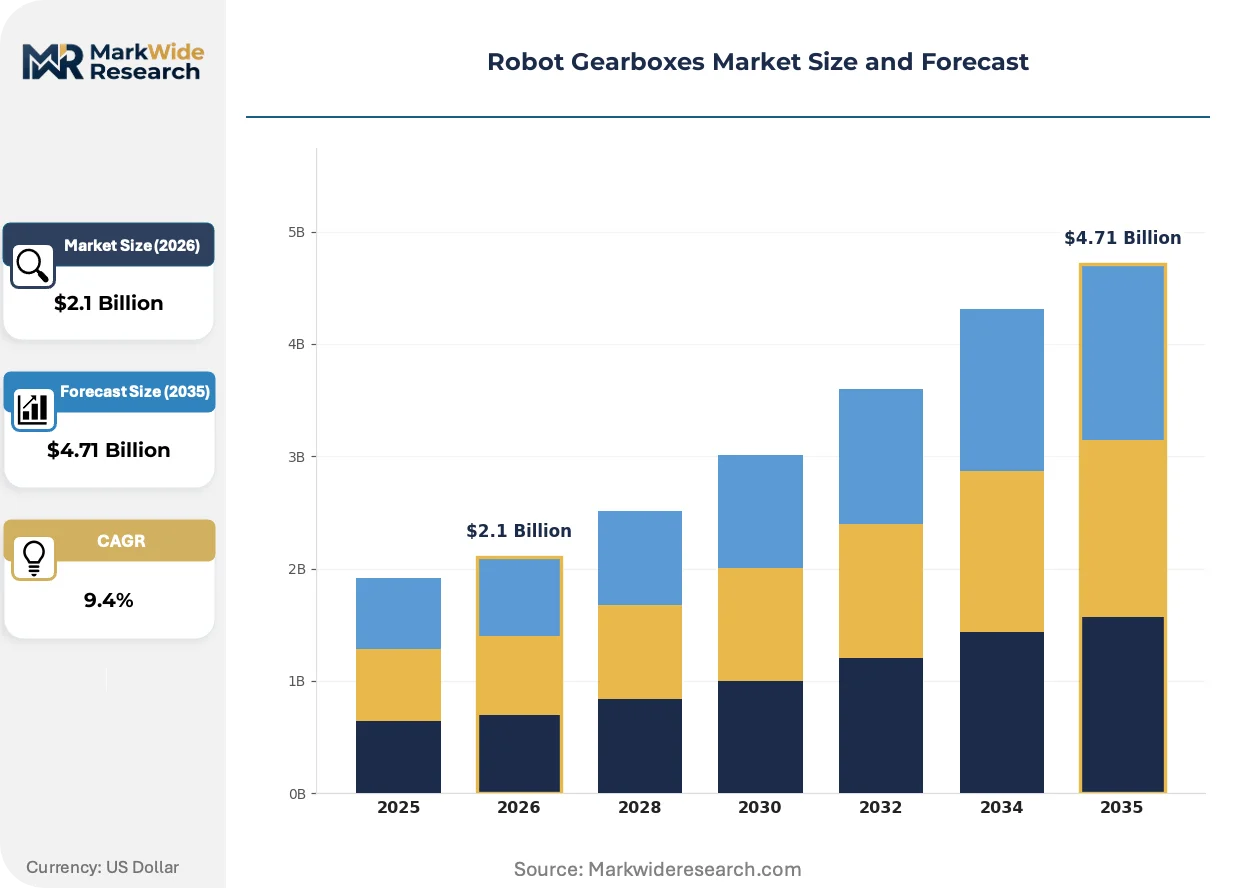
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.71 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Harmonic Drive, Planetary Gearbox, Cycloidal Gearbox, Servo Gearbox Technology: Electric, Hydraulic, Pneumatic, Mechanical Application: Industrial Automation, Medical Robotics, Autonomous Vehicles, Service Robots End User: Manufacturing, Healthcare, Defense, Entertainment |
| Companies Covered | Harmonic Drive LLC, Nabtesco Corporation, Sumitomo Heavy Industries Ltd., Wittenstein SE, Neugart GmbH, Spinea s.r.o., Nidec-Shimpo Corporation, SEJINIGB Co. Ltd., Leaderdrive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robot Gearboxes Market Trends and Innovations
Advanced manufacturing techniques and regulatory recalibration are compressing development cycles for precision motion components while expanding addressable applications beyond traditional factory automation.
Integrated servo-actuator architectures combining harmonic reducers with frameless torque motors are converging with collaborative robot arm designs. Medical device manufacturers in Switzerland and Germany are adopting these compact joint modules for surgical positioning systems. The structural consequence is collapsing axial length requirements that previously demanded multi-component assemblies.
Japan's METI has accelerated JIS standards harmonization with ISO 9409-1 mechanical interface specifications for robot joint interchangeability. Domestic robot OEMs must now certify reducer-motor assemblies through designated testing institutes before commercial deployment. Surgical system builders are responding by pre-qualifying dual-source reducer suppliers to compress MDR compliance timelines.
After-sales service unbundling is fragmenting traditional gearbox procurement patterns. Automotive assembly buyers in Germany are separating reducer hardware purchases from predictive maintenance contracts, forcing suppliers to price lubrication monitoring and vibration analytics as standalone offerings. This disaggregation is most pronounced in high-volume welding line retrofits where uptime guarantees now carry independent pricing.
Robot Gearboxes Market Segmentation
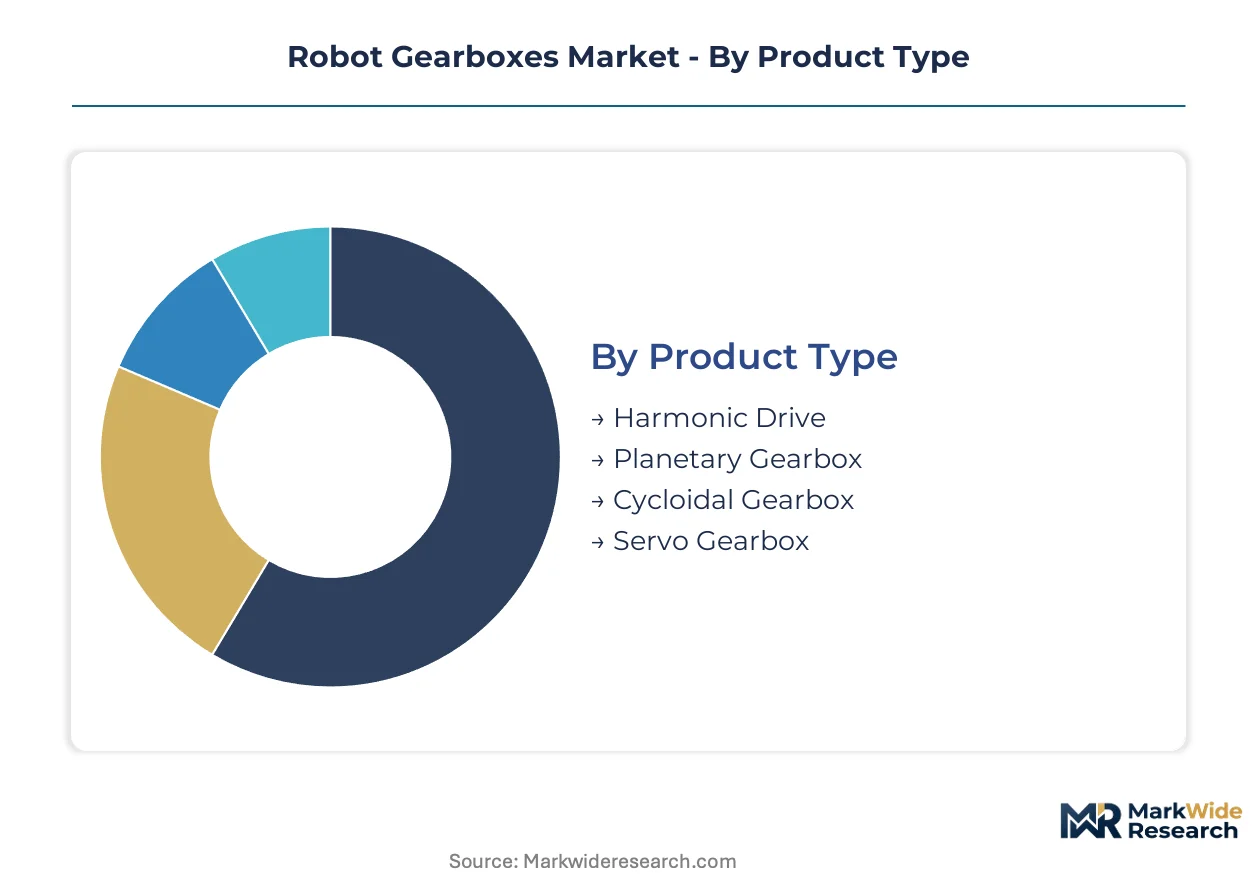
Robot gearbox architectures diverge sharply across torque density, backlash tolerance, and duty cycle requirements. Each specification tier maps to distinct automation environments where precision thresholds and cost constraints dictate technology selection.
Product Type:
Strain-wave and cycloidal torque transmission principles define competitive positioning across payload categories.
- Harmonic Drive:Zero-backlash strain-wave gearing employs a flexible spline meshing with a rigid circular spline to achieve arc-minute positioning accuracy. Demand concentrates in surgical robotics suites across Germany and Switzerland where MDR compliance mandates sub-millimeter repeatability.
- Planetary Gearbox:Sun-planet-ring gear trains deliver torque multiplication through multiple load-sharing contact points. Automotive welding lines in South Korea and Japan deploy these units for six-axis arms where cost efficiency outweighs absolute precision in high-cycle material handling.
- Cycloidal Gearbox:Eccentric cam-driven disc mechanisms provide shock-resistant torque density for autonomous vehicle steering columns and exoskeleton joints.
- Servo Gearbox:Integrated motor-reducer assemblies compress axial length for collaborative robot arms requiring compact joint actuation.
Planetary systems lead on scale; harmonic drives lead on momentum.
Technology:
Actuation energy sources determine response bandwidth, maintenance burden, and environmental compatibility across deployment contexts.
- Electric:Brushless DC and AC servo motors paired with precision reducers dominate factory automation where ISO 9409-1 mechanical interfaces ensure interchangeability. IEC 61508 SIL certification requirements in EU automotive assembly are accelerating certified electric drivetrain procurement.
- Hydraulic:Fluid power transmission sustains heavy-payload industrial segments where stall torque density exceeds electric motor practical limits.
- Pneumatic:Compressed air actuation persists in explosive atmosphere environments and food-grade washdown applications.
- Mechanical:Direct mechanical linkages and spring-based energy storage serve niche rehabilitation and passive exoskeleton implementations.
Electric architectures dominate installed base; hydraulic retains position in extreme torque regimes.
Application:
End-use precision requirements and duty cycle profiles segment demand across divergent certification pathways.
- Industrial Automation:Six-axis arms, SCARA systems, and delta robots on automotive and electronics assembly lines constitute volume demand. CE marking under EU Machinery Directive and Japan's METI-coordinated JIS standards harmonization are recalibrating procurement specifications.
- Medical Robotics:Surgical positioning systems and rehabilitation devices command premium placement for zero-backlash harmonic drives. FDA and Swissmedic clearance timelines favor pre-qualified dual-source reducer suppliers.
- Autonomous Vehicles:Steering and braking actuation systems prioritize cycloidal shock resistance and compact packaging.
- Service Robots:Last-mile delivery and hospitality automation deploy cost-optimized planetary configurations.
Industrial automation leads on scale; medical robotics climbs the fastest on margin expansion.
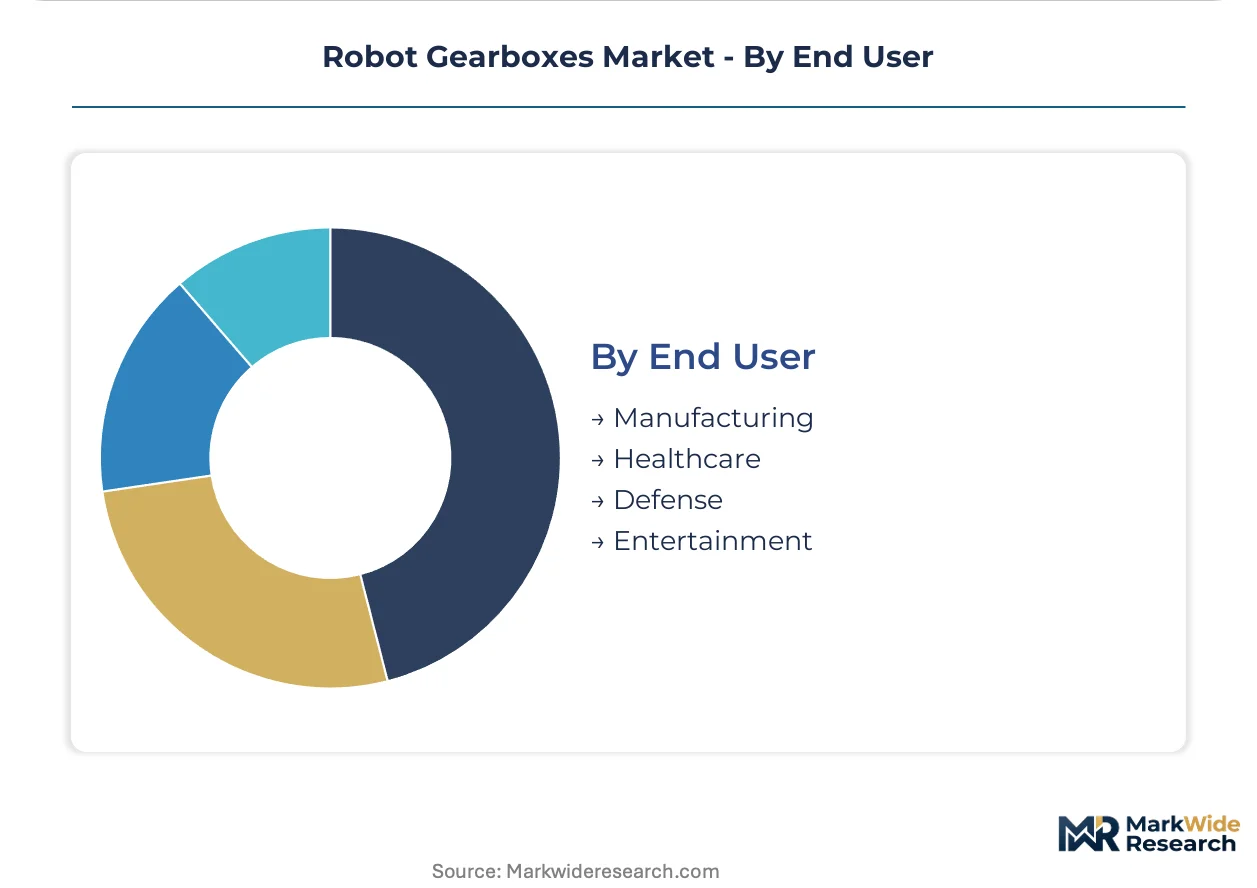
End User:
Capital intensity and regulatory exposure differentiate procurement behavior across buyer categories.
- Manufacturing:Automotive OEMs and tier-one electronics assemblers in Germany, Japan, and South Korea drive concentrated demand for certified high-precision reducers. Robot density per employee in these markets sustains replacement and expansion cycles.
- Healthcare:Hospital systems and surgical device manufacturers prioritize MDR-compliant drivetrains with validated fatigue life documentation.
- Defense:Unmanned ground and aerial platforms require hardened gearboxes with extended temperature operating ranges.
- Entertainment:Theme park animatronics and motion simulation systems demand specialized lubrication and noise suppression.
Manufacturing leads on scale; healthcare leads on specification intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting precision gearbox production toward jurisdictions with streamlined certification pathways. Manufacturers in Japan and Germany absorb higher compliance costs for CE marking and JIS standards alignment, while Chinese producers leverage GB standards evolution to capture domestic robot OEM sourcing.
Germany
Automotive welding lines in Stuttgart and Munich sustain concentrated demand for IEC 61508 SIL-certified cycloidal reducers. CE marking under the EU Machinery Directive compels tier-one suppliers to pre-qualify dual-source drivetrain vendors. The Baden-Württemberg precision engineering cluster hosts metrology infrastructure for ISO 9409-1 interchangeability validation.
Japan
Robot density per manufacturing employee in Aichi and Osaka prefectures exceeds global benchmarks, driving replacement cycles for strain-wave gearboxes. METI-coordinated JIS harmonization with ISO standards mandates third-party reducer-motor assembly certification. Nagoya-based OEMs are expanding cobot arm production lines that compress axial length requirements.
China
Domestic robot manufacturers in Shenzhen and Shanghai are redirecting sourcing toward GB-certified drivetrain producers under dual carbon goals. MIIT industrial robot subsidies accelerate localization of harmonic drive supply chains. The Yangtze River Delta concentration of EV battery assembly lines creates parallel demand for compact joint actuators.
South Korea
Electronics manufacturing in Gyeonggi-do and Incheon sustains premium placement for zero-backlash medical-grade reducers. The country's national industrial safety regulator enforces functional safety compliance mirroring IEC frameworks for automated cells. Busan-Ulsan heavy industry corridors deploy high-torque cycloidal units for shipbuilding automation.
United States
Surgical robotics clusters in Boston and Minneapolis prioritize FDA-cleared drivetrains with validated fatigue documentation. OSHA workplace safety directives for collaborative automation are accelerating certified reducer procurement in automotive assembly. Michigan-based tier-one suppliers are retrofitting welding lines with predictive maintenance-enabled gearbox systems.
Robot Gearboxes Market Competitive Landscape
Japanese producers anchor the precision-tier supply base; German specialists hold the integrated servo-actuator segment. The vendor structure concentrates around three technology archetypes: strain-wave specialists, cycloidal torque-dense manufacturers, and planetary cost-optimized fabricators. Strategic moves center on backward integration into specialty alloy sourcing and geographic expansion through joint ventures in Chinese industrial zones.
Within the strain-wave archetype, Harmonic Drive LLC and Nabtesco Corporation exemplify premium positioning through decades of accumulated positioning accuracy expertise. Wittenstein SE occupies a position among German integrated system architects that compress axial length for collaborative applications. Sumitomo Heavy Industries Ltd. represents the diversified industrial conglomerate model with cross-sector gearbox deployment capabilities. SEJINIGB Co. Ltd. and Leaderdrive exemplify Asia-based challengers competing on cost-optimized planetary configurations for high-volume material handling.
| Leading Market Players |
|---|
| Harmonic Drive LLC |
| Nabtesco Corporation |
| Sumitomo Heavy Industries Ltd. |
| Wittenstein SE |
| Neugart GmbH |
| Spinea s.r.o. |
| Nidec-Shimpo Corporation |
| SEJINIGB Co. Ltd. |
| Leaderdrive |
| Others |
Pricing and Supply Chain Analysis
Automotive OEM consolidation around IEC 61508 SIL-certified drivetrains is compressing procurement timelines and forcing gearbox suppliers to absorb certification costs upfront, reshaping margin structures across premium and standard tiers. This specification tightening cascades through supplier qualification processes, amplifying pricing power for pre-certified Japanese and German producers while squeezing second-tier planetary gearbox fabricators.
Pricing Analysis
Distributor margins for precision reducers typically run 12-18% in European automotive channels, with direct-to-OEM contracts commanding steeper volume discounts for six-axis arm manufacturers. Pricing stratifies across MDR-compliant medical grades, CE-marked industrial tiers, and uncertified economy configurations for material handling. Cost compression in standard planetary segments is intensifying because Chinese domestic producers are undercutting Japanese incumbents on automotive welding line contracts. Tier-one electronics assemblers in South Korea exhibit highest price sensitivity, while Swiss surgical device manufacturers accept substantial premiums for validated fatigue documentation.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Nagoya, and Shanghai orchestrate hub-and-spoke patterns for precision reducer fulfillment, with Stuttgart handling EU automotive certification logistics and Nagoya serving medical robotics clusters. Manufacturing concentrates in Japan, Germany, and China, with Aichi prefecture hosting strain-wave flexspline production and Baden-Württemberg anchoring cycloidal reducer assembly. High-grade bearing steel draws from concentrated East Asian smelter capacity, creating single-source vulnerability for specialty alloy inputs. Distribution runs through authorized distributor networks for certified tiers, while economy planetary units flow direct from Shenzhen fabricators to Indian automotive tier-one suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in robot gearboxes rests on medical-grade certification premiums and backward integration into specialty alloy sourcing that captures alloy volatility upside. The cost-down driver is Chinese domestic competition forcing efficiency gains in planetary production lines.
For Market Incumbents: Anticipate strain-wave fatigue limitations in high-cycle material handling by accelerating cycloidal architecture R&D for twenty-million-rotation applications. Nabtesco Corporation's dominance creates single-source vulnerability that automotive OEMs will diversify away from; preempt this defection with dual-source joint venture structures in Chinese industrial zones. Certification investment in MDR-compliant medical tiers is the defensive lever that preserves margin premiums against Chinese planetary undercutting. For New Entrants and Emerging Players: Launch via direct OEM partnerships in India's underpenetrated manufacturing automation segment, where robot density per industrial worker remains below ten units and cost-optimized planetary configurations face limited incumbent saturation. Target automotive tier-one suppliers in Pune and Chennai with GB-certified drivetrains that satisfy evolving localization requirements under China's MIIT subsidies. The most penetrable white-space is exoskeleton joint actuation, where shock-resistant cycloidal demand outpaces established supplier capacity. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated servo-actuator specialists that compress axial length for collaborative applications, as this technology converges with cobot arm production expansion in Japan and Germany. Long-term viability favors vendors with captive specialty alloy sourcing and dual certification pathways across CE marking and FDA clearance. The signal to watch is JIS-ISO harmonization enforcement tightening, which will disqualify uncertified challengers and concentrate procurement among pre-qualified incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Alloys | Captures bearing steel margin and insulates against East Asian smelter concentration risk. |
| MDR Compliance Pre-Qualification | Compresses Swissmedic clearance timelines for surgical robotics positioning systems. |
| Joint Venture in Chinese Industrial Zones | Secures GB standards certification and MIIT subsidy access for domestic robot OEM sourcing. |
| Integrated Servo-Actuator Development | Collapses axial length requirements for collaborative robot arm designs in Aichi prefecture. |
| Predictive Maintenance Service Unbundling | Captures standalone pricing for vibration analytics in German automotive welding line retrofits. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with precision gearbox procurement managers at automotive OEMs, surgical device engineering leads, industrial automation distributors, and aftermarket service heads with secondary validation. Bottom-up triangulation drew from customs trade data for reducer imports, METI production statistics, SEC filings of diversified industrial conglomerates, and ISO 9409-1 certification registries. Top-down cross-checks anchored market sizing against robot density benchmarks from the International Federation of Robotics and EU Machinery Directive compliance databases.
The forecast window anchored historical reference periods to installed base replacement cycles and greenfield automation capex trajectories across the projection horizon. Segmentation modeling spanned gearbox architecture, actuation energy source, end-use precision tier, and regional regulatory cluster. CAGRs derived from elasticity analysis of robot density growth against reducer content per arm, with specific inputs including JIS-ISO harmonization enforcement timelines and Chinese dual carbon localization mandates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt alloy price spikes or accelerated Chinese domestic substitution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Smart Sorting Machine Market
Industrial Automation
Global SCADA Market
Industrial Automation
Latin America HMI Market
Industrial Automation
Cross-Belt Sorters Market
Industrial Automation
Global Intelligent Process Automation Market
Industrial Automation
Industrial Human-Machine Interface Market
Industrial Automation
North America Industrial Automation Market
Industrial Automation
Global Distribution Feeder Automation System Market
Industrial Automation
Modular Automation and Services Market
Industrial Automation
China Factory Automation and Industrial Controls Market
Industrial Automation
Smart Factory Market
Industrial Automation
Smart Handwriting Machine Market
Industrial Automation
Modular High-Bay Solutions Market
Industrial Automation
Forklift-Mounted Computers Market
Industrial Automation
Asia Pacific Manufacturing Execution Systems (MES) Market
Industrial Automation
Material Handling Robotics Market