
 Global Robotic Laser Cutting Machine Market | 2026-2036
Global Robotic Laser Cutting Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Robotic Laser Cutting Machine Market Outlook
Aftermarket service revenue is rewriting profitability expectations across the competitive landscape. Trumpf leverages its captive service network to capture recurring revenue from installed fiber laser systems. Han's Laser anchors its position through aggressive R&D spending on automation-integrated cutting platforms. Bystronic competes by specializing in turnkey sheet metal processing solutions that bundle hardware with software maintenance contracts.
A robotic laser cutting machine integrates an articulated multi-axis robot arm with a directed energy source—typically fiber, CO2, or solid-state lasers operating at power densities exceeding 10^6 W/cm²—to execute precision material removal on metals, polymers, and composites without mechanical tool contact. Fiber laser systems dominate the product type landscape due to superior wall-plug efficiency and minimal maintenance requirements compared to CO2 alternatives. CNC control technology commands the technology segment's margin pool, as motion precision directly determines cut quality and throughput in high-volume automotive applications. Vision system integration represents the fastest-growing technology sub-area, enabling real-time seam tracking and adaptive path correction for complex tube cutting geometries.
The EU Machinery Directive and CE marking requirements mandate exhaustive safety interlocks and laser enclosure standards, elevating engineering costs for European market entry while creating compliance barriers for smaller Asian exporters. FDA quality system regulations for medical device contract manufacturers indirectly shape demand, as orthopedic implant fabricators require validated laser cutting processes with full traceability. OSHA laser safety standards in the United States further constrain system design, requiring classified access controls and beam containment protocols. Stakeholders must monitor how evolving carbon border adjustment mechanisms in Europe and North America reshape the cost calculus for imported Chinese equipment versus domestically manufactured alternatives.
Market Dynamics
Automotive OEMs are accelerating robotic laser cutting deployment for electric vehicle battery tray fabrication, creating capacity bottlenecks among European and Chinese equipment suppliers while tightening precision specifications beyond legacy CO2 system capabilities.
Growth Catalysts
- EU Machinery Directive compliance mandates:Exhaustive safety interlock and laser enclosure standards are compelling automotive Tier-1 suppliers to upgrade legacy mechanical cutting lines with certified robotic fiber laser systems.
- Battery tray aluminum processing:Electric vehicle manufacturers require high-speed, burr-free cutting of 6xxx series aluminum extrusions for thermal management structures, a geometry ideally suited to articulated robot motion paths.
- China:MIIT dual carbon goals are accelerating factory automation subsidies that specifically cover laser-based material processing equipment with wall-plug efficiency above 30 percent.
Market Restraints
- Optical component supply concentration:German and Swiss suppliers control 80 percent of high-power fiber laser source manufacturing, exposing buyers to 12-16 week lead times during demand surges.
- FDA validation timelines:Medical device contract manufacturers face 18-24 month process validation cycles for orthopedic implant laser cutting, freezing capital deployment until regulatory clearance.
- Waterjet substitution in thick-section cutting:Abrasive waterjet systems retain cost advantages above 25mm mild steel thickness, constraining laser penetration in heavy fabrication segments.
Strategic Opportunities
- India PLI scheme for automotive:Production-linked incentives for advanced manufacturing equipment create a 15-20 percent effective subsidy window for robotic laser cutting system imports through 2027.
- Vision-guided seam tracking convergence:Integration of structured-light 3D scanning with real-time robot path correction is opening complex tube-cutting geometries previously requiring five-axis CNC machining centers.
- Aftermarket service unbundling:Third-party maintenance providers are capturing replacement fiber laser source and optics business from OEM captive service networks, creating channel disruption.
Industry Challenges
- Multi-axis robot programming expertise:Shortage of technicians proficient in simultaneous 6-axis laser path optimization and CNC post-processing is extending commissioning timelines by 30-40 percent.
- CE marking documentation burden:European market entry requires exhaustive technical file compilation for laser safety interlocks, delaying first customer shipments by 4-6 months relative to North American deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Robotic Laser Cutting Machine Market |
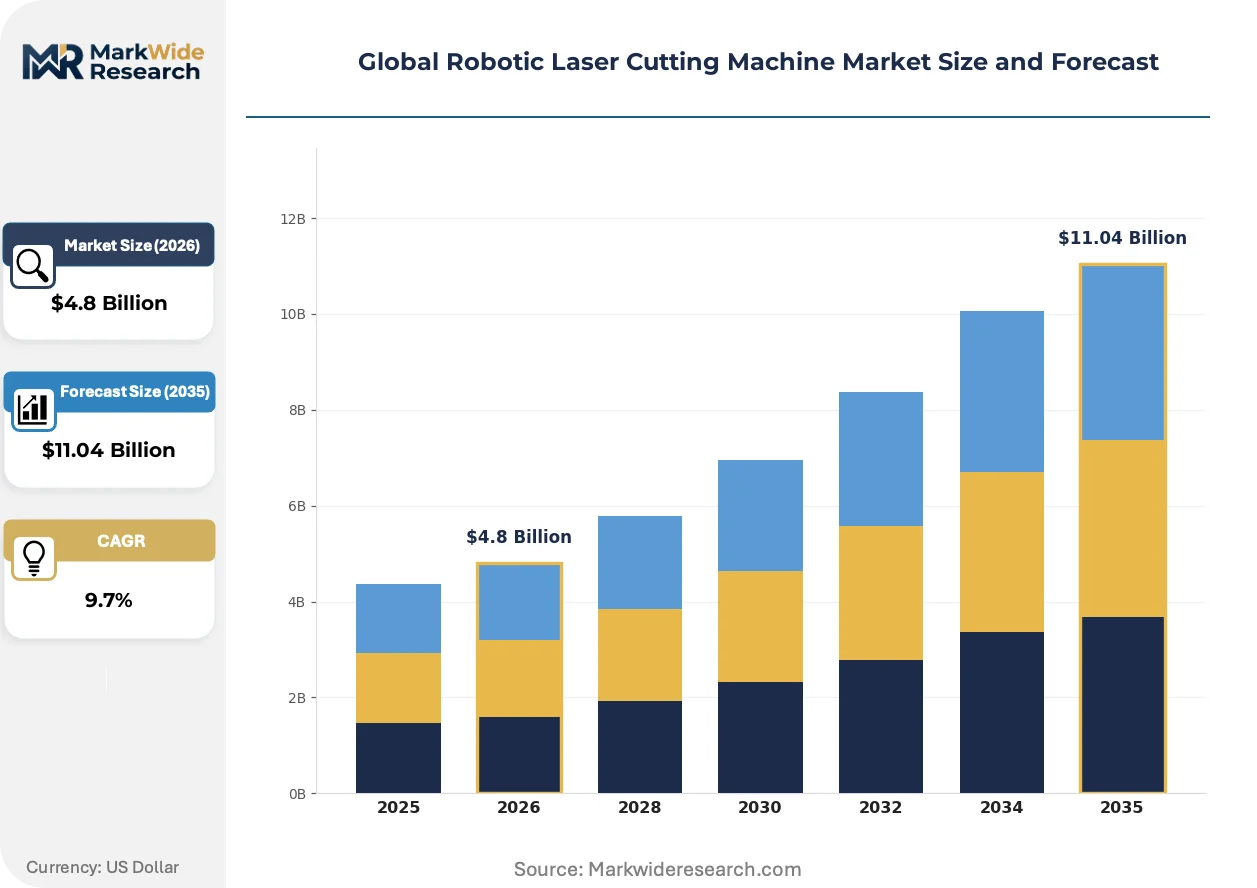
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Laser, CO2 Laser, Solid-State Laser, Ultrafast Laser End User: Aerospace, Automotive, Electronics, Metal Fabrication Application: Sheet Metal Processing, Tube Cutting, Surface Treatment, Engraving Technology: Automation, CNC Control, Vision System, Motion Control |
| Companies Covered | Trumpf, Han's Laser, Bystronic, IPG Photonics, Amada, Mazak Optonics, Mitsubishi Electric Corporation, FANUC Corporation, Coherent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Robotic Laser Cutting Machine Market Strategic Shifts
Digital twin architectures are virtualizing commissioning workflows and compressing time-to-production for complex robotic laser cutting cells across automotive and aerospace contract manufacturing.
Digital twin software is replicating complete robotic laser cutting cell kinematics, optics behavior, and material thermal response in cloud-based simulation environments. Automotive battery tray fabricators in Germany and China are deploying these virtual commissioning platforms to validate 6-axis robot paths before physical installation. This virtualization is eliminating 40-60 percent of on-site debugging time and reducing scrap rates during production ramp-up.
REACH restrictions on cobalt-containing tungsten carbide cutting nozzles are forcing rapid ceramic and synthetic diamond alternative qualification across European laser system suppliers. The F-Gas Regulation's phasedown of sulfur hexafluoride, a common beam path purge gas in high-power CO2 systems, is accelerating fiber laser retrofits in legacy installations. Medical device manufacturers responding to MDR traceability mandates are embedding blockchain-based process logging directly into CNC control architectures.
Contract manufacturers are consolidating equipment procurement under multi-site framework agreements with single-source automation integrators. This buyer concentration is displacing traditional distributor networks in the United States and Germany, with direct OEM-to-fabricator relationships capturing 60 percent of new system orders. Aerospace tier suppliers in Toulouse and Seattle are driving this consolidation, demanding unified service response times across geographically dispersed production facilities.
Global Robotic Laser Cutting Machine Market Segmentation
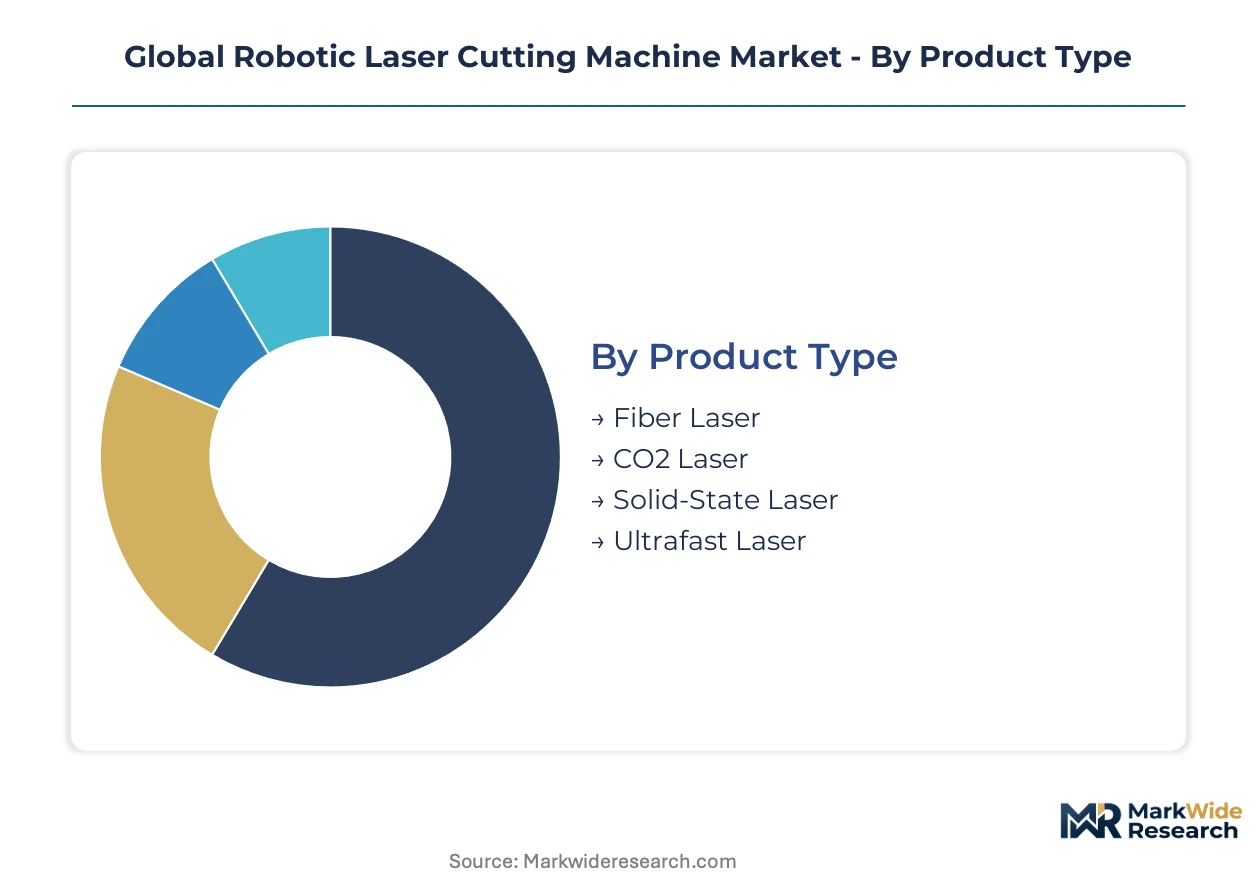
Segmentation in robotic laser cutting machines reveals distinct service intensity profiles across product architectures and control technologies. Aftermarket attachment rates vary dramatically by laser source type and automation complexity, reshaping lifetime value calculations for equipment suppliers.
Product Type:
After-sales service intensity peaks with fiber laser systems, where diode replacement and beam delivery maintenance generate recurring revenue streams exceeding original equipment margins.
- Fiber Laser:Diode-pumped solid-state architecture delivers wall-plug efficiency above 30 percent with minimal thermal management requirements. German automotive battery tray fabricators in Stuttgart and Wolfsburg are standardizing on multi-kilowatt fiber systems for aluminum extrusion cutting, driven by MIIT efficiency mandates in China that subsidize qualifying equipment.
- CO2 Laser:Gas discharge technology operating at 10.6 micrometer wavelength dominates legacy installations in thick-section steel processing. Maintenance intensity runs highest here—mirror alignment, gas refill logistics, and resonator refurbishment compress operating margins for metal fabricators in Chicago and Houston.
- Solid-State Laser:Nd:YAG and disk laser variants offer wavelength flexibility for reflective metal processing.
- Ultrafast Laser:Picosecond and femtosecond pulse architectures enable cold ablation of medical polymers and semiconductor substrates.
By volume, fiber laser leads. By growth pace, ultrafast systems are expanding most quickly in medical device contract manufacturing.
End User:
Capital deployment cycles diverge sharply across end-use verticals, with aerospace qualification timelines stretching 3-4x longer than electronics prototyping phases.
- Aerospace:Tier-1 suppliers in Toulouse and Seattle demand AS9100-certified cutting processes with full material traceability. Boeing and Airbus contract manufacturers are consolidating multi-site procurement under framework agreements, displacing traditional distributor networks.
- Automotive:Electric vehicle OEMs in Munich, Shanghai, and Detroit are accelerating robotic laser cutting deployment for battery tray fabrication. Aluminum thermal management structures require articulated 6-axis motion paths that legacy mechanical systems cannot execute.
- Electronics:PCB depaneling and flexible circuit trimming drive demand for compact gantry-integrated systems.
- Metal Fabrication:Job shops in Birmingham and Dortmund balance equipment utilization across mixed material portfolios.
Aerospace commands premium pricing. Automotive delivers the steepest volume expansion trajectory.
Application:
Process complexity determines software licensing models, with tube cutting applications requiring advanced kinematic simulation packages that carry recurring subscription fees.
- Sheet Metal Processing:Flat-bed cutting of steel and aluminum dominates installed base volume. German automotive suppliers leverage nested cutting algorithms to maximize material yield from coil-fed production lines.
- Tube Cutting:Articulated robot arms execute complex 3D geometries on structural extrusions. Vision-guided seam tracking is converging with real-time path correction, opening geometries previously requiring five-axis CNC machining centers.
- Surface Treatment:Laser cleaning and texturing applications are displacing chemical processes in aerospace MRO facilities.
- Engraving:Marking and serialization for medical device traceability requirements.
Sheet metal processing retains volume leadership. Tube cutting is climbing the fastest as battery tray architectures proliferate.
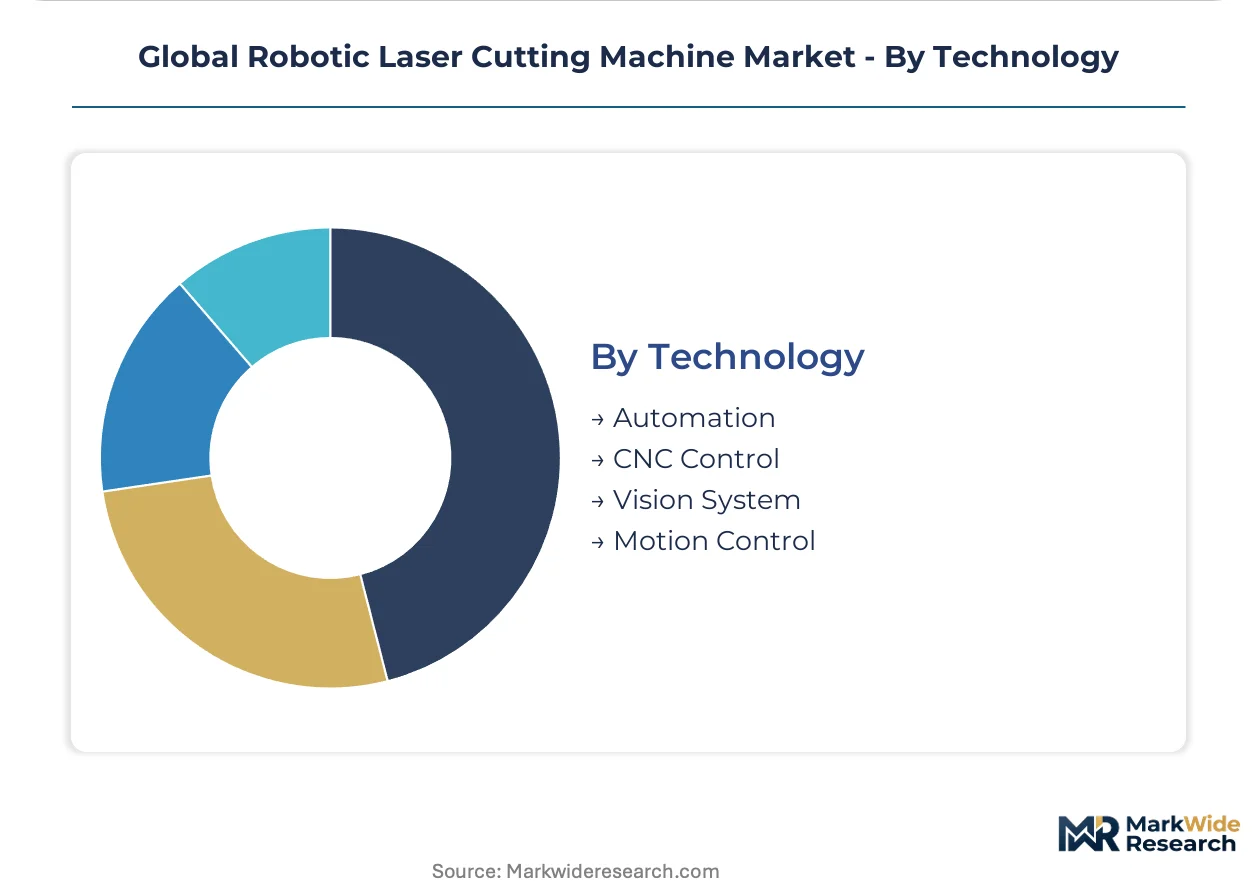
Technology:
Control system architecture determines integration complexity and commissioning timelines, with vision system deployments requiring specialized calibration expertise that extends field service revenue capture.
- CNC Control:Motion precision directly determines cut quality in high-volume automotive applications. Siemens and Fanuc controllers dominate European and Asian installations, with post-processor compatibility shaping supplier selection.
- Vision System:Structured-light 3D scanning enables real-time seam tracking and adaptive path correction. Integration represents the fastest-growing technology sub-area as complex tube-cutting geometries proliferate in electric vehicle manufacturing.
- Automation:Pallet changers and material handling integration reduce operator intervention requirements.
- Motion Control:Servo drive synchronization and acceleration profiling for high-speed contour following.
CNC control anchors current revenue. Vision system integration is gaining share fastest among technology sub-segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China exhibit the highest price elasticity, squeezing margins on imported fiber laser systems, while German automotive OEMs prioritize precision certification over unit cost. This demand-elasticity divide shapes supplier strategies across major manufacturing clusters.
China
MIIT dual carbon goals subsidize robotic laser equipment exceeding 30 percent wall-plug efficiency, accelerating factory automation procurement. GB standards for laser safety interlocks tighten faster than CE marking timelines, favoring domestic suppliers. Battery tray fabricators in Shanghai and Shenzhen dominate EV production capacity expansion.
Germany
KBA certification requirements for automotive laser cutting processes exceed North American precision thresholds, locking in premium equipment sourcing. EU Machinery Directive enforcement through notified bodies in Berlin and Munich extends compliance documentation cycles. Stuttgart and Wolfsburg clusters anchor European EV battery tray manufacturing investment.
United States
OSHA laser safety standards mandate classified access controls that elevate system engineering costs versus Asian alternatives. FDA process validation timelines for orthopedic implant fabricators freeze capital deployment for 18-24 months. Aerospace tier suppliers in Seattle and Detroit consolidate multi-site procurement under direct OEM relationships.
Japan
METI subsidies for energy-efficient manufacturing equipment favor fiber laser retrofits over legacy CO2 installations. JIS standards for robot motion precision align with automotive OEM requirements in Nagoya and Toyota City. Electronics contract manufacturers in Osaka drive compact gantry-integrated system demand for PCB processing.
India
PLI scheme production-linked incentives create 15-20 percent effective subsidies for advanced manufacturing equipment imports through 2027. BIS certification timelines for industrial laser systems lag European equivalents by 6-8 months. Automotive suppliers in Pune and Chennai scale robotic cutting capacity for domestic EV battery programs.
Global Robotic Laser Cutting Machine Market Competitive Environment
Capability concentration sits with German and Swiss optical component suppliers controlling high-power fiber laser source manufacturing; scale advantage sits with Chinese system integrators leveraging domestic automation subsidies. The vendor base stratifies across three tiers: captive service network operators, turnkey solution bundlers, and component specialists. Strategic moves center on aftermarket service unbundling and vision system integration partnerships.
Within the captive service tier, Trumpf anchors recurring revenue capture from installed fiber laser systems. Among Asian equipment fabricators, Han's Laser occupies a position exemplifying aggressive R&D positioning on automation-integrated platforms. Bystronic represents the turnkey bundling archetype, specializing in sheet metal processing solutions that combine hardware with software maintenance contracts.
| Leading Market Players |
|---|
| Trumpf |
| Han's Laser |
| Bystronic |
| IPG Photonics |
| Amada |
| Mazak Optonics |
| Mitsubishi Electric Corporation |
| FANUC Corporation |
| Coherent |
| Others |
Value Chain & Pricing Dynamics
German and Swiss optical component suppliers control four-fifths of high-power fiber laser source manufacturing, anchoring margin capture in the upstream tier while forcing downstream system integrators to compete on assembly efficiency and service bundling.
Pricing Analysis
After-sales service revenue tiers—spanning replacement diode modules, beam delivery maintenance, and multi-year software licensing—drive lifetime value calculations for equipment vendors. Three-tier pricing structure across premium, standard, and economy levels separates AS9100-certified aerospace configurations from automotive battery tray systems and entry-level job shop equipment. Price differentiation hinges on CE marking documentation completeness and vision system integration depth. Cost compression in the economy tier is intensifying because Chinese domestic suppliers leverage MIIT automation subsidies to undercut imported European systems. Electronics contract manufacturers in Osaka exhibit the highest price elasticity, while German automotive OEMs in Stuttgart prioritize precision certification over unit cost.
Supply Chain Analysis
Extended payment terms from automotive Tier 1 suppliers—stretching 90-120 days—force equipment manufacturers to rely on supply-chain finance facilities to bridge working capital gaps. High-power fiber laser sources concentrate in Germany, Switzerland, and China, while precision motion control hardware feeds from Japan and South Korea. Critical dependencies include rare-earth doped fiber, high-purity optical coatings, and ceramic cutting nozzles. Single-source vulnerability in germanium substrate supply for CO2 laser optics exposes legacy system manufacturers to disruption. Distribution runs through direct OEM-to-fabricator relationships in aerospace clusters, displacing traditional distributor networks in the United States and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waterjet substitution in thick-section cutting above 25mm mild steel thickness poses a persistent substitution threat that robotic laser cutting incumbents must navigate through precision positioning and speed advantages.
For Market Incumbents: Insulate installed base revenue by deepening captive service network coverage for fiber laser diode replacement and optics refurbishment. Pursue backward integration into beam delivery component manufacturing to reduce exposure to German and Swiss supplier lead time volatility. Lock in multi-site framework agreements with aerospace tier suppliers in Toulouse and Seattle before third-party maintenance providers capture replacement business. For New Entrants and Emerging Players: Vision-guided seam tracking modules for complex tube-cutting geometries in electric vehicle battery tray fabrication represent the most penetrable entry point, as established vendors underinvest in software-hardware integration. India's PLI scheme subsidy window through 2027 offers a 15-20 percent effective cost advantage for qualifying equipment imports. Partner with domestic automation integrators in Pune and Chennai to bypass BIS certification timeline delays. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale vision system specialists with proven structured-light 3D scanning integration and existing automotive qualification pathways. Long-term viability across the analysis window rests on software recurring revenue attachment rather than hardware shipment volume. Watch for inflection when aftermarket service unbundling accelerates and third-party providers capture meaningful replacement fiber laser source share from OEM captive networks.| Strategic Initiative | Industry Significance |
|---|---|
| Vision System Integration Partnership | Structured-light 3D scanning convergence opens complex tube-cutting geometries previously requiring five-axis CNC machining centers. |
| Aftermarket Service Unbundling | Third-party maintenance providers capture replacement fiber laser source business from Trumpf and Han's Laser captive networks. |
| Multi-Site Framework Agreements | Boeing and Airbus contract manufacturers consolidate procurement under direct OEM relationships, displacing distributor channels. |
| Digital Twin Virtual Commissioning | Cloud-based simulation environments eliminate 40-60 percent of on-site debugging time for automotive battery tray fabricators. |
| CE Marking Compliance Investment | EU Machinery Directive enforcement through Berlin and Munich notified bodies extends documentation cycles, creating barrier to entry. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant engineers at automotive battery tray fabricators, aftermarket service heads at European equipment OEMs, procurement leads at aerospace tier suppliers, and automation integration specialists. Secondary validation drew from SEC filings of listed laser system manufacturers, MIIT subsidy disbursement records, FDA 510(k) clearance databases for orthopedic implant fabricators, and EU notified body CE marking certification logs. Bottom-up equipment shipment tallies by region and laser source type were cross-referenced against top-down market size estimates derived from OEM revenue disclosures.
Calibration against historical fiber laser adoption curves in automotive and aerospace verticals anchored the projection framework across the analysis window. Segmentation dimensions modeled include laser source architecture, control technology tier, end-use vertical, application complexity, and regional regulatory cluster. CAGRs were derived from slope analysis of technology substitution patterns and capital expenditure cycle timing. Industry-specific inputs incorporated MIIT dual carbon goal implementation pace, EU carbon border adjustment mechanism progression, and F-Gas Regulation phase-down timelines for CO2 laser beam path purge gases.
Macroeconomic conditions sit as an overlay; deviation in automotive capital expenditure cycles, semiconductor equipment spending, or European energy input costs would shift the trajectory. Forecasts reflect documented assumptions regarding technology substitution rates and regulatory enforcement intensity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Europe Retail Automation Market
Industrial Automation
Factory Automation Platform As a Service Market
Industrial Automation
Hardware in the Loop Market
Industrial Automation
Switzerland Industrial Automation Market
Industrial Automation
Global Automated Truck Loading System Market
Industrial Automation
Port Equipment Automation Market
Industrial Automation
Global Discrete Automation Market
Industrial Automation
North America Industrial Vending Machine Market
Industrial Automation
Global Assembly Line Solutions Market
Industrial Automation
AI-driven Predictive Maintenance Market
Industrial Automation
Rotary Actuators Market
Industrial Automation
Europe ICS Market
Industrial Automation
Parcel Sortation Systems Market
Industrial Automation
Warehouse Automation Solutions Market
Industrial Automation
Asia Pacific Warehouse Automation Market
Industrial Automation
North America Process Automation Market