
 Europe Factory Automation and Industrial Controls Market | 2026-2036
Europe Factory Automation and Industrial Controls Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Factory Automation and Industrial Controls Market Foresight
CE marking under the EU Machinery Directive is redrawing competitive access across the European supplier base. Siemens AG leverages its deep TIA Portal ecosystem to anchor automation projects across German automotive OEMs. Schneider Electric SE differentiates through EcoStruxure architecture, competing for energy-intensive process industries in France and Benelux.
Factory automation and industrial controls encompass programmable logic controllers, human-machine interfaces, supervisory control and data acquisition systems, and sensor networks that execute real-time process orchestration with millisecond response tolerances. These systems enable continuous production flow, quality consistency, and predictive intervention in discrete and process manufacturing environments. PLC and SCADA deployments represent the mature revenue core, while Industrial IoT and AI technology segments capture the fastest expansion as edge analytics penetrate predictive maintenance workflows. Robotics integration services command premium margins where aerospace and pharmaceutical end users demand validated, audit-ready automation lines.
EMA medical device regulations, REACH chemical compliance, and the EU AI Act collectively elevate documentation, traceability, and safety-validation burdens for control system vendors serving pharmaceutical and food processing clients. The F-Gas Regulation further restricts refrigerant-based cooling in industrial enclosures, pushing thermal management redesigns across PLC and HMI hardware portfolios. Stakeholders must monitor how the CSRD disclosure framework reshapes capital allocation toward verifiable carbon-footprint reduction in automation infrastructure procurement.
Market Dynamics
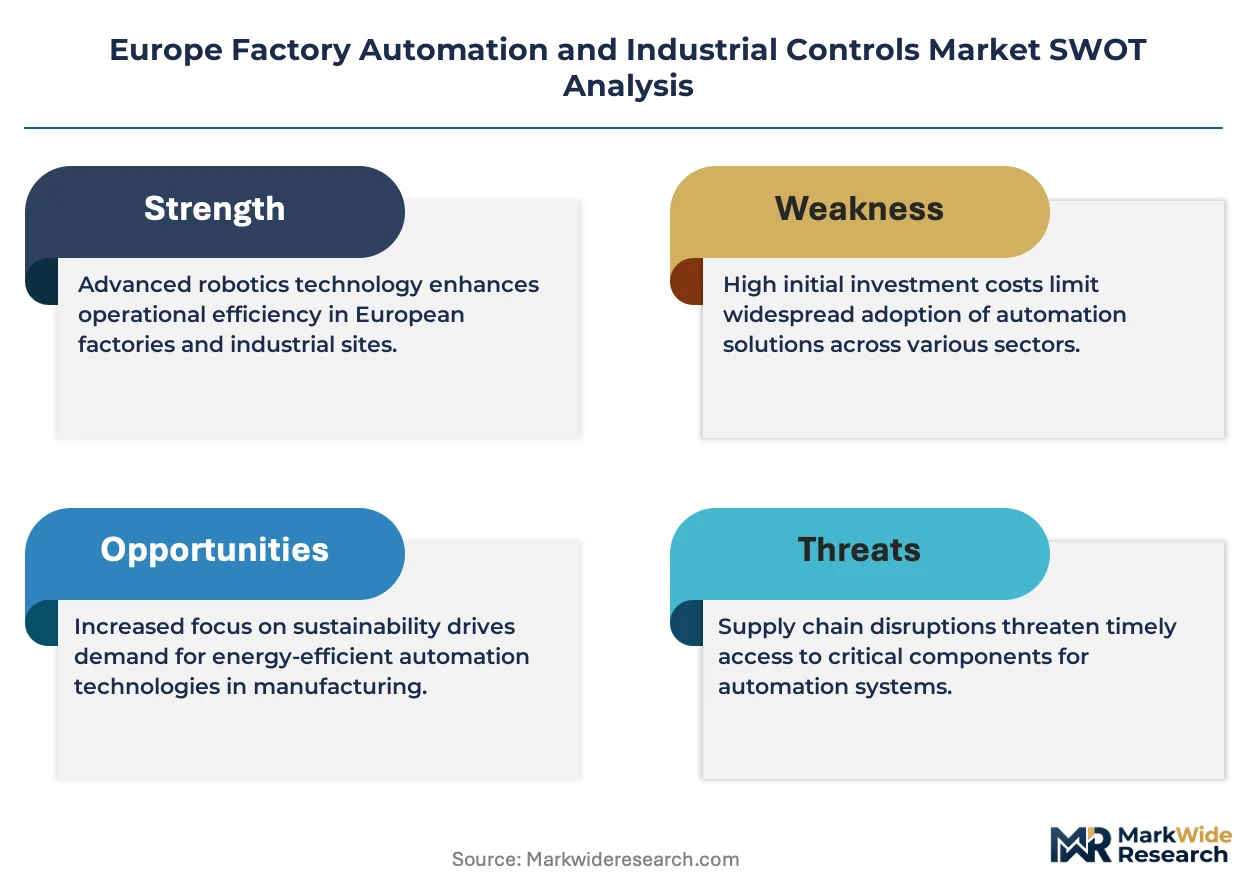
CE marking under the revised EU Machinery Directive is compressing supplier certification timelines while accelerating consolidation among control system vendors serving German automotive and Northern Italian precision manufacturing clusters.
Growth Catalysts
- EU Green Deal energy mandates:Tightening efficiency standards for production equipment are forcing retrofit cycles across France's process industries and Benelux chemical corridors, expanding addressable demand for servo drives and intelligent motor controls.
- Collaborative robotics deployment:Automotive manufacturers in Stuttgart and Wolfsburg are integrating force-limited cobots into final assembly lines, creating pull for safety-certified PLCs and torque-sensing actuator networks.
- EMA medical device traceability:Pharmaceutical packaging lines across Ireland and Switzerland now require serialized batch tracking, driving SCADA upgrades with audit-ready electronic record capabilities.
Market Restraints
- Semiconductor input volatility:Industrial-grade microcontrollers and power electronics face allocation constraints, extending PLC and HMI lead times for mid-tier system integrators serving Eastern European markets.
- REACH chemical compliance costs:Substance-of-very-high-concern restrictions on flame retardants and coatings are forcing enclosure material redesigns, elevating non-recurring engineering for hardware portfolios.
- Legacy fieldbus entrenchment:PROFIBUS and DeviceNet installations across aging German automotive plants create switching friction, delaying Industrial Ethernet adoption despite TSN availability.
Strategic Opportunities
- Poland and Czech Republic manufacturing expansion:Greenfield automotive and electronics assembly investments near Wrocław and Ostrava lack incumbent automation suppliers, creating first-mover positioning for integrated robot-controller vendors.
- CSRD disclosure framework alignment:Mandatory Scope 3 carbon reporting is redirecting procurement budgets toward automation infrastructure with verifiable energy-intensity metrics, favoring vendors with lifecycle assessment tooling.
- Edge-AI and digital twin convergence:Real-time predictive maintenance models deployed on plant-floor edge devices are compressing downtime in aerospace machining cells, opening premium service revenue streams.
Industry Challenges
- Functional safety engineering scarcity:SIL-certified programming expertise for process industries concentrates in Southern Germany and Northern Italy, constraining project velocity for vendors expanding into Nordic pharmaceutical markets.
- EU AI Act validation burdens:Machine learning components in quality inspection systems now require conformity assessment procedures that extend deployment timelines by 6-12 months for food and beverage OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Factory Automation and Industrial Controls Market |
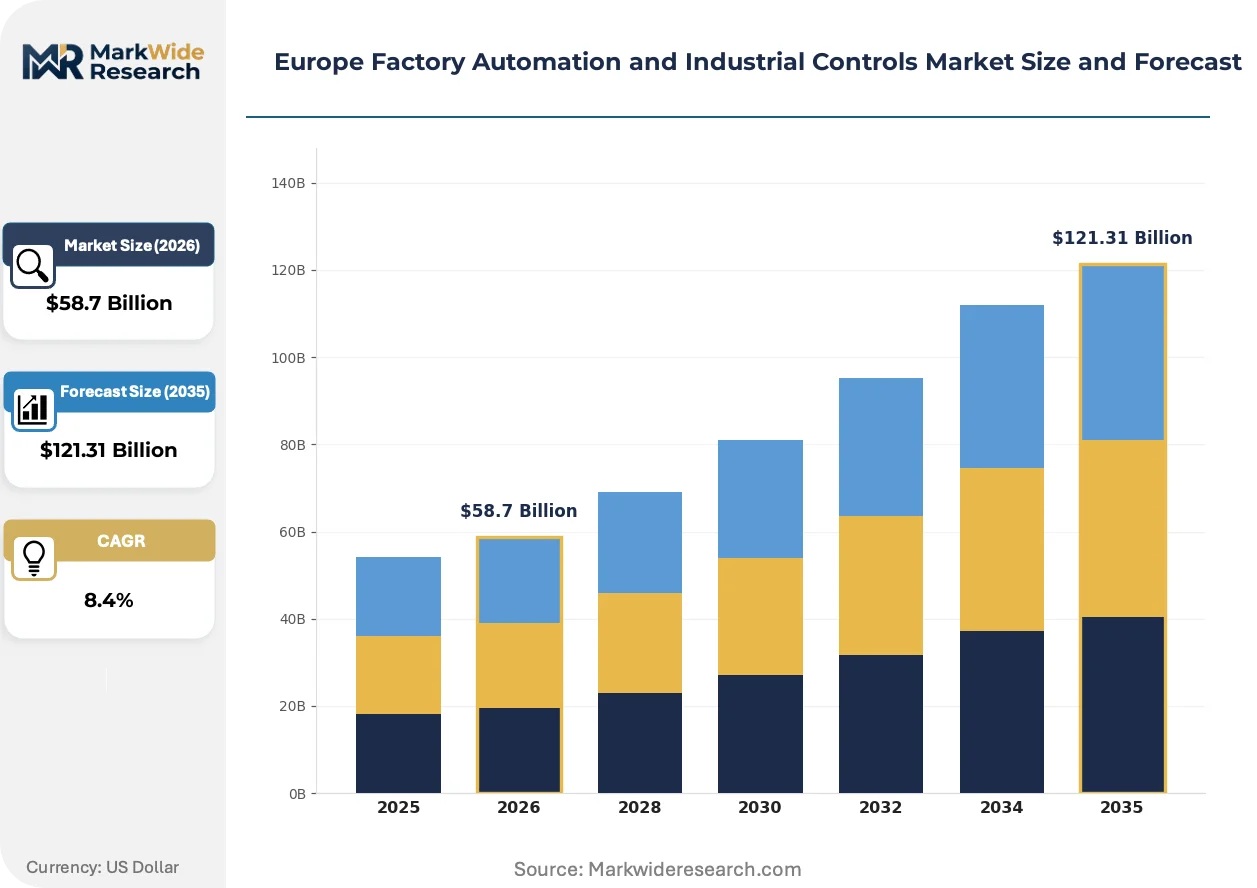
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $121.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PLC, HMI, SCADA, Sensors Technology: Industrial IoT, Cloud Computing, Robotics, AI End User: Manufacturing, Aerospace, Food & Beverage, Pharmaceuticals Service Type: Consulting, Integration, Maintenance, Support |
| Companies Covered | Rockwell Automation Inc, Mitsubishi Electric Corporation, Schneider Electric SE, Omron Corporation, Emerson Electric Company, Siemens AG, Honeywell International Inc, Robert Bosch GmbH, ABB Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Factory Automation and Industrial Controls Market Shifts & Advancements
Edge-native control architectures are displacing centralized SCADA hierarchies while the EU AI Act and CSRD framework reshape how automation vendors document algorithmic decision-making and carbon intensity across their installed base.
Compact safety PLCs with integrated motion control are miniaturizing the traditional rack-and-module architecture that dominated European automotive lines for three decades. Tier-one suppliers in Bavaria and Baden-Württemberg are piloting these unified controllers in battery module assembly, collapsing panel footprint by half while consolidating programming environments. This compression is miniaturizing the physical automation footprint required for high-mix production, enabling reconfigurable cells inside existing plant envelopes without structural expansion.
The F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants is forcing thermal management redesigns across industrial enclosure portfolios. Cooling system vendors must now qualify CO2 and hydrocarbon alternatives, extending hardware recertification cycles and elevating engineering overhead for PLC and HMI manufacturers serving outdoor or foundry applications. French and German control hardware suppliers are absorbing these compliance costs into premium product tiers, segmenting portfolios between climate-controlled and harsh-environment ratings.
Outcome-based service contracts are displacing traditional spare-parts-and-break-fix arrangements in Northern Italy's precision manufacturing cluster. Machine tool OEMs in Milan and Turin now bundle uptime guarantees with automation retrofits, transferring operational risk to system integrators while capturing recurring revenue. This reconfiguration is most visible in aerospace component machining, where AS9100-certified suppliers demand validated availability metrics written into procurement specifications rather than capital equipment purchase orders.
Europe Factory Automation and Industrial Controls Market Segmentation
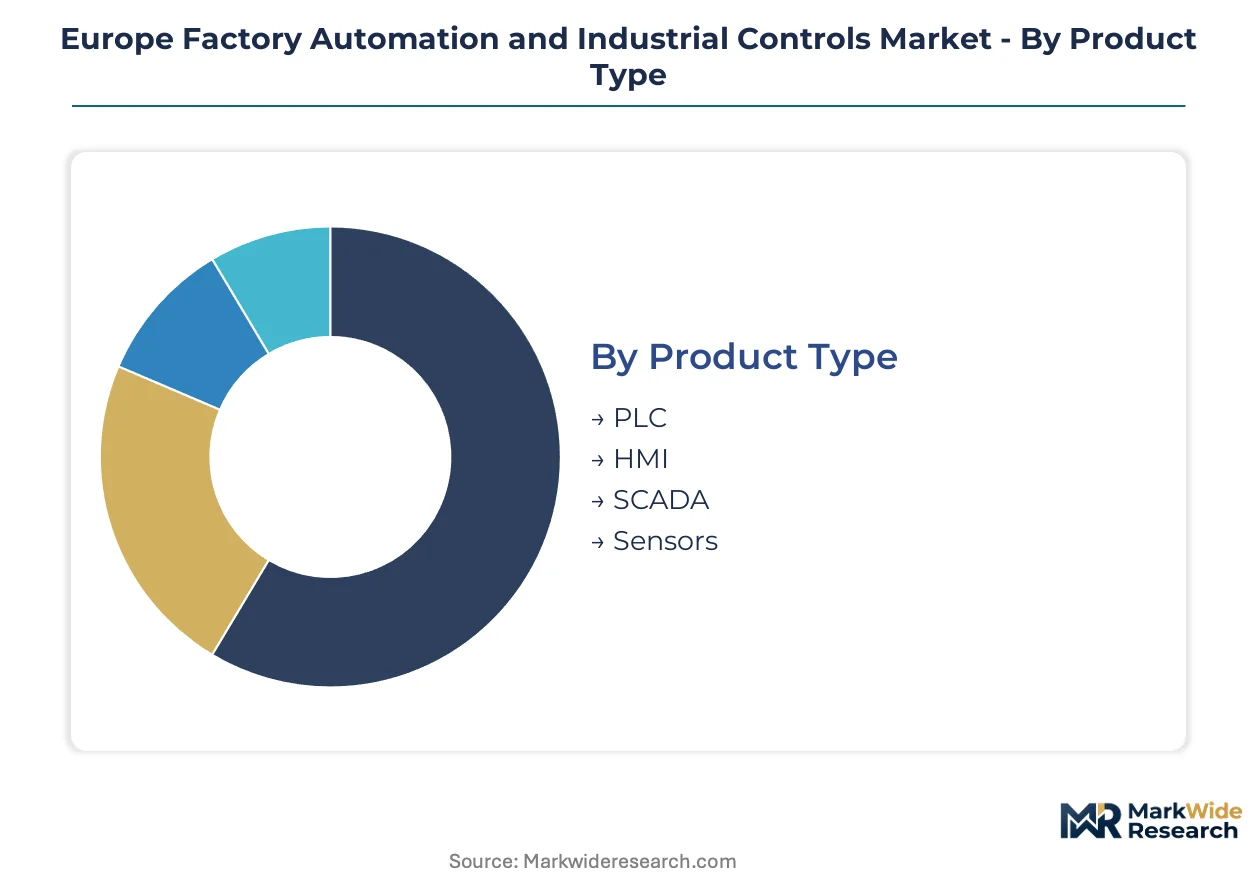
Segmentation in European factory automation reveals how technology maturity, regulatory complexity, and end-use precision requirements fragment purchasing behavior across the value chain. Buyers in Germany's automotive belt prioritize functional safety certification, while Northern Italian precision manufacturers emphasize integration service depth.
Product Type:
Margin pools concentrate in safety-certified controllers and edge-enabled sensor networks where ECHA REACH compliance and CE marking under the Machinery Directive elevate engineering overhead.
- PLC:Programmable logic controllers execute deterministic process control with millisecond scan cycles across discrete manufacturing cells. German automotive OEMs in Stuttgart and Wolfsburg demand SIL-certified safety PLCs for collaborative robotics integration, compressing panel footprints while consolidating programming environments.
- Sensors:Industrial sensor networks capture temperature, pressure, position, and vibration data for real-time feedback loops. Northern Italy's precision manufacturing clusters in Milan and Turin are deploying torque-sensing actuator networks for aerospace component validation, driven by AS9100 traceability mandates.
- HMI:Human-machine interfaces provide operator visualization and alarm management across plant-floor terminals.
- SCADA:Supervisory control and data acquisition systems orchestrate multi-site process visibility for chemical corridors in Benelux.
PLC holds installed capacity. Sensors are rotating up the share rankings.
Technology:
Revenue concentration tracks with deployment complexity, where AI-enabled quality inspection and edge-native architectures command premium pricing against cloud-hosted analytics.
- AI:Machine learning components in vision systems and predictive maintenance models require EU AI Act conformity assessment procedures. Pharmaceutical packaging lines across Ireland now demand validated algorithmic decision-making documentation, extending deployment timelines by 6-12 months but securing audit-ready automation lines.
- Industrial IoT:Edge-native IIoT architectures displace centralized SCADA hierarchies with distributed data processing on plant-floor devices. French process industries under EU Green Deal energy mandates are retrofitting servo drives with intelligent motor controls, capturing verifiable energy-intensity metrics for CSRD disclosure frameworks.
- Cloud Computing:Cloud-hosted manufacturing execution systems enable remote diagnostics and over-the-air updates.
- Robotics:Force-limited collaborative robots integrate with safety-certified control networks for final assembly automation.
Industrial IoT holds installed capacity. AI is climbing the fastest.
End User:
Application-specific validation requirements create tiered pricing structures, with aerospace and pharmaceutical buyers absorbing premium margins for certified, audit-ready automation lines.
- Pharmaceuticals:Drug manufacturing and packaging lines require serialized batch tracking with EMA medical device traceability. Facilities across Switzerland and Ireland are upgrading SCADA systems with electronic record capabilities, driven by MDR compliance and patient safety validation protocols.
- Aerospace:AS9100-certified machining cells demand validated availability metrics and predictive maintenance uptime guarantees. Component suppliers in Baden-Württemberg are bundling outcome-based service contracts with automation retrofits, transferring operational risk to system integrators.
- Manufacturing:Discrete production across automotive and electronics assembly drives volume demand for standard control architectures.
- Food & Beverage:Hygienic design requirements and F-Gas Regulation thermal management constraints shape enclosure specifications.
Manufacturing holds installed capacity. Pharmaceuticals is gaining share fastest.
Service Type:
Procurement patterns diverge between capital equipment buyers and operational expenditure models, with integration and maintenance services capturing recurring revenue streams.
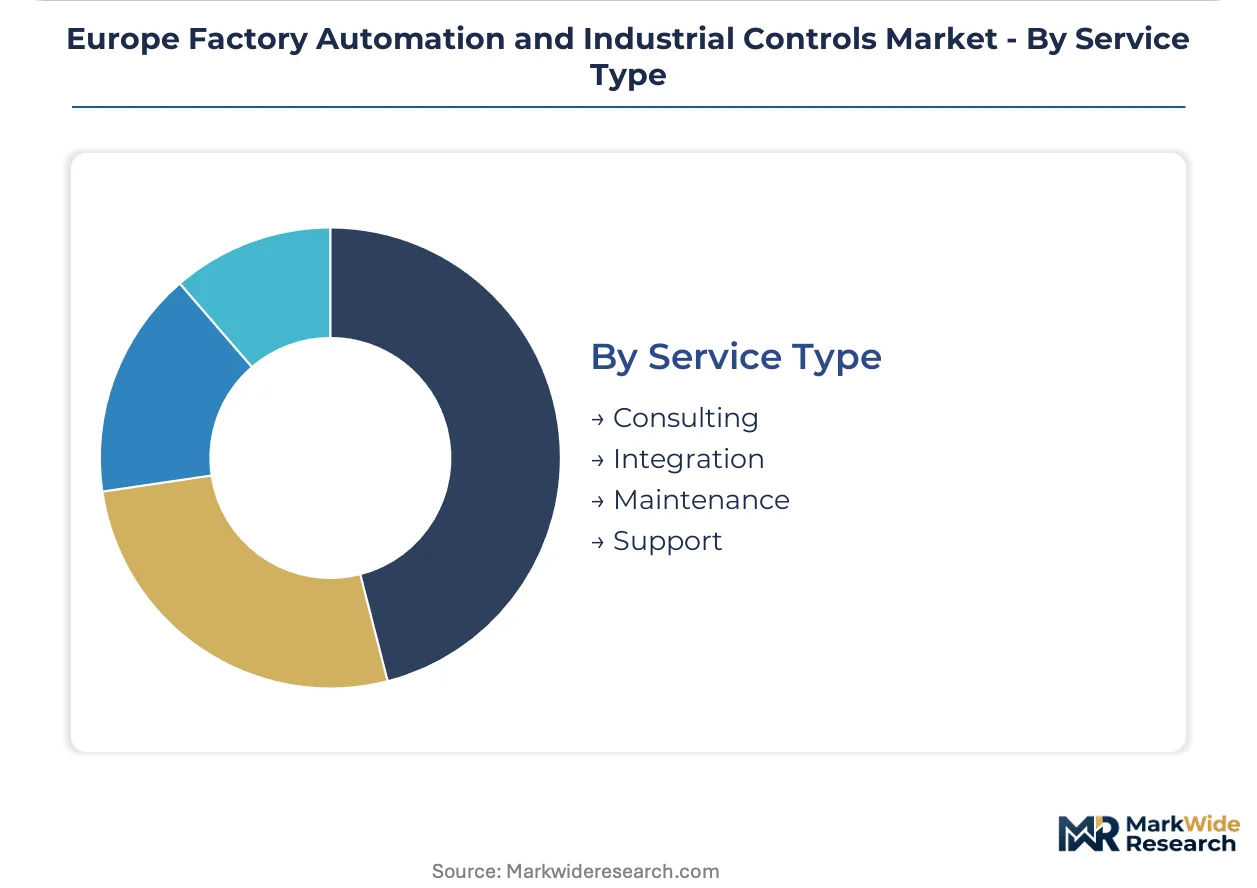
- Integration:Robotics integration services command premium margins where force-limited cobot deployment requires safety-certified PLC programming and torque-sensing network calibration. System integrators serving Poland and Czech Republic greenfield investments near Wrocław and Ostrava lack incumbent suppliers, creating first-mover positioning.
- Maintenance:Outcome-based uptime guarantees are displacing traditional break-fix arrangements in Northern Italy's precision manufacturing cluster. Machine tool OEMs now capture recurring revenue through validated availability metrics written into procurement specifications.
- Consulting:Functional safety engineering expertise for SIL-certified process control concentrates in Southern Germany.
- Support:Remote diagnostics and spare parts logistics face semiconductor input volatility extending lead times.
Maintenance holds installed capacity. Integration is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal energy mandates and Machinery Directive revisions are redirecting capital flows toward retrofit cycles and greenfield automation investments across the continent's manufacturing belt.
Germany
Automotive OEMs in Stuttgart and Wolfsburg are accelerating collaborative robotics deployment for battery module assembly. KBA vehicle safety standards intersect with CE marking requirements under the revised Machinery Directive, compressing supplier certification timelines. The Baden-Württemberg precision manufacturing cluster is piloting compact safety PLCs with integrated motion control.
France
Process industries along the Lyon chemical corridor are retrofitting servo drives with intelligent motor controls to capture verifiable energy-intensity metrics. ANSM pharmaceutical traceability rules align with EMA medical device regulations, elevating documentation burdens for SCADA vendors serving packaging lines. Île-de-France hosts Schneider Electric's EcoStruxure development hub.
Italy
Machine tool OEMs in Milan and Turin are bundling outcome-based uptime guarantees with automation retrofits for aerospace component suppliers. REACH chemical compliance on flame retardants is forcing enclosure material redesigns across PLC portfolios. The Northern Italy precision manufacturing cluster leads Europe in torque-sensing actuator network deployment.
Poland
Greenfield automotive investments near Wrocław lack incumbent automation suppliers, creating first-mover positioning for integrated robot-controller vendors. EU structural funds are channeling capital toward electronics assembly capacity expansion. The Silesian manufacturing corridor is absorbing German supply chain spillover as OEMs diversify production geography.
Switzerland
Pharmaceutical packaging facilities across Basel are upgrading SCADA systems with electronic record capabilities to satisfy Swissmedic and EMA dual compliance. CSRD disclosure frameworks are redirecting procurement budgets toward automation infrastructure with lifecycle assessment tooling. The Swiss precision engineering cluster validates availability metrics for AS9100-certified aerospace machining contracts.
Europe Factory Automation and Industrial Controls Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and integration service breadth. The supplier base concentrates around three tiers: diversified electrical conglomerates with full-stack portfolios, pure-play automation vendors with vertical expertise, and regional system integrators capturing service revenue. Archetypal competitive moves include strategic partnerships for edge-AI capability access and geographic expansion into Central European greenfield markets.
Among Germany-based diversified industrials, Siemens AG and Robert Bosch GmbH exemplify the full-stack archetype spanning hardware through software ecosystems. Schneider Electric SE occupies a position within the French-led energy-management tier, competing for process industry accounts. These three anchors represent divergent strategic postures: ecosystem lock-in through programming environments, component-scale manufacturing efficiency, and energy-intensity optimization architectures.
| Leading Market Players |
|---|
| Rockwell Automation Inc |
| Mitsubishi Electric Corporation |
| Schneider Electric SE |
| Omron Corporation |
| Emerson Electric Company |
| Siemens AG |
| Honeywell International Inc |
| Robert Bosch GmbH |
| ABB Ltd |
| Others |
Supply & Pricing Matrix
Forty-five-to-sixty-day lead times for industrial-grade microcontrollers and power electronics concentrate pricing power with German and Japanese semiconductor distributors serving PLC and HMI manufacturers. Inventory scarcity across these input categories is compressing margins for mid-tier system integrators while elevating premium capture for vendors with strategic stockpile arrangements.
Pricing Analysis
Certification level under the EU Machinery Directive and F-Gas Regulation creates the primary spread between premium and standard tiers. Three-tier pricing structure across SIL-certified safety systems, standard industrial controllers, and economy-grade HMIs dominates procurement contracts. Cost compression in economy-grade enclosures is intensifying because REACH chemical compliance on flame retardants forces material redesigns. Automotive OEMs in Stuttgart and Wolfsburg exhibit lowest price sensitivity due to uptime guarantee requirements, while Polish greenfield investors near Wrocław absorb highest sensitivity as first-time automation buyers.
Supply Chain Analysis
Strategic stockpile preferences among German automotive OEMs contrast with just-in-time inventory models favored by Northern Italian machine tool builders. Taiwan, Germany, and Japan anchor semiconductor wafer and industrial microcontroller supply. The ecosystem draws from rare earth magnet feeds for servo motors, copper busbar stock for power distribution, and specialized aluminum alloys for heat-dissipating enclosures. Single-source vulnerability concentrates in EU-sourced safety-certified PLC firmware. Distribution runs through authorized distributor networks with technical support capabilities rather than commodity electronics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation among German automotive OEMs and Northern Italian aerospace suppliers is shifting negotiation leverage toward volume buyers with multi-site standardization mandates. This buyer-power concentration elevates ecosystem lock-in and outcome-based contracting as defensive imperatives.
For Market Incumbents: Fortify ecosystem stickiness through deeper TIA Portal and EcoStruxure programming environment integration. Backward integration into edge-AI chip design reduces exposure to semiconductor allocation volatility from Taiwan and Japan. Prioritize SIL-certified safety engineering capacity expansion in Southern Germany to capture Nordic pharmaceutical automation demand before functional safety talent scarcity constrains project velocity. For New Entrants and Emerging Players: Post-sales outcome-based uptime guarantee services represent the most penetrable white-space where incumbents under-serve. Target Poland and Czech Republic greenfield automotive corridors near Wrocław and Ostrava with integrated robot-controller bundles lacking incumbent supplier relationships. Lead with CSRD-aligned lifecycle assessment tooling to differentiate against established vendors without carbon-footprint verification capabilities. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electrical conglomerates with under-optimized automation divisions lacking vertical software depth. Long-term viability hinges on edge-native architecture transition and AI Act compliance infrastructure buildout. Monitor EU AI Act conformity assessment timeline extensions as the signal to watch for vendor distress creating acquisition entry points.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Edge-AI Silicon | Captive supply of inference chips reduces Taiwan semiconductor allocation exposure for German PLC vendors. |
| SIL-Certified Safety Engineering Acquisition | Functional safety talent scarcity in Southern Germany constrains Nordic pharmaceutical market expansion velocity. |
| CSRD-Aligned Lifecycle Assessment Tooling | Carbon-footprint verification capabilities redirect procurement budgets from incumbent suppliers lacking disclosure frameworks. |
| Outcome-Based Uptime Guarantee Contracts | Recurring revenue capture transfers operational risk from Northern Italian aerospace buyers to integrators. |
| Poland-Czech Greenfield Distribution Buildout | First-mover positioning near Wrocław and Ostrava automotive investments lacks entrenched automation supplier presence. |
Research Methodology
Cross-validation between primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and system integration specialists anchors the qualitative findings against secondary validation. Regulatory filings with EMA and ECHA, EU customs trade data for industrial controller imports, and Machinery Directive certification databases provide bottom-up triangulation against top-down market sizing.
Sensitivity analysis across technology adoption curves, regulatory enforcement intensity, and semiconductor supply scenarios shapes the analytical framework. Segmentation dimensions span product type, technology maturity, end-use validation requirements, and service model configuration. CAGRs derive from installed base evolution and replacement cycle compression under EU Green Deal mandates, with edge-AI penetration rates and collaborative robotics deployment velocity as industry-specific forecast inputs across the projection horizon.
Underlying assumptions cover REACH chemical compliance timeline adherence and EU AI Act enforcement consistency, with deviation risk concentrated in semiconductor allocation volatility and functional safety engineering supply constraints. Revision becomes warranted when F-Gas Regulation thermal management redesign costs or CSRD disclosure adoption rates cross thresholds altering capital equipment procurement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Geosteering Technology Market
Industrial Automation
Warehousing Automation Equipment Market
Industrial Automation
Latin America Factory Automation and Industrial Controls Market
Industrial Automation
Global Smart Warehousing Market
Industrial Automation
Agricultural Automation Market
Industrial Automation
Digital Industrial Scales Market
Industrial Automation
Latin America Laboratory Automation Market
Industrial Automation
Conveyor Sorting Systems Market
Industrial Automation
Europe Warehouse Automation Systems Market
Industrial Automation
Robotic Paint Booth Market
Industrial Automation
Global Distribution Feeder Automation System Market
Industrial Automation
North America Smart Factory Market
Industrial Automation
AI-driven Predictive Maintenance Market
Industrial Automation
North America Process Automation Market
Industrial Automation
Industrial Automation Products Market
Industrial Automation
Asia-Pacific Programmable Logic Controller Market