
 Motion Control Drive Market | 2026-2036
Motion Control Drive Market Size, Share, and Industry Trends Forecast 2026-2036
Motion Control Drive Market Outlook
Aftermarket service revenue is narrowing as original equipment manufacturers capture lifecycle value through predictive maintenance subscriptions. Siemens AG leverages its digital twin ecosystem to lock in recurring software revenue across installed servo drive bases. Bosch Rexroth anchors its position through backward integration into linear motion components and proprietary drive-integrated safety systems.
Motion control drives are electromechanical power conversion systems that regulate motor torque, velocity, and position through pulse-width modulation at switching frequencies typically between 2-16 kHz, serving primarily to synchronize multi-axis machinery in automated production environments. AC drives and servo drives together command the dominant share of product-type revenue, with servo drives capturing premium pricing in robotics applications where positioning accuracy below one arc-minute is mandatory. Field-oriented control technology is displacing scalar V/Hz methods in high-performance segments, while digital control platforms enable real-time parameter tuning through Ethernet-based fieldbus protocols.
The US Department of Energy enforces minimum efficiency standards under NEMA MG-1 that compel drive-motor system upgrades in industrial facilities. The EU Ecodesign Directive and CE marking requirements for electromagnetic compatibility shape product development roadmaps for vendors seeking European market access. China's GB standards for motor system efficiency and the MIIT's industrial energy conservation mandates are tightening compliance thresholds for imported drive equipment. Stakeholders must weigh regional certification divergence against platform standardization economics when configuring global product portfolios.
Market Dynamics
Field-oriented control architecture is displacing scalar V/Hz methods across precision manufacturing, compressing margins for legacy drive vendors while rewarding real-time digital control platforms. Taiwan's semiconductor fabrication cluster and Germany's automotive corridor are pulling divergent specifications that fragment platform standardization economics.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants is accelerating migration toward energy-efficient AC drive architectures in industrial cooling systems. Food processing facilities in the Netherlands and Denmark are retrofitting compressor drives to meet 2027 compliance thresholds.
- Semiconductor wafer handling:Taiwan and South Korean fabrication facilities are expanding servo drive installations for sub-micron positioning accuracy in EUV lithography stages. This precision requirement is pulling 16 kHz switching frequency demand into mainstream specification sheets.
- Industrial energy conservation mandates:China's MIIT efficiency standards are tightening compliance thresholds for imported drive equipment. Domestic motor system retrofits in Jiangsu and Guangdong provinces are creating replacement volume for variable frequency drives.
Market Restraints
- IGBT and SiC module concentration:Power semiconductor supply is consolidating among Japanese and German foundries, exposing drive manufacturers to 26-week lead time volatility for high-voltage switching components.
- CE marking electromagnetic compatibility:European market access requires extensive EMC testing under Ecodesign Directive frameworks, adding 8-14 months to product launch timelines for non-EU vendors.
- Mechanical transmission substitution:Direct-drive torque motors are eliminating gearbox-servo combinations in wind turbine pitch systems and rotary indexing tables, compressing addressable servo drive unit volume.
Strategic Opportunities
- India PLI scheme for manufacturing:Production-linked incentives for advanced manufacturing equipment are attracting drive system assembly investments in Tamil Nadu and Gujarat industrial corridors.
- Digital twin convergence:Physics-based simulation platforms are merging with drive parameter tuning tools, enabling predictive commissioning that reduces startup engineering hours by half.
- Agricultural automation:Autonomous tractor and harvester OEMs in Brazil and Australia are specifying IP67-rated servo drives for precision seeding and chemical application systems.
Industry Challenges
- Power electronics engineering scarcity:Specialized talent for magnetics design and thermal management is concentrating among German and Japanese industrial conglomerates, constraining mid-tier vendor R&D throughput.
- Legacy fieldbus integration:Manufacturing facilities in the US Rust Belt and European Mittelstand retain DeviceNet and Profibus infrastructure, forcing dual-protocol development costs for drive vendors seeking replacement sales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motion Control Drive Market |
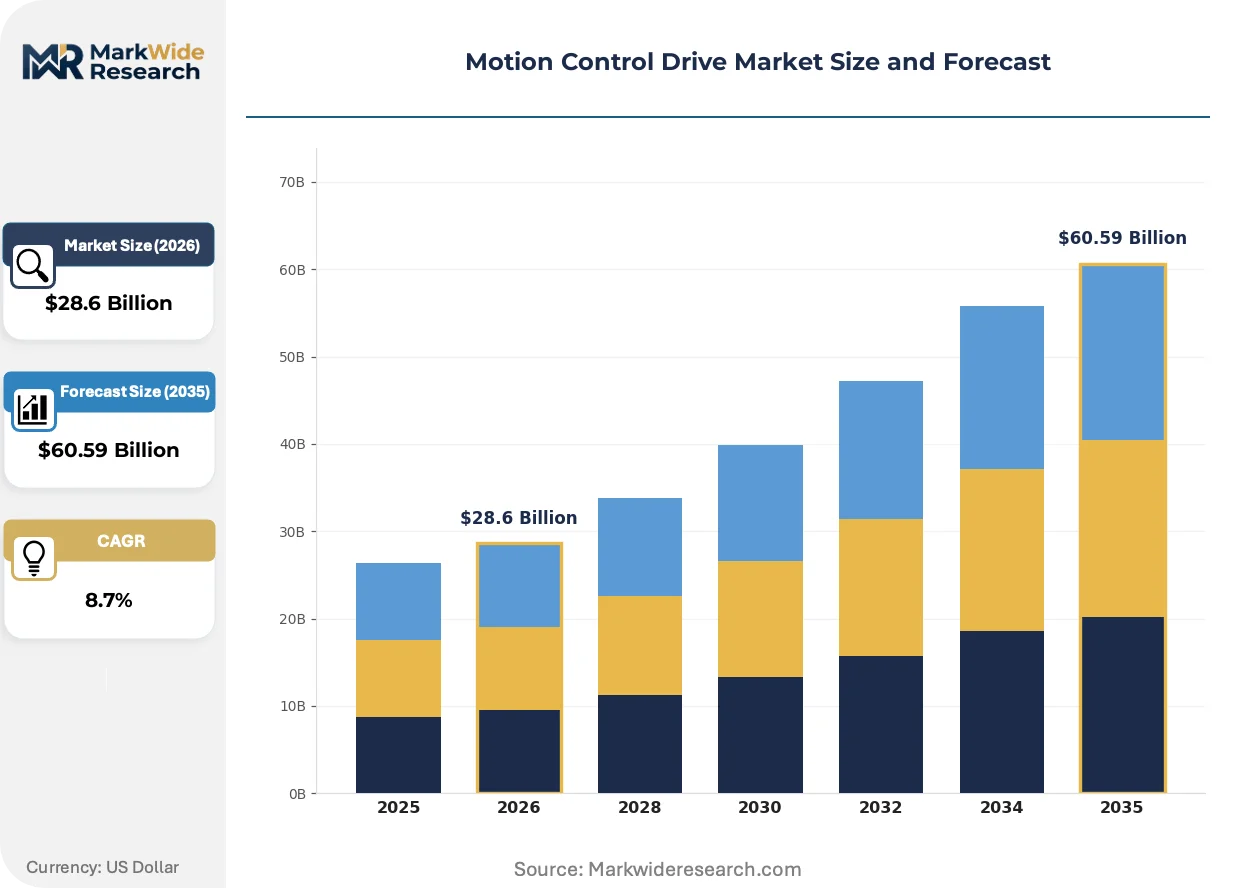
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Drives, DC Drives, Servo Drives, Stepper Drives Technology: Digital Control, Analog Control, Adaptive Control, Field-Oriented Control Application: Robotics, Industrial Automation, Conveying Systems, CNC Machines End User: Aerospace, Automotive, Manufacturing, Packaging |
| Companies Covered | ABB Ltd., Rockwell Automation, Siemens AG, Delta Electronics, Bosch Rexroth, Yaskawa Electric Corporation, Schneider Electric, FANUC Corporation, Mitsubishi Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motion Control Drive Market Strategic Shifts
Ethernet-based real-time control protocols are collapsing the boundary between drive hardware and edge computing, enabling closed-loop adjustments at millisecond latency. This convergence is redrawing competitive advantage around software-defined motion architectures rather than power stage specifications alone.
Artificial intelligence-based vibration analysis is digitizing predictive maintenance workflows for servo drive-motor combinations. Automotive stamping press operators in Stuttgart and Wolfsburg are deploying edge-trained anomaly detection models that compress unplanned downtime windows. The technology is digitizing service revenue capture, shifting value from replacement hardware to subscription diagnostics.
The EU F-Gas Regulation and accompanying Ecodesign Directive are mandating efficiency testing under standardized load profiles for drive-motor combinations above 0.12 kW. Industrial refrigeration OEMs are redesigning compressor controls to meet 2027 refrigerant phase-down timelines. German pump and fan manufacturers are responding with permanent magnet motor-drive packages that exceed IE5 efficiency thresholds.
Machine builders are consolidating vendor relationships around full-stack motion suppliers capable of delivering linear actuators, gearboxes, and safety-certified drives from single source. This pattern concentrates procurement authority among technical buyers in packaging machinery and electronics assembly equipment. The shift is most visible in Taiwan's precision manufacturing ecosystem, where system integrators are reducing qualified vendor lists from twelve to three.
Motion Control Drive Market Segmentation
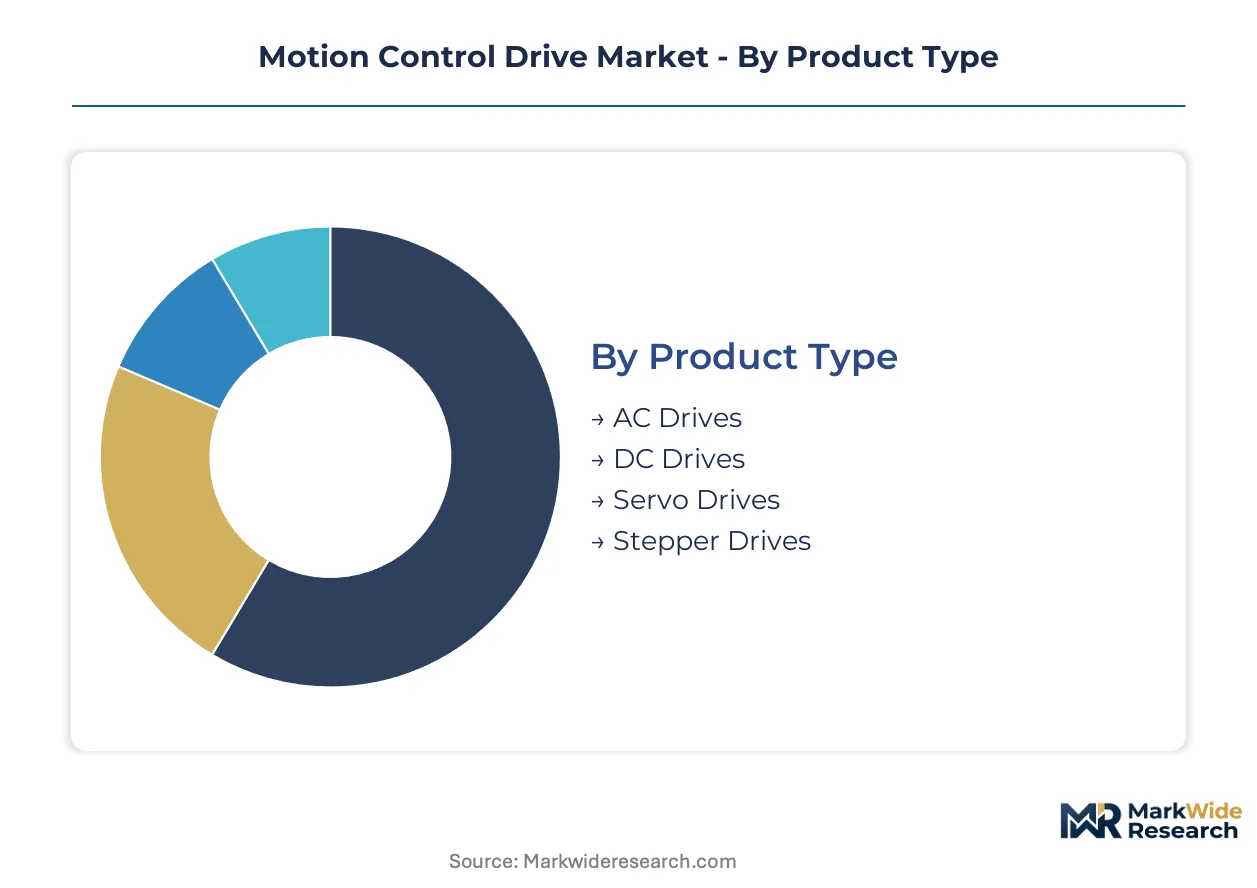
Motion control drive segmentation reflects divergent service intensity across product architectures. AC drives generate predictable aftermarket revenue through fan and pump retrofits, while servo drives demand specialized commissioning support for multi-axis synchronization.
Product Type:
After-sales-service intensity varies sharply across power conversion architectures, with high-frequency switching platforms requiring predictive maintenance subscriptions.
- AC Drives:Variable frequency drives modulate motor speed through pulse-width modulation at 2-8 kHz switching frequencies. Demand concentrates in Netherlands and Danish food processing facilities retrofitting compressor systems to meet EU F-Gas Regulation phase-down timelines.
- Servo Drives:Closed-loop systems execute sub-arc-minute positioning through 16 kHz switching and real-time feedback. Taiwan semiconductor fabrication clusters and South Korean EUV lithography stages are pulling premium specifications for wafer handling precision.
- DC Drives:Legacy thyristor-based architectures persist in steel rolling mill retrofits where torque control simplicity outweighs efficiency gains.
- Stepper Drives:Open-loop positioning systems serve cost-sensitive pick-and-place equipment in electronics assembly.
By volume, AC Drives leads. By growth pace, Servo Drives is expanding most quickly.
Technology:
Control algorithm sophistication determines margin structure, with real-time digital platforms commanding software-recurring revenue models.
- Field-Oriented Control:Vector control methods decouple torque and flux components for dynamic response below 1 millisecond. Stuttgart and Wolfsburg automotive stamping presses deploy these architectures for synchronous multi-axis coordination.
- Digital Control:FPGA and DSP-based platforms enable Ethernet fieldbus integration and edge-parameter tuning. China's MIIT efficiency mandates are accelerating migration from analog platforms in Jiangsu province motor system retrofits.
- Adaptive Control:Self-tuning algorithms adjust gain parameters in response to load inertia variations.
- Analog Control:Potentiometer-based tuning persists in legacy installations with limited connectivity requirements.
By installed base, Analog Control still dominates. By replacement velocity, Digital Control is gaining share fastest.
Application:
Application-specific duty cycles shape thermal design and IP rating requirements, with continuous-duty conveying systems demanding different magnetics than intermittent robotics.
- Robotics:Six-axis articulated arms require coordinated servo loops with harmonized torque ripple below 0.5%. Taiwan precision manufacturing integrators are consolidating vendor lists around suppliers offering drive-integrated safety certification.
- CNC Machines:Multi-axis milling centers execute contouring algorithms with nanometer-scale following error. German machine tool builders in Baden-Württemberg specify drives with proprietary linear motion integration.
- Industrial Automation:General machinery applications span packaging lines and assembly stations with moderate positioning requirements.
- Conveying Systems:Long material handling lines prioritize energy recovery and regenerative braking.
By revenue concentration, CNC Machines leads. By specification intensity, Robotics shows the steepest expansion trajectory.
End User:
End-user verticals impose distinct certification burdens, with aerospace demanding DO-160 environmental testing that automotive ISO 26262 safety integrity levels do not require.
- Automotive:Stamping press and powertrain assembly lines specify drives with SIL 3 safety integration. Stuttgart corridor OEMs deploy AI-based vibration analysis for predictive maintenance subscription capture.
- Manufacturing:Discrete production facilities balance capital efficiency against flexibility requirements. US Rust Belt facilities retain DeviceNet infrastructure that forces dual-protocol development costs on replacement vendors.
- Aerospace:Flight control surface actuation and fuel pump systems require extended temperature range validation.
- Packaging:High-speed filling and cartoning machines prioritize rapid changeover through electronic cam profiling.
By procurement volume, Manufacturing leads. By specification premium, Aerospace climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. German automotive buyers absorb premium servo pricing for sub-arc-minute precision, while Chinese industrial retrofits prioritize variable frequency drives under MIIT efficiency mandates.
United States
Rust Belt manufacturing facilities drive replacement volume for legacy AC drives with DeviceNet compatibility requirements. The Department of Energy enforces NEMA MG-1 minimum efficiency standards that compel drive-motor system upgrades. Detroit-area stamping plants are deploying AI-based vibration analysis for predictive maintenance subscription capture.
Germany
Automotive corridor OEMs around Stuttgart and Wolfsburg specify SIL 3 safety-integrated drives for powertrain assembly lines. The EU Ecodesign Directive and CE marking requirements for electromagnetic compatibility shape product development roadmaps. Baden-Württemberg machine tool builders source drives with proprietary linear motion integration from consolidated vendor lists.
China
Jiangsu and Guangdong provinces generate replacement volume for variable frequency drives under tightening MIIT industrial energy conservation mandates. GB standards for motor system efficiency are raising compliance thresholds for imported equipment. Yangtze River Delta semiconductor fabrication clusters are expanding servo drive installations for precision wafer handling.
Taiwan
Semiconductor fabrication facilities are pulling 16 kHz switching frequency demand into mainstream specification sheets for EUV lithography stages. The island's precision manufacturing ecosystem is reducing qualified vendor lists from twelve to three around full-stack motion suppliers. Hsinchu Science Park integrators prioritize drive-integrated safety certification for six-axis robotics.
South Korea
Memory and logic foundries are expanding servo drive installations for sub-micron positioning accuracy in advanced lithography. The country's industrial energy efficiency regulations are accelerating migration from analog control platforms. Pyeongtaek and Hwaseong semiconductor complexes specify closed-loop systems with real-time feedback for wafer handling precision.
Motion Control Drive Market Competitive Environment
Capability concentration sits with German and Japanese industrial conglomerates possessing captive power electronics engineering talent; scale advantage sits with diversified automation vendors with broad installed bases. The vendor base separates into three strategic archetypes: full-stack motion suppliers with backward integration into linear components, digital platform specialists capturing recurring software revenue, and regional fabricators competing on retrofit compatibility. Dominant competitive moves include predictive maintenance subscription bundling and vendor list consolidation by system integrators.
Among diversified automation conglomerates, Siemens AG and ABB Ltd. exemplify the digital platform archetype with emphasis on recurring software revenue capture. Rockwell Automation occupies a position representing North American-centric retrofit specialists addressing legacy fieldbus infrastructure. Bosch Rexroth anchors the full-stack motion tier through in-house production of linear actuators and drive-integrated safety systems. Yaskawa Electric Corporation and Mitsubishi Electric sit within the Japanese industrial electronics cluster with concentrated capability in magnetics design and thermal management.
| Leading Market Players |
|---|
| ABB Ltd. |
| Rockwell Automation |
| Siemens AG |
| Delta Electronics |
| Bosch Rexroth |
| Yaskawa Electric Corporation |
| Schneider Electric |
| FANUC Corporation |
| Mitsubishi Electric |
| Others |
Value Chain & Pricing Dynamics
IGBT and SiC module concentration among Japanese and German foundries determines both pricing tier spreads and supply chain shape, compressing margins for drive manufacturers exposed to 26-week lead time volatility while rewarding those with captive power electronics engineering or long-term offtake agreements with premium pricing power.
Pricing Analysis
Predictive maintenance subscriptions now drive lifetime value capture across installed servo drive bases. Three-tier pricing structure across premium, standard, and economy levels separates vendors offering drive-integrated safety certification and digital twin convergence from commodity AC drive suppliers. Cost compression in legacy scalar V/Hz architectures is intensifying because field-oriented control platforms are displacing analog methods. Chinese industrial retrofit buyers under MIIT mandates exhibit highest price sensitivity, while Taiwan semiconductor fabrication clusters absorb premium servo pricing for sub-arc-minute precision.
Supply Chain Analysis
Silicon carbide wafer and rare-earth magnet feedstocks draw from Japan, China, and Germany as primary upstream nodes. Power semiconductor fabrication concentrates in Japanese and German foundries, while magnetics assembly rests on Chinese rare-earth processing capacity. Single-source vulnerability in high-voltage switching components exposes drive manufacturers to allocation risk during capacity constraints. Distribution runs through OEM direct channels for automotive and semiconductor accounts, with industrial distributors serving retrofit replacement volume in the US Rust Belt and European Mittelstand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Motion control drive markets fragment across divergent specification requirements from Taiwan semiconductor clusters and Germany automotive corridors, creating niches for specialized vendors as system integrators consolidate qualified supplier lists from twelve to three.
For Market Incumbents: Insulate installed base value through predictive maintenance subscription bundling and backward integration into linear motion components. Direct-drive torque motor substitution in wind turbine pitch systems threatens gearbox-servo combinations, demanding defensive investment in drive-integrated safety certification to maintain procurement authority with Taiwan precision manufacturing integrators. For New Entrants and Emerging Players: Establish a beachhead in India's Tamil Nadu and Gujarat industrial corridors where PLI scheme incentives attract assembly investment with lower incumbent saturation. Agricultural automation in Brazil and Australia offers penetrable white-space for IP67-rated servo drives in autonomous tractor applications, with precision seeding OEMs seeking alternatives to consolidated vendor lists. For Investors and Strategic Acquirers: EU F-Gas Regulation reshapes the acquisition landscape by accelerating migration toward energy-efficient AC drive architectures and compressing valuation multiples for legacy refrigerant-dependent compressor control vendors. Long-term viability centers on software-defined motion platforms with recurring revenue capture. Target acquisition archetype: digital control specialists with Ethernet fieldbus integration capability. The signal to watch is vendor list consolidation velocity among Taiwan system integrators as inflection indicator for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Subscription Launch | Captures lifecycle value from Stuttgart stamping press operators through AI-based vibration analysis. |
| Backward Integration into Linear Actuators | Mirrors Bosch Rexroth's full-stack motion supplier positioning for Baden-Württemberg machine tool builders. |
| Digital Twin Platform Convergence | Reduces startup engineering hours by half for multi-axis commissioning in semiconductor fabrication. |
| CE Marking and EMC Certification Investment | Accelerates European market access timelines for non-EU vendors facing Ecodesign Directive requirements. |
| India Manufacturing Footprint Establishment | Accesses PLI scheme incentives for advanced equipment assembly in Tamil Nadu industrial corridors. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and maintenance directors; and secondary validation through SEC filings, customs and trade data, IHS Markit industrial production databases, and IEEE technical standards documentation. Bottom-up unit demand modeling triangulated against top-down macroeconomic indicators across the analysis window.
Forecast inputs span product type segmentation by switching frequency and control architecture, technology tier by algorithm sophistication, application intensity by positioning accuracy requirements, and end-user vertical by certification burden. CAGRs were derived from replacement cycle analysis and efficiency mandate compliance timelines. Modeled variables include MIIT retrofit mandates in Jiangsu province, EU F-Gas Regulation phase-down schedules, and semiconductor capital equipment spending patterns.
Stress conditions across power semiconductor lead times, rare-earth magnet price volatility, and fieldbus protocol transition rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and technology substitution curves. Cross-checking against IEA industrial energy efficiency benchmarks and SEMI capital equipment forecasts is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
South East Asia Warehouse Automation Market
Industrial Automation
Model Based Manufacturing Technologies Market
Industrial Automation
Industrial Robotic Motors Market
Industrial Automation
Predictive Maintenance Market
Industrial Automation
Factory Automation Market
Industrial Automation
Global PC Based Automation Market
Industrial Automation
Factory Automation Platform As a Service Market
Industrial Automation
Industrial Automation Device Manager Software Market
Industrial Automation
Switzerland Industrial Automation Market
Industrial Automation
Asia Industry 4.0 Market
Industrial Automation
Programmable Logic Controller [PLC] Market
Industrial Automation
Europe Warehouse Automation Systems Market
Industrial Automation
Global Programmable Logical Controllers Automation Market
Industrial Automation
Industrial Multiprotocol Gateways Market
Industrial Automation
Middle East and Africa Process Automation Market
Industrial Automation
Smart Sorting Machine Market