
 Parcel Sortation Systems Market | 2026-2036
Parcel Sortation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Parcel Sortation Systems Market Intelligence
The capability gap between fully automated robotic sorting systems and conventional manual or hybrid sorters is expanding as logistics providers demand higher throughput. Vanderlande specializes in complex, high-capacity systems for major airports and e-commerce hubs. Interroll focuses on providing modular conveyor and sorter components, catering to a wider range of integrators and smaller-scale operations. Dematic leverages its software integration capabilities to offer complete warehouse automation solutions.
Parcel sortation systems are integrated mechanical and software solutions designed to automatically identify, track, and divert packages within a distribution or fulfillment center. These systems are engineered for specific throughput capacities, with high-end automated sorters capable of processing over 20,000 parcels per hour. Within product types, robotics and advanced automated sorters command the highest investment, driven by the logistics providers and e-commerce end-user segments. Modular installation approaches are gaining traction for their flexibility, allowing facilities to scale capacity without a complete system overhaul.
System design and implementation are governed by stringent safety regulations, including OSHA standards in the United States and the CE marking directives in Europe. Compliance with ISO standards for machinery safety and ergonomics directly influences equipment engineering and workplace integration. Stakeholder decisions will center on balancing the high initial capital expenditure for automation against long-term operational cost savings and labor availability.
Market Dynamics
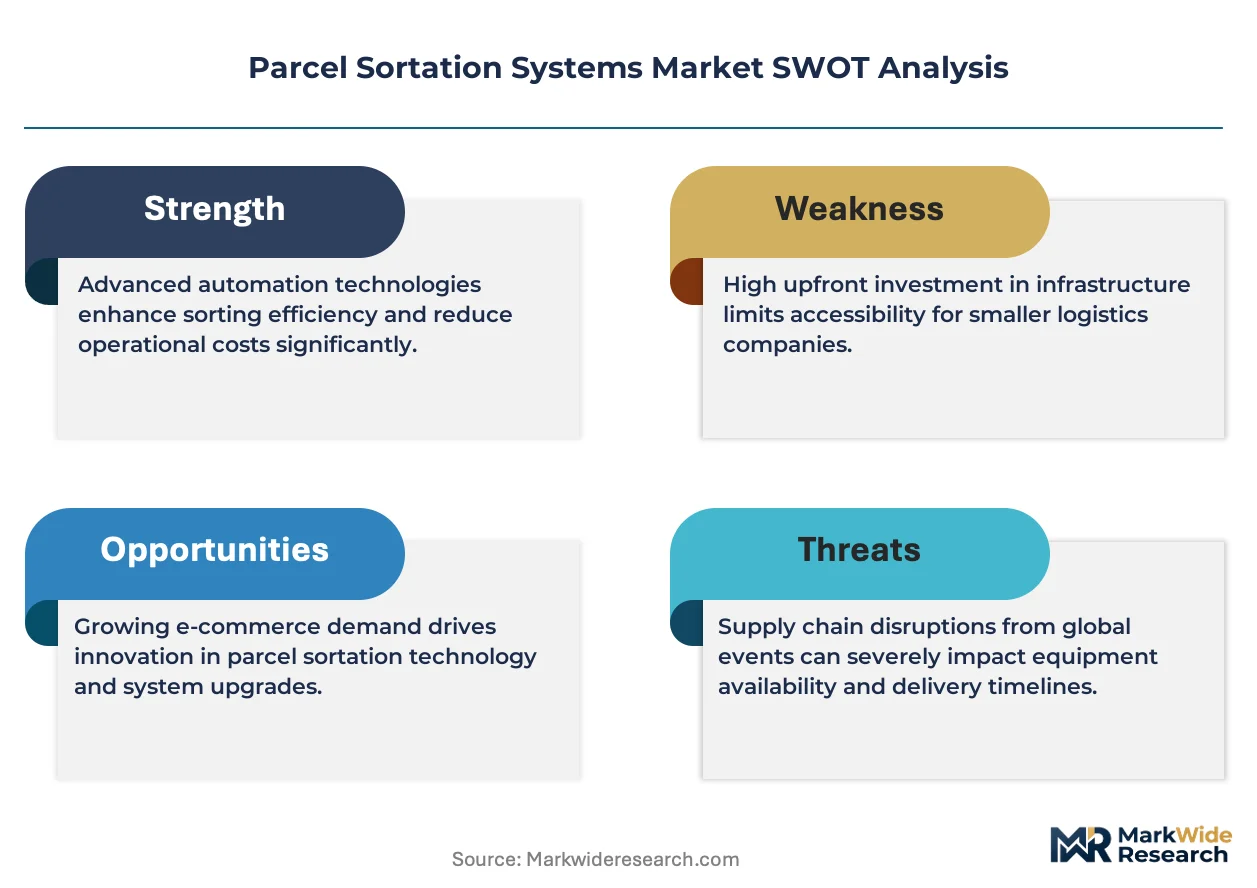
The central dynamic shaping the parcel sortation systems market is the escalating requirement for higher throughput from the e-commerce sector. This demand creates a widening capability gap between advanced robotic sorters and conventional manual systems, forcing logistics providers to automate.
Growth Catalysts
- E-commerce Fulfillment:The expansion of direct-to-consumer shipping models necessitates high-speed, accurate sortation systems capable of handling a diverse mix of parcel sizes and shapes to meet delivery expectations.
- AI-Powered Vision Systems:The integration of artificial intelligence with optical recognition technology enables automated identification and classification of parcels without manual intervention, significantly boosting processing speeds and accuracy.
- Logistics Hub Concentration:Demand for high-capacity systems is geographically focused within major logistics corridors in Germany, the United States, and China, creating dense pockets of investment in automation.
Market Restraints
- High Capital Expenditure:The significant upfront investment required for fully automated robotic sorting systems presents a substantial barrier to entry for smaller logistics operators and distribution centers.
- System Inflexibility:Many high-throughput sorters are engineered for specific parcel profiles, struggling to efficiently process non-conveyable or irregularly shaped items, which still require manual handling.
- Component Lead Times:Specialized components, such as high-speed diverters and advanced control modules, often have long manufacturing lead times, creating potential bottlenecks in system implementation and upgrades.
Strategic Opportunities
- Modular System Adoption:Phased automation through modular components offers a flexible upgrade path, allowing facilities to scale capacity and capabilities without the disruption of a complete system overhaul.
- Pharmaceutical Logistics:The pharmaceutical supply chain requires precise, gentle handling and track-and-trace capabilities, opening an adjacent market for specialized sortation systems designed for cold-chain and high-value products.
- Robotics-as-a-Service (RaaS):Subscription-based models for robotic sorting solutions can lower the initial investment barrier, making advanced automation accessible to a broader segment of the market.
Industry Challenges
- Legacy System Integration:A primary operational hurdle is the complexity of integrating modern sortation control software with pre-existing Warehouse Management Systems (WMS), often leading to data silos and inefficiencies.
- Skilled Labor Scarcity:A persistent shortage of technicians and engineers qualified to install, maintain, and troubleshoot sophisticated automated and robotic sortation equipment constrains operational uptime.
- Regulatory Compliance:Adherence to stringent, evolving safety standards, such as OSHA regulations and CE marking directives, requires continuous engineering focus and can delay system deployment.
Report Scope
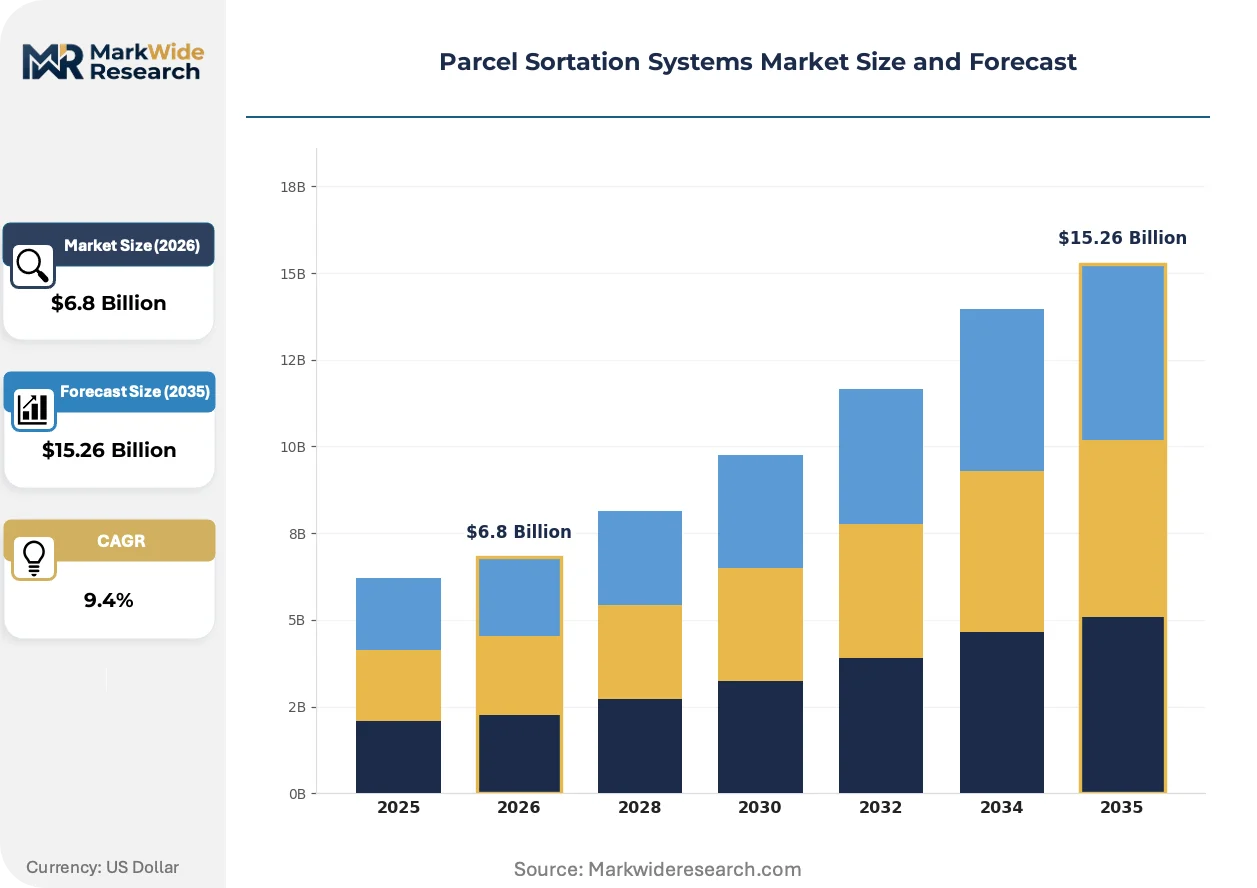
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Parcel Sortation Systems Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Sorters, Manual Sorters, Hybrid Sorters, Robotics Technology: Barcode Scanning, RFID, Conveyor Systems, Optical Recognition End User: Retailers, Logistics Providers, E-commerce, Wholesalers Installation: On-premise, Modular, Integrated, Cloud-based |
| Companies Covered | Bastian Solutions, Honeywell Intelligrated, Dematic, Daifuku, Interroll, Vanderlande, Fives, Siemens, BEUMER Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Parcel Sortation Systems Market Strategic Shifts & Innovations
The market's evolution is defined by a push toward software-defined flexibility and modularity. This allows logistics operators to adapt their physical infrastructure to fluctuating demand patterns without undertaking massive, disruptive capital projects, shifting value toward integrated software and robotics.
AI-powered optical recognition is a transformative technology using advanced cameras and machine learning algorithms to identify parcel characteristics in real time. E-commerce and third-party logistics providers are the primary adopters, seeking to eliminate manual data entry. This technology is integrating directly with sorter induction points to automate routing decisions, which improves overall system throughput and accuracy.
Workplace safety regulations, including OSHA standards in the United States and the EU's Machinery Directive, are influencing system design. These mandates compel a reduction in manual lifting and repetitive stress injuries, directly spurring investment in automated solutions. The equipment engineering segment is most affected, now embedding ergonomic principles and certified safety controls into sorter architecture from the outset.
A notable behavioral shift is the move toward modular installation strategies over monolithic system replacements. This approach displaces the traditional, high-risk "rip-and-replace" model, enabling operators to scale capacity and add new functions like robotic picking incrementally. The trend is most visible in mid-sized fulfillment centers across the United States and Europe, where balancing capital outlay with future-proofing is critical.
Parcel Sortation Systems Market Segmentation
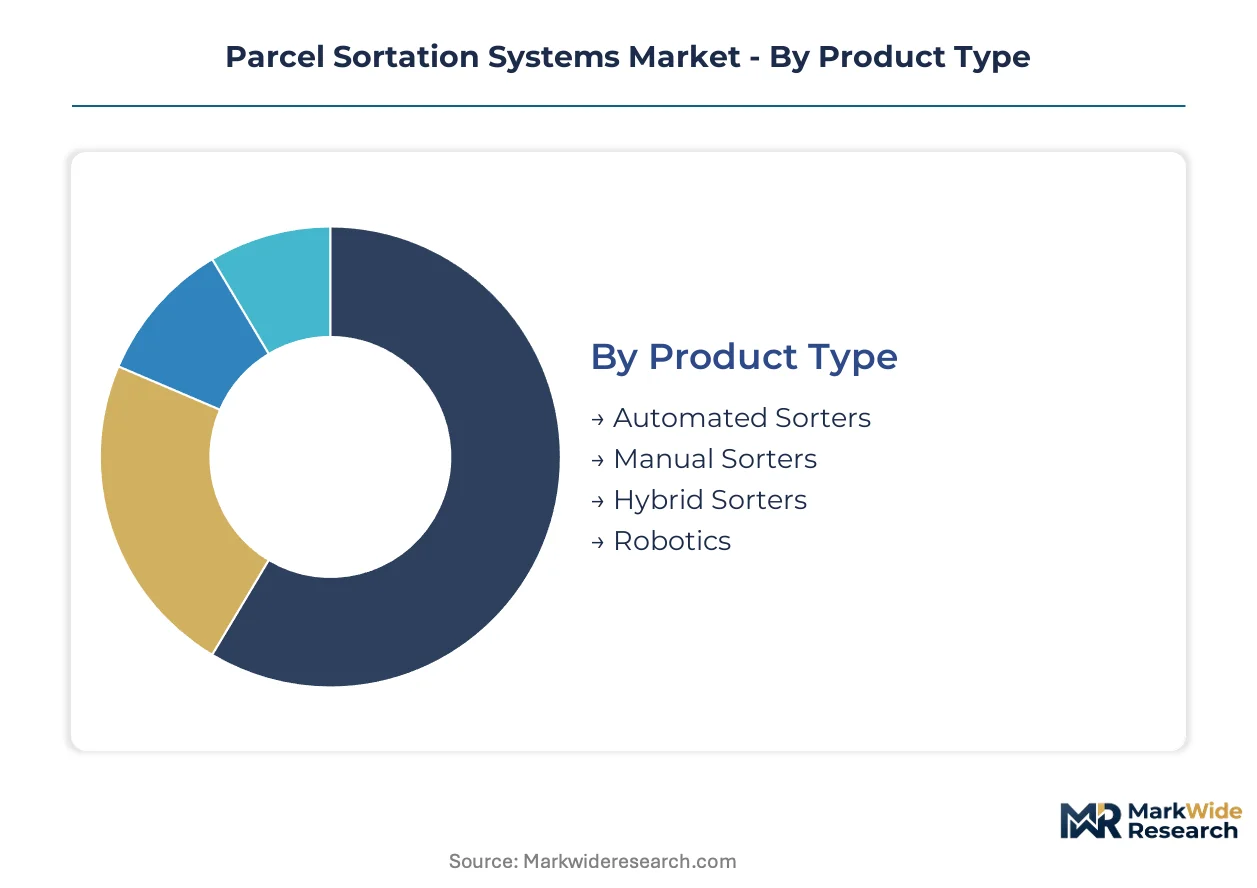
Understanding the segmentation of the parcel sortation systems market provides critical insights into investment patterns and technological adoption across various operational contexts. This analysis highlights how different product types, technologies, end-users, and installation methods shape market dynamics.
Product Type:
Investment decisions for parcel sortation systems are primarily driven by the desired level of automation and processing speed required for operational efficiency.
- Robotics:Robotic systems incorporate articulated arms or mobile robots for picking, placing, and sorting parcels, often operating autonomously within a defined workspace. E-commerce fulfillment centers demand these systems for their flexibility and ability to handle diverse parcel sizes, reducing reliance on manual labor in high-volume environments.
- Automated Sorters:These systems use high-speed conveyors, diverters, and scanning technology to automatically route parcels to designated destinations with minimal human intervention. Logistics providers in Germany and the United States utilize automated sorters extensively for their throughput capacity, critical for managing large volumes in major hubs.
- Hybrid Sorters:Hybrid systems combine automated components with manual workstations, offering a flexible solution for facilities with varied parcel profiles or fluctuating volumes.
- Manual Sorters:Manual sorting involves human operators physically directing parcels, often supported by basic conveyor belts, suitable for lower volume operations or specialized handling.
Automated Sorters lead on scale; Robotics leads on momentum.
Technology:
The selection of core technology for parcel sortation systems directly impacts accuracy, speed, and the range of parcel types that can be efficiently processed.
- Optical Recognition:Optical recognition systems employ advanced cameras and AI algorithms to identify parcel attributes, including barcodes, labels, and package dimensions, for automated routing. E-commerce companies prioritize this technology for its ability to process diverse, non-standardized packages quickly, significantly boosting throughput in direct-to-consumer operations.
- Conveyor Systems:Conveyor systems form the backbone of most sortation facilities, using motorized belts and rollers to transport parcels efficiently between different processing stages. Logistics hubs in China rely heavily on robust conveyor systems to manage the immense volumes of parcels, ensuring continuous flow and minimizing bottlenecks.
- Barcode Scanning:Barcode scanning systems use laser or camera-based readers to identify parcel information from 1D or 2D barcodes, enabling basic tracking and routing functions.
- RFID:Radio-Frequency Identification (RFID) technology uses electromagnetic fields to automatically identify and track tags attached to parcels, offering enhanced visibility without line-of-sight.
Optical Recognition drives efficiency gains; RFID offers enhanced flexibility.
End User:
Different end-user segments require parcel sortation systems tailored to their unique operational needs, parcel volumes, and delivery expectations.
- E-commerce:E-commerce operations demand high-speed, accurate sortation systems capable of handling a vast array of parcel sizes and types, from small envelopes to bulky goods. The rapid expansion of direct-to-consumer shipping models globally drives substantial investment in advanced sortation, particularly in the United States and China, to meet stringent delivery timelines.
- Logistics Providers:Logistics providers deploy large-scale sortation hubs with high-throughput capacities to manage vast volumes of parcels for various clients, requiring robust and scalable solutions. Major players in Germany and the US invest in sophisticated systems to optimize network efficiency and reduce transit times, processing millions of parcels daily across their distribution networks.
- Retailers:Retailers utilize sortation systems for in-store fulfillment, returns processing, and distributing inventory to multiple store locations, often integrating with existing supply chains.
- Wholesalers:Wholesalers employ sortation systems to efficiently consolidate and distribute bulk orders to retailers or other businesses, focusing on volume handling and accuracy for large shipments.
E-commerce drives volume processing; Logistics Providers demand precision at scale.
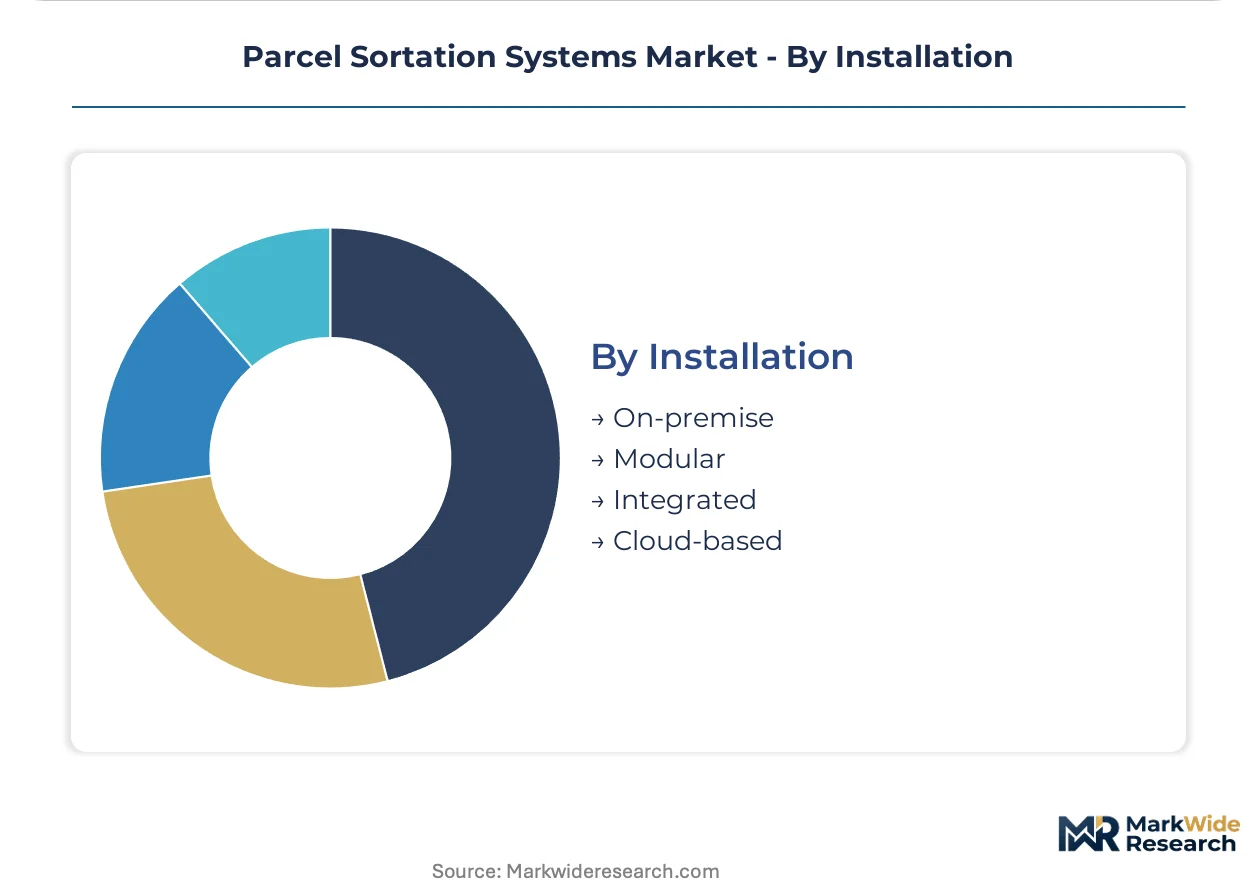
Installation:
The chosen installation approach for parcel sortation systems dictates the initial capital outlay, operational flexibility, and future scalability of a facility.
- Modular:Modular installations involve deployable, standardized components that can be added or reconfigured incrementally, allowing facilities to scale capacity and functionality over time. Mid-sized fulfillment centers in Europe and the United States increasingly adopt modular systems for their flexibility, enabling phased upgrades without complete system overhauls.
- Integrated:Integrated systems involve a holistic design where all sortation components, software, and material handling equipment are custom-engineered to work seamlessly within a facility. Large, purpose-built logistics hubs favor integrated solutions for maximum throughput and optimized space utilization, particularly where complex workflows and high automation levels are required.
- On-premise:On-premise installations refer to sortation systems physically located and managed within a company's own facilities, offering direct control over hardware and software.
- Cloud-based:Cloud-based solutions manage sortation software and data processing remotely, offering scalability, reduced IT overhead, and real-time analytics for system optimization.
Modular solutions offer superior adaptability; On-premise installations provide direct control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Concentrations of highly skilled engineering talent and logistics expertise anchor regional demand for parcel sortation systems. These regions often feature dense networks of distribution centers and e-commerce fulfillment operations. Localized regulatory frameworks and infrastructural developments further shape the adoption and deployment of advanced automation technologies across diverse markets.
United States
The extensive e-commerce fulfillment network and high labor costs drive substantial demand for automated sortation systems. OSHA standards mandate workplace safety, directly influencing the design and implementation of automated material handling solutions. Major logistics hubs, such as those in Memphis and Louisville, see continuous investment in high-throughput sorters to manage vast parcel volumes.
Germany
Germany's robust manufacturing base and central role in European logistics necessitate precision and efficiency in parcel handling. CE marking directives ensure equipment safety and performance, guiding system engineering and integration. The Rhine-Ruhr region, a key industrial and logistics corridor, remains a significant adopter of advanced automated sorters for its dense distribution networks.
China
Immense parcel volumes generated by a booming e-commerce sector fuel the rapid expansion of sortation infrastructure. GB standards for industrial machinery ensure quality and safety in domestically produced and imported systems. Major economic zones like the Yangtze River Delta are witnessing widespread deployment of large-scale automated and robotic sortation facilities.
Japan
Japan's focus on technological innovation and high-quality logistics services creates a strong market for advanced sortation solutions. JIS standards for industrial equipment promote reliability and interoperability, influencing system design. The Tokyo Bay area, a primary economic and logistics gateway, actively integrates sophisticated sortation technologies to optimize urban delivery networks.
United Kingdom
The United Kingdom's mature e-commerce market and dense population centers require efficient parcel processing and last-mile delivery solutions. Health and Safety Executive (HSE) guidelines emphasize ergonomic design and operator safety in material handling equipment. Logistics parks in the Midlands region represent key investment areas for modular and integrated sortation systems.
Parcel Sortation Systems Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the parcel sortation systems market. The competitive landscape features a blend of large, integrated solutions providers and specialized component manufacturers. Strategic archetypes include full-service automation integrators, modular component suppliers, and software-focused solution providers. Competitive moves center on technology innovation, particularly in AI-powered vision systems, and strategic partnerships to offer comprehensive warehouse automation.
Within the full-service automation tier, Dematic GmbH, a German-based company, exemplifies comprehensive warehouse automation solutions, leveraging its software integration capabilities. Vanderlande Industries, a Dutch firm, represents a specialist in complex, high-capacity systems for major airports and e-commerce hubs. Interroll Holding AG, a Swiss company, occupies a position as a leading global manufacturer of modular conveyor and sorter components, catering to a wider range of integrators and smaller-scale operations.
| Leading Market Players |
|---|
| Bastian Solutions |
| Honeywell Intelligrated |
| Dematic |
| Daifuku |
| Interroll |
| Vanderlande |
| Fives |
| Siemens |
| BEUMER Group |
| Others |
Cost & Logistics Intelligence
Labor costs in major logistics hubs increase operational expenditure, pushing demand for automated systems, which then influences the project-based pricing of these complex solutions for end-users.
Pricing Analysis
Project-based pricing for integrated solutions often bundles hardware, software, and installation services, while modular components are typically sold transactionally. Price differentiation stems from the customization level required for integrated solutions and the guaranteed throughput capacity. Pricing pressure stems from the high capital expenditure required, with buyers seeking long-term operational cost savings. Smaller logistics operators and distribution centers are most price-sensitive, whereas major e-commerce players prioritize throughput and reliability over initial cost.
Supply Chain Analysis
Specialized component supply for high-speed diverters and advanced control modules often rests on manufacturers in Germany, Japan, and the United States. The supply chain relies heavily on high-precision mechanical parts, advanced sensors, and complex control electronics. Component lead times create a logistics chokepoint, delaying system implementation and upgrades. Distribution runs through direct sales from integrators to large end-users, with modular components also moving via specialized distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The parcel sortation systems market functions as a stable compounder, driven by the relentless expansion of e-commerce fulfillment needs. Continuous investment in automation reflects the necessity for higher throughput and accuracy across distribution networks.
For Market Incumbents: Acquire software integration specialists to enhance existing hardware platforms, countering the threat of software-focused solution providers. Deepen R&D into AI-powered vision systems, maintaining a technological edge against emerging automation startups. Invest in modular component manufacturing capacity, addressing component lead time constraints and offering flexible upgrade paths for customers.
For New Entrants and Emerging Players: Third-party logistics providers represent a penetrable segment for specialized robotic solutions, particularly for handling non-conveyable items. Offer Robotics-as-a-Service (RaaS) models, lowering the initial investment barrier for mid-sized fulfillment centers. Focus on niche applications like pharmaceutical logistics, providing precise handling and track-and-trace capabilities through a value-based go-to-market angle.
For Investors and Strategic Acquirers: Consolidation pressure builds where high capital expenditure and complex integration skills are required for comprehensive warehouse automation. Long-term viability for the market remains strong over the next decade, supported by e-commerce growth. Target acquisition archetypes include specialized software providers or component manufacturers with strong intellectual property in AI vision. A signal to watch is the increasing adoption rate of RaaS models, indicating market readiness for subscription-based automation.
| Strategic Initiative | Industry Significance |
|---|---|
| Enhance AI Vision Integration | Improves accuracy and speed for diverse parcel profiles, reducing manual intervention. |
| Expand Modular System Offerings | Provides flexible scaling options for mid-sized facilities, lowering capital expenditure. |
| Develop Robotics-as-a-Service Models | Lowers entry barriers for advanced automation, broadening market access. |
| Invest in Skilled Labor Training Programs | Addresses technician scarcity, ensuring operational uptime and system maintenance. |
| Specialize in Pharmaceutical Logistics Solutions | Captures adjacent market demand for precise, cold-chain handling of high-value products. |
Research Approach
Coverage spans the United States, Germany, China, Japan, and the United Kingdom, with primary inputs from each key geography. The analysis combines in-depth interviews with logistics executives, warehouse managers, and automation engineers. Secondary validation draws from industry association reports, government regulatory filings, and specialized trade publications. Bottom-up and top-down triangulation ensures data accuracy and market sizing integrity.
Market dimensions were modeled at granular levels across product type, technology, end-user, and installation method. The analytical framework projects growth across the analysis window, considering regional economic indicators and e-commerce penetration rates. Compound annual growth rates were derived from historical data trends and projected demand shifts. Forecast inputs include parcel volume growth estimates and automation investment trends.
Revisions become necessary when significant shifts in global trade policies or technological breakthroughs in robotics materialize. Forecasts reflect assumptions regarding capital expenditure trends and labor availability. Geopolitical events impacting supply chains or major shifts in consumer delivery expectations could also alter projections. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Automatic Screw Feeding System Market
Industrial Automation
Mining Automation Solutions Market
Industrial Automation
Industrial Embedded Systems Market
Industrial Automation
Supervisory Control and Data Acquisition (SCADA) Market
Industrial Automation
Liquid Handling Technology Market
Industrial Automation
Operational Predictive Maintenance Market
Industrial Automation
Smart Escalator Market
Industrial Automation
Pick and Place Machines Market
Industrial Automation
South Korea Automation and Industrial Control Market
Industrial Automation
Motion Positioning Stages Market
Industrial Automation
Cold Storage AGV Market
Industrial Automation
Global PC Based Automation Market
Industrial Automation
Mini-Load Systems Market
Industrial Automation
Latin America Automated Storage and Retrieval System Market
Industrial Automation
Industrial Networking Solutions Market
Industrial Automation
Asia-Pacific Automation Components Market