
 Middle East and Africa Industrial Automation Market | 2026-2036
Middle East and Africa Industrial Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Industrial Automation Market Foresight
System integrator networks across the Middle East and Africa are reconfiguring as original equipment manufacturers bypass traditional distributors to serve energy and water projects directly. Siemens AG leverages its Dubai-based digital industries headquarters to anchor automation software deployment across Gulf petrochemical complexes. ABB Ltd competes through localized engineering centers in Saudi Arabia and South Africa that sustain long-term service contracts for mining and metals customers. Schneider Electric SE differentiates via EcoStruxure architecture deployments targeting water treatment utilities from Morocco to Kenya.
Middle East and Africa industrial automation encompasses programmable logic controllers, distributed control systems, human-machine interfaces, and robotic assemblies that execute process control, motion sequencing, and real-time data acquisition across continuous and discrete manufacturing operations. These systems typically operate on IEC 61131-3 programming environments with millisecond scan cycles to ensure deterministic response in hazardous environments such as offshore platforms and chemical reactors. Control Systems and SCADA technology command substantial installed bases across oil and gas infrastructure, while Robotics adoption is accelerating fastest among automotive component manufacturers establishing North African export hubs. Sensors penetration remains deepest in water treatment applications where leak detection and pressure monitoring compliance requirements create sticky replacement cycles.
SFDA equipment validation protocols in Saudi Arabia and UAE's MOHAP pharmaceutical manufacturing standards are tightening Good Automated Manufacturing Practice requirements for batch control and electronic record integrity. South Africa's NRCS enforces SANS 10142 electrical installation codes that dictate PLC panel certification for industrial facilities, while Egypt's industrial modernization framework under the Ministry of Trade and Industry mandates IEC compliance for imported automation hardware. Stakeholders must monitor how divergent national certification timelines affect project scheduling across multi-country deployments.
Market Dynamics
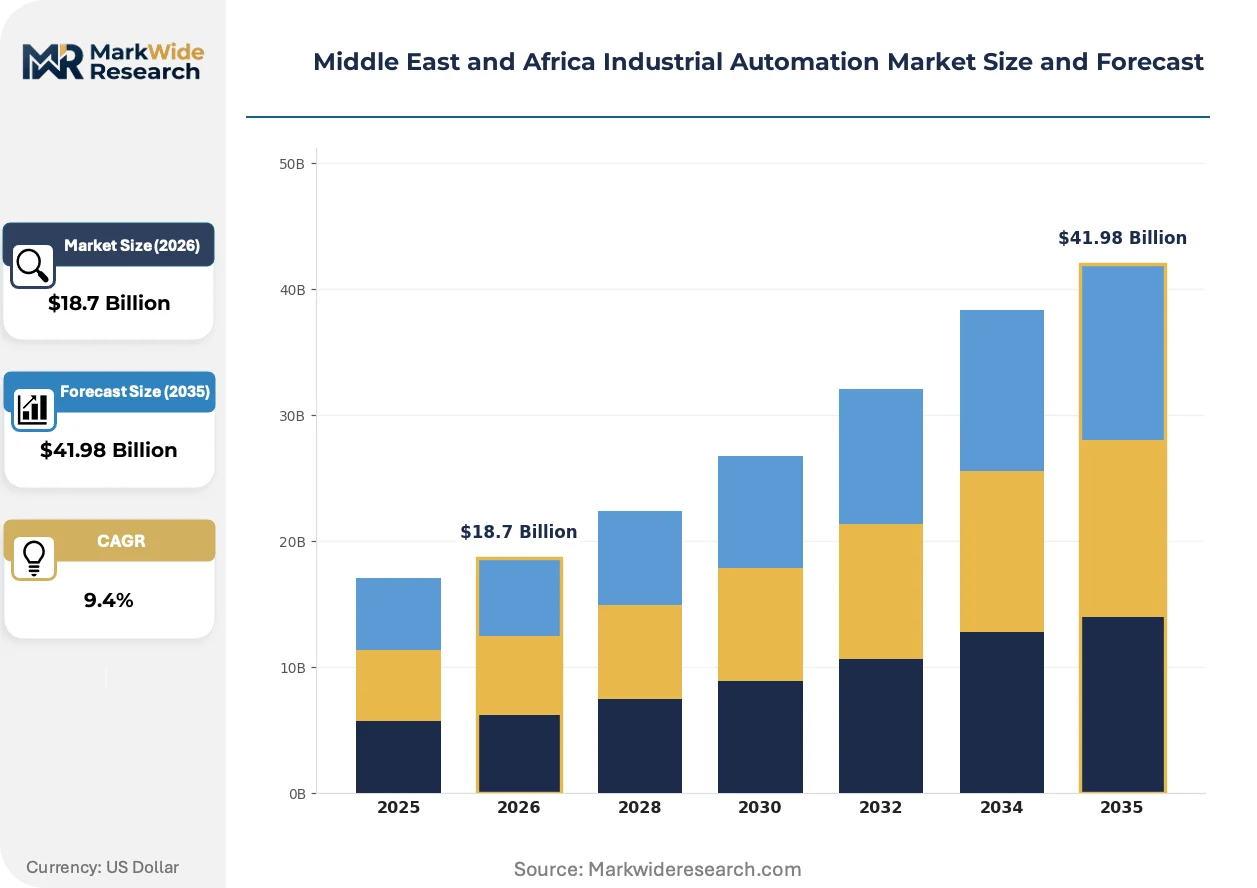
The Middle East and Africa industrial automation market is reconfiguring around direct OEM-to-end-user relationships that bypass traditional distribution tiers, compressing margin pools while accelerating deployment timelines for energy and water infrastructure projects.
Growth Catalysts
- Saudi Vision 2030 manufacturing targets:Domestic capacity mandates are redirecting petrochemical capital toward localized assembly lines requiring DCS and PLC integration.
- Water treatment compliance:Moroccan and Kenyan utilities are deploying sensor networks to meet leak detection standards, creating sticky replacement cycles for pressure monitoring hardware.
- Edge computing architectures:Millisecond scan cycle requirements for offshore platform safety are pulling real-time data processing closer to hazardous zone equipment.
Market Restraints
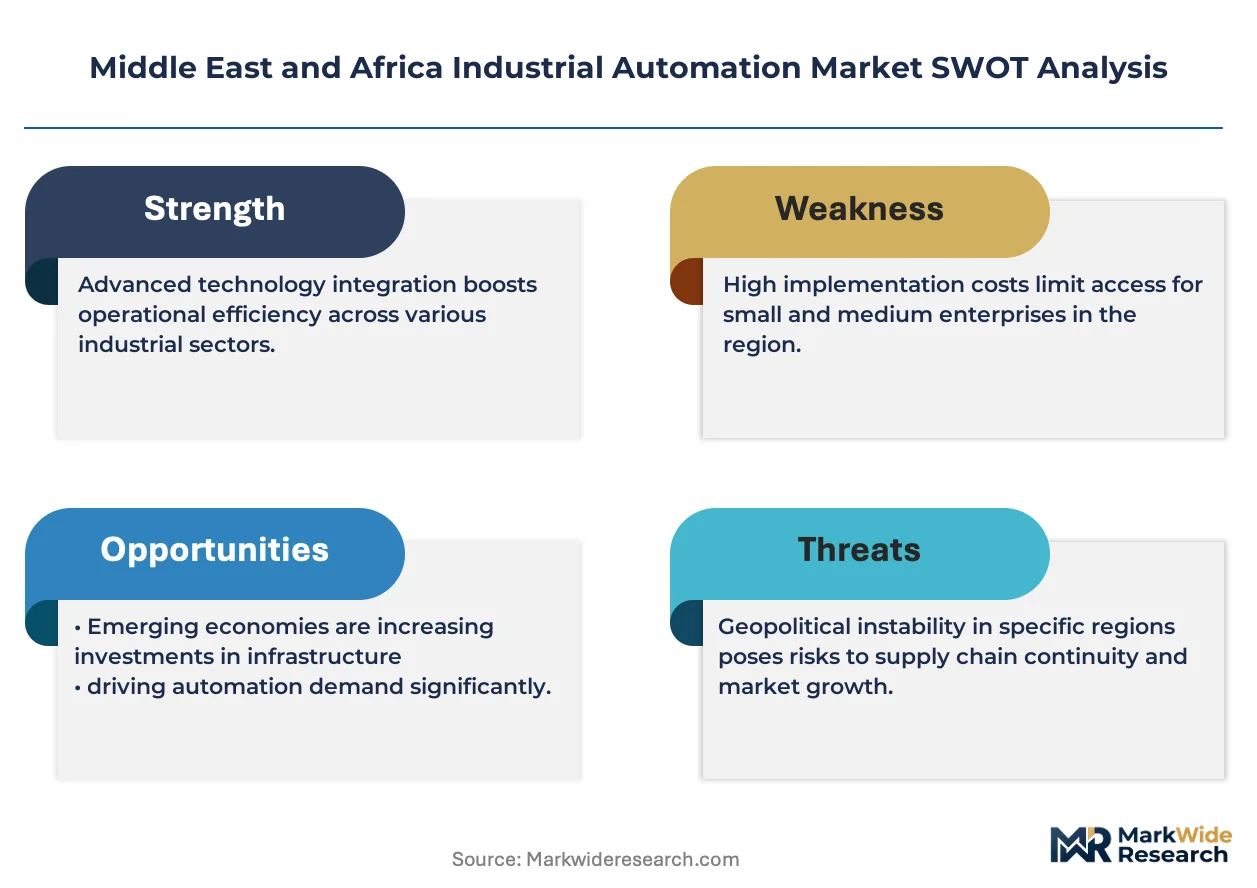
- Semiconductor input volatility:PLC and HMI manufacturing faces component lead time uncertainty from concentrated East Asian foundry supply.
- Multi-jurisdiction certification friction:Divergent SFDA, MOHAP, and NRCS validation timelines delay pharmaceutical and electrical panel deployments across Saudi Arabia, UAE, and South Africa.
- Skilled integrator scarcity:IEC 61131-3 programming expertise concentrates in Dubai and Johannesburg, leaving secondary markets dependent on fly-in engineering.
Strategic Opportunities
- Egyptian industrial modernization:Ministry of Trade and Industry IEC compliance mandates for imported hardware create certification service revenue pools for pre-shipment validation providers.
- Robotics in North African automotive:Component export hubs in Morocco and Tunisia are accelerating articulated arm deployment for precision assembly operations.
- Digital twin convergence:Petrochemical operators are merging SCADA data streams with predictive maintenance platforms to compress unplanned outage duration.
Industry Challenges
- Legacy DCS migration complexity:Brownfield oil and gas facilities face integration friction when retrofitting deterministic control layers onto 1990s-era proprietary networks.
- Certification timeline misalignment:Pharmaceutical manufacturers must sequence SFDA equipment validation, MOHAP inspections, and GAMP documentation across multi-country supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Industrial Automation Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensors, Robotics, Control Systems, Industrial PCs Application: Manufacturing, Oil & Gas, Water Treatment, Chemical Processing Technology: PLC, SCADA, DCS, HMI End User: Aerospace, Automotive Component Manufacturers, Food & Beverage, Pharmaceuticals |
| Companies Covered | Siemens AG, ABB Ltd, Schneider Electric SE, Honeywell International Inc, Rockwell Automation Inc, Emerson Electric Co, Yokogawa Electric Corporation, Mitsubishi Electric Corporation, OMRON Corp, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Industrial Automation Market Shifts & Advancements
Deterministic control architectures are fragmenting as edge-native platforms compress the traditional separation between field devices and central SCADA layers. Three developments are restructuring deployment patterns across the region.
Time-sensitive networking over standard Ethernet is collapsing the historical boundary between IT and OT infrastructure in process industries. Gulf petrochemical operators are adopting TSN-enabled PLCs to unify safety-critical control traffic with enterprise analytics on shared cabling. This convergence is collapsing dedicated fieldbus installation costs while demanding new cybersecurity segmentation skills from integrators.
SFDA and MOHAP pharmaceutical manufacturing standards are tightening electronic record integrity requirements for batch control systems. Automated audit trail capabilities now determine vendor selection for Saudi and UAE drug manufacturers upgrading to GAMP 5 guidelines. Facilities in Dubai Industrial City are responding by prioritizing controllers with embedded data integrity verification over lower-cost alternatives lacking built-in compliance features.
System integrators are unbundling long-term service contracts into discrete performance modules. Mining and metals customers in South Africa now procure PLC maintenance, HMI refresh cycles, and cybersecurity monitoring as separate line items rather than bundled annual agreements. This granularity is most visible in Johannesburg engineering procurement, where NRCS-certified panel builders compete on individual service tier pricing.
Middle East and Africa Industrial Automation Market Segmentation
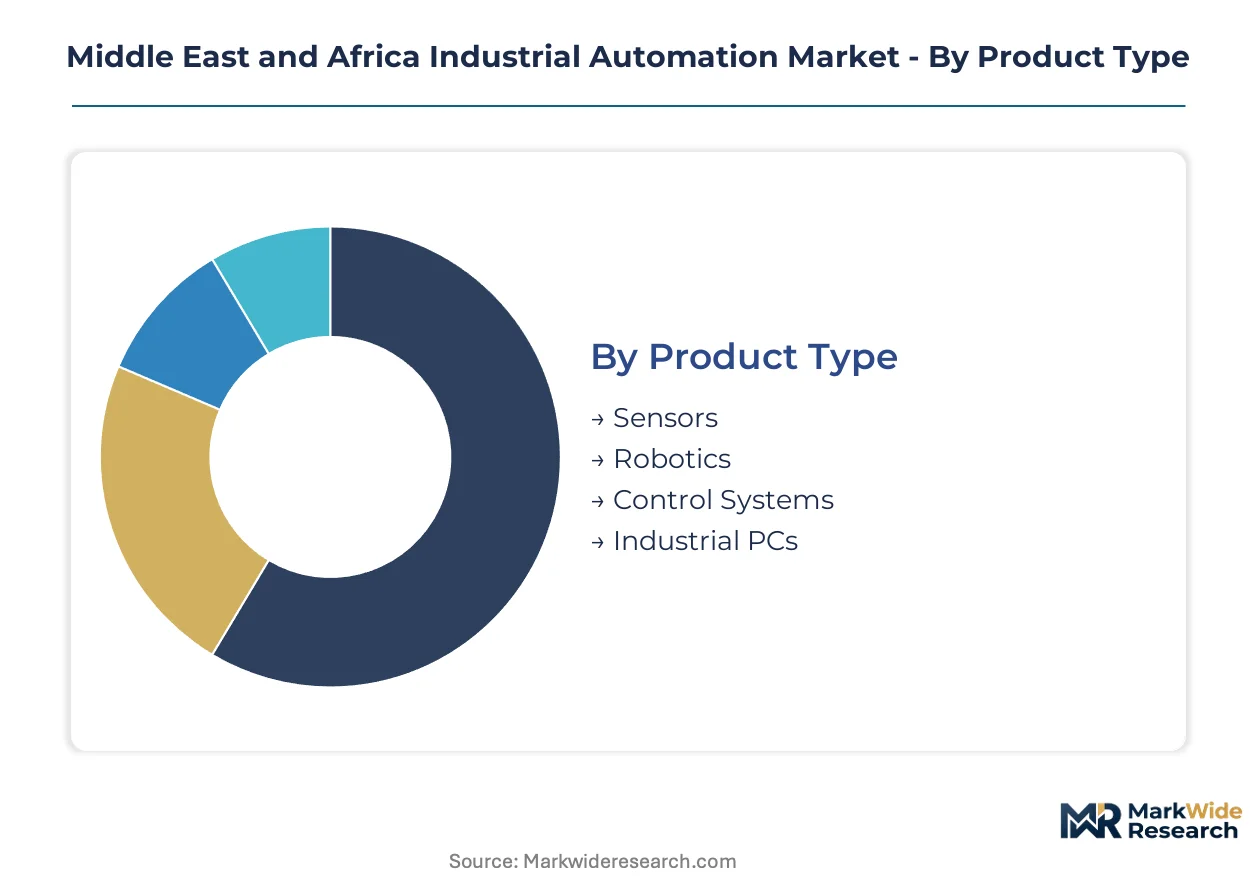
Industrial automation deployment patterns across the Middle East and Africa diverge sharply between hydrocarbon infrastructure and emerging manufacturing clusters. Segmentation reveals how technology selection tracks end-use hazard profiles, regulatory intensity, and capital availability rather than uniform upgrade cycles.
Product Type:
The use-case spectrum spans deterministic safety systems in offshore environments through flexible sensing arrays in batch manufacturing.
- Control Systems:Distributed control platforms coordinate continuous process operations across refinery distillation columns and desalination membrane trains. Gulf petrochemical operators in Jubail and Ruwais prioritize these systems for their deterministic scan cycles and integrated safety instrumented functions.
- Sensors:Pressure transducers, flow meters, and temperature probes constitute the measurement layer for leak detection and asset condition monitoring. Moroccan and Kenyan water utilities are deploying these networks to meet compliance mandates, creating replacement demand cycles tied to calibration protocols.
- Robotics:Articulated arm assemblies execute precision welding and material handling in automotive component plants.
- Industrial PCs:Ruggedized computing platforms host HMI visualization and edge analytics at zone-rated field locations.
The dominant share belongs to Control Systems, while Sensors is closing the gap fastest.
Application:
Cost tier stratification separates continuous process industries with 20-year asset horizons from discrete manufacturing with shorter automation refresh cycles.
- Oil & Gas:Upstream, midstream, and downstream facilities deploy SCADA and DCS platforms for wellhead monitoring, pipeline leak detection, and refinery process optimization. Saudi Aramco and ADNOC operators are accelerating platform upgrades to capture marginal barrel economics through tighter throughput control.
- Water Treatment:Municipal desalination and wastewater facilities rely on sensor networks and PLC-based control for chemical dosing and membrane integrity monitoring. Egyptian and South African utilities face mounting pressure to reduce non-revenue water through automated distribution monitoring.
- Manufacturing:Assembly lines and fabrication facilities integrate PLCs with robotic material handling for productivity gains.
- Chemical Processing:Batch and continuous reactors demand SIL-rated control systems for hazardous zone operation.
Oil & Gas commands the largest installed base, though Water Treatment is expanding most quickly as utilities modernize aging infrastructure.
Technology:
Volume concentration in hydrocarbon economies favors platforms with proven hazardous area certification and long-term vendor support commitments.
- SCADA:Supervisory control platforms aggregate field device data across geographically distributed assets including offshore platforms, pipeline networks, and well pads. UAE-based operators leverage these systems for centralized monitoring of remote production facilities from Dubai control centers.
- PLC:Programmable logic controllers execute discrete sequencing and regulatory control in manufacturing and utility applications. South African mining houses specify these for conveyor interlocking and crusher control, with NRCS-certified panel builders supplying locally assembled enclosures.
- DCS:Distributed control architectures dominate large-scale continuous process units with integrated safety and advanced process control.
- HMI:Human-machine interface terminals provide operator visualization and alarm management across all automation tiers.
SCADA holds the dominant position, while PLC is gaining share fastest through manufacturing diversification programs.
End User:
Customer type segmentation reflects regulatory intensity divergence between life sciences validation requirements and heavy industry durability specifications.
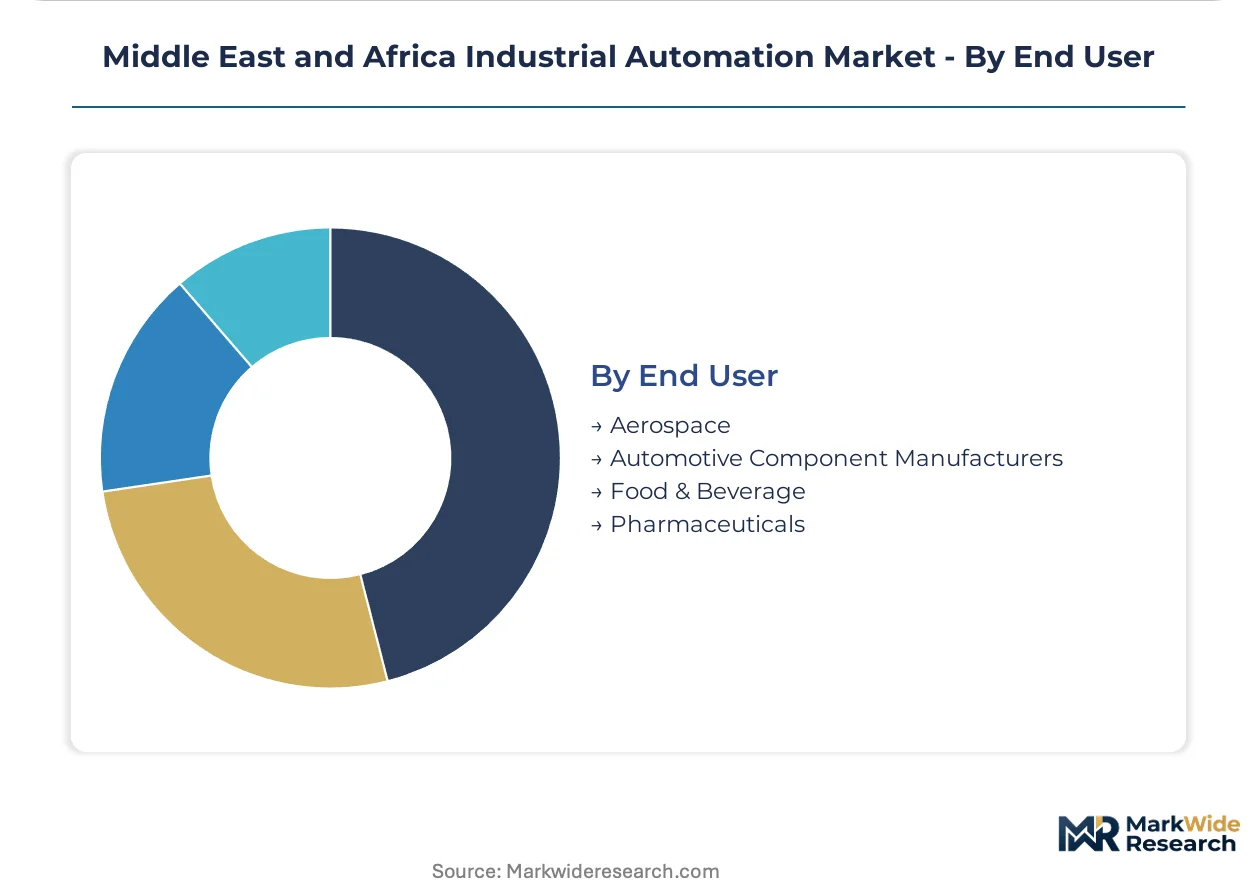
- Pharmaceuticals:Drug manufacturers in Saudi Arabia and the UAE deploy batch control systems with electronic record integrity features to satisfy SFDA and MOHAP GAMP requirements. Facilities in Dubai Industrial City and King Abdullah Economic City prioritize controllers with embedded audit trail capabilities over lower-cost alternatives.
- Automotive Component Manufacturers:Precision assembly operations in Moroccan and Tunisian export hubs utilize robotic welding and vision-guided material handling. These plants serve European OEM supply chains and demand automation platforms with ISO/TS 16949 traceability.
- Food & Beverage:Hygienic processing lines in Egypt and South Africa integrate washdown-rated sensors and stainless steel actuators.
- Aerospace:MRO facilities and component fabricators in the UAE deploy precision motion control for machining and assembly operations.
Pharmaceuticals represents the most technology-intensive segment, while Automotive Component Manufacturers is climbing the fastest on export hub investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ras Al-Khair industrial complex and Jubail pipeline network anchor Saudi Arabia's automation demand, while the Jebel Ali port infrastructure underwrites UAE's logistics-manufacturing integration. These hydrocarbon-linked assets concentrate procurement authority in Riyadh and Dubai control centers.
Saudi Arabia
Aramco's Marginal Barrel Program and SABIC downstream expansions drive DCS procurement for refinery optimization. SFDA pharmaceutical validation protocols tighten GAMP requirements for King Abdullah Economic City drug manufacturers. Jubail Industrial City hosts the densest concentration of SIL-rated safety instrumented systems in the Gulf.
United Arab Emirates
ADNOC offshore platform digitization and Dubai Industrial City manufacturing mandates pull automation investment toward real-time process control. MOHAP pharmaceutical standards enforce electronic record integrity for KIZAD free zone drug facilities. Abu Dhabi control centers aggregate SCADA data from remote production assets across the emirate.
South Africa
Eskom grid instability and mining house automation retrofits sustain PLC demand for conveyor and crusher control. NRCS enforces SANS 10142 electrical installation codes that dictate certified panel requirements for industrial facilities. Johannesburg engineering clusters concentrate IEC 61131-3 programming expertise for regional fly-in deployment.
Egypt
Ministry of Trade and Industry industrial modernization mandates IEC compliance for imported automation hardware. Suez Canal Economic Zone petrochemical investments require integrated control systems for hazardous zone operation. Cairo-Alexandria corridor utilities deploy sensor networks to reduce non-revenue water losses.
Morocco
Automotive component export hubs serving European OEM supply chains accelerate robotic welding deployment. Moroccan water utilities face leak detection compliance mandates that sustain pressure monitoring hardware replacement cycles. Casablanca-Tangier industrial corridor concentrates precision assembly automation investment.
Middle East and Africa Industrial Automation Market Competitive Landscape
On the supply side, the industry is consolidating around direct OEM-to-end-user relationships that bypass traditional distribution tiers, compressing margin pools while accelerating deployment timelines. Three strategic archetypes dominate: Gulf-based digital headquarters anchoring regional petrochemical contracts, localized engineering centers sustaining long-term mining and metals service agreements, and architecture-led platforms targeting water treatment compliance mandates. Competitive moves center on certification service bundling for multi-jurisdiction pharmaceutical deployments and edge-native platform development for offshore safety applications.
Among European-headquartered conglomerates, Siemens AG and ABB Ltd exemplify the Gulf-anchored archetype through Dubai and Riyadh operational bases. Schneider Electric SE occupies a position within the architecture-specialist tier, leveraging platform-level deployments across North African water utilities. These three entities represent the dominant supply-side configuration for energy and infrastructure automation procurement across the region.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Ltd |
| Schneider Electric SE |
| Honeywell International Inc |
| Rockwell Automation Inc |
| Emerson Electric Co |
| Yokogawa Electric Corporation |
| Mitsubishi Electric Corporation |
| OMRON Corp |
| Others |
Supply & Pricing Matrix
Jebel Ali's concentration of system integrators and panel builders anchors regional automation hardware availability, with Dubai Industrial City procurement offices translating that supply density into tiered pricing leverage for petrochemical and pharmaceutical end users.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs DCS and PLC procurement, with price differentiation driven by IEC 61131-3 certification grade and after-sales service bundling. Cost compression in standard-tier hardware is intensifying because East Asian component lead time volatility forces integrators to absorb inventory carrying costs. Water utilities in Morocco and Kenya exhibit highest price sensitivity due to municipal budget constraints, while Saudi Aramco maintains lowest sensitivity through long-term framework agreements.
Supply Chain Analysis
Extended payment terms from 60 to 90 days dominate supplier-financing arrangements as Dubai-based distributors manage working capital for Egyptian and South African project deployments. Semiconductor fabrication concentrates in Taiwan, South Korea, and Japan, while PLC enclosure manufacturing draws from China and Germany. Single-source vulnerability in advanced process control modules threatens brownfield upgrade timelines. Distribution runs through authorized system integrator networks rather than direct OEM channels for projects below threshold contract values.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a switching-cost fortress, with IEC 61131-3 programming expertise scarcity and multi-jurisdiction certification entrenchment protecting incumbent positions against price-based displacement.
For Market Incumbents: Build certification-service bundling as the primary moat, combining SFDA validation support with MOHAP inspection coordination for pharmaceutical manufacturers. Anchor long-term service contracts through localized engineering centers in Riyadh and Johannesburg to capture fly-in dependent secondary markets. Threat substitution comes from edge-native platforms that collapse traditional SCADA deployment timelines. For New Entrants and Emerging Players: Pursue Egyptian industrial modernization as the most penetrable entry vector, where Ministry of Trade and Industry IEC compliance mandates create pre-shipment validation service gaps. Target water treatment utilities in secondary North African markets where Schneider Electric's architecture dominance remains incomplete. Lead with subscription-based sensor monitoring to bypass capital-intensive DCS procurement barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among system integrators with NRCS-certified panel building capabilities and long-term mining service contracts in South Africa. Five-to-ten year viability favors acquisition targets combining hazardous area certification expertise with edge computing platform development. Watch for inflection when Saudi Vision 2030 manufacturing targets accelerate domestic PLC assembly capacity beyond current import dependency.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Service Bundling | SFDA and MOHAP validation integration compresses multi-country pharmaceutical deployment timelines. |
| Edge-Native Platform Development | TSN-enabled PLCs for offshore safety applications collapse traditional IT-OT infrastructure separation costs. |
| Localized Engineering Center Expansion | Johannesburg and Riyadh facilities capture fly-in dependent secondary markets with IEC 61131-3 expertise scarcity. |
| Backward Integration into Panel Building | In-house NRCS-certified enclosure production secures margin capture on South African mining retrofits. |
| Digital Twin Convergence Partnership | SCADA data stream integration with predictive maintenance platforms reduces unplanned outage duration for ADNOC operators. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and EPC contractor disclosures. Interviews with plant engineers, automation procurement leads at petrochemical operators, system integrator technical directors, and aftermarket service heads inform demand-side validation. Secondary sources include SEC 10-K filings from listed automation vendors, IEC standards documentation, and national industrial modernization framework publications. Bottom-up project pipeline assessment triangulates against top-down hydrocarbon capital expenditure tracking.
Forecast inputs span product type segmentation across control systems, sensors, robotics, and industrial PCs; application tiers from oil and gas through water treatment and manufacturing; technology deployment from SCADA through PLC and DCS architectures; and end-user intensity from pharmaceutical validation requirements to automotive export hub automation. CAGRs derive from installed base replacement cycle analysis and greenfield capacity addition modeling. Edge computing adoption curves and GAMP 5 compliance upgrade timelines inform technology transition assumptions.
Sensitivities concentrate around semiconductor supply normalization trajectories and Gulf petrochemical operator marginal barrel economics. Forecasts reflect assumptions on certification timeline convergence across SFDA, MOHAP, and NRCS jurisdictions. Macroeconomic deviation in hydrocarbon pricing, regulatory acceleration in pharmaceutical validation, or breakthrough edge-native platform adoption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Port Equipment Automation Market
Industrial Automation
Intelligent Conveyor System Market
Industrial Automation
Europe Warehouse Automation Systems Market
Industrial Automation
UV Curing System Market
Industrial Automation
North America Automated Storage and Retrieval System Market
Industrial Automation
North America Industrial Automation Market
Industrial Automation
Smart Elevator Automation System Market
Industrial Automation
Global Industrial Automation and Control Systems Market
Industrial Automation
Motion Positioning Stages Market
Industrial Automation
Modular High-Bay Solutions Market
Industrial Automation
Europe Process Automation Market
Industrial Automation
South Korea Factory Automation and Industrial Controls Market
Industrial Automation
Europe Water Automation and Instrumentation Market
Industrial Automation
Switzerland Industrial Automation Market
Industrial Automation
Electric Linear Actuator Market
Industrial Automation
Palletizing Systems Market