
 Intralogistics Market | 2026-2036
Intralogistics Market Size, Share, and Industry Trends Forecast 2026-2036
Intralogistics Market Outlook
Asset-light leasing models for automated guided vehicles and robotics-as-a-service arrangements is narrowing the capital barrier for mid-size warehouse operators. Daifuku leverages its vertical integration in conveyor manufacturing to control component costs across Asian installations. Dematic sustains technology leadership in high-throughput sortation systems for parcel and postal networks. KNAPP specializes in software-driven warehouse management platforms that integrate robotics with real-time inventory tracking.
Intralogistics encompasses the internal movement, storage, and handling of materials within distribution centers, manufacturing plants, and fulfillment facilities, typically employing conveyor belts with throughput rates exceeding 10,000 items per hour, automated storage and retrieval systems reaching heights above 40 meters, and software platforms orchestrating order-picking algorithms. The technology dimension spans automated guided vehicles, conveyor systems, robotics, and warehouse management systems, with robotics capturing expanding margin pools as labor costs rise and SKU proliferation demands adaptive gripping and vision systems. Application segments include retail, manufacturing, e-commerce, and food and beverage, where e-commerce fulfillment drives the fastest equipment refresh cycles due to same-day delivery service-level agreements and returns-processing complexity.
OSHA workplace safety standards and the EPA's emissions frameworks for industrial equipment shape forklift electrification timelines and warehouse ventilation requirements in the United States, while the EU Green Deal and REACH chemical safety protocols influence battery chemistry choices and material handling equipment procurement across European distribution networks. Stakeholders must monitor how evolving carbon-border adjustment mechanisms and battery recycling mandates alter total-cost-of-ownership calculations for electrified intralogistics fleets.
Market Dynamics
E-commerce fulfillment centers are compressing equipment refresh cycles as same-day delivery SLAs force warehouse operators to replace fixed conveyor infrastructure with adaptive robotic systems that handle SKU proliferation and returns complexity.
Growth Catalysts
- EU Green Deal fleet electrification mandates:Warehouse operators across Germany, France, and the Netherlands are replacing diesel forklifts with lithium-ion alternatives to meet carbon-reduction timelines and avoid penalties.
- Pharmaceutical cold chain expansion:Temperature-controlled automated storage and retrieval systems are penetrating biologics distribution networks as cell and gene therapies require precise environmental control.
- Robotics-as-a-service financing:Mid-size 3PL providers are accessing autonomous mobile robots through operating leases rather than capital expenditure, flattening adoption barriers.
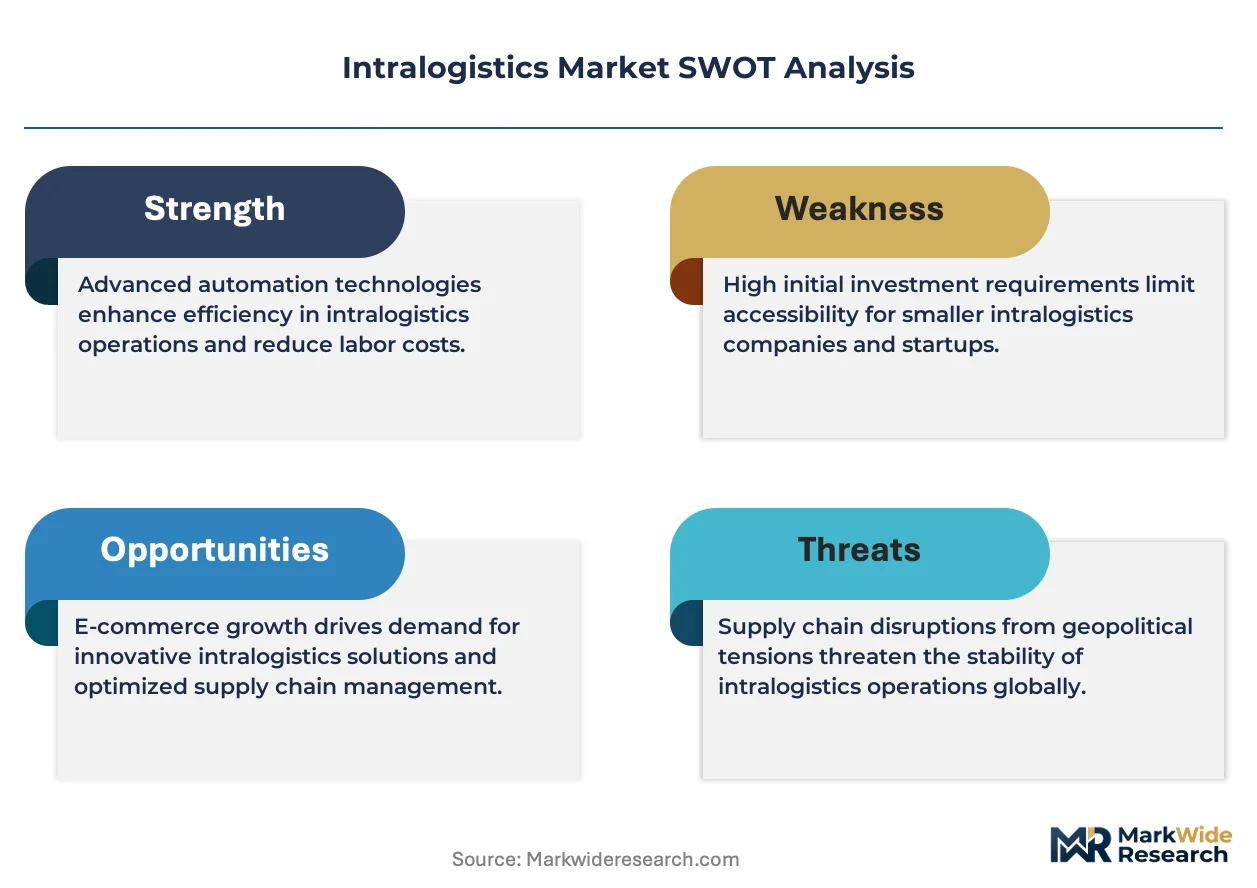
Market Restraints
- Lithium-ion battery supply concentration:Cathode material processing capacity clusters in China, exposing European and North American equipment manufacturers to supply disruption and price volatility.
- Technical limitation in adaptive gripping:Current robotic end-effectors struggle with deformable packaging formats common in food and beverage, limiting automation penetration in that vertical.
- REACH chemical compliance friction:Battery chemistry choices for automated guided vehicles face extended approval timelines under ECHA substance evaluation protocols.
Strategic Opportunities
- India warehouse automation underpenetration:Organized retail and pharmaceutical distribution in Mumbai, Delhi, and Bangalore remain below automation saturation thresholds, creating first-mover positioning for integrated system providers.
- Convergence of digital twin simulation with warehouse execution:Virtual commissioning of automated storage and retrieval systems before physical installation is compressing deployment risk and downtime.
- US Inflation Reduction Act clean energy incentives:Domestic battery manufacturing tax credits are reshaping total-cost-of-ownership calculations for electrified intralogistics fleets procured by American operators.
Industry Challenges
- Controls engineering talent scarcity:Programming and maintenance of programmable logic controllers for high-throughput sortation systems outpaces vocational training pipeline output in Germany and the United States.
- Legacy warehouse management system integration:Brownfield facilities running decade-old software stacks require expensive middleware development to orchestrate new robotic hardware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intralogistics Market |
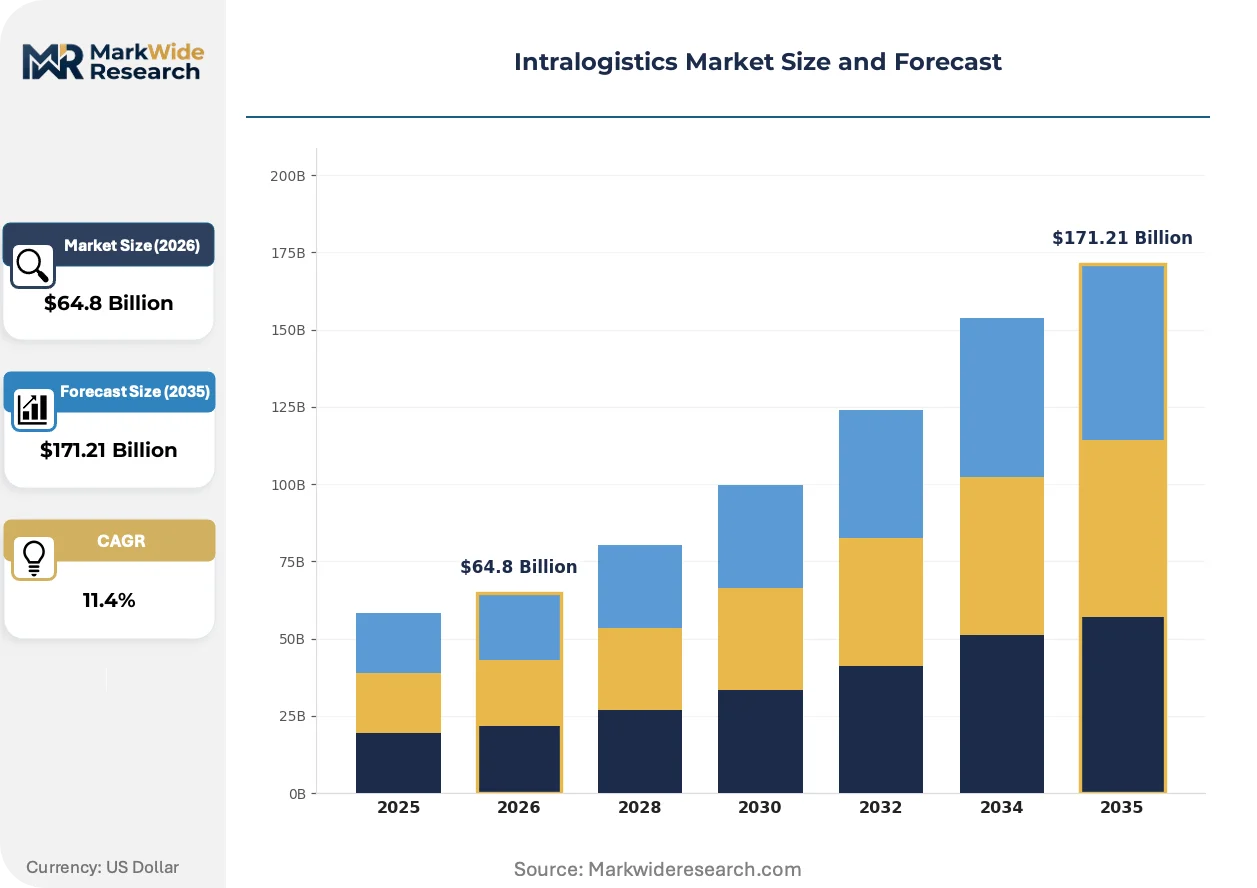
| Market Size in 2026 | $64.8 Billion |
| Market Size in 2035 | $171.21 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Automated Guided Vehicles, Conveyor Systems, Robotics, Warehouse Management Systems Application: Retail, Manufacturing, E-commerce, Food & Beverage End User: Third-Party Logistics, Distributors, Manufacturers, Warehousing Providers Service Type: Consulting, System Integration, Maintenance, Software Development |
| Companies Covered | Vanderlande, FORTNA, Daifuku, Kardex, Swisslog, Dematic, WITRON, Bastian Solutions, KNAPP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intralogistics Market Strategic Shifts
Artificial intelligence and edge computing architectures are reshaping how warehouse operators balance throughput velocity against energy consumption and labor availability.
Computer vision-guided robotic piece-picking is digitizing order fulfillment workflows in apparel and electronics e-commerce. Fashion retailers in Germany and the United Kingdom are deploying these systems to handle soft-goods variability without pre-programmed SKU data. The technology is digitizing inventory handling by converting unstructured bin environments into machine-readable picking sequences that adapt to real-time demand signals.
EPA emissions frameworks for industrial equipment are accelerating forklift electrification timelines in the United States. Warehouse operators in California and New York face compressed compliance deadlines for phasing out propane and diesel-powered material handling equipment. Cold storage and food distribution facilities are most affected, responding by preponing capital replacement cycles and negotiating battery supply agreements with domestic manufacturers.
Service contract unbundling is fragmenting how warehouse operators procure automation equipment. Large 3PL providers in the Netherlands and Belgium are separating hardware acquisition from software licensing and maintenance services, forcing original equipment manufacturers to defend recurring revenue through performance-based uptime guarantees rather than bundled service packages. This pattern is most visible in parcel and postal sortation networks where operational continuity carries premium contractual penalties.
Intralogistics Market Segmentation
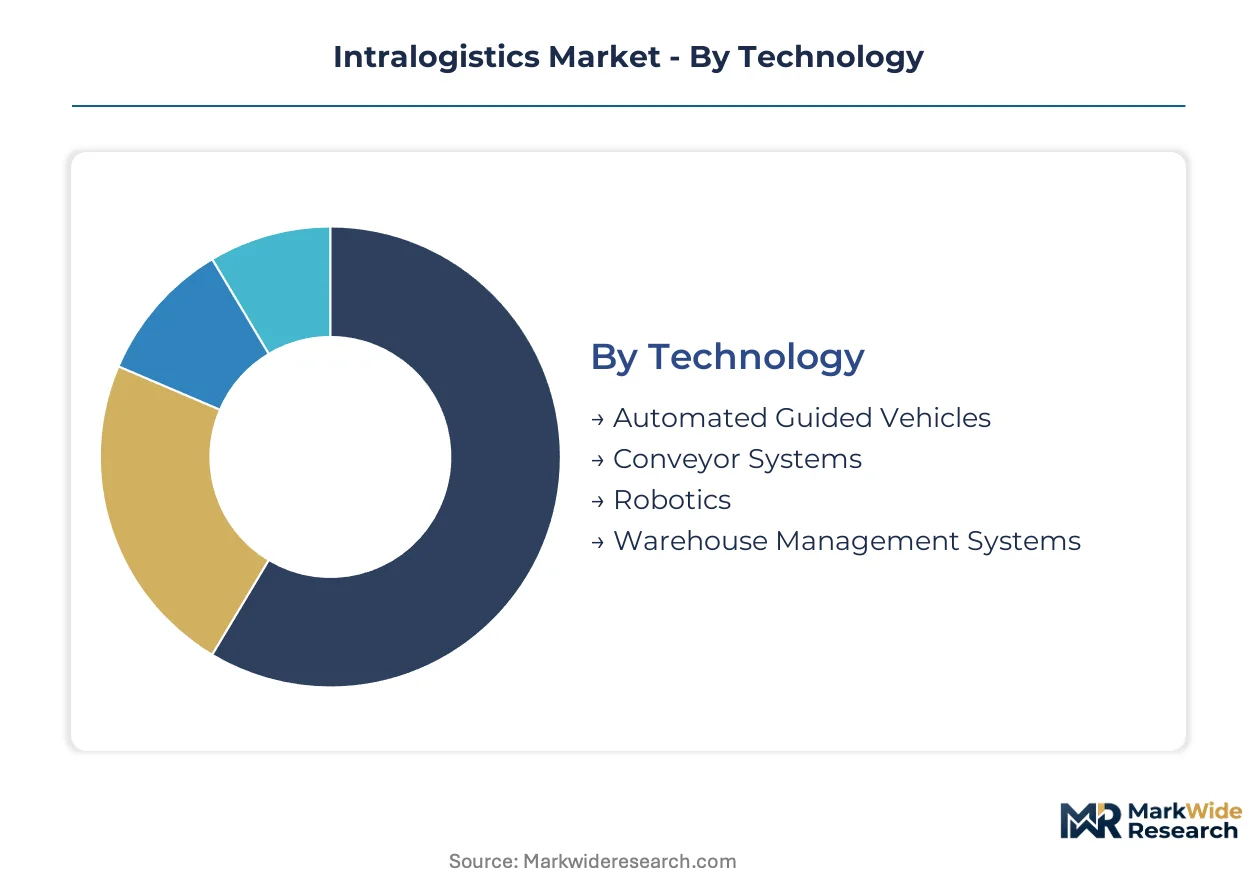
Intralogistics technology selection hinges on throughput velocity, SKU complexity, and facility age. Application context determines whether operators prioritize adaptive robotics or proven conveyor infrastructure. End-user procurement power and service bundling preferences further fragment vendor engagement models.
Technology:
Equipment choice spans fixed infrastructure to adaptive systems, with capital intensity and flexibility trading off across the spectrum.
- Automated Guided Vehicles:Lithium-ion powered units navigate warehouse floors via magnetic tape, laser guidance, or vision-based pathfinding. German automotive manufacturers and Dutch pharmaceutical distributors are electrifying fleets fastest to meet EU Green Deal carbon timelines and avoid municipal diesel restrictions in Stuttgart and Rotterdam.
- Conveyor Systems:Belt and roller configurations handle bulk material flow at throughputs exceeding 10,000 items per hour. Established e-commerce fulfillment centers in the United States retain these systems for predictable parcel volumes, though brownfield integration with modern warehouse management systems demands costly middleware development.
- Robotics:Articulated arms and mobile manipulators execute piece-picking, palletizing, and depalletizing with adaptive grippers. Vision-guided systems are penetrating apparel and electronics fulfillment in the United Kingdom and Germany where SKU proliferation outpaces fixed automation.
- Warehouse Management Systems:Software platforms orchestrate inventory tracking, order routing, and labor allocation through algorithmic optimization. Cloud-native deployments are displacing on-premise installations among mid-size 3PL providers seeking faster deployment cycles.
Established volume favors conveyor systems; emerging adoption favors robotics.
Application:
Operational requirements diverge sharply between temperature-controlled environments and high-velocity consumer fulfillment.
- Retail:Store replenishment and omnichannel fulfillment demand seasonal surge capacity and returns processing infrastructure. European fashion retailers are retrofitting regional distribution centers with robotic sortation to handle unpredictable e-commerce return volumes.
- Manufacturing:Just-in-time component delivery and finished goods staging require tight enterprise resource planning integration. Automotive plants in Germany and the United States are deploying automated guided vehicles for sequenced parts delivery to assembly lines.
- E-commerce:Same-day delivery service-level agreements compress order cycle times to under four hours. This application is climbing the fastest as operators replace fixed infrastructure with adaptive systems capable of handling millions of SKUs without pre-programmed handling rules.
- Food & Beverage:Temperature-controlled storage and handling of deformable packaging formats creates automation complexity. Cold chain operators face EPA and EU F-Gas Regulation compliance pressures while robotic grippers struggle with soft packaging variability.
Volume concentration sits with retail; technology refresh intensity peaks in e-commerce.
End User:
Procurement sophistication and capital access separate integrated operators from fragmented facility owners.
- Third-Party Logistics:Asset-light operators managing multi-tenant facilities prioritize flexible automation and robotics-as-a-service financing. Dutch and Belgian 3PLs are unbundling hardware from software procurement to negotiate performance-based uptime guarantees.
- Distributors:Pharmaceutical and industrial parts distributors require lot-level traceability and serialized inventory control. Temperature-controlled automated storage and retrieval systems are penetrating biologics distribution networks serving cell and gene therapy manufacturers.
- Manufacturers:Captive distribution operations align intralogistics with production schedules and quality protocols. German automotive and pharmaceutical manufacturers are modernizing distribution networks with integrated warehouse management platforms.
- Warehousing Providers:Real estate-focused operators lease space and increasingly partner with automation vendors for turnkey system deployment. Indian organized retail and pharmaceutical distribution in Mumbai and Delhi remain below automation saturation.
Capital depth favors manufacturers; financing innovation favors third-party logistics.
Service Type:
Revenue models are fragmenting as operators separate upfront system design from ongoing performance commitments.
- Consulting:Facility design and workflow optimization services precede capital deployment. Digital twin simulation is compressing deployment risk by enabling virtual commissioning of automated storage and retrieval systems before physical installation.
- System Integration:Mechanical installation, controls programming, and software configuration deliver turnkey automation. Controls engineering talent scarcity in Germany and the United States is extending project timelines and inflating labor costs.
- Maintenance:Preventive and corrective services preserve uptime for high-throughput sortation systems. Service contract unbundling is forcing original equipment manufacturers to defend recurring revenue through uptime guarantees rather than bundled packages.
- Software Development:Custom warehouse management system extensions and middleware for legacy integration address brownfield complexity. Legacy warehouse management system integration demands expensive middleware development for decade-old software stacks.
Revenue stability favors maintenance; margin expansion favors software development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances are reshaping intralogistics infrastructure investments, with manufacturing hubs expanding automated storage capacity to handle volatile cross-border flows while consumer markets prioritize last-mile fulfillment velocity.
Germany
Automotive sequenced parts delivery and pharmaceutical cold chain expansion dominate capital allocation. The EU Green Deal accelerates lithium-ion forklift fleet conversions in Stuttgart and Munich distribution clusters. Bavarian automotive plants deploy automated guided vehicles for just-in-time assembly line feeding.
United States
E-commerce same-day delivery SLAs compress order cycle times below four hours in major metros. EPA emissions frameworks force propane forklift phaseouts in California and New York cold storage facilities. Chicago and Dallas fulfillment centers lead adaptive robotics adoption for returns processing complexity.
China
Domestic consumption growth strains warehouse automation capacity in Yangtze River Delta manufacturing zones. Dual carbon goals under MIIT guidance push battery chemistry localization for automated guided vehicles. Shenzhen and Shanghai e-commerce operators refresh conveyor infrastructure for parcel volume surges.
Netherlands
Rotterdam port logistics and multi-tenant 3PL facilities drive robotics-as-a-service financing innovation. REACH chemical compliance extends battery approval timelines for automated guided vehicle deployments. Eindhoven region pharmaceutical distributors invest in temperature-controlled automated storage for biologics.
India
Organized retail and pharmaceutical distribution in Mumbai and Delhi remain below automation saturation thresholds. PLI scheme incentives attract warehouse management system providers to establish local integration capabilities. Bangalore e-commerce fulfillment centers pilot robotic piece-picking for apparel variability.
Intralogistics Market Competitive Environment
On the supply side, the industry is consolidating around integrated system providers capable of spanning mechanical hardware, controls engineering, and software orchestration. Three strategic archetypes dominate: Japanese conglomerates with captive conveyor manufacturing, European specialists in high-throughput sortation, and software-centric platforms integrating third-party robotics. Competitive moves concentrate on vertical integration into battery supply chains and geographic expansion through local system integration partnerships.
Among Japanese industrial conglomerates, Daifuku Co., Ltd. exemplifies the vertically integrated archetype with in-house conveyor component production. European specialists in parcel sortation include Vanderlande and Dematic, representing the high-throughput hardware tier. KNAPP AG occupies a position emphasizing software-driven warehouse management platforms that orchestrate heterogeneous robotic fleets.
| Leading Market Players |
|---|
| Vanderlande |
| FORTNA |
| Daifuku |
| Kardex |
| Swisslog |
| Dematic |
| WITRON |
| Bastian Solutions |
| KNAPP |
| Others |
Value Chain & Pricing Dynamics
The Rotterdam-Antwerp logistics corridor anchors European intralogistics equipment flows, where freight cost volatility feeds upstream into lithium-ion battery pricing and downstream into three-tier equipment leasing structures across premium automation, standard conveyor systems, and economy-grade material handling.
Pricing Analysis
Industrial OEM buyers anchor a hybrid pricing structure blending project-based system integration with robotics-as-a-service subscriptions. Three-tier pricing stratifies across premium certified systems meeting EU Green Deal carbon thresholds, standard lithium-ion configurations, and economy-grade lead-acid alternatives. Pricing pressure stems from cathode material cost volatility concentrated in Chinese processing facilities. Mid-size 3PL providers exhibit highest price sensitivity, while pharmaceutical distributors prioritize uptime guarantees over capital expenditure.
Supply Chain Analysis
Extended payment terms from European system integrators to Korean and Japanese battery cell manufacturers are compressing working capital cycles throughout the supplier base. Component sourcing draws from China for cathode materials, South Korea for cell manufacturing, and Germany for precision mechanical components. Single-source vulnerability concentrates in lithium carbonate refining capacity. Distribution runs through regional system integration hubs in Stuttgart, Chicago, and Shanghai before final commissioning at operator facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated e-commerce operators capable of dictating performance-based uptime terms, fragmenting vendor pricing power across the equipment base.
For Market Incumbents: Build switching-cost moats through captive software ecosystems that lock warehouse management system data architectures. Deepen backward integration into battery pack assembly to offset Korean cell supplier pricing power. Defend against emerging robotics-as-a-service entrants by bundling predictive maintenance algorithms with hardware leases. For New Entrants and Emerging Players: Pursue white-space penetration in Indian pharmaceutical distribution, where Mumbai and Delhi automation saturation remains below European benchmarks. Target robotics-as-a-service financing for mid-size 3PL providers in Belgium and the Netherlands. Lead with cloud-native warehouse management platforms requiring minimal legacy middleware development. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates divesting non-core conveyor manufacturing divisions. Long-term viability hinges on software-orchestration capabilities rather than mechanical hardware production. Monitor EPA enforcement acceleration in California and New York as an inflection signal for electrified fleet replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Robotics-as-a-Service Financing | Mid-size 3PL providers in the Netherlands access automation without capital expenditure barriers. |
| Backward Integration into Battery Assembly | European system integrators reduce dependency on Korean cell manufacturer pricing volatility. |
| Cloud-Native WMS Deployment | Operators bypass legacy middleware costs for brownfield robotic integration projects. |
| Digital Twin Virtual Commissioning | Pharmaceutical distributors in Germany compress deployment risk for cold chain automation. |
| EU Green Deal Compliance Certification | Automotive OEMs in Stuttgart secure municipal operating permits for electrified fleets. |
Study Parameters
The analysis maps automated guided vehicles, conveyor systems, robotics, and warehouse management platforms, each validated through warehouse operations directors, OEM procurement managers, system integration engineers, and aftermarket service heads. Primary interview findings triangulate against customs trade records, SEC equipment manufacturer filings, EU ETS carbon registry data, and pharmaceutical distribution facility databases. Bottom-up installation counts reconcile with top-down equipment spending estimates across the analysis window.
Assumptions held fixed include current EU Green Deal carbon reduction timelines and existing lithium-ion battery chemistry standards, while variables include robotics adoption velocity and 3PL consolidation patterns. Segmentation dimensions span technology type, application vertical, end-user procurement sophistication, and service model bundling. CAGRs derive from equipment replacement cycle analysis and e-commerce fulfillment capacity expansion trajectories. Industry-specific inputs incorporate SKU proliferation rates and same-day delivery SLA penetration.
Sensitivities concentrate around battery supply disruption, REACH chemical approval delays, and robotics-as-a-service financing availability. Forecasts reflect documented assumptions regarding electrification mandates and labor cost trajectories. Macroeconomic contraction, regulatory timeline acceleration, or adaptive gripping technology breakthroughs would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Palletizing Systems Market
Industrial Automation
Industrial Internet Connectivity Tracker Market
Industrial Automation
US and Europe Warehouse Automation Market
Industrial Automation
Mining Automation Systems Market
Industrial Automation
Global Industrial Automation and Control Systems Market
Industrial Automation
Europe Industrial Automation Software Market
Industrial Automation
Tilt Tray Sorter Market
Industrial Automation
Europe Water Automation and Instrumentation Market
Industrial Automation
UK Industrial Automation System Integrator Market
Industrial Automation
Monitor Arm Market
Industrial Automation
Robotic Paint Booth Market
Industrial Automation
Industrial Automation Software Market
Industrial Automation
Asia Pacific Retail Automation Market
Industrial Automation
Digital Transformation in Manufacturing Market
Industrial Automation
Mini-Load Systems Market
Industrial Automation
Europe Process Automation Market