
 Lauryl Dimethyl Amine Oxide Market | 2026-2036
Lauryl Dimethyl Amine Oxide Market Size, Share, and Industry Trends Forecast 2026-2036
Lauryl Dimethyl Amine Oxide Market Outlook
The gap between pharmaceutical-grade and industrial-grade lauryl dimethyl amine oxide is realigning procurement patterns across the value chain. BASF SE leverages its integrated alkylene oxide feedstock position to sustain cost discipline in commodity liquid grades. Evonik Industries AG anchors its portfolio on high-purity concentrates for European cosmetics formulators. Stepan Company competes through regional manufacturing scale in North American household cleaning supply chains.
Lauryl dimethyl amine oxide is a tertiary amine oxide prepared by oxidizing lauryl dimethylamine with hydrogen peroxide, typically supplied at active concentrations ranging from 30% to 50% in aqueous solution and functioning primarily as a mild amphoteric surfactant that reduces irritation in anionic systems while boosting viscosity and foam stability. The liquid product type dominates volume flows into industrial cleaning applications where dilution economics favor bulk tanker delivery, whereas powder and granular forms capture premium positioning in personal care dry formulations where processing latitude and shelf stability determine specification value. End-user demand splits structurally between household cleaning, which occupies mature volume pools tied to private-label dishwasher and laundry products, and cosmetics, where sulfate-free and mild-surfactant trends are expanding specification premiums for high-active concentrates.
EPA industrial discharge standards and REACH Article 57 substance restrictions are tightening biodegradability and aquatic toxicity benchmarks for amine oxide surfactants entering wastewater streams. FDA oversight of cosmetic ingredient safety through the Modernization of Cosmetics Regulation Act interacts with state-level California Proposition 65 enforcement to elevate documentation burdens for suppliers serving personal care channels. BIS certification requirements for surfactant imports into India add a parallel compliance layer affecting export-oriented producers. Stakeholders must monitor how regulatory divergence across these jurisdictions reshapes formulation substitution risks and qualification timelines for new supply relationships.
Market Dynamics
Sulfate-free formulation mandates across personal care are compressing specification cycles for amphoteric surfactants, forcing raw material suppliers to recertify active concentrations under tighter biodegradability thresholds.
Growth Catalysts
- REACH Article 57 substance restrictions:ECHA's tightening aquatic toxicity benchmarks are disqualifying legacy quaternary ammonium alternatives, redirecting formulator procurement toward amine oxide chemistries with superior biodegradation profiles.
- Sulfate-free personal care:Consumer brands in Southeast Asian manufacturing clusters are expanding mild-surfactant portfolios, concentrating demand for high-active concentrates that reduce irritation in anionic systems.
- Hydrogen peroxide oxidation efficiency:Continuous processing improvements in tertiary amine oxidation are lowering per-unit production costs for 30-50% aqueous solutions supplied to industrial cleaning channels.
Market Restraints
- Lauryl alcohol feedstock volatility:Palm kernel and coconut oil price swings transmit directly into amine oxide cost structures, compressing margin visibility for contract producers without backward integration into fatty alcohol supply.
- Supply concentration in German alkylene oxide hubs:BASF SE's integrated feedstock position creates procurement dependency risks for non-integrated formulators seeking cost-competitive commodity grades.
- Technical ceiling in powder formulation stability:Hygroscopicity limitations in granular amine oxides restrict shelf-life extension for dry personal care products, capping premium positioning against synthetic alternatives.
Strategic Opportunities
- Indian BIS certification pathway:Import qualification requirements for surfactants are creating first-mover advantages for suppliers establishing certified local distribution ahead of domestic production scale-up.
- EPA industrial discharge compliance services:Wastewater treatment operators are bundling amine oxide specification consulting with chemical supply contracts, opening value-added revenue streams beyond commodity sales.
- Bio-based lauryl alcohol convergence:Fermentation-derived fatty alcohol supply is intersecting with carbon accounting mandates, enabling premium positioning for mass-balance-certified amine oxides in European cosmetics channels.
Industry Challenges
- Modernization of Cosmetics Regulation Act documentation:FDA's expanded ingredient safety filing requirements are extending qualification timelines for new suppliers entering US personal care channels.
- ISO 16128 natural origin certification complexity:Calculating renewable carbon indices for amine oxides with mixed petrochemical and bio-based feedstocks demands specialized analytical capabilities scarce among mid-tier producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lauryl Dimethyl Amine Oxide Market |
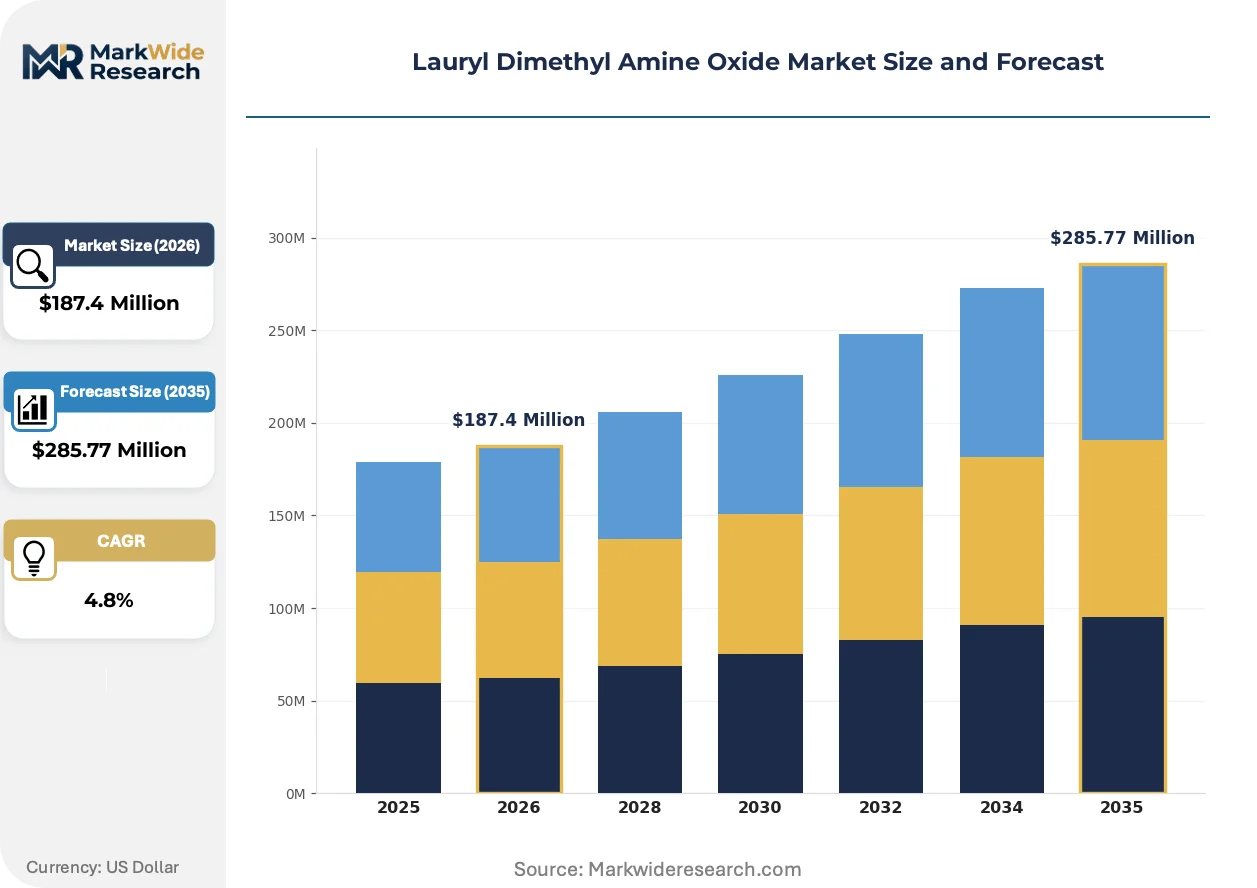
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granular, Concentrate End User: Cosmetics, Household Cleaning, Industrial Cleaning, Personal Care Application: Surfactant, Foam Stabilizer, Emulsifier, Antistatic Agent Distribution Channel: Online, Retail, Distributors, Direct Sales |
| Companies Covered | Evonik Industries AG, Clariant AG, BASF SE, The Lubrizol Corporation, Enaspol a.s., Kao Corporation, Lonza Group Ltd., Oxiteno, Stepan Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lauryl Dimethyl Amine Oxide Market Strategic Shifts
Formulation science and regulatory chemistry are converging to redefine how amphoteric surfactants qualify for premium positioning across personal care and industrial end-uses.
Micro-encapsulation technology for controlled-release amine oxide actives is decentralizing the traditional concentration-vs-stability tradeoff in dry shampoo and powder cleanser formulations. European cosmetics laboratories are piloting lipid-shell encapsulation at pilot scale, enabling 70%+ active loading without caking or moisture uptake. This is decentralizing supply relationships by letting regional compounders compete on formulation IP rather than bulk active sourcing alone.
California Proposition 65 enforcement expansion is forcing ingredient disclosure granularity that REACH alone never required. Personal care brands serving dual US-EU markets are harmonizing to the stricter California standard, elevating documentation burdens for amine oxide suppliers. The cosmetics segment is responding by consolidating supplier panels to those with dedicated regulatory affairs functions capable of managing multi-jurisdiction filing.
Contract manufacturing concentration in Vietnamese and Indonesian surfactant processing zones is compressing traditional distributor layers. Multinational hygiene product companies are establishing direct technical service relationships with these Southeast Asian producers, bypassing European and North American trading houses that historically intermediated specification negotiations. This channel compression is most visible in household cleaning supply chains where tanker-scale volumes justify dedicated technical account management.
Lauryl Dimethyl Amine Oxide Market Segmentation
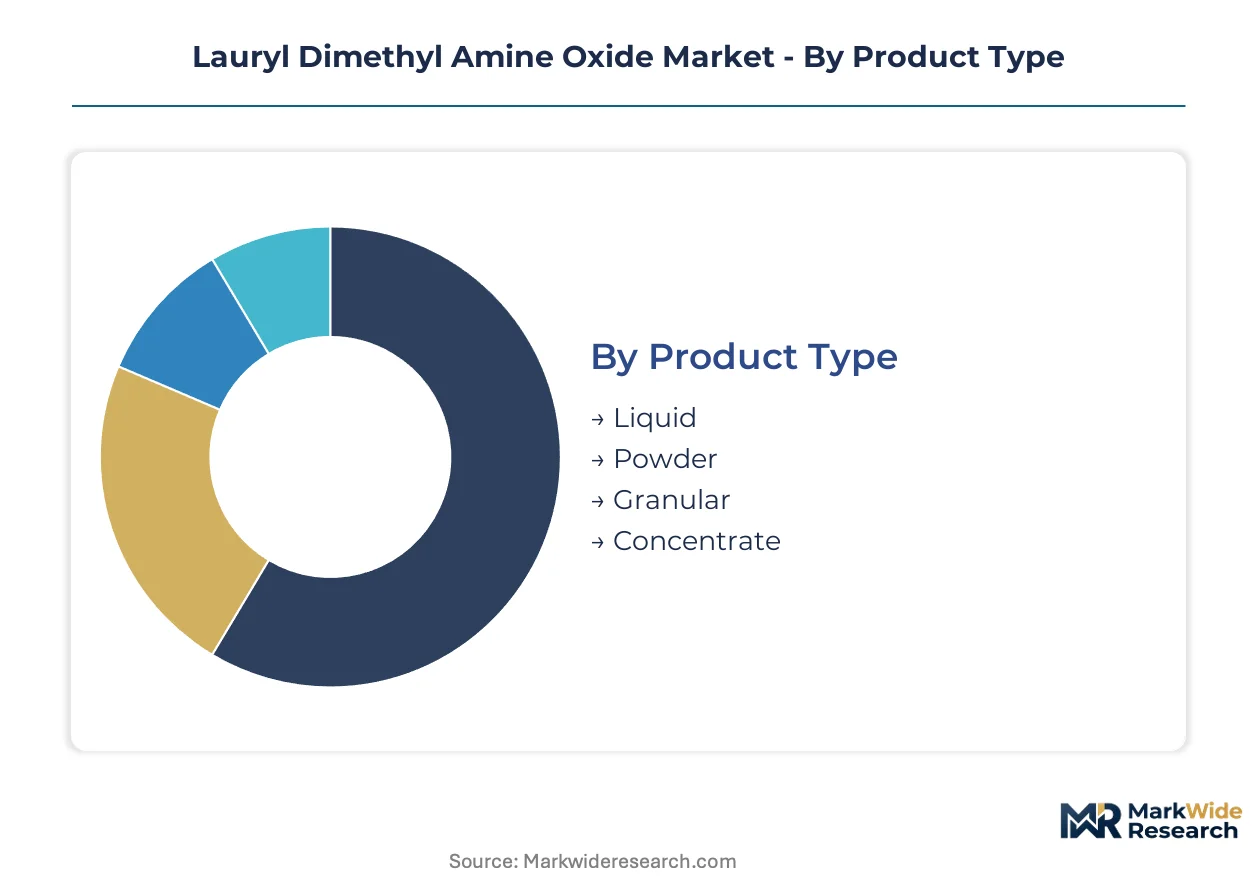
Lauryl dimethyl amine oxide procurement patterns diverge sharply across physical form, end-use chemistry, and channel economics. Specification premiums concentrate where formulation flexibility intersects with regulatory qualification burdens.
Product Type:
Physical state determines handling infrastructure, active concentration economics, and shelf-stability requirements across personal care and industrial supply chains.
- Liquid:Supplied as 30-50% aqueous solutions in bulk tanker configurations, this form dominates industrial cleaning procurement where dilution economics favor pump-and-transfer delivery systems. Demand concentrates in North American household cleaning supply chains tied to private-label dishwasher and laundry product manufacturing.
- Concentrate:High-active formulations above 50% active content command specification premiums in European cosmetics channels where sulfate-free mild-surfactant trends are compressing formulation cycles. Southeast Asian manufacturing clusters are expanding concentrate procurement to serve multinational hygiene product companies seeking viscosity-building and irritation-reduction properties in anionic systems.
- Powder:Spray-dried forms enable dry blending in powder cleanser and bath product formulations.
- Granular:Free-flowing particulate grades address caking resistance requirements in high-humidity storage environments.
Liquid leads on scale; concentrate leads on momentum.
End User:
Application chemistry and regulatory exposure create divergent margin profiles across consumer-facing and industrial discharge environments.
- Household Cleaning:Mature volume pools in dishwasher detergents and laundry products generate baseline demand for commodity-grade liquid amine oxides. EPA industrial discharge standards and REACH aquatic toxicity benchmarks are elevating biodegradability documentation requirements for suppliers serving this channel.
- Cosmetics:Sulfate-free and mild-surfactant formulation mandates are expanding specification premiums for high-purity concentrates. FDA Modernization of Cosmetics Regulation Act documentation burdens and California Proposition 65 enforcement are consolidating supplier panels toward those with dedicated multi-jurisdiction regulatory affairs capabilities.
- Industrial Cleaning:Wastewater treatment operators bundle amine oxide specification consulting with chemical supply contracts, creating value-added revenue streams beyond commodity sales.
- Personal Care:Shampoo, body wash, and facial cleanser formulations drive demand for foam-stabilizing amphoteric surfactants with reduced irritation profiles.
Household cleaning anchors volume; cosmetics commands margin expansion.
Application:
Functional role in formulation matrices determines active concentration requirements and compatibility testing protocols.
- Surfactant:Primary cleansing function in anionic systems demands precise active concentration management to achieve mildness without sacrificing foaming performance. Micro-encapsulation technology pilots in European cosmetics laboratories are enabling controlled-release surfactant actives with 70%+ active loading.
- Foam Stabilizer:Viscosity-building and bubble persistence properties concentrate demand in sulfate-free personal care formulations where traditional foam boosters face substitution pressure.
- Emulsifier:Oil-water phase stabilization applications span personal care lotions and industrial cleaning degreasers.
- Antistatic Agent:Surface charge modification functions in textile and plastic processing applications.
Surfactant claims the largest application share; foam stabilizer gains share fastest.
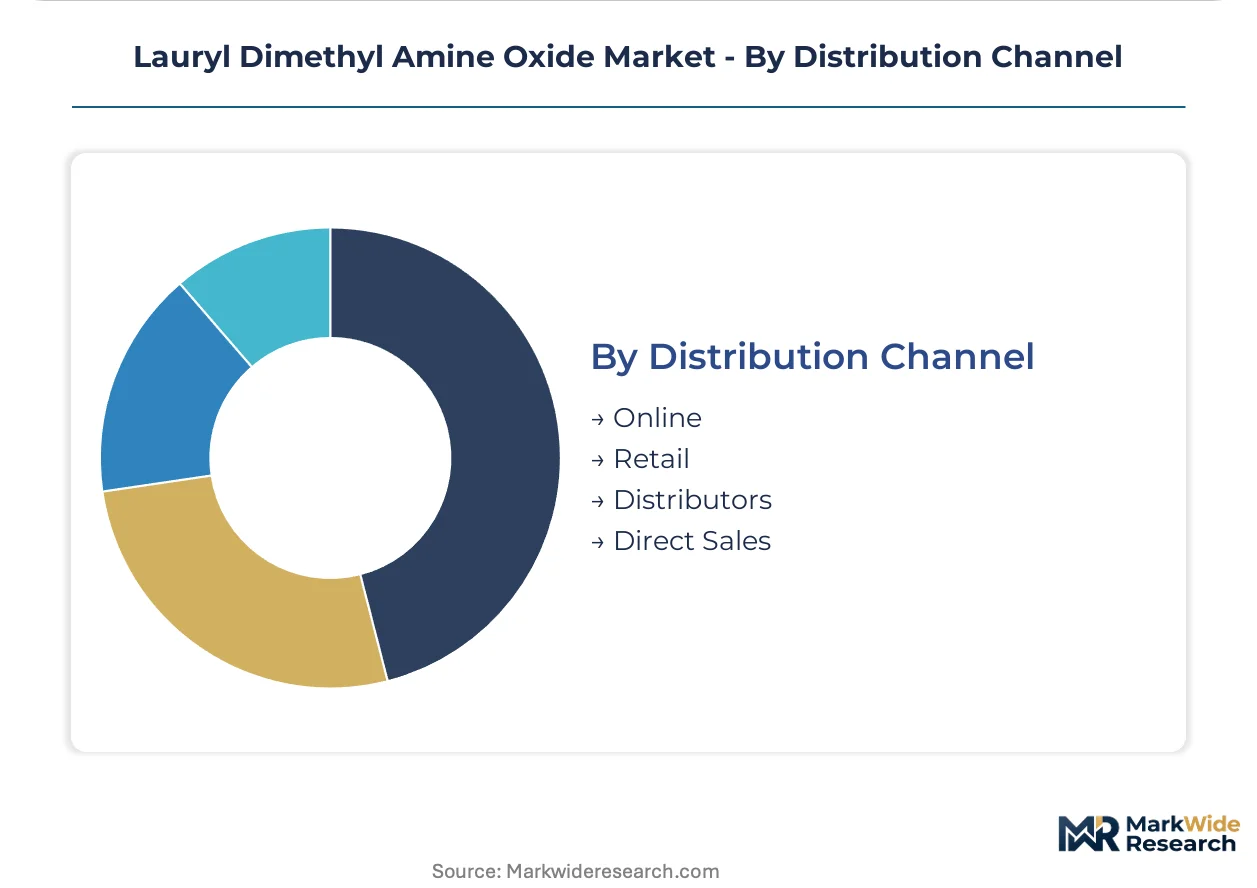
Distribution Channel:
Channel structure reflects volume scale, technical service intensity, and geographic proximity to manufacturing clusters.
- Distributors:Traditional intermediaries retain relevance in fragmented personal care formulator bases requiring small-batch flexibility and regulatory documentation support. Vietnamese and Indonesian surfactant processing zones are compressing distributor layers as multinational hygiene product companies establish direct technical service relationships.
- Direct Sales:Tanker-scale volumes in industrial cleaning and household cleaning supply chains justify dedicated technical account management, bypassing European and North American trading houses that historically intermediated specification negotiations.
- Online:Digital procurement platforms serve specialty chemical buyers seeking rapid specification comparison and sample fulfillment.
- Retail:Packaged consumer-facing products in small-format configurations.
Distributors retain formulator access; direct sales capture industrial volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States diverge in feedstock integration depth, with German producers commanding captive alkylene oxide supply while US formulators rely more heavily on merchant fatty alcohol markets. Southeast Asian manufacturing clusters are absorbing contract volume as multinational hygiene companies regionalize supply chains. Regulatory fragmentation across REACH, EPA, and BIS jurisdictions is reshaping qualification requirements for cross-border suppliers.
United States
Household cleaning manufacturers in the Midwest and Gulf Coast drive baseline demand for commodity liquid grades. EPA industrial discharge standards under the Clean Water Act elevate biodegradability documentation burdens for surfactant suppliers. Chicago and Houston processing zones concentrate private-label dishwasher and laundry product formulation activity.
Germany
European cosmetics formulators in the Rhine-Ruhr corridor command premium pricing for high-purity concentrates. ECHA's REACH Article 57 substance restrictions disqualify legacy quaternary ammonium alternatives, redirecting procurement toward amine oxide chemistries. Ludwigshafen and surrounding alkylene oxide hubs sustain integrated feedstock positions for commodity-grade producers.
China
Domestic personal care brands in the Yangtze River Delta are expanding sulfate-free formulation portfolios. MIIT and MEE guidelines on industrial wastewater discharge tighten aquatic toxicity benchmarks for surfactant manufacturing. Shanghai and Zhejiang processing zones concentrate contract production for multinational hygiene companies.
India
Import-dependent formulators in Maharashtra and Gujarat face BIS certification requirements for surfactant raw materials. CDSCO and FSSAI oversight of cosmetic ingredient safety extends qualification timelines for new supply relationships. Mumbai-Pune industrial corridor anchors domestic contract manufacturing for regional personal care brands.
Vietnam
Multinational hygiene product companies are establishing direct technical service relationships with Ho Chi Minh City surfactant processors. ASEAN harmonization of cosmetic ingredient regulations creates parallel compliance pathways alongside national standards. Southern manufacturing zones absorb household cleaning volume previously routed through European trading houses.
Lauryl Dimethyl Amine Oxide Market Competitive Environment
Top-tier vendors anchor integrated feedstock positions, while mid-scale compounders compete on formulation flexibility and regional regulatory expertise. The vendor base stratifies across three tiers: alkylene oxide-integrated multinationals, regional surfactant specialists with dedicated regulatory affairs functions, and contract manufacturers concentrated in Southeast Asian processing zones. Two dominant competitive moves are reshaping positioning: backward integration into fatty alcohol supply to mitigate palm kernel and coconut oil price volatility, and geographic expansion through BIS certification pathways in India ahead of domestic production scale-up.
Among European-integrated multinationals, BASF SE and Evonik Industries AG exemplify divergent strategic archetypes. BASF represents the commodity-scale vector with captive feedstock discipline, while Evonik occupies the high-purity concentrate position serving cosmetics formulators. Stepan Company anchors the North American regional manufacturing scale archetype. Clariant AG and Lonza Group Ltd. sit within the specialty chemical tier where regulatory affairs capabilities determine personal care channel access. Kao Corporation and Oxiteno represent Asia-Pacific and Latin American regional champions respectively, with Enaspol a.s. exemplifying the Central European specialist model.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Clariant AG |
| BASF SE |
| The Lubrizol Corporation |
| Enaspol a.s. |
| Kao Corporation |
| Lonza Group Ltd. |
| Oxiteno |
| Stepan Company |
| Others |
Value Chain & Pricing Dynamics
Sulfate-free formulation mandates from European cosmetics brands are compressing specification cycles and forcing contract producers to recertify active concentrations under tighter biodegradability thresholds, which concentrates procurement power among integrated suppliers with captive hydrogen peroxide oxidation capacity and widens price spreads between commodity liquid grades and high-purity concentrates.
Pricing Analysis
Capacity additions in Vietnam and Indonesia are reshaping price floors for commodity liquid grades supplied to household cleaning channels. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by REACH compliance tier and active concentration purity. Cost compression in standard-grade liquids is intensifying because palm kernel oil volatility transmits directly into fatty alcohol feedstock costs. Private-label dishwasher detergent manufacturers exhibit highest price sensitivity, while European sulfate-free cosmetics formulators show least sensitivity due to qualification switching costs.
Supply Chain Analysis
Empty container repositioning and bulk tanker cleaning cycles create reverse-logistics overhead that commodity-grade suppliers absorb through minimum order quantities. Feedstock supply concentrates in Germany, Malaysia, and the Philippines where palm kernel and coconut oil processing clusters anchor lauryl alcohol output. Hydrogen peroxide oxidation capacity, aqueous solution blending infrastructure, and spray-drying equipment for powder grades constitute critical component dependencies. Single-source vulnerability around German alkylene oxide hubs exposes non-integrated formulators to allocation risk during feedstock crimp periods. Distribution runs through direct technical service relationships for tanker-scale industrial volumes and regional distributor networks for personal care formulators requiring small-batch flexibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through hydrogen peroxide oxidation efficiency gains and premium-tier concentrate positioning in European cosmetics channels where sulfate-free certification commands specification premiums.
For Market Incumbents: Deploy captive alkylene oxide integration as the primary lever. BASF SE and Evonik Industries AG should deepen upstream control over fatty alcohol supply to neutralize palm kernel oil volatility. Invest in dedicated regulatory affairs functions capable of managing FDA Modernization of Cosmetics Regulation Act documentation and California Proposition 65 filing burdens, as these compliance capabilities are consolidating supplier panels and locking out mid-tier competitors without multi-jurisdiction expertise. For New Entrants and Emerging Players: Micro-encapsulation technology for controlled-release amine oxide actives offers a technology-first wedge into European dry shampoo and powder cleanser formulations where 70%+ active loading without caking represents unmet demand. Target Indian BIS certification pathways ahead of domestic production scale-up, as import qualification requirements create first-mover advantages. Pursue direct technical service relationships with Vietnamese and Indonesian surfactant processors rather than competing through European and North American trading house intermediation. For Investors and Strategic Acquirers: Asymmetric upside sits with regional surfactant specialists possessing dedicated regulatory affairs capabilities and established BIS certification in India. The five-to-ten-year viability window favors acquisition targets with backward integration into fatty alcohol supply or fermentation-derived bio-based lauryl alcohol partnerships enabling mass-balance certification. Monitor EPA industrial discharge standard tightening and REACH Article 57 substance restriction expansion as inflection indicators that would accelerate substitution away from legacy quaternary ammonium alternatives toward amine oxide chemistries.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fatty Alcohol Supply | Captive lauryl alcohol production insulates margin structures from palm kernel oil price volatility. |
| Green Manufacturing Transition | Fermentation-derived bio-based feedstock enables mass-balance certification for European cosmetics channels. |
| Long-term Supply Agreement | Tanker-scale offtake contracts with multinational hygiene companies secure volume visibility. |
| Joint Venture | Local production partnerships in India satisfy BIS certification requirements ahead of domestic scale-up. |
| Capacity Expansion | Hydrogen peroxide oxidation capacity additions in Southeast Asian clusters capture regional demand concentration. |
Study Parameters
Bottom-up cosmetics and household cleaning formulation modeling reconciled against top-down hydrogen peroxide oxidation capacity tracking forms the analytical core. Primary interviews with plant managers at German and Southeast Asian surfactant processing facilities, procurement leads at multinational hygiene product companies, technical R&D directors at European cosmetics formulators, and distribution channel partners in India validated demand assumptions. Secondary sources include customs and trade data for lauryl alcohol and amine oxide flows, Cefic surfactant industry reports, SEC 10-K filings from listed chemical producers, and ECHA REACH registration dossiers for aquatic toxicity benchmarking.
Historical trendline analysis of active concentration pricing spreads and specification premium trajectories informed projection frameworks. Segmentation dimensions modeled span physical form, end-use industry, application function, and regional regulatory cluster. CAGRs were derived from slope analysis of volume and value trendlines across the projection horizon. Industry-specific forecast inputs include hydrogen peroxide oxidation efficiency improvement curves and BIS certification timeline assumptions for Indian market entry.
The model holds under stable palm kernel and coconut oil feedstock availability; deviation in vegetable oil price volatility or REACH substance restriction acceleration would shift margin distribution between integrated and non-integrated producers. Forecasts reflect documented assumptions about sulfate-free formulation adoption rates and EPA discharge standard implementation timing. Practitioners should monitor ECHA aquatic toxicity benchmark revisions and California Proposition 65 enforcement expansion for early signals of qualification burden escalation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Electroplating Chemicals Market
Chemicals
Global Tetraacetylethylenediamine (TAED) Market
Chemicals
Global Chiral Chemicals Market
Chemicals
Indonesia Nitric Acid Market
Chemicals
Negative Photoresist Chemicals Market
Chemicals
Tanning Agents Market
Chemicals
Global Diacetone Alcohol Market
Chemicals
Morpholine Market
Chemicals
Global Hydrogen Fluoride Market
Chemicals
Middle East and Africa Methyl Acrylate Market
Chemicals
Methyl P-Hydroxybenzoate Market
Chemicals
Perchloric Acid Market
Chemicals
Glycerol Carbonate Market
Chemicals
Asia-Pacific Surface Treatment Chemicals Market
Chemicals
India Ethoxylates Market
Chemicals
Isooctyl Alcohol Market