
 Schneider's Insect Medium Market | 2026-2036
Schneider's Insect Medium Market Size, Share, and Industry Trends Forecast 2026-2036
Schneider's Insect Medium Market Insights
Buyer concentration among contract research organizations and university core facilities is hardening as institutional procurement shifts toward multi-year supply agreements. Thermo Fisher Scientific leverages its distribution breadth to serve high-volume academic purchasers. HiMedia Laboratories anchors its position through cost-competitive powdered medium formulations tailored to emerging research markets. Merck sustains premium positioning via stringent quality certifications that appeal to pharmaceutical-grade insect cell applications.
Schneider's Insect Medium comprises a chemically defined nutrient formulation optimized for Drosophila melanogaster and related dipteran cell lines, typically containing yeastolate, peptone, and buffered salts at pH 6.8–7.2 to support continuous cell propagation. The medium enables recombinant protein expression, viral vector production, and genetic screening protocols in biomedical and agricultural research settings. Liquid medium dominates current procurement volumes due to convenience in high-throughput screening workflows, while powdered medium commands attention from cost-sensitive laboratories seeking extended shelf stability. Research applications absorb the largest share of consumption, though commercial breeding operations represent an expanding usage category as insect-based biomanufacturing scales.
FDA oversight of cell culture reagents used in therapeutic development pathways shapes quality documentation requirements for suppliers targeting clinical translation. The EPA regulates insect-rearing facilities engaged in biocontrol agent production, creating compliance thresholds that favor validated medium formulations. ISO 13485 and GMP-adjacent standards increasingly filter procurement criteria at institutional buyers. Stakeholders must track evolving intersection points between research-grade and clinical-grade quality regimes as insect cell platforms migrate toward regulated bioproduction environments.
Market Dynamics
Academic procurement consolidation toward multi-year supply agreements is compressing vendor margins while elevating quality documentation requirements across the Schneider's Insect Medium supply base.
Growth Catalysts
- REACH framework compliance:ECHA registration mandates for chemical substances are standardizing formulation purity benchmarks across European research institutions, accelerating replacement of non-compliant legacy media.
- Recombinant protein production:Biopharmaceutical pipelines leveraging Drosophila S2 cells for therapeutic protein expression are expanding validated medium consumption at contract manufacturing organizations.
- Germany:Sustained federal funding for entomology infrastructure through the Deutsche Forschungsgemeinschaft is stabilizing demand from Max Planck Institute networks and technical universities.
Market Restraints
- Yeastolate supply volatility:Concentrated sourcing of this peptone derivative from fermentation facilities in China creates input cost instability during animal nutrition demand spikes.
- Liquid medium shelf constraints:Cold chain requirements for ready-to-use formulations limit distribution reach to laboratories lacking −20°C storage infrastructure in emerging research markets.
- Serum-free adaptation barriers:Cell line conditioning protocols required for chemically defined medium migration extend validation timelines at pharmaceutical-grade facilities.
Strategic Opportunities
- Japan:Underpenetrated agricultural biotechnology sector offers expansion potential as METI-funded insect farming initiatives for food protein gain regulatory clarity.
- Lyophilized powder formats:Extended ambient stability enables direct-to-laboratory e-commerce distribution, bypassing traditional distributor markups in cost-sensitive segments.
- ISO 13485 convergence:Diagnostic-grade certification pathways for insect cell substrates are opening clinical translation revenue streams previously restricted to mammalian platforms.
Industry Challenges
- Cell culture specialist scarcity:Dipteran cell line expertise concentrates in aging academic cohorts, constraining technical support capacity at scaling commercial breeding operations.
- GMP-adjacent documentation gaps:Research-grade batch records lack the audit trails required for pharmaceutical master file submissions, forcing costly requalification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Schneider's Insect Medium Market |
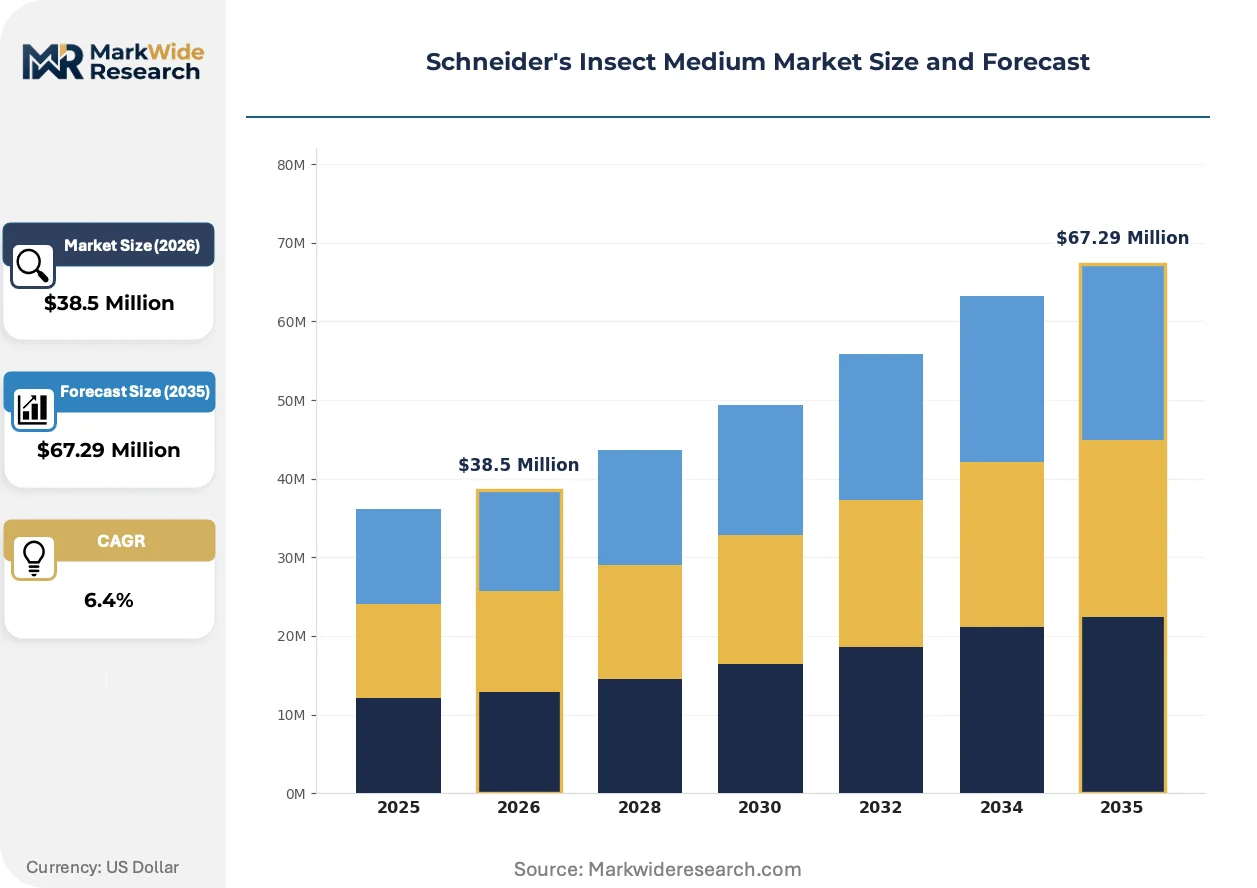
| Market Size in 2026 | $38.5 Million |
| Market Size in 2035 | $67.29 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Medium, Agar Medium, Powdered Medium, Gel Medium Usage Type: Research, Breeding, Educational, Commercial Distribution Channel: Online Retail, Distributors, Direct Sales, Specialty Stores Application: Biological Research, Entomology Studies, Ecosystem Analysis, Pest Control |
| Companies Covered | Merck, HiMedia Laboratories, Thermo Fisher Scientific, Sigma-Aldrich, US Biological, Bio-Techne, Corning, Atlanta Biologicals, Sartorius, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Schneider's Insect Medium Market Trends and Innovations
Chemically defined medium formulations are displacing traditional yeastolate-supplemented recipes as regulatory scrutiny intensifies on lot-to-lot variability in bioproduction environments.
Serum-free synthetic media is unifying nutrient delivery through precisely titrated lipid and carbohydrate substitutes. Contract research organizations in the United States are accelerating adoption to streamline FDA master file submissions for viral vector manufacturing. This unification is compressing the competitive gap between research-grade and clinical-grade formulation tiers.
EPA facility registration requirements for biocontrol agent production are mandating environmental release containment protocols at insect-rearing sites. The regulation forces medium suppliers to validate sterility assurance levels beyond traditional research-grade specifications. Agricultural biotechnology clusters in California and North Carolina are absorbing compliance costs through dedicated production line segregation.
Core facility consolidation is compressing vendor relationships toward sole-source agreements with integrated service bundles. University procurement offices in Germany and Japan are displacing spot purchasing through framework contracts covering media, cell lines, and technical training. This concentration is most visible at German Excellence Initiative institutions where multi-year tenders now predominate.
Schneider's Insect Medium Market Segmentation
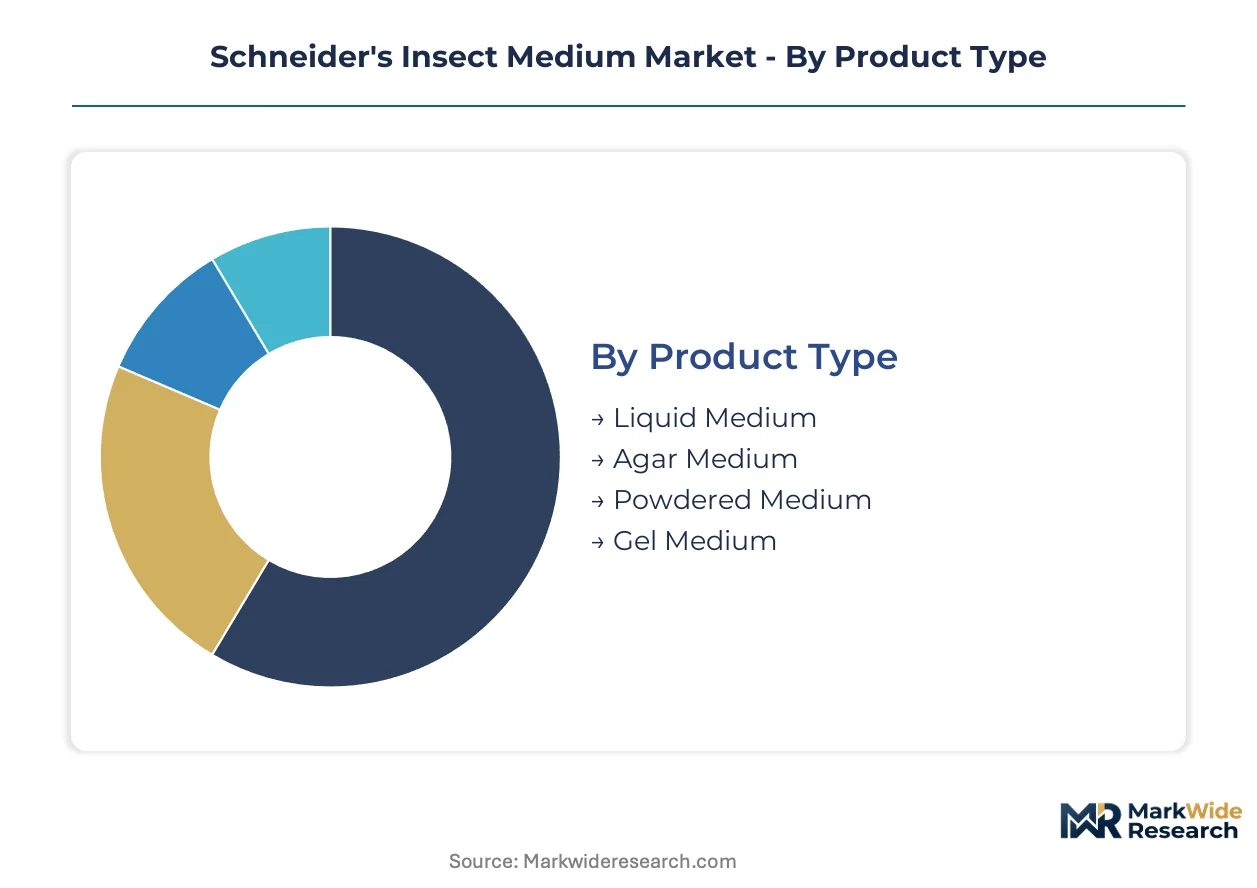
Schneider's Insect Medium procurement patterns diverge sharply across product formats, end-use environments, and supply chain configurations. Understanding these fault lines clarifies where formulation investments align with buyer willingness to pay for quality documentation versus convenience.
Product Type:
Cost sensitivity and storage infrastructure availability separate buyers in this dimension.
- Liquid Medium:Ready-to-use aqueous formulation buffered at pH 6.8–7.2 eliminates reconstitution steps. High-throughput screening facilities at German Max Planck Institutes and US contract research organizations absorb the largest procurement volumes despite cold chain dependencies.
- Powdered Medium:Lyophilized format extends ambient shelf stability to 24+ months, enabling stockpiling by cost-conscious university core facilities. HiMedia Laboratories anchors market position through competitive pricing in emerging research markets lacking −20°C infrastructure.
- Agar Medium:Solid substrate variant supports colony isolation and clonal selection protocols in Drosophila genetics laboratories.
- Gel Medium:Semi-solid matrix enables specialized applications in insect embryo culture and organ dissection workflows.
Liquid medium leads volumes today; powdered medium is gaining share fastest.
Usage Type:
Documentation requirements and validation rigor distinguish commercial buyers from academic adopters.
- Research:Dominant consumption category encompassing recombinant protein expression, viral vector production, and genetic screening. Academic laboratories prioritize lot-to-lot consistency for reproducibility, while biopharmaceutical facilities demand ISO 13485-adjacent batch records.
- Commercial:Expanding usage category spanning insect-based food protein manufacturing and biocontrol agent production. EPA facility registration mandates in the United States and EFSA oversight in Europe are elevating sterility assurance requirements beyond traditional research-grade specifications.
- Breeding:Sustained demand from agricultural biotechnology clusters maintaining continuous insect colonies for entomopathogenic nematode and predator insect propagation.
- Educational:Price-sensitive segment served through distributor networks supplying undergraduate teaching laboratories with basic formulation grades.
Research applications anchor current demand; commercial breeding operations show the steepest expansion trajectory.
Distribution Channel:
Procurement scale and technical support requirements determine channel selection.
- Distributors:Thermo Fisher Scientific leverages global logistics infrastructure to serve high-volume academic purchasers requiring integrated cell line and media bundles. Multi-year framework contracts predominate at German Excellence Initiative institutions and Japanese national university corporations.
- Direct Sales:Pharmaceutical-grade buyers with GMP-adjacent documentation needs engage manufacturers directly to secure customized batch records and audit trail packages.
- Online Retail:E-commerce platforms enable small-laboratory procurement of powdered formats with ambient shipping profiles, bypassing traditional distributor markups.
- Specialty Stores:Regional suppliers serve localized agricultural research stations with formulation customization for non-model insect species.
Distributor relationships dominate procurement value; direct sales channels are expanding most quickly among commercial breeding operations.
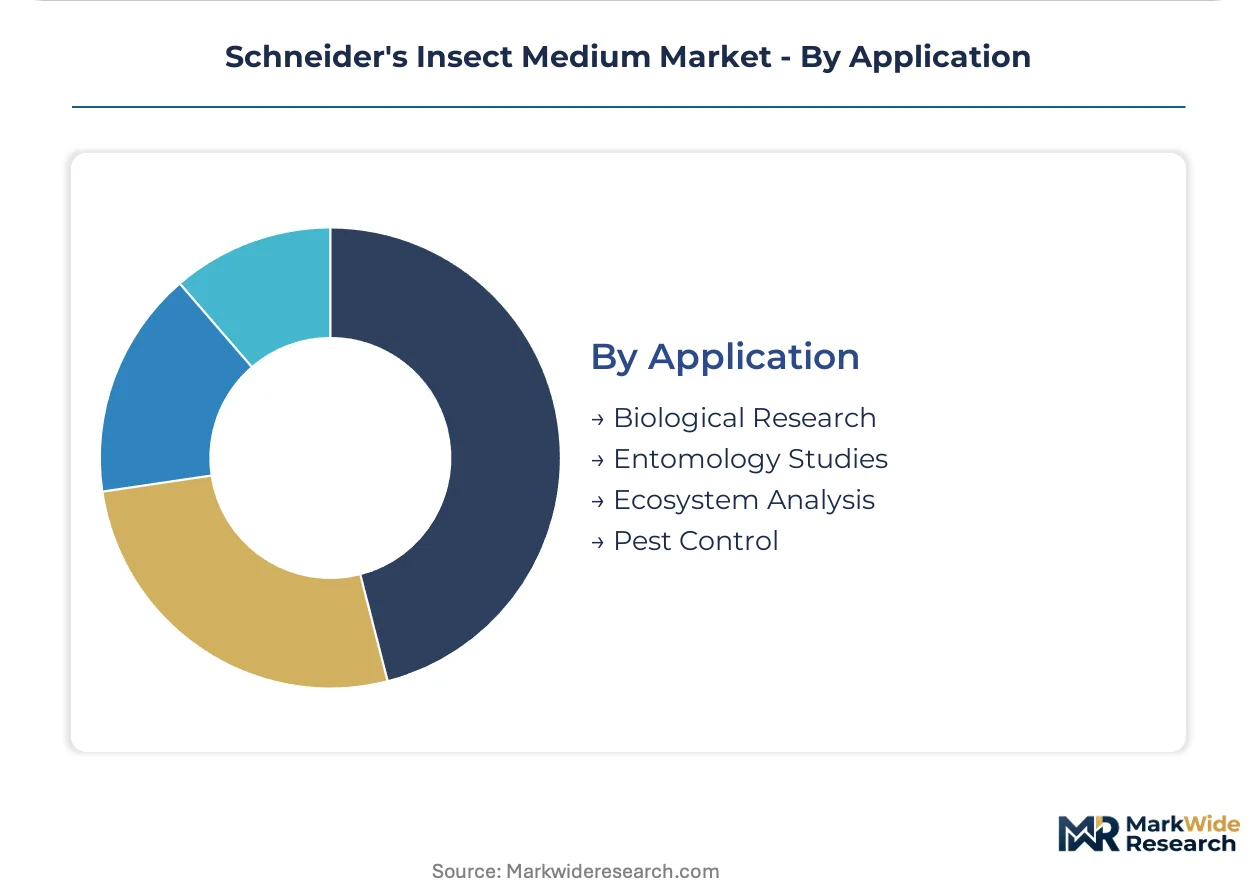
Application:
Regulatory exposure and therapeutic proximity shape quality tier selection.
- Biological Research:Recombinant protein production using Drosophila S2 cell lines drives premium medium consumption at contract manufacturing organizations preparing FDA master file submissions. Serum-free synthetic formulations are displacing yeastolate-supplemented recipes as lot-to-lot variability scrutiny intensifies.
- Entomology Studies:Foundational academic demand from Drosophila melanogaster genetics laboratories maintains baseline volumes for traditional formulation grades.
- Pest Control:Biocontrol agent production facilities in California and North Carolina absorb compliance costs through dedicated production line segregation mandated by EPA environmental release containment protocols.
- Ecosystem Analysis:Field entomology applications utilize basic medium grades for specimen transport and short-term maintenance.
Biological research commands the largest value share; pest control applications are climbing the fastest as agricultural biotechnology scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Drosophila genetics expertise concentrates in aging academic cohorts across Germany, the United States, and Japan, anchoring sustained procurement volumes at Max Planck Institutes, NIH-funded consortia, and RIKEN networks. These talent clusters shape medium formulation demand through multi-year framework contracts and stringent quality documentation requirements.
United States
Contract manufacturing organizations in California and North Carolina absorb the largest commercial volumes for viral vector production. EPA facility registration mandates for biocontrol agent production force dedicated production line segregation at agricultural biotechnology clusters. The NIH-funded Drosophila Genomics Resource Center at Indiana University stabilizes baseline demand for research-grade formulations.
Germany
Max Planck Institute networks and technical universities maintain continuous cell culture operations through Deutsche Forschungsgemeinschaft infrastructure grants. ECHA registration mandates under REACH standardize formulation purity benchmarks, accelerating replacement of non-compliant legacy media. Bavarian Excellence Initiative institutions displace spot purchasing through multi-year tenders covering integrated media and technical training bundles.
Japan
METI-funded insect farming initiatives for food protein are gaining regulatory clarity, expanding commercial breeding demand beyond traditional research applications. The country's national pharmaceutical regulator maintains stringent documentation thresholds for cell culture reagents used in therapeutic development pathways. Tokyo and Osaka metropolitan clusters concentrate entomology research infrastructure at RIKEN and national university corporations.
United Kingdom
Biopharmaceutical pipelines leveraging Drosophila S2 cells for therapeutic protein expression are elevating ISO 13485-adjacent procurement criteria. The Medicines and Healthcare products Regulatory Agency shapes quality documentation requirements for suppliers targeting clinical translation. Cambridge and Oxford research clusters maintain dedicated insect cell core facilities serving contract research organizations.
India
Cost-sensitive university laboratories lacking −20°C storage infrastructure drive powdered medium adoption through competitive pricing tiers. The Central Drugs Standard Control Organization maintains oversight of cell culture reagents used in diagnostic development. Bangalore and Hyderabad biotechnology parks are emerging as entomology research hubs with expanding insect cell culture capabilities.
Schneider's Insect Medium Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation tiers, creating a bifurcated structure where scale-driven distributors serve high-volume academic purchasers while boutique suppliers capture premium pharmaceutical-grade contracts. The vendor base stratifies into three functional archetypes: integrated life science conglomerates with global logistics infrastructure, regionally anchored medium specialists with cost-competitive powdered formulations, and quality-certification leaders targeting clinical translation pathways. Dominant competitive moves include backward integration into raw material sourcing and geographic expansion through e-commerce platforms bypassing traditional distributor markups.
Among diversified conglomerates, Thermo Fisher Scientific exemplifies scale-driven positioning through integrated cell line and media bundles, while Merck occupies the premium-tier vector via stringent quality certifications. HiMedia Laboratories represents the regionally focused specialist archetype with cost-competitive powdered medium formulations tailored to emerging research markets. These three anchors illustrate the competitive tension between convenience, certification, and cost across procurement segments.
| Leading Market Players |
|---|
| Merck |
| HiMedia Laboratories |
| Thermo Fisher Scientific |
| Sigma-Aldrich |
| US Biological |
| Bio-Techne |
| Corning |
| Atlanta Biologicals |
| Sartorius |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between ISO 13485-compliant pharmaceutical tiers and research-grade commodity formulations manifests in dual supply chain architectures: validated batch documentation commands 40-60% price premiums through direct manufacturer relationships, while cost-optimized powdered formats circulate through distributor networks serving budget-constrained academic core facilities.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for powdered medium formats, compressing margins on standard research-grade formulations. Three-tier pricing structure across premium, standard, and economy levels separates GMP-adjacent documentation packages from basic lot-release testing and unvalidated teaching grades. Price differentiation rests on certification investment and cold chain infrastructure requirements. Cost compression in the liquid medium tier is intensifying because German and Japanese academic consortia are consolidating procurement through multi-year framework contracts. University core facilities in emerging markets exhibit highest price sensitivity, while contract manufacturing organizations in California and North Carolina demonstrate lowest sensitivity due to regulatory compliance imperatives.
Supply Chain Analysis
Single-source vulnerability sits with Chinese fermentation facilities supplying yeastolate and peptone derivatives, creating input cost instability during animal nutrition demand spikes. Manufacturing concentration spans Germany, the United States, and Japan for formulated media, while raw material extraction draws from China, India, and select European fermentation hubs. Critical dependencies include yeastolate, buffered salts, and synthetic lipid substitutes. Tariff exposure on Chinese-sourced biological extracts threatens margin stability at mid-tier suppliers. Distribution runs through integrated life science conglomerates with global logistics infrastructure, though direct-to-laboratory e-commerce platforms are gaining share in powdered format segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Schneider's Insect Medium functions as a regulatory compounder where REACH framework compliance and FDA master file documentation requirements are accelerating replacement cycles and premium-tier procurement.
For Market Incumbents: Anticipate margin compression from Indian and Chinese cost-competitive entrants by securing backward integration into yeastolate sourcing and locking German Excellence Initiative institutions into multi-year technical training bundles. Certification investment in ISO 13485 pathways represents the critical defensive lever against clinical-grade market erosion. Capacity addition in Southeast Asian fermentation hubs can offset Chinese supply volatility. For New Entrants and Emerging Players: Launch via direct-to-laboratory e-commerce distribution of lyophilized powdered formats to bypass Thermo Fisher Scientific's distributor markups in cost-sensitive Indian and Southeast Asian research markets. Agricultural biotechnology clusters in Japan's METI-funded insect farming initiatives offer the most penetrable white-space target. Technical training partnerships with aging Drosophila genetics cohorts provide differentiated go-to-market positioning against commodity suppliers. For Investors and Strategic Acquirers: Consolidation pressure builds where GMP-adjacent documentation capabilities intersect with scaled fermentation infrastructure, favoring acquisition of regional medium specialists with validated batch record systems. Five-to-ten-year viability hinges on clinical translation revenue streams from insect cell platforms in viral vector manufacturing. The signal to watch as inflection indicator is FDA master file submission volume from Drosophila S2 cell-based therapeutic protein pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Yeastolate Sourcing | Captive supply of peptone derivatives insulates margin stability from Chinese fermentation demand spikes. |
| ISO 13485 Certification Investment | Diagnostic-grade batch documentation unlocks clinical translation revenue at contract manufacturing organizations. |
| Lyophilized Powder Format Expansion | Ambient-stable formulations enable direct-to-laboratory e-commerce distribution bypassing traditional markups. |
| Multi-Year Framework Contract Securement | German Excellence Initiative tenders displace spot purchasing and lock out cost-competitive challengers. |
| Technical Training Bundle Development | Dipteran cell line expertise scarcity creates defensive moat through knowledge transfer partnerships with academic cohorts. |
Research Methodology
Coverage spans Germany, the United States, Japan, India, and the United Kingdom, with primary inputs from each market's research infrastructure clusters. The analysis combines structured interviews with cell culture core facility directors, procurement officers at Max Planck Institutes and NIH-funded consortia, regulatory affairs leads at contract manufacturing organizations, and technical R&D directors at medium formulation suppliers. Secondary validation draws from ECHA REACH registration databases, FDA master file submission records, Deutsche Forschungsgemeinschaft funding disclosures, and METI insect farming initiative documentation. Bottom-up demand modeling from individual laboratory procurement patterns triangulates against top-down sectoral spending estimates from national research funding agencies.
Granularity-level modeling distinguishes liquid, powdered, agar, and gel format segments across research, commercial, breeding, and educational usage categories. The analytical framework projects volume and value outputs across the analysis window through segmented demand elasticity curves and substitution dynamics between yeastolate-supplemented and chemically defined formulations. CAGRs derive from regression analysis of historical procurement data against funding trajectory indicators. Industry-specific forecast inputs include Drosophila S2 cell line adoption rates in biopharmaceutical pipelines and EPA facility registration timelines for biocontrol agent production.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained yeastolate supply disruption or accelerated serum-free synthetic medium substitution. Forecasts reflect documented assumptions regarding REACH compliance enforcement consistency and METI regulatory clarity timelines for insect-based food protein applications. Yeastolate price volatility, dipteran cell line specialist retirement waves, and GMP-adjacent documentation standardization pace represent primary revision triggers. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Global Benzalkonium Chloride Market
Chemicals
Calcium Disodium Ethylene Diamine Tetra-Acetate Market
Chemicals
Linear Mercaptans Market
Chemicals
Potassium Alum Market
Chemicals
Global Pine Chemicals Market
Chemicals
Penoxsulam Market
Chemicals
Coal Tar Market
Chemicals
India Ethoxylates Market
Chemicals
Middle East and Africa Construction Chemicals Market
Chemicals
Tributyl Phosphate Market
Chemicals
Calcium Methoxide Market
Chemicals
Amine Oxide Market
Chemicals
Paint Remover Market
Chemicals
Aircraft Cleaning Chemicals Market
Chemicals
Middle East and Africa Methyl Acrylate Market
Chemicals
Global Amines Market