
 Pinoxaden Market | 2026-2036
Pinoxaden Market Size, Share, and Industry Trends Forecast 2026-2036
Pinoxaden Market Intelligence
The consolidation of purchasing power among large agricultural cooperatives and corporate farming enterprises is repositioning the competitive landscape for pinoxaden suppliers. Syngenta AG leverages its extensive distribution network and established brand to maintain a strong market presence. Meanwhile, Corteva Agriscience differentiates through its focus on integrated pest management solutions for cereal growers. UPL Limited competes by offering cost-effective generic formulations, particularly in price-sensitive agricultural economies.
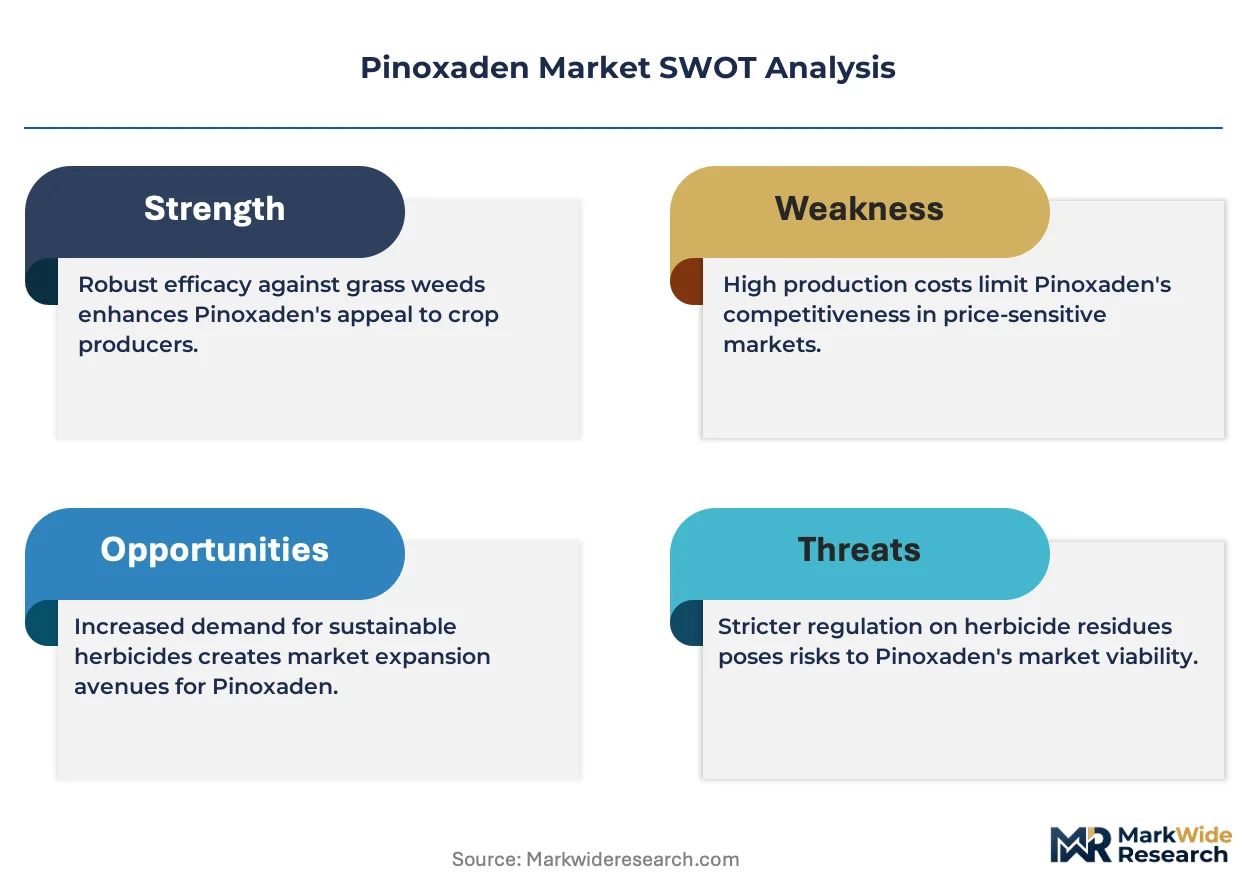
Pinoxaden is a selective, post-emergence herbicide belonging to the phenylpyrazole chemical family. It functions by inhibiting the acetyl-CoA carboxylase (ACCase) enzyme, which is essential for fatty acid synthesis in grass weeds. Its primary purpose is the control of wild oats, ryegrass, and other graminaceous weeds in staple crops. The Cereal Crops application segment constitutes the largest share of use, with Formulated Concentrate products leading due to their ease of transport and mixing for large-scale field application.
Market access and formulation standards are governed by stringent regulatory frameworks. In the United States, the EPA sets maximum residue levels (MRLs), while in Europe, the EFSA and ECHA oversee approval and re-registration processes under REACH. These regulations dictate permissible application rates and pre-harvest intervals. Navigating the evolving landscape of weed resistance and divergent regional environmental mandates remains the central strategic challenge for manufacturers.
Market Dynamics
The market's trajectory is defined by the agricultural sector's response to widespread herbicide resistance in key grass weeds. This dynamic compels a shift toward integrated weed management strategies and advanced formulations to preserve the efficacy of pinoxaden in staple cereal crops, balancing crop yield demands with environmental stewardship.
Growth Catalysts
- Food Security Mandates:National policies in major grain-exporting countries, such as Canada and Brazil, prioritize high-yield cereal production, sustaining consistent demand for effective grass weed control solutions like pinoxaden to protect harvests.
- Precision Agriculture Technologies:The adoption of GPS-guided sprayers and drone-based field mapping allows for more targeted and efficient application of herbicides, optimizing input costs for commercial farmers and justifying investment in premium products.
- Cereal Crop Expansion:Continued expansion of cultivated areas for wheat and barley, particularly in regions like the Black Sea basin, creates new acreage requiring post-emergence herbicide treatment for graminaceous weeds.
Market Restraints
- Weed Resistance Development:The accelerated evolution of ACCase-inhibitor resistance in target species like wild oats and ryegrass diminishes product effectiveness over time, requiring complex and costly resistance management programs for growers.
- Regulatory Scrutiny:Stringent maximum residue levels (MRLs) and environmental risk assessments by bodies like the European Food Safety Authority (EFSA) can lead to restrictions on application rates or even de-registration.
- Generic Competition:The availability of lower-cost generic pinoxaden formulations, especially in price-sensitive agricultural economies in Asia and Latin America, puts pressure on the pricing power of originator brands.
Strategic Opportunities
- Novel Co-Formulations:Developing products that combine pinoxaden with herbicides featuring different modes of action presents a clear opportunity to offer growers a built-in resistance management tool and improve weed control spectrum.
- Geographic Expansion:Market entry into Eastern European agricultural economies, where cereal production is intensifying and modernizing, offers significant growth potential for suppliers with established distribution networks.
- Expanded Crop Labeling:Pursuing regulatory approval for use in minor crops or for specialized applications, such as in seed production fields, can open new, high-value niche segments for pinoxaden.
Industry Challenges
- Divergent Regulatory Compliance:Navigating the complex and often conflicting registration requirements and data submission standards between major regulatory bodies, such as the US EPA and Europe's ECHA, creates significant administrative and financial burdens.
- Grower Education on Stewardship:A primary operational challenge involves training end-users on proper application timing, nozzle selection, and tank-mixing protocols to delay resistance and ensure compliance with pre-harvest intervals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pinoxaden Market |
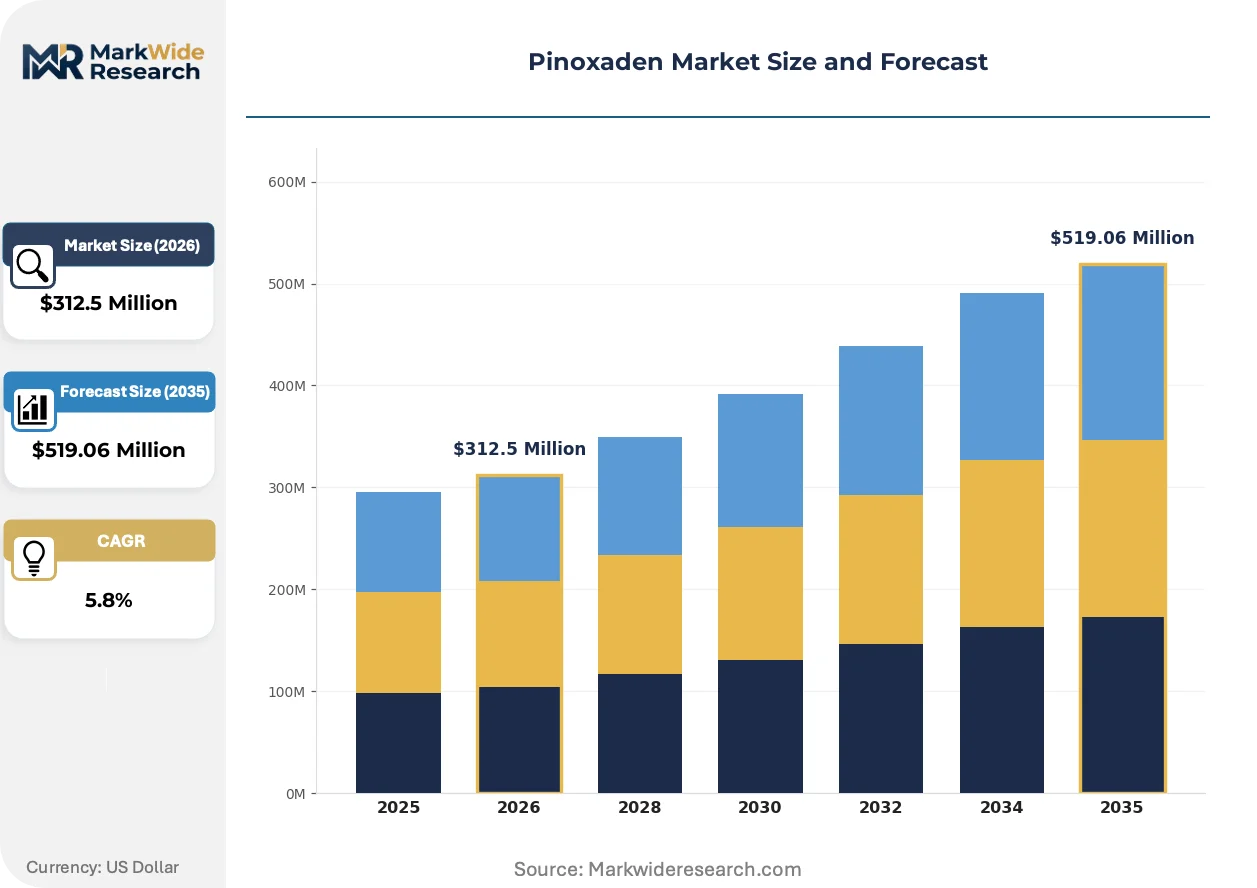
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Technical Grade, Formulated Concentrate, Wettable Powder, Granular Form Application: Cereal Crops, Pulses, Oilseeds, Turf Management, Non-Crop Areas End User: Commercial Farmers, Agricultural Cooperatives, Landscape Maintenance, Contract Sprayers Distribution Channel: Direct Sales, Agricultural Retailers, E-Commerce Platforms, Distributors |
| Companies Covered | Syngenta AG, BASF SE, Bayer CropScience, Corteva Agriscience, UPL Limited, Nufarm Limited, FMC Corporation, Sumitomo Chemical, Adama Agricultural Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pinoxaden Market Strategic Shifts & Innovations
Product development is pivoting from standalone herbicidal efficacy to system-level performance. This shift emphasizes formulation science that enhances compatibility with digital farming platforms and addresses complex weed resistance profiles in large-scale agriculture, ensuring the longevity of the molecule's utility.
Advanced adjuvant and safener technologies are being integrated directly into pinoxaden formulations to improve plant uptake and enhance crop safety. Large corporate farms and agricultural cooperatives are the primary adopters, seeking to maximize the performance of each spray application. This focus on optimizing the active ingredient's performance through formulation science is overtaking the previous strategy of simply increasing application rates to combat early-stage resistance.
Regulatory frameworks, particularly the European Union's Farm to Fork Strategy, mandate significant reductions in overall pesticide use and risk. This policy compels manufacturers to develop more targeted, lower-dose formulations and provide extensive data on environmental impact. Cereal growers in member states like France and Germany are most affected, accelerating their use of integrated weed management programs that rely on highly effective, low-use-rate products.
Consolidation among agricultural cooperatives and large-scale distributors is centralizing purchasing decisions for crop protection chemicals. This change disrupts the traditional direct-to-farmer sales model, favoring suppliers who can offer portfolio-wide agreements and demonstrate robust supply chain security. The trend is most visible in the grain belts of North America and Brazil, where a few large enterprises control a substantial share of agrochemical procurement.
Pinoxaden Market Segmentation
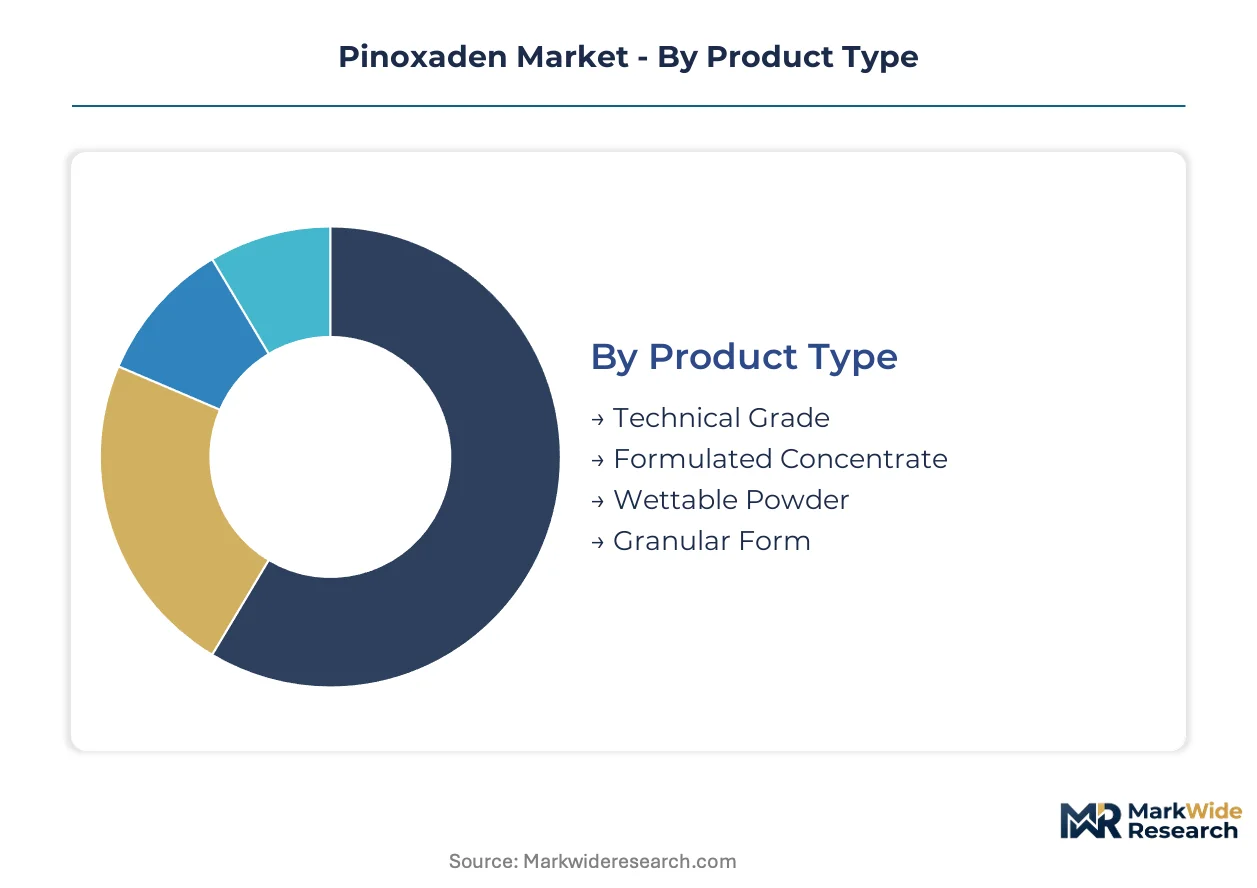
Pinoxaden market segmentation reveals how diverse user requirements and application methods shape product demand. Understanding these distinct segments allows manufacturers to tailor formulations, distribution strategies, and regulatory compliance efforts for optimal market penetration and sustained growth.
Product Type:
The form factor of pinoxaden influences purchasing decisions based on application equipment, storage, and mixing convenience for end-users.
- Formulated Concentrate:This liquid formulation offers high active ingredient concentration, facilitating easy transport and mixing in large spray tanks for broad-acre applications. Commercial farmers in Brazil's grain belt prefer this type for its efficiency in large-scale field operations.
- Technical Grade:Representing the pure active ingredient, technical grade pinoxaden serves as the raw material for various formulated products. Chemical manufacturers utilize this form for compounding into diverse end-use products, ensuring supply chain flexibility for downstream producers.
- Wettable Powder:This dry, finely ground formulation disperses readily in water, suitable for specific application equipment or tank-mix compatibility needs.
- Granular Form:Granular pinoxaden offers advantages in targeted, controlled-release applications, reducing drift and enhancing environmental precision.
Volume sits with Formulated Concentrate; growth tilts toward Granular Form.
Application:
The specific crop or area where pinoxaden is applied dictates product efficacy requirements and regulatory approvals.
- Cereal Crops:This segment represents the primary application area for pinoxaden, controlling graminaceous weeds like wild oats and ryegrass in wheat and barley fields. Farmers in Canada and Ukraine heavily rely on pinoxaden to protect significant cereal harvests.
- Pulses:Pinoxaden is critical for managing grass weeds in pulse crops such as lentils and chickpeas, protecting yields in regions like India and Australia. This application requires careful selectivity to avoid crop injury.
- Oilseeds:Application in oilseed crops, including canola and sunflower, targets problematic grass weeds to ensure crop quality and yield.
- Turf Management:Pinoxaden finds niche use in professional turf management for selective grass weed control in amenity areas and sports fields.
- Non-Crop Areas:This segment includes applications in industrial sites, railways, and utility areas where broad-spectrum grass weed control is necessary.
Cereal Crops dominates pinoxaden use; Pulses application is expanding.
End User:
The scale and operational structure of the user influence procurement patterns and demand for specific product features.
- Commercial Farmers:Large-scale agricultural operations constitute a significant end-user segment, demanding high-efficacy products suitable for extensive acreage and integrated weed management programs. Farmers in the United States prioritize solutions that optimize input costs.
- Agricultural Cooperatives:These organizations aggregate purchasing power for their member farmers, influencing product selection based on collective needs and preferred supplier relationships. Cooperatives in Germany often seek portfolio-wide agreements.
- Landscape Maintenance:Professionals managing public parks, golf courses, and commercial landscapes use pinoxaden for targeted grass weed control.
- Contract Sprayers:Specialized service providers offer application services to multiple farmers, requiring versatile and efficient pinoxaden formulations.
Commercial Farmers represent the largest consumer base; Contract Sprayers serve specialized needs.
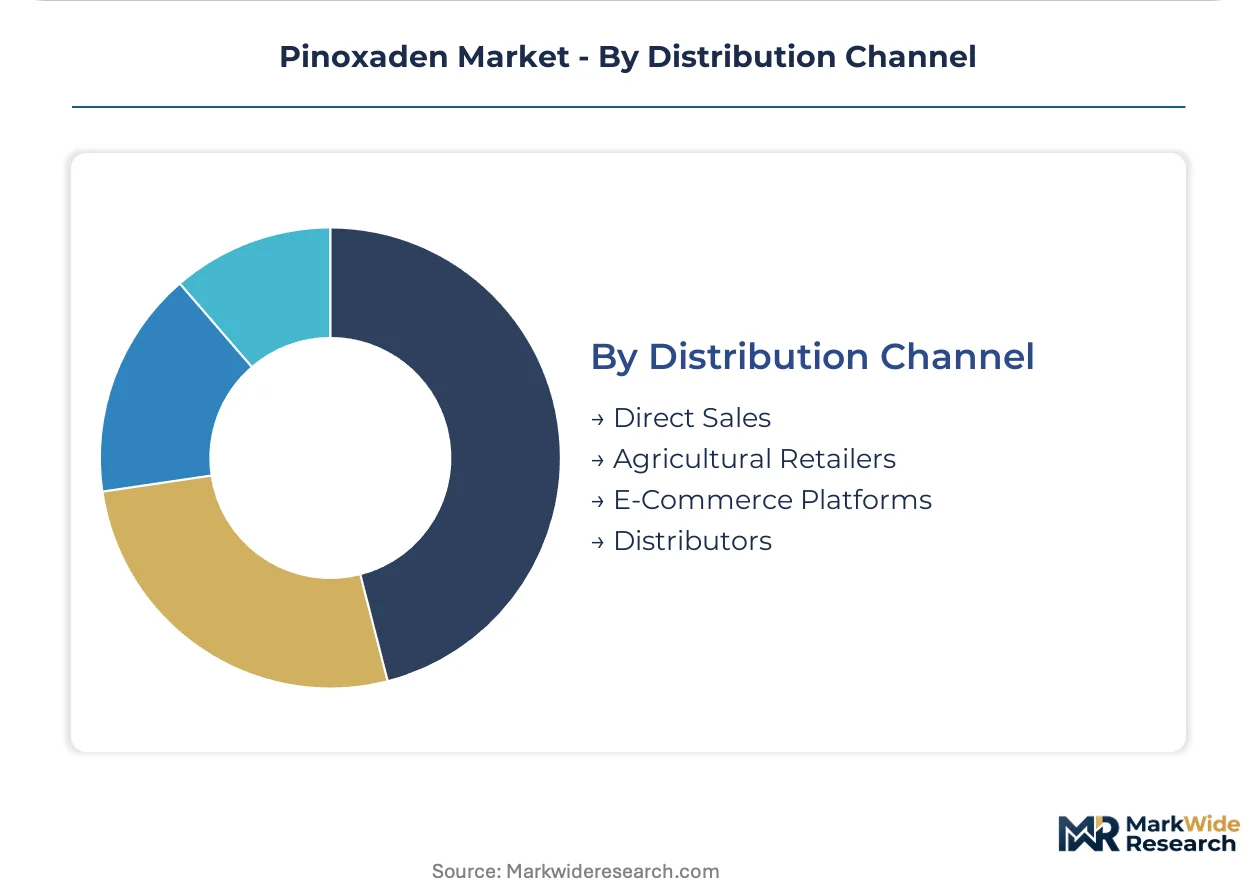
Distribution Channel:
Market access and product availability are determined by the efficiency and reach of various distribution networks.
- Agricultural Retailers:Local and regional agricultural retailers serve as crucial points of sale, providing farmers with products, advice, and logistical support. These channels remain vital for reaching a broad farmer base in rural areas of France.
- Distributors:Large distributors manage extensive supply chains, warehousing, and logistics, connecting manufacturers with retailers and large commercial farming operations. Major distributors play a central role in delivering products across South Africa.
- Direct Sales:Manufacturers engage in direct sales for very large corporate farms or key strategic accounts, facilitating custom solutions and direct technical support.
- E-Commerce Platforms:Online platforms are emerging as a convenient channel for purchasing agricultural inputs, particularly for smaller farms or specific product needs.
Agricultural Retailers remain the traditional channel; E-Commerce Platforms are gaining traction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pinoxaden demand concentrates in regions with extensive cereal crop cultivation due to food security mandates. Large-scale commercial farming operations drive product uptake, particularly in global grain belts. This regional focus ensures targeted herbicide application.
Canada
Canadian farmers exhibit strong demand for pinoxaden to control wild oats and other graminaceous weeds in vast wheat and barley fields. Health Canada's Pest Management Regulatory Agency (PMRA) sets strict guidelines for pesticide use and residue levels. The Canadian Prairies, encompassing provinces like Saskatchewan and Alberta, serve as a major hub for large-scale cereal production and herbicide adoption.
Brazil
Brazil's agricultural sector drives pinoxaden demand for effective grass weed control in its expanding corn and soybean rotation systems. The national health surveillance agency, ANVISA, regulates agrochemical approvals and application standards within the country. Brazil's prominent grain belt, particularly in states such as Mato Grosso and Goiás, utilizes pinoxaden for maximizing crop yields.
United States
United States commercial farmers prioritize pinoxaden solutions that optimize input costs and support integrated weed management in cereal crops. The Environmental Protection Agency (EPA) establishes maximum residue levels and application protocols for all herbicides. The Midwest states, including Iowa and Illinois, represent significant areas for corn and wheat cultivation, creating consistent demand.
Ukraine
Ukraine's agricultural sector shows sustained demand for pinoxaden to protect significant cereal harvests, especially wheat and barley, in the Black Sea basin. National agricultural policies often prioritize high-yield production and efficient crop protection strategies. Expanding cultivated areas across the Black Sea region require robust post-emergence herbicide treatment for graminaceous weeds.
France
French cereal growers increasingly seek effective, low-use-rate pinoxaden products as part of integrated weed management programs. The European Food Safety Authority (EFSA) and European Chemicals Agency (ECHA) govern regulatory approvals under the EU's Farm to Fork Strategy. Northern France, including regions like Champagne-Ardenne, actively implements advanced weed control practices.
Pinoxaden Market Key Industry Players
European and North American producers anchor one tier of the pinoxaden market, emphasizing brand and efficacy, while Asian and Latin American specialists hold another, focusing on cost-effective generic formulations. The market exhibits a tiered structure, with global agrochemical giants competing alongside regional players. Strategic archetypes include innovation-driven originators, integrated solution providers, and generic manufacturers. Dominant competitive moves involve portfolio diversification through novel co-formulations and strategic geographic expansion into emerging agricultural economies.
Among global agrochemical leaders, Syngenta AG exemplifies a strong market presence through its extensive distribution networks and established brand recognition. Corteva Agriscience occupies a position as an integrated solution provider, differentiating its offerings through a focus on integrated pest management solutions for cereal growers. UPL Limited sits within the generic segment, representing a key player offering cost-effective formulations, particularly in price-sensitive agricultural economies across Asia and Latin America.
| Leading Market Players |
|---|
| Syngenta AG |
| BASF SE |
| Bayer CropScience |
| Corteva Agriscience |
| UPL Limited |
| Nufarm Limited |
| FMC Corporation |
| Sumitomo Chemical |
| Adama Agricultural Solutions |
| Others |
Cost & Logistics Intelligence
The global price of key chemical intermediates, such as phenylpyrazole precursors, heavily influences pinoxaden pricing across the supply chain into formulated products. This commodity benchmark cascades through manufacturing costs, affecting the final price points for commercial farmers.
Pricing Analysis
The pinoxaden market operates with a distinct volume-versus-margin split, where high-volume generic formulations offer lower margins compared to premium branded products. Pricing is primarily per-unit transactional, influenced by formulation efficacy and the brand premium commanded by originator companies. Geographic delivery costs also create price differentiation across regions. Pricing pressure stems from the availability of cost-effective generic pinoxaden formulations in emerging agricultural economies. Commercial farmers in price-sensitive markets, especially in Asia and Latin America, exhibit the highest price sensitivity.
Supply Chain Analysis
Domestic content mandates, particularly in regions promoting local manufacturing, are reshaping sourcing strategies for pinoxaden. The supply of technical grade pinoxaden concentrates in China and India, which serve as major hubs for chemical intermediate production. The industry relies heavily on key chemical intermediates for synthesis and on specialized adjuvants for formulation. Single-source vulnerability for these complex intermediates represents a structural supply chain risk. Downstream, product distribution runs through established agricultural retailers and large-scale distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story, where stringent regulatory frameworks like the EU's Farm to Fork Strategy create a significant barrier-to-entry moat for highly compliant players.
For Market Incumbents: Anchor market position by continuously investing in novel co-formulations that offer enhanced efficacy against evolving herbicide resistance in cereal crops. Strengthen distribution networks, particularly with large agricultural cooperatives, to counteract generic competition and maintain brand loyalty. Strategic R&D into new modes of action or advanced adjuvant technologies will defend against the threat of diminishing product effectiveness.
For New Entrants and Emerging Players: Agricultural retailers represent a crucial channel partner for market entry, especially in regions with fragmented farming structures. Target underpenetrated Eastern European agricultural economies, where cereal production is expanding and modernizing. A cost-effective generic formulation strategy, coupled with clear data on efficacy, offers a viable go-to-market angle in price-sensitive markets.
For Investors and Strategic Acquirers: Distressed-cycle entries favor integrated solution providers in key agricultural geographies like Brazil. The long-term viability of pinoxaden, particularly its role in integrated weed management, provides sustained demand over a 5-10 year window. Acquisition targets should include mid-sized specialty chemical firms with strong R&D in formulation science or regional distribution strengths. Regulatory approvals for new co-formulations or expanded crop labeling serve as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Novel Co-Formulation Development | Enhances efficacy against resistant wild oats in Canadian cereal crops. |
| Geographic Expansion into Eastern Europe | Captures new acreage demand in Ukraine's expanding grain belt. |
| Digital Farming Platform Integration | Optimizes application rates for commercial farmers in Brazil's grain belt. |
| Expanded Crop Labeling for Pulses | Unlocks high-value niche segments in India's agricultural sector. |
| Sustainable Formulation R&D | Addresses EU Farm to Fork Strategy mandates for lower pesticide use. |
Research Approach
EPA filings, EFSA assessments, and industry association reports formed the secondary backbone for market sizing and trend analysis. Primary interviews were conducted with agrochemical R&D directors, commercial farmers, agricultural cooperative managers, and regulatory affairs specialists to gather qualitative insights. This combined approach allowed for robust bottom-up market sizing and top-down validation of data points.
A bottom-up market sizing approach, validated by top-down analysis, was employed to estimate market volumes and values across the analysis window. Segmentation dimensions included product type, application, end user, distribution channel, and regional crop cycles. Compound annual growth rates were derived from historical trends, projected demand, and supply-side capacity expansions. Key industry-specific forecast inputs included cereal crop acreage expansion and herbicide resistance trends.
Several conditions sit outside the modeled scope, including unforeseen geopolitical events or radical technological breakthroughs in weed control. Forecasts reflect assumptions regarding regulatory stability and agricultural policy continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Malaysia Construction Chemicals Market
Chemicals
Perchloric Acid Market
Chemicals
Methyldiisopropanolamine Market
Chemicals
South Korea Methanol Market
Chemicals
Ammonia Market
Chemicals
Hexafluorosilicic Acid Market
Chemicals
Hydrazine Hydrate Market
Chemicals
RDX and HMX Market
Chemicals
Japan Methanol Market
Chemicals
Calcium Disodium Ethylene Diamine Tetra-Acetate Market
Chemicals
Asia-Pacific Fluorosilicic Acid Market
Chemicals
Desalination Chemicals Market
Chemicals
Global Oxo Alcohols Market
Chemicals
Benzoyl Alcohol Market
Chemicals
Glyoxal Market
Chemicals
Global Waterproofing Chemicals Market