
 Elemental Analysis Market | 2026-2036
Elemental Analysis Market Size, Share, and Industry Trends Forecast 2026-2036
Elemental Analysis Market Intelligence
Direct sales channels for high-end spectrometers and analyzers are narrowing the role of third-party distributors for large institutional accounts. This shift allows for deeper customer relationships and integrated service contracts. Thermo Fisher Scientific leverages its extensive global service network to support complex instrumentation in university and government research institutions. Agilent Technologies differentiates through its strong focus on life sciences and diagnostics applications. PerkinElmer sustains a significant presence in environmental and food testing segments with its specialized analytical solutions.
Elemental analysis involves techniques to determine the elemental and isotopic composition of a material sample, often achieving detection limits down to parts-per-trillion. Its primary purpose is quantifying elements to identify trace contaminants or verify material purity in diverse matrices from chemicals to biological tissues. Within the product landscape, Spectrometers using Inductively Coupled Plasma (ICP) technology dominate the high-performance segment. Environmental testing and pharmaceutical applications are the primary growth segments, driven by stringent quality control and safety compliance mandates.
Regulatory frameworks from the US Food and Drug Administration (FDA) and the European Medicines Agency (EMA) mandate stringent elemental impurity testing in pharmaceutical products under ICH Q3D guidelines. Similarly, ISO 17025 standards for testing and calibration laboratories dictate equipment accuracy and method validation protocols, directly influencing instrument purchasing decisions. Navigating the evolving landscape of substance restrictions and analytical method validation will be critical for both instrument manufacturers and end-user laboratories.
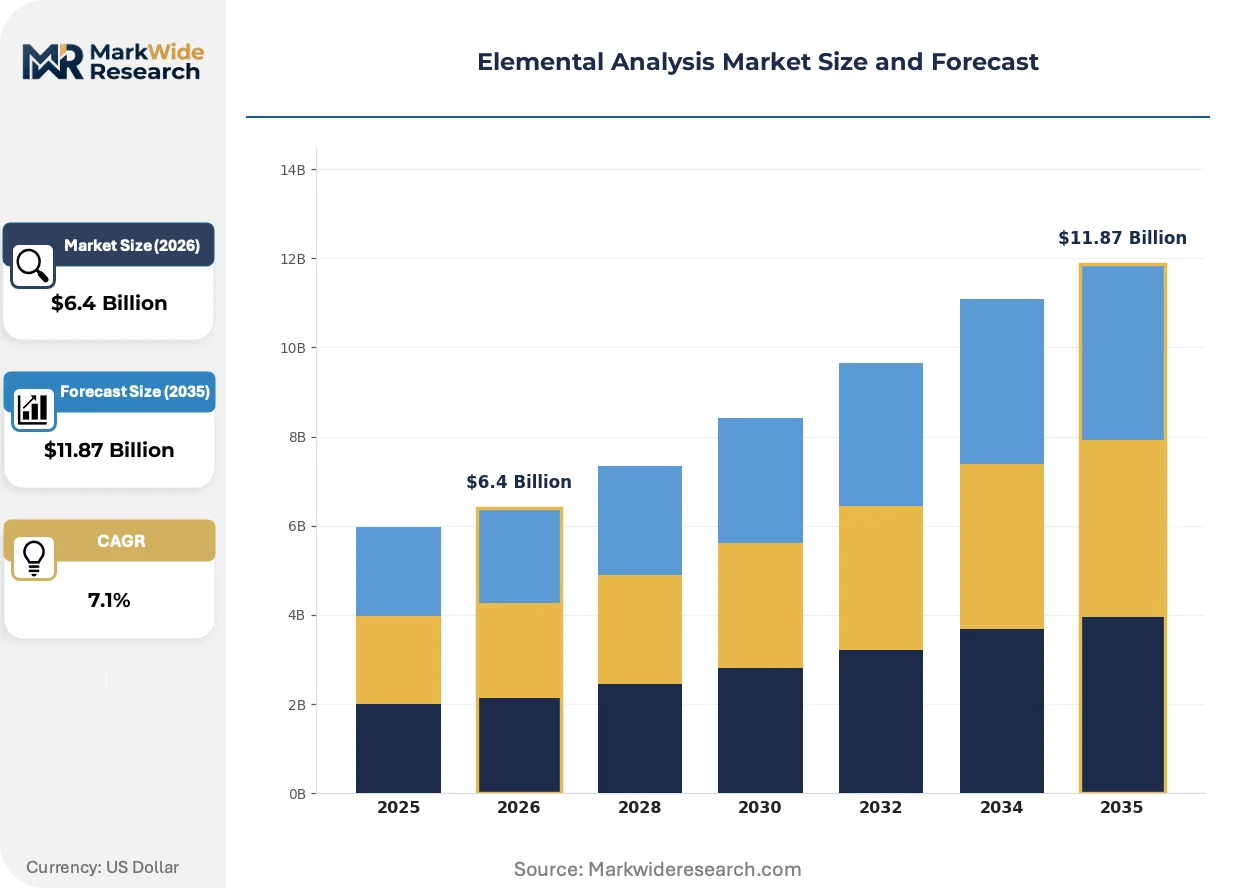
Market Dynamics
The elemental analysis market's core dynamic is the escalating requirement for parts-per-billion and parts-per-trillion detection limits. This pressure originates from both stringent international regulations like the EU's REACH and the technical demands of advanced manufacturing in sectors such as semiconductors and biopharmaceuticals.
Growth Catalysts
- Pharmaceutical Impurity Mandates:Guidelines like ICH Q3D for elemental impurities compel pharmaceutical companies to conduct rigorous testing on raw materials and final drug products, directly driving demand for high-sensitivity spectrometers.
- Environmental Monitoring Regulations:Stricter heavy metal limits set by agencies like the US Environmental Protection Agency (EPA) for drinking water and industrial effluent require continuous and more precise monitoring, expanding the user base for analytical instruments.
- Advanced Materials Development:The push for higher efficiency in batteries and semiconductors necessitates ultra-pure materials, creating a substantial need for trace element analysis to control contamination in manufacturing hubs like South Korea and Taiwan.
Market Restraints
- High Instrument Cost:The significant capital investment required for high-performance systems such as Inductively Coupled Plasma Mass Spectrometry (ICP-MS) and their high total cost of ownership create a substantial barrier to entry for smaller laboratories.
- Sample Matrix Interference:Complex sample matrices, particularly in biological tissues or environmental sludge, can cause spectral and non-spectral interferences, complicating method development and compromising analytical accuracy without advanced correction techniques.
- Skilled Operator Scarcity:Operating advanced elemental analyzers and developing robust analytical methods requires a high level of technical expertise, and a shortage of qualified chemists and technicians limits market expansion.
Strategic Opportunities
- Battery Materials Analysis:The rapid growth of the electric vehicle industry creates a significant opportunity in analyzing the purity and composition of lithium, nickel, and cobalt used in battery manufacturing.
- Food Safety and Authenticity:Emerging regulations and consumer demand for food safety and provenance are opening new applications in testing for heavy metals, mineral content, and geographic origin in food products. *Automation and AI Integration: Incorporating artificial intelligence and machine learning into analytical software can automate method development, data interpretation, and system diagnostics, lowering the expertise barrier and improving laboratory efficiency.
Industry Challenges
- Method Validation Complexity:Validating analytical methods to meet the stringent requirements of standards like ISO 17025 is a time-consuming and resource-intensive process, delaying the deployment of new testing services.
- Data Integrity Compliance:Adhering to data integrity regulations such as the FDA's 21 CFR Part 11 for electronic records adds significant software and procedural overhead for laboratories in regulated environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elemental Analysis Market |
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $11.87 Billion |
| CAGR (2026 – 2036) | 7.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spectrometers, Chromatographs, Sensors, Analyzers Technology: ICP, AAS, XRF, NAA Application: Environmental Testing, Food Testing, Metals Analysis, Pharmaceuticals End User: Laboratories, Research Institutions, Manufacturing Facilities, Quality Control |
| Companies Covered | Thermo Fisher Scientific Inc., Agilent Technologies Inc., PerkinElmer Inc., Shimadzu Corporation, Bruker Corporation, HORIBA Ltd., Analytik Jena AG, SPECTRO Analytical Instruments GmbH, Elementar Analysensysteme GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elemental Analysis Market Strategic Shifts & Innovations
The market is defined by a push toward miniaturization and automation, seeking to move elemental analysis from centralized laboratories to field applications and production lines. This shift prioritizes speed, ease of use, and real-time data for process control and immediate decision-making.
Laser-Induced Breakdown Spectroscopy (LIBS) provides a method for rapid, in-situ elemental analysis without extensive sample preparation. Industries such as scrap metal recycling and mining are adopting portable LIBS analyzers for quick material identification and sorting. Consequently, the approach to quality control is migrating from a reliance on sending samples to off-site labs toward real-time, on-site analysis enabled by these field-deployable instruments.
Stricter regulations from bodies like the European Food Safety Authority (EFSA) and the US FDA on toxic elements such as lead and arsenic in foodstuffs, particularly baby food, are compelling changes in industry practice. This forces food producers to implement more rigorous testing protocols throughout their supply chains. The food and beverage testing segment is most impacted, increasing its investment in high-sensitivity ICP-MS to meet sub-ppb detection requirements.
A fundamental shift from one-time capital equipment sales to integrated service models is altering buyer behavior. These long-term agreements bundle instrumentation with consumables, software updates, and ongoing support, offering budget predictability. This model is disrupting traditional third-party distributor channels, especially in North America and Europe where manufacturers are forging direct relationships with large government and academic research institutions.
Elemental Analysis Market Segmentation
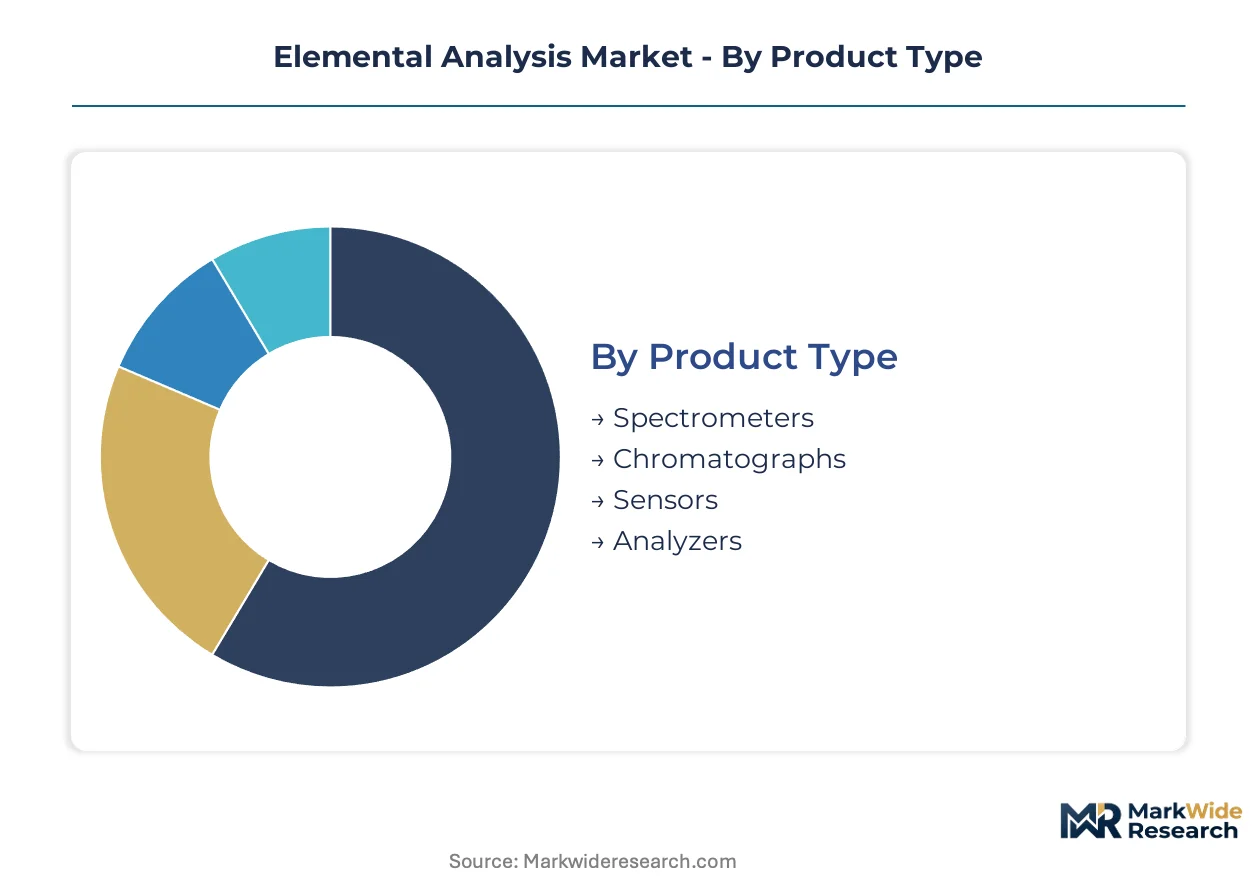
The Elemental Analysis Market is segmented to reflect the diverse instrumental approaches, technological underpinnings, application areas, and end-user requirements driving its expansion. Understanding these distinct segments is crucial for manufacturers to tailor product development and for laboratories to optimize analytical workflows for specific needs.
Product Type:
The diverse range of elemental analysis instruments addresses specific analytical challenges across various industries, from high-precision research to rapid field deployment.
- Spectrometers:These devices measure the interaction of matter with electromagnetic radiation, providing detailed elemental composition data. Demand concentrates in pharmaceutical manufacturing and environmental monitoring, driven by stringent regulatory compliance from agencies like the US FDA and the European Medicines Agency.
- Analyzers:These integrated systems perform complete analytical procedures, often incorporating sample preparation and data processing. Manufacturing facilities and quality control laboratories are increasingly adopting them for real-time process control and product purity verification in sectors such as semiconductors.
- Chromatographs:These instruments separate complex mixtures into individual components before elemental detection, crucial for speciation studies in environmental and food safety applications.
- Sensors:Compact and often portable, these devices offer real-time, in-situ elemental detection for rapid screening and process monitoring in industries like scrap metal recycling.
Established volume favors Spectrometers; emerging adoption favors Sensors.
Technology:
Application focus defines the selection of elemental analysis technologies, balancing sensitivity, speed, and sample compatibility for specific analytical tasks.
- ICP:Inductively Coupled Plasma techniques, including ICP-OES and ICP-MS, offer exceptional detection limits down to parts-per-trillion. Pharmaceutical testing and semiconductor manufacturing in South Korea rely on ICP for ultra-trace impurity detection.
- XRF:X-ray Fluorescence provides non-destructive, rapid elemental analysis of solid, liquid, and powder samples. Its use is expanding in quality control for metals and minerals, particularly in industrial settings and mining operations.
- AAS:Atomic Absorption Spectroscopy is a mature technique for quantifying individual elements, commonly used for routine metal analysis in water and food samples.
- NAA:Neutron Activation Analysis offers high sensitivity for bulk elemental composition without extensive sample preparation, often used in forensic and geological studies.
High-precision requirements drive demand for ICP, while portability needs propel XRF.
Application:
Volume contribution highlights the critical sectors driving elemental analysis, reflecting both regulatory mandates and industrial quality requirements.
- Environmental Testing:This application segment involves the analysis of water, soil, and air samples for pollutants and heavy metals. Agencies like the US EPA and the European Food Safety Authority mandate rigorous testing, expanding instrument usage across Europe and North America.
- Pharmaceuticals:Elemental analysis ensures drug product purity and compliance with guidelines like ICH Q3D, scrutinizing raw materials and finished goods. Pharmaceutical manufacturing clusters in Ireland exhibit high demand for these analytical solutions.
- Food Testing:This segment assesses food products for contaminants, nutritional content, and authenticity, driven by consumer safety concerns and regulations from bodies like the US FDA.
- Metals Analysis:This application focuses on determining the composition and purity of metals and alloys for quality control, material science, and recycling industries globally.
Regulatory pressures predominantly shape the expansion of Environmental Testing, with Pharmaceuticals seeing growth from material purity demands.
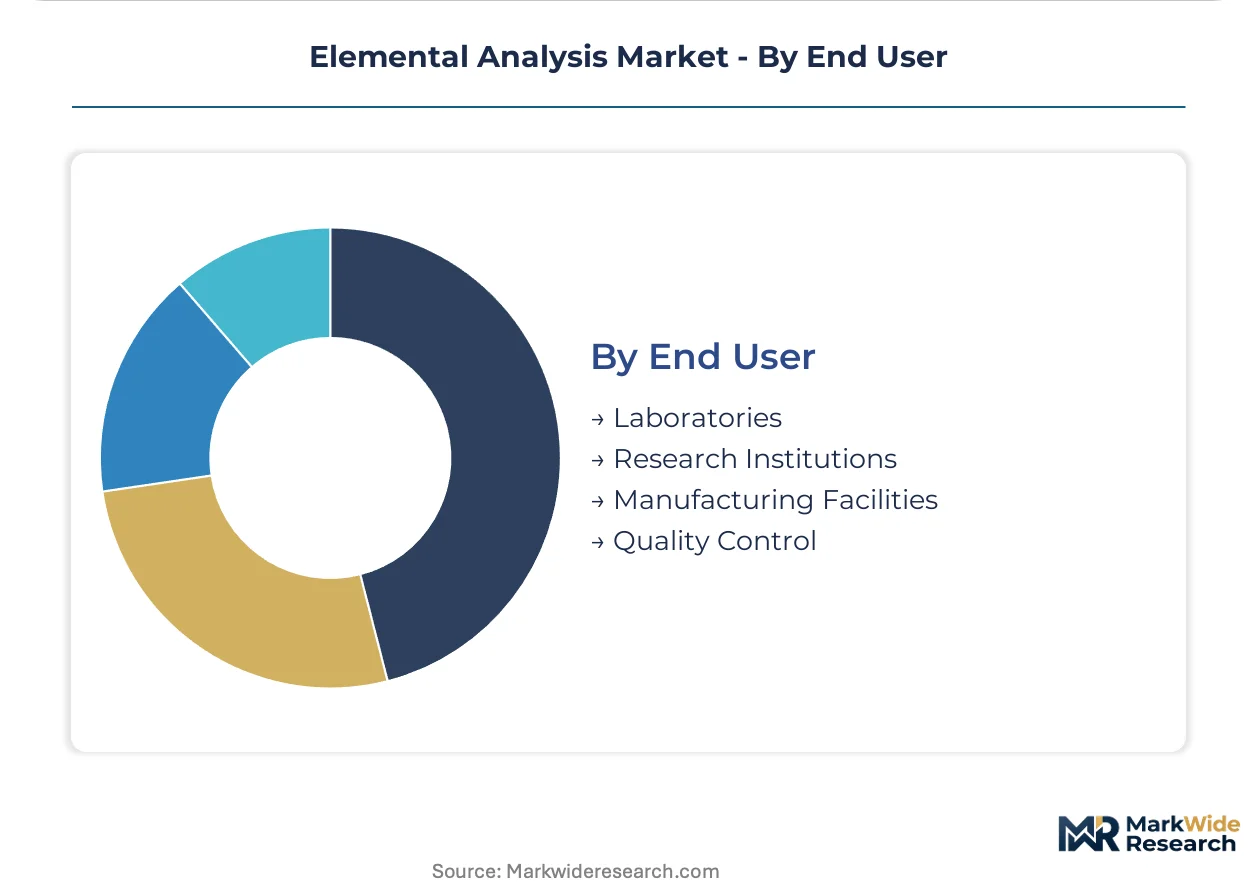
End User:
Customer type and operational scale dictate the specific elemental analysis solutions adopted, ranging from dedicated research facilities to integrated manufacturing lines.
- Laboratories:Commercial and contract research laboratories perform diverse elemental analyses for various clients, requiring versatile and high-throughput instrumentation. These facilities often adhere to ISO 17025 standards, influencing equipment purchasing decisions.
- Manufacturing Facilities:These users integrate elemental analysis into their production processes for real-time quality control, ensuring material specifications and minimizing defects. The semiconductor industry in South Korea exemplifies this integration for ultra-pure material verification.
- Research Institutions:Universities and government research centers utilize advanced elemental analyzers for fundamental scientific inquiry and method development, often supported by organizations like Thermo Fisher Scientific.
- Quality Control:Dedicated departments within various industries employ elemental analysis to verify product specifications and ensure compliance with industry standards and safety regulations.
Specialized analytical needs are met by Laboratories, whereas routine compliance tasks increasingly fall to Manufacturing Facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A robust maritime shipping network underpins global trade, facilitating the distribution of elemental analysis instruments and their components across continents. This infrastructure supports specialized manufacturing and research hubs, driving localized demand for advanced analytical solutions. Regulatory oversight further shapes regional market dynamics.
United States
Demand for elemental analysis in the United States stems from stringent pharmaceutical quality control and extensive environmental monitoring. The US Food and Drug Administration (FDA) mandates elemental impurity testing under ICH Q3D guidelines for drug products. Major research institutions and pharmaceutical manufacturing centers in states like California and Massachusetts drive innovation and instrument adoption.
Germany
German industry exhibits high demand for elemental analysis, particularly in advanced materials development and environmental protection. European Medicines Agency (EMA) guidelines, aligned with ICH Q3D, compel pharmaceutical companies to invest in high-sensitivity instrumentation. Industrial clusters in Bavaria and North Rhine-Westphalia integrate analytical solutions for quality control in automotive and chemical manufacturing.
South Korea
South Korea's robust semiconductor fabrication centers and advanced materials industries create significant demand for ultra-trace elemental analysis. The country's national regulators emphasize purity standards for critical components, driving the adoption of high-precision ICP-MS systems. Major technology hubs around Seoul and Gyeonggi Province are focal points for advanced analytical instrument deployment.
Ireland
Ireland's prominent pharmaceutical manufacturing clusters are a primary driver for elemental analysis market growth. Compliance with ICH Q3D guidelines for drug purity is a critical requirement for pharmaceutical companies operating in the region. Facilities in Dublin and Cork actively invest in sophisticated analytical instrumentation to meet international regulatory standards.
China
The Chinese market for elemental analysis is expanding due to rapid industrialization, environmental protection initiatives, and advanced manufacturing goals. National environmental regulations, including heavy metal limits, necessitate widespread testing in water and soil samples. Manufacturing zones in the Yangtze River Delta and Pearl River Delta utilize elemental analysis for quality control in electronics and materials production.
Elemental Analysis Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, with established global players alongside specialized regional manufacturers. This market structure supports both high-volume standardized instruments and custom-engineered solutions. Strategic archetypes include diversified analytical instrument providers and niche technology innovators. Companies are increasingly pursuing strategic partnerships and portfolio diversification to capture new application areas.
Within the diversified analytical instrument provider archetype, Thermo Fisher Scientific Inc. and Agilent Technologies Inc. exemplify global reach and broad product portfolios. These US-based corporations leverage extensive distribution networks to serve diverse end-user segments, from pharmaceutical research to environmental monitoring. Shimadzu Corporation, a Japan-based entity, also occupies a significant position, particularly in laboratory instrumentation and analytical solutions, reinforcing its presence in Asian markets. These players often compete on integrated service contracts and technological breadth.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Agilent Technologies Inc. |
| PerkinElmer Inc. |
| Shimadzu Corporation |
| Bruker Corporation |
| HORIBA Ltd. |
| Analytik Jena AG |
| SPECTRO Analytical Instruments GmbH |
| Elementar Analysensysteme GmbH |
| Others |
Cost & Logistics Intelligence
South Korea's concentration of advanced semiconductor manufacturing drives high demand for ultra-trace elemental analysis, allowing instrument manufacturers to command premium pricing for high-sensitivity ICP-MS systems. This specialized demand ensures robust margins for providers of precision analytical equipment.
Pricing Analysis
Volume-based discounts characterize the pricing structure for large institutional purchases of elemental analysis instruments, particularly high-end spectrometers. Price differentiation stems from instrument performance, specialized application solutions, and comprehensive integrated service contracts bundling support and consumables. Pricing softness impacts entry-level systems, driven by competition and the high total cost of ownership for smaller laboratories. Conversely, large pharmaceutical companies and semiconductor manufacturers exhibit lower price sensitivity for mission-critical, high-precision systems due to stringent regulatory compliance.
Supply Chain Analysis
Export control regimes on advanced analytical instrumentation and their specialized components limit global technology flows, particularly for high-sensitivity ICP-MS systems. The supply of these complex instruments largely concentrates in the United States, Japan, and Germany. Manufacturing relies on high-purity gases, precision optics, and advanced electronic sensors. Single-source vulnerability for critical components represents a structural risk. Distribution increasingly runs through direct manufacturer channels, especially for large institutional and government research accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The elemental analysis market is experiencing a buyer-power shift, driven by the consolidation of purchasing decisions among large institutional accounts. Direct manufacturer relationships are displacing traditional distribution channels, reshaping market dynamics.
For Market Incumbents:Pre-empt competitive threats from miniaturized, automated solutions by investing heavily in AI integration for method development and data interpretation. Leverage extensive global service networks to deepen integrated service contracts, addressing the high total cost of ownership for complex instrumentation. Develop specialized analytical solutions for emerging battery materials analysis and food authenticity applications to maintain market leadership. This counteracts the skilled operator scarcity and method validation complexity challenges.
For New Entrants and Emerging Players:Underpenetration in real-time, on-site quality control applications presents a significant opportunity for innovative players. Target industries like scrap metal recycling and mining with portable Laser-Induced Breakdown Spectroscopy (LIBS) analyzers for rapid, in-situ elemental analysis. Offer automated, AI-integrated solutions that reduce the need for highly skilled operators, thereby lowering the expertise barrier. This strategy allows market entry by providing cost-effective, field-deployable instruments for process control.
For Investors and Strategic Acquirers:Capital is best deployed toward niche technology innovators specializing in automation, AI integration, and miniaturized elemental analysis solutions. The long-term viability of this market hinges on continuous regulatory tightening and the technical demands of advanced manufacturing sectors. Acquisition targets should include firms with proprietary software for data interpretation or novel sensor technologies. The signal to watch is the increasing integration of real-time, on-site analytical capabilities into manufacturing process lines.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate AI into Analytical Software | Automates method development and data interpretation, lowering the expertise barrier for end-users. |
| Develop Portable LIBS Analyzers | Enables rapid, in-situ elemental analysis for industries like scrap metal recycling. |
| Expand Direct Service Networks | Deepens customer relationships and supports complex instrumentation for large institutional accounts. |
| Invest in Battery Materials Analysis R&D | Addresses the growing need for purity control in lithium and cobalt for electric vehicles. |
| Achieve ISO 17025 Method Validation | Ensures analytical accuracy and compliance for laboratories in regulated environments. |
Research Approach
Initial hypotheses were tested against primary input from pharmaceutical quality control managers, semiconductor fabrication engineers, and environmental agency compliance officers, then refined. This involved extensive interviews with laboratory directors and instrument specialists across key geographies. Secondary validation was conducted using US FDA guidelines, EMA directives, ISO 17025 standards, and relevant industry association reports. A robust bottom-up and top-down triangulation approach ensured data consistency.
Demand-supply balance modeling projected market evolution across the analysis window, considering technological advancements and regulatory shifts. Segmentation dimensions included product type, core technology, key applications, end-user categories, and geographic regulatory clusters. Compound Annual Growth Rates were derived from historical data, projected regulatory impacts, and technological adoption curves. Key inputs included ICH Q3D compliance rates and global semiconductor manufacturing output.
The forecast holds incumbent behavior within observed patterns; aggressive moves by disruptive technology startups or major regulatory overhauls would shift outcomes. Forecasts reflect assumptions regarding current market dynamics and technological trajectories. Material shifts in global trade policies or unforeseen advancements in sensor technology would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Paper Moisture Meter Market
Testing Equipment
CHS (Carbon Hydrogen Sulfur) Analyzers Market
Testing Equipment
Asia-Pacific Process Analytics Market
Testing Equipment
Global Host Cell Contaminant Testing Market
Testing Equipment
Test Point Hoses Market
Testing Equipment
Glass Testing Equipment Market
Testing Equipment
Grease Analyzer Market
Testing Equipment
Chlorine Meter Market
Testing Equipment
2D Chromatography Market
Testing Equipment
Ammonia Testing Market
Testing Equipment
Materials Testing Equipment Market
Testing Equipment
Chloride Reagents Kits Market
Testing Equipment
Gold Tester Market
Testing Equipment
Hydrocarbon Tester Market
Testing Equipment
Rheometer Market
Testing Equipment
Chemical Testing Services Market