
 Paint Stripper Market | 2026-2036
Paint Stripper Market Size, Share, and Industry Trends Forecast 2026-2036
Paint Stripper Market Analytics
The capital-intensity gap between integrated manufacturers and specialty chemical producers is collapsing as environmental compliance costs escalate. Sherwin-Williams Company leverages its captive distribution network to sustain margin capture across North American retail channels. PPG Industries, Inc. anchors its position through backward integration into resin and additive supply chains. Henkel AG & Co. KGaA differentiates via industrial-grade formulations that navigate stringent workplace safety protocols.
Paint stripper denotes a chemical formulation engineered to dissolve, soften, or mechanically lift cured coatings from substrates through alkaline hydrolysis, solvent penetration, or enzymatic action, typically operating at pH ranges of 11–14 for caustic variants or incorporating N-methylpyrrolidone, benzyl alcohol, or dibasic esters in safer alternatives. Its primary commercial purpose centers on surface preparation for refinishing, restoration, and maintenance across architectural, industrial, and transportation assets. Aqueous formulations now lead volume shipments as regulatory pressure on volatile organic compounds intensifies, while bio-based alternatives represent the fastest-expanding margin pool despite higher unit costs. The automotive application segment concentrates demand from collision repair networks and OEM refinishing operations where throughput speed governs purchasing decisions.
The EPA's risk management rule under TSCA Section 6 restricts methylene chloride in consumer paint strippers, while OSHA's methylene chloride standard governs occupational exposure limits in commercial settings. The EU REACH regulation and F-Gas Directive further constrain solvent chemistries available to European formulators, redirecting product development toward low-VOC and bio-derived alternatives. Stakeholders must monitor pending state-level prohibitions in California and New York that could outpace federal timelines and force accelerated portfolio restructuring.
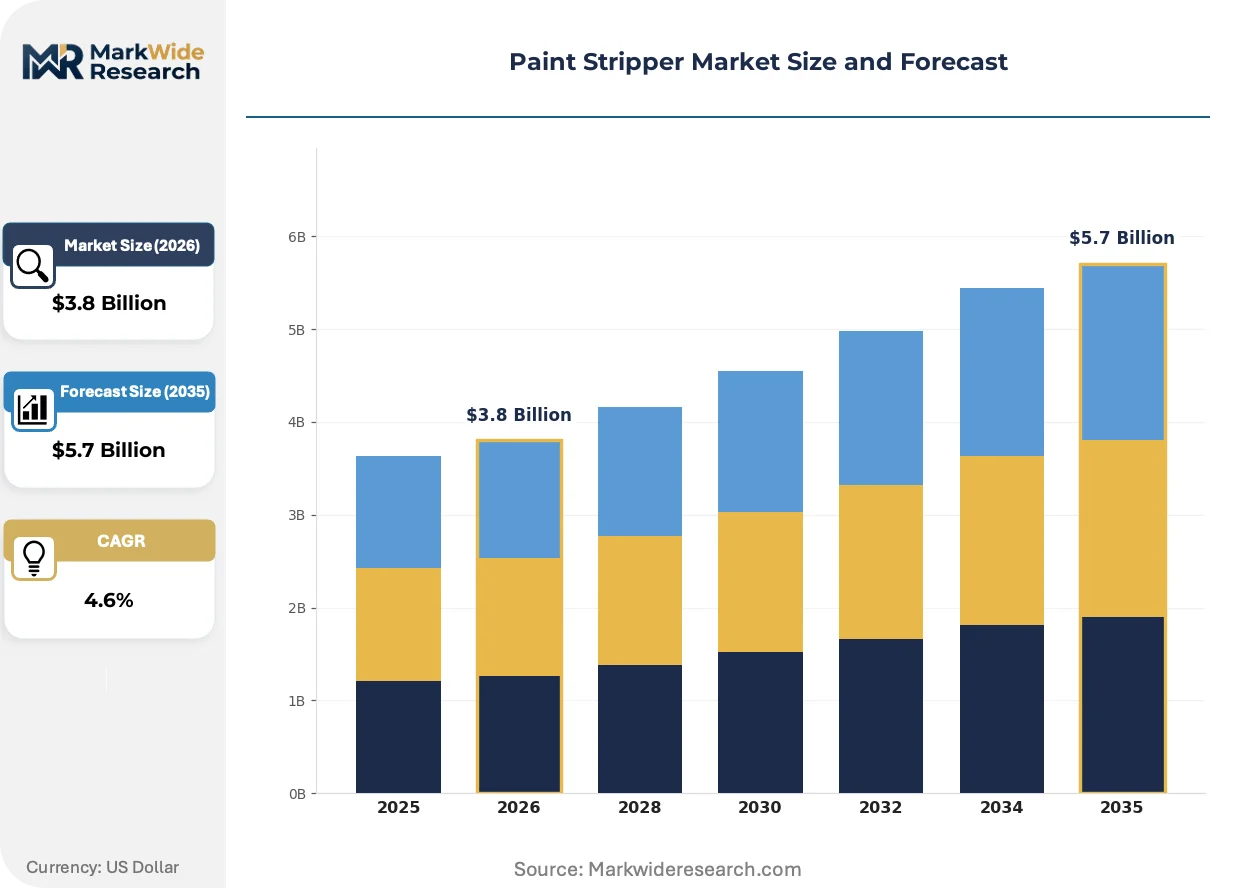
Market Dynamics
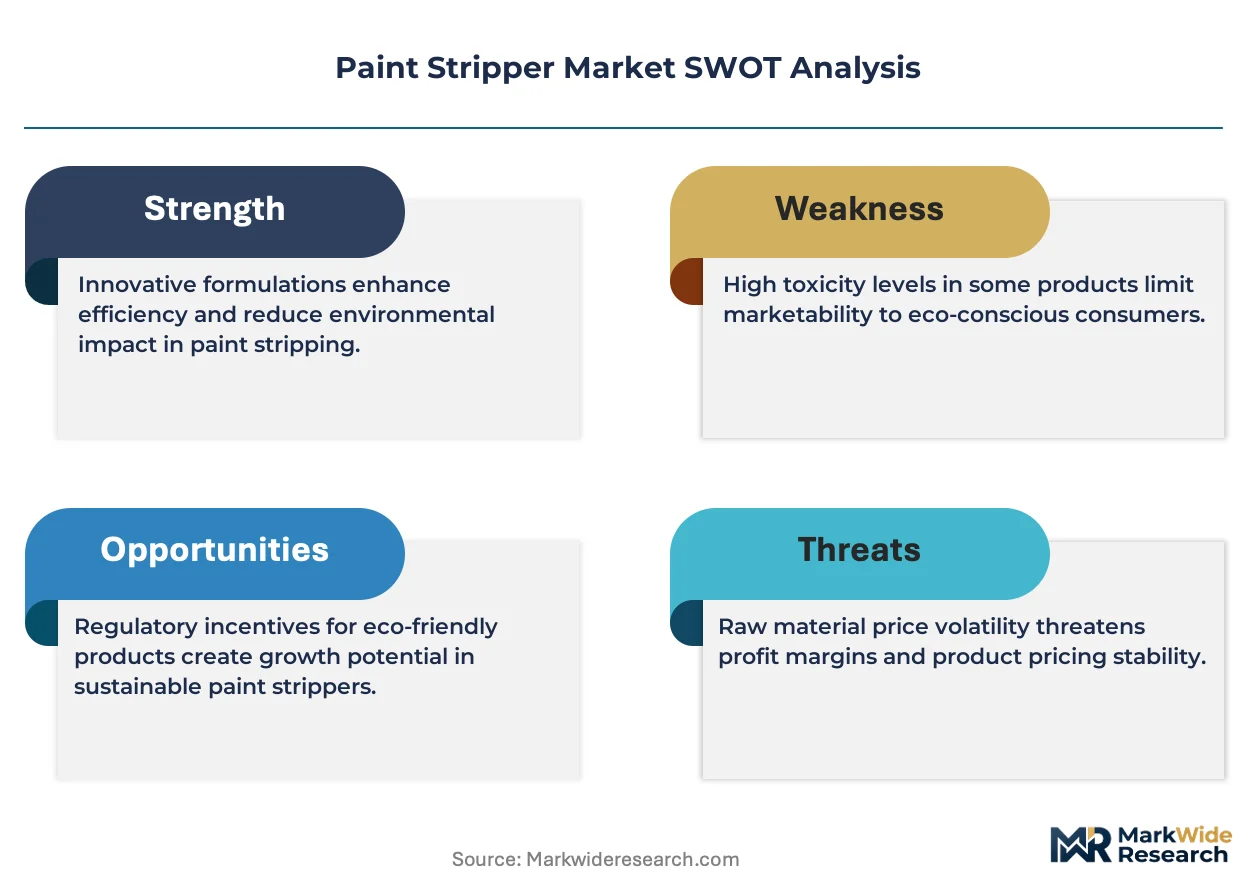
EPA restrictions on methylene chloride formulations are forcing formulators to rebuild product portfolios around safer chemistries, collapsing the historical cost advantage of solvent-based systems and redistributing margin pools toward aqueous and bio-derived alternatives.
Growth Catalysts
- Automotive refinishing expansion:Rising vehicle age across the United States, Germany, and Japan sustains collision repair network demand for high-throughput stripping systems.
- REACH compliance migration:European formulators accelerating low-VOC aqueous development capture displaced solvent volume as F-Gas Directive constraints tighten.
- Infrastructure rehabilitation:Federal bridge and building restoration programs in the United States generate steady commercial offtake for industrial-grade caustic formulations.
Market Restraints
- Raw material cost volatility:Benzyl alcohol and dibasic ester feedstock prices fluctuate with petrochemical cycle swings, compressing formulator margins.
- Supply concentration risk:Specialty surfactant production concentrates among German and Dutch chemical clusters, creating geographic vulnerability for aqueous formulation scale-up.
- Performance gap in safer alternatives:N-methylpyrrolidone replacements require longer dwell times on epoxy and polyurethane coatings, limiting adoption in time-sensitive OEM operations.
Strategic Opportunities
- Bio-based formulation white space:Enzymatic and terpene-derived systems targeting California's anticipated state-level methylene chloride prohibition ahead of federal timelines.
- Aerospace MRO penetration:Stricter workplace exposure limits under OSHA's methylene chloride standard create entry points for industrial-grade benzyl alcohol systems in aircraft depainting operations.
- Direct-to-contractor digital channels:E-commerce platforms serving independent restoration contractors bypass traditional distribution markups in the United States and United Kingdom.
Industry Challenges
- Formulation chemist scarcity:Expertise in alkaline hydrolysis and enzymatic catalysis concentrates among aging specialists, constraining R&D throughput for safer chemistry transitions.
- Multi-jurisdiction registration timelines:TSCA Section 6 compliance, EU CLP classification, and state-level VOC rules require parallel regulatory submissions, extending product launch cycles.
- Legacy equipment incompatibility:Aqueous systems demand stainless steel tankage and modified spray application hardware, raising retrofit costs for existing contractor operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paint Stripper Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aqueous, Solvent-Based, Bio-Based, Gel Application: Wood, Metal, Concrete, Automotive End User: DIY, Commercial, Industrial, Automotive Repair Packaging Type: Container, Spray Can, Pail, Drum |
| Companies Covered | 3M Company, Sherwin-Williams Company, PPG Industries, Inc., Akzo Nobel N.V., Henkel AG & Co. KGaA, Rust-Oleum Corporation, Franmar Chemical, Inc., Jasco Products Company, LLC, Sunnyside Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paint Stripper Market Evolving Landscape
Formulation science is bifurcating between high-performance industrial systems and consumer-safe alternatives, with regulatory pressure acting as the primary accelerant rather than end-user preference alone.
Enzymatic paint stripping technology is fragmenting the traditional solvent-chemistry value chain. Cellulase and lipase formulations hydrolyze specific coating binders without substrate damage. Automotive collision repair networks in Japan and Germany pilot these systems for aluminum panel refinishing. The technology is fragmenting established supplier relationships as biotechnology firms enter chemical supply chains previously dominated by petrochemical majors.
EPA's risk management rule under TSCA Section 6 imposes workplace exposure controls and consumer sales prohibitions on methylene chloride products. Commercial formulators must reformulate or exit the retail channel entirely. OSHA's companion methylene chloride standard tightens permissible exposure limits in industrial settings, driving demand for closed-loop application equipment and alternative chemistries among United States-based refinishing operations.
Certification-driven procurement now governs contractor purchasing decisions. LEED v4.1 and WELL Building Standard compliance requirements specify low-VOC surface preparation methods. Facility managers in commercial real estate portfolios across the United States and United Kingdom now mandate aqueous or bio-based stripping for interior renovation projects, displacing solvent-based products regardless of unit cost premiums.
Paint Stripper Market Segmentation
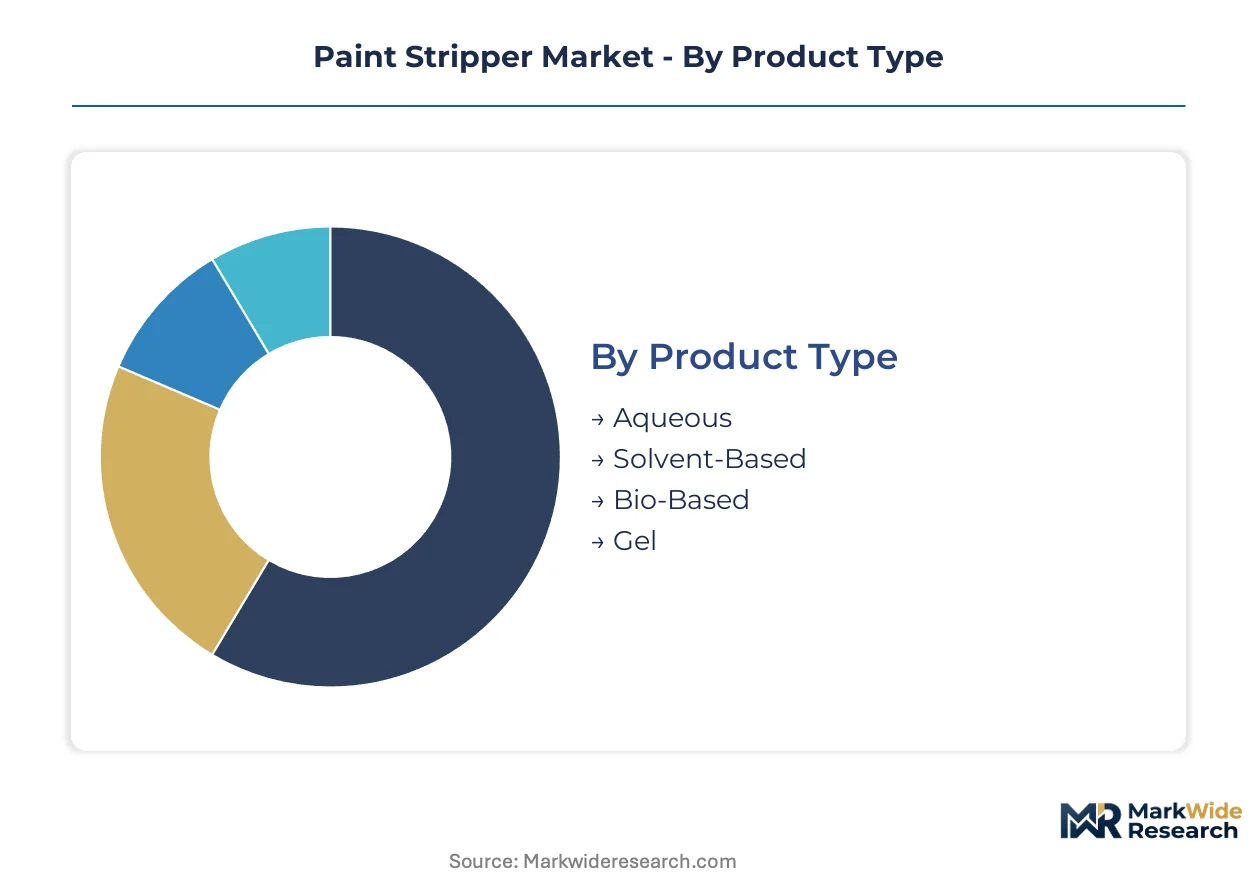
Segmentation in the paint stripper market tracks how regulatory pressure and performance requirements split demand across formulation chemistries, substrate compatibility, and user sophistication. Each dimension reveals distinct margin pools and substitution vulnerabilities as aqueous and bio-based alternatives displace legacy solvent systems.
Product Type:
Aqueous formulations face the steepest substitution pressure from bio-based alternatives as EPA restrictions on methylene chloride accelerate chemistry transitions across all price tiers.
- Aqueous:Water-based systems incorporating alkaline hydrolysis agents operate at pH 11–14 to dissolve cured coatings without volatile organic compound emissions. Demand concentrates in United States commercial real estate renovation where LEED v4.1 certification mandates low-VOC surface preparation methods. These systems require stainless steel application equipment, raising contractor switching costs.
- Solvent-Based:Traditional formulations utilizing N-methylpyrrolidone, benzyl alcohol, or dibasic esters deliver rapid coating penetration and shorter dwell times on epoxy substrates. Automotive OEM refinishing operations in Germany and Japan retain preference for solvent performance despite regulatory headwinds from OSHA exposure limits and REACH authorization requirements.
- Bio-Based:Enzymatic and terpene-derived systems hydrolyze coating binders through cellulase and lipase catalysis without substrate damage. California's anticipated state-level methylene chloride prohibition ahead of federal timelines positions this segment for accelerated adoption.
- Gel:Thickened formulations with controlled cling properties enable vertical surface application without runoff. Historic building restoration contractors in the United Kingdom specify gel systems for ornate architectural detail work.
Aqueous anchors the volume base while bio-based gains share at the steepest rate.
Application:
Substrate-specific performance requirements split the market between high-throughput industrial operations and precision restoration work with divergent dwell time tolerances.
- Wood:Formulations must balance coating removal efficacy against substrate damage prevention on porous grain structures. Furniture restoration workshops in Italy and antique dealers in Massachusetts drive demand for low-pH enzymatic systems.
- Metal:Alkaline and solvent systems target oxide layer preservation during coating removal. United States military vehicle depots and German automotive collision networks specify metal-grade formulations for aluminum panel refinishing.
- Concrete:Caustic formulations penetrate masonry pores to lift epoxy and urethane floor coatings. Infrastructure rehabilitation programs across United States federal bridge portfolios sustain commercial offtake for industrial-grade systems.
- Automotive:Speed-governed stripping for collision repair and OEM refinishing demands rapid throughput with substrate compatibility. Japanese and German pilot programs test enzymatic alternatives for aluminum-intensive vehicle architectures.
Automotive commands the highest throughput requirements while concrete infrastructure work delivers the most stable demand profile.
End User:
User sophistication determines formulation selection authority, with certified contractors exercising stricter chemistry specifications than retail purchasers.
- DIY:Consumer purchasers face EPA prohibition on methylene chloride retail sales, redirecting volume toward aqueous and bio-based alternatives with extended dwell times. Home improvement retailers in the United States and United Kingdom now stock reformulated product lines exclusively.
- Commercial:Independent restoration contractors and small refinishing shops balance performance requirements against equipment retrofit costs. E-commerce platforms serving this segment bypass traditional distribution markups.
- Industrial:Large-scale manufacturing facilities and maintenance depots specify closed-loop application systems to comply with OSHA methylene chloride exposure limits. Aerospace MRO operations in the United States represent a concentrated demand pocket for benzyl alcohol formulations.
- Automotive Repair:Collision repair networks prioritize throughput speed in purchasing decisions. German and Japanese facilities pilot enzymatic systems for aluminum panel work while retaining solvent systems for steel substrates.
Industrial users anchor the value pool while automotive repair channels expand most quickly as vehicle age increases across major economies.
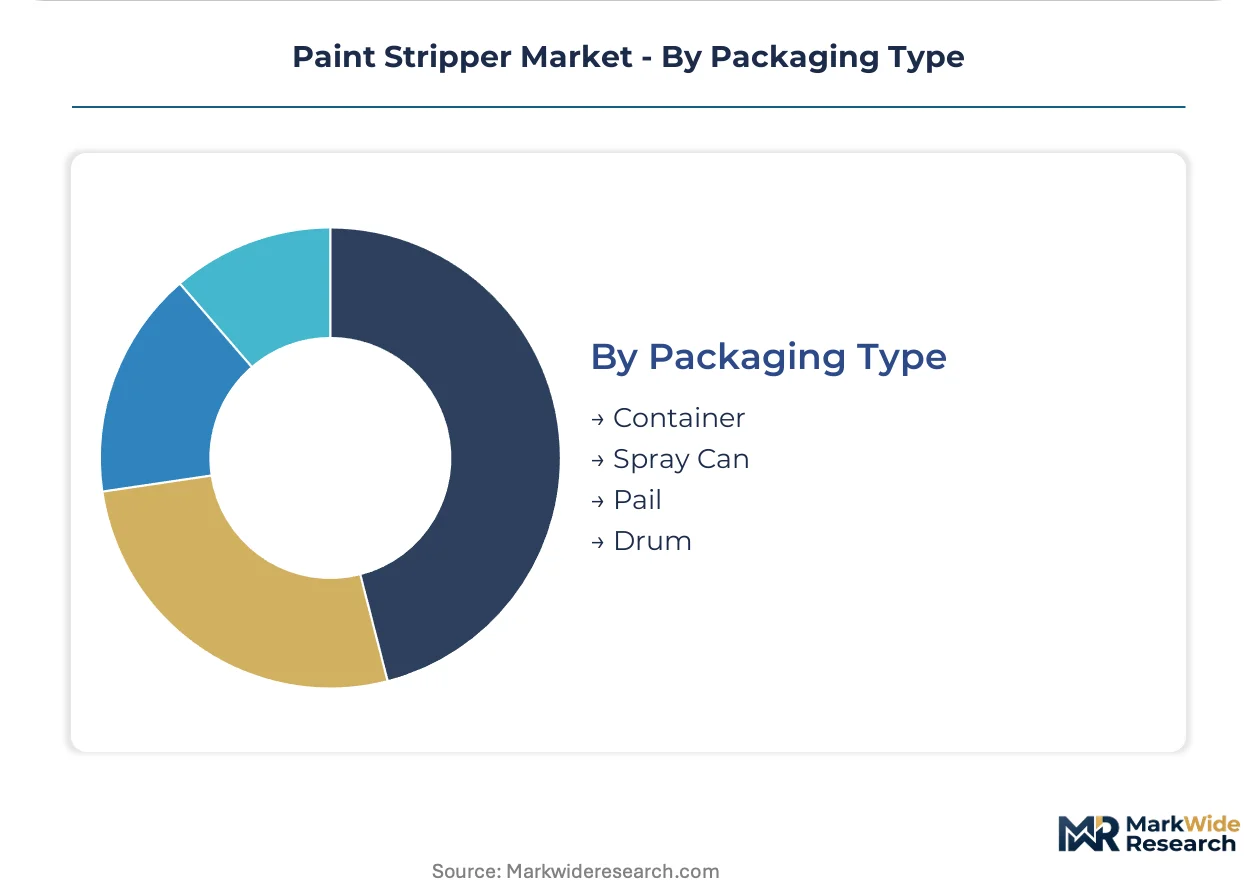
Packaging Type:
Packaging format aligns with application scale and regulatory handling requirements, from consumer convenience to bulk industrial supply.
- Container:Standard plastic and metal vessels for brush or dip application serve commercial contractors and DIY users. California and New York state-level VOC regulations influence container sizing and labeling requirements.
- Spray Can:Aerosol delivery enables controlled application on complex geometries. Retail channel restrictions on methylene chloride formulations have compressed this format's addressable market.
- Pail:Mid-volume packaging serves independent restoration contractors and small commercial shops. United Kingdom heritage building specialists favor pail formats for gel product application.
- Drum:Bulk supply for industrial-scale operations and automotive refinishing networks. German chemical clusters supply specialty surfactant concentrates in drum format for aqueous formulation scale-up.
Drum packaging dominates industrial value capture while container formats face margin compression from retail channel restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where federal infrastructure programs sustain premium industrial-grade offtake, while European formulators absorb compliance cost premiums under REACH and F-Gas Directive constraints without equivalent volume elasticity.
United States
Bridge rehabilitation programs and aging vehicle fleets drive demand across industrial and automotive refinishing channels. EPA's TSCA Section 6 risk management rule and OSHA's methylene chloride exposure standard force rapid chemistry transitions. Gulf Coast petrochemical clusters supply benzyl alcohol and dibasic ester feedstocks for aqueous formulation scale-up.
Germany
Automotive OEM refinishing operations and collision repair networks anchor solvent-grade consumption despite regulatory headwinds. ECHA REACH authorization requirements and F-Gas Directive constraints redirect R&D toward low-VOC alternatives. Rhine-Ruhr chemical clusters concentrate specialty surfactant production for aqueous system manufacturing.
Japan
Aluminum-intensive vehicle architectures and precision metal finishing sustain demand for substrate-compatible stripping systems. METI industrial chemical standards govern workplace exposure protocols for automotive facilities. Nagoya-Toyota industrial corridor pilots enzymatic alternatives for lightweight panel refinishing.
United Kingdom
Heritage building restoration and commercial real estate renovation generate steady demand for gel and low-pH enzymatic formulations. CLP classification requirements and anticipated post-Brexit divergence from EU chemical rules create registration uncertainty. Greater Manchester and West Midlands restoration contractors specify aqueous systems for LEED-compliant interior projects.
China
Industrial manufacturing expansion and infrastructure maintenance build demand across metal and concrete substrate applications. MEE environmental standards and dual carbon goals constrain solvent-based formulation expansion. Yangtze River Delta chemical parks scale N-methylpyrrolidone replacement production for domestic and export markets.
Paint Stripper Market Competitive Landscape
Concentration sits with diversified coatings majors that leverage captive distribution and backward integration into resin supply chains. Three archetypes dominate: integrated coatings conglomerates with retail channel control, specialty chemical houses with industrial formulation expertise, and regional producers serving price-sensitive contractor segments. Competitive moves center on portfolio restructuring around safer chemistries and geographic expansion into regulatory-advanced markets where early compliance creates positioning advantages.
Among North American integrated coatings manufacturers, Sherwin-Williams Company and PPG Industries, Inc. occupy positions that exemplify distribution-captured margin structures, while Henkel AG & Co. KGaA represents the European industrial-grade specialization archetype with workplace safety protocol navigation capabilities.
| Leading Market Players |
|---|
| 3M Company |
| Sherwin-Williams Company |
| PPG Industries, Inc. |
| Akzo Nobel N.V. |
| Henkel AG & Co. KGaA |
| Rust-Oleum Corporation |
| Franmar Chemical, Inc. |
| Jasco Products Company, LLC |
| Sunnyside Corporation |
| Others |
Value Network & Pricing Analysis
LEED v4.1 certification gates both supplier qualification and price differentiation simultaneously, forcing contractors to source aqueous formulations at premium unit costs while excluding solvent-based alternatives from commercial real estate renovation bids. This regulatory filter compresses margins for uncertified formulators while concentrating pricing power among compliant producers with captive distribution networks.
Pricing Analysis
The customization-premium spread separates standard aqueous formulations from engineered systems configured to specific substrate requirements. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with industrial drum purchasers capturing scale discounts unavailable to container-format DIY channels. Pricing pressure stems from benzyl alcohol feedstock volatility in Gulf Coast petrochemical clusters. Automotive collision repair networks exhibit lowest price sensitivity due to throughput speed requirements, while independent restoration contractors face acute cost compression.
Supply Chain Analysis
Rhine-Ruhr chemical cluster concentration in Germany creates a chokepoint for specialty surfactant supply to European aqueous formulators. Raw material sourcing draws from United States Gulf Coast benzyl alcohol production, German dibasic ester synthesis, and Dutch enzymatic catalyst manufacturing. Single-source vulnerability concentrates in German-Dutch surfactant supply corridors. Distribution runs through captive coatings retail networks in North America and specialty chemical distributors in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemist expertise in alkaline hydrolysis and enzymatic catalysis concentrates among aging specialists, constraining R&D throughput and creating acquisition premiums for teams with proven safer-chemistry transition experience.
For Market Incumbents: Shield margin capture by accelerating backward integration into resin and additive supply chains before benzyl alcohol price volatility intensifies. Prioritize certification investment for LEED v4.1 compliance to lock out non-compliant regional competitors from United States commercial real estate channels.
For New Entrants and Emerging Players: Lead with bio-based enzymatic formulations targeting California's anticipated state-level methylene chloride prohibition ahead of federal EPA timelines. Penetrate aerospace MRO depainting operations where OSHA exposure limits create immediate demand for benzyl alcohol alternatives, using direct-to-contractor digital channels to bypass established distribution markups.
For Investors and Strategic Acquirers: EPA's TSCA Section 6 risk management rule reshapes the acquisition landscape by devaluing methylene chloride-dependent product portfolios and premiuming aqueous formulation capabilities. Target specialty chemical houses with demonstrated REACH compliance migration experience. Watch for state-level prohibitions in New York and California as inflection signals for accelerated portfolio restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Gulf Coast petrochemical proximity secures benzyl alcohol feedstock cost stability for aqueous scale-up. |
| Enzymatic Formulation R&D Partnership | Biotechnology firm collaboration accelerates cellulase catalysis development for aluminum panel refinishing. |
| LEED v4.1 Certification Investment | Compliance credential unlocks United States commercial real estate renovation procurement mandates. |
| Direct-to-Contractor Digital Channel | E-commerce platform bypasses traditional distribution markups in United Kingdom heritage restoration segments. |
| California Market Pre-Positioning | State-level methylene chloride prohibition readiness captures regulatory-advanced market positioning. |
Research Methodology
A standing panel of formulation chemists, automotive refinishing procurement managers, commercial real estate facility directors, and specialty chemical distribution partners provided ongoing calibration across primary interview cycles. Secondary validation drew from EPA TSCA filings, OSHA exposure standard documentation, ECHA REACH authorization databases, and United States customs trade data. Bottom-up volume modeling triangulated against top-down market sizing from coatings industry association reports.
Consistency checks validated outputs against ACC chemical production indices and Cefic sector benchmarks across the analysis window. Segmentation modeling tracked formulation chemistry, substrate application, end-user sophistication, and packaging format dimensions. CAGRs derived from regression analysis of historical shipment data correlated with automotive fleet age demographics and federal infrastructure appropriation patterns.
Forecasts assume regulatory continuity in EPA TSCA Section 6 enforcement and ECHA REACH authorization timelines; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as California and New York state-level prohibition timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Hydroxyethyl Methyl Cellulose Market
Chemicals
Global P-Phenylenediamine Market
Chemicals
Middle East Construction Chemicals Market
Chemicals
Paraphenylenediamine (PPD) Market
Chemicals
Household Insecticides Market
Chemicals
Global Bleaching Agents Market
Chemicals
Potassium Alum Market
Chemicals
Metal Finishing Chemicals Market
Chemicals
Allyl Alcohol Market
Chemicals
RO Membrane Chemicals Market
Chemicals
Caustic Soda Market
Chemicals
Methyldiisopropanolamine Market
Chemicals
(S)-(+)-2-Amino-1-Propanol Market
Chemicals
RDX and HMX Market
Chemicals
Tetrapotassium Pyrophosphate Market
Chemicals
Myclobutanil Market