
 Sodium Fluorosilicate Market | 2026-2036
Sodium Fluorosilicate Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Fluorosilicate Market Analysis
Maintenance contracts for fluoridation system calibration and dosing optimization are broadening what municipalities purchase beyond bulk chemical supply. Solvay leverages its European production network to sustain long-term municipal contracts. Hunan Guangcheng Chemical Industry Development Co. Ltd anchors supply for Asian textile processors seeking consistent technical-grade volumes. Honeywell competes through integrated water treatment platforms that bundle sodium fluorosilicate with monitoring hardware.
Sodium fluorosilicate, Na2SiF6, is an inorganic salt produced through neutralization of fluorosilicic acid with sodium chloride or sodium carbonate, typically yielding 98-99% purity for industrial applications and functioning primarily as a fluorine source in water treatment and dental care formulations. Industrial grade dominates current production volumes due to established use in soil stabilization and textile processing, while pharmaceutical grade commands premium positioning as dental product manufacturers tighten purity requirements under evolving pharmacopeial standards. Water fluoridation application segments retain stable demand from municipal procurement cycles, whereas textile treatment represents a faster-growing channel driven by East Asian fabric finishing expansion.
The EPA regulates fluoridation additives under NSF/ANSI Standard 60 in the United States, limiting permissible contaminant levels and shaping supplier qualification requirements for municipal contracts. REACH registration requirements in Europe govern fluorosilicate import volumes and purity documentation, while China's SAMR enforces GB/T quality benchmarks for domestic distribution. India's BIS certification for water treatment chemicals creates additional compliance layers for exporters targeting subcontinental municipalities. Stakeholders must monitor regulatory divergence between fluoridation safety thresholds and industrial emission limits as jurisdictions recalibrate fluorine compound policies.
Market Dynamics
Municipal water fluoridation programs in Brazil and India are expanding procurement volumes while China's tightening GB standards force purity upgrades across manufacturing clusters. This dual pressure from demand expansion and specification escalation compresses supplier margins and accelerates technical-grade differentiation.
Growth Catalysts
- Water treatment infrastructure:Municipal fluoridation mandates in Brazilian states and Indian cities are institutionalizing bulk chemical procurement cycles. These programs lock in multi-year supply agreements with qualified vendors.
- REACH registration:European chemical compliance frameworks are consolidating supplier bases by raising documentation barriers. Registered producers capture preferential access to industrial textile processors seeking audit-ready supply chains.
- East Asian textile clusters:Fabric finishing expansion in manufacturing hubs across China and Vietnam is absorbing technical-grade volumes for stain-resistant and flame-retardant treatments.
Market Restraints
- Fluorosilicic acid supply concentration:Input material production clusters in specific Chinese provinces create geographic vulnerability for downstream sodium fluorosilicate manufacturers dependent on neutralization feedstock.
- Substitution by fluorosilicic acid direct feed:Some municipal water systems are bypassing dry salt conversion entirely, installing liquid acid dosing systems that eliminate sodium fluorosilicate from the treatment chain.
- EPA NSF/ANSI Standard 60 compliance costs:Contaminant testing and certification expenses for US municipal qualification disproportionately burden smaller producers seeking entry into regulated procurement channels.
Strategic Opportunities
- Indian subcontinent underpenetration:BIS certification requirements have filtered out informal suppliers, creating structured openings for documented producers to capture state-level water board contracts.
- Integrated dosing platform bundling:Hardware-software-chemical combinations that automate fluoridation monitoring and calibration are displacing commodity-only supply relationships in advanced municipal systems.
- Pharmaceutical-grade purification:Dental care formulation manufacturers are tightening pharmacopeial specifications, enabling premium positioning for producers with crystallization and heavy-metal removal capabilities.
Industry Challenges
- Analytical chemistry talent scarcity:Qualified personnel for GB/T and BIS compliance documentation, impurity profiling, and batch certification are concentrated among established producers, constraining quality expansion.
- Legacy dosing system retrofit complexity:Municipalities operating decades-old fluoridation infrastructure face integration friction when upgrading to precision-controlled feed systems compatible with modern purity grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Fluorosilicate Market |
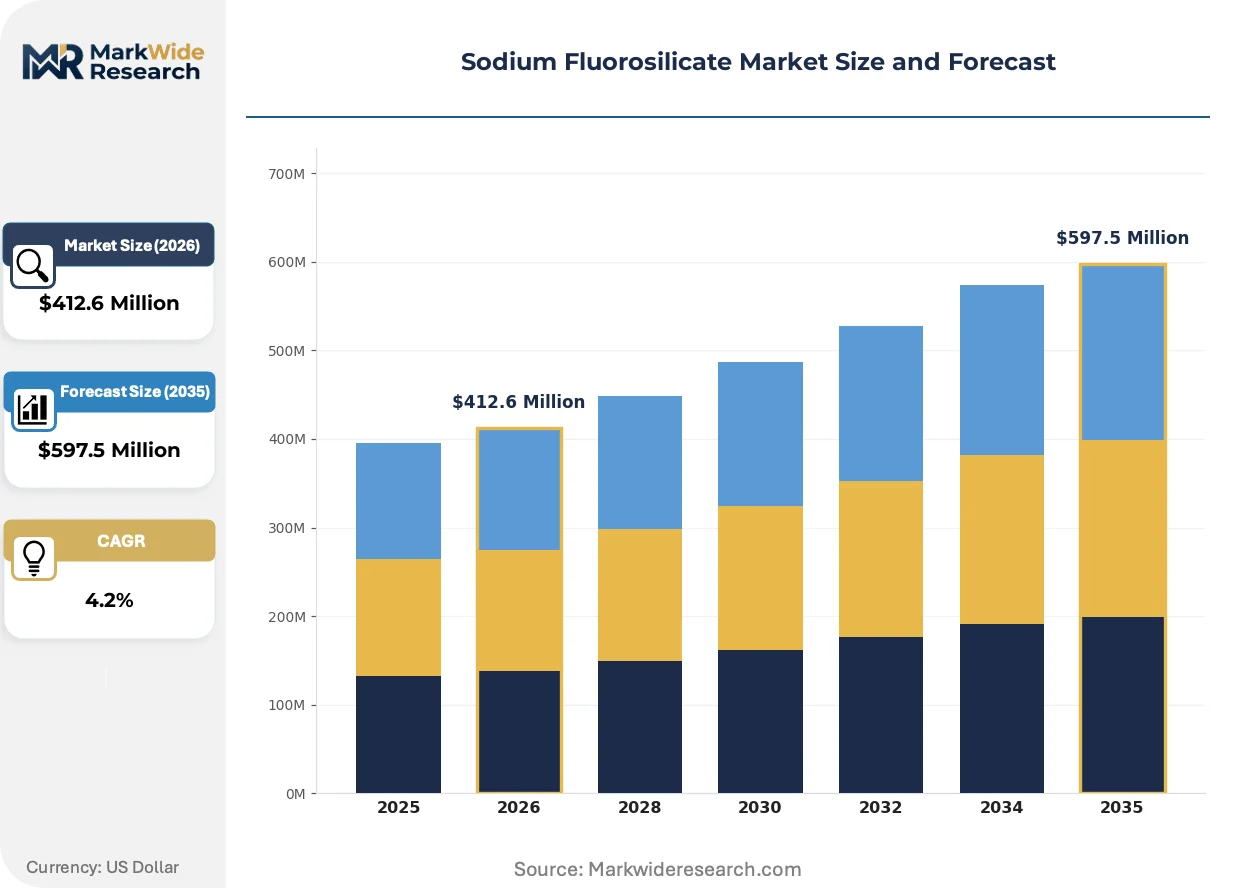
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $597.5 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Food Grade, Pharmaceutical Grade, Technical Grade Application: Water Fluoridation, Dental Products, Soil Stabilization, Textile Treatment End User: Municipalities, Dental Clinics, Agriculture, Textile Industry Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | ORICA Chemicals, Crystran, Solvay, Spectrum Chemical MFG Corp., Hunan Guangcheng Chemical Industry Development Co. Ltd, Prayon, Merck KGaA, American Elements, Honeywell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Fluorosilicate Market Emerging Trajectories
Continuous crystallization and membrane filtration technologies are reshaping production economics while regulatory divergence between fluoridation safety thresholds and industrial emission limits forces dual-track compliance investments. These pressures are compressing commodity margins and rewarding technical differentiation.
Advanced crystallization systems with real-time particle size control are absorbing market share from conventional batch precipitation methods. Municipal procurement officers in Brazil and India are specifying these higher-purity grades for their reduced caking and improved dissolution kinetics. The technology is absorbing volume from standard technical-grade supply as buyers prioritize dosing reliability over unit cost.
China's SAMR enforcement of tightened GB/T quality benchmarks is forcing domestic producers to upgrade purification infrastructure. Industrial textile processors seeking export certification are diverting procurement toward documented compliance-grade supply. Manufacturers with dual certification for water treatment and industrial applications are capturing cross-segment contracts previously split among specialized suppliers.
Service unbundling is fragmenting traditional chemical supply relationships. Municipalities in São Paulo state and Maharashtra are separating chemical procurement from system calibration and maintenance, creating distinct vendor categories. This shift is most visible in Brazilian and Indian urban water authorities with dedicated fluoridation program budgets, where technical service contracts now run parallel to bulk chemical tenders.
Sodium Fluorosilicate Market Segmentation
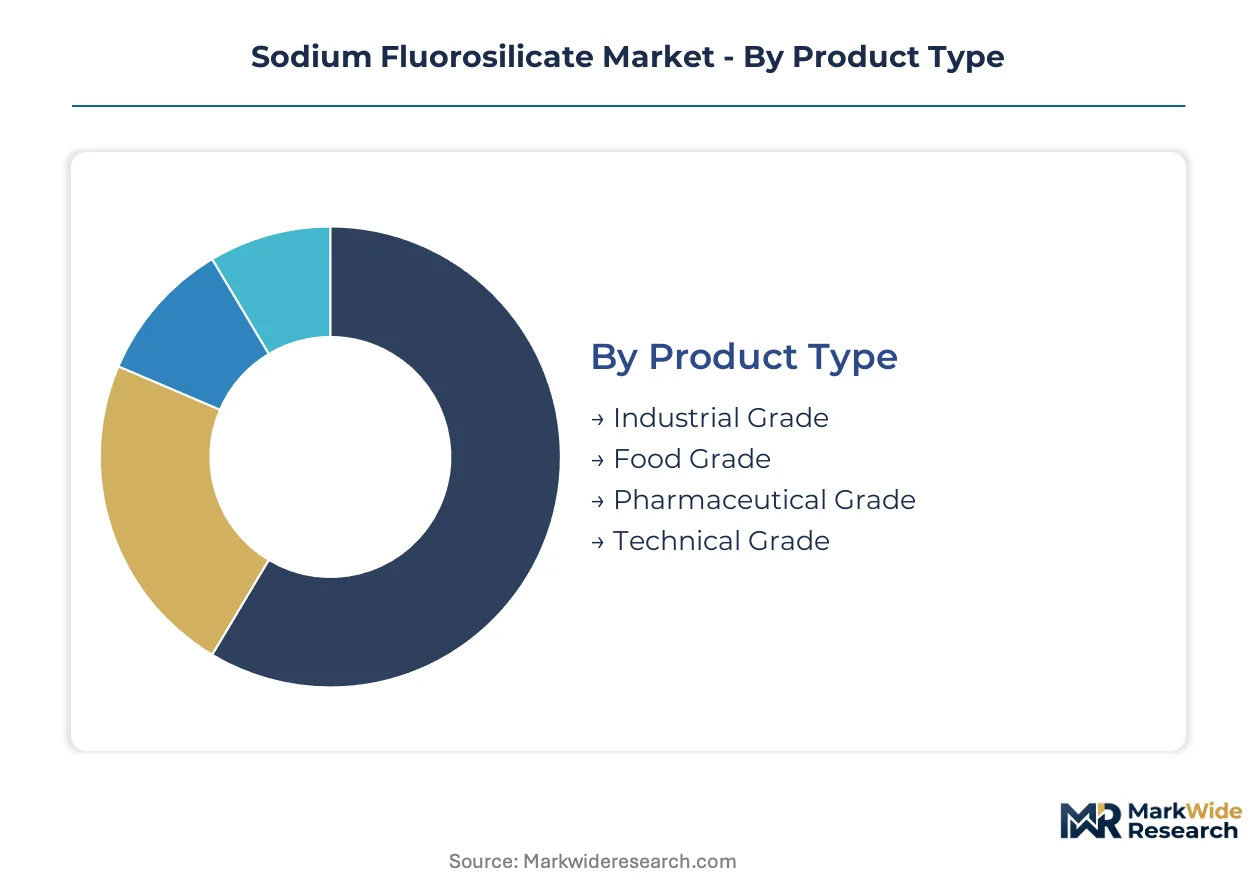
Sodium fluorosilicate procurement patterns diverge sharply between regulated municipal water systems and industrial processors. Specification requirements, purity thresholds, and compliance documentation create distinct commercial channels that rarely overlap.
Product Type:
Purity gradients determine pricing architecture and regulatory qualification pathways across manufacturing tiers.
- Industrial Grade:Standard 98-99% purity specification serves soil stabilization and bulk textile processing. Chinese manufacturing clusters absorb the largest volumes for fabric finishing operations.
- Pharmaceutical Grade:Crystallization and heavy-metal removal capabilities achieve pharmacopeial compliance for dental care formulations. Premium positioning rewards producers with documented batch certification and impurity profiling infrastructure.
- Food Grade:NSF/ANSI Standard 60 alignment permits municipal water system deployment with contaminant thresholds below industrial specifications.
- Technical Grade:Intermediate purity band captures textile processors seeking export certification without pharmaceutical-grade cost structures.
Mature deployment sits with Industrial Grade. Newer deployment is concentrated in Pharmaceutical Grade.
Application:
End-use chemistry dictates volume scale and contract duration, with infrastructure-linked programs locking in multi-year supply agreements.
- Water Fluoridation:Municipal procurement cycles institutionalize bulk chemical demand. Brazilian state water boards and Indian urban authorities are expanding program coverage with qualified vendor lists.
- Textile Treatment:Stain-resistant and flame-retardant fabric finishing in Vietnam and China is climbing the fastest. East Asian manufacturing hubs specify technical-grade volumes with documented compliance for export markets.
- Dental Products:Toothpaste and mouthwash formulations require pharmaceutical-grade inputs under tightening pharmacopeial standards.
- Soil Stabilization:Construction and geotechnical applications absorb industrial-grade volumes with less stringent purity documentation.
Contract duration extends longest in Water Fluoridation. Margin compression concentrates in Soil Stabilization.
End User:
Buyer sophistication varies from calibrated dosing systems to commodity spot purchasing.
- Municipalities:Brazilian and Indian urban water authorities separate chemical procurement from system maintenance, creating parallel vendor categories.
- Textile Industry:Fabric finishers in Chinese and Vietnamese manufacturing clusters prioritize audit-ready supply chains for export certification.
- Dental Clinics:Formulation manufacturers drive pharmaceutical-grade demand with tightening heavy-metal specifications.
- Agriculture:Soil treatment applications purchase industrial-grade volumes through distributor networks with minimal technical service attachment.
Technical service bundling dominates Municipalities. Spot purchasing characterizes Agriculture.
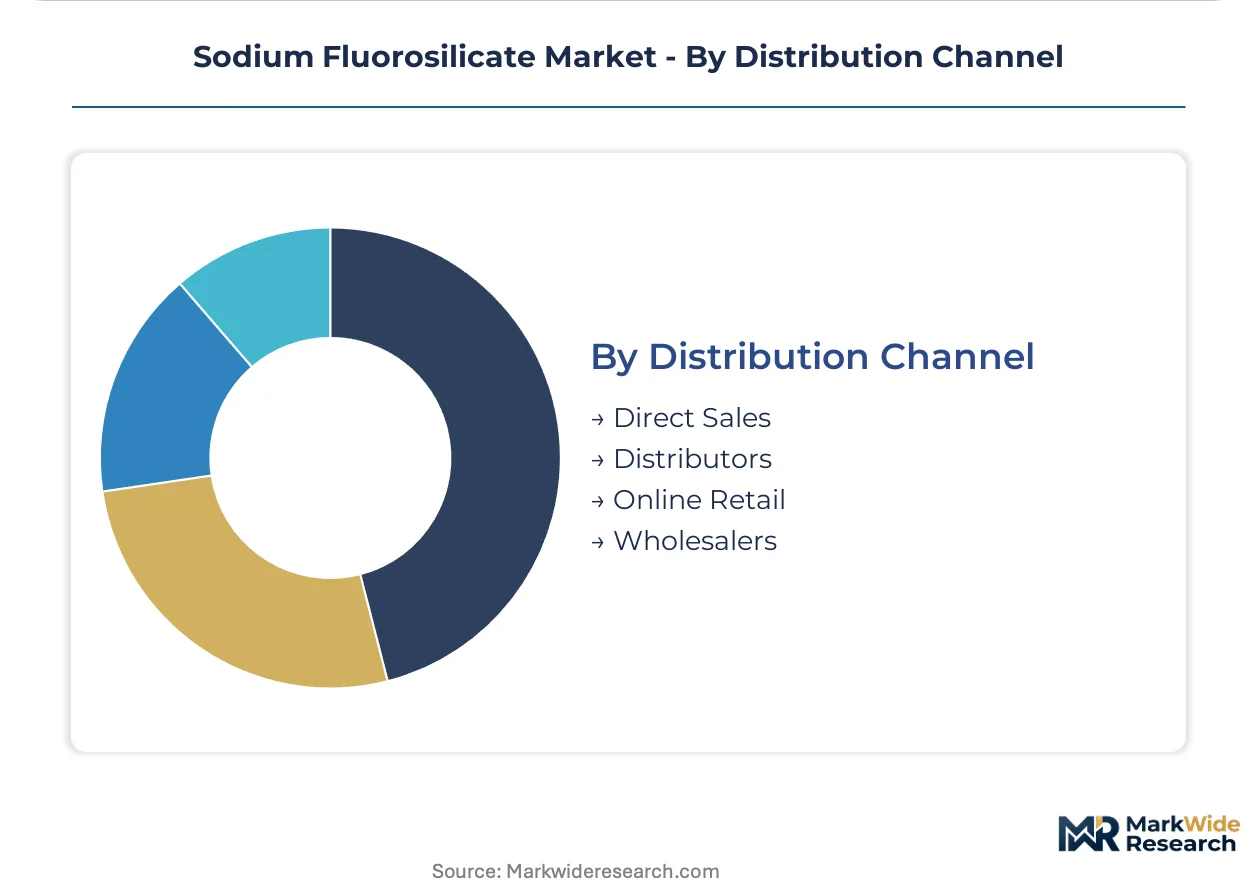
Distribution Channel:
Channel selection reflects buyer scale, compliance documentation requirements, and geographic concentration of demand.
- Direct Sales:Large municipal contracts and textile processor volumes bypass intermediaries for price negotiation and technical service integration. Solvay and Honeywell deploy field teams for system calibration bundling.
- Distributors:Regional chemical distributors hold inventory for mid-scale industrial buyers requiring documented compliance without direct manufacturer relationships.
- Wholesalers:Bulk aggregation serves smaller textile finishers and agricultural applicators with standardized industrial-grade specifications.
- Online Retail:Limited to small-volume laboratory and dental supply purchases with minimal regulatory documentation requirements.
Contract value concentrates in Direct Sales. Transaction frequency peaks in Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Changsha anchors production capacity for Asian textile processors, while São Paulo state water boards institutionalize multi-year fluoridation procurement. Municipal program expansion across Brazil and India is tightening vendor qualification requirements.
China
Hunan province manufacturing clusters supply technical-grade volumes to Vietnamese fabric finishers seeking export certification. SAMR enforcement of tightened GB/T quality benchmarks is forcing crystallization infrastructure upgrades among domestic producers. Changsha-based chemical parks are absorbing capacity investments to meet textile sector documentation requirements.
Brazil
São Paulo state water authorities separate chemical procurement from system maintenance, creating parallel vendor categories for fluoridation programs. ANVISA alignment with WHO guidelines shapes municipal additive specifications. Urban water boards in Minas Gerais and Rio de Janeiro are expanding program coverage with qualified vendor lists.
India
Maharashtra and Gujarat urban authorities are expanding fluoridation procurement cycles with BIS-certified suppliers. CDSCO oversight of water treatment chemical purity creates compliance documentation layers for imported volumes. Mumbai and Ahmedabad manufacturing corridors are absorbing technical-grade supply for regional textile processors.
United States
EPA NSF/ANSI Standard 60 compliance costs disproportionately burden smaller producers seeking municipal contract entry. Municipal water systems in Texas and California are evaluating liquid acid dosing alternatives that bypass dry salt conversion. Great Lakes region utilities maintain established procurement relationships with documented suppliers.
Germany
REACH registration requirements consolidate supplier bases by raising documentation barriers for industrial textile processors. ECHA oversight of fluorosilicate import volumes shapes purity documentation standards. Rhine-Ruhr industrial corridor manufacturers prioritize audit-ready supply chains for export certification.
Sodium Fluorosilicate Market Vendor Landscape
Capital-heavy producers compete with asset-light distributors across distinct procurement channels. The vendor base stratifies between integrated chemical manufacturers with crystallization capabilities and regional distributors holding inventory for mid-scale industrial buyers. Three archetypes dominate: European-registered producers capturing REACH-compliant textile contracts, Chinese manufacturers supplying technical-grade volumes to Asian fabric finishers, and integrated water treatment platforms bundling chemicals with monitoring hardware. Capacity expansion and strategic partnerships represent the dominant competitive vectors as producers seek backward integration into fluorosilicic acid supply.
Among European-registered producers, Solvay occupies a position exemplifying long-term municipal contract sustainability through production network leverage. Hunan Guangcheng Chemical Industry Development Co. Ltd represents the technical-grade specialist archetype serving Asian textile clusters with consistent volume supply. Honeywell sits within the integrated platform tier, competing through bundled offerings that combine sodium fluorosilicate with dosing hardware and calibration services.
| Leading Market Players |
|---|
| ORICA Chemicals |
| Crystran |
| Solvay |
| Spectrum Chemical MFG Corp. |
| Hunan Guangcheng Chemical Industry Development Co. Ltd |
| Prayon |
| Merck KGaA |
| American Elements |
| Honeywell |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical-industrial grade bifurcation manifests in dual pricing architectures and divergent supply chain configurations across sodium fluorosilicate procurement channels. Municipal buyers in Brazil and India absorb food-grade volumes through multi-year contract structures anchored to BIS and ANVISA compliance documentation, while East Asian textile processors source technical-grade supply through spot-adjacent arrangements tied to GB/T certification tiers.
Pricing Analysis
Margin tightening in industrial-grade supply reflects fluorosilicic acid feedstock cost volatility and SAMR-mandated purity upgrade investments. Contract-based long-term offtake dominates municipal procurement with pricing indexed to certification maintenance and dosing system calibration bundling. Price differentiation separates pharmaceutical-grade batches with heavy-metal documentation from commodity technical-grade volumes. Brazilian state water boards exhibit lowest price sensitivity due to locked-in fluoridation mandates, whereas Vietnamese fabric finishers demonstrate acute cost responsiveness to purity-grade trade-offs.
Supply Chain Analysis
Single-source vulnerability sits with Hunan province fluorosilicic acid production clusters feeding downstream neutralization operations. Manufacturing concentrates in China, Brazil, and India with raw material dependencies spanning fluorosilicic acid, sodium chloride, and sodium carbonate. Supply chain risk centers on geographic concentration of feedstock production creating tariff-exposed chokepoints for non-Chinese manufacturers. Distribution runs through direct sales for municipal contracts and regional chemical distributors for mid-scale textile processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
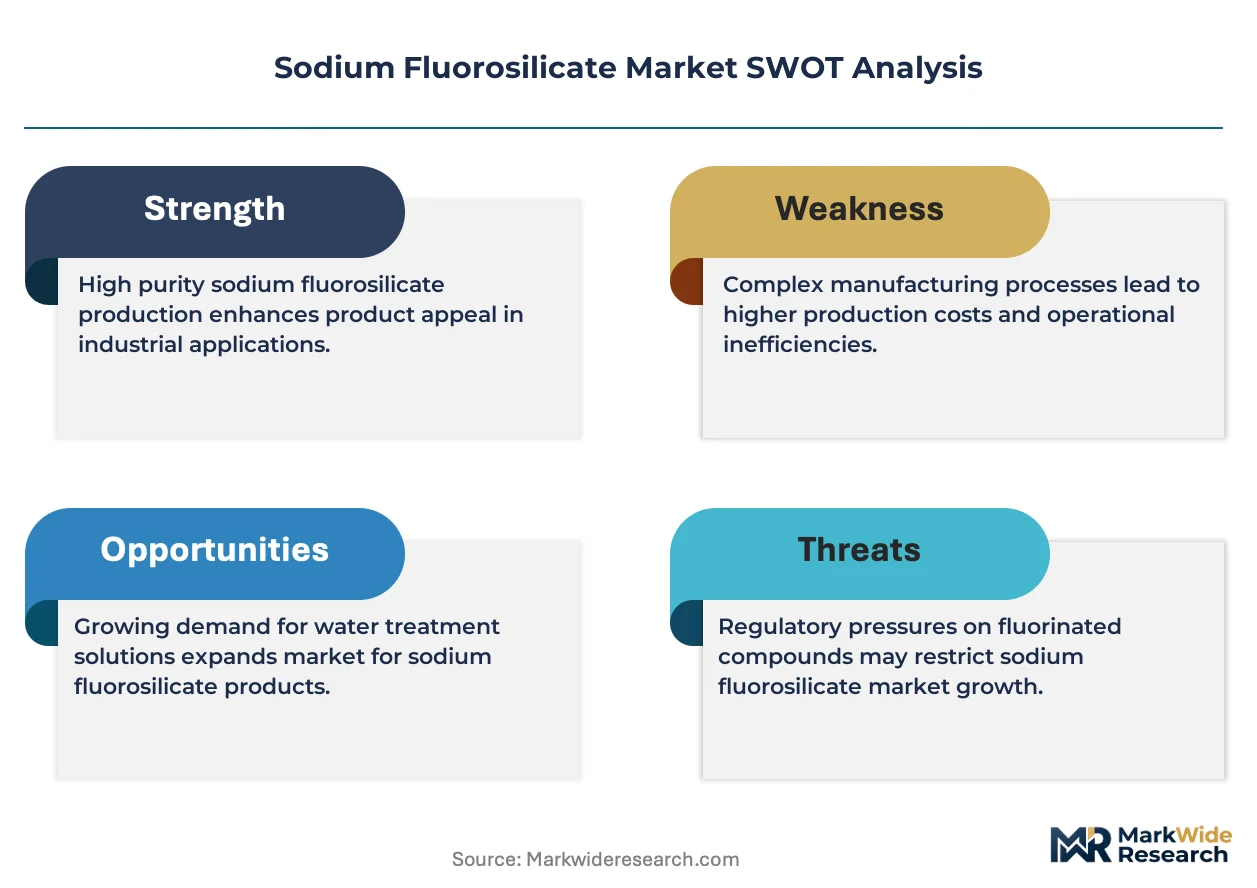
Backward integration into fluorosilicic acid supply represents the decisive competitive lever as producers race to secure captive feedstock and escape geographic concentration risk.
For Market Incumbents: To counter liquid acid direct-feed substitution in US municipal systems, Solvay and Honeywell should deepen dosing platform bundling with hardware-software integration and pursue capacity addition in Indian BIS-certified corridors. Certification investment in dual water treatment and industrial-grade compliance documentation captures cross-segment contracts previously split among specialized suppliers. For New Entrants and Emerging Players: Capture Maharashtra and Gujarat state water board procurement cycles by securing BIS certification ahead of program expansion waves. The most penetrable segment sits with Indian subcontinent municipalities where documentation barriers have filtered informal suppliers. A technical service-first go-to-market angle displaces commodity-only relationships in São Paulo-style unbundled procurement environments. For Investors and Strategic Acquirers: Re-rating potential sits with crystallization-capable mid-caps given SAMR enforcement of tightened GB/T benchmarks forcing domestic upgrade cycles. Long-term viability favors producers with demonstrated heavy-metal removal infrastructure and dual regulatory qualification across water treatment and pharmaceutical channels. Watch fluorosilicic acid supply contract renegotiation patterns as inflection indicators for margin compression or relief.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive fluorosilicic acid supply secures margin control against Hunan province concentration risk. |
| Certification Investment | Dual GB/T and BIS compliance documentation unlocks cross-segment municipal and textile contracts. |
| Dosing Platform Bundling | Honeywell-style hardware-software-chemical combinations displace commodity-only supply relationships. |
| Capacity Expansion | Changsha chemical park investments meet Vietnamese fabric finisher export certification demand. |
| Long-term Supply Agreement | Brazilian state water board multi-year contracts institutionalize bulk chemical procurement cycles. |
Methodological Framework
Trade databases, regulatory filings, and customs records formed the secondary backbone for this analysis, cross-referenced with primary interviews involving fluoridation program managers at Brazilian state water boards, procurement leads at Indian urban authorities, technical directors at Chinese textile chemical distributors, and plant managers at Hunan province manufacturing clusters. Bottom-up volume estimates from application-specific consumption rates triangulated against top-down production capacity assessments across the analysis window.
Historical trendline analysis tracked grade-specific pricing dynamics and procurement cycle patterns across water treatment and industrial channels. The analytical framework segmented by purity tier, end-use application, and regional regulatory cluster throughout the forecast period. CAGRs derived from regression-adjusted growth rates incorporating municipal program expansion timelines, textile sector capacity buildouts, and compliance cost pass-through assumptions. Industry-specific inputs included fluorosilicic acid supply contract renegotiation frequencies and BIS certification pipeline volumes.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to SAMR enforcement intensity and liquid acid substitution adoption curves across US municipal systems. Deviation in fluorosilicic acid feedstock availability or REACH registration timeline extensions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
3-Fluoro-5-Nitrotoluene Market
Chemicals
Calcium Hydride Market
Chemicals
Asia-Pacific Non-Phthalate Plasticizers Market
Chemicals
Europe Flame Retardant Chemicals Market
Chemicals
North America Methanol Market
Chemicals
Leather Tanning Chemicals Market
Chemicals
Hydrogenated Dimer Acid Market
Chemicals
Acrylic Acids and Esters Market
Chemicals
Guaiacol Market
Chemicals
Amine Oxide Market
Chemicals
India Methanol Market
Chemicals
P-Ethylphenol Market
Chemicals
1,3-Dibromoadamantane Market
Chemicals
Global Zinc Pyrithione Market
Chemicals
4-Dichlorodiphenyl Sulfone (DCDPS) Market
Chemicals
Calcium Disodium Ethylene Diamine Tetra-Acetate Market