
 Household Insecticides Market | 2026-2036
Household Insecticides Market Size, Share, and Industry Trends Forecast 2026-2036
Household Insecticides Market Intelligence
Asian contract manufacturers is consolidating production of pyrethroid-based formulations for private-label brands serving European and North American retailers. SC Johnson & Son leverages its captive aerosol filling infrastructure across Wisconsin and Illinois to sustain margin control in coil and mat segments. Godrej Consumer Products Limited anchors South Asian distribution through dense kirana store networks, while Reckitt Benckiser Group PLC competes on clinical efficacy claims in premium spray positioning.
Household insecticides comprise synthetic and naturally derived chemical formulations engineered to disrupt arthropod nervous systems or reproductive cycles, typically delivered through aerosol propellants, residual sprays, bait matrices, or vaporizing substrates. Pyrethroid concentrations generally range from 0.5% to 2.0% by weight in consumer-grade aerosols, with emulsifiable concentrates requiring dilution for perimeter application in outdoor use cases. Aerosols and sprays still occupy the largest revenue share due to immediate knockdown perception, though natural extracts represent the fastest-expanding active ingredient category as EU REACH restrictions and EPA re-registration timelines constrain organophosphate availability. Indoor use formulations command premium pricing over garden applications because of stricter inhalation exposure limits and child-safety packaging mandates.
EPA re-registration reviews for pyrethroids and the EU Biocidal Products Regulation jointly determine which active ingredients retain market access across OECD markets, directly constraining R&D pipelines toward bio-based alternatives. India's Central Insecticides Board and China's Ministry of Ecology and Environment enforce divergent residue tolerance thresholds, fragmenting formulation portfolios by geography. BIS certification requirements and state-level vector control tenders in Maharashtra and Tamil Nadu shape competitive entry for multinational suppliers. Stakeholders must monitor regulatory divergence between OECD hazard-based assessments and emerging economy risk-based frameworks when allocating formulation development budgets.
Market Dynamics
EPA's pyrethroid re-registration timeline and REACH's biocidal restrictions are forcing manufacturers to rebuild formulation portfolios around bio-based actives, compressing R&D cycles while fragmenting geographic product lines.
Growth Catalysts
- Vector-borne disease awareness:Urban apartment dwellers in Mumbai and São Paulo now treat preventive pest management as essential household expenditure, expanding addressable demand beyond reactive purchase patterns.
- EU Biocidal Products Regulation:The BPR's streamlined authorization pathway for low-risk substances accelerates market entry for citronella and geraniol formulations, rewarding early movers in natural active ingredient development.
- Coil and mat electrification:Plug-in vaporizer devices are capturing share from combustion-based formats in Southeast Asian markets, driven by electricity grid expansion and indoor air quality concerns.
Market Restraints
- Pyrethroid supply concentration:Active ingredient synthesis clusters in Yangtze River Delta chemical parks, exposing formulation houses to single-region disruption risk and input cost volatility.
- Residual efficacy limitations:Natural extracts degrade faster than synthetic pyrethroids on porous surfaces, forcing higher application frequency and eroding perceived value in premium positioning.
- BIS certification timelines:India's mandatory insecticide testing protocols extend product launch windows by 8-14 months, freezing working capital and delaying revenue recognition for new entrants.
Strategic Opportunities
- Subscription-based replenishment:Direct-to-consumer auto-ship models for refill cartridges bypass kirana store margin stacking, capturing full retail value in tier-2 Indian cities.
- Smart home integration:Connected vaporizers with app-controlled scheduling and usage analytics appeal to tech-forward households in Seoul and Tokyo, opening premium pricing headroom.
- PLI scheme alignment:India's production-linked incentive scheme for specialty chemicals subsidizes domestic active ingredient manufacturing, reducing import dependency for local formulation brands.
Industry Challenges
- Toxicology expertise scarcity:Formulation chemists with dual competency in synthetic and botanical actives command 40% salary premiums, constraining R&D team scaling for mid-tier manufacturers.
- Multi-jurisdiction dossier management:Divergent data requirements between EPA's 40 CFR Part 158 and EU BPR Annex II force parallel registration tracks, duplicating toxicology study expenditure.
- Aerosol propellant transition:Compressed air systems replacing hydrocarbon propellants require capital-intensive filling line retooling, straining balance sheets for regional spray producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Household Insecticides Market |
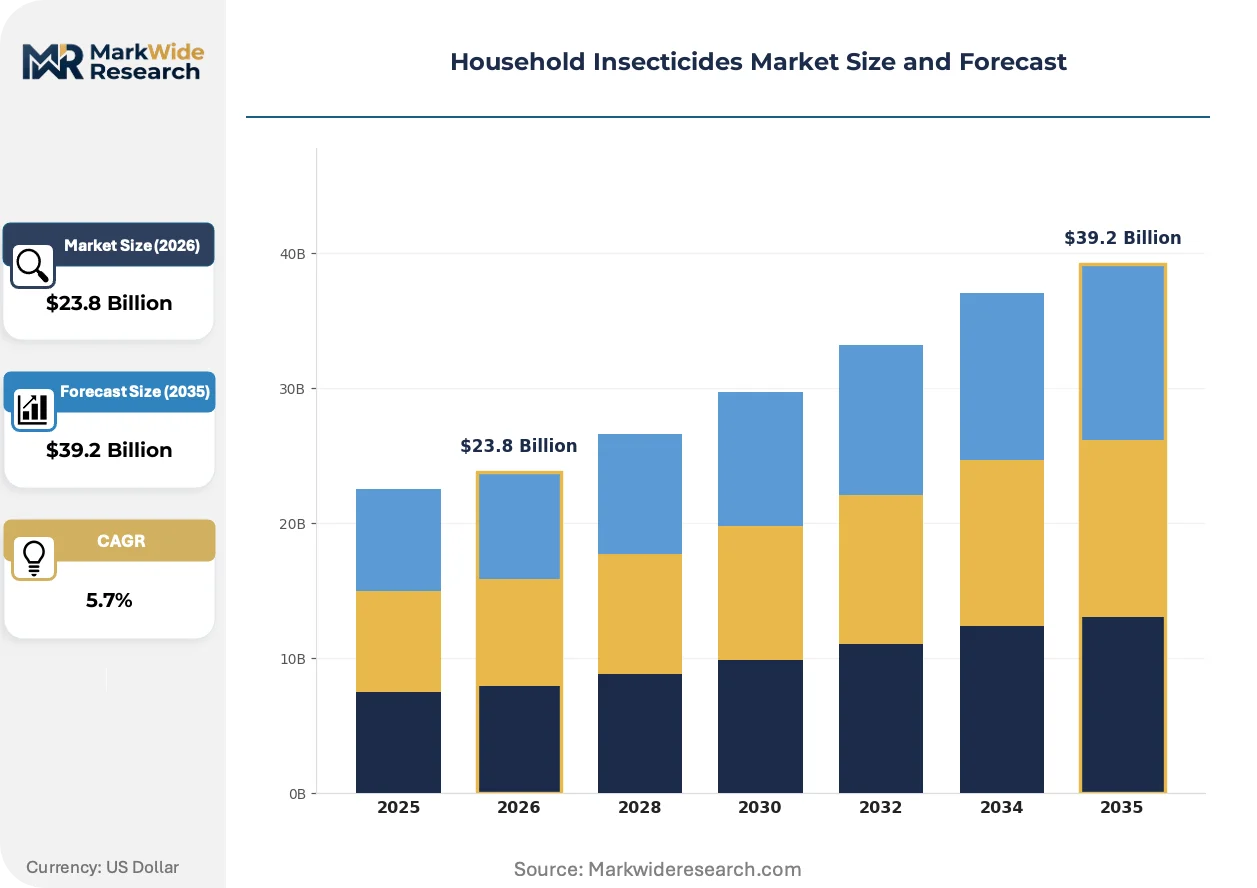
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $39.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aerosols, Sprays, Baits, Powders Active Ingredient: Pyrethroids, Insect Growth Regulators, Organophosphates, Natural Extracts Use Case: Indoor Use, Outdoor Use, Gardens, Pest Control Formulation: Liquid, Granular, Gel, Emulsifiable Concentrates |
| Companies Covered | SC Johnson & Son, Reckitt Benckiser Group PLC, Godrej Consumer Products Limited, Spectrum Brands Holdings, Sumitomo Chemical Co., Ltd., FMC Global Specialty Solutions, Bayer AG, Henkel AG & Co. KGaA, Dabur India Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Household Insecticides Market Strategic Shifts & Innovations
Formulation chemistry and delivery mechanisms are diverging sharply between OECD markets with hazard-based regulation and emerging economies optimizing for cost-accessibility, fragmenting product architecture globally.
Encapsulated microemulsion technology extends residual pyrethroid efficacy on porous surfaces from days to weeks through controlled-release polymer matrices. Apartment management companies in Florida and Texas are specifying encapsulated formulations in multi-unit service contracts. This performance extension is decentralizing competitive advantage from brand marketing toward technical specification compliance.
REACH's 2026 sunset dates for non-authorized biocidal actives are accelerating reformulation programs across European private-label suppliers. Manufacturers are diverting R&D budgets toward botanical extract stability research and natural synergist identification. Aerosol segments face the steepest margin compression as propellant and active ingredient substitutions simultaneously raise unit costs.
Urban Indian households are fragmenting purchase channels between quick-commerce platforms for emergency knockdown sprays and monthly kirana stock-ups for preventive coils. Quick-commerce penetration in Bangalore and Hyderabad now captures 23% of impulse insecticide purchases, forcing traditional distributors to absorb last-mile delivery costs or lose shelf visibility. This channel bifurcation is most pronounced among dual-income households with limited storage space.
Household Insecticides Market Segmentation
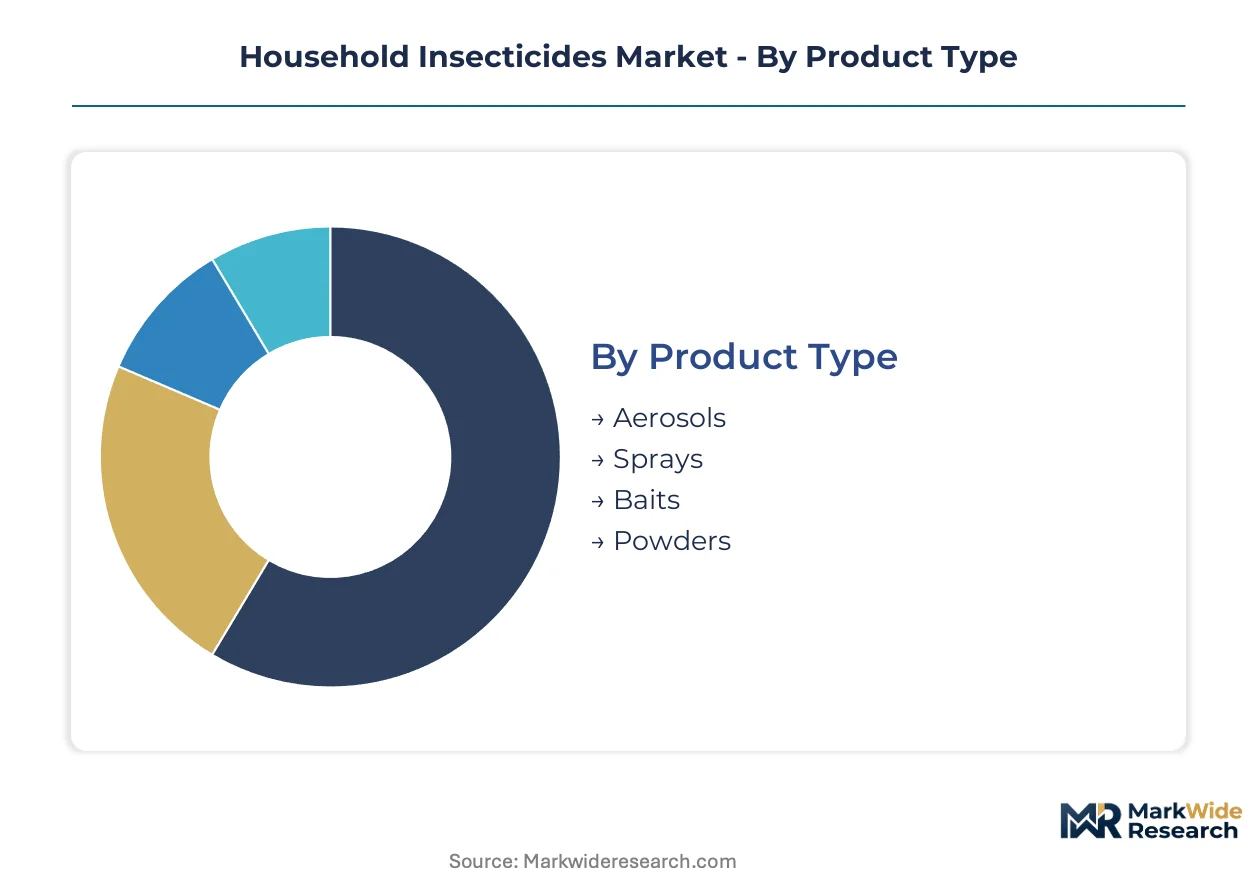
Household insecticide manufacturers must align formulation portfolios with divergent regulatory thresholds across OECD and emerging markets. Product architecture now fragments between premium indoor formulations with stricter exposure limits and cost-optimized outdoor variants. Segmentation strategy determines which R&D investments yield market access versus margin compression.
Product Type:
Aerosols command volume leadership through immediate knockdown perception, while baits capture premium positioning via residual efficacy claims.
- Aerosols:Hydrocarbon or compressed air propellant systems deliver 0.5% to 2.0% pyrethroid concentrations in consumer-grade formats. Demand concentrates in urban Indian and Brazilian households seeking emergency knockdown capability, though EPA re-registration timelines are forcing active ingredient substitutions that raise unit costs.
- Sprays:Trigger-activated liquid formulations enable targeted perimeter application with adjustable droplet size. Apartment management companies in Florida and Texas specify encapsulated microemulsion sprays in multi-unit service contracts, rewarding technical specification compliance over brand equity.
- Baits:Matrix-embedded attractant systems disrupt reproductive cycles through delayed toxicity. Residential kitchens in Seoul and Tokyo drive adoption for cockroach and ant control where spray drift concerns limit aerosol use.
- Powders:Dust formulations target crawl spaces and wall voids with desiccant or neurotoxic action. Rural Indian households with storage constraints favor single-application seasonal treatments.
Today's leader: Aerosols. Tomorrow's challenger: Baits.
Active Ingredient:
Synthetic chemistry dominates current revenue, yet botanical extraction capabilities are becoming the decisive competitive moat.
- Pyrethroids:Synthetic esters of chrysanthemum-derived acids deliver rapid paralysis through sodium channel disruption. Synthesis concentration in Yangtze River Delta chemical parks exposes formulation houses to single-region supply risk and input cost volatility.
- Insect Growth Regulators:Juvenile hormone analogs and chitin synthesis inhibitors interrupt molting cycles for population suppression. Vector control tenders in Maharashtra and Tamil Nadu specify IGR combinations for dengue prevention programs.
- Organophosphates:Acetylcholinesterase inhibitors face steep availability constraints under EU REACH restrictions and EPA re-registration reviews. Legacy agricultural channels maintain limited household access in markets with weaker inhalation exposure standards.
- Natural Extracts:Citronella, geraniol, and pyrethrin formulations gain accelerated authorization under EU Biocidal Products Regulation low-risk pathways. European private-label suppliers are diverting R&D budgets toward botanical extract stability research.
Pyrethroids anchor present volume. Natural extracts are climbing the fastest.
Use Case:
Indoor applications command pricing premiums through child-safety packaging mandates and inhalation exposure limits, while outdoor formats optimize for cost-accessibility.
- Indoor Use:Formulations must satisfy stricter residue tolerance thresholds and ventilation requirements. Dual-income households in Bangalore and Hyderabad fragment purchases between quick-commerce emergency sprays and monthly kirana stock-ups.
- Outdoor Use:Perimeter treatments and lawn applications prioritize residual persistence over acute toxicity. Brazilian middle-class households in São Paulo treat preventive pest management as essential expenditure.
- Gardens:Ornamental and vegetable plot protection requires selectivity against beneficial insects. EU REACH sunset dates for non-authorized biocidal actives are accelerating reformulation programs among garden-focused suppliers.
- Pest Control:Professional service specifications drive demand for emulsifiable concentrates and bulk concentrates. Encapsulated microemulsion technology extends residual efficacy from days to weeks on porous surfaces.
Indoor Use captures margin leadership. Pest Control shows steepest expansion trajectory.
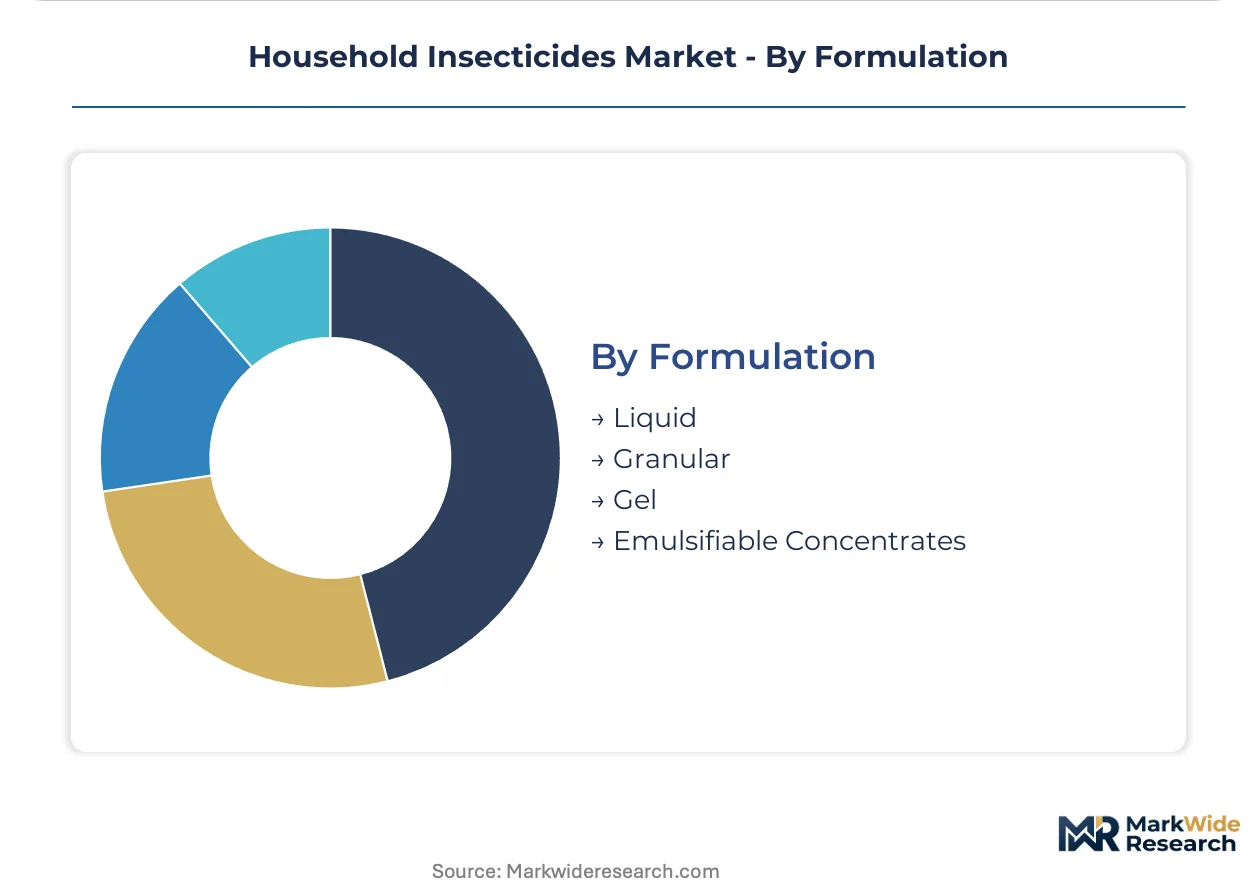
Formulation:
Liquid formats retain manufacturing scale advantages, while gel matrices enable precision placement in sensitive environments.
- Liquid:Ready-to-use and dilutable formats span aerosol, spray, and mop-on application methods. SC Johnson & Son leverages captive aerosol filling infrastructure across Wisconsin and Illinois to sustain margin control.
- Granular:Clay or sand-based carriers release actives through moisture activation. Lawn and perimeter applications in Texas and Florida favor broadcast spreader compatibility.
- Gel:Bait matrix formulations enable discrete placement in electrical outlets and appliance housings. Tokyo and Seoul households with limited storage space prefer single-point application systems.
- Emulsifiable Concentrates:Oil-in-water systems require dilution for professional-grade residual spraying. India's BIS certification timelines extend product launch windows by 8-14 months for concentrate imports.
Liquid formulations dominate current production. Gel systems are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's kirana store networks and Brazil's tropical climate conditions generate comparable per-household expenditure intensity, yet regulatory divergence fragments formulation portfolios between these demand centers.
United States
Multi-unit apartment management companies in Florida and Texas specify encapsulated microemulsion sprays for service contracts, prioritizing technical compliance over brand equity. EPA's pyrethroid re-registration timeline forces active ingredient substitutions that raise unit costs for aerosol manufacturers. SC Johnson & Son leverages captive filling infrastructure across Wisconsin and Illinois to sustain margin control in coil and mat segments.
India
Maharashtra and Tamil Nadu state vector control tenders shape competitive entry for multinational suppliers targeting dengue prevention programs. BIS certification requirements extend product launch windows by 8-14 months, freezing working capital for new entrants. Quick-commerce platforms in Bangalore and Hyderabad now capture 23% of impulse insecticide purchases, forcing traditional distributors to absorb last-mile delivery costs.
Brazil
São Paulo's middle-class households treat preventive pest management as essential expenditure, expanding addressable demand beyond reactive purchase patterns. ANVISA enforces residue tolerance thresholds that diverge from OECD hazard-based assessments, requiring separate formulation tracks. Yangtze River Delta chemical parks supply concentrated pyrethroid inputs, exposing Brazilian formulation houses to single-region disruption risk.
Germany
EU Biocidal Products Regulation sunset dates for 2026 accelerate reformulation programs among private-label suppliers serving European retailers. ECHA's streamlined authorization pathway for low-risk substances rewards early movers in citronella and geraniol development. Asian contract manufacturers consolidate production of pyrethroid-based formulations for German retail channels.
China
MEE enforcement of divergent residue tolerance thresholds fragments export-oriented formulation portfolios by destination geography. Yangtze River Delta chemical parks concentrate pyrethroid synthesis, exposing global supply chains to single-region input cost volatility. Domestic demand concentrates in urban apartment clusters where vector-borne disease awareness intensifies preventive purchase patterns.
Household Insecticides Market Key Industry Players
North American producers anchor one tier through captive aerosol infrastructure; Asian specialists hold contract manufacturing dominance for private-label supply. The vendor base splits between multinational brand houses with integrated filling assets and regional formulation specialists serving price-sensitive emerging markets. Three archetypes define positioning: technology-led specification suppliers, distribution-dense local champions, and scale-driven contract manufacturers. Competitive moves concentrate on geographic licensing partnerships and backward integration into active ingredient synthesis.
Among diversified consumer goods conglomerates, SC Johnson & Son, Reckitt Benckiser Group PLC, and Godrej Consumer Products Limited occupy positions that exemplify contrasting geographic anchoring strategies. SC Johnson & Son represents North American infrastructure-led positioning through Midwest manufacturing concentration. Reckitt Benckiser Group PLC exemplifies European premium-tier clinical efficacy positioning. Godrej Consumer Products Limited anchors South Asian distribution density through kirana network penetration. These three entities collectively illustrate how regional regulatory divergence rewards divergent capability investments rather than global standardization.
| Leading Market Players |
|---|
| SC Johnson & Son |
| Reckitt Benckiser Group PLC |
| Godrej Consumer Products Limited |
| Spectrum Brands Holdings |
| Sumitomo Chemical Co., Ltd. |
| FMC Global Specialty Solutions |
| Bayer AG |
| Henkel AG & Co. KGaA |
| Dabur India Limited |
| Others |
Cost & Logistics Intelligence
Pyrethroid active ingredient spot pricing in Yangtze River Delta chemical parks cascades through formulation houses into three distinct pricing tiers across retail channels, with premium indoor formulations absorbing regulatory compliance costs while economy outdoor variants compete on raw material efficiency.
Pricing Analysis
Kirana store margin stacking in Indian distribution absorbs 18-22 percentage points before consumer-facing pricing, compressing manufacturer returns unless offset by direct-to-consumer subscription models. Three-tier pricing structure across premium, standard, and economy levels separates clinical efficacy-positioned sprays from basic coil formats, with EPA re-registration timelines forcing active ingredient substitutions that raise unit costs in aerosol segments. Cost compression in natural extract formulations is intensifying because botanical stability research demands R&D premiums. Urban apartment dwellers in São Paulo show least price sensitivity for preventive pest management, while rural Indian households with seasonal storage constraints exhibit highest elasticity.
Supply Chain Analysis
Dual-sourcing qualification requirements from European retailers now mandate at least two approved pyrethroid suppliers, fragmenting procurement strategies away from Yangtze River Delta concentration. Active ingredient synthesis clusters in China, India, and Germany feed global formulation networks, with emulsifiable concentrates and aerosol propellants drawing from petrochemical and botanical extraction streams. Single-source vulnerability persists in encapsulated microemulsion polymer matrices, where specialized suppliers hold process patents. Distribution runs through kirana networks in South Asia, big-box retail in North America, and quick-commerce platforms in East Asian megacities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Household insecticides function as a stable compounder anchored by vector-borne disease awareness converting reactive purchases into essential preventive expenditure across tropical and subtropical geographies.
For Market Incumbents: Anticipate EPA pyrethroid re-registration outcomes by diversifying active ingredient portfolios toward botanical extracts with EU BPR low-risk authorization pathways. Backward integration into captive aerosol filling infrastructure sustains margin control against contract manufacturing margin compression. Prioritize BIS certification pre-submission in India to compress 8-14 month launch windows. For New Entrants and Emerging Players: Launch via quick-commerce direct distribution in Bangalore and Hyderabad to bypass kirana margin stacking and capture impulse purchase velocity. Target subscription-based replenishment models for vaporizer refill cartridges in tier-2 Indian cities where storage constraints favor auto-ship convenience. White-space exists in smart home-integrated connected vaporizers for Seoul and Tokyo tech-forward households. For Investors and Strategic Acquirers: Asymmetric upside sits with Asian contract manufacturers consolidating pyrethroid-based formulation production for private-label European and North American retail channels. Five-to-ten year viability hinges on botanical extraction capability buildout ahead of REACH sunset enforcement. Watch EU Biocidal Products Regulation authorization timelines as inflection indicator for natural active ingredient market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Botanical Active Ingredient Development | EU BPR low-risk pathway acceleration rewards early movers in citronella and geraniol stability research. |
| Encapsulated Microemulsion Capacity Expansion | Florida and Texas apartment management specifications reward technical compliance over brand marketing. |
| Quick-Commerce Channel Partnership | Bangalore and Hyderabad platforms capture 23% of impulse purchases, forcing distributor adaptation. |
| Backward Integration into Aerosol Filling | Midwest captive infrastructure sustains margin control against hydrocarbon propellant transition costs. |
| Smart Home Integration Investment | App-controlled scheduling and usage analytics open premium pricing headroom in Seoul and Tokyo. |
Research Approach
Bottom-up household expenditure modeling reconciled against top-down active ingredient production tracking forms the analytical core of this study. Primary interviews with formulation chemists, kirana store proprietors, vector control procurement officers, and quick-commerce category managers combined with secondary validation from EPA re-registration dockets, EU BPR authorization databases, BIS certification records, and Indian state tender disclosures. Trade flow analysis across Yangtze River Delta chemical park outputs and customs data triangulates supply-side concentration against demand fragmentation.
Historical trendline analysis of pyrethroid pricing volatility, regulatory authorization success rates, and channel penetration trajectories informed projection frameworks across product type, active ingredient chemistry, use case, and formulation format dimensions. CAGRs derived from segment-level elasticity modeling against macroeconomic indicators and urbanization rates. Forecast inputs incorporated vector-borne disease incidence tracking and electrification penetration curves for vaporizer device adoption.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EPA pyrethroid re-registration delays or Yangtze River Delta supply disruptions. Deviation in EU REACH sunset enforcement timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Tetrapotassium Pyrophosphate Market
Chemicals
Solder Flux Market
Chemicals
Global Aluminum Chloro Hydrate (ACH) Market
Chemicals
Acid Anhydrides Market
Chemicals
Lauryl Myristyl Alcohol Market
Chemicals
Egypt Construction Chemicals Market
Chemicals
Oxybenzone Market
Chemicals
Global Inorganic Fluorides Market
Chemicals
Benzenoid Market
Chemicals
Hexamine Market
Chemicals
Africa Mining Chemicals Market
Chemicals
Neopentyl Polyhydric Alcohol Market
Chemicals
Nonaisoprenol Market
Chemicals
Quaternium-15 Market
Chemicals
Sulfuric Acid Market
Chemicals
Non-Halogenated Flame Retardant Chemicals Market