
 Cement Surface Treatment Chemicals Market | 2026-2036
Cement Surface Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Cement Surface Treatment Chemicals Market Insights
Silicate-based densifiers is recalibrating product economics in cement surface treatment as contractors substitute traditional solvent-borne sealers with lower-VOC alternatives that reduce reapplication cycles. Sika AG leverages its European manufacturing footprint to sustain supply continuity for infrastructure-grade curing compounds across German and Swiss project pipelines. BASF SE anchors its position through backward integration into acrylic polymer feedstocks, securing formulation consistency for waterproofing agents. Mapei S.p.A. competes on application-specific specialization, dominating industrial flooring systems with epoxy-modified surface hardeners in Italian and Middle Eastern markets.
Cement surface treatment chemicals comprise formulated admixtures and topical applications—typically acrylic, silicate, or epoxy resin systems with solids content ranging from 15% to 40%—designed to modify porosity, abrasion resistance, and chemical durability of cured concrete surfaces. These products function primarily to extend service life in high-traffic or chemically exposed environments where unprotected concrete undergoes carbonation, chloride ingress, or freeze-thaw degradation. Waterproofing agents command the largest share of product-type value pools due to their specification in below-grade and marine infrastructure, while adhesion promoters represent the fastest-expanding category as bonded overlays gain preference over full-depth replacement in bridge deck rehabilitation. Among applications, tunnel linings and parking structures concentrate margin capture because these projects require multi-layer systems combining curing compounds with dust proofers and surface hardeners.
EPA regulations under the National Emission Standards for Hazardous Air Pollutants constrain solvent-borne formulation in US commercial construction, while REACH registration requirements in Europe mandate full substance toxicity dossiers for silicate and epoxy constituents imported above one-tonne thresholds. India's BIS certification for construction chemicals under IS 9103 creates a compliance gateway that filters uncertified imports from Southeast Asian suppliers. Stakeholders must monitor divergence between regional VOC limits and performance standards, as formulation platforms that satisfy EPA and REACH constraints may fail BIS adhesion tests or MEE emission protocols, fragmenting product portfolios by geography.
Market Dynamics
Formulation chemistry is pivoting toward water-borne silicate systems as VOC limits tighten across multiple jurisdictions, compressing solvent-borne product lifecycles and forcing raw material substitution in curing compounds and densifiers.
Growth Catalysts
- India's PLI scheme for construction chemicals:Production-linked incentives are accelerating domestic manufacturing capacity for surface hardeners and waterproofing agents, pulling procurement away from Southeast Asian imports.
- Metro rail expansions:Tunnel lining specifications in Mumbai, Delhi, and Bangalore are generating sustained demand for multi-layer treatment systems combining curing compounds with dust proofers.
- Epoxy-modified surface hardeners:Industrial flooring contractors are specifying these systems for abrasion resistance in high-traffic logistics facilities, displacing conventional acrylic sealers.
Market Restraints
- Petrochemical feedstock volatility:Acrylic polymer prices fluctuate with propylene oxide markets, squeezing margin predictability for waterproofing agent manufacturers.
- German-Swiss supply concentration:Infrastructure-grade curing compound production clusters in Central Europe, exposing project timelines to single-source risk during transport disruptions.
- REACH registration thresholds:One-tonne substance dossier requirements for silicate and epoxy constituents create compliance friction for imported formulations entering European markets.
Strategic Opportunities
- Below-grade waterproofing in Vietnam:Flood-resilient infrastructure mandates in Ho Chi Minh City and Hanoi are opening specification windows for crystalline waterproofing agents in basement and tunnel applications.
- Carbon-capture concrete compatibility:Emerging CO2-cured concrete technologies require reformulated curing compounds that do not interfere with carbonation kinetics, creating first-mover advantage for adapted product lines.
- Bonded overlay rehabilitation:Bridge deck maintenance programs are shifting from full-depth replacement to thin polymer-modified overlays, expanding adhesion promoter demand in transportation agencies.
Industry Challenges
- Application technician certification:Multi-layer system installation requires trained crews for epoxy-modified hardeners, and qualified labor pools remain thin in secondary Indian and Southeast Asian markets.
- BIS IS 9103 testing timelines:India's construction chemical certification process creates six-to-nine-month market entry delays, filtering out smaller international suppliers lacking local testing partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cement Surface Treatment Chemicals Market |
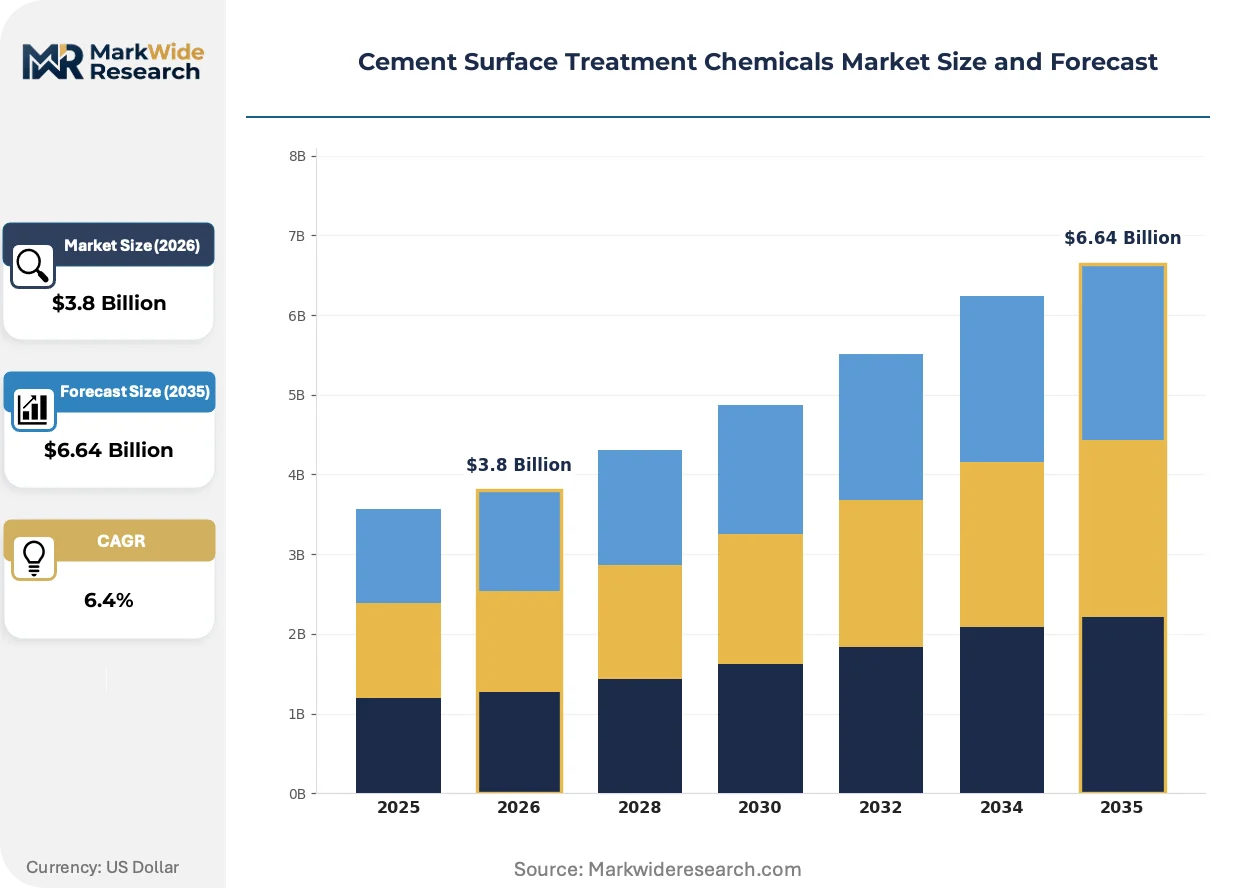
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Waterproofing Agents, Surface Hardeners, Curing Compounds, Adhesion Promoters, Dust Proofers Application: Industrial Flooring, Bridge Decks, Tunnel Linings, Parking Structures, Airport Runways End User: Construction Contractors, Infrastructure Developers, Commercial Builders, Government Agencies, Consulting Engineers Distribution Channel: Direct Sales, Distributors, Online Platforms, Retailers, Specialty Stores |
| Companies Covered | BASF SE, Sika AG, 3M, Dow, Fosroc International Ltd, The Euclid Chemical Company, Akzo Nobel N.V., Henkel AG & Co. KGaA, Mapei S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cement Surface Treatment Chemicals Market Trends and Innovations
Product development is converging on performance-validated water-borne platforms that satisfy divergent regional emission standards while maintaining chloride ingress resistance and abrasion thresholds specified by infrastructure engineers.
Lithium silicate densifiers is consolidating specification preference in commercial flooring and warehouse applications, penetrating industrial maintenance budgets at the expense of sodium silicate and solvent-borne acrylic alternatives. Facility managers in German logistics hubs and Indian manufacturing zones are specifying these systems for permanent dustproofing without reapplication cycles. The technology is consolidating supplier R&D budgets around single-component, spray-applied formats that reduce labor cost and application error rates.
REACH Annex XVII restrictions on N-methyl-2-pyrrolidone (NMP) in epoxy formulations are forcing reformulation of high-performance surface hardeners used in European industrial flooring. Manufacturers are substituting with dipropylene glycol dimethyl ether and other aprotic solvents, validating adhesion and cure speed through accelerated weathering protocols. German industrial coating contractors face the steepest compliance curve, as their project specifications historically relied on NMP-based penetration and flow characteristics.
Asset owner engineering departments are unbundling material supply from application service contracts, disintermediating traditional distributor-applicator relationships in favor of direct manufacturer-to-contractor procurement. This pattern concentrates in Indian metro rail and Middle Eastern airport infrastructure projects, where owners specify approved product lists and negotiate separate installation agreements. Specification authority is migrating from applicator networks to owner engineering consultants with performance-based warranty requirements.
Cement Surface Treatment Chemicals Market Segmentation
Cement surface treatment chemicals fragment across formulation chemistry, infrastructure application, and procurement channel, with each dimension carrying distinct regulatory burdens and margin structures. Specification authority varies sharply by segment, from owner-engineer material approvals in waterproofing systems to contractor-driven brand selection in retail curing compounds.
Product Type:
REACH dossier requirements and BIS IS 9103 certification create divergent compliance thresholds across formulation categories, filtering supplier participation by technical registration capability.
- Waterproofing Agents:Crystalline and polymer-modified formulations dominate below-grade specifications, with crystalline systems requiring BIS certification for Indian metro rail procurement. Mumbai and Delhi tunnel projects specify multi-layer waterproofing combining cementitious crystalline admixtures with topical sealers, creating bundled procurement patterns.
- Surface Hardeners:Epoxy-modified and lithium silicate variants displace sodium silicate in high-traffic industrial flooring. German logistics hubs specify lithium silicate densifiers for permanent dustproofing without reapplication cycles, compressing maintenance budgets.
- Curing Compounds:Water-borne resin formulations face EPA NESHAP constraints on solvent content in US commercial construction.
- Adhesion Promoters:Bridge deck rehabilitation programs specify these for bonded polymer-modified overlays.
- Dust Proofers:Penetrating silicate sealers serve warehouse and manufacturing facility maintenance.
Leading the category by volume: Waterproofing Agents. Growing fastest: Adhesion Promoters.
Application:
Project scale and specification complexity stratify the application landscape, with transportation infrastructure commanding multi-layer systems and industrial flooring driving repeat maintenance demand.
- Tunnel Linings:Multi-layer treatment systems combine curing compounds, waterproofing agents, and surface hardeners in single specifications. Bangalore metro expansions generate sustained procurement for cementitious crystalline systems with 50-year design life requirements.
- Industrial Flooring:Abrasion resistance specifications in logistics facilities drive epoxy-modified hardener demand. Indian manufacturing zones specify lithium silicate densifiers for permanent dustproofing, displacing acrylic sealers with shorter reapplication cycles.
- Bridge Decks:Bonded overlay rehabilitation shifts procurement toward adhesion promoters and polymer-modified systems.
- Parking Structures:Chloride ingress protection mandates combine waterproofing with carbonation-resistant treatments.
- Airport Runways:Freeze-thaw durability specifications concentrate curing compound demand in cold climate installations.
Volume concentrates in Tunnel Linings. Steepest expansion trajectory: Bridge Decks rehabilitation.
End User:
Procurement authority migration from applicators to owner-engineers restructures channel relationships, with infrastructure developers and government agencies increasingly specifying approved product lists separately from installation contracts.
- Infrastructure Developers:Metro rail and airport authorities in India and the Middle East unbundle material supply from application services, negotiating direct manufacturer procurement. These stakeholders specify performance-based warranties and maintain approved product registries.
- Construction Contractors:Commercial and industrial project execution relies on distributor relationships for curing compounds and dust proofers, with brand selection driven by application crew familiarity.
- Commercial Builders:Retail and office construction specifies surface hardeners through architect-driven material schedules.
- Government Agencies:Public works departments mandate BIS-certified products for state-funded infrastructure.
- Consulting Engineers:Specification authority migration positions these stakeholders as gatekeepers for waterproofing system approvals.
Procurement volume leader: Infrastructure Developers. Fastest authority shift: Consulting Engineers.
Distribution Channel:
Channel selection correlates with project scale and specification complexity, with direct sales capturing infrastructure-grade formulations and distributors retaining commercial construction access.
- Direct Sales:Infrastructure-grade curing compounds and multi-layer waterproofing systems flow through manufacturer-contractor direct relationships. Indian metro rail and Middle Eastern airport projects concentrate procurement in this channel, bypassing traditional distributor-applicator networks.
- Distributors:Regional stocking relationships serve commercial builders and smaller contractors with curing compounds and surface hardeners.
- Online Platforms:Maintenance-grade dust proofers and small-volume curing compounds migrate to digital procurement.
- Retailers:Consumer-oriented concrete sealers and decorative treatments reach residential contractors.
- Specialty Stores:Application equipment and companion products support professional applicator trade.
Channel volume leader: Direct Sales. Fastest digital migration: Online Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates demand through metro rail expansions and production-linked incentive schemes, while regulatory divergence across major economies fragments formulation portfolios by geography.
India
Mumbai, Delhi, and Bangalore metro rail projects specify multi-layer waterproofing systems for tunnel linings. The PLI scheme for construction chemicals accelerates domestic manufacturing capacity for surface hardeners. Maharashtra and Karnataka industrial zones drive lithium silicate densifier procurement for permanent dustproofing in manufacturing facilities.
United States
Bridge deck rehabilitation programs specify bonded polymer-modified overlays requiring adhesion promoters. EPA National Emission Standards for Hazardous Air Pollutants constrain solvent-borne curing compound formulations. Texas and California infrastructure agencies unbundle material supply from installation contracts, concentrating procurement authority with owner-engineers.
Germany
Logistics hubs specify lithium silicate densifiers for abrasion-resistant industrial flooring without reapplication cycles. REACH Annex XVII restrictions on N-methyl-2-pyrrolidone force epoxy hardener reformulation. The Rhine-Ruhr and Stuttgart manufacturing clusters anchor supply continuity for infrastructure-grade curing compounds.
China
Flood-resilient infrastructure mandates in coastal cities drive crystalline waterproofing agent specifications. Ministry of Ecology and Environment directives tighten VOC limits, redirecting chemistry toward water-based systems. Yangtze River Delta construction chemical manufacturers scale silicate densifier production for domestic and Southeast Asian export markets.
Vietnam
Ho Chi Minh City and Hanoi basement waterproofing specifications open demand for crystalline admixtures in below-grade applications. National technical standards for construction chemicals create compliance gateways filtering uncertified imports. Southern Vietnam industrial zones concentrate procurement for dust proofers in warehouse and logistics facility maintenance.
Cement Surface Treatment Chemicals Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers localize production to satisfy India's PLI incentives and circumvent REACH registration friction for European supply. The vendor base stratifies across three tiers: diversified chemical conglomerates with backward-integrated polymer feedstocks, specialized construction chemical firms with application-specific expertise, and regional formulators serving price-sensitive commercial segments. Competitive moves center on geographic expansion through domestic manufacturing partnerships and portfolio diversification into carbon-capture-compatible curing compounds.
Within the diversified chemical tier, BASF SE and Dow exemplify scale-driven positioning through captive acrylic polymer production. Sika AG occupies a specialist position anchored by European manufacturing continuity for infrastructure-grade formulations. Mapei S.p.A. represents application-focused competition, concentrating on epoxy-modified systems for industrial flooring specifications. These three archetypes illustrate how competitive advantage derives from feedstock control, geographic proximity to project pipelines, or technical specialization in multi-layer system integration.
| Leading Market Players |
|---|
| BASF SE |
| Sika AG |
| 3M |
| Dow |
| Fosroc International Ltd |
| The Euclid Chemical Company |
| Akzo Nobel N.V. |
| Henkel AG & Co. KGaA |
| Mapei S.p.A. |
| Others |
Pricing and Supply Chain Analysis
Propylene oxide feedstock costs cascade through acrylic polymer supply chains into waterproofing agent pricing tiers, with manufacturers passing volatility to infrastructure developers through project-based contracts while absorbing margin compression in spot-market curing compound sales to commercial builders.
Pricing Analysis
Volume concentrates in project-based long-term offtake agreements for tunnel lining specifications, while margins accrue to premium lithium silicate densifiers sold through direct manufacturer channels. Price differentiation hinges on BIS IS 9103 certification grade and volume scale, with certified formulations commanding substantial premiums over uncertified imports. Cost compression in economy-grade sodium silicate hardeners is intensifying because Indian PLI-driven domestic capacity expansion floods secondary markets. Small commercial contractors exhibit highest price sensitivity, whereas metro rail authorities prioritize performance warranties over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from Indian metro rail authorities and Middle Eastern airport developers mandate multi-supplier qualification for crystalline waterproofing agents, forcing distributors to maintain redundant inventory positions. Manufacturing concentrates in Germany, China, and India, with silicate densifier production anchored in Yangtze River Delta facilities serving Southeast Asian export markets. Supply chains draw from propylene oxide, lithium carbonate, and epoxy resin feedstocks. Single-source vulnerability concentrates in German-Swiss curing compound production clusters. Distribution runs through direct sales for infrastructure-grade formulations and regional distributors for commercial construction segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where REACH registration thresholds and BIS certification timelines filter out undercapitalized formulators, concentrating share among vertically integrated polymer producers and specialized construction chemical firms with testing partnerships.
For Market Incumbents: Anchor supply continuity through captive acrylic polymer production or long-term propylene oxide offtake agreements to defend against feedstock volatility eroding waterproofing agent margins. Accelerate BIS IS 9103 certification partnerships in Maharashtra and Karnataka to preempt PLI-scheme competitors from capturing metro rail specifications. For New Entrants and Emerging Players: E-commerce platforms for maintenance-grade dust proofers and small-volume curing compounds offer the lowest barrier to specification authority, bypassing entrenched distributor-applicator relationships in Indian industrial zones. Target crystalline waterproofing agents for Vietnam's flood-resilient basement specifications, where national technical standards create compliance gateways favoring agile entrants with local testing capabilities over established exporters facing registration delays. For Investors and Strategic Acquirers: First-mover product launches for carbon-capture-compatible curing compounds are the leading indicator that formulation adaptability will separate viable targets from stranded asset risks. Mid-cap specialists with backward-integrated silicate feedstocks and existing BIS certification infrastructure represent optimal acquisition profiles. Watch for divergence between regional VOC limits and performance standards forcing portfolio fragmentation by geography.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Polymers | Captive propylene oxide supply insulates waterproofing agent margins from petrochemical volatility. |
| BIS Certification Partnership | IS 9103 approval unlocks Indian metro rail procurement and filters Southeast Asian import competition. |
| Carbon-Capture-Compatible Formulation | CO2-cured concrete curing compounds capture first-mover advantage in emerging specification standards. |
| Direct Sales Channel Expansion | Manufacturer-contractor relationships bypass distributor networks in infrastructure developer procurement. |
| Water-Borne Silicate R&D Scale-Up | EPA NESHAP and MEE compliance redirects chemistry away from solvent-borne product lifecycles. |
Research Methodology
Multi-period observation of propylene oxide pricing spreads, BIS certification issuance rates, and metro rail project award volumes anchored the trend analysis, supplemented by interviews with construction chemical plant managers, procurement leads at Indian infrastructure developers, distribution channel partners, and technical R&D directors at silicate densifier manufacturers. Secondary validation drew from customs and trade data, ACC and Cefic construction chemical reports, SEC 10-K filings of diversified chemical conglomerates, and Indian government PLI scheme disclosures. Bottom-up project pipeline enumeration triangulated against top-down formulation chemistry demand modeling.
Input-output matrices mapped acrylic polymer feedstock costs through waterproofing agent pricing tiers, silicate densifier application rates per square meter of industrial flooring, and curing compound volumes per kilometer of tunnel lining across product type, application, end user, and distribution channel segmentation dimensions. CAGRs were derived from regression analysis of historical procurement patterns projected across the analysis window, incorporating PLI scheme capacity addition schedules and REACH registration timelines as industry-specific forecast inputs.
Inputs from Indian metro rail authorities, German logistics hub facility managers, and Vietnamese construction chemical distributors were available through the study window; gaps in real-time propylene oxide spot pricing and BIS laboratory testing queue lengths introduce uncertainty bands around near-term margin forecasts. Deviation in MEE VOC limit enforcement stringency or EPA NESHAP rulemaking would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Low-Foaming Detergent Market
Cleaning Chemicals
Surface Cleaning Products Market
Cleaning Chemicals
Cleaning Chemicals Market
Cleaning Chemicals
High-Performance Descaling and Deliming Chemicals for HoReCa Equipment Market
Cleaning Chemicals
US Specialty Cleaners Market
Cleaning Chemicals
Electrostatic Liquid Cleaner Market
Cleaning Chemicals
Fabric Softener Market
Cleaning Chemicals
Fragrance-Free Cleaning Chemicals for Sensitive Environments Market
Cleaning Chemicals
Document Cleaning Powder Market
Cleaning Chemicals
Dust Control Systems and Suppression Chemicals Market
Cleaning Chemicals
Industrial and Institutional Hand Hygiene Chemicals Market
Cleaning Chemicals
Instrument Detergents for Manual Cleaning Market
Cleaning Chemicals
Bio-Enzymatic Odor Control Chemicals for Restrooms and Waste Areas Market
Cleaning Chemicals
Europe Mastic Remover Market
Cleaning Chemicals
Chlorinating Agents Market
Cleaning Chemicals
Cleaning Products Market