
 Acrylic Dental Material Market | 2026-2036
Acrylic Dental Material Market Size, Share, and Industry Trends Forecast 2026-2036
Acrylic Dental Material Market Insights
Buyer concentration among dental laboratory chains is hardening as regional networks consolidate procurement of prefabricated acrylic resins and denture base materials. Dentsply Sirona leverages its vertically integrated supply chain to dominate North American distribution of heat-cure and self-cure acrylic systems. Ivoclar Vivadent AG anchors European demand through its specialized cadre of shade-matched denture acrylics and thermoplastic sheets. Kulzer GmbH competes on R&D intensity with advanced PMMA formulations optimized for digital denture workflows.
Acrylic dental materials encompass polymethyl methacrylate-based resins, copolymer sheets, and pre-polymerized beads formulated for intraoral prosthetic applications, typically polymerized through heat-activated, chemical-cure, or light-activated mechanisms at molecular weights exceeding 500,000 g/mol to ensure flexural strength above 65 MPa. These materials serve primarily as denture bases, temporary crowns, orthodontic retainers, and custom impression trays where biocompatibility, polishability, and color stability determine clinical acceptance. Resins command the largest volume share due to universal denture fabrication demand, while temporary crowns represent the fastest-expanding product category as same-day dentistry protocols proliferate across dental clinics. Prosthodontics generates the dominant application revenue stream, though dental implants are displacing traditional removable prosthetics in premium segments and reshaping acrylic toward provisional and aesthetic adjunct roles.
FDA 510(k) clearance pathways and ISO 20795-1 standards govern biocompatibility and mechanical property benchmarks for denture base polymers in the United States, while Europe's MDR and CE marking requirements under EN ISO 20795-1 impose stricter post-market surveillance and clinical evidence obligations on acrylic dental material manufacturers. These regulatory frameworks elevate barriers for uncertified imports and compel incumbents to maintain dedicated regulatory affairs functions across multiple jurisdictions. Stakeholders must monitor evolving digital dentistry standards and polymer additive restrictions that could force reformulation cycles and disrupt established supplier qualifications.
Market Dynamics
Dental laboratory chain consolidation is compressing supplier margins while CAD/CAM resin adoption forces material manufacturers to reformulate for digital workflows rather than conventional heat-cure protocols.
Growth Catalysts
- MDR compliance pathways:Europe's stricter biocompatibility surveillance under EN ISO 20795-1 is accelerating replacement cycles for legacy acrylic inventories as clinics upgrade to certified formulations.
- Same-day dentistry protocols:Chairside CAD/CAM systems in prosthodontics clinics are expanding demand for rapid-cure provisional resins that polymerize under visible light within minutes.
- Germany's manufacturing cluster:Baden-Württemberg's dense concentration of dental device producers creates localized demand pull for shade-matched PMMA sheets and pre-polymerized beads.
Market Restraints
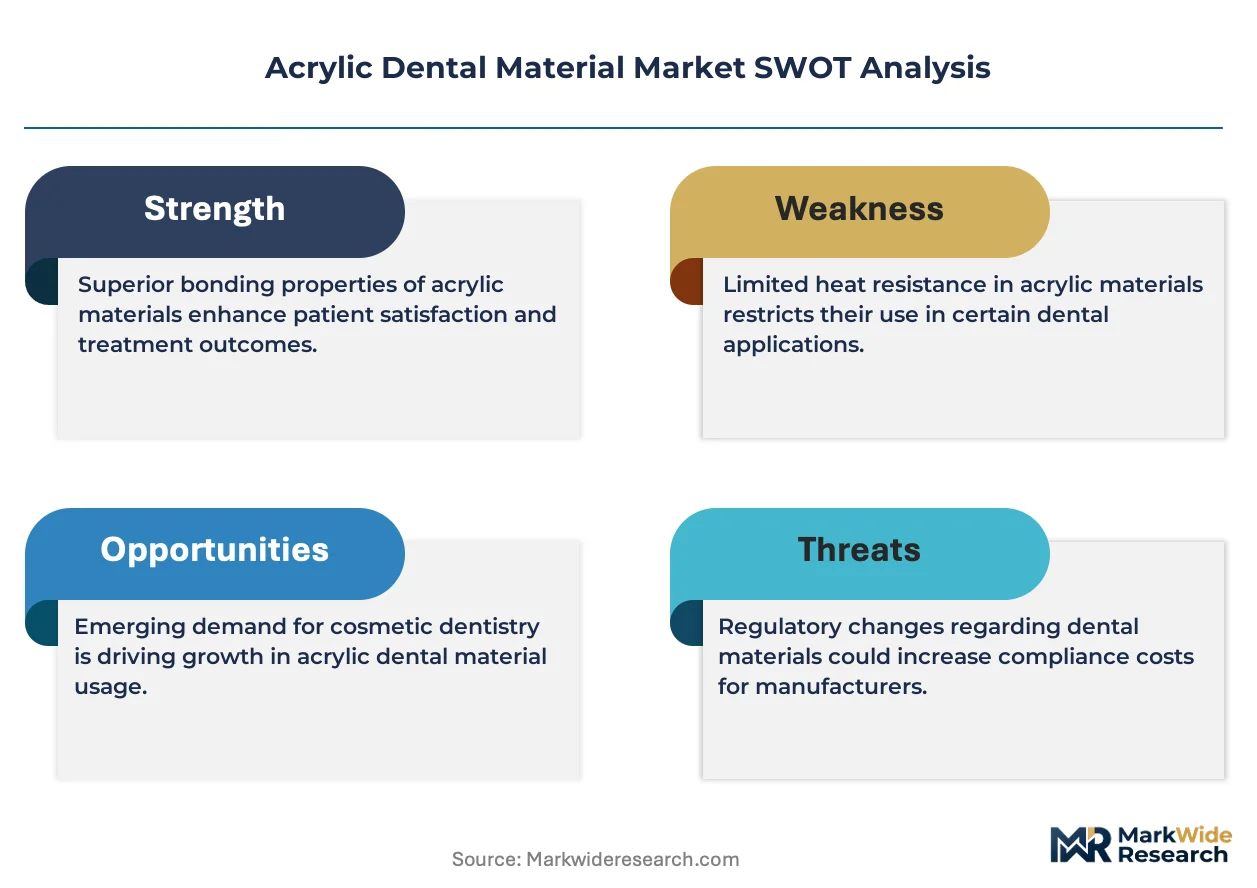
- Methyl methacrylate price volatility:Petrochemical feedstock fluctuations directly compress margins for heat-cure and self-cure resin producers without long-term supply contracts.
- Implant prosthetic substitution:Titanium and zirconia implant-supported restorations are eroding addressable volume for traditional removable acrylic appliances in premium patient segments.
- FDA 510(k) pathway duration:Biocompatibility documentation requirements for novel polymer additives extend time-to-market for reformulated denture base materials by 12-18 months.
Strategic Opportunities
- India's dental infrastructure expansion:Government health schemes and private clinic networks in tier-2 cities are creating first-time demand for affordable heat-cure denture systems.
- 3D printing resin convergence:Photopolymerizable acrylic formulations compatible with DLP and SLA printers open workflow integration for digital denture laboratories.
- Japan's aging demographic mandate:METI-supported eldercare dental programs are expanding reimbursement coverage for removable prosthetics using domestically certified PMMA materials.
Industry Challenges
- CAD/CAM technician scarcity:Digital denture design workflows require specialized training in intraoral scanning and nesting software that conventional dental technicians lack.
- Legacy equipment integration:Laboratories with substantial investment in conventional flask-and-press systems face capital inefficiency when migrating to milling-compatible resin protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acrylic Dental Material Market |
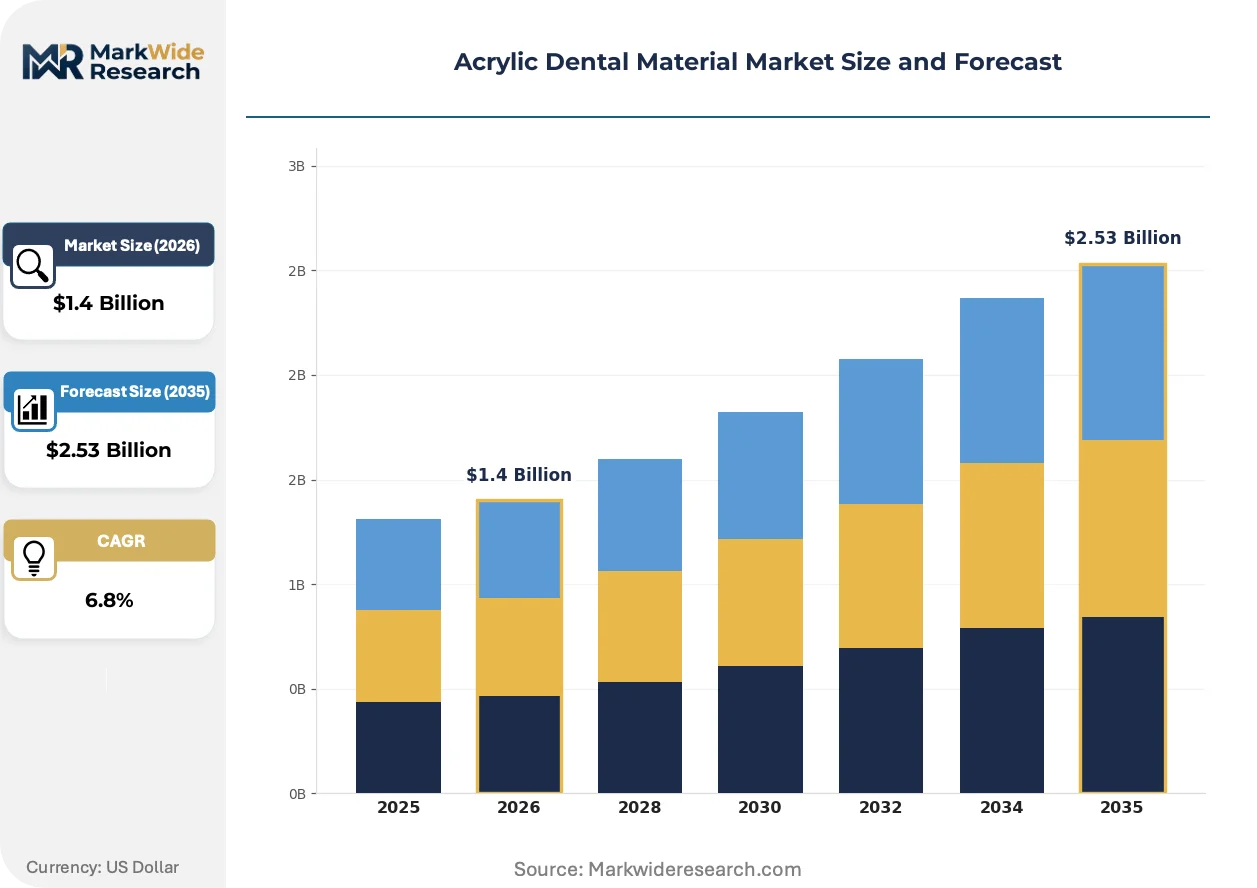
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Resins, Acrylic Sheets, Denture Fittings, Temporary Crowns Application: Orthodontics, Prosthodontics, Dental Implants, Custom Trays End User: Dental Clinics, Hospitals, Research Labs, Dental Laboratories Packaging Type: Bottles, Boxes, Blisters, Bulk Containers |
| Companies Covered | Dentsply Sirona, Ivoclar Vivadent AG, Kulzer GmbH, GC Corporation, 3M ESPE, VITA Zahnfabrik, SHOFU Dental Corporation, Lang Dental Manufacturing Co., Inc., Keystone Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acrylic Dental Material Market Trends and Innovations
Digital fabrication protocols are redefining material specifications across denture production, with polymer chemistry, regulatory evidence requirements, and procurement models all shifting simultaneously.
Photopolymerizable acrylic resins formulated for 385-405 nm light curing are overtaking methyl methacrylate-based heat-cure systems in chairside applications. Prosthodontics clinics with same-day service capabilities are adopting these materials at accelerating rates. The shift is compressing demand for conventional flask polymerization equipment and associated consumables.
Europe's MDR post-market surveillance obligations now require clinical performance data for denture base polymers that previously needed only technical file documentation. Manufacturers must maintain vigilance systems for adverse event reporting across multiple member states. German and French dental laboratories are prioritizing suppliers with established notified body relationships and EU-wide distribution infrastructure.
Buyer concentration among multi-site dental laboratory networks is consolidating procurement of prefabricated acrylic resins under master service agreements. Regional chains are displacing independent laboratories as the primary volume customers for denture base materials. This concentration is most visible in North American markets where private equity-backed dental service organizations control substantial removable prosthetic volume.
Acrylic Dental Material Market Segmentation
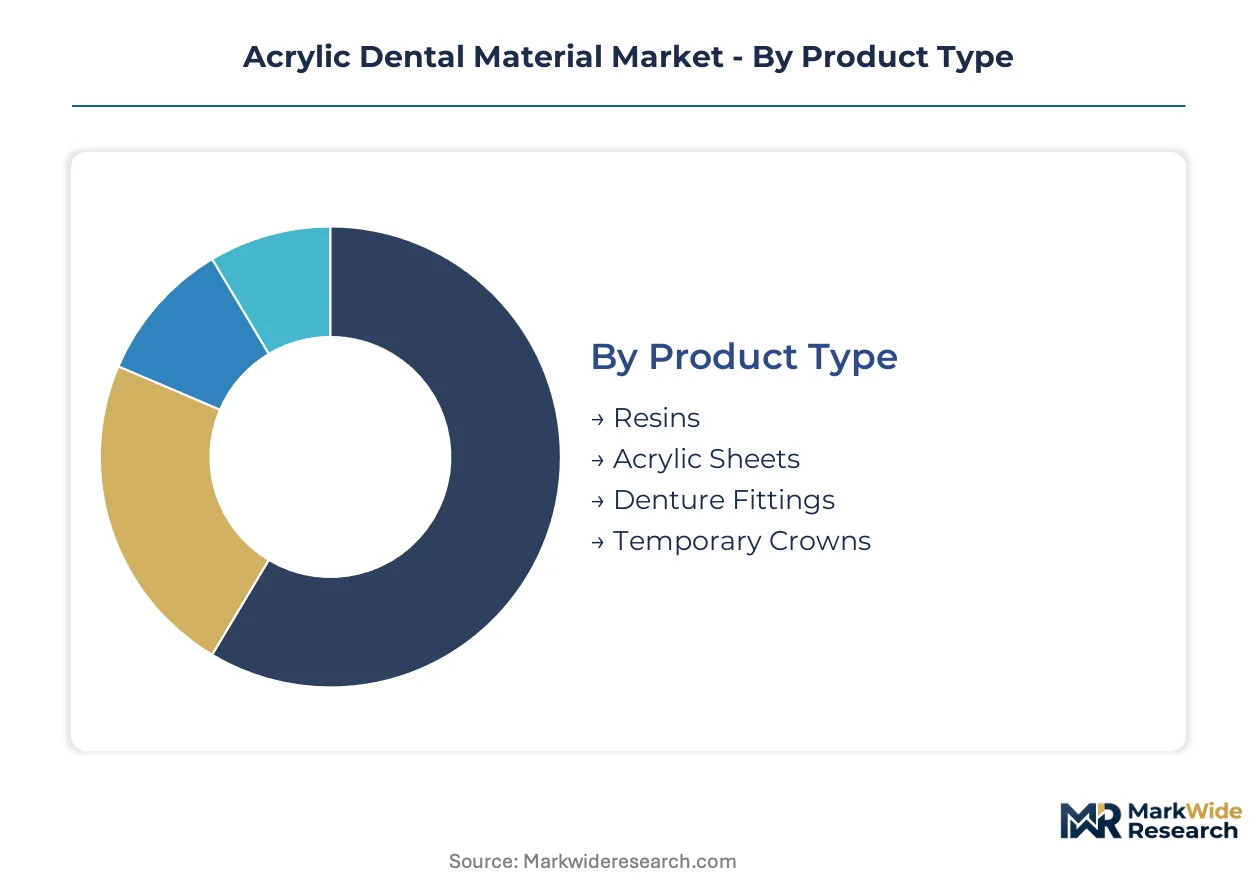
Segmentation in acrylic dental materials reveals distinct procurement patterns across product forms and clinical settings. Material specifications diverge sharply between chairside rapid-cure applications and laboratory-based fabrication workflows.
Product Type:
Standalone polymer systems dominate high-volume denture production, while embedded resin formulations integrate with digital milling and 3D printing platforms.
- Resins:Polymethyl methacrylate-based heat-cure and self-cure formulations polymerize through peroxide-amine initiation at molecular weights exceeding 500,000 g/mol. Demand concentrates in Germany's Baden-Württemberg manufacturing cluster where dental device producers require shade-matched PMMA beads for conventional flask techniques. MDR compliance pathways are accelerating replacement of legacy inventories with EN ISO 20795-1 certified formulations.
- Temporary Crowns:Photopolymerizable bis-acryl composites cure under 385-405 nm visible light within 90-180 seconds for same-day dentistry protocols. Prosthodontics clinics with chairside CAD/CAM capabilities are expanding procurement of these rapid-set materials as patient throughput pressures intensify.
- Acrylic Sheets:Pre-polymerized PMMA copolymer plates serve orthodontic retainers and baseplate fabrication with standardized thickness tolerances.
- Denture Fittings:Pre-fabricated clasps, teeth, and attachment components reduce laboratory labor hours in removable prosthetic assembly.
Volume placements concentrate in Resins; the faster expansion belongs to Temporary Crowns.
Application:
Prosthetic volume flows through established laboratory networks, while implant-related acrylic use shifts toward provisional and aesthetic adjunct roles.
- Prosthodontics:Complete and partial denture fabrication consumes the majority of heat-cure PMMA resin volume through conventional flask-and-press polymerization. Dental laboratory chain consolidation is compressing supplier margins as regional networks consolidate procurement under master service agreements.
- Dental Implants:Acrylic serves provisional crown and surgical guide applications as titanium and zirconia displace traditional removable appliances in premium segments. Implant-supported restorations are eroding addressable volume for conventional removable prosthetics.
- Orthodontics:Retainer fabrication and appliance construction utilize thermoplastic acrylic sheets for clear aligner alternatives and Hawley retainers.
- Custom Trays:Light-cured and self-cure resins form individual impression trays for prosthodontic and implant planning workflows.
Procurement scale peaks in Prosthodontics; Implant-related acrylic applications are gaining share fastest.
End User:
Customer type determines formulation requirements, with clinical settings prioritizing speed and laboratories emphasizing mechanical precision.
- Dental Laboratories:Independent and chain-affiliated labs process bulk resin volumes through heat-cure protocols for denture base fabrication. Buyer concentration among multi-site networks is displacing independent laboratories as primary volume customers.
- Dental Clinics:Chairside operations demand rapid-cure provisional materials compatible with intraoral scanning and same-day delivery protocols.
- Hospitals:Academic medical centers and oral surgery departments utilize acrylic for pre-surgical planning models and trauma splints.
- Research Labs:Material science and clinical research facilities evaluate novel polymer formulations and biocompatibility profiles.
Material throughput centers on Dental Laboratories; Dental Clinics are climbing the fastest.
Packaging Type:
Packaging configuration tracks order scale and shelf-life requirements across customer segments.
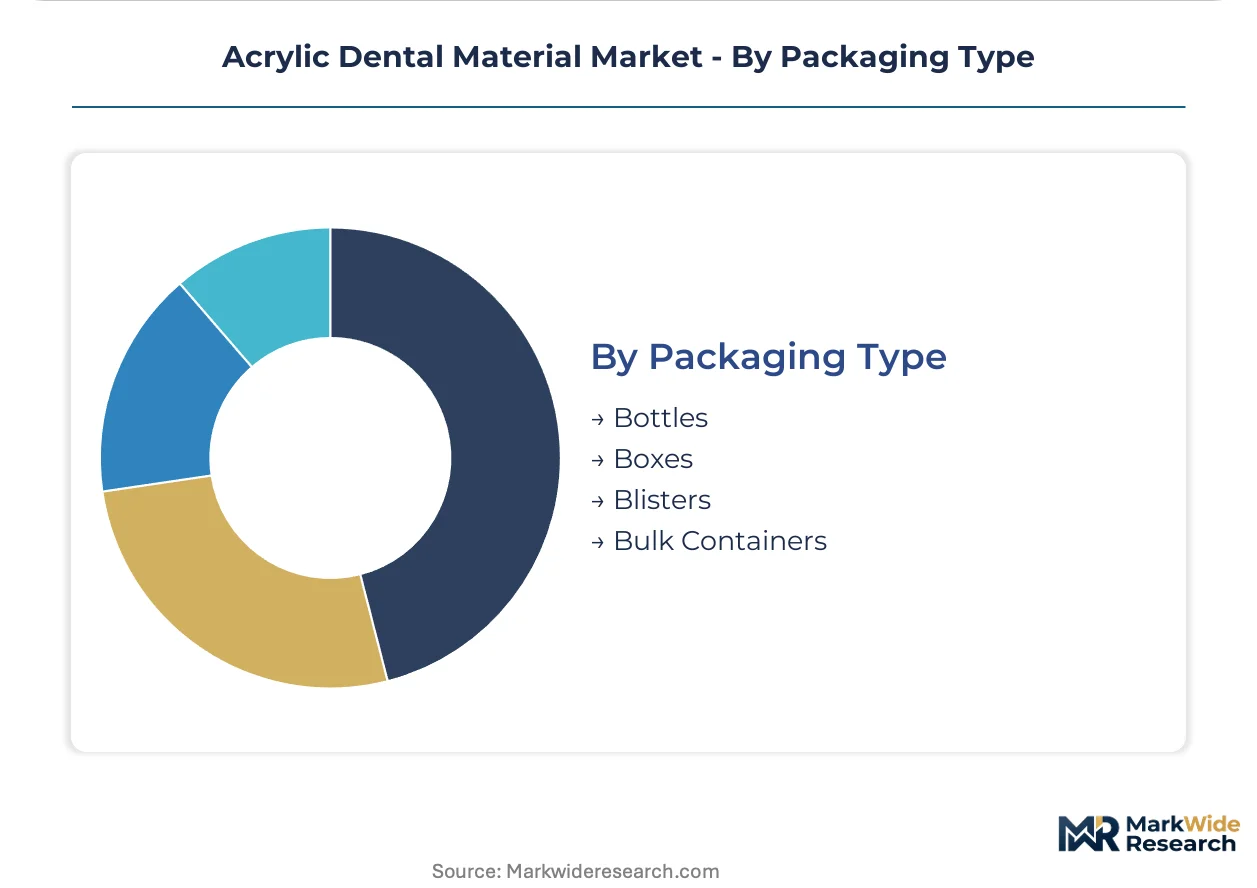
- Bottles:Liquid monomer and powder polymer kits in amber glass or HDPE containers protect photosensitive components from premature initiation.
- Boxes:Pre-weighed cartridge systems align with digital denture workflow specifications for automated dispensing.
- Blisters:Unit-dose temporary crown materials and repair kits serve emergency clinical applications.
- Bulk Containers:Industrial-scale resin supply serves high-throughput dental manufacturing facilities and distribution warehouses.
Shipment volume concentrates in Bottles; Bulk Containers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement concentration among dental laboratory chains is reshaping geographic demand patterns. Germany's manufacturing cluster around Baden-Württemberg anchors European resin consumption. India's tier-2 city clinic expansion and Japan's aging demographic programs are generating new volume centers outside traditional Western markets.
United States
Dental service organization consolidation is compressing supplier margins as regional laboratory networks centralize acrylic procurement under master service agreements. FDA 510(k) clearance pathways for novel polymer additives extend time-to-market by 12-18 months, elevating barriers for uncertified imports. Charlotte-based Dentsply Sirona leverages vertically integrated distribution to dominate heat-cure and self-cure system volumes across North American prosthodontics clinics.
Germany
Baden-Württemberg's dense concentration of dental device producers generates localized demand pull for shade-matched PMMA sheets and pre-polymerized beads. MDR post-market surveillance obligations under EN ISO 20795-1 now require clinical performance data that previously needed only technical file documentation. Ivoclar Vivadent AG anchors European demand through its specialized cadre of denture acrylics, with laboratories prioritizing suppliers with established notified body relationships.
India
Government health schemes and private clinic networks in tier-2 cities are creating first-time demand for affordable heat-cure denture systems. The country's national pharmaceutical regulator maintains biocompatibility documentation requirements that parallel ISO 20795-1 frameworks without full equivalence. Mumbai and Delhi-NCR dental manufacturing corridors are expanding domestic compounding capacity for PMMA bead production serving South Asian export markets.
Japan
METI-supported eldercare dental programs are expanding reimbursement coverage for removable prosthetics using domestically certified PMMA materials. Chairside CAD/CAM adoption in Tokyo and Osaka prosthodontics clinics is accelerating demand for rapid-cure provisional resins compatible with same-day delivery protocols. GC Corporation and SHOFU Dental Corporation anchor domestic supply chains with specialized formulations for aging-population denture fabrication workflows.
Brazil
ANVISA biocompatibility surveillance is tightening import requirements for denture base polymers without established Brazilian registration holders. São Paulo's dental laboratory district concentrates demand for conventional flask-and-press heat-cure systems serving Latin American export markets. Private clinic networks in Rio de Janeiro and Minas Gerais are piloting digital denture workflows that require reformulated milling-compatible resin specifications.
Acrylic Dental Material Market Competitive Landscape
German and Swiss producers anchor the premium formulation tier; US and Japanese specialists hold scale-driven and application-specific positions respectively. Market structure concentrates around three to five vertically integrated resin compounders with dedicated regulatory affairs functions across multiple jurisdictions. Strategic archetypes include: full-spectrum dental material conglomerates with polymer chemistry depth; regional specialists optimizing for specific curing protocols; and digital workflow enablers with CAD/CAM resin expertise. Dominant competitive moves center on backward integration into PMMA monomer supply and technology licensing partnerships with intraoral scanner manufacturers.
Within the premium formulation tier, Ivoclar Vivadent AG and Kulzer GmbH exemplify European specialists with deep shade-matching capabilities and MDR compliance infrastructure. Dentsply Sirona occupies a position as the archetypal vertically integrated North American distributor with captive supply chain control over heat-cure and self-cure acrylic systems. These three companies represent contrasting strategic positions: Liechtenstein-based formulation expertise, German R&D intensity in digital workflow optimization, and US-scale distribution leverage through dental service organization procurement channels.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Ivoclar Vivadent AG |
| Kulzer GmbH |
| GC Corporation |
| 3M ESPE |
| VITA Zahnfabrik |
| SHOFU Dental Corporation |
| Lang Dental Manufacturing Co., Inc. |
| Keystone Industries |
| Others |
Pricing and Supply Chain Analysis
Captive backward integration into methyl methacrylate monomer supply anchors pricing power for German and Swiss compounders serving MDR-certified denture base markets, while outsourced resin procurement exposes smaller laboratories to petrochemical feedstock volatility compressing margins on conventional heat-cure systems.
Pricing Analysis
High-volume resin placements trade on thin margins against premium-capture in shade-matched CAD/CAM-compatible formulations. Pricing stratifies across premium, standard, and economy tiers driven by EN ISO 20795-1 certification grade and volume scale in master service agreements. Cost compression in economy heat-cure segments is intensifying because dental laboratory chain consolidation centralizes procurement leverage. Independent laboratories exhibit highest price sensitivity; vertically integrated multinational manufacturers demonstrate lowest.
Supply Chain Analysis
Skilled polymer chemist scarcity in Baden-Württemberg and Osaka manufacturing corridors constrains formulation capacity expansion for next-generation photopolymerizable resins. Supply concentrates in Germany, Japan, and the United States for PMMA bead production, drawing from Saudi and South Korean petrochemical feedstocks. Single-source vulnerability sits with methyl methacrylate monomer supply contracted through integrated chemical majors. Distribution runs through dental service organization procurement channels and specialized dental distribution networks serving laboratory clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified polymer chemist scarcity across German and Japanese manufacturing hubs props pricing for MDR-compliant denture base formulations, constraining rapid capacity expansion despite accelerating digital denture demand.
For Market Incumbents: Anticipate implant prosthetic substitution eroding removable appliance volume in premium segments by accelerating R&D in provisional crown resins for same-day dentistry protocols. Defend margin position through captive control of PMMA monomer supply and exclusive notified body relationships streamlining MDR compliance pathways for dental laboratory chains. For New Entrants and Emerging Players: Photopolymerizable resin formulations for chairside CAD/CAM systems offer the most penetrable wedge against entrenched heat-cure incumbents. Target India's tier-2 city clinic networks with affordable rapid-cure systems compatible with government health scheme reimbursement. Pursue technology licensing partnerships with intraoral scanner manufacturers to secure workflow integration. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by full-spectrum dental material conglomerates seeking digital workflow capabilities. Long-term viability favors specialists with demonstrated MDR compliance infrastructure and established shade-matching libraries. Watch FDA 510(k) clearance timelines for novel polymer additives as inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Compliance Infrastructure Investment | EN ISO 20795-1 certification accelerates replacement cycles for legacy acrylic inventories across European dental laboratories. |
| Photopolymerizable Resin Development | 385-405 nm light-cure formulations capture chairside CAD/CAM volume from conventional heat-cure protocols in prosthodontics clinics. |
| Backward Integration into Monomer Supply | Captive methyl methacrylate sourcing insulates margin compression from petrochemical feedstock volatility. |
| Digital Workflow Partnership | Intraoral scanner compatibility agreements secure preferred supplier status in consolidating dental laboratory chains. |
| India Manufacturing Footprint Expansion | Domestic PMMA compounding capacity serves government health scheme demand and South Asian export markets. |
Research Methodology
Multi-period observation of dental laboratory procurement patterns, CAD/CAM system installations, and MDR compliance certification timelines anchored the trend analysis, supplemented by interviews with prosthodontics clinic directors, dental laboratory chain procurement managers, polymer R&D directors at material manufacturers, and notified body certification specialists. Secondary validation drew from FDA 510(k) clearance databases, EUDAMED post-market surveillance records, EN ISO 20795-1 technical documentation, and customs trade data for methyl methacrylate resin shipments. Bottom-up volume estimates from individual product categories triangulated against top-down market sizing from industry association reports.
Segment-weighting approaches modeled resin, temporary crown, acrylic sheet, and denture fitting categories alongside application splits across prosthodontics, implants, orthodontics, and custom trays. Geographic clustering captured country-level regulatory pathway differences and manufacturing concentration effects. CAGRs derived from fitted growth curves incorporating replacement cycle acceleration from MDR compliance mandates and digital denture workflow adoption rates across the projection horizon. Forecast inputs included dental laboratory chain consolidation velocity, chairside CAD/CAM penetration in prosthodontics practices, and methyl methacrylate price elasticity assumptions.
Several conditions sit outside the modeled scope, including unforeseen polymer additive regulatory restrictions, abrupt implant prosthetic substitution acceleration, and pandemic-scale disruptions to dental clinic operations. Forecasts reflect documented assumptions about regulatory pathway durations and technology adoption curves. Material deviation in FDA 510(k) clearance timelines, notified body capacity constraints, or methyl methacrylate supply disruptions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Tooth Filling Materials Market
Dental Materials
Solid Toothpaste Market
Dental Materials
Dental Gypsum Market
Dental Materials
Charcoal Teeth Whitening Powder Market
Dental Materials
Fluoride Mouthwash Market
Dental Materials
Global Zirconia Based Dental Materials Market
Dental Materials
Zirconia Based Dental Ceramics Market
Dental Materials
Global Demineralized Bone Matrix Market
Dental Materials
Fluoride-Free Toothpaste Market
Dental Materials
Dental Amalgam Market
Dental Materials
Dental Polymerization Lamps Market
Dental Materials
Global Dental Adhesive Market
Dental Materials
Global Dental Zirconia Block Market
Dental Materials
Dental Materials for 3D Printing Market
Dental Materials
Dental Biomaterials Market
Dental Materials
Global Teeth Whitening Product Market