
 Global Biotechnology-Based Chemical Market | 2026-2036
Global Biotechnology-Based Chemical Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biotechnology-Based Chemical Market Foresight
Specialty chemical distribution networks are reshaping how biotechnology-derived intermediates reach pharmaceutical and agricultural formulators. BASF SE leverages captive fermentation capacity in Ludwigshafen to supply enzyme precursors directly to European drug manufacturers. DuPont anchors North American demand through its recombinant DNA platform for industrial biosurfactants. DSM competes on specialty biopolymer grades for medical device applications, while Cargill, Incorporated extends its agricultural origination network into biofertilizer downstream channels.
Biotechnology-based chemicals comprise molecules, polymers, and functional materials synthesized through living organisms or enzymatic processes, typically operating at 30–37°C and pH 6.5–7.5 in stirred-tank bioreactors with titers reaching 50–200 g/L for optimized strains. Their primary purpose is to replace petroleum-derived feedstocks with renewable, precisely structured compounds for high-specification end uses. Enzymes and biopolymers command the deepest margin pools due to pharmaceutical-grade certification requirements and limited qualified supply bases. Fermentation technology dominates installed capacity, though recombinant DNA platforms are capturing the fastest expansion as CRISPR-edited strains slash production cycle times for biosurfactants and biopesticides.
The EPA regulates biobased pesticide registrations under FIFRA, while the EMA enforces GMP standards for enzymatic active pharmaceutical ingredients through its centralized marketing authorization pathway. REACH compliance in Europe and FDA quality agreements in the United States shape market access timelines and capital allocation for new bioreactor investments. Stakeholders must monitor how the EU Green Deal's biobased content mandates and the U.S. Inflation Reduction Act's domestic production credits will redirect contract manufacturing flows across the Atlantic.
Market Dynamics
CRISPR-edited microbial strains are compressing fermentation cycle times by 30-40%, forcing incumbent pharmaceutical intermediate suppliers to rebuild strain libraries or surrender margin to contract biomanufacturers with advanced gene-editing capabilities.
Growth Catalysts
- Inflation Reduction Act domestic production credits:U.S. pharmaceutical formulators are accelerating captive bioreactor investments to qualify for API manufacturing subsidies, redirecting contract flows from European CMOs toward domestic fermentation capacity.
- Enzymatic active pharmaceutical ingredient certification:EMA's centralized GMP pathway for biotech-derived APIs creates preferential market access timelines, concentrating procurement among qualified fermentation suppliers in Germany and Switzerland.
- Biofertilizer downstream channels:Agricultural biologicals distributors in Brazil and India are building dedicated cold-chain infrastructure for live microbial inoculants, extending addressable acreage for nitrogen-fixing seed treatments.
Market Restraints
- Pharmaceutical-grade glucose feedstock volatility:Fermentation titers above 150 g/L require ultra-pure carbohydrate streams, and corn-derived glucose price swings in the U.S. Midwest directly compress bioreactor operating margins.
- Single-source enzyme precursor supply:European drug manufacturers remain dependent on Ludwigshafen and Basel corridor fermentation capacity, creating geographic concentration risk for time-sensitive intermediate shipments.
- Petroleum-derived surfactant cost floor:Biosurfactants face persistent substitution pressure from synthetic alkyl polyglucosides when crude oil trades below $70 per barrel, capping pricing power in industrial cleaning applications.
Strategic Opportunities
- Underpenetrated Indian ag-biologicals market:FSSAI and CDSCO are harmonizing biopesticide registration pathways, enabling multinational fermentation houses to transfer validated production strains to Indian CMOs for domestic formulation.
- EU Green Deal biobased content mandates:Packaging and medical device manufacturers must source certified biopolymers by 2030, creating guaranteed offtake for polylactic acid and polyhydroxyalkanoate grades meeting EN 13432 compostability standards.
- Continuous flow biocatalysis convergence:Immobilized enzyme platforms married to microreactor engineering enable real-time quality monitoring, attracting pharmaceutical fine chemical producers seeking to replace batch fermentation with plug-and-play modular systems.
Industry Challenges
- CRISPR strain engineer talent scarcity:Fermentation facilities in the U.S. and Germany compete for microbial geneticists capable of multiplexed genome editing, with compensation premiums exceeding 40% for candidates with GMP-compliant strain documentation experience.
- EMA quality agreement timeline compression:New enzymatic API facilities face 18-24 month certification queues, delaying revenue recognition and straining capital deployment schedules for bioreactor investments above 10,000-liter scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biotechnology-Based Chemical Market |
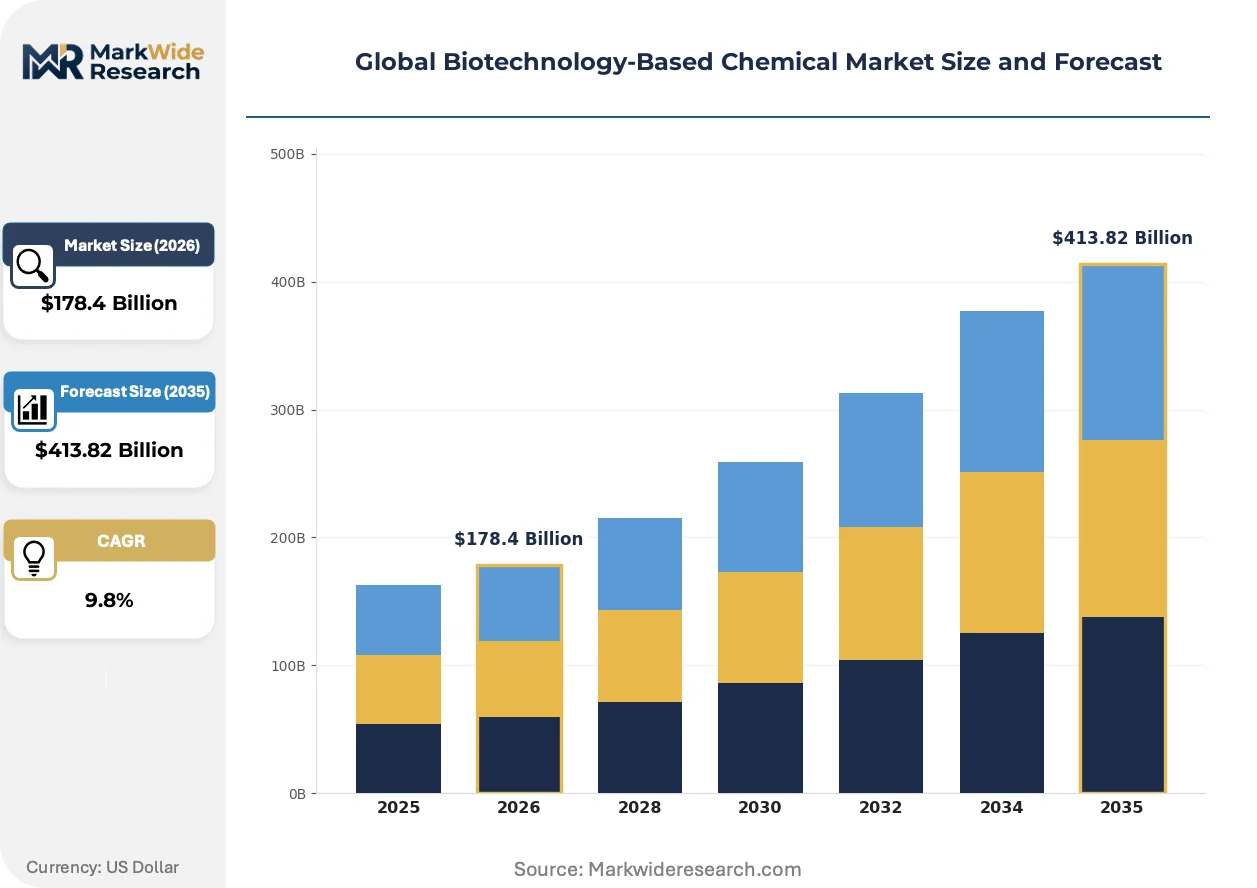
| Market Size in 2026 | $178.4 Billion |
| Market Size in 2035 | $413.82 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzymes, Biosurfactants, Biopolymers, Biofertilizers, Biopesticides Technology: Fermentation, Recombinant DNA, Protein Engineering, Cell Culture, Bioconversion Application: Pharmaceuticals, Agriculture, Food & Beverage, Personal Care, Environmental Management End User: Biopharmaceutical Companies, Agrochemical Firms, Food Manufacturers, Cosmetic Producers |
| Companies Covered | BASF SE, DuPont, Evonik Industries, Cargill, Incorporated, Archer Daniels Midland, Toray Industries, Mitsubishi Chemical, DSM, GF Biochemicals Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biotechnology-Based Chemical Market Shifts & Advancements
Biotechnology-based chemical production is fragmenting across three simultaneous vectors: gene-editing precision, regulatory geography arbitrage, and procurement model restructuring that favors modular over asset-heavy supply relationships.
Continuous manufacturing is migrating from pharmaceutical small-molecule synthesis into fermentation-derived intermediate production. Novartis and Eli Lilly are piloting perfusion bioreactor trains with real-time metabolite monitoring, cutting batch-to-batch variability for monoclonal antibody precursors. This shift is compressing working capital requirements and enabling just-in-time delivery contracts that displace traditional 10,000-liter stainless steel tank farms.
REACH authorization requirements for persistent organic pollutants are forcing reformulation of industrial biosurfactants used in metalworking fluids. ECHA's 2024 restriction proposals on per- and polyfluoroalkyl substances are redirecting R&D spending toward protein-based emulsifiers that biodegrade within 28 days. German automotive suppliers are qualifying rhamnolipid alternatives ahead of enforcement deadlines, creating first-mover certification advantages for compliant fermentation houses.
Pharmaceutical procurement teams are consolidating enzymatic API contracts under outcome-based supply agreements that tie payment to batch yield consistency rather than input volume. Merck KGaA and Sanofi have shifted 30% of intermediate spend to performance-guaranteed contracts with fermentation CMOs, transferring yield risk downstream. This restructuring is most advanced in Switzerland and southern Germany, where qualified supplier density enables competitive benchmarking.
Global Biotechnology-Based Chemical Market Segmentation
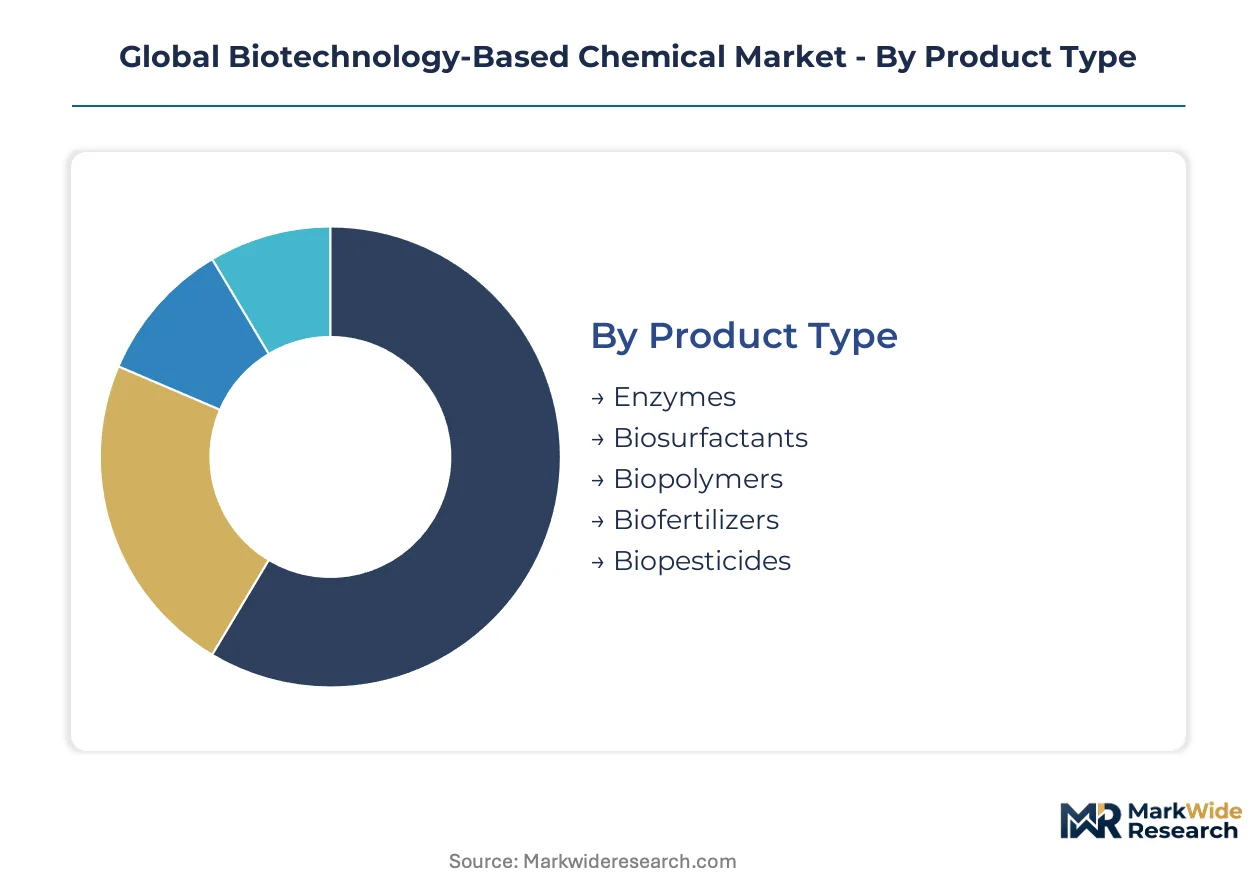
Segmentation in biotechnology-based chemicals reveals how production technology, regulatory pathways, and end-use specifications create distinct margin architectures. Each dimension carries implications for capital intensity, certification timelines, and geographic sourcing strategy.
Product Type:
Cost tiers separate commodity-grade agricultural inputs from pharmaceutical-certified specialties requiring GMP documentation and strain pedigree verification.
- Enzymes:Catalytic proteins produced via submerged fermentation or recombinant expression, typically stabilized through immobilization on silica or polymer carriers. Pharmaceutical-grade oxidoreductases command premiums in Germany and Switzerland where EMA certification barriers limit qualified supply. Enzymes command the established base.
- Biosurfactants:Microbial glycolipids and lipopeptides with critical micelle concentrations 10-100x lower than synthetic alternatives. Rhamnolipid demand concentrates in German automotive metalworking fluid reformulations driven by ECHA restrictions on fluorinated surfactants. The steepest expansion runs through biosurfactants.
- Biopolymers:Polylactic acid and polyhydroxyalkanoate thermoplastics meeting EN 13432 compostability standards for medical device and packaging applications.
- Biofertilizers:Live microbial inoculants including nitrogen-fixing rhizobia and phosphate-solubilizing bacilli requiring cold-chain distribution infrastructure.
- Biopesticides:Bacillus thuringiensis and Beauveria bassiana formulations regulated under EPA FIFRA and equivalent national frameworks for integrated pest management.
Enzymes retain the revenue foundation through recurring pharmaceutical procurement contracts. Biosurfactants are climbing the fastest as industrial surfactant substitution accelerates under REACH restrictions.
Technology:
Application requirements dictate technology selection, with pharmaceutical APIs demanding recombinant precision while agricultural biologicals tolerate classical fermentation economics.
- Fermentation:Submerged culture of wild-type or conventionally improved strains in stirred-tank bioreactors operating at 30-37°C with titers reaching 50-200 g/L for optimized production hosts. This platform anchors installed capacity across Brazilian biofertilizer plants and Indian enzyme facilities where capital constraints favor proven infrastructure.
- Recombinant DNA:Plasmid-based expression systems enabling heterologous protein production in Escherichia coli or Pichia pastoris with defined genetic stability. CRISPR-edited strains are compressing cycle times for biosurfactant production in U.S. contract manufacturing organizations qualifying for Inflation Reduction Act credits. Recombinant DNA commands the established base.
- Protein Engineering:Directed evolution and rational design approaches modifying catalytic efficiency, thermal stability, or substrate specificity for industrial process conditions.
- Cell Culture:Mammalian or insect cell expression systems for complex glycoproteins and monoclonal antibody precursors requiring post-translational modification machinery absent in microbial hosts.
- Bioconversion:Whole-cell or enzyme-catalyzed transformation of renewable feedstocks into platform chemicals, typically operating at ambient pressure with reduced downstream separation burden. The steepest expansion runs through bioconversion.
Recombinant DNA retains dominance in pharmaceutical value chains. Bioconversion is expanding most quickly as chemical manufacturers retrofit existing infrastructure for biocatalytic process steps.
Application:
Volume concentration varies dramatically, with agricultural applications consuming tonnage scales while pharmaceutical grams command disproportionate value capture.
- Pharmaceuticals:Enzymatic active pharmaceutical ingredients, biocatalytic intermediates, and excipients requiring FDA quality agreements and EMA centralized marketing authorization. U.S. formulators are consolidating procurement under outcome-based contracts that transfer yield risk to fermentation CMOs. Pharmaceuticals command the established base.
- Agriculture:Biofertilizers, biopesticides, and biostimulants distributed through dedicated cold-chain networks in Brazil and India where FSSAI and CDSCO harmonization is enabling multinational strain transfers.
- Food & Beverage:Processing aids including amylases, proteases, and lipases with GRAS or equivalent safety designations for starch modification and dairy applications.
- Personal Care:Biosurfactants and biopolymers replacing petroleum-derived emulsifiers and microplastics in cosmetic formulations subject to EU microplastic restriction proposals.
- Environmental Management:Bioremediation cultures and wastewater treatment enzymes addressing petroleum hydrocarbon degradation and nutrient removal in industrial effluent. The steepest expansion runs through environmental management.
Pharmaceuticals anchor value generation through certification-protected margins. Environmental management is gaining share fastest as industrial discharge regulations tighten across manufacturing geographies.
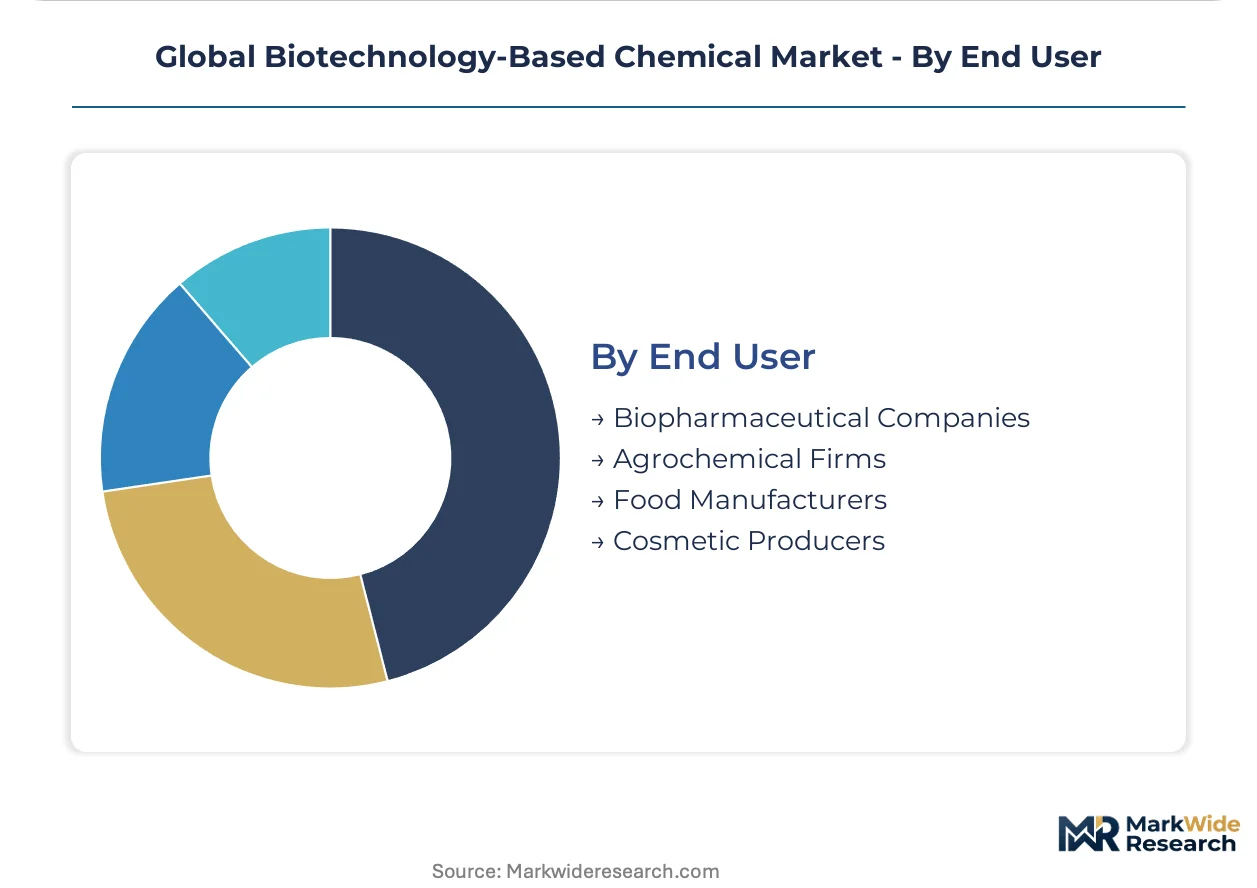
End User:
Customer type determines procurement sophistication, with biopharmaceutical companies imposing GMP documentation burdens that agricultural formulators rarely match.
- Biopharmaceutical Companies:Developers of biologics and small-molecule drugs sourcing enzymatic APIs and biocatalytic intermediates with full batch records and strain pedigree documentation. Merck KGaA and Sanofi have shifted substantial intermediate spend to performance-guaranteed fermentation contracts in Switzerland and southern Germany. Biopharmaceutical companies command the established base.
- Agrochemical Firms:Integrated crop protection companies and specialized biologicals distributors building downstream formulation capacity for live microbial products in Brazil and India.
- Food Manufacturers:Industrial processors sourcing GRAS-designated enzymes for starch liquefaction, protein hydrolysis, and lipid modification with focus on cost-per-activity-unit economics.
- Cosmetic Producers:Formulators seeking biodegradable surfactants and biopolymer rheology modifiers to preempt EU microplastic and persistent organic pollutant restrictions. The steepest expansion runs through cosmetic producers.
Biopharmaceutical companies retain procurement volume leadership through recurring enzymatic API demand. Cosmetic producers are expanding most quickly as clean-label and biodegradability specifications reshape ingredient selection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's liquid bulk terminals anchor European biobased chemical flows, while Union Pacific's chemical corridor rail lines connect U.S. Midwest fermentation feedstock origins to Gulf Coast processing clusters. These infrastructure backbones determine where capital-intensive bioreactor investments achieve lowest delivered cost.
United States
Domestic API manufacturing subsidies under the Inflation Reduction Act are redirecting contract flows from European CMOs toward U.S. fermentation capacity. FDA quality agreement requirements and EPA FIFRA registrations shape facility certification timelines. The Gulf Coast corridor from Houston to New Orleans concentrates perfusion bioreactor investments serving pharmaceutical formulators.
Germany
EMA centralized marketing authorization for enzymatic APIs creates preferential market access timelines, concentrating procurement among qualified fermentation suppliers. ECHA REACH restrictions on per- and polyfluoroalkyl substances redirect R&D toward protein-based emulsifiers. The Ludwigshafen-Basel corridor anchors European enzyme precursor supply for time-sensitive intermediate shipments.
India
FSSAI and CDSCO harmonization of biopesticide registration pathways enables multinational fermentation houses to transfer validated production strains to Indian CMOs. The country's national pharmaceutical regulator enforces GMP standards for enzymatic active pharmaceutical ingredients. Maharashtra and Gujarat host expanding fermentation capacity for domestic biofertilizer formulation.
Brazil
Agricultural biologicals distributors are building dedicated cold-chain infrastructure for live microbial inoculants, extending addressable acreage for nitrogen-fixing seed treatments. ANVISA regulates biobased pesticide registrations alongside the national agricultural defense framework. São Paulo state anchors downstream formulation capacity for biofertilizer distribution networks.
Switzerland
Swissmedic enforces pharmaceutical-grade certification standards that create barriers limiting qualified enzyme precursor supply. Outcome-based supply agreements tying payment to batch yield consistency are restructuring procurement relationships. The Basel-Zurich corridor concentrates performance-guaranteed fermentation contracts with biopharmaceutical companies.
Global Biotechnology-Based Chemical Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: diversified chemical conglomerates with captive fermentation capacity, specialized biomanufacturing CMOs with advanced gene-editing capabilities, and agricultural processors extending origination networks into biofertilizer channels. Competitive positioning depends on strain library depth, GMP certification status, and geographic proximity to pharmaceutical clusters. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players seeking to secure qualified supply positions ahead of EU Green Deal biobased content mandates.
Within the diversified chemical conglomerate tier, BASF SE and DuPont occupy positions defined by integrated fermentation infrastructure and direct supply relationships with pharmaceutical formulators. DSM sits within the specialty biopolymer segment, representing the certification-driven archetype where EN 13432 compostability standards create margin protection. Cargill, Incorporated exemplifies the agricultural processor extension model, leveraging origination networks to capture downstream value in biofertilizer channels.
| Leading Market Players |
|---|
| BASF SE |
| DuPont |
| Evonik Industries |
| Cargill, Incorporated |
| Archer Daniels Midland |
| Toray Industries |
| Mitsubishi Chemical |
| DSM |
| GF Biochemicals Ltd. |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese fermentation intermediates is compressing spot pricing for commodity-grade enzymes while tightening margins for European GMP-certified suppliers, creating divergent pricing postures across the Atlantic.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, technical-grade, and agricultural-grade levels separates enzymatic APIs certified under EMA centralized pathways from bulk fermentation outputs. Price differentiation rests on GMP documentation burden and strain pedigree verification, with Swiss and German suppliers commanding premiums against Indian spot-market competition. Cost compression in technical-grade biosurfactants is intensifying because petroleum-derived alkyl polyglucosides retain cost parity below crude oil thresholds. Agricultural formulators in Brazil exhibit highest price sensitivity, while biopharmaceutical procurement teams in Basel and Zurich prioritize batch-yield consistency over unit economics.
Supply Chain Analysis
Export-control restrictions on CRISPR-edited strain libraries limit technology transfer from U.S. contract biomanufacturers to Indian CMOs, fragmenting global production networks. Supply concentrates in Germany, Switzerland, and the United States for pharmaceutical-grade enzymatic precursors, while Brazil and India anchor agricultural biologicals formulation. Raw material dependencies center on pharmaceutical-grade glucose from U.S. Midwest corn processing, specialized nitrogen sources for nitrogen-fixing inoculants, and silica carriers for enzyme immobilization. Single-source vulnerability runs through the Ludwigshafen-Basel corridor for time-sensitive intermediate shipments. Distribution runs through dedicated cold-chain networks for live microbial products in tropical agriculture markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics logic is reshaping competitive positioning as modular perfusion bioreactor systems enable plug-and-play interoperability between pharmaceutical formulators and contract fermentation houses, collapsing traditional asset-heavy supply relationships.
For Market Incumbents: Entrench GMP-certified capacity positions in Switzerland and southern Germany through EMA quality agreement pre-certification, defending against CRISPR-enabled contract biomanufacturers capturing Inflation Reduction Act domestic production credits. Deepen backward integration into pharmaceutical-grade glucose feedstock through origination partnerships with U.S. Midwest processors, securing margin protection against carbohydrate price volatility.
For New Entrants and Emerging Players: Indian ag-biologicals distribution presents the most penetrable white-space opportunity, leveraging FSSAI-CDSCO registration harmonization to transfer validated production strains from multinational fermentation houses to domestic CMOs. Target biofertilizer cold-chain infrastructure buildouts in Maharashtra and Gujarat through joint venture structures with established agricultural distributors, avoiding capital-intensive greenfield fermentation investments.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across continuous-flow biocatalysis sub-segments as microreactor engineering displaces 10,000-liter stainless steel tank farms, compressing working capital requirements for modular platform operators. Acquisition focus should center on CRISPR strain engineering boutiques with GMP-compliant documentation libraries and established pharmaceutical CMO relationships. Monitor EMA certification queue lengths as early signal for capacity-constraint inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Perfusion Bioreactor Scale-Up | Novartis and Eli Lilly piloting real-time metabolite monitoring cuts batch-to-batch variability for monoclonal antibody precursors. |
| Backward Integration into Feedstock | Cargill's origination network extension into pharmaceutical-grade glucose secures margin protection against Midwest corn price swings. |
| EMA Pre-Certification Investment | Swiss and German suppliers building 18-24 month quality agreement buffers ahead of enzymatic API demand inflection. |
| CRISPR Strain Library Acquisition | Contract biomanufacturers with multiplexed genome editing capabilities capture Inflation Reduction Act domestic production credits. |
| Cold-Chain Infrastructure Partnership | Brazilian agricultural distributors building dedicated networks for live microbial inoculants extend nitrogen-fixing seed treatment acreage. |
Research Methodology
Operator-level perspectives from fermentation plant managers, pharmaceutical procurement leads, agricultural biologicals distributors, and regulatory affairs directors anchored the qualitative base, triangulated against secondary validation from EMA centralized marketing authorization filings, EPA FIFRA registration databases, SEC 10-K disclosures from diversified chemical conglomerates, and customs trade data tracking fermentation intermediate flows. Bottom-up capacity assessments across Ludwigshafen, Basel, Houston, and São Paulo clusters converged with top-down market sizing.
Scenario-bracketing around Inflation Reduction Act implementation pace and EU Green Deal biobased mandate enforcement timelines framed the analytical approach across the analysis window. Segmentation dimensions modeled include product type tier, end-use application, technology platform, and regional regulatory cluster. CAGRs derived from installed bioreactor capacity expansion schedules, strain titer improvement curves, and substitution elasticity estimates for petroleum-derived alternatives.
Practitioners should monitor EMA certification queue compression, CRISPR strain engineer compensation inflation, and petroleum-chemical cost parity thresholds for early signals of forecast revision. Material shifts in U.S. domestic production credit permanence or REACH authorization acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Asia-Pacific Methyl Acrylate Market
Chemicals
Dimethylaminopropylamine (DMAPA) Market
Chemicals
Trichlorosilane Market
Chemicals
Phosphorus Pentasulfide (P2S5) Market
Chemicals
Cupric Chloride Market
Chemicals
Africa Mining Chemicals Market
Chemicals
Industrial Odor Management Market
Chemicals
Potassium Iodide Market
Chemicals
Aluminum Chemicals Market
Chemicals
5 Dinitroaniline Market
Chemicals
LAMEA Dimethyl Phosphate Market
Chemicals
Ethylenediamine (EDA) Market
Chemicals
Metal Finishing Chemicals Market
Chemicals
Methyl P-Hydroxybenzoate Market
Chemicals
Global Electronic Grade Phosphoric Acid Market
Chemicals
Fluorochemicals Market