
 India Anhydrous Hydrogen Fluoride Market | 2026-2036
India Anhydrous Hydrogen Fluoride Market Size, Share, and Industry Trends Forecast 2026-2036
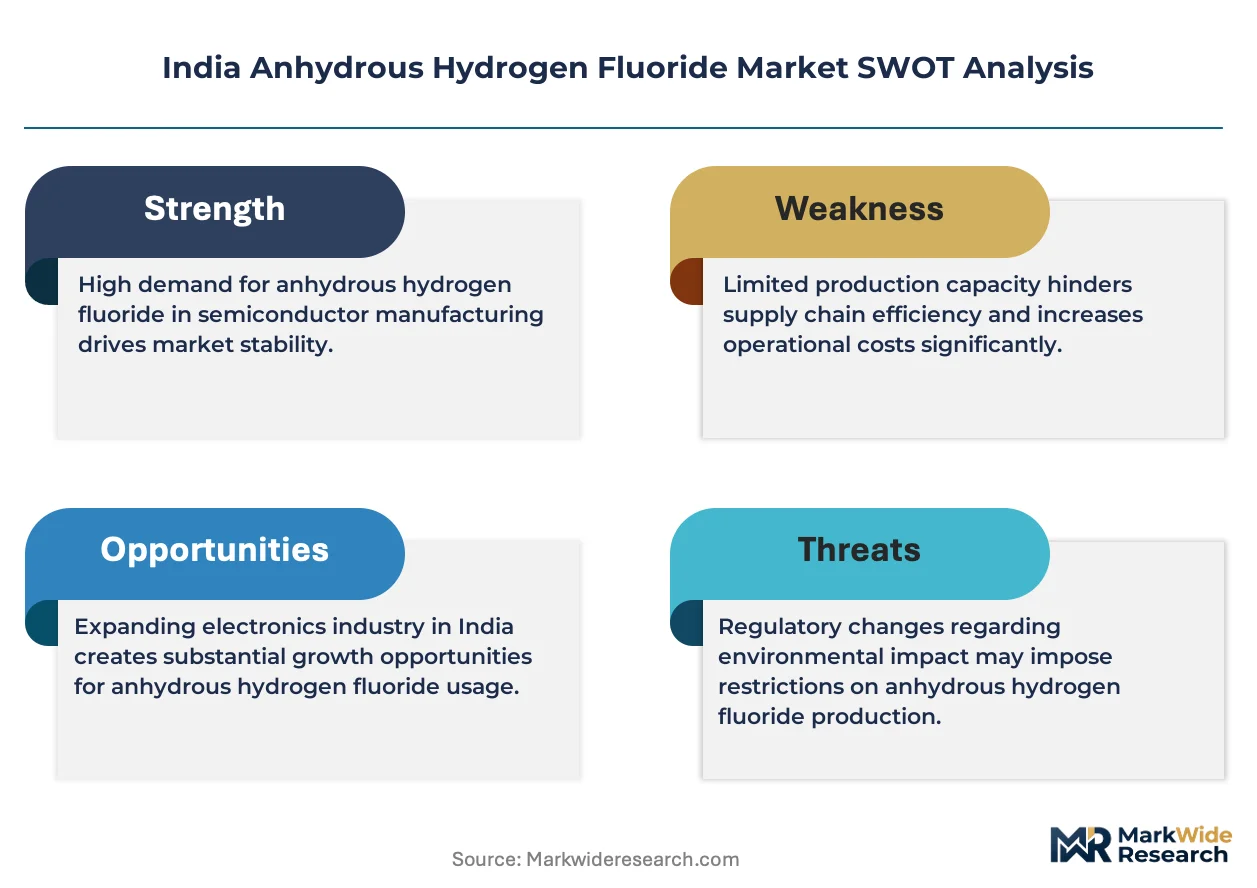
India Anhydrous Hydrogen Fluoride Market Insights
Modular bulk-supply contracts with on-site storage tanks are repositioning procurement economics for large consumers. Gujarat Fluorochemicals Limited anchors production capacity through captive feedstock integration at its Dahej complex. Navin Fluorine International Limited differentiates via specialty fluorochemical downstream derivatives. SRF Limited leverages its refrigerant-grade expertise to sustain volume leadership in domestic distribution.
Anhydrous hydrogen fluoride is a colorless, corrosive liquid or gas with the chemical formula HF, typically manufactured through the reaction of fluorspar with sulfuric acid and distilled to achieve purity grades exceeding 99 percent; it serves as the foundational feedstock for fluorinated compounds used in semiconductor etching, refrigerant synthesis, and pharmaceutical intermediates. The liquid form dominates commercial transactions due to safer handling logistics and established bulk transport infrastructure. Semiconductor applications represent the fastest-expanding demand pool as domestic chip fabrication capacity expands. Chemical Manufacturing as an industry vertical commands the deepest margin pools through backward-integrated consumption models.
The Bureau of Indian Standards enforces purity specifications that filter out sub-scale importers, while the Central Pollution Control Board mandates stringent effluent handling protocols for HF manufacturing facilities. The PLI scheme for electronics manufacturing indirectly amplifies demand by subsidizing domestic semiconductor and component production. Stakeholders must track how evolving BIS certification timelines and state-level environmental clearances reshape the feasibility of new capacity additions.
Market Dynamics
Semiconductor fabs in Gujarat and Tamil Nadu are scaling fluorinated chemistry procurement faster than domestic supply can respond, creating a structural tension between captive production economics and merchant market reliance.
Growth Catalysts
- PLI scheme for electronics manufacturing:The production-linked incentive framework subsidizes domestic semiconductor and component fabrication, amplifying feedstock demand for etching-grade anhydrous hydrogen fluoride.
- Dahej and Mundra chemical park clustering:Integrated manufacturing zones in western India concentrate fluorochemical capacity, reducing logistics costs for downstream refrigerant and pharmaceutical intermediate producers.
- BIS purity certification tightening:The Bureau of Indian Standards is elevating impurity thresholds for industrial-grade HF, filtering out sub-scale importers and consolidating procurement toward certified domestic producers.
Market Restraints
- Fluorspar import dependence:India sources over 90 percent of its calcium fluoride feedstock from China and Mexico, exposing margins to freight volatility and geopolitical supply interruptions.
- Central Pollution Control Board effluent protocols:Stringent calcium fluoride sludge and fluoride ion discharge limits impose capital-intensive wastewater treatment requirements on greenfield capacity.
- Sulfuric acid price cyclicality:The primary reagent for HF synthesis tracks phosphate fertilizer and copper smelter output, creating input cost instability that compresses producer margins during acid supply crunches.
Strategic Opportunities
- Specialty fluorochemical downstream derivatives:Pharmaceutical intermediates and agrochemical actives command premium pricing over commodity refrigerant-grade material, rewarding R&D investment in fluorination chemistry.
- Tamil Nadu semiconductor corridor expansion:The state's emerging electronics manufacturing cluster offers geographic diversification for suppliers seeking to reduce western India concentration risk.
- Modular bulk-supply with on-site storage:Large consumers are negotiating tank-infrastructure partnerships that lock in volume commitments while reducing working capital burdens for producers.
Industry Challenges
- Fluorine-handling technician scarcity:The specialized safety protocols for anhydrous HF transfer and maintenance limit operational scalability, particularly for second-shift and weekend production expansion.
- State environmental clearance timelines:Gujarat and Tamil Nadu pollution control boards are extending scrutiny periods for new HF manufacturing permits, delaying project commissioning by 12-18 months.
- Legacy refrigerant-grade capacity retrofit costs:Existing plants designed for R-22 and R-134a feedstock production require significant furnace and distillation column upgrades to meet semiconductor-grade purity specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Anhydrous Hydrogen Fluoride Market |
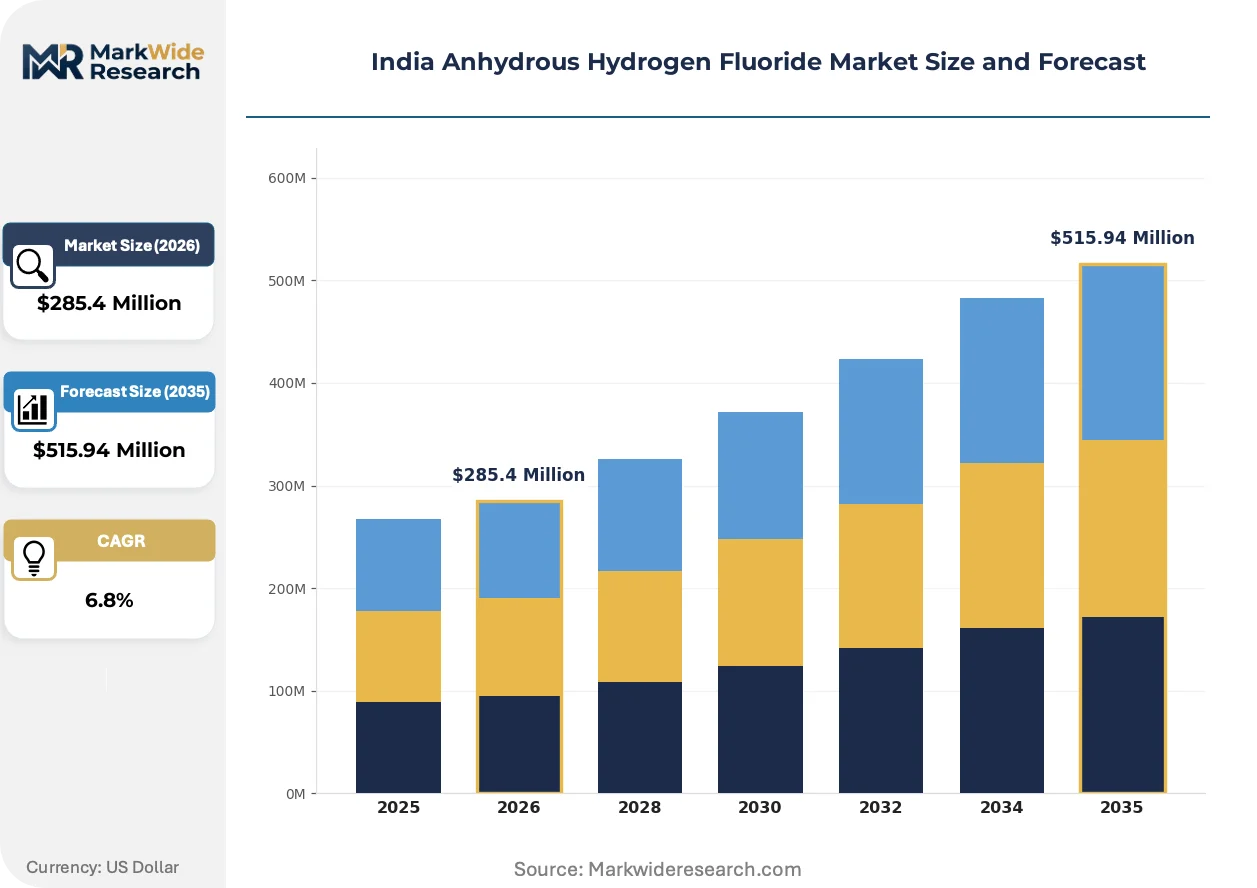
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gaseous, Liquid, Purity 99%, Purity 95% Application: Semiconductors, Refrigerants, Glass Etching, Metal Surface Treatment Industry Vertical: Electronics, Chemical Manufacturing, Pharmaceuticals, Manufacturing End User: OEMs, Tier-1 Suppliers, Distributors, Retailers |
| Companies Covered | Honeywell International Inc., Solvay, Linde plc, Arkema, Lanxess, Navin Fluorine International Limited, Gujarat Fluorochemicals Limited, SRF Limited, Orbia Fluor & Energy Materials, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Anhydrous Hydrogen Fluoride Market Trends and Innovations
Electronics-grade purity requirements are forcing a bifurcation between commodity refrigerant supply and specialty semiconductor feedstock production, with technology investments clustering around etching chemistry rather than legacy cooling applications.
Semiconductor-grade anhydrous hydrogen fluoride distillation systems are expanding into the Gujarat fabrication ecosystem, delivering sub-ppb metal impurity levels essential for advanced node chip manufacturing. Tata Electronics and Micron's planned fabs are specifying direct pipeline connections to on-site purification units, bypassing conventional drum handling entirely. This infrastructure is expanding into merchant supply arrangements as smaller semiconductor component producers seek equivalent purity without capital expenditure.
The BIS certification mandate for industrial chemicals is tightening purity benchmarks, compelling importers to submit batch-specific assay documentation and third-party laboratory verification. Domestic producers with captive testing facilities are accelerating certification timelines, capturing procurement from buyers facing project delays from documentation gaps. Semiconductor and pharmaceutical end-uses are most affected, with several multinational electronics contract manufacturers restricting vendor lists to BIS-certified suppliers exclusively.
Long-term offtake agreements with embedded price collars are displacing spot market transactions for volumes exceeding 500 metric tons annually. Large refrigerant blenders and fluoropolymer manufacturers are negotiating five-year supply contracts with inflation-adjusted price bands, transferring inventory risk to producers. This pattern is most visible in western India, where Dahej-based chemical parks enable pipeline delivery that supports continuous consumption models incompatible with spot procurement logistics.
India Anhydrous Hydrogen Fluoride Market Segmentation
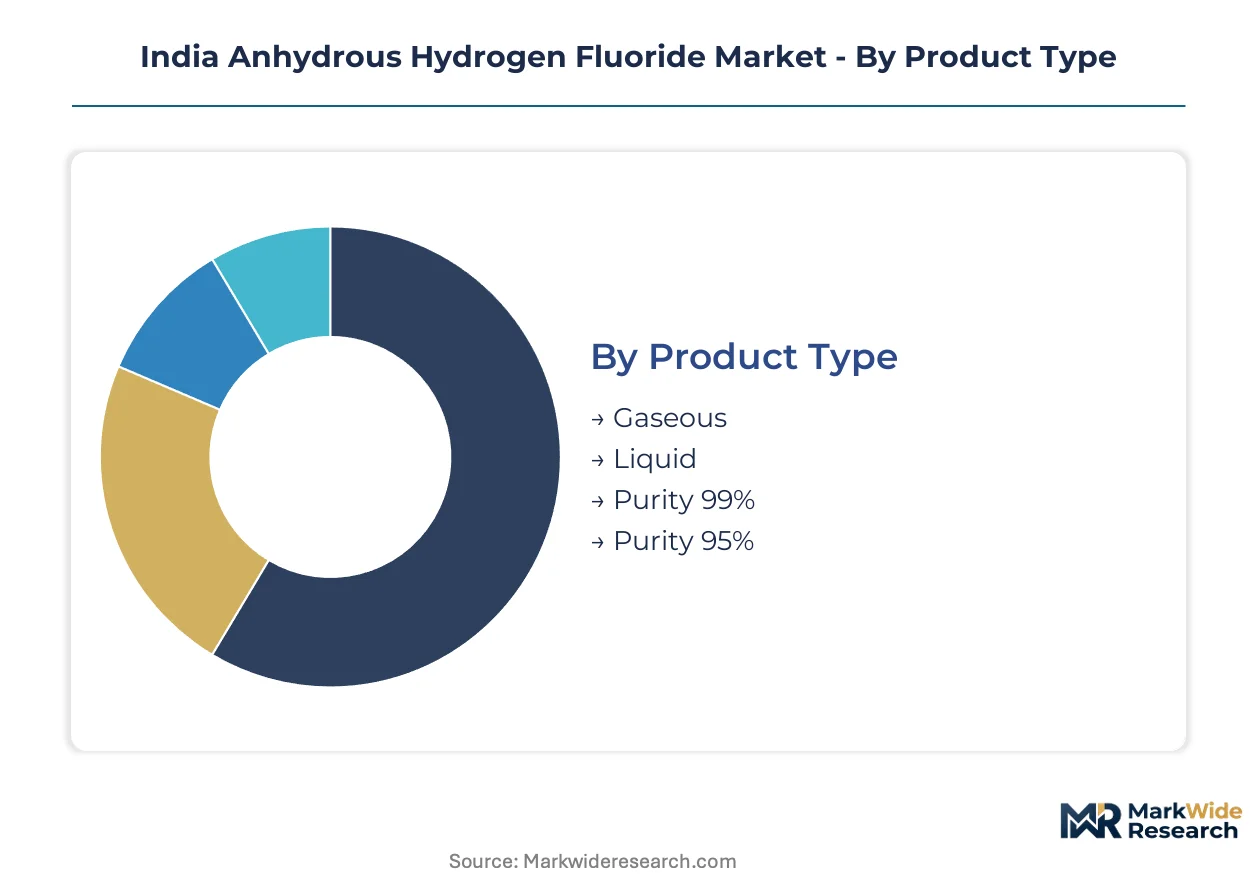
Anhydrous hydrogen fluoride procurement patterns diverge sharply across purity grades and physical forms, with semiconductor-grade specifications commanding fundamentally different supply chain configurations than commodity refrigerant feedstock. Understanding these segment boundaries clarifies where margin pools concentrate and which technical specifications filter supplier eligibility.
Product Type:
Supply concentration around Dahej and Mundra chemical parks favors liquid-form distribution infrastructure, while gaseous supply requires specialized pressure vessel logistics that limit viable supplier pools.
- Liquid:Dominates commercial transactions through established bulk transport infrastructure and safer handling logistics. Dahej-based chemical parks enable pipeline delivery to large refrigerant blenders and fluoropolymer manufacturers, supporting continuous consumption models.
- Gaseous:Requires specialized pressure vessel handling and direct pipeline connections for semiconductor fabs. Tata Electronics and Micron specify on-site purification units with sub-ppb metal impurity delivery, bypassing conventional drum handling entirely.
- Purity 99%:Meets BIS certification mandates for semiconductor and pharmaceutical end-uses, with batch-specific assay documentation filtering sub-scale importers from certified procurement lists.
- Purity 95%:Serves refrigerant synthesis and industrial metal treatment applications where lower specification thresholds reduce production costs and expand viable supplier options.
Today's leader: Liquid. Tomorrow's challenger: Gaseous.
Application:
Cost tier differentiation separates etching-grade semiconductor chemistry from commodity refrigerant feedstock, with purity premiums widening as domestic chip fabrication capacity expands.
- Semiconductors:Fastest-expanding demand pool driven by PLI-subsidized domestic chip fabrication. Gujarat and Tamil Nadu fabs specify direct pipeline connections to on-site purification units, creating infrastructure lock-in for qualified suppliers.
- Refrigerants:Volume leader through R-22 and R-134a feedstock demand from SRF Limited and Gujarat Fluorochemicals captive consumption models. Legacy capacity requires furnace upgrades to meet semiconductor-grade specifications.
- Glass Etching:Serves architectural and automotive glass processing with moderate purity requirements and established drum-based logistics networks.
- Metal Surface Treatment:Industrial applications for stainless steel pickling and aluminum brightening, concentrated in western India manufacturing clusters.
Semiconductors are climbing the fastest; refrigerants still move the most volume.
Industry Vertical:
Margin structure varies dramatically across verticals, with backward-integrated chemical manufacturing capturing value through captive consumption while electronics verticals pay premiums for certified supply security.
- Chemical Manufacturing:Deepest margin pools through captive fluorspar-to-fluorochemical integration. Gujarat Fluorochemicals and Navin Fluorine sustain volume leadership through in-house production of downstream derivatives.
- Electronics:PLI scheme subsidies amplify demand for etching-grade material, with BIS certification timelines creating procurement bottlenecks for projects requiring rapid qualification.
- Pharmaceuticals:Specialty fluorochemical intermediates for active pharmaceutical ingredients command premium pricing over commodity grades, rewarding R&D investment in fluorination chemistry.
- Manufacturing:Broad industrial consumption for metal treatment and general chemical synthesis, price-sensitive and served through distributor networks rather than direct supplier relationships.
Chemical Manufacturing owns the margin; Electronics is gaining share fastest.
End User:
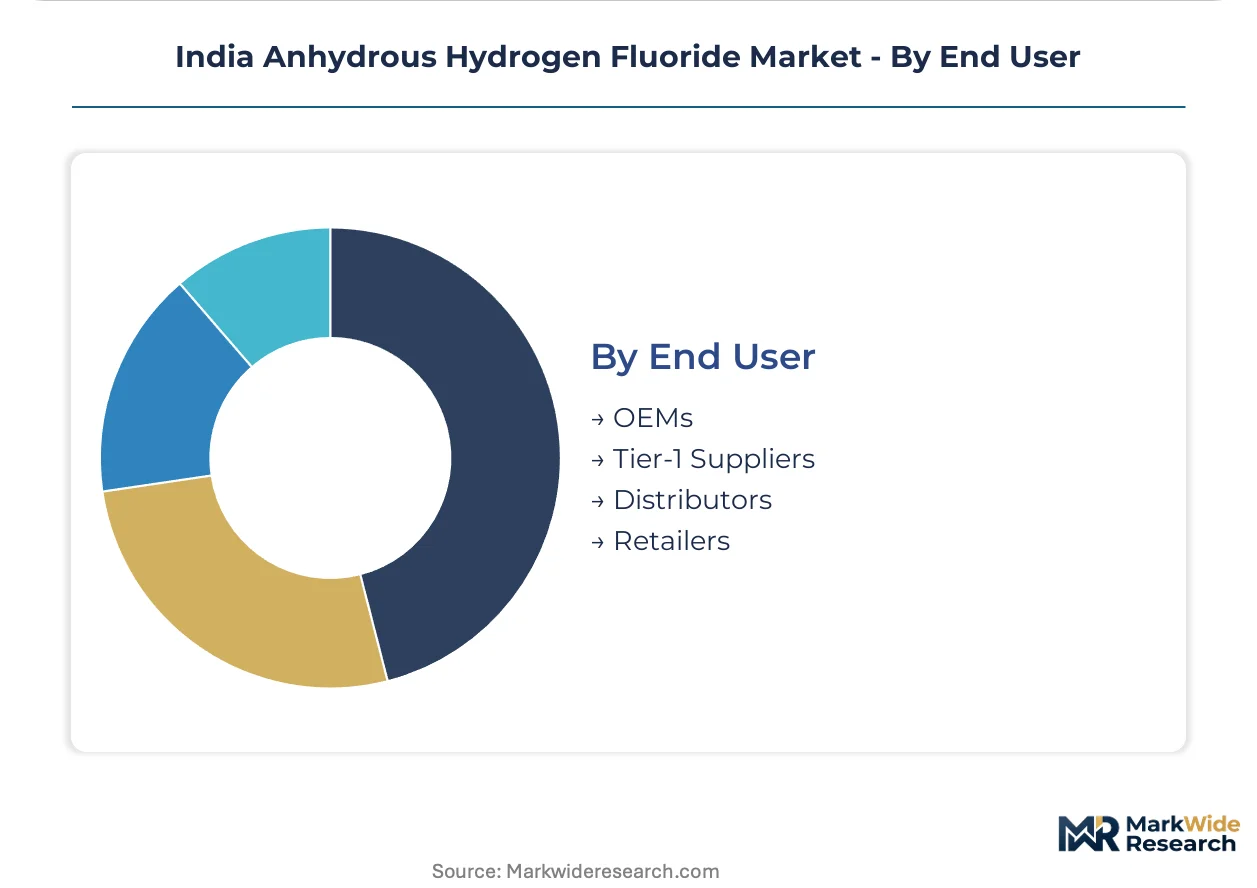
Customer type determines contract structure, with OEMs negotiating long-term offtake agreements while distributors absorb inventory risk for fragmented downstream demand.
- OEMs:Large refrigerant blenders and fluoropolymer manufacturers negotiate five-year supply contracts with inflation-adjusted price bands, transferring inventory risk to producers through embedded price collars.
- Tier-1 Suppliers:Semiconductor component producers seek merchant supply arrangements with equivalent purity to on-site purification, without capital expenditure for dedicated infrastructure.
- Distributors:Serve fragmented pharmaceutical and manufacturing demand through drum-based logistics, capturing margin through technical service and smaller lot flexibility.
- Retailers:Minimal direct participation due to hazardous material handling requirements and BIS certification complexity limiting small-scale market entry.
OEMs set the contract terms; Tier-1 Suppliers are expanding fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fluorochemical production in India traces its industrial lineage to Gujarat's petrochemical corridor expansion in the 1990s, when integrated chemical parks first concentrated sulfuric acid and fluorspar processing capacity. Today regional demand patterns reflect this western India manufacturing gravity while semiconductor investments pull supply chains toward southern and western state clusters.
Gujarat
Dahej and Mundra chemical parks host the densest concentration of anhydrous hydrogen fluoride capacity, with pipeline infrastructure connecting captive producers to refrigerant blenders and fluoropolymer manufacturers. The state's pollution control board enforces effluent discharge protocols that extend environmental clearance timelines for greenfield projects. Tata Electronics' Dholera semiconductor fab is negotiating direct pipeline supply arrangements that bypass conventional drum logistics entirely.
Tamil Nadu
Hosur and Sriperumbudur electronics manufacturing clusters are scaling fluorinated chemistry procurement for semiconductor component fabrication faster than regional supply infrastructure can respond. The state's industrial policy offers capital subsidies for chemical plants locating within 50 kilometers of designated electronics manufacturing zones. Micron Technology's planned assembly and test facility is specifying sub-ppb purity delivery requirements that favor on-site purification partnerships over merchant supply.
Maharashtra
Mumbai-Pune industrial corridor demand concentrates in pharmaceutical intermediate synthesis and specialty fluorochemical derivatives. The state's FDA equivalent regulates active pharmaceutical ingredient manufacturing with batch documentation requirements that filter supplier qualification toward BIS-certified domestic producers. Tarapur chemical estate hosts backward-integrated fluorochemical operations serving agrochemical and pharmaceutical formulators with captive consumption models.
Karnataka
Bengaluru's semiconductor design ecosystem is translating into fabrication demand as the state attracts electronics manufacturing services contractors. The Karnataka Industrial Areas Development Board is allocating land parcels within existing chemical parks for fluorochemical expansion to serve this emerging demand pool. Mysuru and Peenya industrial zones are seeing distributor network expansion for drum-based supply to smaller pharmaceutical and metal treatment end-users.
Telangana
Hyderabad's pharmaceutical manufacturing base consumes fluorinated intermediates for active ingredient synthesis, with demand growing at rates exceeding national averages. The state's life sciences cluster policy provides tax incentives for chemical plants supplying FDA-regulated facilities with documented purity certification. Genome Valley and Pashamylaram industrial areas are attracting specialty fluorochemical investments targeting pharmaceutical contract manufacturing organizations.
India Anhydrous Hydrogen Fluoride Market Competitive Landscape
Premium-margin players sit above commodity-margin players across purity-grade and application-specialization dimensions, with semiconductor-grade certification creating a structural tier that filters out refrigerant-focused competitors. The vendor base clusters around three strategic archetypes: captive-integrated chemical conglomerates with backward fluorspar-to-derivative control, specialty fluorochemical specialists with R&D depth in pharmaceutical and agrochemical intermediates, and global industrial gas distributors leveraging merchant supply infrastructure. Dominant competitive moves include long-term offtake agreements with embedded price collars and modular bulk-supply partnerships with on-site tank infrastructure.
Among India-based producers, Gujarat Fluorochemicals Limited, Navin Fluorine International Limited, and SRF Limited occupy positions across distinct competitive tiers. Gujarat Fluorochemicals exemplifies the captive-integrated archetype through its Dahej complex operations. Navin Fluorine represents specialty downstream derivative focus with pharmaceutical intermediate positioning. SRF anchors volume leadership in domestic distribution through refrigerant-grade expertise. Global participants including Honeywell International Inc., Solvay, and Linde plc compete through merchant supply arrangements and technology licensing rather than indigenous manufacturing presence.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Solvay |
| Linde plc |
| Arkema |
| Lanxess |
| Navin Fluorine International Limited |
| Gujarat Fluorochemicals Limited |
| SRF Limited |
| Orbia Fluor & Energy Materials |
| Others |
Pricing and Supply Chain Analysis
Semiconductor-grade versus refrigerant-grade purity divergence separates premium contract structures from commodity spot transactions, with BIS certification timelines creating procurement bottlenecks that inflate etching-chemistry premiums while legacy refrigerant feedstock trades on volume discounts through Dahej pipeline networks.
Pricing Analysis
Long-term offtake agreements with embedded price collars dominate transactions exceeding 500 metric tons annually, transferring inventory risk to producers through inflation-adjusted bands. Price differentiation rests on BIS certification status and volume scale, with semiconductor fabs paying substantial premiums for sub-ppb metal impurity documentation. Cost compression in refrigerant-grade material intensifies as SRF Limited and Gujarat Fluorochemicals expand captive consumption models. Chemical Manufacturing verticals show least price sensitivity due to backward-integrated margin capture, while fragmented metal treatment end-users resist pass-through of fluorspar cost volatility.
Supply Chain Analysis
BIS certification gating filters supplier eligibility toward domestic producers with captive testing facilities, accelerating procurement timelines for Tata Electronics and Micron while excluding documentation-deficient importers. Supply concentrates in China and Mexico for calcium fluoride feedstock, with India drawing over 90 percent of fluorspar requirements from these sources. Sulfuric acid reagent supply hinges on phosphate fertilizer and copper smelter output cycles. Single-source vulnerability in fluorspar imports exposes margins to freight volatility and geopolitical interruption. Distribution runs through Dahej and Mundra chemical park pipeline infrastructure for large consumers, with drum-based logistics serving smaller pharmaceutical and glass etching end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where semiconductor-grade certification requirements are displacing commodity refrigerant supply, rewarding producers who anchor etching-chemistry capabilities ahead of PLI-subsidized fab commissioning.
For Market Incumbents: Deepen backward integration into fluorspar sourcing through offtake partnerships with Mexican and Chinese miners, reducing exposure to freight volatility that compresses margins during supply crunches. Expand on-site purification infrastructure at Tamil Nadu semiconductor corridors to capture Micron and Tata Electronics pipeline supply arrangements before merchant competitors qualify. Accelerate BIS certification timelines through captive laboratory investment to filter sub-scale importers from procurement lists.
For New Entrants and Emerging Players: The premium-to-economy price gap in pharmaceutical intermediate grades offers white-space entry for fluorination chemistry specialists with R&D depth in agrochemical actives. Target Karnataka and Telangana life sciences clusters where Genome Valley tax incentives reduce capital intensity for FDA-regulated facilities. Pursue modular bulk-supply partnerships with on-site tank infrastructure to lock volume commitments from smaller semiconductor component producers seeking purity without capital expenditure.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialty fluorochemical specialists possessing pharmaceutical intermediate pipelines and BIS-certified testing infrastructure. Long-term viability favors producers who bridge refrigerant-grade legacy capacity toward semiconductor-grade retrofit completion within the projection horizon. Acquisition target archetype: mid-cap fluorochemical operators with underutilized distillation assets in western India chemical parks. Watch for PLI scheme disbursement acceleration as inflection indicator for etching-grade demand pull-through.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorspar Supply | Mexican and Chinese mining offtakes reduce freight volatility exposure for Dahej-based producers. |
| Semiconductor-Grade Distillation Retrofit | Furnace and column upgrades unlock sub-ppb purity delivery for Tata Electronics pipeline contracts. |
| On-Site Purification Partnership | Tank infrastructure at Tamil Nadu fabs transfers inventory risk while locking volume commitments. |
| BIS Certification Acceleration | Captive laboratory investment filters importers and captures procurement from documentation-constrained buyers. |
| Pharmaceutical Intermediate R&D Expansion | Agrochemical and API fluorination chemistry commands premium pricing over commodity refrigerant grades. |
Research Methodology
Direct dialogue with fluorochemical plant managers, procurement leads at refrigerant blenders, semiconductor fab supply chain directors, and BIS certification officials grounded qualitative findings, cross-referenced with customs trade data, CDSCO pharmaceutical filings, SEC 10-K disclosures from global industrial gas distributors, and state pollution control board environmental clearance records. Bottom-up and top-down triangulation validated production capacity estimates against consumption patterns across purity grades.
Bottom-up modeling anchored volume projections to individual fab procurement specifications and chemical park capacity announcements, while top-down analysis traced PLI scheme subsidy disbursement patterns against electronics manufacturing investment flows. Segmentation dimensions included purity tier, physical form, application end-use, and regional production hub concentration. CAGRs were derived from fitted growth curves incorporating fluorspar import volatility, sulfuric acid price cyclicality, and state-level environmental clearance timeline extensions. Industry-specific inputs encompassed semiconductor node migration schedules and refrigerant phase-out regulatory trajectories.
Caveats apply where fluorspar supply interruptions, BIS certification timeline delays, or PLI scheme restructuring could materially shift the outlook for etching-grade demand acceleration. Forecasts reflect assumptions regarding environmental clearance progression and captive feedstock integration economics. A model refresh is warranted upon material change in China-Mexico fluorspar export policy or central subsidy disbursement velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Aerosol Insecticides Market
Chemicals
Malaysia Construction Chemicals Market
Chemicals
Calcium Hydroxide Market
Chemicals
Aluminum Ammonium Sulfate Market
Chemicals
Valeryl Chloride Market
Chemicals
Methyl P-Hydroxybenzoate Market
Chemicals
Negative Photoresist Chemicals Market
Chemicals
Copper Oxychloride Market
Chemicals
India Metal Treatment Chemical Market
Chemicals
Sodium Aluminum Hydride Market
Chemicals
Tetrapotassium Pyrophosphate Market
Chemicals
Ferric Chloride Market
Chemicals
Menadione Market
Chemicals
Paint Stripper Market
Chemicals
Biphenyltetracarboxylic Dianhydride Market
Chemicals
Methidathion (CAS 950-37-8) Market