
 Electrostatic Coalescers Market | 2026-2036
Electrostatic Coalescers Market Size, Share, and Industry Trends Forecast 2026-2036
Electrostatic Coalescers Market Foresight
The gap between engineered vertical systems and basic horizontal units is restructuring how vendors allocate R&D budgets and field-service networks. Schlumberger Limited leverages its integrated oilfield services platform to bundle coalescer deployments with upstream project contracts. Sulzer Ltd anchors its position through specialized separation technology leadership in multi-phase processing applications. Alfa Laval competes by extending its heat-transfer and fluid-handling expertise into compact system designs for offshore platforms.
An electrostatic coalescer applies high-voltage electric fields to destabilize emulsions and accelerate droplet coalescence in hydrocarbon streams, typically operating at field strengths between 0.5 and 5 kV per centimeter to achieve water-in-oil separation efficiencies exceeding 95 percent. Vertical systems dominate capital expenditure in greenfield refinery projects where footprint constraints and gravity-settling optimization drive specification. Horizontal systems retain installed-base density across mature onshore oilfields in North America and Russia where retrofit economics favor vessel replacement over technology migration. Compact systems represent the fastest-growing product configuration as offshore operators prioritize weight reduction and modular installation.
The American Petroleum Institute enforces separation-performance benchmarks that mandate electrostatic treatment for certain heavy crude grades before pipeline transport. EPA discharge regulations for produced water are tightening oil-in-water limits, forcing operators to upgrade primary separation trains with higher-efficiency coalescing technology. Stakeholders must monitor how evolving carbon-intensity disclosure rules from EU regulators and emerging methane-emission frameworks reshape capital allocation between conventional electrostatic systems and alternative separation technologies.
Market Dynamics
The transition from horizontal to vertical electrostatic coalescer configurations is compressing vessel footprints while forcing vendors to rebuild field-service networks around modular, skid-mounted installations rather than conventional stick-built projects.
Growth Catalysts
- EPA discharge mandates:Tightening oil-in-water limits for produced water are compelling upstream operators to retrofit separation trains with higher-efficiency electrostatic treatment before surface discharge or reinjection.
- Heavy oil processing expansion:Saudi Aramco and ADNOC are adding electrostatic dehydration capacity to handle rising volumes of high-viscosity crudes that resist gravity settling alone.
- High-voltage transformer miniaturization:Advances in compact transformer design are reducing energy intensity per barrel treated, improving project economics for marginal field developments.
Market Restraints
- Specialized alloy input costs:Vessel fabrication relies on duplex stainless steels and nickel alloys vulnerable to volatility in Indonesian nickel and South African chromium supply.
- Skilled commissioning engineer scarcity:Electrostatic field calibration and safety interlock programming require technicians with combined high-voltage and hydrocarbon processing expertise that training pipelines have not replenished.
- Membrane filtration substitution:Ceramic and polymeric membrane systems are capturing niche applications in low-salinity produced water treatment where oil droplet sizes permit.
Strategic Opportunities
- Offshore platform electrification:Floating production units in Brazil's pre-salt fields need compact, weight-optimized coalescers that integrate with all-electric processing architectures.
- EU methane regulation alignment:The EU Methane Regulation's monitoring requirements create pull for sealed electrostatic vessels that reduce fugitive emissions compared to open settling tanks.
- Digital twin convergence:Coupling electrostatic coalescers with real-time emulsion characterization sensors and predictive control algorithms opens premium pricing for integrated separation packages.
Industry Challenges
- API 12J certification timelines:Third-party validation of separation performance to American Petroleum Institute standards extends project delivery schedules by four to eight months.
- Legacy control system integration:Brownfield installations must bridge proprietary high-voltage safety protocols with existing SCADA architectures using custom gateway engineering.
- Electrode fouling prediction:Asphaltene and scale deposition on electrode surfaces remains difficult to model, forcing reactive maintenance schedules that disrupt continuous operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrostatic Coalescers Market |
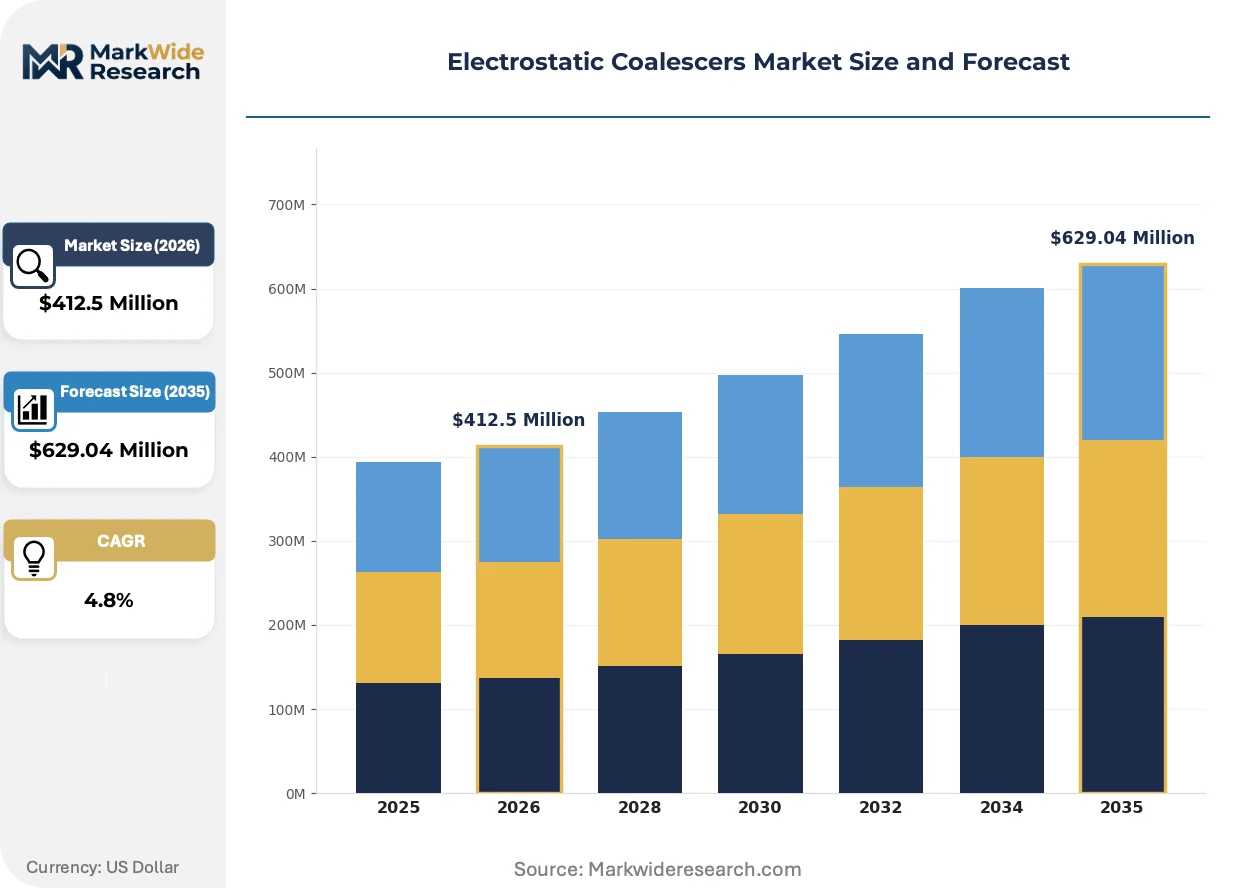
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $629.04 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Systems, Horizontal Systems, Compact Systems, Mobile Units Application: Crude Oil Treatment, Water Treatment, Waste Oil Recycling, Chemical Processing End User: Oil & Gas Industry, Power Generation, Chemical Manufacturing, Environmental Services Technology: Coalescing Plates, Multi-Phase Separators, Diaphragm Pumps, Filtration Systems |
| Companies Covered | Schlumberger Limited, Sulzer Ltd, Alfa Laval, Parker Hannifin Corp, Eaton, Pall Corporation, National Oilwell Varco, TechnipFMC, CECO Environmental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrostatic Coalescers Market Shifts & Advancements
Electrostatic coalescer technology is converging with digital instrumentation and modular construction methods that are compressing project timelines and shifting competitive advantage toward system integrators with software capabilities.
Variable-frequency electrostatic treatment is automating emulsion characterization and field-strength adjustment in real time. Offshore operators in the North Sea are deploying these systems to handle fluctuating water cuts without manual recalibration. The technology is automating the separation optimization loop that previously required dedicated process engineers on each platform.
REACH restrictions on per- and polyfluoroalkyl substances are phasing out certain fluoropolymer electrode coatings used for corrosion resistance. Equipment fabricators are qualifying ceramic and glass-lined alternatives that maintain dielectric performance without restricted chemistries. European refinery projects now specify PFAS-free electrostatic coalescers to preempt regulatory liability.
Lease operators in the Permian Basin are unbundling coalescer maintenance from original equipment contracts, awarding multi-year service agreements to third-party specialists with regional inventory positions. This disintermediation of vendor-captive service is compressing aftermarket margins for integrated oilfield services firms while expanding addressable market for independent maintenance providers.
Electrostatic Coalescers Market Segmentation
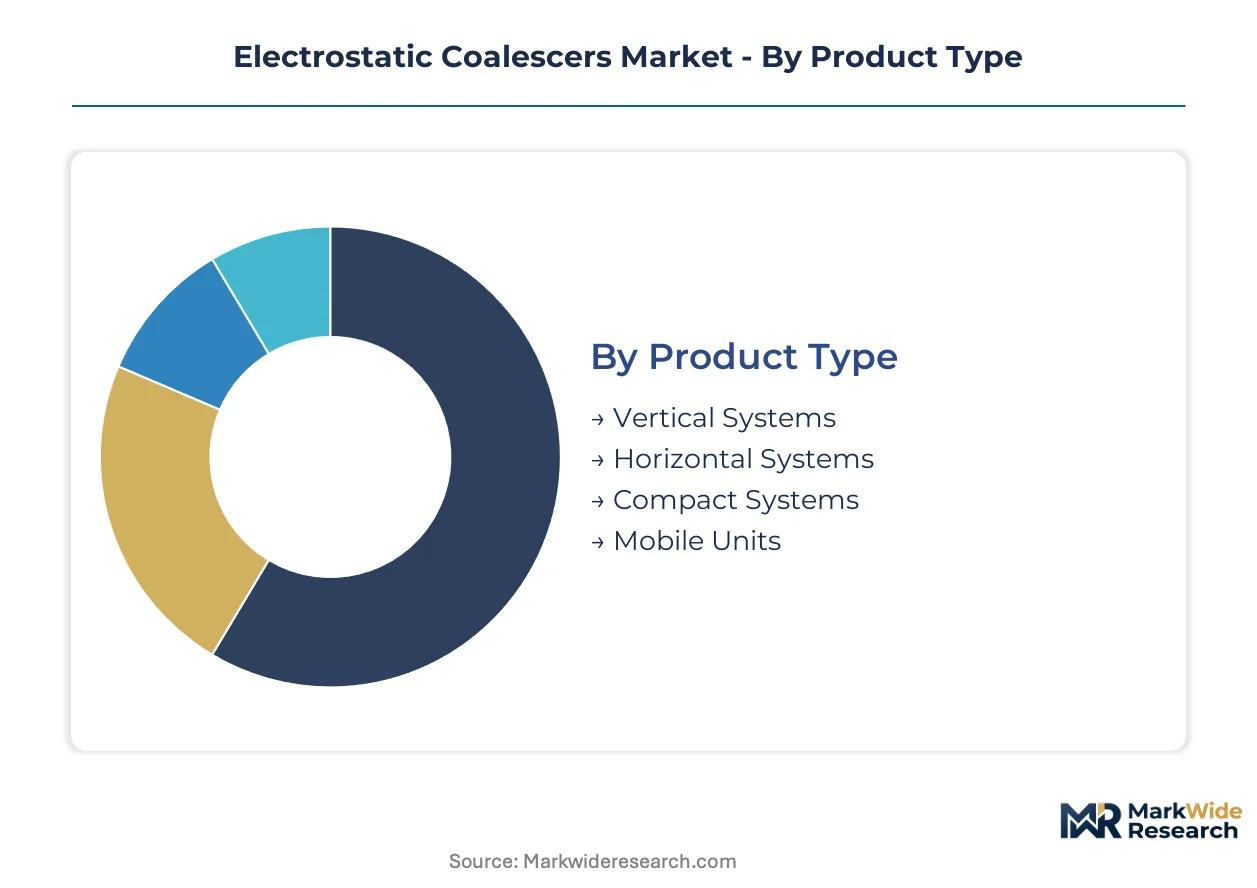
Segmentation in electrostatic coalescers reflects divergent engineering priorities between footprint-constrained offshore installations and cost-sensitive onshore retrofits. Vendors configure product portfolios around voltage transformer specifications, vessel geometry, and integration complexity rather than commodity hardware differentiation.
Product Type:
Supply concentration clusters around vertical system fabricators with integrated high-voltage transformer capabilities, while horizontal vessel specialists compete on replacement-cycle timing and regional service density.
- Vertical Systems:Tall cylindrical vessels optimize gravity settling through staged electrode zones, achieving separation efficiencies above 95 percent at field strengths of 2-5 kV per centimeter. Greenfield refinery projects in Saudi Arabia and the United Arab Emirates specify these units where plot space commands premium valuations and API 12J certification is mandatory.
- Horizontal Systems:Low-profile vessels with extended residence times dominate mature onshore oilfields across North America and Russia where retrofit economics favor vessel replacement over technology migration. These units retain installed-base density through simpler electrode maintenance access and lower structural foundation requirements.
- Compact Systems:Skid-mounted configurations with miniaturized transformers serve offshore platforms in Brazil's pre-salt fields where weight reduction and helicopter-lift installation constrain procurement decisions.
- Mobile Units:Trailer-deployed electrostatic treatment addresses temporary processing needs in Permian Basin lease operations and Canadian oil sands projects with shifting wellhead locations.
Horizontal systems absorb the bulk of installed capacity; compact systems are expanding most quickly.
Application:
Application demand distributes according to produced water discharge regulations and heavy crude processing economics, with water treatment emerging as a compliance-driven revenue line distinct from hydrocarbon recovery optimization.
- Crude Oil Treatment:Dehydration of water-in-oil emulsions upstream of pipeline transport or refining, mandated by API standards for crudes above specific viscosity and density thresholds. Saudi Aramco and ADNOC expansion projects concentrate procurement volume here.
- Water Treatment:Polishing of produced water to meet EPA oil-in-water discharge limits or reinjection specifications, with tightening regulatory thresholds in the US Gulf Coast and North Sea forcing technology upgrades.
- Waste Oil Recycling:Re-refining of used lubricants and industrial oils where electrostatic destabilization precedes vacuum distillation, concentrated in European circular-economy compliance frameworks.
- Chemical Processing:Solvent recovery and emulsion breaking in specialty chemical manufacturing, a niche application with project-specific engineering requirements.
Crude oil treatment commands the dominant share of capital expenditure; water treatment is climbing the fastest as discharge standards tighten.
End User:
End-user procurement patterns separate between integrated operators with captive engineering capabilities and independent service companies purchasing treatment-as-a-service.
- Oil & Gas Industry:Upstream operators, midstream pipeline companies, and refiners represent the core demand base, with national oil companies in Kuwait and Qatar driving large-tender activity.
- Power Generation:Fuel oil conditioning for combustion turbines and diesel engines, a steady but lower-growth segment tied to plant commissioning cycles.
- Chemical Manufacturing:Process stream purification in petrochemical complexes, with demand tracking ethylene cracker and aromatics plant investments.
- Environmental Services:Remediation contractors and waste management firms deploying mobile units for spill response and tank cleaning operations.
Oil and gas operators absorb the bulk of installed capacity; environmental services is expanding most quickly through unbundled maintenance contracts.
Technology:
Technology segmentation reflects convergence between electrostatic treatment and complementary mechanical separation stages, with vendors bundling multi-component packages to defend margin position.
- Coalescing Plates:Parallel-plate interceptors that enhance droplet collision frequency through controlled flow geometry, often integrated upstream of electrostatic zones to reduce power demand.
- Multi-Phase Separators:Combined gravity, electrostatic, and sometimes centrifugal treatment in single vessels, specified for offshore platforms where equipment count directly impacts topside weight.
- Diaphragm Pumps:Emulsion transfer and pressure boosting systems with materials compatibility for high-salinity produced water, a peripheral technology category with limited standalone market presence.
- Filtration Systems:Post-coalescer polishing stages addressing residual solids and stabilized emulsions, increasingly specified where membrane substitution threatens electrostatic market share.
Multi-phase separators absorb the bulk of installed capacity; coalescing plates are expanding most quickly through retrofit bundling strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jubail Industrial City anchors electrostatic coalescer procurement volume through Saudi Aramco's heavy oil expansion programs. National oil companies across the Middle East are mandating API 12J certified dehydration systems for new upstream capacity.
Saudi Arabia
Jafurah unconventional gas developments and Marjan offshore upgrades drive vertical system demand. The Saudi Standards, Metrology and Quality Organization enforces SASO certification for pressure vessel imports. Eastern Province fabrication yards in Jubail and Ras Al-Khair concentrate vessel assembly for domestic and export contracts.
United Arab Emirates
ADNOC's Lower Zakum and Umm Shaif field expansions specify compact electrostatic treatment packages. MOHAP oversees equipment safety compliance for offshore installations. Dubai's Jebel Ali Free Zone hosts service centers supporting modular system integration for pre-salt export markets.
United States
Permian Basin lease operators retrofit horizontal vessels to meet EPA Region 6 produced water discharge limits. The Environmental Protection Agency enforces oil-in-water thresholds under the Clean Water Act National Pollutant Discharge Elimination System. Houston's Energy Corridor houses engineering offices coordinating Gulf Coast refinery upgrade projects.
Brazil
Petrobras pre-salt floating production units demand weight-optimized compact coalescers for Búzios and Mero fields. ANP regulatory frameworks mandate separation performance verification for deepwater production systems. Rio de Janeiro's Cidade do Petróleo technology cluster concentrates vendor engineering support for offshore procurement.
Norway
Johan Sverdrup phase 2 and Arctic field developments prioritize sealed electrostatic vessels reducing methane fugitive emissions. The Norwegian Environment Agency implements OSPAR discharge guidelines for North Sea operations. Stavanger's Forus industrial park hosts separation technology specialists serving Equinor and Aker BP projects.
Electrostatic Coalescers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across high-voltage transformer integration and field-service network density. The market structure consolidates around integrated oilfield services firms with captive project pipelines and specialized separation technology houses with modular fabrication capabilities. Two strategic archetypes dominate: full-service platform bundlers and component-specialist fabricators. Competitive moves center on API 12J certification pre-qualification programs and regional inventory positioning for aftermarket service capture.
Among integrated oilfield services providers, Schlumberger Limited and TechnipFMC occupy positions spanning project engineering through commissioning support. Sulzer Ltd exemplifies the specialized separation technology archetype with concentrated expertise in multi-phase processing applications. These three companies represent distinct competitive vectors: bundled upstream contracts, modular offshore systems, and precision separation engineering.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Sulzer Ltd |
| Alfa Laval |
| Parker Hannifin Corp |
| Eaton |
| Pall Corporation |
| National Oilwell Varco |
| TechnipFMC |
| CECO Environmental |
| Others |
Supply & Pricing Matrix
London Metal Exchange nickel futures volatility cascades through electrostatic coalescer supply chains, compressing margins for duplex stainless steel fabricators and forcing tiered pricing stratification across API-certified premium systems, standard industrial units, and economy-grade retrofit vessels.
Pricing Analysis
Throughput-based pricing anchors electrostatic coalescer contracts, with operators paying per-barrel treatment fees tied to dehydration efficiency guarantees rather than capital equipment ownership. Three-tier pricing structure across premium, standard, and economy levels reflects API 12J certification status, high-voltage transformer integration depth, and bundled aftermarket service intensity. Cost compression in economy-grade horizontal vessels is intensifying because Permian Basin lease operators unbundle maintenance from original equipment contracts. National oil companies in Saudi Arabia and the United Arab Emirates exhibit the lowest price sensitivity, prioritizing uptime guarantees and field-service network density over unit capital cost.
Supply Chain Analysis
Dual-sourcing requirements from ADNOC and Saudi Aramco procurement mandates force fabricators to qualify secondary transformer suppliers alongside primary high-voltage component vendors, lengthening vendor onboarding cycles. Manufacturing concentrates in Germany, South Korea, and the United States for precision transformer windings, while vessel fabrication clusters in Saudi Arabia, the United Arab Emirates, and Singapore. Duplex stainless steel plate, nickel alloy electrodes, and ceramic insulator assemblies constitute critical input dependencies. Single-source vulnerability sits with Indonesian nickel supply exposed to export restriction volatility. Distribution runs through oilfield services integrators and direct national oil company tenders, with regional inventory positioning determining aftermarket service capture rates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrostatic coalescer markets operate under supply-constrained conditions where skilled commissioning engineer scarcity props pricing power for vendors with captive training pipelines and established field-service networks.
For Market Incumbents: Deepen backward integration into high-voltage transformer manufacturing to insulate margin structures from nickel alloy price volatility and secure component availability for large-tender fulfillment. Expand API 12J certification pre-qualification programs ahead of regulatory tightening in Middle Eastern national oil company procurement frameworks. Prioritize digital twin convergence investments to defend against membrane filtration substitution threats in produced water treatment applications. For New Entrants and Emerging Players: The premium-to-economy price-point gap in compact offshore systems creates white-space opportunity for modular fabricators with weight-optimized vessel designs targeting Brazil's pre-salt floating production units. Target environmental services contractors in North America with mobile unit lease models that bypass capital-intensive original equipment manufacturing. Pursue unbundled maintenance contract capture in the Permian Basin through regional inventory positioning and rapid-response field engineering networks. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized separation technology houses with modular fabrication capabilities in Singapore and the United Arab Emirates, where national oil company tender pipelines provide revenue visibility through macroeconomic volatility. Long-term viability hinges on software-integrated system architectures that command premium pricing through predictive maintenance and real-time emulsion characterization. Watch electrode fouling prediction algorithm development as the inflection signal separating commodity hardware vendors from system integrators with recurring revenue streams.| Strategic Initiative | Industry Significance |
|---|---|
| API 12J Certification Pre-Qualification | Saudi Aramco and ADNOC procurement mandates require third-party validation, extending project timelines by four to eight months. |
| High-Voltage Transformer Backward Integration | In-house manufacturing of compact transformer designs reduces energy intensity exposure and secures supply for large-tender fulfillment. |
| Digital Twin Platform Development | Real-time emulsion characterization sensors coupled with predictive control algorithms open premium pricing for integrated separation packages. |
| Regional Service Network Expansion | Jebel Ali Free Zone and Houston Energy Corridor inventory positioning captures unbundled maintenance contracts from Permian Basin operators. |
| PFAS-Free Electrode Coating Qualification | REACH restrictions on fluoropolymer coatings force ceramic and glass-lined alternative validation for European refinery project eligibility. |
Research Methodology
Document review covered American Petroleum Institute standards filings, EPA discharge regulation dockets, and national oil company tender documentation, complemented by interviews with upstream project engineers, high-voltage equipment procurement managers, and aftermarket service directors. Secondary validation drew from customs trade data, SEC 10-K equipment segment disclosures, and offshore project development databases. Bottom-up unit deployment estimates triangulated against top-down capital expenditure allocations across the analysis window.
Segmentation outputs reflect product type, application, end user, and technology dimensions modeled through the projection horizon. CAGRs derived from regression analysis against crude oil production forecasts, heavy oil processing capacity additions, and regulatory compliance timeline assumptions. Industry-specific inputs included API 12J certification pipeline tracking, high-voltage transformer miniaturization adoption curves, and membrane filtration substitution threat assessments.
Inputs from national oil company procurement officers and separation technology vendors were available through the study window; gaps in real-time electrode fouling performance data introduce uncertainty bands around maintenance cost assumptions. Deviation in EPA oil-in-water discharge limit enforcement or EU methane regulation implementation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Glycol Pumps Market
Pumps and Control Devices
Fine Bubble Diffusers Market
Pumps and Control Devices
Jetting Pumps Market
Pumps and Control Devices
Global Piston Pumps Market
Pumps and Control Devices
Vertical Inline Pumps Market
Pumps and Control Devices
United States Subsea Pumps Market
Pumps and Control Devices
Suction Pump Market
Pumps and Control Devices
Vertical Immersion Pumps Market
Pumps and Control Devices
Latin America Pumps Market
Pumps and Control Devices
Solar Fountain Pumps Market
Pumps and Control Devices
End Suction Pump Market
Pumps and Control Devices
Global Submersible Pumps Market
Pumps and Control Devices
Global Diaphragm Pump Market
Pumps and Control Devices
Europe Asia Submerged Pump Market
Pumps and Control Devices
Rotating Equipment Market
Pumps and Control Devices
Mixed Flow Pump Market