
 Shipboard Incineration Market | 2026-2036
Shipboard Incineration Market Size, Share, and Industry Trends Forecast 2026-2036
Shipboard Incineration Market Intelligence
A capability gap between integrated waste-to-energy systems and standalone incinerators is rotating competitive dynamics. Wärtsilä Corporation leverages its extensive marine technology portfolio to offer comprehensive environmental compliance packages. In contrast, Alfa Laval specializes in high-efficiency thermal processing units that integrate with other onboard systems. Niche suppliers such as TeamTec AS sustain market presence by providing compact, reliable incinerators tailored for offshore support vessels and smaller commercial ships.
Shipboard incineration is a controlled combustion process designed to thermally treat solid and liquid waste generated during a vessel's operation. These systems must achieve high combustion efficiency to minimize harmful emissions and comply with strict international standards for air pollution. The solid waste disposal application accounts for the largest share of deployments, serving the needs of commercial vessels. Within technology, thermal oxidation remains the standard, while continuous incinerators are favored for large passenger ferries and cruise ships due to their high throughput capacity.
The International Maritime Organization's MARPOL Convention, particularly Annex V and VI, establishes the foundational rules for onboard waste management and air emissions. In specific jurisdictions, regulations like the US EPA's Vessel General Permit and the EU's Port Reception Facilities Directive impose additional compliance requirements. These regulatory pressures directly influence incinerator design and operational parameters. Stakeholders must now evaluate the viability of next-generation technologies like gasification to meet anticipated zero-emission port standards.
Market Dynamics
Stringent maritime environmental regulations, particularly from the International Maritime Organization, are the central force compelling investment in advanced shipboard incineration systems, moving the market beyond simple waste disposal to integrated emissions compliance and energy recovery.
Growth Catalysts
- Stricter IMO Regulations:The enforcement of MARPOL Annex VI, which sets limits on sulphur oxides and nitrogen oxides, necessitates the adoption of high-efficiency incinerators on newbuilds and existing vessels.
- Fleet Expansion:Demand from growing commercial vessel segments, especially container ships and LNG carriers, directly fuels new incinerator installations as part of standard vessel outfitting.
- Shipbuilding Concentration:Global shipbuilding's concentration in South Korean and Chinese yards streamlines the integration of compliant waste management systems.
Market Restraints
- High Capital Outlay:The significant upfront investment required for advanced thermal oxidation systems, especially those with energy recovery, deters adoption among smaller, budget-conscious shipowners.
- Alternative Waste Management:The availability of port reception facilities and the use of onboard compactors and shredders for non-hazardous waste present viable substitutes for incineration.
- Onboard System Constraints:Limited space and available power on smaller vessels, such as offshore support vessels, restrict the feasibility of installing larger, more efficient incinerator units.
Strategic Opportunities
- Waste-to-Energy Integration:Developing incinerators that connect with steam generation or other energy recovery systems provides a clear value proposition by reducing vessel fuel consumption.
- Retrofit Market for Existing Fleets:A large global fleet of older vessels requires upgrades to meet new environmental mandates, creating a substantial market for retrofitting modern incinerators.
- Next-Generation Technology:Anticipated zero-emission port standards create an opening for gasification and pyrolysis systems that offer superior emissions profiles compared to conventional incineration.
Industry Challenges
- System Integration Complexity:Integrating new incinerators with a vessel’s existing automation, control, and power management systems requires specialized engineering expertise and extensive commissioning time.
- Crew Training and Skill Gaps:The operation and maintenance of sophisticated, electronically controlled incinerators demand a higher level of crew competency than legacy manual systems.
- Variable Regional Enforcement:Navigating inconsistent enforcement of regulations like the US EPA's Vessel General Permit and local port rules creates compliance uncertainty for global operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shipboard Incineration Market |
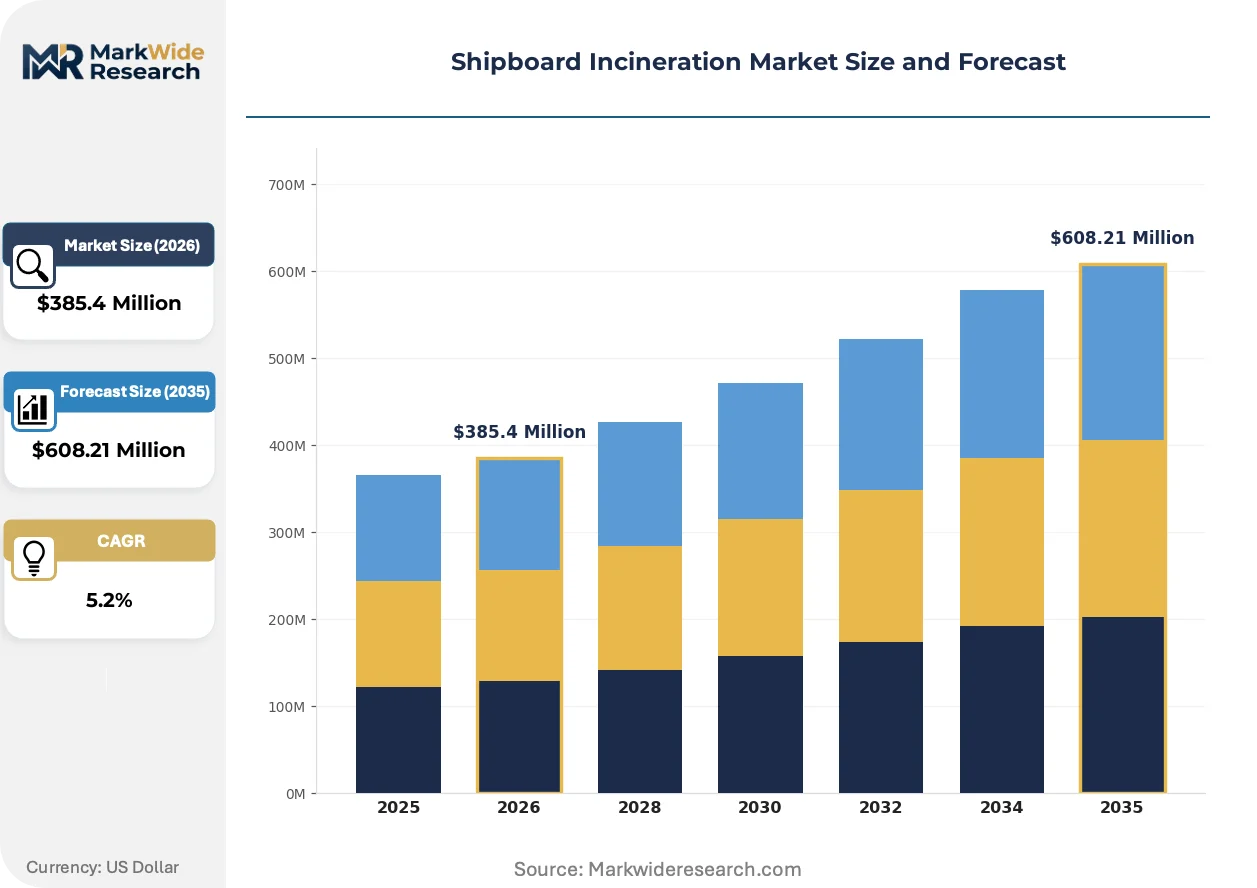
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $608.21 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Incinerators, Continuous Incinerators, Rotary Kiln Incinerators, Fluidized Bed Incinerators Technology: Thermal Oxidation, Gasification, Pyrolysis, Plasma Arc Application: Solid Waste Disposal, Sewage Treatment, Medical Waste Management, Hazardous Waste Processing End User: Commercial Vessels, Military Ships, Offshore Support Vessels, Passenger Ferries |
| Companies Covered | Wärtsilä Corporation, Atlas Incinerators A/S, TeamTec AS, Evac Group, Alfa Laval, Scanship Environmental AS, Hanshin Marine Equipment Co., Ltd., INCINER8 Limited, DETEGASA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shipboard Incineration Market Strategic Shifts & Innovations
A fundamental shift is underway as shipboard incinerators evolve from standalone disposal units into integrated components of a vessel's total environmental and energy management strategy. This evolution is driven by technological convergence and new operational paradigms.
Thermal oxidation paired with advanced flue gas cleaning is the leading technology. These systems capture and neutralize harmful pollutants before atmospheric release. Cruise and large container ship segments are primary adopters, seeking to exceed baseline compliance. This integrated approach is supplanting standalone incinerators unable to meet stricter emission limits.
The European Union's Port Reception Facilities Directive influences equipment selection by promoting onboard waste reduction. This policy incentivizes incinerators with higher thermal efficiency to minimize disposal fees in EU ports. Passenger ferries and container ships on European trade routes are most affected, prioritizing compact, automated systems.
Ship operators are procuring complete environmental compliance packages, not just individual hardware. This disrupts the traditional sales model, favoring suppliers who can bundle incinerators with monitoring services. The trend is most pronounced in newbuild specifications for LNG carriers and large vessels from Asian shipyards.
Shipboard Incineration Market Segmentation
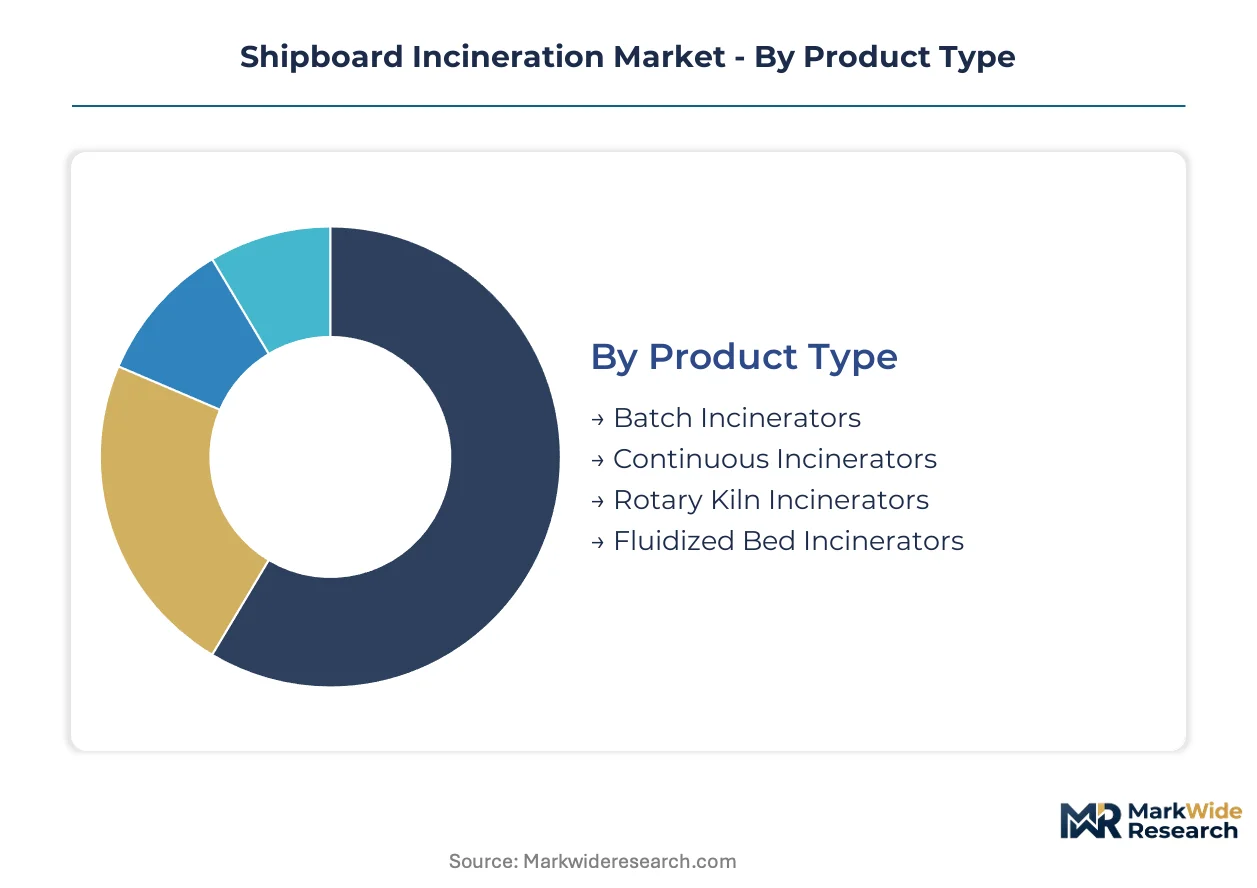
The Shipboard Incineration Market segmentation provides a granular view of how distinct product types, technologies, applications, and end-users shape demand dynamics. Understanding these segments is crucial for manufacturers to align product development with specific vessel requirements and evolving environmental mandates.
Product Type:
Product Type segmentation highlights how evolving waste management needs create substitution pressure across different incinerator designs.
- Continuous Incinerators:These systems are designed for high throughput and uninterrupted operation, processing large volumes of waste efficiently. Demand concentrates from large passenger ferries and cruise ships, driven by their extensive waste generation and need for constant disposal.
- Batch Incinerators:Operating on a start-stop cycle, these units process waste in discrete loads, offering flexibility for varied waste volumes. Demand from smaller commercial vessels and offshore support vessels is significant due to their compact size and suitability for intermittent waste disposal.
- Rotary Kiln Incinerators:Specialized for processing diverse and often challenging waste streams, including sludges and some hazardous materials, through a rotating combustion chamber.
- Fluidized Bed Incinerators:These systems use a bed of inert material, fluidized by air, to achieve highly efficient and uniform combustion, often for specific waste types.
Batch Incinerators anchor the volume base while Continuous Incinerators gain share at the steepest rate.
Technology:
Technology segmentation reflects varying investment levels and operational complexities for onboard waste processing.
- Thermal Oxidation:This mature technology involves the high-temperature combustion of waste, effectively reducing its volume and neutralizing pollutants. Demand from commercial vessels remains strong, driven by its proven reliability and ability to meet current emissions standards.
- Gasification:An advanced process converting waste into a synthetic gas (syngas) through controlled heating in a low-oxygen environment, enabling potential energy recovery. Demand from next-generation LNG carriers and cruise ships is emerging, seeking lower emissions and integrated waste-to-energy solutions.
- Pyrolysis:This technology thermally decomposes organic materials in the absence of oxygen, yielding liquid oil, char, and gases for potential energy utilization.
- Plasma Arc:Utilizing extremely high temperatures generated by plasma torches, this technology breaks down waste into its elemental components, offering superior destruction capabilities for complex waste.
Thermal Oxidation represents a mature technology base, while Gasification exhibits significant innovation potential.
Application:
Application segmentation illustrates the diverse waste streams managed by shipboard incinerators, influencing system capacity.
- Solid Waste Disposal:This application focuses on the incineration of general refuse, food waste, packaging materials, and other non-hazardous solids generated during vessel operations. Demand from all types of commercial vessels is universal, driven by strict MARPOL Annex V regulations for waste discharge.
- Sewage Treatment:This segment involves the incineration of sludge generated from onboard sewage treatment plants, reducing volume and ensuring hygienic disposal. Demand from passenger vessels and large commercial ships is crucial for comprehensive waste management and regulatory compliance.
- Medical Waste Management:Specialized incinerators handle infectious and clinical waste generated on vessels with medical facilities, such as cruise ships or hospital ships.
- Hazardous Waste Processing:This niche application addresses the disposal of specific controlled substances, chemical residues, or other hazardous materials, requiring high-temperature destruction.
Solid Waste Disposal remains the universal application for shipboard incinerators, with Medical Waste Management serving specialized vessel operations.
End User:
End User segmentation reveals how specific vessel types drive demand based on operational profiles and regulatory compliance needs.
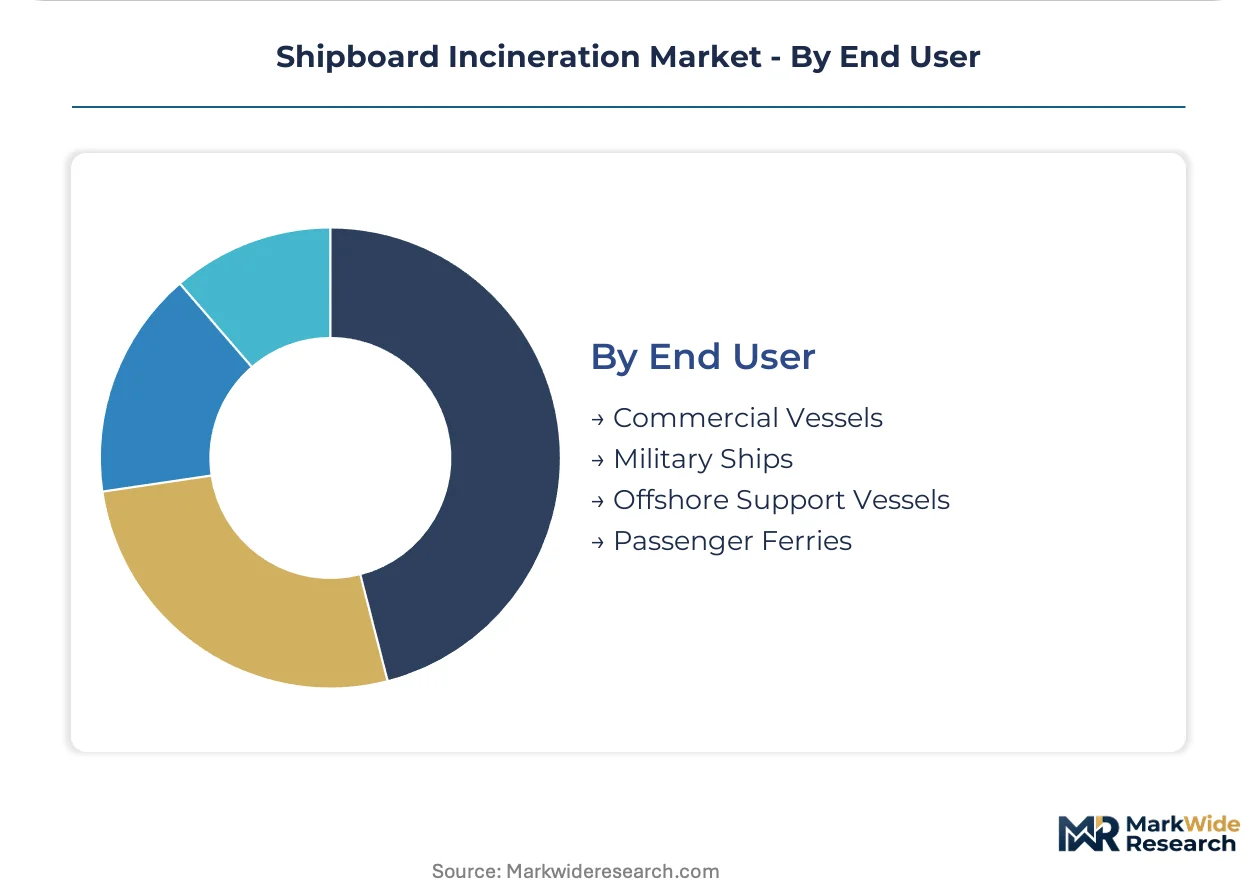
- Commercial Vessels:This broad category includes container ships, bulk carriers, tankers, and general cargo ships, requiring robust incinerators for routine waste management. Demand from global trade expansion and the outfitting of newbuilds in South Korean and Chinese shipyards is substantial.
- Passenger Ferries:These vessels generate high volumes of diverse waste, necessitating continuous and high-capacity incinerators with advanced emission controls. Demand is particularly strong on European trade routes due to stringent EU Port Reception Facilities Directive requirements.
- Military Ships:These vessels require secure, reliable, and often compact waste disposal systems to support extended deployments and maintain operational autonomy.
- Offshore Support Vessels:Operating in remote locations, these vessels need self-sufficient and compact waste management solutions due to limited access to port reception facilities.
Commercial Vessels hold the largest market share for incinerator deployments, while Passenger Ferries exhibit a distinct demand for high-capacity units.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for shipboard incineration systems exhibits asymmetry, with Asian shipbuilding hubs often dictating terms for new installations while European demand prioritizes advanced environmental compliance. This dynamic influences technology adoption and market growth across different maritime regions. Strict international regulations drive investment in high-efficiency incinerators globally.
South Korea
South Korea's shipyards drive substantial demand for shipboard incinerators, particularly for newbuild LNG carriers and large container ships. MARPOL Annex VI compliance mandates advanced waste management systems on these vessels. Shipbuilding hubs in Ulsan, Geoje, and Mokpo integrate these systems during vessel construction.
China
Chinese shipyards represent a significant market for shipboard incinerator installations due to their high volume of new commercial vessel construction. National environmental standards, alongside MARPOL Annex VI, necessitate efficient waste treatment solutions. Major shipbuilding centers in Shanghai, Dalian, and Guangzhou are focal points for these installations.
United States
United States demand stems from both new vessel requirements and the retrofit market for its extensive domestic fleet. The US EPA's Vessel General Permit imposes specific environmental compliance requirements for vessels operating in American waters. Maritime operators in the Gulf Coast and Great Lakes regions frequently upgrade their onboard waste management systems.
Germany
German demand emphasizes high-capacity, continuous incinerators for its advanced passenger ferries and cruise ships. The EU's Port Reception Facilities Directive influences equipment selection, promoting onboard waste reduction. Shipyards in Hamburg, Rostock, and Papenburg specialize in integrating sophisticated waste-to-energy systems.
Japan
Japanese shipowners prioritize modern shipboard incinerators for fleet modernization and enhanced operational efficiency. National maritime environmental policies, complementing MARPOL Annex VI, encourage the adoption of advanced waste treatment technologies. Major shipyards in Imabari, Nagasaki, and Kure are key integrators of these systems.
Shipboard Incineration Market Key Industry Players
Concentration sits with established marine technology providers offering comprehensive environmental compliance packages. The market exhibits a tiered structure, ranging from integrated system suppliers to niche component manufacturers. Large players pursue portfolio diversification and strategic partnerships to broaden their market reach across different vessel segments. Smaller specialists often focus on compact, reliable units tailored for specific vessel types, carving out distinct competitive positioning within their chosen niches.
From the provided list, Wärtsilä Corporation represents a global marine technology provider, offering extensive environmental compliance packages that leverage its broad marine technology portfolio to address diverse marine waste management needs. Alfa Laval, a Swedish company, exemplifies specialization in high-efficiency thermal processing units designed to integrate seamlessly with other onboard systems, focusing on optimal thermal performance. TeamTec AS, a Norwegian firm, anchors the niche segment by providing compact, reliable incinerators specifically tailored for offshore support vessels and smaller commercial ships, sustaining market presence through focused product offerings and robust design. This differentiation highlights the capability gap between integrated waste-to-energy solutions and standalone incinerators, influencing competitive dynamics.
| Leading Market Players |
|---|
| Wärtsilä Corporation |
| Atlas Incinerators A/S |
| TeamTec AS |
| Evac Group |
| Alfa Laval |
| Scanship Environmental AS |
| Hanshin Marine Equipment Co., Ltd. |
| INCINER8 Limited |
| DETEGASA |
| Others |
Cost & Logistics Intelligence
Scale economies in incinerator manufacturing and integration shape both supply concentration and a competitive price floor for standard units. This dynamic influences market entry and product differentiation across vessel segments.
Pricing Analysis
Configured-to-order pricing for integrated waste-to-energy systems commands a premium over standard standalone incinerators. Price differentiation stems from customization levels for specific vessel types and the inclusion of advanced flue gas cleaning. Pricing softness reflects the high capital outlay for advanced systems, especially for budget-conscious smaller shipowners. Commercial vessels and offshore support vessels exhibit higher price sensitivity than large cruise lines.
Supply Chain Analysis
Critical system integration expertise for advanced incinerators, often concentrated in South Korea and China, underpins the supply chain. Key component dependencies include specialized high-temperature alloys for combustion chambers and advanced sensor arrays for emissions monitoring. Single-source vulnerability for proprietary control software presents a structural risk. Distribution runs through direct sales channels to shipyards and large vessel operators, often bundled with broader environmental compliance packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents an early-cycle expansion story, driven by the increasing penetration of advanced waste-to-energy systems on newbuilds and retrofits.
For Market Incumbents: Fortify core market share in thermal oxidation by investing in modular designs that simplify integration with existing vessel systems. Diversify into gasification and pyrolysis technologies to address anticipated zero-emission port standards, mitigating the threat from next-generation technologies. Leverage existing relationships with major shipyards in South Korea and China to offer comprehensive compliance packages.
For New Entrants and Emerging Players: Lead with specialized, compact incinerator solutions tailored for the underserved offshore support vessel segment, where space and power are constraints. Target the retrofit market for smaller commercial ships with cost-effective, high-efficiency batch incinerators that meet MARPOL Annex VI. A go-to-market angle focusing on simplified installation and crew training can differentiate offerings.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors firms with proven expertise in integrated waste-to-energy solutions and advanced flue gas cleaning. The long-term viability of shipboard incineration is strong, supported by persistent regulatory pressure and the need for onboard autonomy. Acquisition targets should include niche suppliers with proprietary gasification or pyrolysis technologies. Watch for port reception facility investment as a signal for market shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Flue Gas Cleaning Integration | Enhances compliance with MARPOL Annex VI emissions limits for commercial vessels. |
| Modular Incinerator Design | Simplifies installation and retrofitting processes for diverse vessel types, reducing system integration complexity. |
| Gasification Technology R&D | Positions suppliers for anticipated zero-emission port standards and integrated waste-to-energy solutions. |
| Crew Training Programs | Addresses skill gaps for operating sophisticated, electronically controlled incinerators on newbuilds. |
| Strategic Partnerships with Shipyards | Streamlines integration of waste management systems during vessel construction in Asian shipbuilding centers. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and robust secondary validation. Primary data involved discussions with shipyard engineers, vessel owners, maritime regulators, and technology developers. Secondary sources included MARPOL Annex VI documentation, IMO reports, shipbuilding association statistics, and company annual reports. Both bottom-up and top-down triangulation ensured data accuracy.
The forecasting boundary for this study extends over the projection horizon, utilizing a multi-layered analytical framework. Segmentation dimensions modeled include product type, technology, application, end-user, and vessel size. Compound annual growth rates (CAGRs) were derived from historical trends and projected regulatory impacts. Key forecast inputs included newbuild order books and retrofit mandates for existing fleets.
The analysis sits within stated boundaries; outcomes outside significant regulatory shifts or unforeseen technological disruptions would require recalibration. Forecasts reflect assumptions regarding global trade growth and environmental compliance. Practitioners should keep alternative scenarios live as shipbuilding activity and maritime environmental policies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste to Energy Systems
Brazil Waste to Energy Market
Waste to Energy Systems
Germany Waste-To-Energy Market
Waste to Energy Systems
Oil and Gas Waste Heat Recovery Market
Waste to Energy Systems
Anaerobic Digestion Equipment Market
Waste to Energy Systems
Waste to Diesel Market
Waste to Energy Systems
Global Waste-To-Energy Technologies Market
Waste to Energy Systems
Europe Waste-To-Energy Market
Waste to Energy Systems
Asia-Pacific Waste-To-Energy Market
Waste to Energy Systems
Waste to Energy (WTE) Market
Waste to Energy Systems
Nuclear Waste Recycling Market
Waste to Energy Systems
Global Waste to Fuel Technology Market
Waste to Energy Systems
Nuclear Waste Management Market
Waste to Energy Systems
ORC Industrial Waste Heat to Power Market
Waste to Energy Systems
China Waste to Energy Market
Waste to Energy Systems
Austria Waste to Energy Market
Waste to Energy Systems
North America Waste to Energy Market