
 Thermal Incinerator Market | 2026-2036
Thermal Incinerator Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Incinerator Market Analytics
China's Zhejiang province is fragmenting thermal incinerator supply as local environmental equipment makers multiply around Ningbo and Hangzhou. Dürr Cleantechnology leverages its German engineering base to dominate high-temperature regenerative thermal oxidizer exports into East Asia. Zeeco sustains technology leadership in multi-chamber incineration systems for petrochemical flares across the US Gulf Coast. Fives anchors European demand through its integrated combustion and environmental solutions portfolio.
A thermal incinerator destroys hazardous gases, liquid wastes, and particulate-laden exhaust streams through controlled high-temperature oxidation, typically operating between 760°C and 1,100°C depending on contaminant destruction requirements. The equipment serves industrial facilities requiring volatile organic compound abatement, pathogen destruction, or toxic emission neutralization before atmospheric release. Stationary incinerators occupy the dominant revenue position due to permanent installation at refineries and chemical complexes with continuous waste streams. Medical waste incinerators represent the fastest-expanding product category as healthcare facilities replace aging autoclave infrastructure with dual-chamber thermal destruction units. Rotary kiln technology commands premium pricing margins where heterogeneous feedstock composition demands controlled residence time and temperature profiling.
The US EPA enforces Maximum Achievable Control Technology standards that mandate thermal destruction efficiency thresholds for hazardous air pollutants from chemical manufacturing. China's Ministry of Ecology and Environment implements GB emission standards that compel provincial industrial clusters to retrofit or replace substandard combustion equipment. The EU Industrial Emissions Directive requires best available technique reference documents for waste incineration, shaping product certification requirements across member states. Stakeholders must monitor regulatory divergence between jurisdictions to align R&D investment with emerging compliance thresholds rather than legacy specifications.
Market Dynamics
The thermal incinerator market is being fundamentally restructured by the divergence between EU Industrial Emissions Directive compliance deadlines and China's GB standard enforcement timelines, forcing equipment vendors to maintain parallel certification portfolios rather than unified product platforms.
Growth Catalysts
- EU Industrial Emissions Directive:Germany's chemical processing corridor is expanding thermal oxidation capacity to meet best available technique requirements, creating sustained replacement demand for regenerative thermal oxidizer systems.
- Petrochemical flaring standards:The US EPA Maximum Achievable Control Technology mandates are compelling Gulf Coast refineries to upgrade multi-chamber incineration infrastructure for hazardous air pollutant destruction.
- Yangtze River Delta enforcement:China's provincial environmental bureaus are tightening volatile organic compound limits across Zhejiang and Jiangsu manufacturing clusters, accelerating equipment retrofit cycles.
Market Restraints
- Refractory material cost volatility:High-alumina ceramic lining prices fluctuate with bauxite supply disruptions from Guinea and Australia, compressing margins on rotary kiln system contracts.
- German engineering concentration:Premium regenerative thermal oxidizer technology remains concentrated among specialized fabricators in Baden-Württemberg and Bavaria, creating supply bottlenecks for East Asian export orders.
- Autoclave substitution:Steam sterilization systems are displacing thermal incinerators in smaller healthcare facilities below 50-bed capacity due to lower capital requirements and simpler permitting.
Strategic Opportunities
- India's biomedical waste rules:The 2016 Biomedical Waste Management Rules amendment is mandating phase-out of single-chamber incinerators across Maharashtra and Gujarat healthcare clusters.
- Dual-chamber medical systems:Pathogen destruction protocols for pharmaceutical manufacturing are creating demand for integrated thermal oxidation with heat recovery in sterile production environments.
- Remote monitoring convergence:IoT sensor networks combined with predictive maintenance algorithms are enabling performance-based service contracts for continuous-duty refinery installations.
Industry Challenges
- Combustion engineering specialization:Shortage of thermal oxidizer design engineers with expertise in heterogeneous waste stream characterization is delaying project commissioning timelines.
- Legacy DCS integration:Brownfield chemical plants require complex protocol translation between modern incinerator control systems and existing distributed control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Incinerator Market |
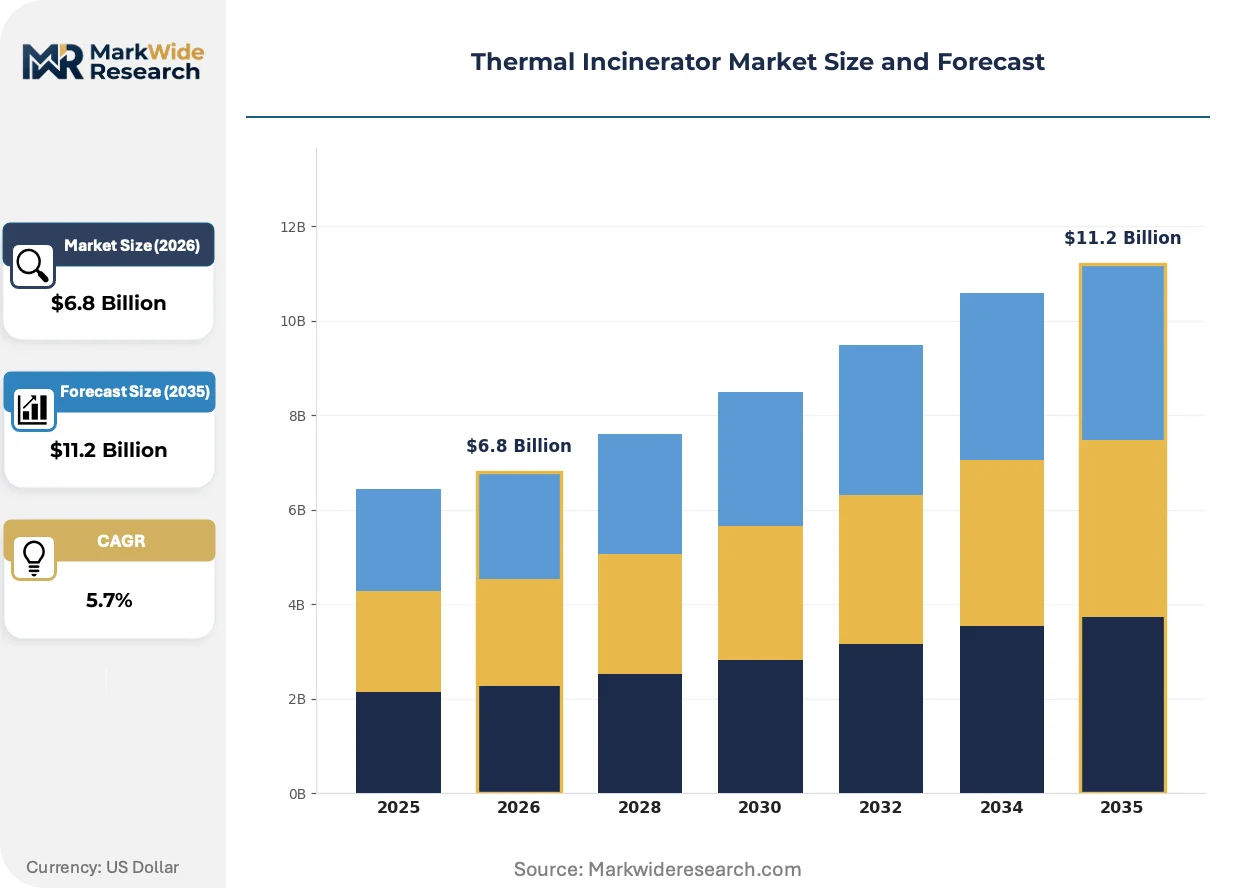
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Incinerators, Stationary Incinerators, Hazardous Waste Incinerators, Medical Waste Incinerators End User: Municipalities, Healthcare Facilities, Industrial Plants, Military Operations Technology: Combustion Technology, Rotary Kiln, Fluidized Bed, Controlled Air Application: Waste Treatment, Energy Recovery, Pollution Control, Fumes Management |
| Companies Covered | Tecam, AEREON, Tornado Combustion Technologies, Pollution Systems, Catalytic Products International, Fives, Honeywell International, Dürr Cleantechnology, Zeeco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Incinerator Market Evolving Landscape
Digital twin technology is compressing the design-validation cycle for thermal oxidation systems while regulatory stringency divergence between jurisdictions is fragmenting product standardization efforts.
Computational fluid dynamics modeling is virtualizing the traditional pilot-scale testing phase for regenerative thermal oxidizer design. Petrochemical operators in Texas and Louisiana are adopting virtual commissioning protocols to reduce field installation timelines. This virtualization is compressing the competitive advantage of established vendors with extensive physical test facilities.
The EU Industrial Emissions Directive's 2024 best available technique reference document revision is tightening particulate emission thresholds for waste incineration. Cement and lime manufacturers across Poland and the Czech Republic are retrofitting existing thermal oxidizers with enhanced baghouse filtration. Medical waste incinerator suppliers are responding by integrating ceramic filter systems into standard product configurations.
Performance contracting is displacing capital purchase models for volatile organic compound abatement equipment. Chemical manufacturers in China's Shandong province are adopting availability-guaranteed service agreements that transfer operational risk to equipment vendors. This shift is most pronounced among state-owned enterprises with constrained capex budgets and strict environmental compliance liabilities.
Thermal Incinerator Market Segmentation
Thermal incinerator procurement patterns diverge sharply across installation permanence, waste stream toxicity, and regulatory jurisdiction. Equipment specification varies with destruction efficiency mandates, feedstock heterogeneity, and thermal recovery requirements. Segmentation clarity enables vendors to align combustion engineering capabilities with compliance-driven replacement cycles.
Product Type:
Cost tier stratification separates capital-intensive permanent installations from deployable emergency response units.
- Stationary Incinerators:Fixed-base systems anchor revenue concentration through permanent installation at refineries and chemical complexes with continuous waste streams. German chemical processing corridors and US Gulf Coast petrochemical clusters sustain replacement demand for high-capacity regenerative thermal oxidizer configurations.
- Medical Waste Incinerators:Dual-chamber thermal destruction units are displacing aging autoclave infrastructure in healthcare facilities above 50-bed capacity. India's Maharashtra and Gujarat healthcare clusters are mandating phase-out of single-chamber systems under amended biomedical waste rules.
- Hazardous Waste Incinerators:Specialized systems handle toxic industrial byproducts requiring destruction and removal efficiency above 99.99%.
- Mobile Incinerators:Trailer-mounted or skid-based units serve emergency response and remote military operations with rapid deployment requirements.
Stationary incinerators hold installed capacity. Medical waste incinerators are rotating up the share rankings.
End User:
Application context determines combustion temperature profiles, residence time specifications, and emission control architecture.
- Industrial Plants:Chemical manufacturing, petroleum refining, and cement production facilities operate the largest installed base of thermal oxidation capacity. China's Yangtze River Delta manufacturing clusters and Germany's chemical processing corridor are expanding capacity to meet tightening volatile organic compound enforcement.
- Healthcare Facilities:Hospitals and pharmaceutical manufacturers require pathogen destruction protocols with integrated heat recovery for sterile production environments. Autoclave substitution pressure concentrates in facilities below 50-bed capacity.
- Municipalities:Local governments manage solid waste streams through centralized thermal treatment facilities.
- Military Operations:Defense installations deploy containerized incineration for field-deployed waste management and demilitarization activities.
Industrial plants command the dominant share of new orders. Healthcare facilities are climbing the fastest among end-user categories.
Technology:
Maturity gradients separate established combustion architectures from emerging thermal treatment modalities.
- Rotary Kiln:Cylindrical refractory-lined vessels enable controlled residence time and temperature profiling for heterogeneous feedstock composition. Premium pricing margins attach to systems handling mixed industrial waste streams with variable calorific content.
- Combustion Technology:Conventional thermal oxidation systems serve standardized waste streams with predictable destruction characteristics across municipal and industrial installations.
- Fluidized Bed:Suspended particle combustion achieves uniform heat distribution for fine particulate and sludge waste streams.
- Controlled Air:Two-stage combustion with oxygen limitation manages particulate emissions and thermal NOx formation.
Combustion technology retains the broadest installed footprint. Rotary kiln systems are gaining share fastest in hazardous waste applications.
Application:
Volume concentration varies with regulatory enforcement intensity and waste stream monetization potential.
- Waste Treatment:Primary thermal destruction function dominates procurement rationale across municipal, medical, and industrial waste categories. EU Industrial Emissions Directive compliance deadlines and China's GB standard enforcement timelines are fragmenting equipment certification requirements.
- Pollution Control:Volatile organic compound abatement and hazardous air pollutant destruction drive refinery and chemical plant upgrades. US EPA Maximum Achievable Control Technology mandates compel Gulf Coast infrastructure replacement.
- Energy Recovery:Waste-to-heat and waste-to-power configurations improve project economics through steam generation or electricity production.
- Fumes Management:Dedicated thermal oxidation of process exhaust streams addresses odor control and toxic gas neutralization.
Waste treatment anchors the application mix. Pollution control is rotating up the share rankings on regulatory enforcement acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway underwrites Germany's centrality in thermal oxidation equipment trade, connecting Bavarian engineering clusters to Black Sea manufacturing outposts and Rotterdam transshipment hubs.
United States
Gulf Coast petrochemical complexes drive regenerative thermal oxidizer procurement as flaring intensity triggers EPA enforcement actions. The Maximum Achievable Control Technology standard compels multi-chamber system upgrades across Texas and Louisiana refining corridors. Houston's ship channel industrial cluster sustains replacement demand for high-temperature destruction units.
Germany
Chemical processing plants along the Ludwigshafen-Leuna axis expand oxidation capacity to meet EU Industrial Emissions Directive deadlines. The best available technique reference document revision tightens particulate thresholds for waste incineration. Baden-Württemberg fabricators dominate premium regenerative thermal oxidizer exports into East Asian markets.
China
Yangtze River Delta manufacturing clusters face volatile organic compound enforcement acceleration from provincial environmental bureaus. The Ministry of Ecology and Environment implements GB emission standards compelling retrofit cycles across Zhejiang and Jiangsu. Ningbo and Hangzhou equipment makers fragment supply as local fabrication capacity multiplies.
India
Maharashtra and Gujarat healthcare clusters phase out single-chamber incinerators under amended biomedical waste rules. The 2016 Biomedical Waste Management Rules mandate dual-chamber thermal destruction for facilities above specified bed capacity. Mumbai-Pune pharmaceutical corridors adopt integrated oxidation with heat recovery for sterile production environments.
Japan
Industrial waste treatment facilities upgrade combustion infrastructure ahead of METI efficiency benchmarks. The country's national environmental regulator tightens dioxin emission limits for medical and chemical waste streams. Osaka-Kobe manufacturing belt concentrates demand for rotary kiln systems handling heterogeneous feedstock compositions.
Thermal Incinerator Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in refractory lining, burner assembly, and control module supply. The vendor base separates into three functional layers: turnkey solution providers, specialized oxidation technology developers, and regional fabrication shops serving local permitting requirements. Two dominant competitive moves define current positioning: technology licensing partnerships that bypass capital-intensive physical expansion, and vertical integration into ceramic refractory production to secure margin against bauxite price volatility.
Among European-headquartered specialists, Dürr Cleantechnology and Fives occupy positions reflecting distinct strategic archetypes—engineering-intensive export orientation versus integrated combustion and environmental solutions bundling. Zeeco represents the Gulf Coast-focused petrochemical flare specialist tier. These three entities exemplify how geographic clustering around regulatory enforcement intensity shapes competitive differentiation rather than scale economies alone.
| Leading Market Players |
|---|
| Tecam |
| AEREON |
| Tornado Combustion Technologies |
| Pollution Systems |
| Catalytic Products International |
| Fives |
| Honeywell International |
| Dürr Cleantechnology |
| Zeeco |
| Others |
Value Network & Pricing Analysis
The Rhine-Main-Danube waterway's barge freight dynamics shape cost structures for Bavarian engineering clusters exporting regenerative thermal oxidizers to East Asia, concentrating pricing power among Baden-Württemberg fabricators while forcing downstream differentiation between premium certified systems and economy-tier local alternatives.
Pricing Analysis
Volume-discount tiering structures separate project-scale procurement for Gulf Coast petrochemical complexes from modular unit sales to smaller chemical manufacturers. Pricing stratifies across premium certified, standard compliance, and economy-tier local fabrication levels, with EU BAT certification commanding substantial premiums over GB-standard equivalents. Cost compression in economy-tier segments is intensifying because Ningbo and Hangzhou equipment makers multiply local supply. Municipal healthcare facilities below 50-bed capacity exhibit highest price sensitivity, while integrated refinery operators prioritize availability guarantees over unit economics.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk planning for premium regenerative thermal oxidizer exports. Manufacturing concentration centers on Germany, China, and the United States, with Baden-Württemberg engineering clusters feeding high-temperature systems to East Asian markets. High-alumina ceramic linings, burner assemblies, and distributed control modules constitute critical input dependencies. Single-source vulnerability attaches to bauxite-derived refractory supply from Guinea and Australia. Distribution runs through EPC contractors and direct OEM relationships with major petrochemical and chemical processing operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermal incinerator incumbents confront substitution pressure from steam autoclave systems in healthcare facilities below 50-bed capacity, requiring defensive positioning around destruction efficiency advantages and regulatory compliance permanence.
For Market Incumbents: Entrench technology leadership in multi-chamber systems by deepening captive supply of high-alumina refractory linings against bauxite price volatility, while accelerating IoT-enabled predictive maintenance platforms to lock in performance-based service contracts with Gulf Coast and Yangtze River Delta operators facing stringent EPA and MEE enforcement timelines. For New Entrants and Emerging Players: Establish a beachhead in India's Maharashtra and Gujarat healthcare clusters by targeting dual-chamber medical waste incinerator demand under amended biomedical waste rules, leveraging technology licensing partnerships with European engineering specialists to bypass capital-intensive physical test facility investments while meeting CDSCO-equivalent certification requirements. For Investors and Strategic Acquirers: Regional fabrication shops with established permitting relationships in Zhejiang and Jiangsu provinces offer consolidation targets as local environmental equipment makers fragment supply around Ningbo and Hangzhou. Long-term viability hinges on regulatory enforcement durability across multiple jurisdictions rather than single-market exposure. Watch for divergence between EU Industrial Emissions Directive compliance deadlines and China's GB standard enforcement timelines as inflection indicator for parallel certification portfolio requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Refractory Production | Captive high-alumina ceramic supply secures margin against Guinea and Australia bauxite disruption. |
| IoT Predictive Maintenance Platform Deployment | Sensor networks enable availability-guaranteed contracts with Shandong province state-owned enterprises. |
| Dual-Chamber Medical System Certification | CDSCO-aligned validation opens Maharashtra and Gujarat healthcare cluster replacement cycles. |
| Technology Licensing Partnership | European engineering IP transfer bypasses capital-intensive physical test facility expansion. |
| Regional Fabrication Shop Acquisition | Local Zhejiang and Jiangsu permitting relationships accelerate provincial environmental bureau approvals. |
Research Methodology
Operator-level perspectives from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads anchored the qualitative base for this thermal incinerator market assessment. Primary field engagement combined with secondary validation against EPA enforcement databases, MEE GB standard filings, EU BAT reference documents, and chemical industry association capacity reports. Bottom-up equipment shipment analysis and top-down industrial emissions compliance spending estimates were triangulated to establish market sizing.
Scenario-bracketing framed the analytical approach across the projection horizon, modeling regenerative thermal oxidizer, rotary kiln, and multi-chamber system demand by installation permanence, waste stream toxicity, and regulatory jurisdiction. Segmentation dimensions included product type, end-user industry, combustion technology, and application context. CAGRs were derived from replacement cycle analysis tied to enforcement timeline convergence and divergence patterns. Forecast inputs incorporated refractory material cost indices and provincial environmental bureau staffing expansion rates as demand proxies.
Stress conditions across bauxite supply disruption severity, EU-China regulatory timeline divergence, and autoclave substitution penetration in sub-50-bed healthcare facilities were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about enforcement durability and technology substitution thresholds. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Control Solutions
Tide Gauge Market
Environmental Control Solutions
Scrubber System Market
Environmental Control Solutions
Sailboat Ballast Water Treatment Technology Market
Environmental Control Solutions
Scrubber Market
Environmental Control Solutions
Flue Gas Analyzers Market
Environmental Control Solutions
Modular Energy Control System Market
Environmental Control Solutions
Emission Control Technology Market
Environmental Control Solutions
Enclosed Waste Gas Flares Market
Environmental Control Solutions
North America Nitrogen Oxide Control Systems Market
Environmental Control Solutions
Gas Cleaning Technologies Market
Environmental Control Solutions
Global Leak Detection and Repair (LDAR) Market
Environmental Control Solutions
Residential Water Softening Systems Market
Environmental Control Solutions
Vapor Recovery Services Market
Environmental Control Solutions
Manufacturing Scale Electrostatic Precipitator Market
Environmental Control Solutions
Natural Refrigerants Market
Environmental Control Solutions
CO2 Injector (CO2 Bubbler) Market