
 Cuvettes Market | 2026-2036
Cuvettes Market Size, Share, and Industry Trends Forecast 2026-2036
Cuvettes Market Outlook
Contract research organizations and centralized hospital laboratories is reorganizing procurement patterns across the cuvettes supply base. Thermo Fisher Scientific leverages its diagnostic consumables platform to anchor recurring revenue streams in high-throughput clinical settings. Hellma Analytics specializes in fused quartz manufacturing for UV-Vis applications, sustaining premium positioning through German precision optics heritage. Bio-Rad Laboratories competes in the educational and biotechnology segments with plastic cuvette portfolios optimized for routine absorbance measurements.
Cuvettes are precision-matched optical cells manufactured from borosilicate glass, fused silica, or UV-grade synthetic quartz, designed to maintain exact path lengths between 1 mm and 100 mm for quantitative light transmission analysis in spectrophotometry and fluorometry. Plastic variants dominate high-volume clinical screening due to disposability economics, while optical quartz commands the steepest premiums in pharmaceutical quality control and DNA-protein quantification workflows where UV transparency below 200 nm proves essential. Research institutions represent the fastest-growing end user category as federal funding for life science instrumentation expands across North American and European university systems.
FDA 21 CFR Part 820 quality system regulations and ISO 17025 laboratory accreditation standards shape product specifications for cuvettes entering regulated diagnostic workflows, with FDA inspectors routinely verifying optical path length tolerances during device establishment inspections. The EPA mandates specific cuvette geometries and materials for certified water quality testing methods under Clean Water Act compliance programs, creating specification lock-in for environmental monitoring laboratories. Stakeholders must monitor how evolving dual carbon goals in the EU and China's MEE emissions frameworks redirect glass and quartz sourcing strategies without compromising optical performance thresholds.
Market Dynamics
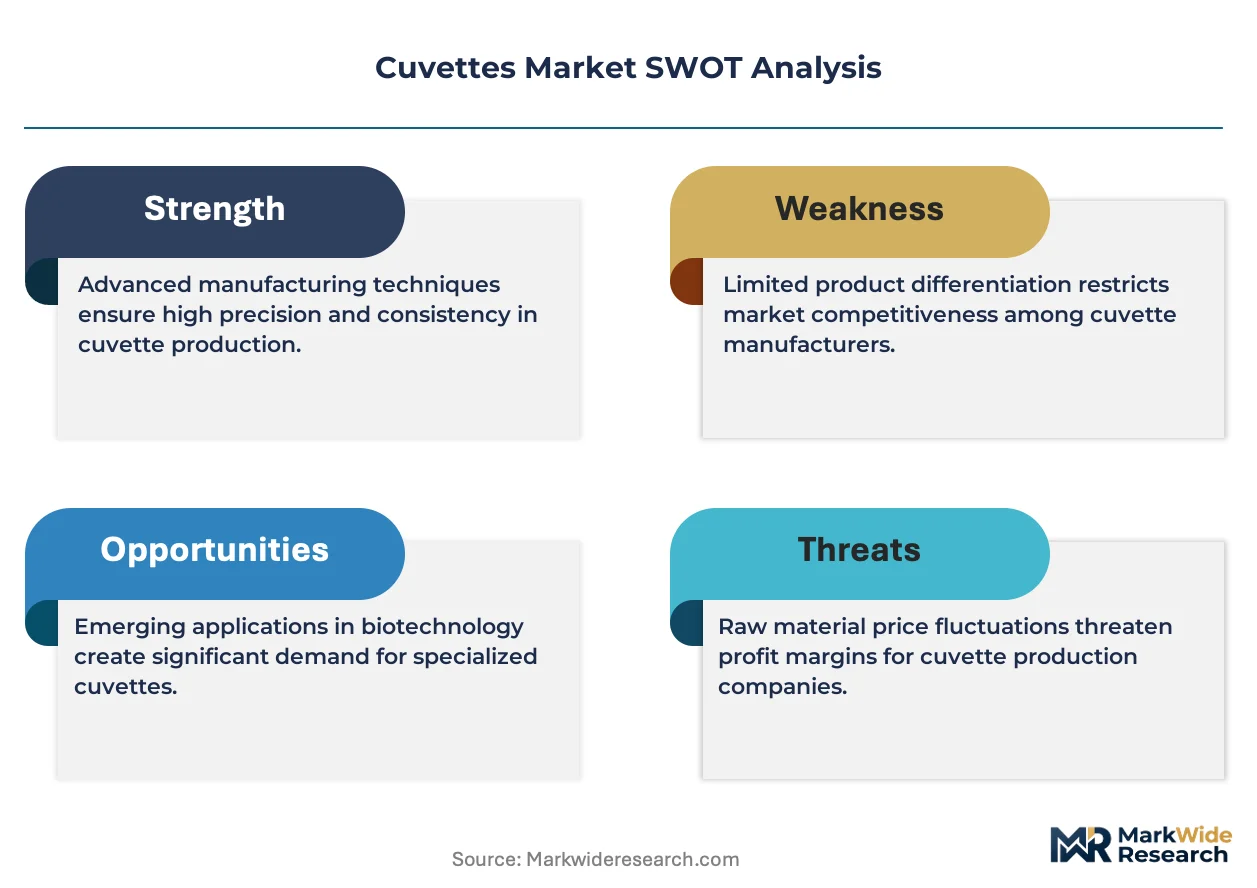
FDA 21 CFR Part 820 quality system regulations and ISO 17025 laboratory accreditation standards are tightening optical path length tolerances for cuvettes entering regulated diagnostic workflows, forcing manufacturers to recertify production lines and absorb compliance costs.
Growth Catalysts
- Clinical Diagnostics Expansion:Hospital laboratories and contract research organizations are intensifying spectrophotometry protocols for high-throughput screening, driving recurring demand for disposable plastic variants.
- REACH Chemical Safety Standards:European environmental testing laboratories must replace borosilicate glass cuvettes with certified fused quartz for EPA-mandated water quality methods under Clean Water Act compliance programs.
- UV-Vis Spectroscopy Advancement:DNA-protein quantification workflows now require UV transparency below 200 nm, pulling pharmaceutical quality control facilities toward premium synthetic quartz materials.
Market Restraints
- Raw Material Concentration:High-purity fused silica feedstock concentrates among German and Chinese suppliers, exposing manufacturers to geopolitical friction and export quota volatility.
- Substitution Pressure:Microfluidic chip-based photometric systems are displacing traditional cuvette formats in point-of-care diagnostic devices, compressing addressable volume in portable instrumentation.
- Certification Timeline Friction:FDA device establishment inspections for optical-grade cuvettes extend 12-18 months, gating new market entrants and freezing product line expansions.
Strategic Opportunities
- Research Institution Funding:Federal life science instrumentation grants across North American university systems are accelerating capital equipment procurement, opening premium quartz cuvette volume.
- Emerging Environmental Monitoring:China's MEE emissions frameworks are mandating certified water testing methods, creating specification lock-in for optical-grade consumables in provincial laboratories.
- Channel Digitization:Direct e-procurement platforms are disintermediating traditional laboratory supply distributors, enabling manufacturers to capture margin and build subscription replenishment models.
Industry Challenges
- Optical Metrology Talent Scarcity:Precision path length calibration requires specialized interferometry expertise that concentrates among aging workforces in Jena and Munich optics clusters.
- Dual Carbon Compliance:EU Green Deal emissions targets are forcing glass and quartz smelters to reconfigure energy-intensive furnaces without degrading optical homogeneity specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cuvettes Market |
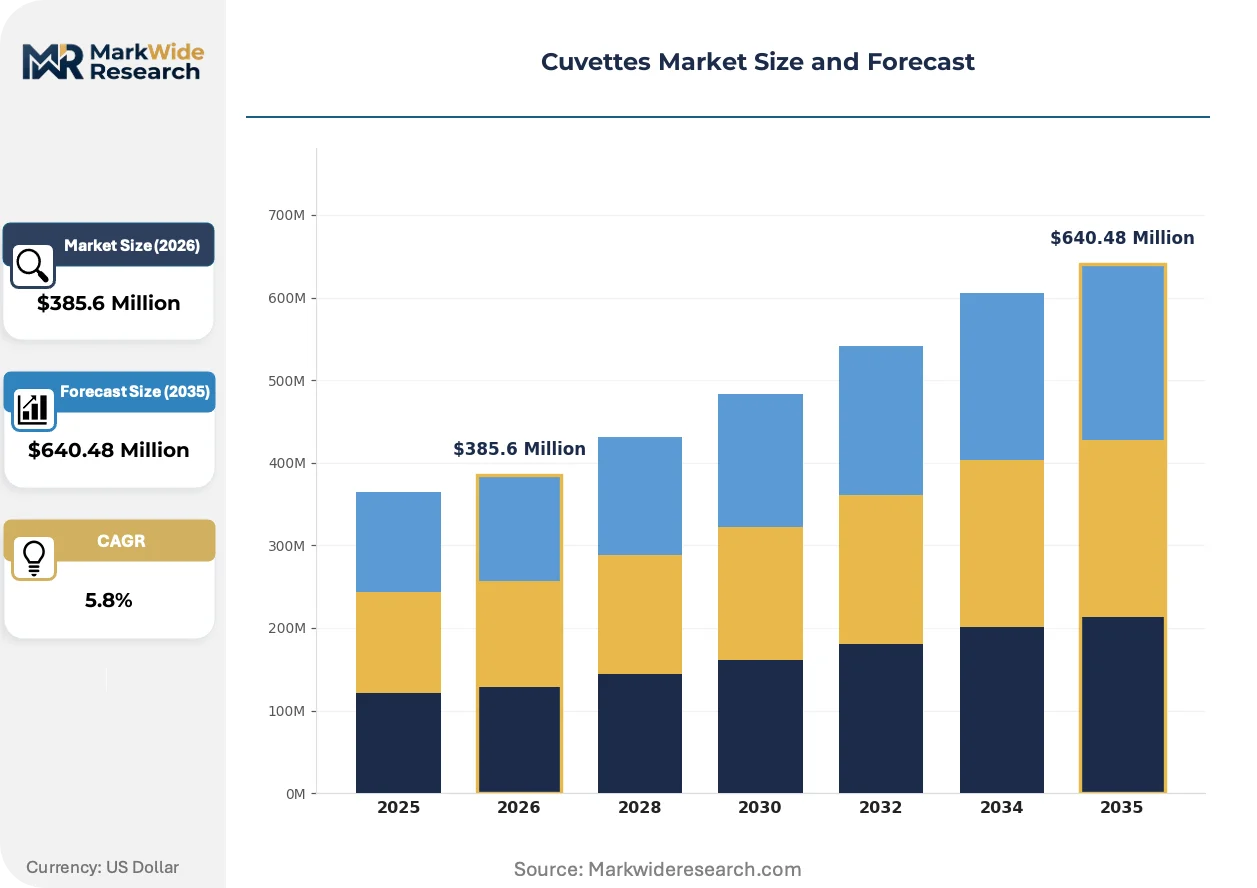
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Glass, Optical Quartz, Disposable Application: Clinical Diagnostics, Environmental Testing, Biotechnology, Educational Analysis End User: Laboratories, Research Institutions, Hospitals, Educational Institutes Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Healthcare Suppliers |
| Companies Covered | Hellma Analytics, Shimadzu Corporation, Thermo Fisher Scientific, Sarstedt AG & Co. KG, Starna Scientific, Agilent Technologies, Bio-Rad Laboratories, VWR International, Brand GmbH + Co KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cuvettes Market Strategic Shifts
Micro-volume spectrophotometry and single-use consumable formats are compressing traditional cuvette architectures while regulatory certification requirements fragment product portfolios across regional compliance regimes.
Micro-volume cuvette technology is miniaturizing sample requirements from milliliter to microliter scales, enabling direct nucleic acid quantification without dilution steps. Biotechnology startups and genomics service providers are adopting these formats fastest, displacing conventional 10 mm path length cells in high-complexity testing environments. The shift is miniaturizing instrument footprints and reducing reagent costs per assay while demanding tighter manufacturing tolerances.
EPA method certification requirements for water quality testing are mandating specific cuvette geometries and materials under Clean Water Act compliance programs. Environmental monitoring laboratories must maintain certified consumable inventories traceable to NIST standards, locking suppliers into multi-year qualification contracts. This regulatory scaffolding privileges incumbent manufacturers with established EPA method equivalency dossiers.
Subscription-based consumable replenishment contracts are displacing spot purchasing in centralized hospital laboratories and pharmaceutical quality control facilities. Group purchasing organizations are consolidating vendor panels to three preferred suppliers, compressing switching flexibility and forcing price transparency. This procurement consolidation concentrates most visibly in Germany's precision optics corridor serving Rhineland pharmaceutical clusters.
Cuvettes Market Segmentation
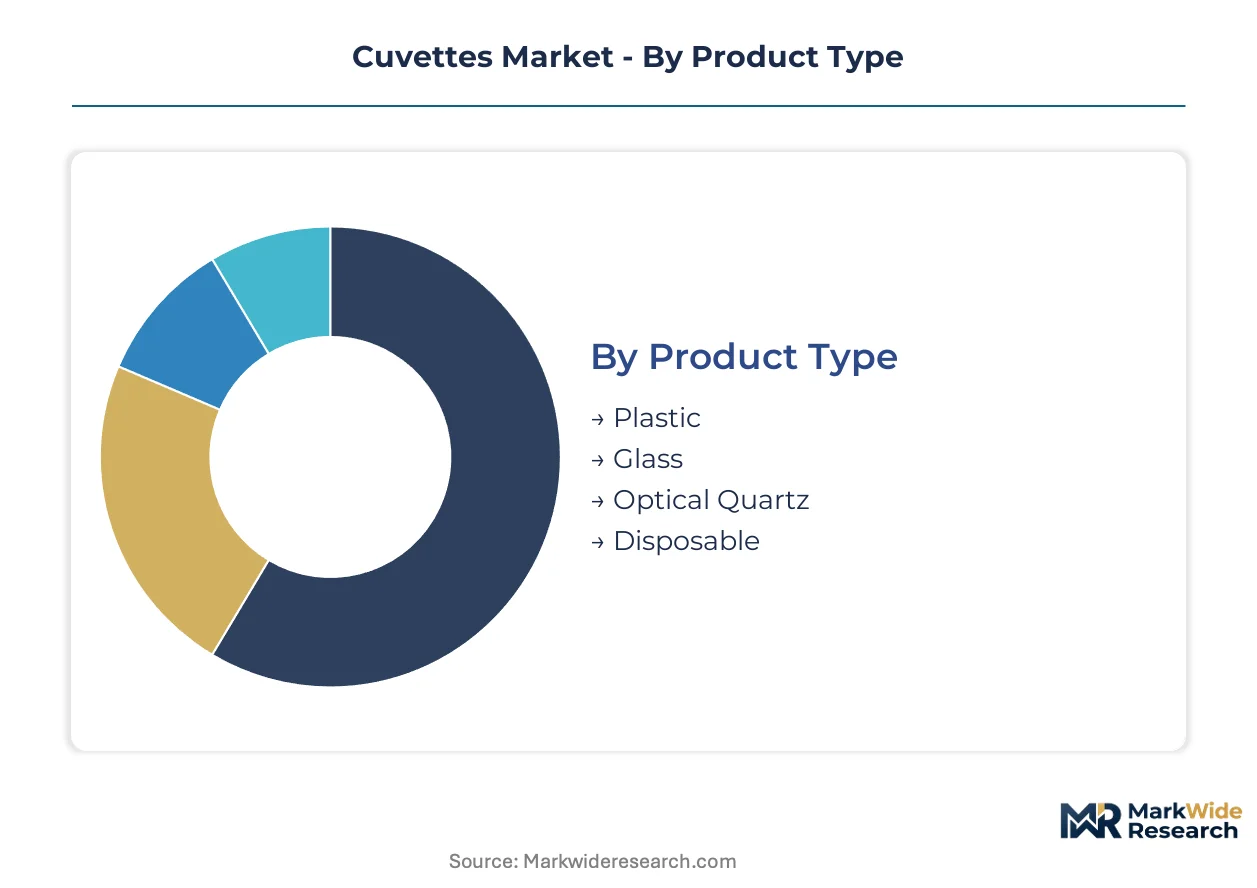
Material composition and end-use precision requirements fragment the cuvettes landscape into distinct margin tiers. Procurement patterns diverge sharply between regulated diagnostic workflows and routine educational screening, forcing manufacturers to maintain parallel certification portfolios.
Product Type:
Premium margin pools concentrate in UV-grade materials where pharmaceutical quality control mandates sub-200 nm transparency tolerances.
- Plastic:Polystyrene and polymethyl methacrylate variants dominate high-throughput clinical screening through disposability economics. Hospital laboratories in Germany's Rhineland pharmaceutical corridor are standardizing on certified plastic cuvettes for routine absorbance protocols under ISO 17025 workflows.
- Optical Quartz:Synthetic fused silica delivers the highest optical homogeneity for DNA-protein quantification and pharmaceutical stability testing. Demand concentrates in Bavarian precision optics clusters serving EMA-regulated quality control facilities where UV transparency below 200 nm is non-negotiable.
- Glass:Borosilicate formulations balance cost and performance for visible-light spectrophotometry in educational settings.
- Disposable:Single-use formats eliminate cross-contamination risks in centralized hospital laboratories processing infectious samples.
Optical quartz holds installed capacity. Plastic is rotating up the share rankings.
Application:
Regulatory certification intensity varies dramatically across use cases, with environmental compliance programs creating specification lock-in.
- Clinical Diagnostics:Spectrophotometry protocols for blood chemistry and immunoassay validation require FDA 21 CFR Part 820 certified consumables. Contract research organizations across North America are consolidating vendor panels to three preferred suppliers for recurring high-throughput screening contracts.
- Environmental Testing:EPA-mandated water quality methods under Clean Water Act programs dictate specific cuvette geometries and NIST-traceable calibration. China's MEE emissions frameworks are accelerating provincial laboratory procurement of certified fused quartz for certified testing workflows.
- Biotechnology:Micro-volume nucleic acid quantification is compressing traditional 10 mm path length architectures.
- Educational Analysis:Undergraduate chemistry laboratories prioritize cost efficiency over optical precision for visible-range experiments.
Clinical diagnostics holds installed capacity. Environmental testing is rotating up the share rankings.
End User:
Capital equipment procurement cycles and consumable replenishment models diverge sharply between institutional categories.
- Research Institutions:Federal life science instrumentation grants across North American university systems are accelerating premium quartz cuvette procurement. Genomics service providers are adopting micro-volume formats fastest, displacing conventional cells in high-complexity testing environments.
- Hospitals:Centralized laboratory networks are shifting from spot purchasing to subscription-based replenishment contracts. Group purchasing organizations in Germany are compressing vendor flexibility and forcing price transparency across Rhineland diagnostic clusters.
- Laboratories:Independent testing facilities balance certification requirements against throughput economics.
- Educational Institutes:Undergraduate programs prioritize durable borosilicate glass for repeated student use.
Hospital networks hold installed capacity. Research institutions are climbing the fastest.
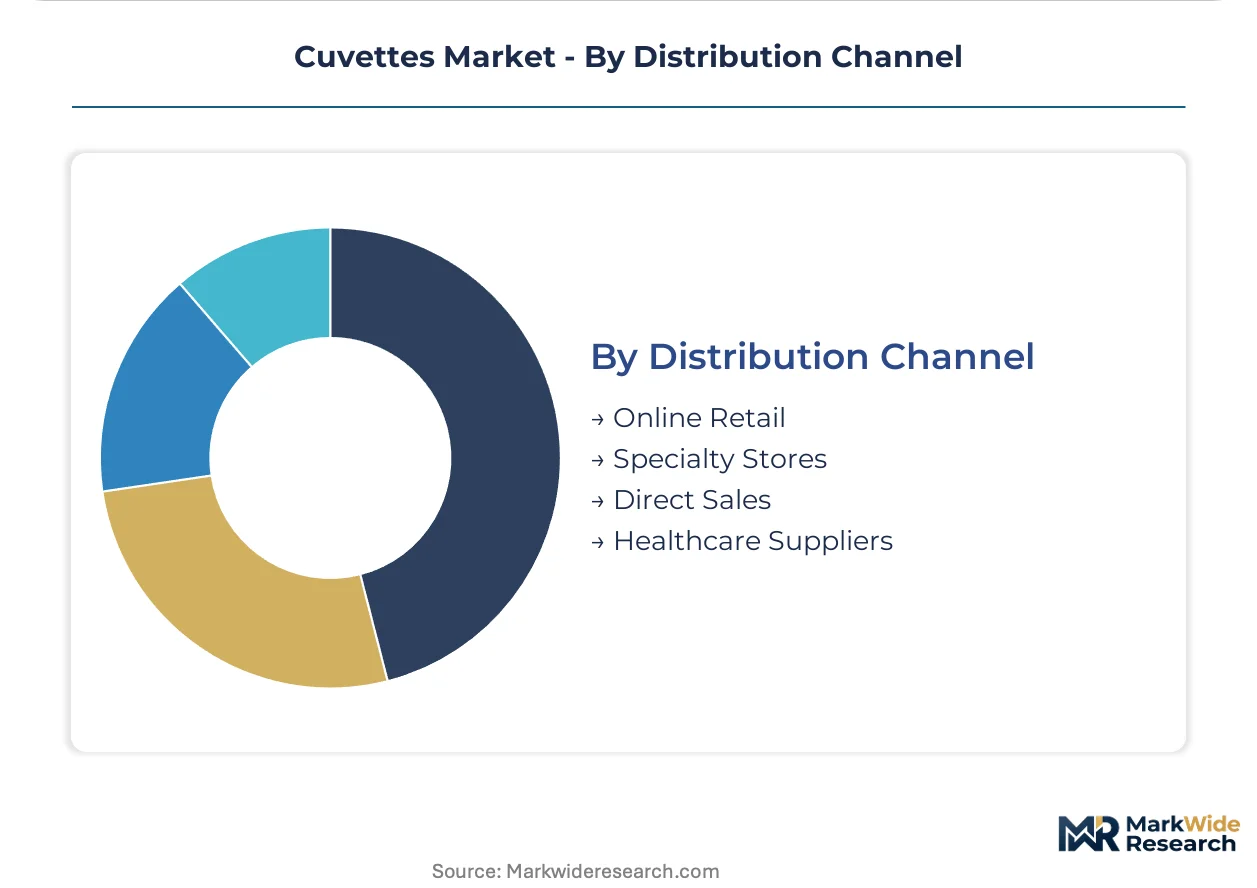
Distribution Channel:
Channel digitization is redistributing margin capture between manufacturers and traditional laboratory supply intermediaries.
- Direct Sales:Manufacturers are bypassing distributors to capture margin through e-procurement platforms serving pharmaceutical quality control facilities. Subscription replenishment models are consolidating most visibly in Germany's precision optics corridor.
- Online Retail:Digital platforms are disintermediating traditional supply chains for mid-volume research customers. Biotechnology startups are adopting direct e-procurement fastest, enabling manufacturers to build recurring revenue streams.
- Specialty Stores:Regional distributors maintain relationships with smaller educational and environmental testing accounts.
- Healthcare Suppliers:Group purchasing organizations aggregate demand from hospital networks under multi-year qualification contracts.
Healthcare suppliers hold installed capacity. Online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision optics manufacturers export fused quartz cuvettes to pharmaceutical quality control facilities across the United States and China. This trade corridor channels premium-grade consumables into FDA-regulated diagnostic workflows and NMPA-certified testing laboratories.
United States
Hospital laboratories and contract research organizations drive recurring demand for disposable plastic cuvettes in high-throughput clinical screening. FDA 21 CFR Part 820 quality system regulations mandate optical path length tolerances for diagnostic consumables. Greater Boston's life science corridor hosts genomics service providers adopting micro-volume formats fastest.
Germany
EMA-regulated pharmaceutical quality control facilities require UV transparency below 200 nm for DNA-protein quantification workflows. REACH chemical safety standards push environmental testing laboratories toward certified fused quartz materials. Bavarian precision optics clusters in Jena and Munich sustain premium manufacturing heritage for analytical consumables.
China
Provincial environmental monitoring laboratories accelerate procurement of optical-grade consumables under MEE emissions frameworks. NMPA device registration requirements shape specifications for cuvettes entering regulated diagnostic supply chains. Yangtze River Delta pharmaceutical clusters import German quartz substrates for quality control applications.
Japan
PMDA quality standards enforce strict optical homogeneity requirements for spectrophotometry consumables in pharmaceutical manufacturing. METI funding programs support university research instrumentation upgrades. Kanto region analytical instrument manufacturers integrate certified cuvettes into OEM spectrophotometer platforms.
India
CDSCO medical device regulations tighten specifications for diagnostic consumables entering hospital laboratory networks. Central government life science research grants expand capital equipment procurement at Indian Institutes of Technology. Maharashtra pharmaceutical manufacturing corridors source certified borosilicate and quartz cuvettes for stability testing protocols.
Cuvettes Market Competitive Environment
Listed leaders compete with private specialists across certification depth and material science capabilities. The vendor base stratifies into three tiers: multinational diagnostics conglomerates with recurring revenue platforms, mid-cap precision optics specialists with German manufacturing heritage, and regional distributors serving educational and environmental testing accounts. Strategic moves center on subscription-based replenishment contracts and direct e-procurement platform deployment.
Within the precision optics specialist tier, Hellma Analytics and Starna Scientific exemplify premium positioning through fused quartz manufacturing heritage. Thermo Fisher Scientific anchors the diagnostics conglomerate archetype with integrated consumables platforms. Among Germany-based fabricators, Brand GmbH + Co KG and Sarstedt AG & Co. KG occupy positions serving clinical and research laboratory supply chains.
| Leading Market Players |
|---|
| Hellma Analytics |
| Shimadzu Corporation |
| Thermo Fisher Scientific |
| Sarstedt AG & Co. KG |
| Starna Scientific |
| Agilent Technologies |
| Bio-Rad Laboratories |
| VWR International |
| Brand GmbH + Co KG |
| Others |
Value Chain & Pricing Dynamics
FDA 21 CFR Part 820 quality system regulations gate both supplier qualification timelines and price differentiation tiers simultaneously, forcing manufacturers to absorb extended certification costs while clinical laboratories demand transparent subscription pricing. This regulatory scaffolding concentrates pricing power among incumbent quartz fabricators with established device establishment dossiers, compressing margins for new entrants facing 12-18 month approval timelines.
Pricing Analysis
Prior-generation borosilicate glass cuvettes trade at commodity spot rates, current-generation plastic variants command contract-based long-term offtake pricing through hospital group purchasing organizations, and next-generation micro-volume quartz formats extract premium-mid-economy pricing differentiation based on UV transparency certification below 200 nm. Price differentiation hinges on ISO 17025 accreditation tier and volume scale commitments from centralized diagnostic networks. Cost compression in plastic disposables is intensifying because Rhineland pharmaceutical clusters are consolidating vendor panels to three preferred suppliers. Educational institutes exhibit highest price sensitivity, while EMA-regulated quality control facilities demonstrate lowest sensitivity due to non-negotiable optical performance thresholds.
Supply Chain Analysis
High-purity fused silica feedstock concentration in Jena and Munich optics clusters creates a chokepoint that exposes manufacturers to export quota volatility from German precision optics heritage sites. Raw material dependencies draw from synthetic quartz ingots, borosilicate glass preforms, and UV-grade polymer resins. Single-source vulnerability concentrates among aging interferometry calibration workforces in Bavaria, threatening path length tolerance consistency. Distribution runs through direct e-procurement platforms disintermediating traditional laboratory supply distributors, with subscription replenishment models consolidating in Germany's precision optics corridor serving pharmaceutical quality control facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as federal life science instrumentation grants accelerate capital equipment procurement across North American university systems, pulling premium quartz cuvette volume into research institutions faster than hospital laboratory replacement rates.
For Market Incumbents: Shield recurring revenue streams by deepening backward integration into synthetic quartz ingot production and securing multi-year EPA method equivalency dossiers before China's MEE emissions frameworks mature. Microfluidic chip-based photometric systems threaten traditional cuvette formats in point-of-care devices, making certification investment in UV-Vis spectroscopy protocols the critical defensive lever.
For New Entrants and Emerging Players: Differentiate on channel digitization by building direct e-procurement platforms for biotechnology startups and genomics service providers adopting micro-volume formats fastest. White-space targets concentrate in China's provincial environmental monitoring laboratories under MEE emissions frameworks and Indian Institutes of Technology expanding capital equipment procurement. A subscription replenishment go-to-market angle bypasses entrenched group purchasing organization vendor panels.
For Investors and Strategic Acquirers: FDA 21 CFR Part 820 timeline extensions reshape the acquisition landscape by privileging targets with existing device establishment inspections over greenfield certification plays. Long-term viability over a 5-10 year horizon rests on quartz material science capabilities and EPA/MEE regulatory dossiers rather than plastic disposables facing substitution pressure. The signal to watch is consolidation velocity among German precision optics specialists as dual carbon compliance forces furnace reconfiguration investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Quartz | Captive supply of UV-grade fused silica insulates margin from German feedstock export volatility. |
| EPA Method Equivalency Dossier Expansion | Multi-year qualification contracts lock environmental monitoring laboratories into certified consumable inventories. |
| Direct E-Procurement Platform Deployment | Subscription replenishment models capture margin from traditional laboratory supply distributors in Rhineland clusters. |
| Micro-Volume Format Certification | DNA-protein quantification workflows below 200 nm extract premium pricing from genomics service providers. |
| Dual Carbon Furnace Reconfiguration | EU Green Deal compliance preserves optical homogeneity specifications while meeting emissions targets. |
Study Parameters
Initial hypotheses were tested against primary input from spectrophotometry equipment manufacturers, clinical laboratory procurement managers, pharmaceutical quality control directors, and precision optics fabrication engineers and refined through secondary validation against FDA 510(k) filings, EPA method certification databases, EMA regulatory submissions, and German trade association production statistics. Bottom-up demand modeling from end-user capital equipment cycles triangulated with top-down market sizing from quartz and borosilicate glass feedstock trade flows.
Variance decomposition across material composition, application certification intensity, and end-user procurement model dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segment-level demand elasticity estimates calibrated against federal research funding trajectories and hospital laboratory consolidation patterns. Industry-specific forecast inputs incorporated REACH chemical safety standard implementation timelines and China's MEE emissions framework provincial rollout schedules.
Material uncertainties — geopolitical friction in high-purity fused silica supply, accelerated microfluidic substitution in point-of-care diagnostics, and EU Green Deal furnace reconfiguration delays — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as regulatory certification timeline volatility and dual carbon compliance cost pass-through evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Colony Counters Market
Laboratory Equipment
Western Blotting Processors Market
Laboratory Equipment
Global Slide Stainer Market
Laboratory Equipment
Global Pipette Tips Market
Laboratory Equipment
Microplate Instrumentation and Supplies Market
Laboratory Equipment
Microplate Reader Market
Laboratory Equipment
Point of Care (POC) Coagulation Testing Devices Market
Laboratory Equipment
Global Laboratory Equipment Services Market
Laboratory Equipment
Platelet Shaker Market
Laboratory Equipment
Laboratory Glassware and Plasticware Market
Laboratory Equipment
Global Hematocrit Test Devices Market
Laboratory Equipment
Laboratory Data Loggers Market
Laboratory Equipment
Global Hematology Instruments and Reagents Market
Laboratory Equipment
Hotplate Stirrers Market
Laboratory Equipment
Global Cell Analysis Instruments Market
Laboratory Equipment
Muffle Laboratory Furnaces Market