
 Medical Device Manufacturing Outsourcing Market | 2026-2036
Medical Device Manufacturing Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Device Manufacturing Outsourcing Market Analysis
Contract manufacturing partnerships between OEMs and third-party producers is tilting toward full-service providers capable of design-through-delivery integration. Jabil leverages vertically integrated electronics manufacturing capabilities to capture high-complexity diagnostic equipment programs. Flex anchors its position through dedicated healthcare campuses in regulated jurisdictions with validated cleanroom infrastructure. Integer Holdings Corporation specializes in catheter and delivery system manufacturing for cardiovascular OEMs.
Medical device manufacturing outsourcing encompasses the delegation of component fabrication, final assembly, sterilization, packaging, and regulatory filing support to external specialists operating under ISO 13485 quality management systems and FDA 21 CFR Part 820 requirements. The practice enables OEMs to convert fixed capital expenditures into variable costs while accessing specialized process technologies such as laser welding and nitinol shape-setting. Contract manufacturing services command the largest value pool within service type segmentation due to recurring production volumes and multi-year supply agreements. Additive manufacturing represents the fastest-expanding technology segment as titanium and PEEK implant producers adopt electron beam melting for patient-specific orthopedic devices. Diagnostic equipment product types maintain mature growth profiles but offer stable margin pools tied to recurring consumable demand.
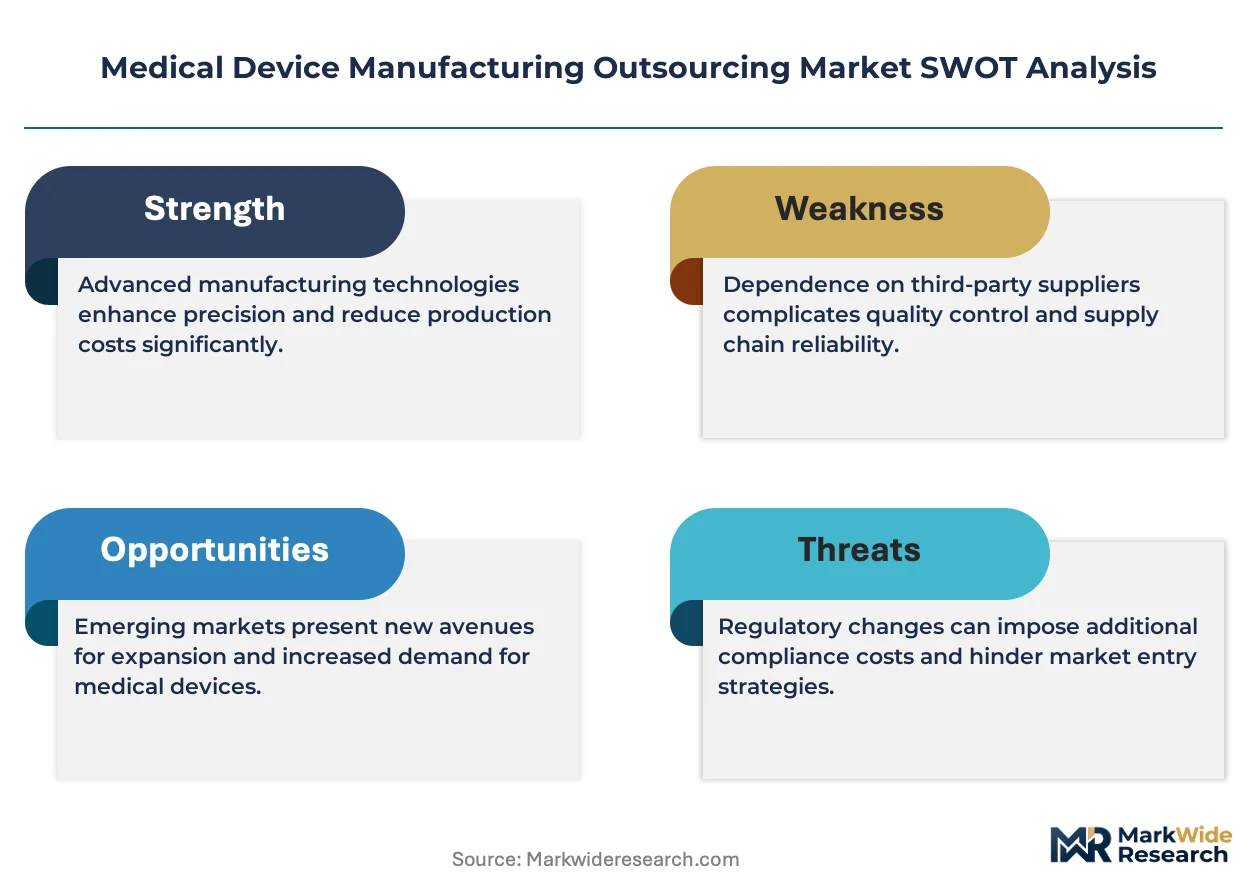
FDA quality system regulations, EU MDR technical documentation requirements, and ISO 14971 risk management standards collectively elevate barriers for new outsourcing entrants while driving incumbent capacity investments. OEMs now require suppliers to maintain dual-site manufacturing capabilities to ensure supply continuity through regulatory inspections or geopolitical disruptions. Stakeholders must evaluate whether captive manufacturing investments or expanded outsourcing partnerships better align with portfolio complexity and geographic regulatory exposure.
Market Dynamics
OEMs now demand full-service contract manufacturers capable of absorbing EU MDR technical documentation burdens and FDA 21 CFR Part 820 quality system compliance, compressing the vendor base toward multi-capability platforms.
Growth Catalysts
- EU MDR compliance complexity:The regulation's expanded clinical evidence requirements and unique device identification mandates push mid-size OEMs toward specialized contract manufacturers with established notified body relationships.
- Electron beam melting adoption:Titanium and PEEK implant producers are migrating patient-specific orthopedic production to electron beam melting platforms, creating dedicated outsourcing demand for validated additive manufacturing cells.
- Costa Rica cluster concentration:The country's free trade zone incentives and specialized medical device workforce have attracted catheter and delivery system manufacturers seeking FDA-aligned quality infrastructure.
Market Restraints
- Nitinol supply concentration:Shape-memory alloy sourcing remains concentrated among a limited set of qualified suppliers, exposing contract manufacturers to input cost volatility and allocation risk.
- ISO 13485 certification timelines:Extended audit backlogs at major registrars delay new entrant qualification, preserving incumbent pricing power but constraining capacity expansion.
- Dual-site manufacturing mandates:OEM supply continuity requirements now demand validated secondary production locations, doubling qualification costs and facility investment thresholds.
Strategic Opportunities
- Mexico nearshoring acceleration:Tijuana and Mexicali medical device parks offer tariff-advantaged access to US demand with growing laser welding and catheter extrusion capabilities.
- Digital health integration:Diagnostic equipment OEMs seek contract manufacturers with embedded electronics and connectivity module assembly to support software-as-medical-device submissions.
- India PLI scheme leverage:The production-linked incentive framework for medical devices is attracting component fabrication investment targeting export markets with cost-competitive precision machining.
Industry Challenges
- Polymer extrusion technician scarcity:Specialized catheter manufacturing requires experienced process engineers capable of multi-lumen tooling design and tight tolerance validation.
- Cleanroom capex intensity:ISO Class 7 and Class 8 validated environments for sterile device assembly demand substantial upfront investment with extended depreciation cycles.
- Legacy MES integration:Paper-based batch records and disconnected quality systems impede real-time production visibility required for OEM audit transparency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Device Manufacturing Outsourcing Market |
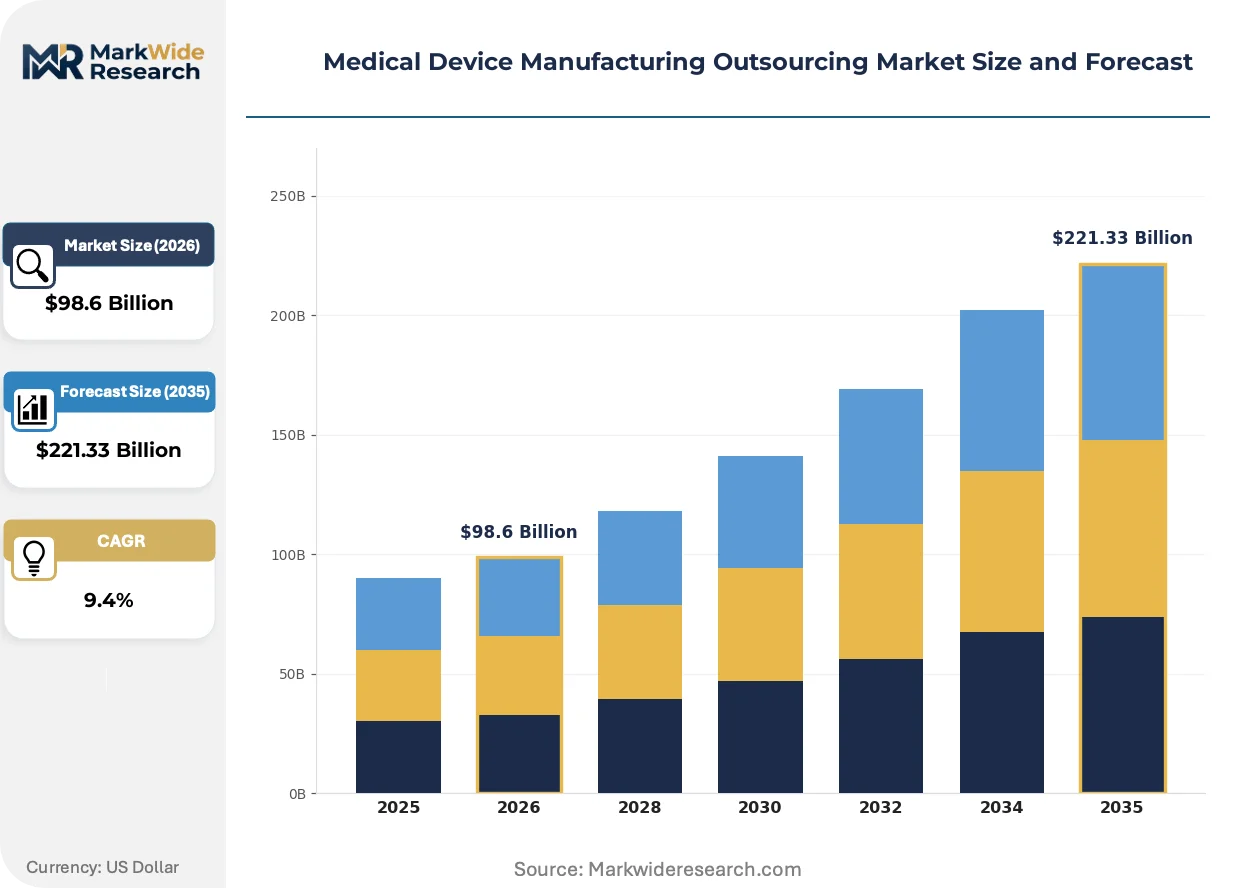
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $221.33 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Contract Manufacturing, Design Services, Regulatory Affairs, Packaging Solutions End User: OEMs, Healthcare Providers, Diagnostic Centers, Biotechnology Firms Product Type: Implants, Surgical Instruments, Diagnostic Equipment, Rehabilitation Devices Technology: Additive Manufacturing, CNC Machining, Injection Molding, 3D Printing |
| Companies Covered | Jabil, Flex, TE Connectivity, Sanmina Corporation, Integer Holdings Corporation, Gerresheimer, Plexus Corporation, Nortech Systems, Phillips-Medisize, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Device Manufacturing Outsourcing Market Emerging Trajectories
Electron beam melting, EU MDR technical documentation automation, and outcome-linked procurement models are compressing traditional outsourcing timelines while elevating capability requirements for contract manufacturing partners.
Additive manufacturing platforms utilizing electron beam melting for titanium lattice structures are rendering obsolete conventional subtractive machining for patient-matched orthopedic implants. Cardiovascular and spinal OEMs are qualifying these platforms for serial production, compressing lead times from weeks to days while eliminating tooling costs.
EU MDR's expanded clinical evaluation requirements and post-market surveillance obligations are forcing contract manufacturers to integrate regulatory affairs capabilities previously retained by OEMs. Diagnostic equipment and active implantable device categories face the steepest documentation burdens, driving partnerships with full-service providers possessing notified body rapport.
Hospital procurement consortiums are consolidating vendor panels and demanding outcome guarantees tied to device reliability metrics, displacing transactional component sourcing. This concentration is most visible in US health system purchasing, where IDNs now mandate single-source accountability for entire product categories.
Medical Device Manufacturing Outsourcing Market Segmentation
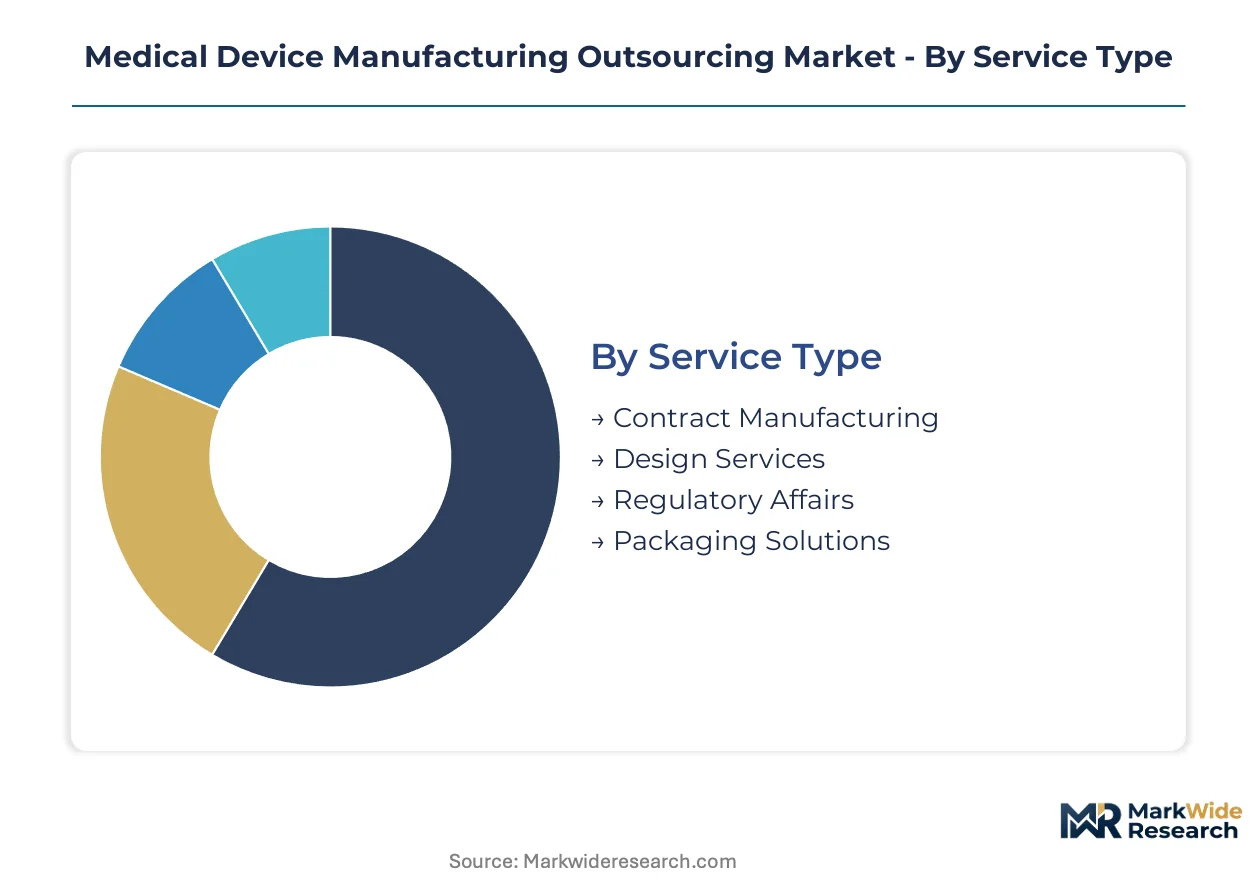
Medical device manufacturing outsourcing segments diverge sharply in capital intensity and qualification timelines. Contract manufacturing cycles span years while regulatory services turn monthly, creating portfolio balancing imperatives for OEM procurement teams.
Service Type:
Cycle times stretch from multi-year production agreements to rapid-turn consulting engagements, compressing vendor selection criteria toward platform breadth.
- Contract Manufacturing:Encompasses component fabrication through final assembly under ISO 13485 and FDA 21 CFR Part 820 protocols. Demand clusters in Costa Rica and Mexico where catheter extrusion and laser welding capabilities serve cardiovascular OEMs facing EU MDR compliance deadlines.
- Design Services:Covers industrial design, DfM optimization, and transfer-to-manufacturing engineering. Biotechnology firms in Ireland leverage these capabilities to accelerate Class III implant development cycles while managing notified body documentation burdens.
- Regulatory Affairs:Technical documentation preparation, 510(k) submission support, and post-market surveillance management. FDA submission backlogs and EU MDR transition timelines drive recurring engagement models.
- Packaging Solutions:Sterile barrier system design, validation testing, and shelf-life studies. Healthcare providers increasingly mandate single-source accountability for packaging integrity tied to infection control protocols.
Contract manufacturing dominates installed base. Regulatory affairs is where expansion concentrates.
End User:
Cost tiers separate capital-constrained innovators from volume-scale incumbents, reshaping pricing structures and payment terms across the vendor base.
- OEMs:Large device manufacturers converting fixed manufacturing assets to variable cost structures. Integer Holdings and Jabil capture multi-year supply agreements from cardiovascular and diagnostic OEMs requiring dual-site manufacturing capabilities.
- Healthcare Providers:Hospital systems and integrated delivery networks consolidating vendor panels. US IDNs now demand outcome guarantees tied to device reliability metrics, displacing transactional sourcing.
- Diagnostic Centers:Imaging and laboratory service operators seeking equipment maintenance and consumable supply partnerships. Recurring reagent and calibration demand supports stable margin pools.
- Biotechnology Firms:Emerging therapeutic device developers lacking in-house manufacturing infrastructure. These entities drive demand for full-service design-through-delivery integration with embedded regulatory support.
OEMs anchor revenue concentration. Biotechnology firms represent the steepest expansion trajectory.
Product Type:
Application criticality determines validation rigor, with implantable categories demanding extensive biocompatibility testing and active device categories requiring electromagnetic compliance.
- Implants:Orthopedic, cardiovascular, and neurological devices requiring biocompatibility validation and sterilization assurance. Electron beam melting adoption for titanium lattice structures is compressing lead times for patient-matched orthopedic production.
- Surgical Instruments:Reusable and single-use devices spanning general surgery through specialized robotic platforms. Mexico nearshoring accelerates as Tijuana parks expand laser welding and precision machining capabilities.
- Diagnostic Equipment:Imaging systems, in-vitro diagnostics, and patient monitoring devices. Software-as-medical-device submissions drive demand for embedded electronics assembly and connectivity module integration.
- Rehabilitation Devices:Prosthetics, orthotics, and mobility assistance equipment. India PLI scheme incentives attract component fabrication investment targeting export markets with cost-competitive production.
Diagnostic equipment commands mature volume base. Implants concentrate technology investment and margin expansion.
Technology:
Volume scalability separates mass-production platforms from job-shop flexibility, with hybrid manufacturing strategies emerging for complex device portfolios.
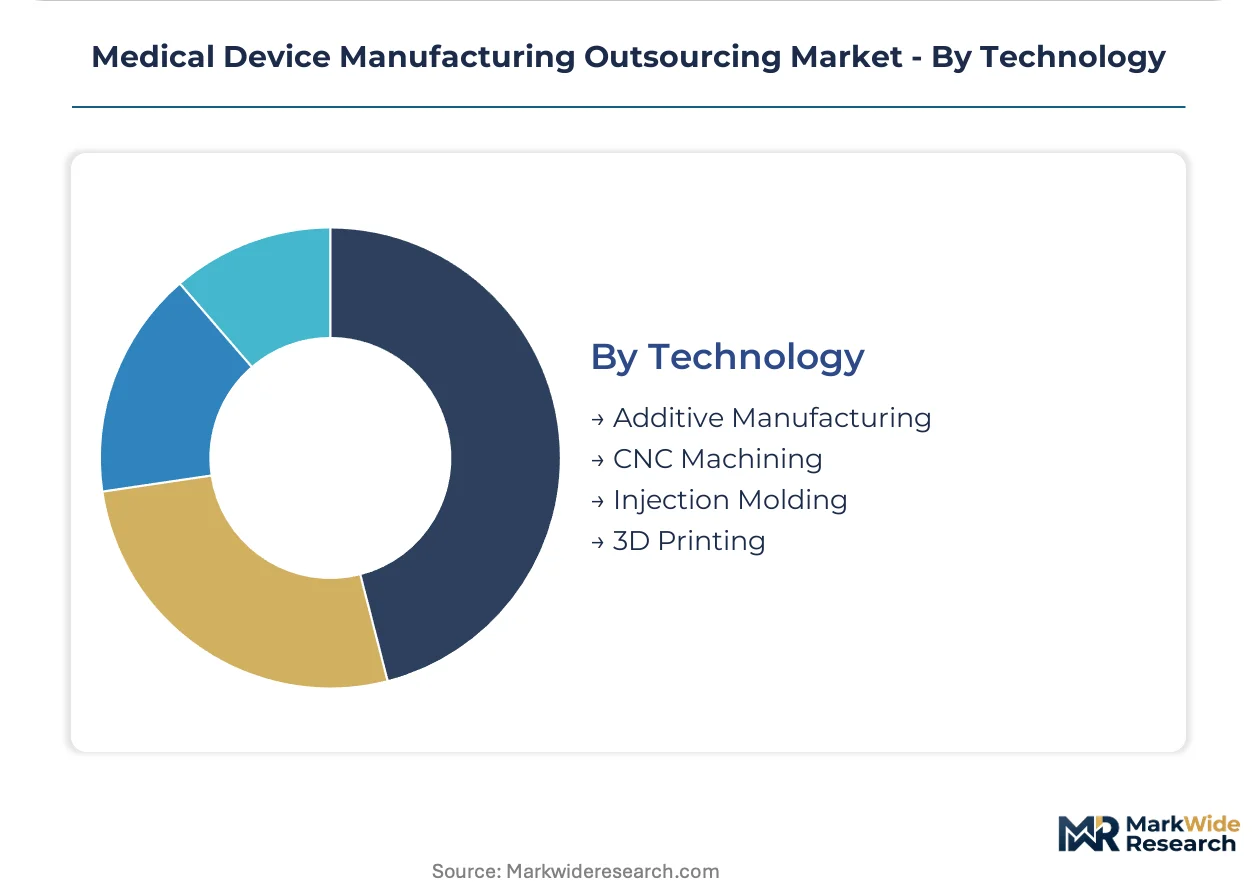
- Additive Manufacturing:Electron beam melting and laser powder bed fusion for titanium and PEEK implants. Cardiovascular and spinal OEMs qualify these platforms for serial production, eliminating conventional tooling costs.
- CNC Machining:Multi-axis milling and turning for precision metal components. Nitinol shape-setting and tight-tolerance catheter mandrel production remain concentrated among qualified supplier networks.
- Injection Molding:High-volume polymer component production with multi-cavity tooling. Cleanroom ISO Class 7 validation requirements elevate capital thresholds for sterile device assembly.
- 3D Printing:Fused deposition modeling and stereolithography for prototyping and surgical planning models. Distinct from production-grade additive manufacturing in regulatory validation requirements.
CNC machining anchors production volume. Additive manufacturing is gaining share fastest among qualification-stage programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Panama Canal's interoceanic shipping lanes underpin Costa Rica's emergence as a catheter manufacturing hub, connecting Central American free trade zones to US East Coast distribution networks within 72 hours.
United States
FDA 21 CFR Part 820 quality system enforcement drives OEMs toward validated contract manufacturers with established inspection histories. The IRA's domestic manufacturing incentives accelerate reshoring discussions for critical implant categories. Minneapolis-St. Paul anchors cardiovascular device engineering concentration alongside Boston's diagnostic equipment corridor.
Ireland
EU MDR technical documentation burdens push biotechnology firms toward full-service providers with notified body relationships. The country's corporate tax framework and skilled pharmaceutical workforce attract Class III implant development programs. Galway and Dublin host specialized cleanroom campuses serving European cardiovascular OEMs.
Mexico
Tariff-advantaged access to US demand accelerates catheter extrusion and laser welding investment in Tijuana medical device parks. IMMEX program maquiladora structures enable duty-deferred component import for sterile assembly export. Mexicali and Tijuana clusters expand precision machining capabilities for surgical instrument OEMs.
Costa Rica
Free trade zone incentives and specialized medical device workforce development attract catheter and delivery system manufacturers. FDA-aligned quality infrastructure supports cardiovascular OEM compliance requirements. The Coyol and Ultrapark clusters concentrate extrusion and molding operations for US-bound sterile devices.
India
CDSCO regulatory alignment with ISO 13485 standards supports export-oriented component fabrication investment. The PLI scheme for medical devices attracts precision machining capacity targeting cost-competitive orthopedic implant production. Karnataka and Gujarat industrial corridors expand nitinol processing and polymer extrusion capabilities.
Medical Device Manufacturing Outsourcing Market Vendor Landscape
On the supply side, the industry is consolidating around multi-capability platforms capable of absorbing EU MDR documentation burdens and FDA quality system compliance. Large-scale electronics manufacturers leverage vertically integrated assembly infrastructure to capture diagnostic equipment programs. Specialized catheter and implant fabricators anchor cardiovascular and orthopedic outsourcing demand. Dominant competitive moves include geographic expansion into tariff-advantaged jurisdictions and backward integration into nitinol shape-setting and polymer compounding.
Among full-service contract manufacturers, Jabil and Flex exemplify the electronics-integrated healthcare campus model, while Integer Holdings Corporation occupies a specialist position in cardiovascular delivery systems. These entities represent divergent scale strategies within a vendor base tilting toward design-through-delivery integration.
| Leading Market Players |
|---|
| Jabil |
| Flex |
| TE Connectivity |
| Sanmina Corporation |
| Integer Holdings Corporation |
| Gerresheimer |
| Plexus Corporation |
| Nortech Systems |
| Phillips-Medisize |
| Others |
Supply Flow & Price Mechanics
The Coyol Free Trade Zone in Costa Rica concentrates catheter extrusion capacity serving US cardiovascular OEMs, translating validated cleanroom infrastructure into pricing power that contract manufacturers wield against buyers facing EU MDR compliance deadlines. This geographic clustering enables tiered quoting structures where FDA-inspected facilities command premiums over Mexico-based alternatives with equivalent technical capabilities.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated cleanroom facilities from ISO 13485-only operations and emerging India-based precision machining shops. Price differentiation hinges on certification tier—FDA 21 CFR Part 820 compliance versus EU MDR notified body rapport—and volume scale tied to multi-year supply agreements. Cost compression in the standard tier is intensifying because biotechnology firms demand embedded regulatory affairs support previously retained in-house. Healthcare providers exhibit the highest price sensitivity due to IDN procurement consolidation, while Class III implant OEMs prioritize qualification speed over unit economics.
Supply Chain Analysis
Tariff exposure between Mexico and the United States dominates supply chain risk calculations as IMMEX program maquiladora structures face potential renegotiation. Component fabrication concentrates in Costa Rica, Mexico, and Ireland, drawing from nitinol shape-memory alloy feedstock, PEEK polymer resin, and titanium powder inputs. Single-source vulnerability in nitinol supply exposes contract manufacturers to allocation risk during aerospace demand spikes. Distribution runs through validated cold-chain logistics networks connecting Central American free trade zones to US East Coast distribution hubs within 72-hour windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical device manufacturing outsourcing sits in early-cycle expansion as electron beam melting adoption for patient-specific orthopedic implants accelerates qualification-stage outsourcing demand beyond traditional machining capacity.
For Market Incumbents: Harden dual-site manufacturing capabilities across tariff-advantaged jurisdictions to absorb OEM supply continuity mandates while insulating margin structures from nitinol input volatility. Deepen backward integration into polymer compounding and shape-memory alloy processing to reduce qualified supplier concentration risk. Prioritize EU MDR technical documentation automation investments that compress OEM time-to-market and justify multi-year contract premiums. For New Entrants and Emerging Players: Pursue biotechnology firm design-through-delivery integration contracts in Ireland and India where emerging therapeutic device developers lack captive manufacturing infrastructure. The most penetrable white space sits in additive manufacturing cell validation for titanium lattice orthopedic implants, where incumbent capacity constraints create qualification bottlenecks. Establish go-to-market positioning through notified body relationship partnerships that accelerate EU MDR submission timelines for cash-constrained innovators. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors contract manufacturers with embedded regulatory affairs capabilities and validated additive manufacturing platforms. Long-term viability across the analysis window rests on capturing recurring production volumes from cardiovascular OEMs converting fixed assets to variable cost structures. The acquisition target archetype combines catheter extrusion expertise with electron beam melting qualification-stage programs. Watch FDA inspection backlog resolution as the signal indicating when capacity expansion investments translate to revenue recognition acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Automation | Compresses OEM submission timelines while embedding contract manufacturers deeper in regulatory value chains. |
| Dual-Site Manufacturing Qualification | Addresses OEM supply continuity mandates through validated secondary locations in Costa Rica and Mexico. |
| Electron Beam Melting Cell Validation | Captures patient-specific orthopedic implant production migrating from subtractive machining platforms. |
| Notified Body Relationship Partnerships | Accelerates biotechnology firm market access through embedded EU MDR clinical evaluation support. |
| Backward Integration into Nitinol Processing | Reduces shape-memory alloy allocation risk exposure concentrated among limited qualified suppliers. |
Methodological Framework
The analysis maps contract manufacturing, design services, regulatory affairs, and packaging solutions segments, each validated through contract manufacturing executives, OEM procurement directors, notified body auditors, and hospital GPO contracts managers. Primary intelligence combines structured interviews with secondary triangulation against FDA 510(k) submission databases, EU MDR technical documentation filings, ISO 13485 registrar audit records, and customs trade data tracking medical device component flows. Bottom-up facility capacity assessments and top-down OEM outsourcing spend estimates converge through iterative reconciliation.
Base-case assumptions hold FDA 21 CFR Part 820 enforcement intensity and EU MDR transition timelines fixed across the projection horizon, with scenario variants testing accelerated additive manufacturing adoption and nitinol supply disruption. Segmentation dimensions modeled include service type, end-user archetype, product criticality tier, and regional regulatory cluster. CAGRs derive from fitted growth curves anchored to disclosed contract values and validated production capacity expansions, incorporating electron beam melting qualification timelines and cleanroom capex depreciation schedules as industry-specific inputs.
Sensitivities concentrate around FDA inspection backlog resolution, EU MDR notified body capacity constraints, and nitinol alloy allocation volatility. Forecasts reflect documented assumptions subject to revision from regulatory enforcement shifts or geopolitical trade policy changes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US Electrosurgical Generators Market
Medical Devices
Specimen Retrieval Nets Market
Medical Devices
North America Refractive Surgery Devices Market
Medical Devices
Clinical Trinocular Microscopes Market
Medical Devices
Heating Pads Market
Medical Devices
Blood Warmers Market
Medical Devices
Pen Needles Market
Medical Devices
Brazil Aesthetic Devices Market
Medical Devices
Smart Wheelchairs Market
Medical Devices
Global Intravenous (IV) Equipment Market
Medical Devices
Venous Procedure Devices Market
Medical Devices
Middle East and Africa Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Medical Puncture Navigation Robot Market
Medical Devices
Arteriovenous Fistula Devices Market
Medical Devices
Hearing Aids Market
Medical Devices
Indwelling Catheter Market