
 Blood Testing Equipment Market | 2026-2036
Blood Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Testing Equipment Market Analysis
Multi-source procurement for reagent consumables is hardening across hospital laboratory networks. Roche Diagnostics leverages its captive immunoassay reagent ecosystem to sustain recurring revenue streams. Abbott Laboratories anchors its position through point-of-care blood gas platforms that reduce turnaround times in emergency departments. Thermo Fisher Scientific differentiates via PCR-based molecular diagnostics that command premium positioning in reference laboratories.
Blood testing equipment comprises automated analytical instruments that quantify cellular, biochemical, and molecular parameters from venous or capillary samples, typically processing 100–800 tests per hour depending on analyzer class. These systems serve clinical decision-making by enabling disease screening, therapeutic monitoring, and transfusion safety verification. Hematology analyzers occupy the largest installed base due to routine complete blood count demand across inpatient and outpatient settings. Immunoassay platforms represent the fastest-expanding category as troponin, procalcitonin, and infectious disease panels shift from batch to random-access processing. Blood gas analyzers concentrate margin pools in critical care settings where pH, pO2, and electrolyte results guide ventilator and vasopressor management.
FDA quality-system regulation and CLIA complexity requirements shape instrument design, software validation, and operator certification pathways in the United States. The EU In Vitro Diagnostic Regulation imposes stricter clinical evidence and post-market surveillance obligations on manufacturers seeking CE marking for European market access. Stakeholders must monitor how laboratory consolidation into regional health systems reshapes purchasing leverage and service contract terms.
Market Dynamics
Integrated delivery networks in the United States are consolidating laboratory procurement into centralized contracts, compressing vendor margins while demanding extended service-level agreements and unified data interoperability across multi-site analyzer fleets.
Growth Catalysts
- CLIA complexity requirements:The FDA's escalating quality-system mandates for in vitro diagnostic devices are compelling hospital laboratories to upgrade aging hematology platforms, creating replacement demand for automated analyzers with enhanced analytical validation protocols.
- Random-access immunoassay processing:Troponin and procalcitonin testing is migrating from batch to continuous-load platforms, accelerating analyzer throughput in emergency departments and critical care units where turnaround time directly affects clinical outcomes.
- Critical care margin concentration:Blood gas analyzers command premium positioning in intensive care settings, where pH, pO2, and electrolyte results guide ventilator management and vasopressor titration, sustaining higher per-test revenue than routine chemistry panels.
Market Restraints
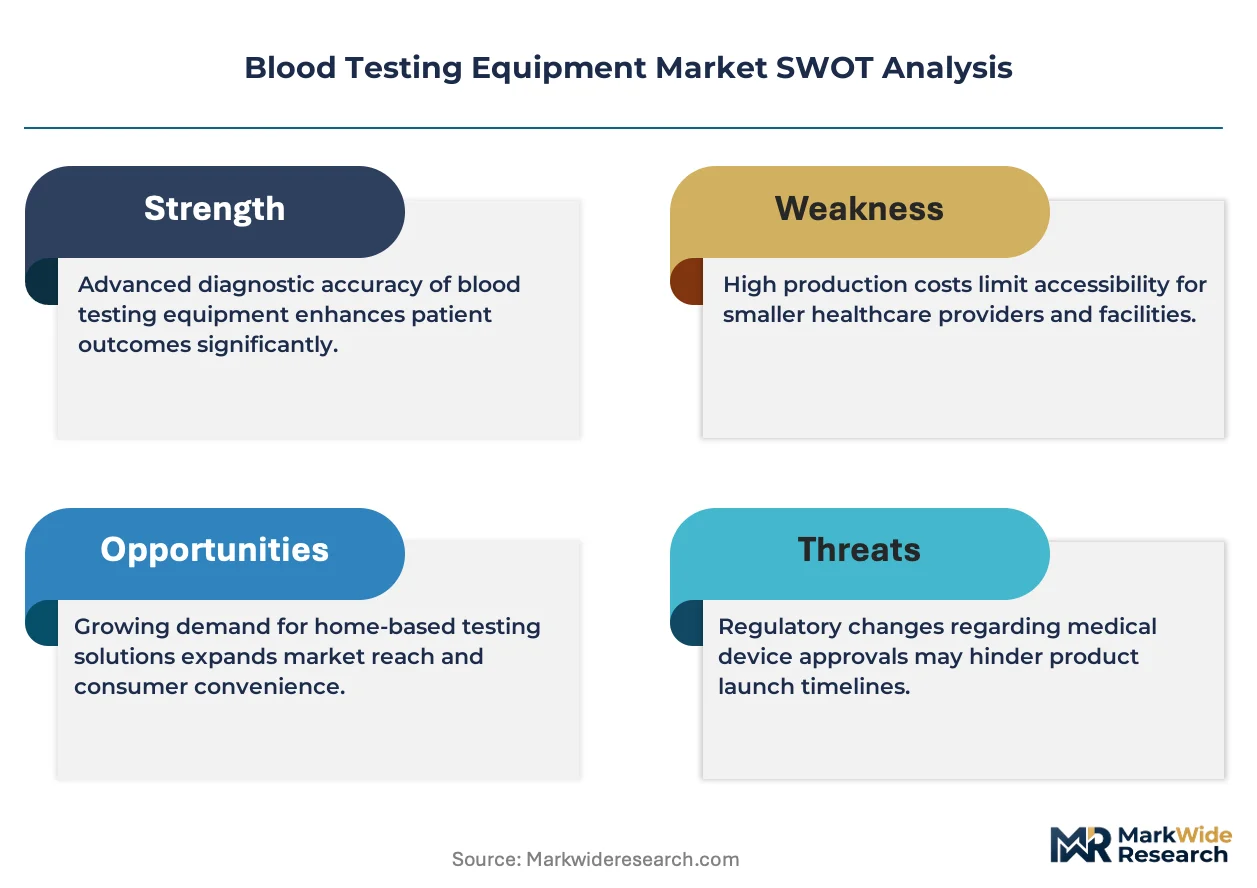
- Reagent lock-in economics:Closed-system consumables from dominant immunoassay manufacturers create switching costs that limit price competition and trap laboratories in multi-year contractual obligations with limited vendor flexibility.
- Specialized service technician scarcity:Field engineering talent capable of calibrating molecular diagnostics and maintaining PCR-based platforms concentrates in metropolitan hospital clusters, leaving rural and community laboratories with extended downtime exposure.
- EU In Vitro Diagnostic Regulation compliance burden:Stricter clinical evidence and post-market surveillance obligations for CE marking are extending product launch timelines and increasing regulatory capital requirements for manufacturers seeking European market access.
Strategic Opportunities
- Point-of-care decentralization:Emergency departments and satellite clinics are adopting cartridge-based blood gas and chemistry platforms that bypass central laboratory workflows, opening channel expansion for manufacturers with compact, operator-independent designs.
- India's diagnostic infrastructure buildout:The country's national health mission and expanding private hospital networks are creating first-time analyzer demand in tier-2 and tier-3 cities previously served by manual methods or referral laboratories.
- Artificial intelligence-enabled result interpretation:Machine learning algorithms integrated into hematology analyzers are flagging abnormal cell morphologies with reduced manual slide review, differentiating premium platforms in high-volume reference laboratories.
Industry Challenges
- Laboratory information system integration:Multi-vendor analyzer fleets generate incompatible data formats that require costly middleware solutions and extended validation periods before achieving seamless electronic medical record connectivity.
- Operator certification pathway fragmentation:CLIA personnel requirements vary by test complexity category, forcing hospital systems to maintain parallel training programs for high-complexity molecular diagnostics versus waived point-of-care devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Testing Equipment Market |
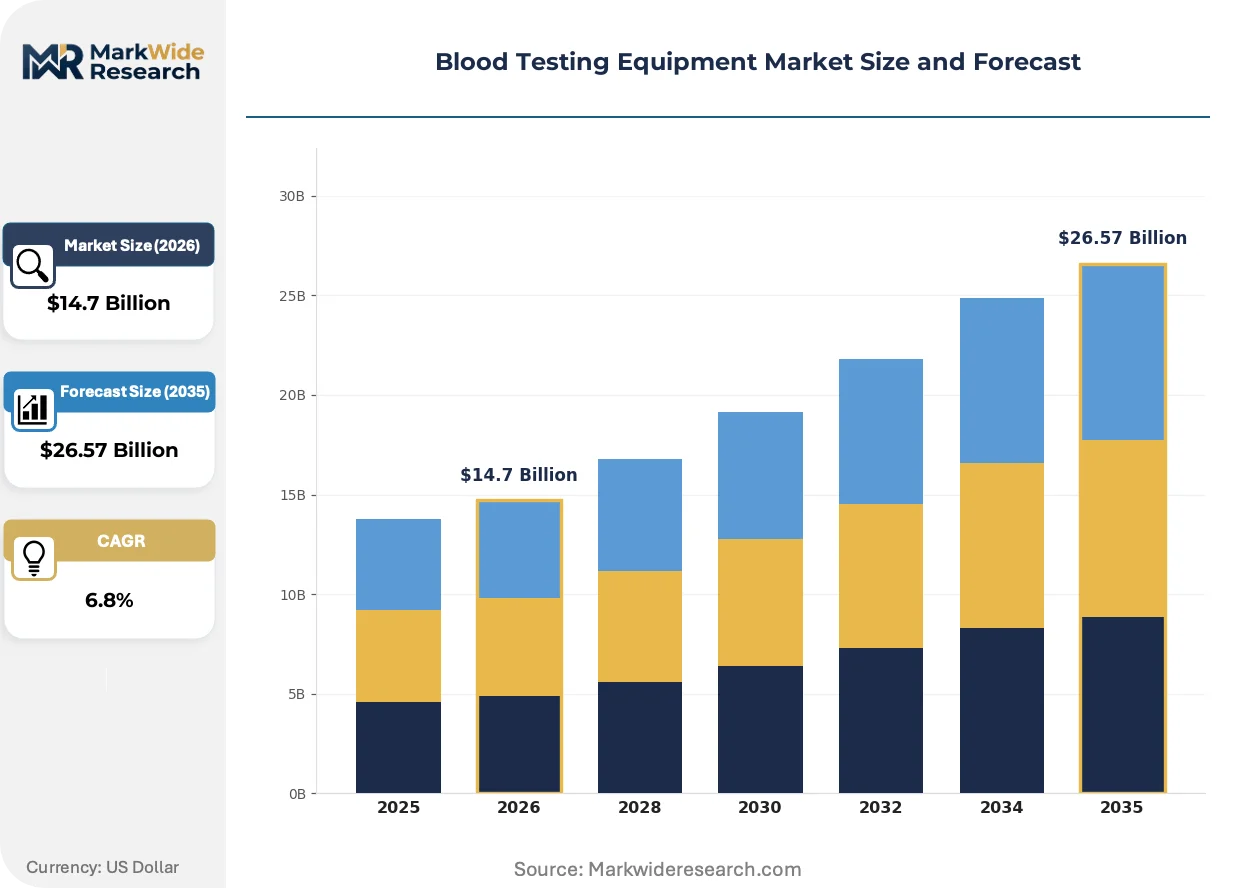
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunoassays, Hematology Analyzers, Coagulation Analyzers, Blood Gas Analyzers Technology: ELISA, PCR, CLIA, Microarray End User: Hospitals, Laboratories, Blood Banks, Diagnostic Centers Application: Transfusion Medicine, Disease Diagnosis, Health Monitoring, Clinical Research |
| Companies Covered | Roche Diagnostics, Abbott Laboratories, Thermo Fisher Scientific, Danaher Corporation, Siemens Healthineers, BD (Becton, Dickinson and Company), Bio-Rad Laboratories, Sysmex Corporation, bioMérieux, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Testing Equipment Market Emerging Trajectories
Automation architectures are converging with digital pathology and artificial intelligence, reshaping how cellular analysis interfaces with downstream clinical decision support and remote specialist consultation.
Next-generation hematology analyzers equipped with digital cell imaging and automated white blood cell differential classification are expanding into oncology and hematology reference laboratories. Academic medical centers in Germany and the United States are deploying these platforms to reduce manual microscopy review volumes. The technology is expanding into routine screening workflows by enabling remote pathologist consultation through cloud-based image sharing.
The EU In Vitro Diagnostic Regulation's stricter clinical evidence requirements are forcing manufacturers to redesign post-market surveillance systems and expand clinical trial footprints across multiple member states. Small and mid-sized diagnostic companies face disproportionate compliance costs relative to revenue scale. The regulation is compressing product launch timelines for innovative platforms while extending certification durations for legacy device families.
Hospital procurement committees are consolidating analyzer purchasing decisions at integrated delivery network headquarters rather than individual facility level. Service contracts and reagent supply agreements are bundling across multi-year terms with performance guarantees. This concentration is most visible in the United States, where Catholic health systems and for-profit chains are standardizing on single-vendor immunoassay ecosystems to leverage volume discounts and simplify inventory management.
Blood Testing Equipment Market Segmentation
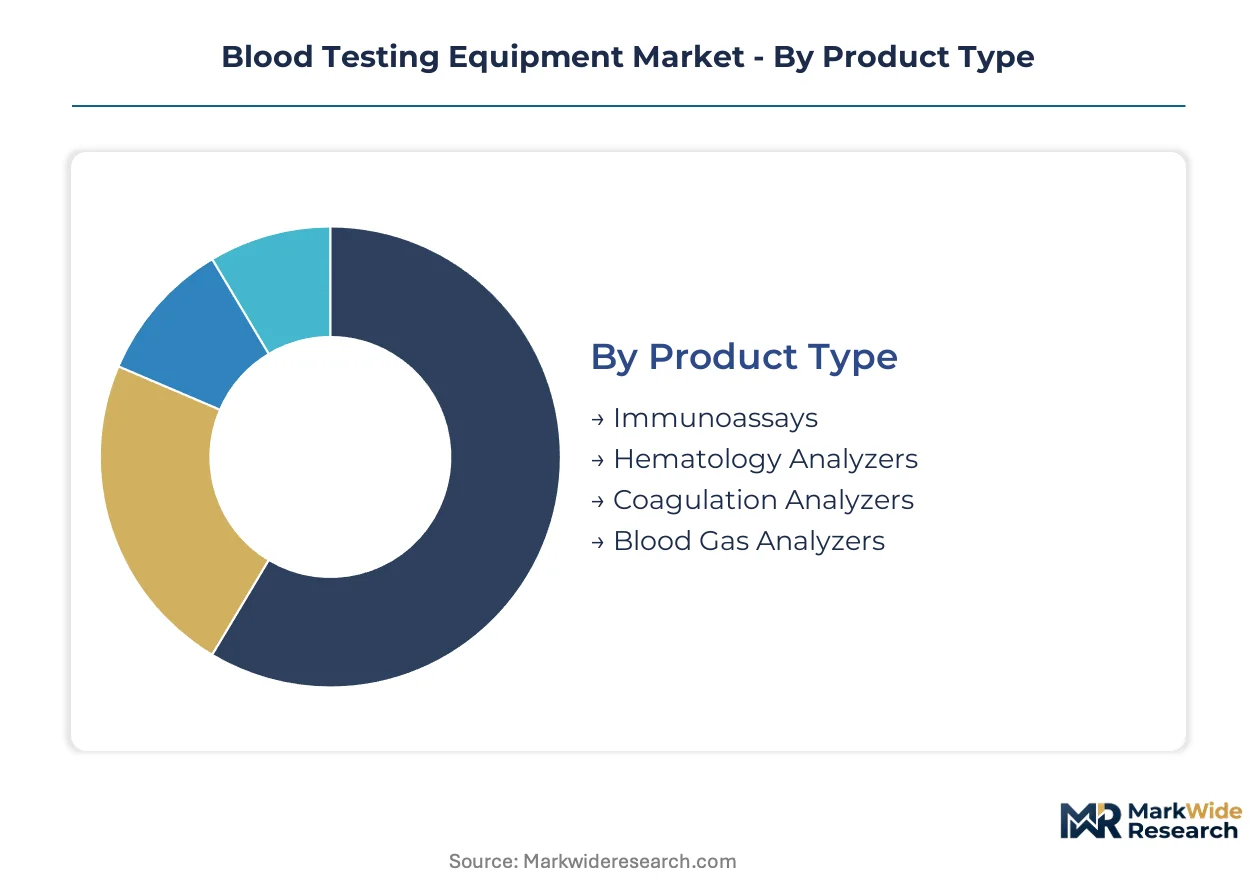
Segmentation in blood testing equipment reveals how procurement leverage concentrates around specific technology platforms and end-use settings. Understanding these divisions exposes where vendor lock-in economics operate strongest and where replacement cycles create openings for competitive displacement.
Product Type:
Supply concentration clusters around platforms with captive reagent ecosystems, creating divergent margin structures across the four equipment categories.
- Immunoassays:These systems detect antibodies, hormones, and infectious disease markers through antigen-antibody binding reactions. Demand concentrates in United States hospital emergency departments where troponin and procalcitonin turnaround times drive purchasing decisions; random-access processing capabilities now displace older batch-mode systems.
- Hematology Analyzers:Equipment quantifies red blood cells, white blood cells, and platelets for complete blood count diagnostics. United States integrated delivery networks standardize on single-vendor fleets across multi-site installations to simplify service contracts and reagent procurement.
- Coagulation Analyzers:Devices measure clotting factors and international normalized ratio for anticoagulation therapy monitoring.
- Blood Gas Analyzers:Critical care platforms assess pH, oxygen, carbon dioxide, and electrolyte levels from arterial samples.
Today's leader: Immunoassays. Tomorrow's challenger: Blood Gas Analyzers.
Technology:
Cost tier differentiation separates reference laboratory installations from point-of-care deployments, with capital intensity and operator training requirements determining addressable market breadth.
- ELISA:Enzyme-linked immunosorbent assay technology enables high-throughput antibody and antigen detection in 96-well microplate formats. Blood banks in the United States deploy these systems for infectious disease screening of donor units, though throughput limitations favor centralized processing over distributed testing.
- PCR:Polymerase chain reaction amplifies DNA and RNA sequences for molecular diagnostics with exceptional sensitivity. United States reference laboratories command premium positioning for PCR-based platforms, but field engineering scarcity restricts deployment in rural community settings.
- CLIA:Chemiluminescence immunoassay delivers automated, high-sensitivity detection for hormones and tumor markers.
- Microarray:Parallel genetic analysis enables multiplexed biomarker profiling from minimal sample volumes.
CLIA installations dominate current volume. PCR platforms are climbing the fastest as infectious disease and oncology panels expand.
End User:
Customer type fragmentation creates divergent purchasing pathways, with centralized procurement in hospital networks contrasting against decentralized decision-making in independent diagnostic facilities.
- Hospitals:Acute care facilities operate the largest installed base of multi-parameter analyzers across emergency, intensive care, and central laboratory departments. United States integrated delivery networks consolidate purchasing decisions at headquarters level, compressing vendor margins while demanding extended service-level agreements.
- Laboratories:Reference and clinical laboratories process high sample volumes for outsourced diagnostic services. India's tier-2 and tier-3 cities are creating first-time analyzer demand as private hospital networks expand beyond metropolitan centers.
- Blood Banks:Transfusion services require specialized screening platforms for donor unit testing.
- Diagnostic Centers:Independent facilities offer rapid turnaround testing for outpatient populations.
Hospitals anchor current procurement volume. Diagnostic Centers are gaining share fastest as point-of-care decentralization accelerates.
Application:
Volume concentration in routine screening contrasts against margin concentration in specialized therapeutic monitoring, reshaping R&D allocation across equipment manufacturers.
- Transfusion Medicine:Blood typing, cross-matching, and infectious disease screening ensure donor unit safety before transfusion. United States blood centers maintain high-throughput immunoassay lines for HIV, hepatitis, and Zika virus detection under FDA quality-system oversight.
- Disease Diagnosis:Pathogen identification, cancer marker detection, and metabolic disorder screening guide treatment initiation. Germany's academic medical centers deploy AI-enabled hematology analyzers to reduce manual microscopy review volumes in oncology workflows.
- Health Monitoring:Chronic disease management through periodic biomarker assessment tracks therapeutic efficacy.
- Clinical Research:Biomarker quantification supports pharmaceutical trial endpoints and epidemiological studies.
Disease Diagnosis commands current investment. Health Monitoring represents the steepest expansion trajectory as remote patient monitoring platforms proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as CE marking timelines under the EU In Vitro Diagnostic Regulation extend product launches, prompting some producers to prioritize FDA-cleared platforms for faster United States market entry while maintaining European operations for reference laboratory sales.
United States
Integrated delivery networks in Texas and Florida are consolidating hematology analyzer procurement into five-year enterprise contracts with performance guarantees. FDA quality-system requirements for in vitro diagnostic devices are compelling hospital laboratories in the Southeast to replace aging platforms. The Boston-Cambridge corridor anchors molecular diagnostics development as academic medical centers deploy AI-enabled cell classification systems.
Germany
Academic medical centers in Heidelberg and Munich are expanding digital pathology integration with hematology workflows. The EU In Vitro Diagnostic Regulation's post-market surveillance obligations are extending certification timelines for manufacturers serving the DACH region. Baden-Württemberg's industrial cluster concentrates blood gas analyzer engineering talent for critical care platform development.
China
Tier-2 city hospital networks in Sichuan and Shaanxi provinces are creating first-time demand for automated immunoassay platforms. NMPA regulatory pathways for imported in vitro diagnostic devices are streamlining for established manufacturers with domestic manufacturing partnerships. The Yangtze River Delta manufacturing base is expanding local production of hematology reagent consumables.
India
Private hospital chains in Karnataka and Telangana are installing random-access immunoassay analyzers in emergency departments previously served by referral laboratories. CDSCO medical device rules are harmonizing with international standards for Class C and D diagnostic equipment. Mumbai-Pune corridor distributors are building cold-chain logistics for reagent supply to tier-3 cities.
Japan
Metropolitan Tokyo hospitals are standardizing on single-vendor hematology fleets to reduce service contract complexity. PMDA consultation pathways for novel in vitro diagnostic algorithms are creating regulatory clarity for AI-integrated analyzers. The Osaka-Kobe industrial zone maintains specialized manufacturing for high-precision blood gas sensor components.
Blood Testing Equipment Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue point-of-care decentralization and cartridge-based miniaturization. The vendor base stratifies between integrated diagnostics conglomerates with captive reagent ecosystems and specialized instrument manufacturers serving reference laboratories. Three archetypes dominate: full-system integrators bundling hardware with multi-year consumable contracts; component specialists supplying optical modules and fluidic systems to original equipment manufacturers; and regional assemblers targeting price-sensitive hospital networks in emerging markets. Competitive moves concentrate on strategic partnerships for artificial intelligence integration and backward integration into critical sensor manufacturing.
Among Switzerland-based diagnostics conglomerates, Roche Diagnostics occupies a position exemplifying the captive reagent ecosystem archetype. Abbott Laboratories, with its Illinois incorporation, represents the point-of-care expansion vector. Thermo Fisher Scientific anchors the reference laboratory premium positioning tier. These three entities collectively illustrate how geographic origin and corporate structure map to divergent competitive strategies in automated hematology and molecular diagnostics platforms.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Abbott Laboratories |
| Thermo Fisher Scientific |
| Danaher Corporation |
| Siemens Healthineers |
| BD (Becton, Dickinson and Company) |
| Bio-Rad Laboratories |
| Sysmex Corporation |
| bioMérieux |
| Others |
Supply Flow & Price Mechanics
Optical sensor module costs cascade from Japanese precision manufacturers through blood gas analyzer assembly lines in Baden-Württemberg, ultimately stratifying into premium critical care platforms versus economy-tier hematology units for India's tier-3 hospital networks.
Pricing Analysis
Input-cost pass-through from specialized reagent chemistries and precision fluidic components drives three-tier pricing structure across premium, standard, and economy levels. FDA-cleared platforms with AI-enabled cell classification command brand premiums from United States academic medical centers, while price erosion runs through economy hematology analyzers as Chinese manufacturers expand domestic production of optical modules. Hospital procurement committees exhibit highest price sensitivity for routine CBC platforms, whereas intensive care units demonstrate lowest sensitivity for blood gas systems where turnaround time determines clinical value.
Supply Chain Analysis
Cold-chain logistics costs for temperature-sensitive reagent consumables concentrate supply risk in the Mumbai-Pune corridor for Indian distribution and the Rhine-Ruhr industrial zone for European fulfillment. Manufacturing draws from German precision engineering for hematology optics, Japanese sensor fabrication for blood gas electrodes, and Chinese polymer molding for disposable cartridges. Single-source vulnerability around rare-earth phosphors for chemiluminescence detection creates chokepoint exposure. Distribution runs through captive field service networks for high-complexity molecular diagnostics, contrasting with third-party logistics for point-of-care cartridge replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory demand as FDA quality-system mandates and EU In Vitro Diagnostic Regulation compliance timelines force replacement cycles across installed analyzer bases.
For Market Incumbents: Anchor defensive positioning through backward integration into blood gas sensor manufacturing and captive reagent production facilities in the Yangtze River Delta. Consolidate service contract bundling across United States integrated delivery networks to raise switching costs against emerging cartridge-based competitors. Prioritize CLIA complexity certification investments that emerging entrants cannot replicate without multi-year validation timelines. For New Entrants and Emerging Players: AI-enabled morphology classification offers technology-first wedge into reference laboratory workflows where manual slide review creates throughput bottlenecks. Target India's tier-2 private hospital networks with compact immunoassay platforms bypassing centralized laboratory infrastructure. Pursue cartridge-based miniaturization for emergency department point-of-care deployment as the most penetrable white-space channel. For Investors and Strategic Acquirers: Consolidation pressure builds where field engineering talent scarcity fragments service capabilities across rural laboratory networks. Five-to-ten year viability favors platforms with dual FDA-CE regulatory clearance and software-defined upgrade architectures. Target acquisition archetypes include regional assemblers with NMPA partnerships for Chinese market access. Monitor CDSCO harmonization progress with international standards as inflection signal for Indian infrastructure deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU In Vitro Diagnostic Regulation compliance enables European reference laboratory sales expansion. |
| Hospital System Partnership | Integrated delivery network contracts lock in multi-year reagent supply and service revenue streams. |
| Software Companion Development | AI-enabled result interpretation differentiates premium hematology platforms in high-volume screening. |
| Backward Integration into Sensors | In-house production of blood gas electrodes reduces dependency on Japanese component suppliers. |
| Reimbursement Strategy | CLIA complexity categorization secures favorable Medicare coverage for molecular diagnostic panels. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with hospital laboratory directors, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at diagnostics manufacturers. Secondary validation draws from FDA 510(k) filings, EUDAMED CE marking databases, hospital procurement records, and NMPA registration disclosures. Bottom-up analyzer shipment modeling triangulates against top-down market sizing from reagent consumable throughput estimates.
Granularity-level modeling disaggregates revenue across product type, technology platform, end-user facility class, and geographic regulatory cluster throughout the forecast period. CAGRs derive from replacement cycle analysis of installed base aging and penetration rate curves for point-of-care decentralization. Industry-specific inputs include CLIA laboratory registration trends, integrated delivery network consolidation patterns, and infectious disease panel menu expansion rates.
The model holds under stable regulatory enforcement timelines; deviation in FDA quality-system audit intensity or EU In Vitro Diagnostic Regulation grace period extensions would shift replacement demand curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Global Slide Stainer Market
Laboratory Equipment
Absorbance Micro Plate Reader Market
Laboratory Equipment
Lab Accessories Market
Laboratory Equipment
Scalable Clinical Chemistry Analyzers Market
Laboratory Equipment
Blood Processing and Storage Equipment Market
Laboratory Equipment
Multi-Cuvette Spectrophotometer Market
Laboratory Equipment
Hotplate Stirrers Market
Laboratory Equipment
Micropipette Puller Market
Laboratory Equipment
Benchtop Centrifuges Market
Laboratory Equipment
Laboratory Rockers and Shakers Market
Laboratory Equipment
Automated Nucleic Acid Extraction Systems Market
Laboratory Equipment
Laboratory Pulverizer Market
Laboratory Equipment
Capillary Blood Collection Tubes Market
Laboratory Equipment
Global Laboratory Grinders Market
Laboratory Equipment
North America Laboratory Hoods and Enclosure Market
Laboratory Equipment
Global Graduated Cylinder Market