
 Beaker Market | 2026-2036
Beaker Market Size, Share, and Industry Trends Forecast 2026-2036
Beaker Market Analysis
Chinese borosilicate glass furnace capacity is decoupling from European specialty glass output as domestic producers scale pyroceram-grade melting lines. Thermo Fisher Scientific leverages its North American distribution density to sustain institutional contract renewals across university systems. Corning Incorporated anchors premium laboratory glass supply through proprietary fusion-draw manufacturing that limits thermal expansion variance. Borosil Glass Works Ltd. competes on cost-adjusted furnace scale across Indian educational procurement channels.
A beaker is a cylindrical vessel with a flat bottom, graduated volume markings, and a pouring lip, manufactured from borosilicate glass or engineered polymers to withstand thermal shock between -80°C and 500°C; it serves as the fundamental liquid-handling container for quantitative preparation, mixing, and heating operations in analytical chemistry and biological processing. Borosilicate glass beakers retain dominant position in pharmaceutical research applications where USP Type I hydrolytic resistance certification governs parenteral drug contact compliance, while polypropylene variants capture fastest growth in high-throughput screening laboratories seeking disposability and breakage reduction. Griffin-form low-profile beakers concentrate margin pools in educational institutes where standardized 250ml and 500ml sizes dominate volume procurement tenders.
FDA cGMP guidelines for container-closure systems and EMA's Annex 1 sterile manufacturing revisions compel pharmaceutical beaker suppliers to document extractables and leachables profiles for each material grade. ISO 3819 dimensional standards and ASTM E960 thermal shock test protocols define minimum performance thresholds that exclude uncertified Asian imports from regulated laboratory environments. Stakeholders must monitor evolving USP-NF Chapter <661.1> plastic packaging system requirements and EU REACH candidate list expansions for boron oxide classification shifts that could reshape material substitution economics.
Market Dynamics
EMA material traceability rules and FDA cGMP container-closure guidelines are forcing pharmaceutical laboratories to document extractables and leachables profiles, reshaping supplier qualification and procurement patterns across regulated research environments.
Growth Catalysts
- EMA Annex 1 sterile manufacturing revisions:German pharmaceutical laboratories are expanding borosilicate glass purchases under tightened material traceability mandates, accelerating demand for certified USP Type I hydrolytic resistance documentation.
- Biologics testing volume expansion:East Asian contract manufacturing clusters are driving fastest demand concentration as monoclonal antibody and cell therapy pipelines scale analytical chemistry operations.
- Pyroceram-grade melting technology:Chinese domestic furnace capacity is decoupling from European specialty glass output through scaled production lines serving regional educational and industrial procurement channels.
Market Restraints
- Boron oxide supply concentration:Raw material processing for borosilicate glass concentrates in limited geographic corridors, exposing manufacturers to input cost volatility and trade flow disruptions.
- REACH candidate list expansion risk:ECHA classification review of boron oxide compounds threatens material substitution economics and could force reformulation investments across European supply chains.
- Polypropylene thermal performance ceiling:Engineered polymer variants face technical limitations above 121°C autoclave cycles, restricting penetration in pharmaceutical sterilization workflows.
Strategic Opportunities
- Indian educational procurement scale:Cost-adjusted furnace operations can capture standardized 250ml and 500ml Griffin-form tenders across government-funded laboratory infrastructure programs.
- High-throughput screening disposability:Polypropylene beaker variants represent emerging white space in automated drug discovery platforms seeking breakage reduction and workflow elimination of washing protocols.
- ISO 3819 certification harmonization:Dimensional standard convergence across Asian and European testing protocols creates pathway for unified product lines reducing SKU complexity.
Industry Challenges
- USP-NF Chapter 661.1 plastic packaging compliance:Polypropylene beaker suppliers face extended certification timelines and analytical chemistry investment requirements to document leachables profiles for pharmaceutical contact applications.
- Fusion-draw manufacturing scale barriers:Premium thermal expansion variance control requires capital-intensive proprietary equipment, limiting new entrant capacity in precision laboratory glass segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beaker Market |
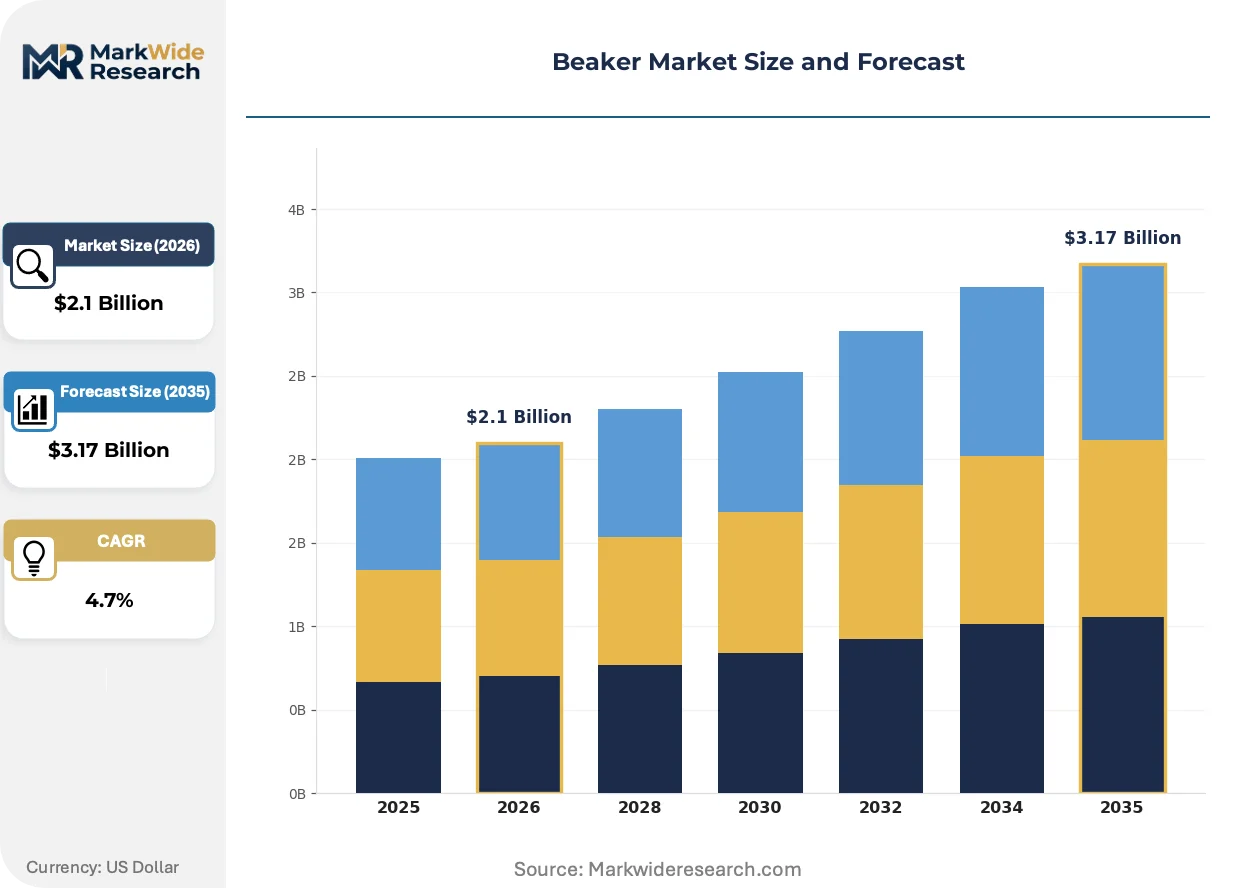
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.17 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cylindrical Beaker, Measuring Beaker, Griffin Beaker, Low Form Beaker Material: Borosilicate Glass, Polypropylene, Polycarbonate, Plastic Application: Chemistry Lab, Pharmaceutical Research, Educational Institutes, Testing Laboratories Size: 100ml, 250ml, 500ml, 1000ml |
| Companies Covered | Thermo Fisher Scientific Inc., Corning Incorporated, DWK Life Sciences, Borosil Glass Works Ltd., Eppendorf AG, VWR International LLC, Merck KGaA, Becton Bellco Glass Inc., Kimble Chase Life Science, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beaker Market Emerging Trajectories
Material science convergence and regulatory documentation requirements are compressing product development cycles while fragmenting procurement authority between centralized laboratory purchasing and decentralized research unit autonomy.
Pyroceram-grade ceramic glass formulations are overtaking conventional borosilicate in high-temperature pharmaceutical processing applications. Contract manufacturing organizations in East Asia are adopting these materials for sustained 500°C thermal shock resistance. The technology is overtaking legacy borosilicate margins in premium analytical chemistry segments where thermal performance differentiation commands pricing power.
REACH candidate list scrutiny of boron oxide compounds is accelerating material substitution investments across European pharmaceutical supply chains. ECHA regulatory pressure is forcing glass manufacturers to develop alternative thermal shock resistant formulations. German and Swiss laboratory equipment distributors are diversifying supplier bases to preempt supply disruption risks from potential substance restrictions.
Consolidated institutional purchasing through North American university system contracts is fragmenting into departmental-level procurement autonomy. Research unit principal investigators are gaining direct control over specialized vessel specifications, bypassing traditional centralized laboratory supply agreements. This behavioral shift concentrates in United States academic medical centers where federal research funding flexibility enables customized equipment procurement.
Beaker Market Segmentation
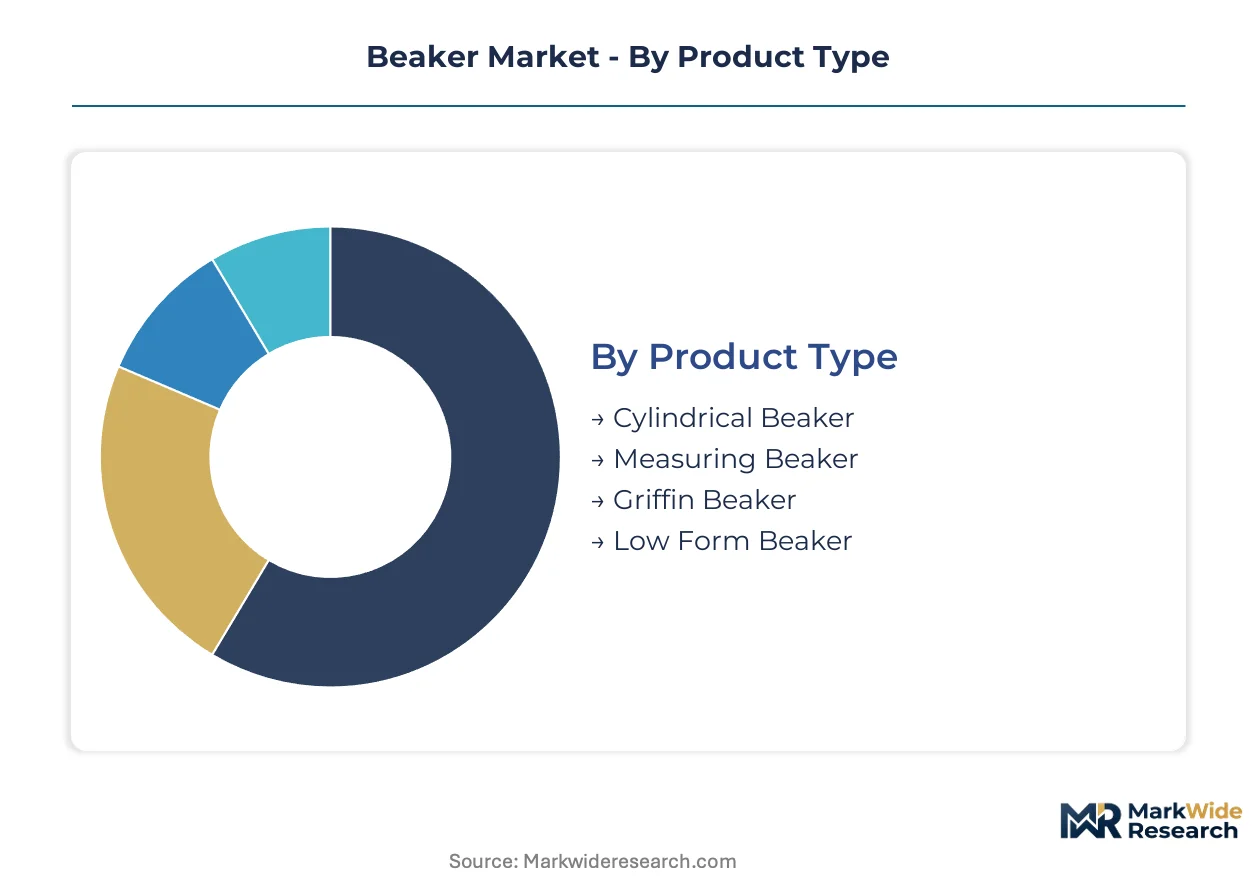
Beaker procurement patterns diverge sharply across end-use environments, with pharmaceutical laboratories demanding certified hydrolytic resistance while educational buyers prioritize cost-adjusted volume scale. Material specifications and dimensional standards create distinct margin pools that suppliers must navigate through differentiated furnace configurations and certification investments.
Product Type:
Research workflows and teaching protocols generate divergent vessel geometry requirements that shape manufacturing tooling and pricing architecture.
- Cylindrical Beaker:Standard straight-walled construction with uniform diameter from base to rim supports consistent stirring and heating across analytical chemistry operations. Pharmaceutical research laboratories in Germany specify these vessels under EMA material traceability mandates for parenteral drug contact applications.
- Griffin Beaker:Low-profile design with reinforced rim and spout optimizes stability during magnetic stirring and reduces breakage in high-throughput environments. Educational institutes in India concentrate procurement of 250ml and 500ml Griffin forms through government-funded laboratory infrastructure tenders.
- Measuring Beaker:Enhanced graduation precision supports quantitative preparation workflows in testing laboratories requiring volumetric accuracy.
- Low Form Beaker:Reduced height-to-diameter ratio improves thermal shock resistance and access for spatula mixing in biological processing applications.
Volume sits with Griffin-form educational procurement; growth tilts toward cylindrical pharmaceutical specifications.
Material:
Thermal performance thresholds and regulatory compliance burdens segment buyers into distinct material loyalty clusters with divergent substitution economics.
- Borosilicate Glass:Silica-boron oxide matrix delivers thermal shock resistance between -80°C and 500°C with USP Type I hydrolytic resistance certification for parenteral drug contact. German pharmaceutical laboratories are expanding purchases under tightened EMA material traceability rules that document extractables and leachables profiles.
- Polypropylene:Engineered polymer variant captures automated drug discovery platforms seeking disposability and elimination of washing protocols. High-throughput screening laboratories in East Asian contract manufacturing clusters are driving fastest adoption despite thermal ceiling limitations at 121°C autoclave cycles.
- Polycarbonate:Transparent thermoplastic offers impact resistance and visual clarity for educational demonstrations where breakage reduction outweighs thermal performance requirements.
- Plastic:Generic polymer category encompasses cost-optimized variants for single-use applications in non-regulated testing environments.
Revenue concentrates in borosilicate pharmaceutical grades; expansion is steepest in polypropylene disposability segments.
Application:
Regulatory intensity and funding sources create four distinct procurement authority structures with incompatible supplier qualification requirements.
- Pharmaceutical Research:FDA cGMP container-closure guidelines and EMA Annex 1 sterile manufacturing revisions compel extractables documentation and USP Type I certification. German laboratories are expanding borosilicate glass purchases under tightened material traceability mandates.
- Educational Institutes:Centralized government procurement channels in India concentrate standardized 250ml and 500ml volume tenders where cost-adjusted furnace scale determines supplier selection.
- Chemistry Lab:Analytical chemistry operations in East Asian contract manufacturing clusters are scaling biologics testing volume fastest.
- Testing Laboratories:Quality control and reference standard preparation workflows require ISO 3819 dimensional compliance.
Margin pools favor pharmaceutical research certification; volume expansion is strongest in educational institute tenders.
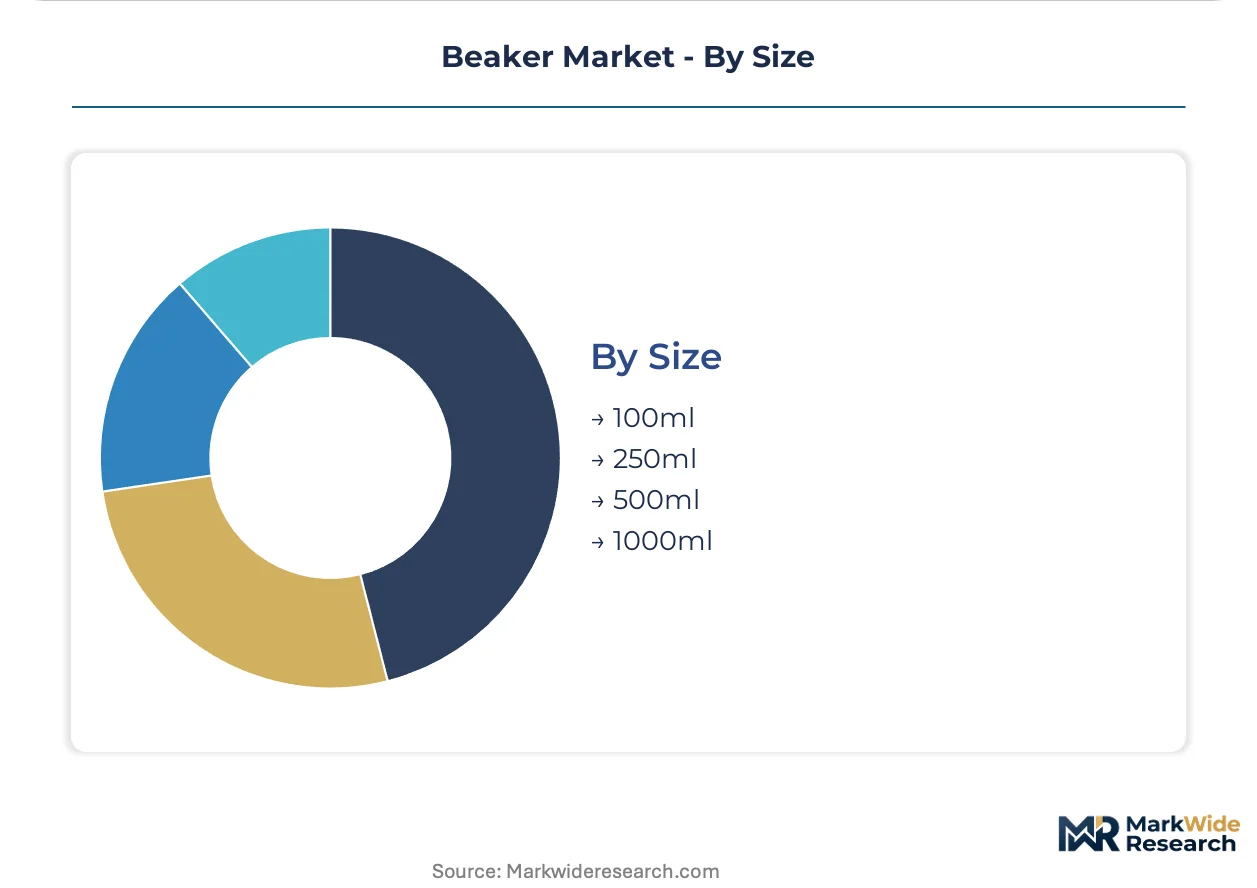
Size:
Procurement standardization and workflow integration determine which volumetric increments sustain manufacturing economies.
- 250ml:Mid-scale vessel dominates educational procurement tenders and routine analytical preparation workflows across chemistry laboratories.
- 500ml:Standardized capacity captures Griffin-form low-profile demand in government-funded laboratory infrastructure programs.
- 100ml:Compact scale serves micro-scale synthesis and reagent preparation in high-throughput screening applications.
- 1000ml:Large-format capacity supports pilot-scale processing and media preparation in biologics manufacturing.
Procurement volume clusters at 250ml and 500ml educational specifications; specialized demand is climbing fastest at 100ml screening scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boron oxide processing corridors in Turkey and Russia anchor raw material flows for borosilicate glass production. Laboratory equipment demand concentrates in pharmaceutical manufacturing clusters across Germany, China, India, and the United States. Regulatory divergence between EMA traceability mandates and FDA container-closure guidelines is reshaping regional procurement patterns.
United States
Academic medical centers in Boston and the San Francisco Bay Area are fragmenting institutional purchasing into departmental-level procurement autonomy. FDA cGMP guidelines for container-closure systems compel extractables documentation across parenteral drug research workflows. Federal research funding flexibility enables principal investigators to bypass centralized laboratory supply agreements for specialized vessel specifications.
Germany
Pharmaceutical research laboratories in Baden-Württemberg and Bavaria are expanding borosilicate glass purchases under tightened EMA material traceability rules. EMA Annex 1 sterile manufacturing revisions mandate documented leachables profiles for each material grade. The Rhine-Main cluster anchors premium laboratory glass distribution through specialized scientific equipment distributors.
China
East Asian contract manufacturing clusters in Jiangsu and Zhejiang provinces are driving fastest biologics testing volume expansion. Domestic producers are scaling pyroceram-grade melting lines, decoupling furnace capacity from European specialty glass output. NMPA alignment with international pharmacopeial standards is accelerating certification investments for export-oriented manufacturers.
India
Government-funded laboratory infrastructure programs in Maharashtra and Karnataka concentrate standardized 250ml and 500ml Griffin-form procurement tenders. CDSCO pharmaceutical manufacturing guidelines are tightening material documentation requirements for domestic drug discovery operations. Cost-adjusted furnace scale determines supplier selection across educational institute channels.
Japan
Precision analytical chemistry operations in the Kanto and Kansai regions sustain demand for low thermal expansion variance vessels. PMDA quality standards for pharmaceutical contact materials reinforce borosilicate glass preference in regulated research environments. Osaka-based scientific equipment distributors are diversifying supplier bases to mitigate REACH-related boron oxide supply risks.
Beaker Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue disposability and automated workflow integration. The market structure consolidates around three to five dominant furnace operators with proprietary fusion-draw capabilities, while mid-scale fabricators compete on cost-adjusted volume for educational procurement channels. Strategic archetypes include premium thermal-performance specialists, scale-driven educational suppliers, and polymer-based disposability innovators. Competitive moves concentrate on backward integration into boron oxide supply and ISO 3819 certification harmonization across Asian and European testing protocols.
Among North American scientific equipment conglomerates, Thermo Fisher Scientific Inc. and Corning Incorporated exemplify divergent positioning archetypes. Thermo Fisher Scientific leverages distribution density to anchor institutional contract renewals across fragmented university procurement environments. Corning Incorporated represents the premium-tier thermal-performance vector through proprietary manufacturing approaches that limit expansion variance. DWK Life Sciences occupies a mid-scale position serving diversified laboratory segments across European and North American regulated environments.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Corning Incorporated |
| DWK Life Sciences |
| Borosil Glass Works Ltd. |
| Eppendorf AG |
| VWR International LLC |
| Merck KGaA |
| Becton Bellco Glass Inc. |
| Kimble Chase Life Science |
| Others |
Supply Flow & Price Mechanics
Pyroceram-grade melting technology adoption in Chinese furnace operations is compressing legacy borosilicate cost curves while fragmenting supplier concentration across East Asian and European production corridors. This dual shift simultaneously erodes margin pools for conventional glass manufacturers and redistributes procurement leverage toward buyers with volume-scale educational tenders.
Pricing Analysis
Warranty-backed USP Type I certification and extractables documentation bundles separate premium pharmaceutical-grade borosilicate from unbundled educational variants. Three-tier pricing structure across premium, standard, and economy levels reflects thermal performance variance, ISO 3819 dimensional precision, and after-sales calibration support. Cost compression in economy-tier Griffin-form procurement is intensifying because Indian government tenders prioritize furnace-scale efficiency over certification depth. Educational institutes exhibit highest price sensitivity; pharmaceutical research laboratories demonstrate lowest sensitivity due to regulatory compliance mandates.
Supply Chain Analysis
Regional distribution centers in Germany, China, and India anchor hub-and-spoke patterns serving pharmaceutical, educational, and industrial procurement channels. Boron oxide processing draws from Turkish and Russian raw material corridors, while fused silica and alumina additives hinge on East Asian mineral processing capacity. Single-source vulnerability concentrates in specialty boron compound refining, exposing manufacturers to ECHA REACH candidate list disruption. Distribution runs through scientific equipment distributors with certified cold-chain capabilities for thermal-shock-sensitive glassware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The beaker market functions as a cost-of-compliance story where EMA Annex 1 sterile manufacturing revisions erect documentation barriers that entrench certified incumbents against uncertified imports.
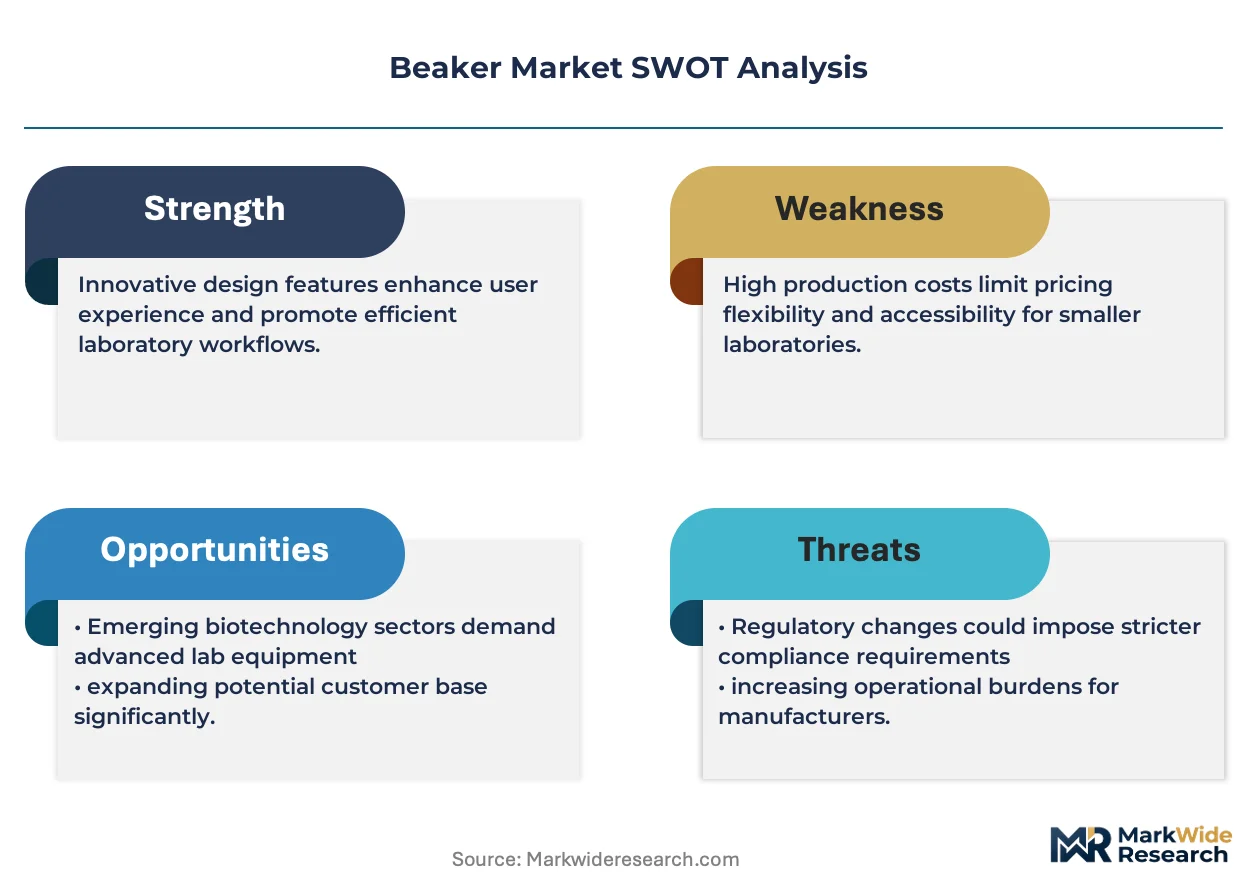
For Market Incumbents: Lock in backward integration into boron oxide supply corridors to preempt REACH-related raw material disruption. Expand pyroceram-grade furnace capacity in East Asian manufacturing clusters to capture biologics testing volume growth. Certification investment in USP-NF Chapter 661.1 plastic packaging compliance represents the critical defensive lever against polypropylene substitution threats. For New Entrants and Emerging Players: Launch via direct-to-laboratory digital channels targeting decentralized procurement autonomy in United States academic medical centers. Polypropylene disposability for high-throughput screening applications offers the most penetrable white space, with automated drug discovery platforms seeking workflow elimination of washing protocols. Griffin-form educational tenders in India provide volume-scale entry with lower certification barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in trade-sale acquisition by scientific equipment conglomerates seeking thermal-performance specialization or regional distribution density. Long-term viability favors furnace operators with proprietary fusion-draw capabilities and documented extractables profiles across the 5-10 year regulatory tightening horizon. The signal to watch is ECHA boron oxide classification rulings that would force material substitution investments and reshape acquisition target valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Boron Oxide Supply | Captive raw material sourcing mitigates ECHA REACH disruption risks for European furnace operators. |
| Pyroceram-Grade Melting Capacity Expansion | 500°C thermal shock resistance commands pricing power in East Asian biologics manufacturing clusters. |
| USP-NF Chapter 661.1 Certification Investment | Plastic packaging compliance unlocks pharmaceutical contact applications for polypropylene variants. |
| ISO 3819 Harmonization Across Asian Protocols | Unified dimensional standards reduce SKU complexity for multi-regional laboratory equipment distributors. |
| Direct-to-Laboratory Digital Channel Launch | Bypasses fragmented institutional purchasing to reach principal investigators in United States academic centers. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with furnace operations managers, laboratory procurement directors, scientific equipment distributors, and pharmaceutical quality assurance leads. FDA cGMP guidance documents, EMA Annex 1 revision drafts, and ISO 3819 dimensional standards provided regulatory benchmarks. Bottom-up triangulation across furnace capacity utilization rates and top-down validation against educational procurement tender volumes ensured cross-verification.
Data-stream reconciliation across production volume surveys, import-export trade flows, and end-use procurement patterns informed the analytical framework over the projection horizon. Segmentation dimensions modeled include material type, product geometry, application environment, and regional regulatory cluster. CAGRs were derived from slope analysis of normalized production indices and procurement tender growth trajectories. Boron oxide price volatility coefficients and EMA material traceability compliance cost curves served as industry-specific forecast inputs.
REACH candidate list expansion, NMPA certification alignment delays, and pyroceram-grade technology substitution rates are the dominant revision risks that could alter trajectory assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Laboratory Furniture Market
Laboratory Equipment
Molecular Microplate Readers and Washers Market
Laboratory Equipment
Laboratory Supplies Market
Laboratory Equipment
Microplate Reader Market
Laboratory Equipment
Asia Pacific Cell Counting Market
Laboratory Equipment
Middle East and Africa Laboratory Hoods and Enclosure Market
Laboratory Equipment
Laboratory Rockers and Shakers Market
Laboratory Equipment
Micropipette Puller Market
Laboratory Equipment
Hotplate Stirrers Market
Laboratory Equipment
Western Blotting Processors Market
Laboratory Equipment
Blood Bank Analyzers Market
Laboratory Equipment
Laboratory Vacuum Drying Oven Market
Laboratory Equipment
Centrifuge Tubes Market
Laboratory Equipment
Automated Blood Analyzer Market
Laboratory Equipment
Laboratory Furnaces Market
Laboratory Equipment
Cuvettes Market