
 Hospital Acquired Infections Therapeutic Market | 2026-2036
Hospital Acquired Infections Therapeutic Market Size, Share, and Industry Trends Forecast 2026-2036
Hospital Acquired Infections Therapeutic Market Intelligence
Pricing for novel combination antibiotics is decoupling from generic vancomycin and metronidazole benchmarks by a widening margin. Pfizer Inc. leverages its hospital-directed sales infrastructure to sustain premium positioning for branded anti-MRSA agents. Merck & Co., Inc. anchors its franchise through backward integration into active pharmaceutical ingredient supply for carbapenem-class therapies.
Hospital acquired infections therapeutics encompass systemic and topical pharmaceutical agents designed to treat pathogen-specific infections contracted during inpatient stays, with minimum inhibitory concentration thresholds guiding formulary selection against resistant gram-negative and gram-positive organisms. These therapies serve the primary commercial purpose of reducing attributable mortality, shortening length of stay, and avoiding reimbursement penalties tied to preventable infection events under value-based care frameworks. Antibiotics occupy the dominant revenue position within product type segmentation, while intravenous delivery mode captures the highest clinical acuity cases and corresponding margin pools. Postoperative care and intensive care unit applications lead volume consumption, though wound management represents the fastest-expanding addressable base as ambulatory surgical site infection protocols tighten.
FDA's Qualified Infectious Disease Product designation and EMA's PRIME eligibility pathway for antibacterial therapies reshape clinical trial incentives and accelerated review timelines. The CDC's National Healthcare Safety Network surveillance requirements directly influence hospital formulary standards and therapeutic procurement priorities across US acute care systems. Stakeholders must monitor how CMS inpatient prospective payment system readmission penalties evolve to determine whether prophylactic therapeutic protocols expand or contract relative to diagnostic-driven treatment models.
Market Dynamics
Hospital formulary committees are tightening minimum inhibitory concentration thresholds for gram-negative coverage, forcing therapeutic portfolios toward pathogen-specific rather than broad-spectrum positioning.
Growth Catalysts
- FDA Qualified Infectious Disease Product designation:Accelerated review timelines incentivize developers to pursue novel antibacterial mechanisms. This pathway compresses regulatory cycles for therapies targeting resistant organisms.
- Intensive care unit expansion:Rising critical care bed capacity across United States health systems drives concentrated demand for intravenous anti-MRSA and carbapenem-class agents. ICU protocols prioritize rapid pathogen identification.
- Reimbursement penalty structures:CMS inpatient prospective payment system readmission penalties for preventable infections push hospitals toward prophylactic therapeutic protocols. Value-based care frameworks reward reduced length of stay.
Market Restraints
- Active pharmaceutical ingredient concentration:Carbapenem API supply concentrates among Asian contract manufacturers, creating single-source vulnerability for finished dose producers. Backward integration remains capital-intensive.
- Generic price compression:Vancomycin and metronidazole commoditization sets aggressive benchmarks that constrain novel combination antibiotic pricing power. Formulary substitution protocols accelerate this pressure.
- Antimicrobial stewardship mandates:CDC National Healthcare Safety Network surveillance requirements restrict empirical prescribing, narrowing the addressable patient pool for broad-spectrum launches.
Strategic Opportunities
- Ambulatory surgical site infection protocols:Wound management applications represent underpenetrated expansion space as outpatient procedure volumes rise. Topical formulations command differentiated margins.
- EMA PRIME eligibility pathway:European accelerated assessment for antibacterial therapies opens parallel market access with reduced clinical trial burden. Developers can sequence regulatory filings.
- Diagnostic-therapeutic convergence:Rapid pathogen identification platforms paired with targeted antimicrobial selection enable precision dosing. Hospital laboratories are integrating pharmacokinetic guidance systems.
Industry Challenges
- Infectious disease pharmacology expertise scarcity:Specialized clinical trial design capabilities for antibacterial development remain concentrated among limited contract research organizations. Talent competition intensifies.
- Formulary access timeline compression:Pharmacy and therapeutics committee review cycles are shortening while evidence requirements expand, forcing compressed health economics and outcomes research generation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hospital Acquired Infections Therapeutic Market |
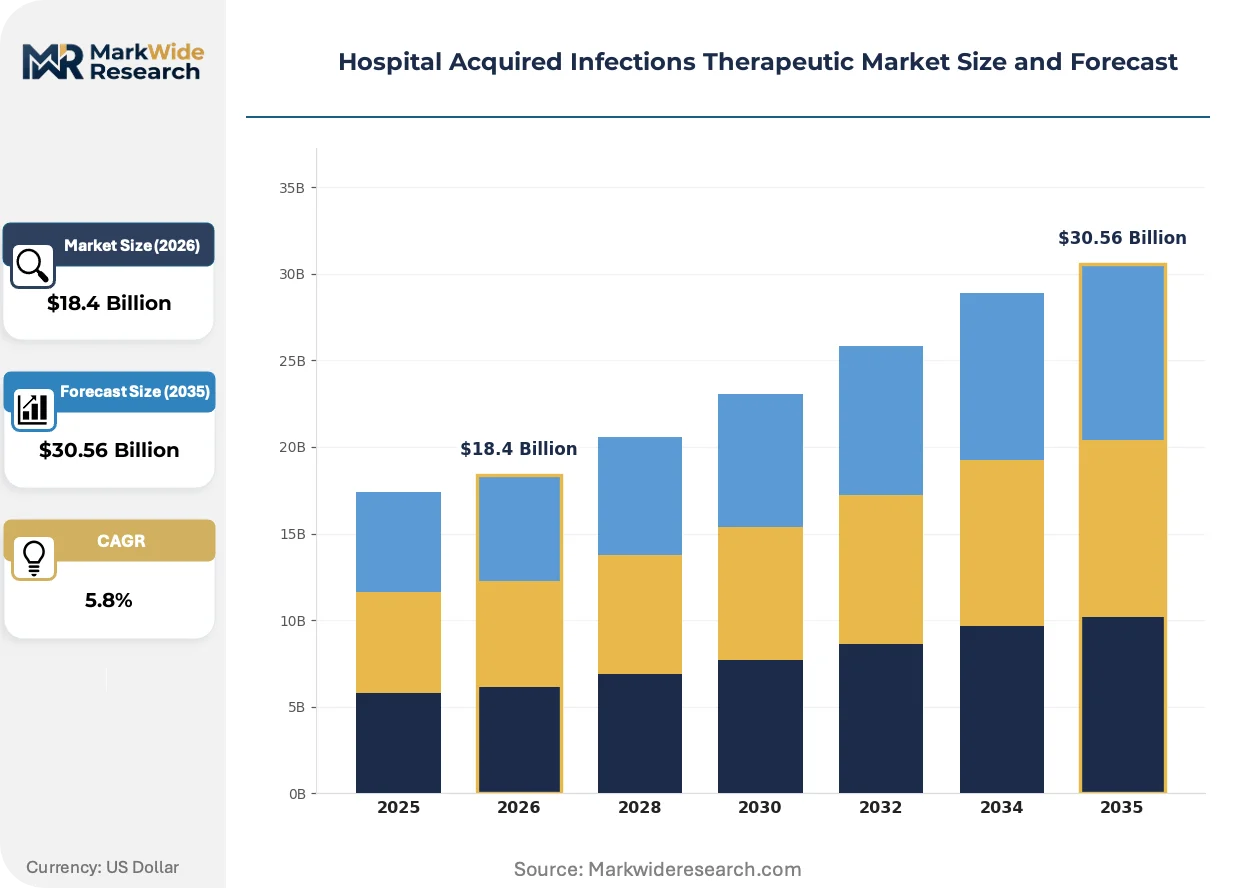
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $30.56 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antifungals, Antivirals, Disinfectants Application: Postoperative Care, Intensive Care Units, Wound Management, Catheterization Delivery Mode: Intravenous, Oral, Topical, Inhalation End User: Hospitals, Long-term Care Facilities, Outpatient Clinics, Rehabilitation Centers |
| Companies Covered | Merck & Co., Inc., Pfizer Inc., Bayer AG, GlaxoSmithKline Plc, Daiichi Sankyo Company, Limited, AbbVie Inc., F. Hoffmann-La Roche Ltd, Abbott Laboratories, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hospital Acquired Infections Therapeutic Market Strategic Shifts & Innovations
Beta-lactamase inhibitor combinations and rapid diagnostic integration are actively restructuring how hospitals match therapies to resistance profiles, compressing the gap between pathogen identification and targeted treatment initiation.
Next-generation beta-lactamase inhibitors paired with established antibiotic backbones are rewriting clinical practice patterns for multidrug-resistant Enterobacteriaceae. Intensive care units in tertiary referral centers are adopting these combinations ahead of formulary standardization. This mechanism expansion is compressing the utility window for last-reserve polymyxin therapies.
EMA's PRIME eligibility pathway for antibacterial therapies is reshaping European clinical trial incentives and accelerated review timelines. Developers are prioritizing quality-of-life endpoints and hospital length-of-stay reductions in protocol design. Gram-negative resistant organism indications are capturing the majority of designations, redirecting pipeline investment toward unmet resistance threats.
Centralized procurement through hospital consolidation is concentrating purchasing power among integrated delivery networks and altering vendor relationship structures. Group purchasing organizations are unbundling traditional bundled contracts into unit-dose and formulary-tiered arrangements. United States acute care systems are leading this contractual restructuring, with multi-hospital systems negotiating direct manufacturer agreements.
Hospital Acquired Infections Therapeutic Market Segmentation
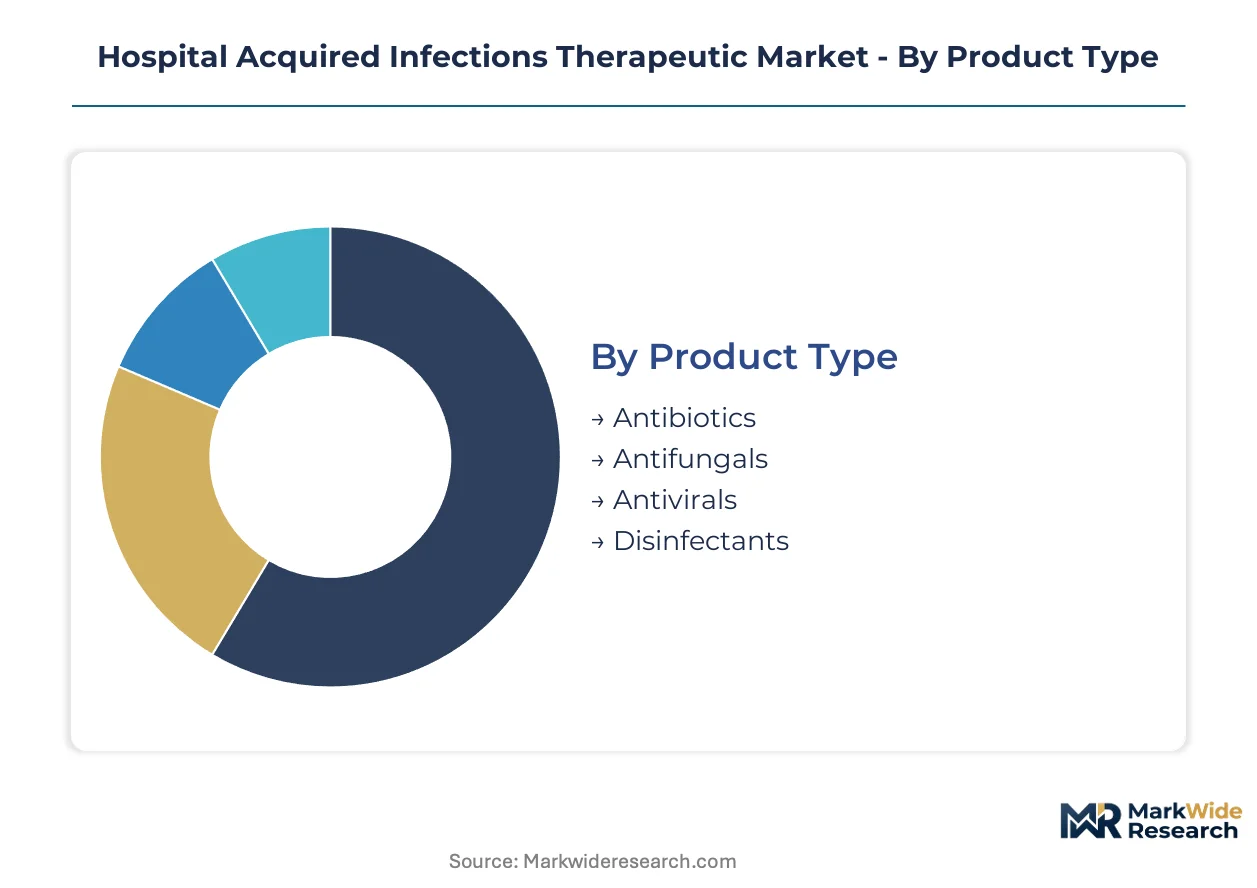
Hospital acquired infections therapeutic markets fragment across four distinct axes. Product type determines reimbursement tier and formulary access. Application and delivery mode dictate clinical workflow integration. End user concentration shapes procurement scale and contract structure.
Product Type:
Antibiotic mechanism classes anchor formulary architecture and drive resistance surveillance priorities.
- Antibiotics:Systemic antibacterial agents targeting gram-positive and gram-negative organisms dominate inpatient therapeutic protocols. Beta-lactamase inhibitor combinations capture critical care demand in United States tertiary centers as resistance profiles shift. FDA Qualified Infectious Disease Product designations cluster within this segment.
- Antifungals:Azole and echinocandin-class therapies address Candida and Aspergillus infections in immunocompromised populations. Hematology-oncology units and transplant centers drive concentrated consumption amid prolonged neutropenia protocols.
- Antivirals:Agents targeting influenza, RSV, and emerging viral pathogens serve outbreak containment scenarios. Pandemic preparedness stockpiling creates episodic demand spikes distinct from chronic therapeutic patterns.
- Disinfectants:Surface and instrument sterilization chemistries complement pharmaceutical interventions. Environmental services departments manage procurement separate from pharmacy therapeutics.
Mature deployment sits with antibiotics. Newer deployment is concentrated in antifungals.
Application:
Clinical setting determines acuity tier, dosing intensity, and monitoring requirements.
- Postoperative Care:Surgical site infection prophylaxis and treatment protocols consume broad-spectrum agents across orthopedic, cardiac, and abdominal procedures. United States hospital systems align perioperative antibiotic selection with CDC National Healthcare Safety Network surveillance benchmarks.
- Intensive Care Units:Ventilator-associated pneumonia and bloodstream infection therapies require rapid pathogen identification and targeted escalation. Carbapenem-class and novel anti-MRSA agents concentrate in tertiary referral center ICUs.
- Wound Management:Chronic and acute wound infections drive topical antimicrobial demand. Outpatient surgical site infection protocols are expanding addressable volume as ambulatory procedure migration accelerates.
- Catheterization:Central line-associated bloodstream infection prevention and treatment protocols guide antiseptic-impregnated device adjacencies. Long-term care facilities manage indwelling catheter complications.
Volume concentration remains in postoperative care. Steepest expansion trajectory is occurring in wound management.
Delivery Mode:
Route of administration aligns with bioavailability requirements, patient acuity, and care setting transitions.
- Intravenous:Hospital inpatient and critical care settings rely on parenteral administration for rapid therapeutic levels. Anti-MRSA glycopeptides and carbapenems command premium positioning through this channel.
- Oral:Step-down therapy and outpatient completion regimens utilize bioavailable agents. Fluoroquinolones and linezolid serve transition-of-care protocols.
- Topical:Wound bed preparation and localized infection control employ antimicrobial dressings and ointments. Margin structures differ substantially from systemic formulations.
- Inhalation:Nebulized antibiotics address ventilator-associated pneumonia and cystic fibrosis exacerbations. Specialized delivery infrastructure limits penetration outside respiratory therapy departments.
Established infrastructure supports intravenous administration. Inhalation delivery is gaining procedural adoption.
End User:
Facility type determines formulary autonomy, procurement scale, and regulatory oversight intensity.
- Hospitals:Acute care systems manage the largest therapeutic volumes through centralized pharmacy and therapeutics committees. Integrated delivery networks concentrate purchasing power across multi-hospital systems.
- Long-term Care Facilities:Skilled nursing and assisted living settings manage catheter-associated and pressure ulcer infections. Antimicrobial stewardship mandates apply with modified surveillance requirements.
- Outpatient Clinics:Ambulatory surgical centers and infusion suites handle postoperative prophylaxis and step-down therapy. Same-day discharge protocols expand oral antimicrobial dispensing.
- Rehabilitation Centers:Post-acute settings manage wound care and device-related infections during functional recovery. Therapy duration extends beyond typical inpatient stays.
Procurement scale concentrates in hospitals. Outpatient clinics are expanding fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Longwood Medical and Academic Area anchors North American infectious disease research concentration, with Massachusetts General Hospital and Brigham and Women's Hospital driving clinical trial enrollment for novel antibacterial therapies.
United States
Integrated delivery networks in Texas and Florida are consolidating procurement for anti-MRSA and carbapenem-class agents. FDA Qualified Infectious Disease Product designations cluster among developers in the Boston-Cambridge corridor. The Research Triangle Park in North Carolina hosts contract research organizations specializing in antibacterial clinical trial design.
Germany
University hospitals in Berlin and Munich are adopting rapid diagnostic platforms for bloodstream infection protocols. EMA PRIME eligibility pathways accelerate assessment timelines for developers targeting resistant gram-negative organisms. The Rhine-Main biotech cluster around Frankfurt houses active pharmaceutical ingredient manufacturers supplying carbapenem intermediates.
Japan
Tokyo's tertiary referral centers are expanding intensive care unit capacity with targeted antimicrobial stewardship programs. PMDA's Sakigake designation system provides priority review for therapies addressing multidrug-resistant pathogens. The Kansai region around Osaka maintains concentration in generic antibiotic manufacturing for regional export.
India
Hyderabad and Ahmedabad manufacturing zones produce carbapenem active pharmaceutical ingredients for global finished dose supply. CDSCO accelerated approval pathways for anti-infectives address domestic hospital-acquired infection burden. Karnataka's biotech corridor in Bangalore houses contract development organizations supporting international trial execution.
Switzerland
Basel's pharmaceutical cluster maintains backward integration into beta-lactamase inhibitor production for combination therapies. Swissmedic's adaptive licensing frameworks support iterative evidence generation for novel antibacterial mechanisms. The Lake Geneva region hosts diagnostic-therapeutic convergence partnerships between device manufacturers and antibiotic developers.
Hospital Acquired Infections Therapeutic Market Key Industry Players
Premium-margin players sit above commodity-margin players across formulary tier positioning, with branded anti-MRSA agents commanding substantial pricing separation from generic vancomycin benchmarks. The vendor base concentrates among multinational pharmaceutical corporations with hospital-directed sales infrastructure and mid-cap specialists with targeted resistance-focused portfolios. Three archetypes dominate: diversified giants with infectious disease franchises, antibacterial pure-plays with QIDP-designated pipelines, and generic manufacturers with cost-optimized carbapenem supply. Competitive moves center on backward integration into active pharmaceutical ingredient supply and diagnostic-therapeutic partnership formations.
Within the diversified pharmaceutical tier, Merck & Co., Inc. and Pfizer Inc. occupy positions shaped by hospital procurement consolidation, with the former exemplifying API supply integration strategies and the latter representing premium branded positioning through established anti-MRSA infrastructure. Among European-headquartered players, Bayer AG and GlaxoSmithKline Plc sit within portfolios where infectious disease therapeutic allocation reflects broader strategic prioritization decisions.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Pfizer Inc. |
| Bayer AG |
| GlaxoSmithKline Plc |
| Daiichi Sankyo Company, Limited |
| AbbVie Inc. |
| F. Hoffmann-La Roche Ltd |
| Abbott Laboratories |
| AstraZeneca |
| Others |
Cost & Logistics Intelligence
Carbapenem active pharmaceutical ingredient costs cascade through finished dose pricing tiers, with Asian contract manufacturing concentration compressing margins for European and North American formulators while enabling premium positioning for backward-integrated multinationals serving United States integrated delivery networks.
Pricing Analysis
Value-based hospital reimbursement anchors therapeutic pricing to length-of-stay reduction and readmission avoidance under CMS inpatient prospective payment system frameworks. Three-tier pricing structure across premium branded anti-MRSA agents, standard beta-lactamase inhibitor combinations, and economy generic vancomycin segments reflects formulary tier placement and FDA Qualified Infectious Disease Product designation status. Cost compression in the generic tier is intensifying because hospital consolidation drives centralized procurement with aggressive substitution protocols. Academic medical centers and tertiary referral centers demonstrate lowest price sensitivity, while long-term care facilities and outpatient clinics face highest budget constraint pressure.
Supply Chain Analysis
Freight cost volatility for temperature-controlled parenteral formulations compounds API sourcing complexity, with cold chain requirements adding 15-20% logistics premium over standard pharmaceutical distribution. Carbapenem API production concentrates in India, China, and South Korea, drawing from 6-APA and 7-ACA intermediate feedstocks sourced from dedicated fermentation facilities. Single-source vulnerability for sterile finished dose capacity represents the dominant structural risk, with FDA inspection backlogs creating approval bottlenecks for alternative suppliers. Distribution runs through group purchasing organization contracts to integrated delivery network central pharmacies, with unit-dose repackaging occurring at regional distribution centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA Qualified Infectious Disease Product designation requirements create a cost-of-compliance moat that advantages developers with established regulatory affairs infrastructure and disadvantages capital-constrained entrants lacking specialized infectious disease pharmacology expertise.
For Market Incumbents: Deepen backward integration into beta-lactamase inhibitor API supply to defend against Asian contract manufacturer pricing volatility and secure formulary tier placement for combination therapies. Expand sterile manufacturing capacity in United States and European regulatory jurisdictions to reduce FDA inspection queue exposure. Prioritize diagnostic-therapeutic partnership formations with rapid pathogen identification platform developers to lock in precision dosing protocols ahead of formulary standardization. For New Entrants and Emerging Players: Begin with topical antimicrobial formulations for ambulatory surgical site infection protocols, where wound management application growth outpaces systemic antibiotic commoditization and margin structures remain differentiated. Target long-term care facility and rehabilitation center channels where antimicrobial stewardship mandates apply with modified surveillance requirements and formulary access timelines extend beyond acute care compression. Pursue EMA PRIME eligibility pathway as primary go-to-market angle to reduce clinical trial burden and sequence regulatory filings ahead of United States FDA submission. For Investors and Strategic Acquirers: FDA QIDP designation grant rate acceleration is the leading indicator that antibacterial pipeline viability is improving and acquisition multiples for late-stage assets will expand. Frame long-term viability around 5-10 year resistance surveillance cycles and hospital formulary consolidation trajectories rather than quarterly revenue volatility. Target antibacterial pure-plays with designated pipelines and established hospital-directed sales infrastructure as acquisition archetypes. Monitor CDC National Healthcare Safety Network resistance profile updates as the inflection signal for therapeutic class demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Supply | Merck's carbapenem intermediate captive production insulates against Asian contract manufacturer concentration risk. |
| Diagnostic-Therapeutic Partnership | Rapid pathogen ID platform alliances enable precision dosing protocols that secure formulary tier placement. |
| EMA PRIME Eligibility Pathway | European accelerated assessment reduces clinical trial burden for developers targeting resistant gram-negative organisms. |
| Hospital System Direct Contracting | Multi-hospital integrated delivery network agreements bypass group purchasing organization bundling constraints. |
| Topical Formulation Development | Wound management applications expand addressable volume as ambulatory surgical site infection protocols tighten. |
Research Approach
Document review covered FDA QIDP designation databases, EMA PRIME eligibility registries, CDC NHSN surveillance reports, and hospital procurement database extracts, complemented by interviews with infectious disease drug development executives, regulatory affairs leads, hospital formulary directors, and group purchasing organization contract managers. Secondary validation drew from SEC 10-K pharmaceutical segment disclosures, clinical trial registry filings, and CMS reimbursement rulemaking dockets. Bottom-up therapeutic volume modeling triangulated against top-down hospital expenditure estimates from national health accounts.
Segment-level revenue outputs across the projection horizon reflect disaggregated modeling of antibiotic mechanism classes, delivery mode infrastructure requirements, and end-user facility type procurement scale. The analytical framework incorporated treatment line positioning, administration route bioavailability constraints, patient acuity stratification, and regional regulatory cluster reimbursement intensity. CAGRs derived from logistic growth curve fitting to historical formulary adoption patterns, adjusted for antimicrobial stewardship mandate implementation timelines and hospital consolidation trajectories. Resistance surveillance trend inputs and ICU bed capacity expansion forecasts informed demand elasticity assumptions.
Underlying measurement precision varies by segment; intravenous antibiotic and intensive care unit application categories carry tighter precision than topical formulation and outpatient clinic channels due to procurement data availability. Forecasts reflect assumptions regarding FDA review timeline stability, API supply chain continuity, and CMS penalty structure persistence that could revise projections if regulatory or geopolitical conditions shift. Stakeholders should weight assumptions against their own operating context and local formulary committee dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Germicidal UV Lamp Market
Infection Control
Catheter-Related Bloodstream Infections (Crbsis) Market
Infection Control
Asia-Pacific Hand Sanitizer Market
Infection Control
Infection Surveillance Solutions Market
Infection Control
Medical Washer Disinfector Market
Infection Control
UV Sterilizer Pouch Market
Infection Control
Alcohol Wipes Market
Infection Control
UV Disinfection Equipment Market
Infection Control
Global High Level Disinfection Services Market
Infection Control
North America Hand Sanitizer Market
Infection Control
Salivary Gland Infection Treatment Market
Infection Control
Medical Disinfectant Wipes Market
Infection Control
Global Viral Clearance Services Market
Infection Control
Point of Care Infection Control Market
Infection Control
North America Bloodstream Infection Testing Market
Infection Control
Global Disease Control and Prevention Vaccine Market