
 Asia Pacific Cell Counting Market | 2026-2036
Asia Pacific Cell Counting Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Cell Counting Market Analysis
Japan's METI circular economy roadmap for laboratory equipment is restructuring procurement criteria across pharmaceutical quality control departments. Thermo Fisher Scientific leverages its automated cell counter installed base to sustain service contract renewals in Japanese clinical laboratories. Beckman Coulter competes on high-throughput flow cytometry configurations for stem cell research facilities in South Korea. Sysmex Corporation dominates hematology-adjacent cell counting through its domestic distribution density and regulatory rapport with PMDA.
Cell counting encompasses quantitative enumeration of viable and non-viable cells using optical, electrical, or laser-based detection principles, with modern instruments achieving throughput exceeding 10,000 cells per second and viability discrimination via fluorescent dye exclusion. The technique underpins bioprocess monitoring, drug toxicity screening, and regenerative medicine quality control across Asia Pacific manufacturing and research operations. Flow cytometers command the highest average selling prices among product types, while automated cell counters generate volume from biotech company expansions in Singapore and Australia. Pharmaceutical firms represent the most concentrated end-user segment, though research laboratories in India drive replacement demand for legacy hemocytometers as institutional funding for life sciences rises.
China's NMPA enforces GMP Annex 1 compliance for cell therapy manufacturing facilities, while India's CDSCO aligns medical device rules with ISO 13485 for in-vitro diagnostic instruments. Australia's TGA maintains parallel conformity assessment pathways that expedite registration for instruments already approved by Japan's PMDA. Stakeholders must track divergence between national medical device classification systems, as reclassification of automated cell counters from Class I to Class II in select jurisdictions would extend approval timelines and reshape vendor entry strategies.
Market Dynamics
China's NMPA enforcement of GMP Annex 1 for cell therapy manufacturing is forcing instrument replacement cycles across bioclusters, while METI's circular economy roadmap in Japan restructures procurement criteria for laboratory equipment durability and serviceability.
Growth Catalysts
- Cell therapy manufacturing scale-up:Biotech companies in China's Yangtze River Delta are outfitting new GMP facilities with automated counting workflows to meet batch release requirements for CAR-T and stem cell products.
- Regulatory harmonization:Australia's TGA maintains parallel conformity assessment pathways that expedite registration for instruments already approved by Japan's PMDA, reducing vendor entry friction.
- Fluorescent viability discrimination:Modern instruments achieving throughput exceeding 10,000 cells per second with dye exclusion protocols are displacing manual hemocytometry in high-volume bioprocess monitoring applications.
Market Restraints
- Instrument capital intensity:Flow cytometers command the highest average selling prices among product types, constraining adoption in Indian research laboratories with limited institutional funding.
- Classification divergence risk:Reclassification of automated cell counters from Class I to Class II in select Asia Pacific jurisdictions would extend approval timelines and reshape vendor registration strategies.
- Laser and optical component supply:Concentration of precision optical source manufacturing outside the region creates vulnerability for instrument makers dependent on imported detection modules.
Strategic Opportunities
- India's research laboratory upgrade cycle:Rising institutional funding for life sciences is driving replacement demand for legacy hemocytometers across academic and government research facilities.
- Singapore biotech expansion:Automated cell counters generate volume from biotech company expansions in the city-state's biomedical manufacturing corridor.
- Service contract unbundling:Vendors can capture recurring revenue streams by separating hardware sales from calibration, validation, and preventive maintenance packages in Japanese clinical laboratories.
Industry Challenges
- GMP validation complexity:Cell therapy manufacturers face extended qualification timelines for automated counting systems under China's tightened GMP annexes for cell-based products.
- Technical workforce scarcity:Flow cytometry configuration expertise for stem cell research facilities remains concentrated among specialists in South Korea and Japan, limiting deployment speed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Cell Counting Market |
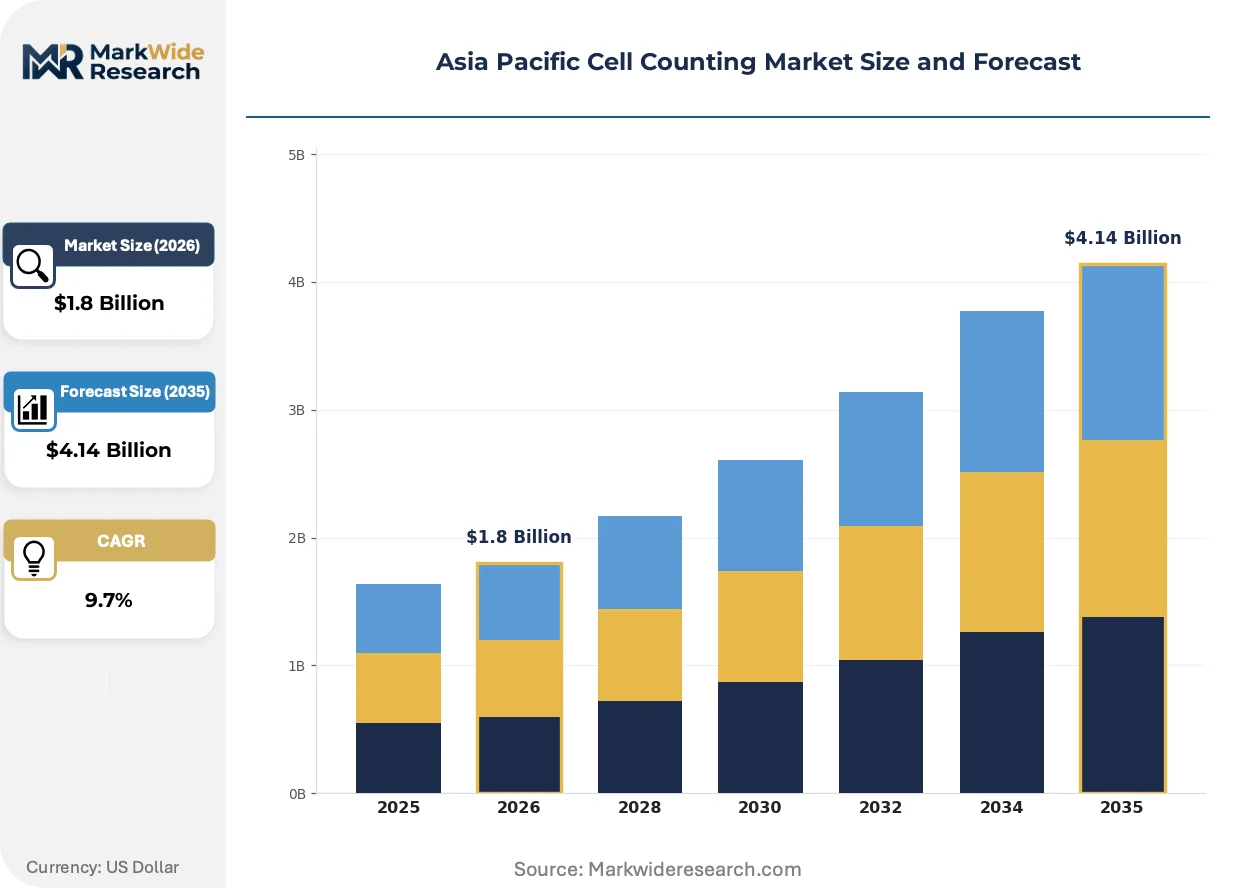
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flow Cytometers, Hemocytometers, Image Cytometers, Automated Cell Counters End User: Pharmaceutical Firms, Research Laboratories, Clinical Laboratories, Biotech Companies Technology: Optical, Electrical, Acoustic, Laser-Based Application: Cell Viability Testing, Cell Proliferation, Apoptosis Analysis, Stem Cell Research |
| Companies Covered | Agilent Technologies, Merck KGaA, Thermo Fisher Scientific, HORIBA Ltd., Olympus Corporation, Beckman Coulter, PerkinElmer, Sysmex Corporation, Bio-Rad Laboratories, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Cell Counting Market Emerging Trajectories
Instrument architecture is fragmenting into configurable subsystems as vendors respond to divergent end-use requirements across bioprocess monitoring, clinical diagnostics, and research applications. Three developments are restructuring competitive positioning.
Automated cell counter hardware is modularizing around swappable detection cartridges that switch between brightfield, fluorescence, and impedance modes without full instrument replacement. Biotech companies in Singapore and Australia are adopting these configurations to reduce capital redundancy across multiple assay types. The shift is compressing replacement cycles for monolithic instruments while expanding addressable market for subsystem vendors.
Japan's METI circular economy roadmap mandates extended service life and component recyclability for laboratory equipment procured by pharmaceutical quality control departments. The policy is forcing vendors to redesign instrument chassis for field-upgradeable electronics and standardized fastener systems. Japanese clinical laboratories are now weighting total cost of ownership over acquisition price in competitive tenders.
CDMOs and CROs in China's bioclusters are consolidating instrument procurement under single-vendor managed service agreements rather than capital purchase models. The shift transfers calibration burden and obsolescence risk to suppliers while locking in multi-year consumable commitments. This pattern is most visible in the Yangtze River Delta, where new GMP facility buildouts favor operational expenditure structures over balance-sheet asset ownership.
Asia Pacific Cell Counting Market Segmentation
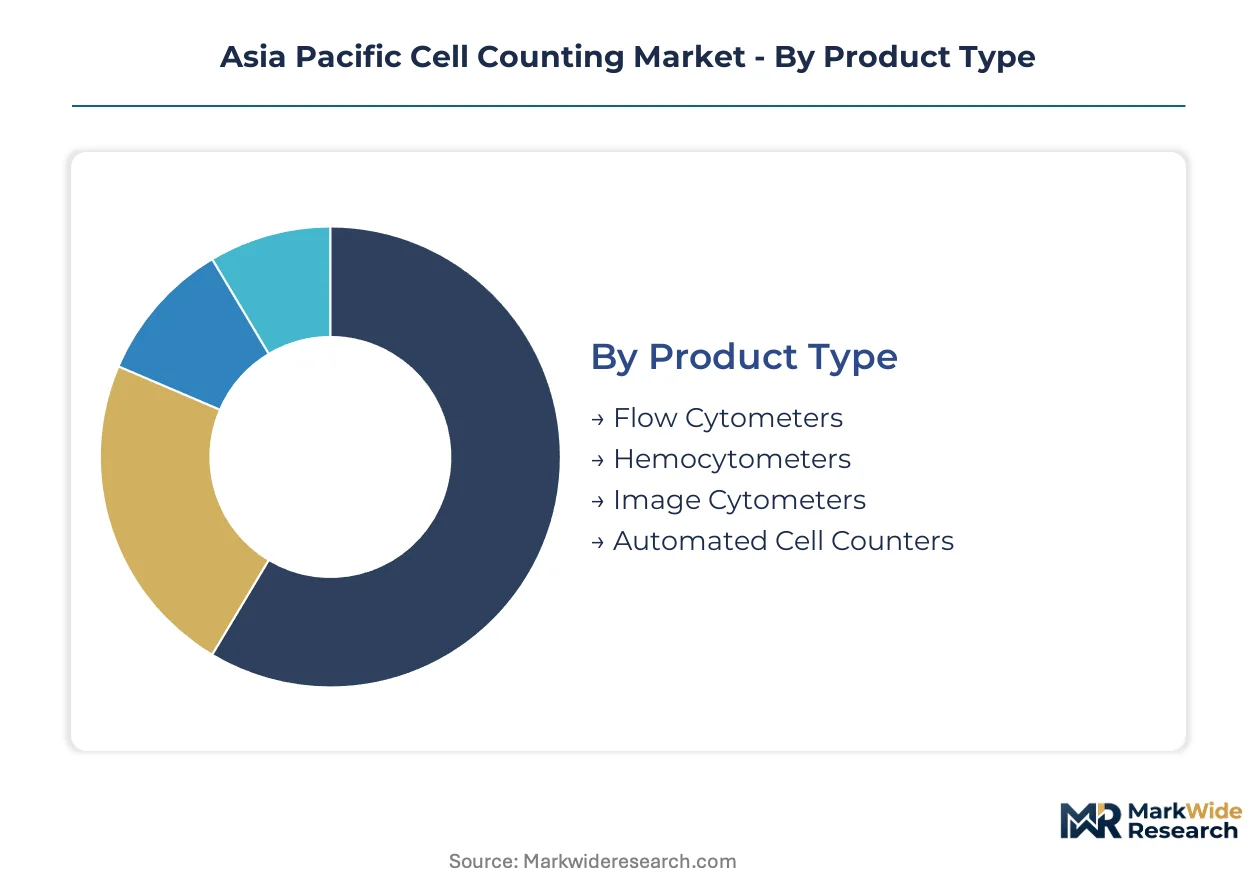
Segmentation in the Asia Pacific cell counting market reveals how regulatory requirements and application complexity fragment procurement patterns across bioprocess, clinical, and research environments. Instrument classification under national medical device frameworks determines approval timelines and vendor entry strategies for each product category.
Product Type:
Flow cytometers and automated cell counters face divergent certification burdens under China's NMPA and Japan's PMDA, with laser-based systems requiring additional electromagnetic compliance testing in South Korea.
- Flow Cytometers:Multi-parameter laser detection systems achieve throughput exceeding 10,000 cells per second with fluorescent viability discrimination. Pharmaceutical quality control departments in Japan's Kanto region prioritize these configurations for stem cell product release testing despite capital intensity constraints.
- Automated Cell Counters:Benchtop instruments with swappable brightfield and fluorescence cartridges are displacing manual methods in China's Yangtze River Delta bioclusters. CDMOs favor operational expenditure models that bundle hardware with calibration services under GMP Annex 1 compliance requirements.
- Hemocytometers:Manual counting chambers persist in Indian academic laboratories with limited institutional funding for automated alternatives.
- Image Cytometers:Camera-based detection systems serve mid-throughput applications in Australian research facilities leveraging TGA-PMDA parallel approval pathways.
Automated cell counters sit at the top of the volume ranking, with image cytometers climbing the fastest as modular architectures reduce capital redundancy.
End User:
Customer type determines service contract structures and consumable lock-in intensity, with pharmaceutical manufacturers demanding validation documentation that academic laboratories rarely require.
- Pharmaceutical Firms:Concentrated demand from CAR-T manufacturers in China's Suzhou and Shanghai bioclusters drives high-throughput instrument configurations with 21 CFR Part 11 compliant software. Batch release protocols mandate redundant counting systems that inflate capital deployment per facility.
- Biotech Companies:Singapore's biomedical manufacturing corridor generates volume from automated workflows as cell therapy developers scale from research to GMP manufacturing. Vendors capture recurring revenue through unbundled calibration and preventive maintenance packages.
- Research Laboratories:Indian government institutes replace legacy hemocytometers as life sciences funding expands, though flow cytometry expertise scarcity limits deployment speed.
- Clinical Laboratories:Japanese hospital networks prioritize total cost of ownership under METI circular economy mandates, weighting serviceability and component recyclability in procurement tenders.
Pharmaceutical firms command the highest average selling prices per installation, while biotech companies expand most quickly as cell therapy manufacturing scales across the region.
Technology:
Detection modality selection hinges on throughput requirements and fluorescent reagent compatibility, with electrical impedance methods offering label-free alternatives for certain bioprocess monitoring applications.
- Laser-Based:Solid-state optical sources enable multi-color fluorescence detection for complex immunophenotyping workflows. South Korean stem cell research facilities concentrate demand for these configurations despite supply chain vulnerability from imported precision optical components.
- Optical:Brightfield and phase-contrast systems serve viability testing in Australian CROs with moderate throughput requirements and capital constraints.
- Electrical:Impedance-based counting provides rapid enumeration without fluorescent dyes, appealing to continuous bioprocess monitoring applications in Chinese CDMOs.
- Acoustic:Emerging label-free detection methods remain confined to specialized research applications with limited commercial penetration.
Laser-based detection dominates revenue per unit, with electrical methods gaining share fastest as bioprocess applications prioritize real-time monitoring without reagent consumption.
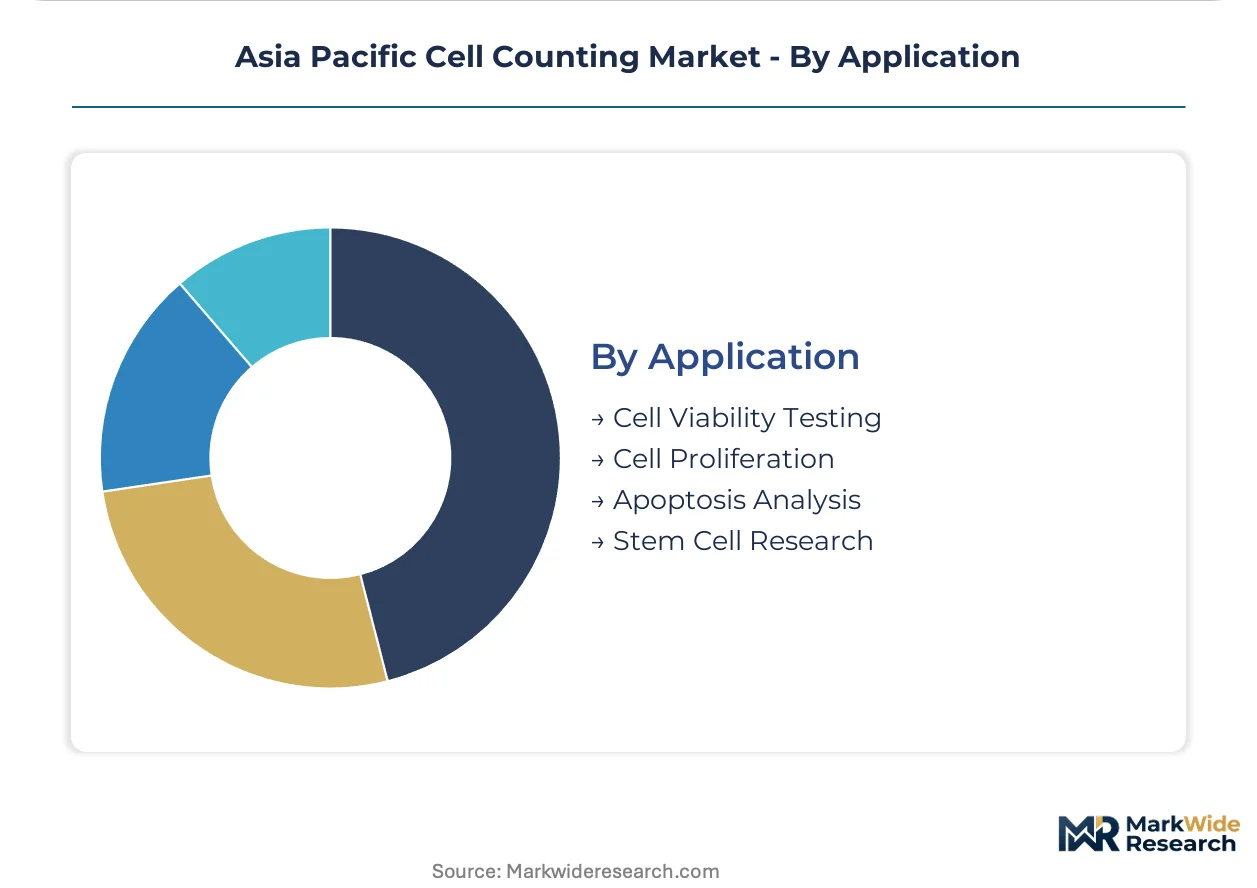
Application:
Assay purpose shapes instrument specification requirements, with regulatory filing support demanding higher documentation burdens than exploratory research.
- Cell Viability Testing:Dye exclusion protocols with automated fluorescence detection underpin batch release decisions for cell therapy products. China's NMPA tightened GMP annexes accelerate instrument replacement cycles as manufacturers qualify new systems for regulatory submission support.
- Stem Cell Research:Multi-parameter phenotyping requires high-dimensional flow cytometry configurations with specialized expertise concentrated in South Korean and Japanese facilities. Technical workforce scarcity constrains deployment speed for complex instrument installations.
- Apoptosis Analysis:Annexin V and caspase detection assays serve drug toxicity screening in pharmaceutical development pipelines.
- Cell Proliferation:Dilution tracking and metabolic assays support bioprocess optimization in monoclonal antibody manufacturing.
Cell viability testing anchors current revenue concentration, with stem cell research applications showing the steepest expansion trajectory as regenerative medicine manufacturing scales across Asia Pacific bioclusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell counting instrumentation first achieved commercial scale in Japanese hematology laboratories during the 1980s, establishing quality benchmarks that now propagate across Asia Pacific biomanufacturing corridors. The industry's regional footprint reflects this lineage, with technology transfer patterns shaping current procurement hierarchies.
China
CAR-T manufacturers in Suzhou and Shanghai bioclusters drive demand for high-throughput automated counters with 21 CFR Part 11 compliant software. NMPA enforcement of GMP Annex 1 for cell therapy manufacturing forces instrument replacement cycles as facilities qualify new systems for batch release protocols. The Yangtze River Delta concentrates CDMO buildouts favoring operational expenditure models over capital purchases.
Japan
Pharmaceutical quality control departments in the Kanto region prioritize flow cytometry configurations for stem cell product release testing. METI's circular economy roadmap restructures procurement criteria around total cost of ownership, weighting serviceability and component recyclability in competitive tenders. Tokyo-Osaka clinical laboratory networks sustain service contract renewals through installed base leverage.
South Korea
Stem cell research facilities concentrate demand for multi-parameter laser detection systems despite supply chain vulnerability from imported precision optical components. The national pharmaceutical regulator aligns medical device classification with international standards, streamlining approval pathways for instruments already cleared by PMDA. Seoul-Gyeonggi bioclusters face technical workforce scarcity that constrains deployment speed for complex instrument installations.
India
Government research institutes replace legacy hemocytometers as life sciences funding expands, though institutional budget constraints limit flow cytometer adoption. CDSCO alignment of medical device rules with ISO 13485 for in-vitro diagnostic instruments reshapes vendor registration strategies. Maharashtra and Karnataka academic clusters anchor replacement demand for manual counting chambers.
Australia
CROs with moderate throughput requirements and capital constraints adopt optical brightfield systems for viability testing. TGA maintains parallel conformity assessment pathways that expedite registration for instruments already approved by Japan's PMDA, reducing vendor entry friction. The biomedical manufacturing corridor in New South Wales and Victoria generates volume from automated workflow expansions.
Asia Pacific Cell Counting Market Vendor Landscape
Capital-heavy instrument manufacturers compete with asset-light subsystem designers across detection module and software architecture layers. The vendor base stratifies into three tiers: diversified life science conglomerates with full-stack portfolios, specialized cytometry houses with laser-optical expertise, and regional distributors with regulatory navigation capabilities. Consolidation pressure concentrates among mid-scale players lacking installed base depth for service contract economics. Dominant competitive moves include modular hardware architectures that reduce customer capital redundancy and managed service agreements that transfer calibration burden to suppliers.
Among diversified life science conglomerates, Thermo Fisher Scientific and Agilent Technologies occupy positions leveraging broad installed bases for recurring service revenue. Sysmex Corporation anchors the hematology-adjacent segment through domestic distribution density and regulatory rapport with PMDA. Beckman Coulter exemplifies the high-throughput flow cytometry specialist archetype competing on configuration expertise for stem cell research facilities.
| Leading Market Players |
|---|
| Agilent Technologies |
| Merck KGaA |
| Thermo Fisher Scientific |
| HORIBA Ltd. |
| Olympus Corporation |
| Beckman Coulter |
| PerkinElmer |
| Sysmex Corporation |
| Bio-Rad Laboratories |
| Others |
Supply Flow & Price Mechanics
Modular instrument architectures with swappable detection cartridges are compressing replacement cycles for monolithic systems while simultaneously fragmenting supplier power across optical subsystem vendors and final instrument assemblers. This technical shift concentrates margin capture with cartridge manufacturers in Japan and Germany while forcing final instrument vendors to compete on service bundling rather than hardware differentiation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates laser-based flow cytometry configurations from benchtop automated counters and manual hemocytometers. Price differentiation centers on certification grade for GMP compliance and after-sales service bundling intensity. Pricing pressure stems from CDMO procurement consolidation under operational expenditure models in China's Yangtze River Delta. Indian research laboratories exhibit highest price sensitivity due to institutional funding constraints, while Japanese pharmaceutical quality control departments prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
Freight costs for precision optical components from Germany and the United States inflate landed costs for laser-based detection modules by fifteen to twenty percent across Asia Pacific assembly facilities. Manufacturing concentration rests on Japan for high-precision optical sources, Germany for laser modules, and China for electronic chassis and impedance detection components. Single-source vulnerability pervades solid-state laser supply given concentration among three German specialty manufacturers. Distribution runs through authorized dealer networks with mandatory calibration certification in Japan and direct vendor-managed inventory at CDMO facilities in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where China's NMPA enforcement of GMP Annex 1 for cell therapy manufacturing creates irreversible instrument replacement demand across bioclusters.
For Market Incumbents: Acquire installed base service contracts in Japanese clinical laboratory networks to lock in recurring revenue against modular subsystem vendors. Deepen backward integration into fluorescence detection cartridge manufacturing to capture margin migrating from final instrument sales. Defend against CDMO procurement consolidation by unbundling hardware from validation and preventive maintenance packages. For New Entrants and Emerging Players: Capture replacement demand for legacy hemocytometers across Indian government research institutes as life sciences funding expands. Penetrate Australia's CRO segment through TGA-PMDA parallel approval pathways that reduce regulatory entry friction. Lead with optical brightfield configurations priced below automated fluorescence systems to displace manual counting methods. For Investors and Strategic Acquirers: Roll-up economics work for regional distributors with PMDA regulatory navigation capabilities because approval timeline compression creates scarcity value for registration expertise. Five-to-ten year viability hinges on positioning against managed service agreement proliferation in Chinese bioclusters. Target acquisition archetypes: mid-scale cytometry specialists with laser-optical configuration expertise. Signal to watch: NMPA reclassification of automated cell counters from Class I to Class II medical devices.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Detection Cartridge Development | Reduces capital redundancy for Singapore biotech companies running multiple assay types. |
| GMP Validation Service Unbundling | Captures recurring revenue from Chinese CDMOs under operational expenditure procurement models. |
| PMDA Regulatory Fast-Track Partnership | Expedites instrument registration for Australian CROs leveraging parallel TGA approval pathways. |
| Optical Component Backward Integration | Mitigates supply vulnerability from German laser module concentration for South Korean facilities. |
| Circular Economy Design Certification | Meets METI procurement criteria for extended service life in Japanese pharmaceutical quality control. |
Methodological Framework
Direct dialogue with bioprocess engineers, regulatory affairs specialists at CDMOs, GMP facility qualification managers, and clinical laboratory procurement directors grounded demand-side assumptions. Secondary validation drew from NMPA medical device registration databases, PMDA approval summaries, TGA conformity assessment records, and CDSCO in-vitro diagnostic rule amendments. Bottom-up instrument shipment tracking across China's Yangtze River Delta bioclusters triangulated against top-down biomanufacturing capacity expansion estimates.
Bottom-up modeling segmented volume by product type, end-user category, detection technology, and application purpose across the projection horizon. Top-down validation cross-referenced biotech manufacturing facility buildout announcements with instrument procurement patterns in Japan's Kanto region and Singapore's biomedical corridor. CAGRs derived from regression analysis of replacement cycle acceleration under tightened GMP annexes and funding trajectory projections for Indian life sciences research.
Regulatory reclassification decisions, supply disruption in precision optical components, and CDMO procurement model shifts are the dominant revision risks that could alter trajectory assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Molecular Microplate Readers and Washers Market
Laboratory Equipment
Lab Accessories Market
Laboratory Equipment
Global Laboratory Glassware Washers Market
Laboratory Equipment
Global Laboratory Equipment and Disposables Market
Laboratory Equipment
Global Automated Analyzers Market
Laboratory Equipment
Hemostasis Analyzers Market
Laboratory Equipment
Global Laboratory Equipment Services Market
Laboratory Equipment
Cuvettes Market
Laboratory Equipment
Microplate Reader Market
Laboratory Equipment
Laboratory Temperature Control Units Market
Laboratory Equipment
Albumin Analyzers Market
Laboratory Equipment
Laboratory Furnaces Market
Laboratory Equipment
Human Platelet Lysate Market
Laboratory Equipment
Multi-Cuvette Spectrophotometer Market
Laboratory Equipment
Centrifuge Tubes Market
Laboratory Equipment
Automated Nucleic Acid Extraction Systems Market