
 Albumin Analyzers Market | 2026-2036
Albumin Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Albumin Analyzers Market Analysis
Hospital procurement channels is tilting toward integrated diagnostics suites that bundle albumin testing with broader metabolic panels. Thermo Fisher Scientific leverages its life sciences distribution network to sustain instrument placement across academic medical centers. Grifols S.A. anchors its position through specialized blood-product testing workflows that require calibrated albumin measurement. Baxter International Inc. competes by extending its peritoneal dialysis monitoring ecosystem to include albumin loss tracking.
An albumin analyzer quantifies serum or urinary albumin concentration through photometric, electrochemical, or immunochemical detection, typically operating within clinical chemistry laboratories at throughput rates of 200–800 tests per hour. The device serves nephrologists, hepatologists, and critical-care physicians who require rapid protein-status assessment for fluid management and nutritional intervention decisions. Automated systems dominate installed base value due to their integration with laboratory information systems and reduced manual calibration overhead. Point-of-care devices represent the fastest-expanding segment as emergency departments and dialysis clinics prioritize turnaround time over batch efficiency. Immunoassay technology occupies the premium tier of the product mix, driven by specificity requirements in low-concentration microalbuminuria detection.
The FDA regulates albumin analyzers as Class II medical devices under 21 CFR 862, requiring 510(k) premarket notification for new instrument platforms or reagent system modifications. Clinical Laboratory Improvement Amendments (CLIA) compliance shapes demand by stratifying analyzer complexity across waived, moderate, and high-complexity laboratory certifications. Stakeholders must monitor pending FDA guidance on artificial intelligence-enabled result interpretation, as algorithm-driven flagging systems could redefine competitive differentiation in the next product generation.
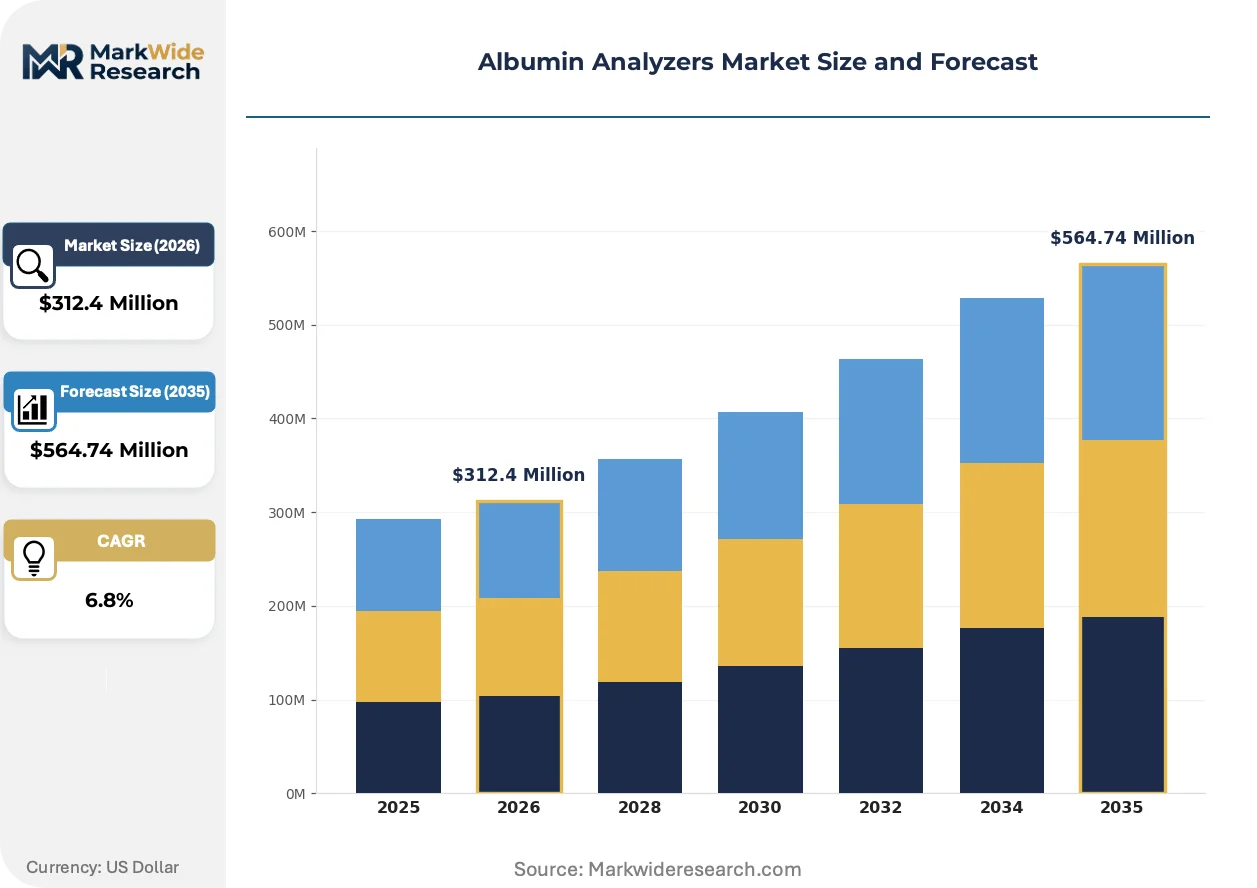
Market Dynamics
Hospital consolidation across the United States is compressing purchasing timelines and favoring vendors with integrated chemistry-immunoassay platforms capable of serving consolidated laboratory networks.
Growth Catalysts
- CLIA Complexity Waivers:Moderate-complexity laboratory certifications under CLIA are expanding point-of-care albumin testing into satellite dialysis clinics previously restricted to high-complexity central labs.
- Peritoneal Dialysis Expansion:Home-based peritoneal dialysis protocols require calibrated albumin loss monitoring, creating instrument demand in ambulatory settings across Medicare-reimbursed networks.
- Microalbuminuria Screening Protocols:Nephrology societies in Germany and Japan are embedding low-concentration albumin detection into diabetes management guidelines, accelerating immunoassay analyzer placements.
Market Restraints
- Reagent Supply Concentration:Calibrated albumin reference materials concentrate among three European suppliers, exposing instrument manufacturers to input volatility and qualification delays.
- FDA 510(k) Recertification Burden:Evolving in vitro diagnostic regulations are compressing analyzer lifecycle economics by requiring premarket notification for software modifications that previously qualified as maintenance updates.
- Photometric Substitution Pressure:Dry chemistry slide technology in compact analyzers threatens wet-chemistry systems in moderate-throughput hospital segments below 400 tests per hour.
Strategic Opportunities
- Veterinary Diagnostic White Space:Companion animal nephrology practices in Australia and Canada remain underpenetrated by automated albumin platforms, presenting first-mover positioning for adapted clinical chemistry systems.
- AI-Enabled Result Interpretation:Pending FDA guidance on algorithm-driven flagging systems creates differentiation potential for analyzers integrating pattern-recognition software for protein-status alerts.
- Emergency Department Triage:Rapid-turnaround albumin testing is displacing send-out protocols in US Level I trauma centers, opening point-of-care cartridge placements previously served by core laboratories.
Industry Challenges
- Laboratory Information System Integration:Middleware compatibility gaps between legacy hospital IT architectures and new analyzer communication protocols extend installation timelines and inflate field engineering costs.
- Multisite Calibration Standardization:Consolidated health systems struggle to maintain traceability consistency across distributed analyzer fleets, complicating quality assurance for inter-laboratory comparison programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Albumin Analyzers Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benchtop Analyzers, Portable Analyzers, Automated Systems, Point-of-Care Devices End User: Clinical Laboratories, Hospitals, Homecare Settings, Research Institutions Technology: Colorimetric Assays, Electrochemical Methods, Immunoassays, Spectrophotometry Application: Renal Disease Diagnosis, Liver Function Tests, Nutritional Assessment, Research Studies |
| Companies Covered | Octapharma AG, Thermo Fisher Scientific, CSL Behring, Baxter International Inc., Albumedix Ltd., Grifols S.A., Merck KGaA, China Biologic Products Inc., Takeda Pharmaceutical Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Albumin Analyzers Market Emerging Trajectories
Analyzer functionality is fragmenting along speed-versus-accuracy axes as emergency departments, dialysis clinics, and central laboratories diverge in their technical requirements and purchasing criteria.
Immunoassay detection for microalbuminuria quantification is migrating from high-complexity reference laboratories into moderate-complexity satellite facilities. Nephrology practices in the United Kingdom and South Korea are adopting these systems to reduce send-out dependency for diabetic kidney disease monitoring. The shift is compressing reference lab revenue streams while expanding addressable instrument placements into previously inaccessible CLIA-moderate settings.
The EU In Vitro Diagnostic Regulation (IVDR) is reclassifying albumin analyzer reagent kits from self-certified to notified-body reviewed status. Manufacturers face extended conformity assessment timelines and elevated clinical evidence requirements for existing product lines. Systems with established IVDR technical documentation are capturing shelf space as distributors prune non-compliant suppliers ahead of transition deadlines.
Leasing arrangements with reagent rental commitments are displacing capital purchase models in US hospital procurement. Integrated delivery networks favor per-test economics that align analyzer costs with utilization volume rather than upfront equipment expenditure. This restructuring concentrates vendor selection power among manufacturers with captive reagent supply chains capable of absorbing instrument depreciation across multi-year contracts.
Albumin Analyzers Market Segmentation
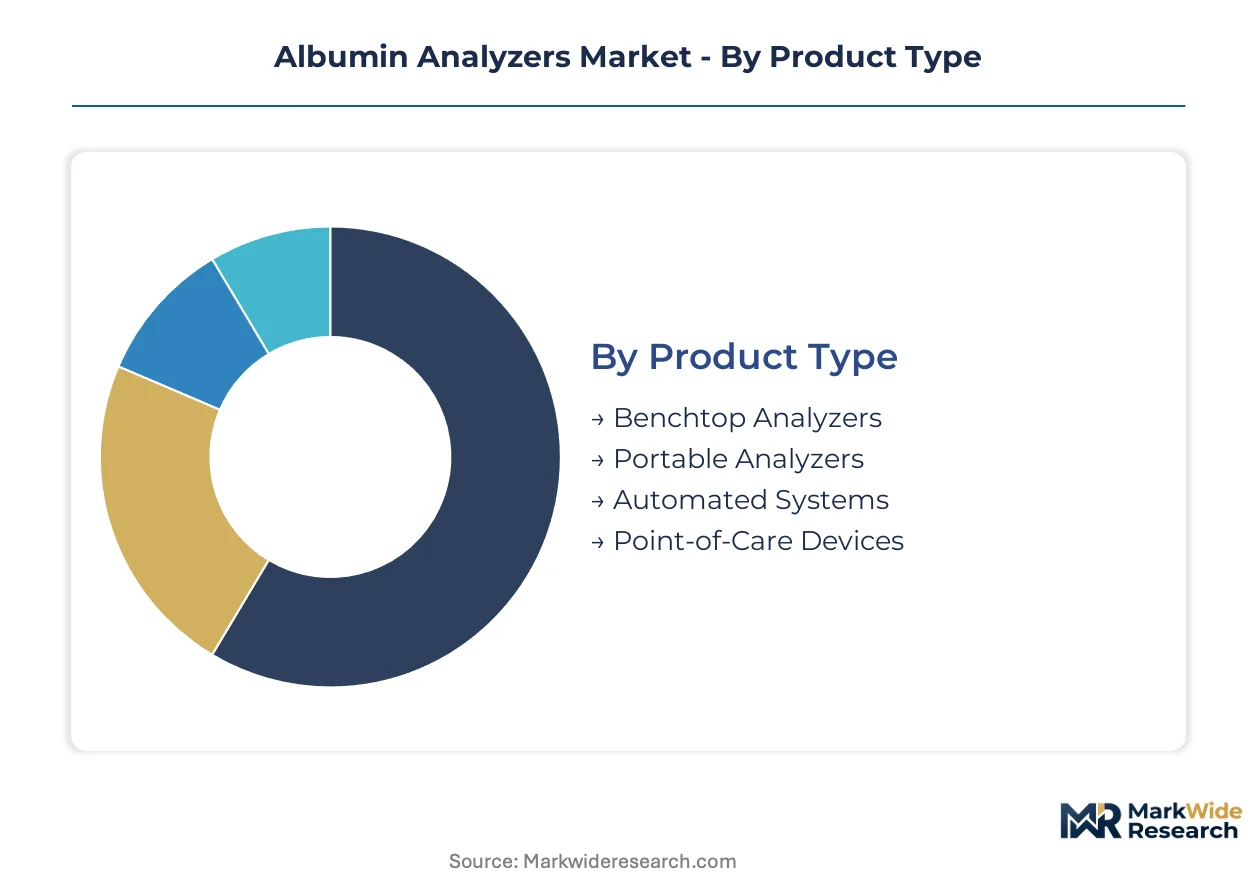
Albumin analyzer purchasing decisions fragment sharply across clinical settings, with after-sales service contracts and reagent supply reliability often outweighing instrument specifications in vendor selection. Segmentation reveals how technical requirements diverge between high-throughput central laboratories and distributed point-of-care networks.
Product Type:
After-sales-service intensity varies dramatically across instrument form factors, with automated systems demanding multi-year field engineering commitments while portable units require minimal technical support.
- Benchtop Analyzers:Mid-sized instruments occupy 200–400 tests per hour throughput bands, serving hospital satellite laboratories that lack capital budgets for floor-standing systems. Demand concentrates in Germany and Japan where mid-sized hospital networks prioritize space-efficient automation over maximum throughput.
- Portable Analyzers:Battery-operated units weighing under 10 kilograms enable albumin testing in mobile health units and remote dialysis clinics. Australian rural health networks and Canadian First Nations communities drive procurement, where transport logistics to centralized laboratories extend turnaround times beyond clinically acceptable windows.
- Automated Systems:Floor-standing platforms integrate with laboratory information systems and support 600+ tests per hour in high-complexity reference laboratories.
- Point-of-Care Devices:Cartridge-based systems deliver results in under 10 minutes for emergency department triage and home dialysis monitoring.
By volume, Automated Systems leads. By growth pace, Point-of-Care Devices is gaining share fastest.
End User:
Procurement authority and budget cycles diverge substantially across customer types, with consolidated health systems negotiating enterprise contracts while research institutions prioritize grant-funded instrument flexibility.
- Clinical Laboratories:Independent and hospital-affiliated reference laboratories process batch samples from multiple collection sites, driving demand for high-throughput systems with middleware connectivity. The United States and United Kingdom dominate installed base value, where laboratory accreditation requirements favor analyzers with documented quality control traceability.
- Hospitals:Acute care facilities require STAT testing capability alongside routine workload capacity, creating hybrid procurement specifications. Demand clusters in Level I trauma centers across the United States, where emergency department throughput pressure accelerates decentralized analyzer placement.
- Homecare Settings:Peritoneal dialysis patients and home health agencies drive demand for simplified operation protocols and remote result transmission.
- Research Institutions:Academic medical centers and contract research organizations prioritize analytical flexibility over regulatory compliance speed.
Clinical Laboratories captures the largest revenue pool. Hospitals show the steepest expansion trajectory for point-of-care placements.
Technology:
Margin structures and reagent economics vary by detection methodology, with immunoassay systems commanding premium pricing for specificity while photometric methods compete on per-test cost.
- Colorimetric Assays:Dye-binding methods using bromocresol green or bromocresol purple dominate serum albumin quantification in moderate-complexity settings. Demand persists in India and Brazil where cost sensitivity favors established wet-chemistry platforms over newer detection modalities.
- Immunoassays:Antibody-based detection achieves microgram-per-milliliter sensitivity required for microalbuminuria screening in diabetic kidney disease protocols. Nephrology practices in South Korea and the Netherlands are adopting these systems to reduce send-out dependency for early-stage renal monitoring.
- Electrochemical Methods:Ion-selective electrode approaches enable miniaturization for wearable and implantable monitoring concepts under development.
- Spectrophotometry:UV-visible absorbance measurement remains the reference method for albumin standardization and calibrator verification.
Colorimetric Assays maintains the broadest installed base. Immunoassays is expanding most quickly into previously inaccessible moderate-complexity settings.
Application:
Clinical utility and reimbursement pathways shape technology selection, with renal and hepatic applications driving routine testing volume while research applications demand analytical versatility.
- Renal Disease Diagnosis:Albumin-to-creatinine ratio testing constitutes the primary screening modality for diabetic nephropathy and chronic kidney disease staging. Japan and Germany have embedded microalbuminuria detection into national diabetes management guidelines, accelerating analyzer placement in primary care networks.
- Liver Function Tests:Serum albumin quantification supports cirrhosis severity scoring and nutritional status assessment in hepatology practices. Demand concentrates in France and Spain where alcohol-related liver disease prevalence sustains testing volume in hospital chemistry departments.
- Nutritional Assessment:Preoperative screening and critical care monitoring drive albumin testing as a protein-status marker in surgical and ICU settings.
- Research Studies:Drug development and epidemiological cohort studies require high-precision albumin measurement for biomarker validation.
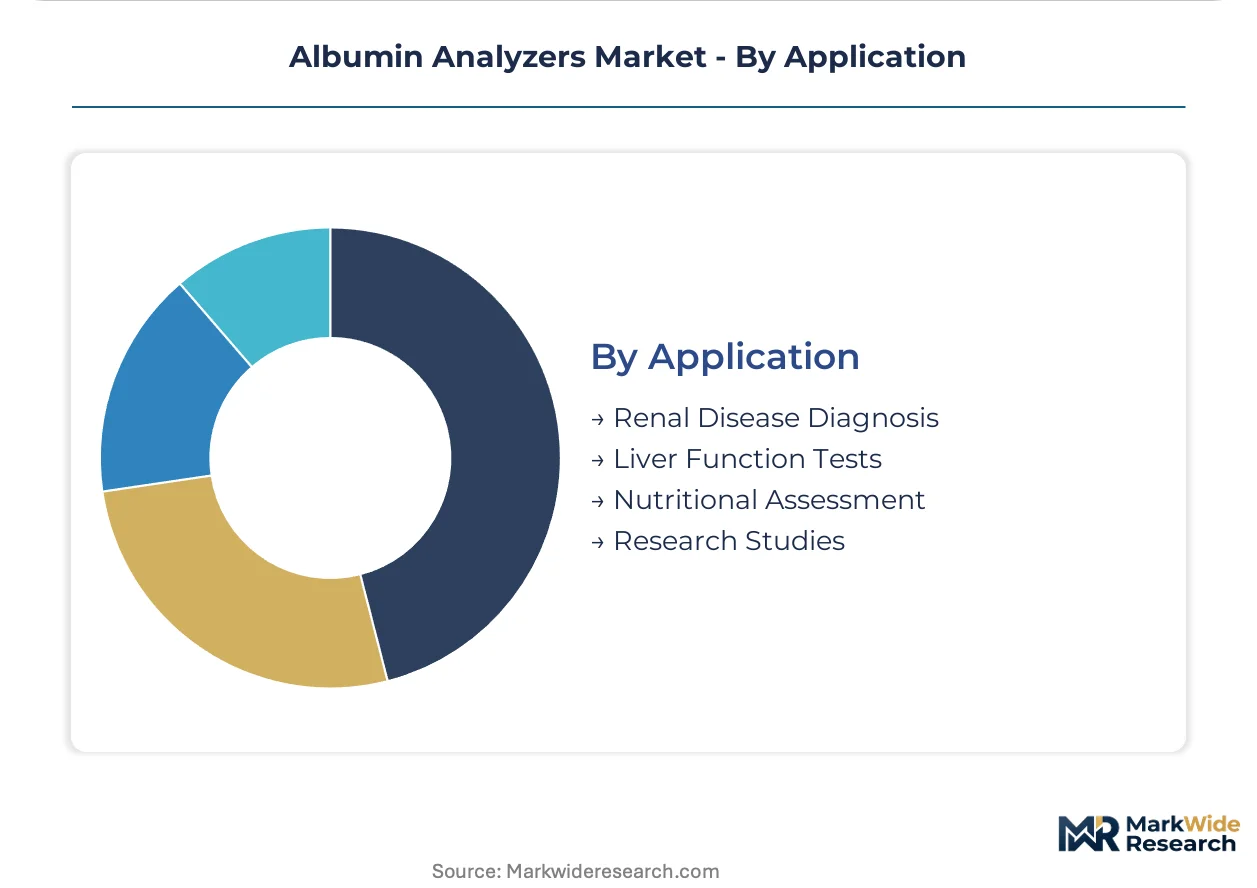
Renal Disease Diagnosis generates the highest test volume. Nutritional Assessment is climbing the fastest as perioperative protocols expand albumin screening into pre-admission testing workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain logistics infrastructure underwrites Europe's dominance in calibrated albumin reference material distribution, while the US Interstate Highway System enables rapid analyzer deployment across consolidated hospital networks.
United States
Hospital consolidation across Texas and Florida is compressing procurement timelines for integrated chemistry-immunoassay platforms. FDA 510(k) recertification cycles for software modifications now require premarket notification previously classified as maintenance updates. The Research Triangle Park corridor in North Carolina hosts multiple clinical laboratory networks expanding automated testing capacity.
Germany
Nephrology societies have embedded microalbuminuria detection into national diabetes management guidelines, accelerating immunoassay analyzer placements in primary care networks. The EU In Vitro Diagnostic Regulation reclassifies reagent kits from self-certified to notified-body reviewed status, extending conformity assessment timelines. The Rhine-Main cluster around Frankfurt sustains demand for high-throughput reference laboratory systems.
Japan
PMDA regulatory frameworks shape analyzer complexity stratification across waived, moderate, and high-complexity laboratory certifications. The Kanto region surrounding Tokyo concentrates demand for floor-standing platforms serving consolidated laboratory networks. METI industrial policy supports domestic manufacturers developing AI-enabled result interpretation modules.
China
NMPA medical device classification governs 510(k)-equivalent premarket notification requirements for new instrument platforms. The Yangtze River Delta around Shanghai hosts expanding clinical laboratory capacity serving hospital consolidation trends. GB standards for in vitro diagnostics are tightening traceability requirements for distributed analyzer fleets.
Australia
Rural health networks in Queensland and Western Australia drive procurement of portable battery-operated units where transport logistics to centralized laboratories extend turnaround times. The TGA regulates analyzers as Class II medical devices with moderate-complexity certification pathways. Companion animal nephrology practices in New South Wales remain underpenetrated by automated platforms.
Albumin Analyzers Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in reagent and reference material supply. The vendor base fragments across three tiers: multinational conglomerates with captive distribution networks, mid-sized specialists in blood-product testing workflows, and regional manufacturers serving price-sensitive moderate-throughput segments. Two dominant competitive moves define current positioning: leasing arrangements with reagent rental commitments displacing capital purchase models, and backward integration into calibrated reference material production to secure supply chain stability.
Within the multinational tier, Thermo Fisher Scientific and Grifols S.A. exemplify divergent strategic archetypes. Thermo Fisher leverages life sciences distribution infrastructure to sustain instrument placement across academic medical centers. Grifols anchors positioning through specialized blood-product testing workflows requiring calibrated albumin measurement. Baxter International Inc. occupies a position extending peritoneal dialysis monitoring ecosystems to include albumin loss tracking. These three entities represent the spectrum from broad-platform diversification to therapy-specific vertical integration.
| Leading Market Players |
|---|
| Octapharma AG |
| Thermo Fisher Scientific |
| CSL Behring |
| Baxter International Inc. |
| Albumedix Ltd. |
| Grifols S.A. |
| Merck KGaA |
| China Biologic Products Inc. |
| Takeda Pharmaceutical Company Limited |
| Others |
Supply Flow & Price Mechanics
Undercapacity in calibrated albumin reference material production across European supply hubs is compressing reagent pricing flexibility while forcing instrument manufacturers toward long-term offtake commitments. This utilization squeeze simultaneously elevates input costs for wet-chemistry systems and accelerates substitution toward dry-chemistry platforms with lower reagent intensity.
Pricing Analysis
Volume-discount tiering structures separate enterprise health systems negotiating per-test economics from mid-sized hospitals purchasing capital equipment outright. Three-tier pricing stratification across premium immunoassay systems, standard automated platforms, and economy point-of-care devices reflects after-sales bundling intensity and reagent lock-in duration. Price differentiation hinges on CLIA certification tier and middleware integration depth. Cost compression in the economy segment is intensifying as dry-chemistry slide technology displaces wet-chemistry alternatives below 400 tests per hour. Satellite dialysis clinics exhibit highest price sensitivity due to Medicare reimbursement constraints, while academic medical centers prioritize analytical performance over per-test cost.
Supply Chain Analysis
Upstream feedstock concentration in calibrated albumin reference materials draws from Germany, the Netherlands, and Switzerland, where three European suppliers control qualification protocols for instrument manufacturers. The supply chain rests on bovine serum albumin derivatives, photometric dyes including bromocresol green and bromocresol purple, and monoclonal antibody reagents for immunoassay tiers. Single-source vulnerability in European reference material production exposes manufacturers to IVDR transition delays and extended conformity assessments. Distribution runs through integrated delivery network procurement committees and GPO contracts in the United States, alongside direct hospital sales in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The albumin analyzer market is approaching a platform-economics inflection as laboratory information system interoperability becomes the primary vendor selection criterion. Integrated chemistry-immunoassay platforms capable of seamless middleware integration are capturing procurement authority from standalone instrument specialists.
For Market Incumbents: Pre-empt dry-chemistry substitution by accelerating backward integration into calibrated reference material production, securing supply chain stability against IVDR qualification delays. Consolidate field engineering networks across consolidated health systems to capture multi-year service contracts that lock out emerging competitors. The priority lever centers on reagent rental economics that align instrument depreciation with utilization volume. For New Entrants and Emerging Players: Australian and Canadian veterinary nephrology practices present the most penetrable white-space target, where companion animal diagnostic demand outpaces automated platform supply. Emergency department triage protocols in US Level I trauma centers offer a second entry vector through rapid-turnaround cartridge systems displacing send-out workflows. A go-to-market angle emphasizing CLIA-waived operation protocols reduces regulatory friction in satellite clinic deployment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers with captive reagent supply chains and installed base lock-in through middleware integration. Long-term viability across the analysis window favors platform integrators over component specialists. Acquisition target archetypes include regional manufacturers with established IVDR technical documentation and moderate-complexity certification pathways. The signal to watch is FDA guidance on artificial intelligence-enabled result interpretation, which could redefine competitive differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| Reagent Rental Commitment Structuring | Aligns instrument costs with utilization volume across consolidated US health systems. |
| IVDR Technical Documentation Investment | Secures shelf space as distributors prune non-compliant European suppliers. |
| AI-Enabled Result Interpretation Development | Positions for FDA algorithm guidance reshaping competitive differentiation. |
| Veterinary Diagnostic Platform Adaptation | Captures first-mover positioning in Australian and Canadian companion animal practices. |
| Point-of-Care Cartridge Miniaturization | Enables emergency department triage placement displacing core laboratory send-outs. |
Methodological Framework
Cross-validation between primary interviews with laboratory directors, biomedical engineers, GPO contracts managers, and nephrology practice administrators and secondary sources including FDA 510(k) filings, CLIA certification databases, hospital procurement records, and EU IVDR technical documentation anchors the qualitative findings. Bottom-up triangulation across instrument shipment data and top-down validation through reagent consumption patterns calibrate market sizing.
Calibration against historical placement cycles and regulatory transition timelines shapes the projection framework. Segmentation dimensions modeled include product form factor, end-user setting, detection technology, clinical application, and regional regulatory cluster. CAGRs derive from fitted growth curves incorporating per-test economics adoption, CLIA complexity waiver expansion, and microalbuminuria protocol embedding. Forecast inputs include Medicare reimbursement trajectory for peritoneal dialysis monitoring and METI industrial policy support for AI module development.
Practitioners should monitor FDA guidance publication on algorithm-driven flagging systems and IVDR transition deadline compliance rates for early signals of competitive repositioning. Forecasts reflect assumptions regarding hospital consolidation pace and reagent supply qualification timelines. Cross-checking against CMS Medicare claims data for albumin testing volume is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Microplate Luminometer Market
Laboratory Equipment
Vacuum Tissue Processors Market
Laboratory Equipment
Hemostasis Analyzers Market
Laboratory Equipment
Global Hematology Instruments and Reagents Market
Laboratory Equipment
Automated Cell Counter Market
Laboratory Equipment
Muffle Laboratory Furnaces Market
Laboratory Equipment
Ion-Selective Clinical Lab Analyzers Market
Laboratory Equipment
Laboratory Ovens Market
Laboratory Equipment
Colony Counters Market
Laboratory Equipment
Portable Hemoglobin Analyzer Market
Laboratory Equipment
Centrifuge Tubes Market
Laboratory Equipment
Global Laboratory Plasticware Market
Laboratory Equipment
Europe Laboratory Hoods and Enclosure Market
Laboratory Equipment
South Korea Pipette Tips Market
Laboratory Equipment
Electrophoresis Transilluminator Market
Laboratory Equipment
Automated Plate Readers Market