
 Glycohemoglobin Analyzers Market | 2026-2036
Glycohemoglobin Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Glycohemoglobin Analyzers Market Foresight
Aftermarket service revenue is tilting toward predictive maintenance contracts and remote calibration support as laboratories seek to maximize analyzer uptime. Siemens Healthineers anchors its position through embedded service networks that reduce mean time to repair. Bio-Rad Laboratories differentiates by leveraging its quality control ecosystem to lock in recurring consumable revenue alongside hardware placements.
Glycohemoglobin analyzers quantify hemoglobin A1c through chromatographic or immunoassay methods, with HPLC systems achieving NGSP-certified precision below three percent coefficient of variation to guide diabetes management and therapeutic adjustment. Laboratory analyzers dominate installed base and margin pools due to throughput requirements in centralized facilities, while point-of-care devices represent the fastest-expanding segment as physician offices and retail clinics pursue same-result workflows without sample transport logistics. Immunoassay technology leads in compact footprints, though HPLC sustains reference-method status for adjudication and standardization programs.
The US FDA oversees premarket clearance and clinical performance claims under CLIA complexity classifications, while the EU MDR and IVDR frameworks impose post-market surveillance and notified body conformity assessments on manufacturers seeking CE marking for European distribution. Japan's PMDA maintains distinct approval pathways that delay entry for non-domestic platforms, creating structural advantage for established registrants. Stakeholders must monitor evolving harmonization between NGSP and IFCC standardization protocols, as dual-credential requirements will determine competitive access to reimbursement-linked procurement channels.
Market Dynamics
Automated HbA1c testing capacity expansion in hospital laboratories is compressing turnaround times and displacing manual batch workflows, while CLIA quality enforcement concentrates procurement toward certified high-throughput platforms.
Growth Catalysts
- CLIA complexity classifications:The FDA's strengthened laboratory quality standards under CLIA push facilities toward certified analyzer platforms, filtering out uncertified equipment and consolidating demand around compliant vendors.
- Diabetes screening mandates:Germany's statutory health insurance coverage for diabetes screening drives replacement cycles for high-throughput glycohemoglobin analyzers in centralized hospital laboratories.
- Point-of-care workflow compression:Physician offices and retail clinics pursue same-result workflows without sample transport logistics, expanding demand for compact immunoassay-based devices.
Market Restraints
- Reagent lock-in costs:Proprietary consumable ecosystems tether laboratories to single-vendor supply chains, inflating lifetime ownership costs beyond initial hardware expenditure.
- Reference method fragmentation:Divergent NGSP and IFCC standardization protocols create dual-credential compliance burdens that delay product launches and restrict reimbursement access.
- PMDA approval delays:Japan's distinct regulatory pathways for in-vitro diagnostics extend market entry timelines for non-domestic analyzer platforms, ceding structural advantage to established registrants.
Strategic Opportunities
- Predictive maintenance contracts:Laboratories seek to maximize analyzer uptime through embedded service networks offering remote calibration support and reduced mean time to repair.
- Retail clinic channel expansion:Pharmacy chains and urgent-care networks represent underpenetrated deployment sites for compact point-of-care glycohemoglobin analyzers with waived complexity status.
- Quality control ecosystem bundling:Manufacturers can lock in recurring consumable revenue by integrating analyzer placements with certified control material and proficiency testing programs.
Industry Challenges
- NGSP-IFCC harmonization delays:Ongoing protocol reconciliation between standardization bodies complicates dual-credential requirements and reimbursement-linked procurement channels.
- Chromatography specialist scarcity:High-performance liquid chromatography systems require trained operators for maintenance and troubleshooting, constraining deployment in resource-limited settings.
- Legacy LIS integration friction:Analyzer connectivity with existing laboratory information systems demands customized middleware development, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glycohemoglobin Analyzers Market |
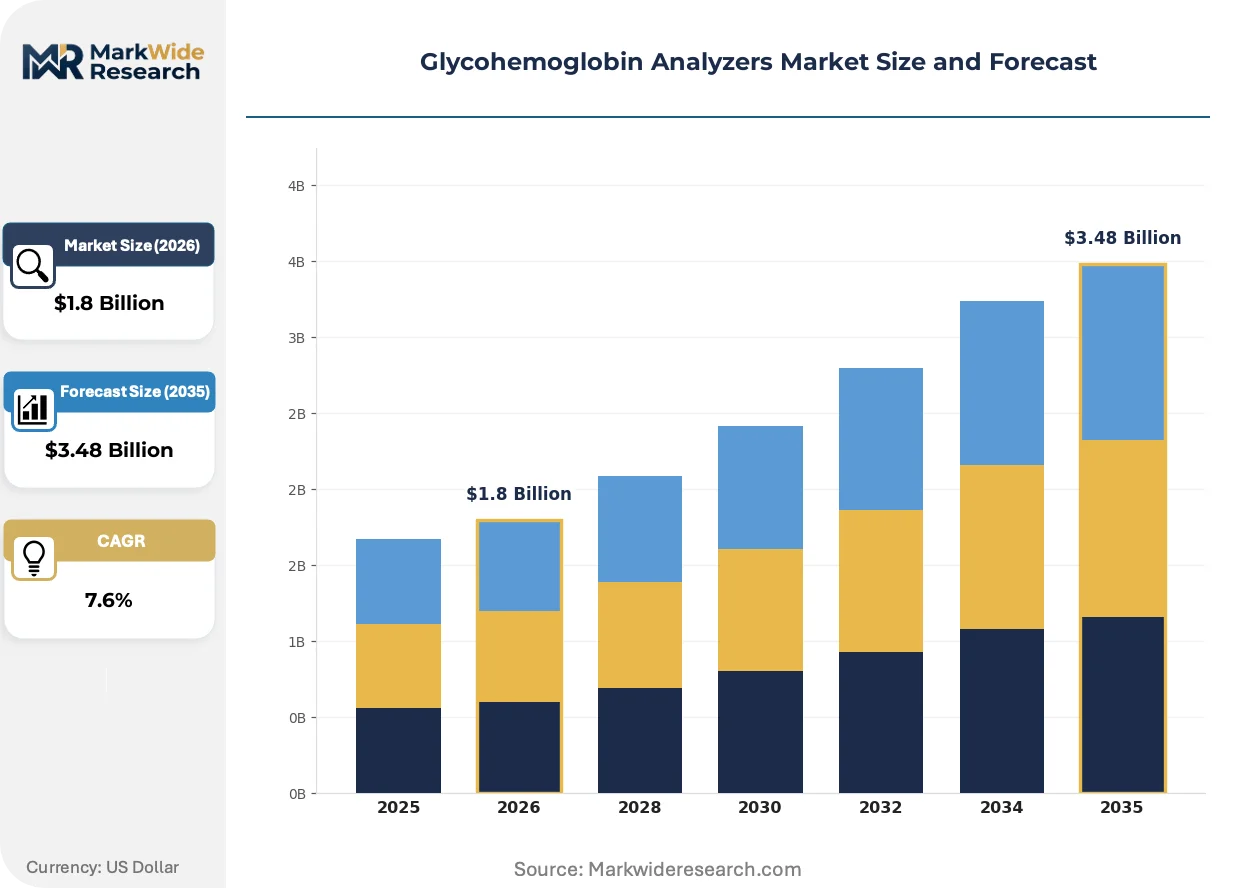
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laboratory Analyzers, Point-of-Care Devices, Handheld Analyzers, Integrated Systems End User: Hospitals, Diagnostic Laboratories, Home Care Settings, Clinics Technology: Immunoassay, HPLC, Enzymatic, Rapid Testing Sample Type: Capillary Blood, Venous Blood, Dried Blood Spots, Plasma |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche, Siemens Healthineers AG, Bio-Rad Laboratories, Danaher Corporation, Thermo Fisher Scientific, Trinity Biotech, Beckman Coulter, Tosoh Bioscience, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glycohemoglobin Analyzers Market Shifts & Advancements
Digital connectivity and remote service architectures are restructuring how glycohemoglobin analyzers are deployed, maintained, and monetized across centralized and distributed care settings.
Cloud-enabled analyzer telemetry is digitizing preventive maintenance workflows by transmitting performance metrics and error logs to manufacturer service centers. Hospital laboratories with high-throughput HPLC installations adopt these systems to preempt component failures and schedule interventions during low-volume periods. This architecture compresses mean time to repair and shifts service revenue from reactive break-fix contracts toward subscription-based uptime guarantees.
The EU IVDR framework imposes strengthened post-market surveillance and notified body conformity assessments on manufacturers seeking CE marking for European distribution. Clinical performance data requirements now extend across the full product lifecycle, compelling vendors to maintain robust quality management systems. Mid-sized analyzer producers face disproportionate compliance costs, accelerating consolidation toward integrated diagnostics conglomerates with dedicated regulatory affairs infrastructure.
Consolidated purchasing by multi-hospital health systems is displacing fragmented procurement decisions at individual laboratory levels. Integrated delivery networks negotiate enterprise-wide analyzer placements with standardized service terms and volume-based reagent pricing. This concentration is most visible in the United States, where hospital system mergers have reduced the number of independent purchasing entities by over one-third in major metropolitan markets.
Glycohemoglobin Analyzers Market Segmentation
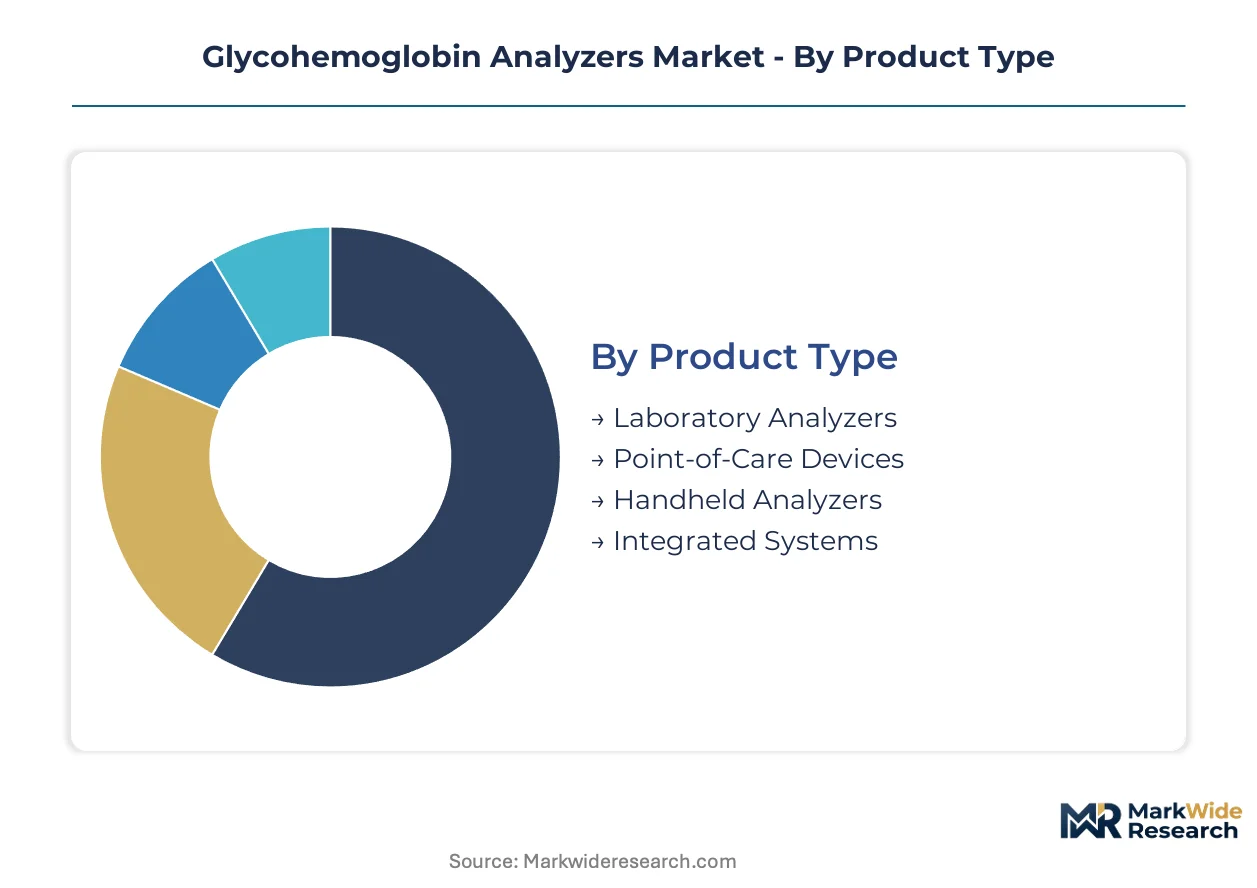
Glycohemoglobin analyzer segmentation reflects divergent workflow requirements across centralized laboratories and distributed care sites. Equipment specifications, throughput demands, and regulatory complexity vary sharply by deployment setting, creating distinct margin pools and competitive dynamics within each category.
Product Type:
Use-case spectrum spans high-volume batch processing in hospital core labs to single-patient testing at retail pharmacy counters.
- Laboratory Analyzers:High-throughput HPLC and immunoassay platforms process hundreds of samples hourly with NGSP-certified precision below three percent coefficient of variation. Hospital laboratories in Germany and the United States drive replacement demand as CLIA enforcement and statutory screening mandates compress turnaround times.
- Point-of-Care Devices:Compact immunoassay systems deliver HbA1c results within minutes at physician offices and urgent-care networks. Pharmacy chains in the United States deploy these for same-visit diabetes management without sample transport logistics.
- Handheld Analyzers:Battery-operated units enable capillary blood testing in mobile health camps and remote clinics with limited infrastructure.
- Integrated Systems:Modular platforms combine glycohemoglobin testing with broader metabolic panels for comprehensive diabetes monitoring in centralized facilities.
Established volume favors Laboratory Analyzers; emerging adoption favors Point-of-Care Devices.
End User:
Customer type determines procurement authority, service contract structure, and reagent lock-in intensity.
- Hospitals:Integrated delivery networks negotiate enterprise-wide analyzer placements with standardized service terms and volume-based consumable pricing. Multi-hospital system consolidation in the United States has reduced independent purchasing entities by over one-third in major metropolitan markets.
- Diagnostic Laboratories:Independent reference labs prioritize NGSP-certified HPLC platforms for adjudication workflows and external quality assurance programs. Germany's statutory health insurance coverage for diabetes screening sustains replacement cycles for high-throughput installations.
- Home Care Settings:Patients with established diabetes use compact devices for periodic monitoring between clinical visits, though reimbursement limitations constrain penetration.
- Clinics:Physician offices and retail clinics seek waived-complexity devices to avoid CLIA personnel requirements and enable same-result workflows.
Procurement concentration tilts toward Hospitals; volume expansion is climbing the fastest at Clinics.
Technology:
Performance tier stratification separates reference-grade chromatography from rapid immunoassay methods.
- Immunoassay:Antibody-based detection enables compact footprints and rapid turnaround for point-of-care deployment. Compact immunoassay devices are gaining share fastest in retail clinic channels where waived-complexity status and minimal maintenance requirements outweigh absolute precision.
- HPLC:High-performance liquid chromatography maintains reference-method status for NGSP standardization and inter-laboratory calibration. Hospital laboratories with trained chromatography specialists favor HPLC for adjudication and quality control programs.
- Enzymatic:Enzyme-catalyzed detection offers intermediate precision with reduced equipment footprint compared to chromatography systems.
- Rapid Testing:Lateral flow and visual readout formats serve screening applications where immediate qualitative results suffice.
Margin concentration rests with HPLC; deployment flexibility favors Immunoassay.
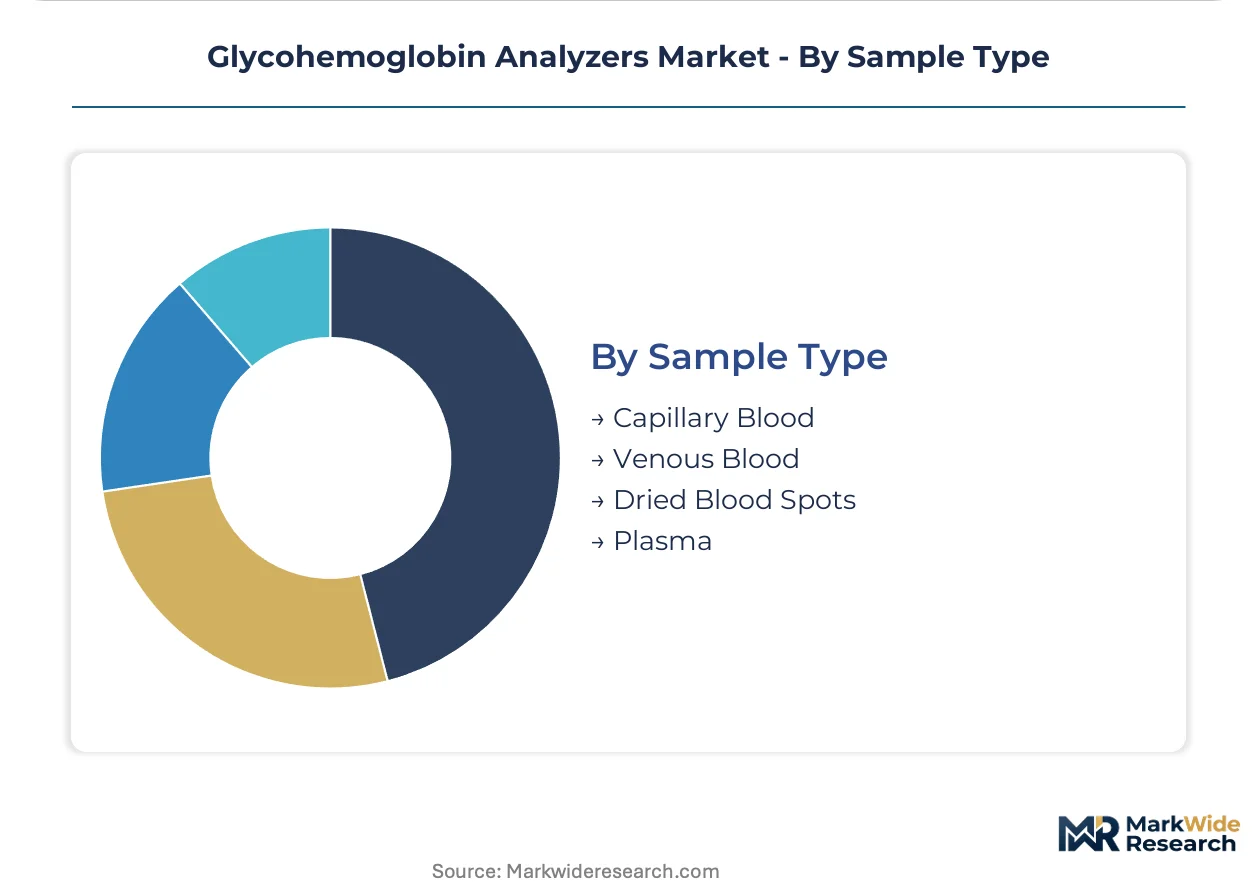
Sample Type:
Collection modality shapes analyzer design, patient compliance, and transport logistics across care settings.
- Capillary Blood:Finger-stick sampling eliminates phlebotomy requirements and enables immediate testing at point-of-care sites. Retail clinics and pharmacy chains in the United States prioritize capillary-compatible devices for walk-in diabetes screening.
- Venous Blood:Standard EDTA tubes support high-throughput batch processing in hospital laboratories with established phlebotomy infrastructure. Centralized facilities in Germany and Japan rely on venous sampling for standardized NGSP-traceable results.
- Dried Blood Spots:Filter paper collection facilitates remote sampling and mail-in laboratory testing for rural populations.
- Plasma:Separated plasma samples enable extended stability for reference laboratory networks with variable transport intervals.
Centralized infrastructure anchors Venous Blood; decentralized expansion favors Capillary Blood.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between centralized laboratory markets and distributed point-of-care deployment. Germany and Japan favor high-throughput HPLC installations in hospital core laboratories, while the United States and emerging markets accelerate compact immunoassay adoption at retail clinics and physician offices.
United States
Hospital system consolidation has compressed independent purchasing entities by over one-third in major metropolitan markets, driving enterprise-wide analyzer negotiations. The FDA's CLIA complexity classifications filter procurement toward certified high-throughput platforms, eliminating uncertified equipment from hospital laboratories. The Southeast corridor from Florida to Georgia anchors replacement demand as integrated delivery networks standardize glycohemoglobin testing protocols across multi-facility footprints.
Germany
Statutory health insurance coverage for diabetes screening sustains aggressive replacement cycles for NGSP-certified HPLC systems in centralized hospital laboratories. The EU IVDR framework imposes strengthened post-market surveillance and notified body conformity assessments on manufacturers seeking CE marking for European distribution. Bavaria's dense network of university hospitals and diagnostic reference laboratories concentrates demand for precision chromatography platforms with inter-laboratory calibration capabilities.
Japan
PMDA approval pathways for in-vitro diagnostics extend market entry timelines for non-domestic analyzer platforms, preserving structural advantage for established registrants. The country's aging diabetes population drives volume growth in both hospital core laboratories and clinic-based screening programs. The Kanto region surrounding Tokyo hosts the highest concentration of accredited clinical laboratories with trained chromatography specialists capable of maintaining reference-method HPLC installations.
China
NMPA regulatory requirements for in-vitro diagnostics create distinct approval pathways that favor domestic manufacturers with established quality management systems. Tier-one hospital expansions in provincial capitals absorb high-throughput laboratory analyzers, while county-level clinics adopt compact point-of-care devices for diabetes screening outreach. The Yangtze River Delta cluster from Shanghai to Hangzhou concentrates procurement authority for multi-hospital health systems negotiating standardized service terms.
India
CDSCO regulatory oversight of medical devices intensifies compliance requirements for imported analyzer platforms, though diagnostic laboratory chains pursue NGSP-certified systems for quality assurance credibility. Private hospital networks in metropolitan centers deploy automated HbA1c testing to differentiate diabetes management services. Maharashtra's Mumbai-Pune corridor anchors demand as corporate hospital chains consolidate laboratory operations under centralized purchasing agreements with volume-based reagent pricing.
Glycohemoglobin Analyzers Market Competitive Landscape
Capability concentration sits with chromatography specialists commanding reference-method credibility; scale advantage sits with diversified diagnostics conglomerates with embedded service networks. The vendor base stratifies across three tiers: integrated multinationals with regulatory affairs infrastructure, mid-sized platform specialists, and regional assemblers. Dominant competitive moves include predictive maintenance contract expansion to lock in recurring service revenue, and quality control ecosystem bundling to tether laboratories to proprietary consumable supply chains.
Among diversified diagnostics conglomerates, Abbott Laboratories, Siemens Healthineers AG, and Roche occupy positions anchoring the premium-tier vector through embedded service networks and regulatory compliance infrastructure. These entities exemplify the integrated archetype that absorbs disproportionate IVDR compliance costs while capturing consolidated purchasing from multi-hospital health systems. Mid-sized specialists including Bio-Rad Laboratories and Tosoh Bioscience represent the chromatography-focused tier, leveraging reference-method status to secure placement in external quality assurance programs and adjudication workflows.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche |
| Siemens Healthineers AG |
| Bio-Rad Laboratories |
| Danaher Corporation |
| Thermo Fisher Scientific |
| Trinity Biotech |
| Beckman Coulter |
| Tosoh Bioscience |
| Others |
Supply & Pricing Matrix
The Yangtze River Delta manufacturing cluster from Shanghai to Hangzhou concentrates precision optical and electromechanical component production for glycohemoglobin analyzers, with capacity utilization rates at contract manufacturers directly influencing reagent pricing power for downstream OEMs. This geographic concentration creates asymmetric bargaining dynamics where multi-hospital health systems negotiate volume-based consumable contracts while smaller diagnostic laboratories absorb premium pricing for proprietary cartridges.
Pricing Analysis
Long-term service contracts with embedded reagent offtake dominate hospital laboratory procurement, locking facilities into predictable per-test economics across five-to-seven year agreements. Pricing stratifies across NGSP-certified reference systems, CLIA-waived point-of-care devices, and economy-tier handheld units based on precision specifications and service bundling intensity. Cost compression in the point-of-care segment intensifies as pharmacy chains standardize procurement across retail clinic networks, while hospital laboratories exhibit lower price sensitivity due to reimbursement pass-through mechanisms and quality assurance requirements.
Supply Chain Analysis
Contract manufacturing for chromatography columns and optical detection modules concentrates in Germany, Japan, and the United States, with specialized foundries maintaining exclusive relationships with tier-one diagnostics conglomerates. Component sourcing draws from precision-machined flow cells, high-purity chromatography resins, and calibrated photodiode arrays, with single-source dependencies for NGSP-certified reference materials creating vulnerability to regulatory hold notifications. Distribution runs through manufacturer-direct field service organizations for laboratory analyzers and medical device distributors for point-of-care deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The glycohemoglobin analyzers market sits at an inflection where EU IVDR compliance costs and CLIA complexity enforcement are simultaneously accelerating consolidation and opening white-space for innovative service models. This regulatory compression favors players with embedded quality management infrastructure and predictive maintenance capabilities.
For Market Incumbents: Build switching-cost moats through predictive maintenance subscriptions that preempt component failures and compress mean time to repair. Consolidate position by acquiring mid-sized chromatography specialists facing disproportionate IVDR compliance burdens, while embedding remote calibration telemetry to tether laboratories to proprietary consumable ecosystems against emerging low-cost entrants. For New Entrants and Emerging Players: Pursue retail clinic channel expansion in the United States Southeast corridor, where integrated delivery network standardization has not yet penetrated independent urgent-care networks. Target waived-complexity immunoassay placements at pharmacy chains seeking same-result diabetes workflows, using direct-to-site distribution partnerships to bypass established GPO contracting structures. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors chromatography specialists with NGSP reference-method credibility and installed base density in Germany and Japan. Long-term viability hinges on dual-credential compliance infrastructure spanning NGSP and IFCC protocols, with acquisition targets showing proficiency testing program integration and external quality assurance lock-in. Monitor harmonization negotiations between standardization bodies as the decisive inflection signal for reimbursement-linked procurement access.| Strategic Initiative | Industry Significance |
|---|---|
| NGSP-IFCC Dual Certification Investment | Unlocks reimbursement-linked procurement channels in Germany and US hospital systems. |
| Predictive Maintenance Platform Deployment | Shifts Siemens Healthineers and Roche toward subscription uptime guarantees from break-fix contracts. |
| Retail Clinic Channel Partnership | Enables Bio-Rad and Abbott to bypass consolidated hospital purchasing committees. |
| Quality Control Ecosystem Bundling | Tethers laboratories to proprietary reagent supply through certified control material integration. |
| EU IVDR Regulatory Infrastructure Buildout | Absorbs compliance costs that would otherwise eliminate mid-sized chromatography specialists. |
Research Methodology
Cross-validation between primary interviews with hospital laboratory directors, CLIA compliance officers, and GPO contracts managers and secondary validation through FDA 510(k) filings, NGSP certification records, and hospital procurement database extracts anchors the qualitative findings. Conversations with biomedical engineers and diagnostic reference laboratory technical directors inform technology adoption patterns, while customs data and SEC 10-K segment disclosures provide shipment and revenue triangulation. Bottom-up modeling of installed base replacement cycles and top-down macroeconomic calibration ensure convergence across estimation approaches.
Calibration against historical NGSP certification timelines and CLIA complexity reclassification events refines the analytical framework across the projection horizon. Segmentation dimensions include product type, end-user setting, technology platform, and sample collection modality, with regional regulatory clusters modeled separately for US CLIA, EU IVDR, and Japan PMDA pathways. CAGRs derive from logistic diffusion curves fitted to replacement cycle data and point-of-care penetration rates, with diabetes prevalence forecasts and statutory screening mandate expansion serving as demand-side anchors.
Macroeconomic conditions sit as an overlay; deviation in healthcare reimbursement rates, diagnostic laboratory staffing availability, or chromatography resin supply would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory harmonization progress and IVDR implementation timelines. Quarterly review of NGSP-IFCC protocol reconciliation statements and notified body conformity assessment backlogs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Global Blood Gas Analyzers Market
Laboratory Equipment
Centrifuge Tubes Market
Laboratory Equipment
Mobile Sterile Units Market
Laboratory Equipment
Capillary Blood Collection Tubes Market
Laboratory Equipment
Laboratory Pulverizer Market
Laboratory Equipment
United States Pipette Tips Market
Laboratory Equipment
Microplate Washer Market
Laboratory Equipment
C-Reactive Protein Analyzers Market
Laboratory Equipment
Histopathology Testing Equipment Market
Laboratory Equipment
Laboratory Temperature Control Units Market
Laboratory Equipment
Lab Accessories Market
Laboratory Equipment
Global Hematology Instruments and Reagents Market
Laboratory Equipment
Blood Testing Equipment Market
Laboratory Equipment
Test Tube Market
Laboratory Equipment
Laboratory Ovens Market
Laboratory Equipment
Global Laboratory Glassware Washers Market