
 US Disposable Face Mask Market | 2026-2036
US Disposable Face Mask Market Size, Share, and Industry Trends Forecast 2026-2036
US Disposable Face Mask Market Analysis
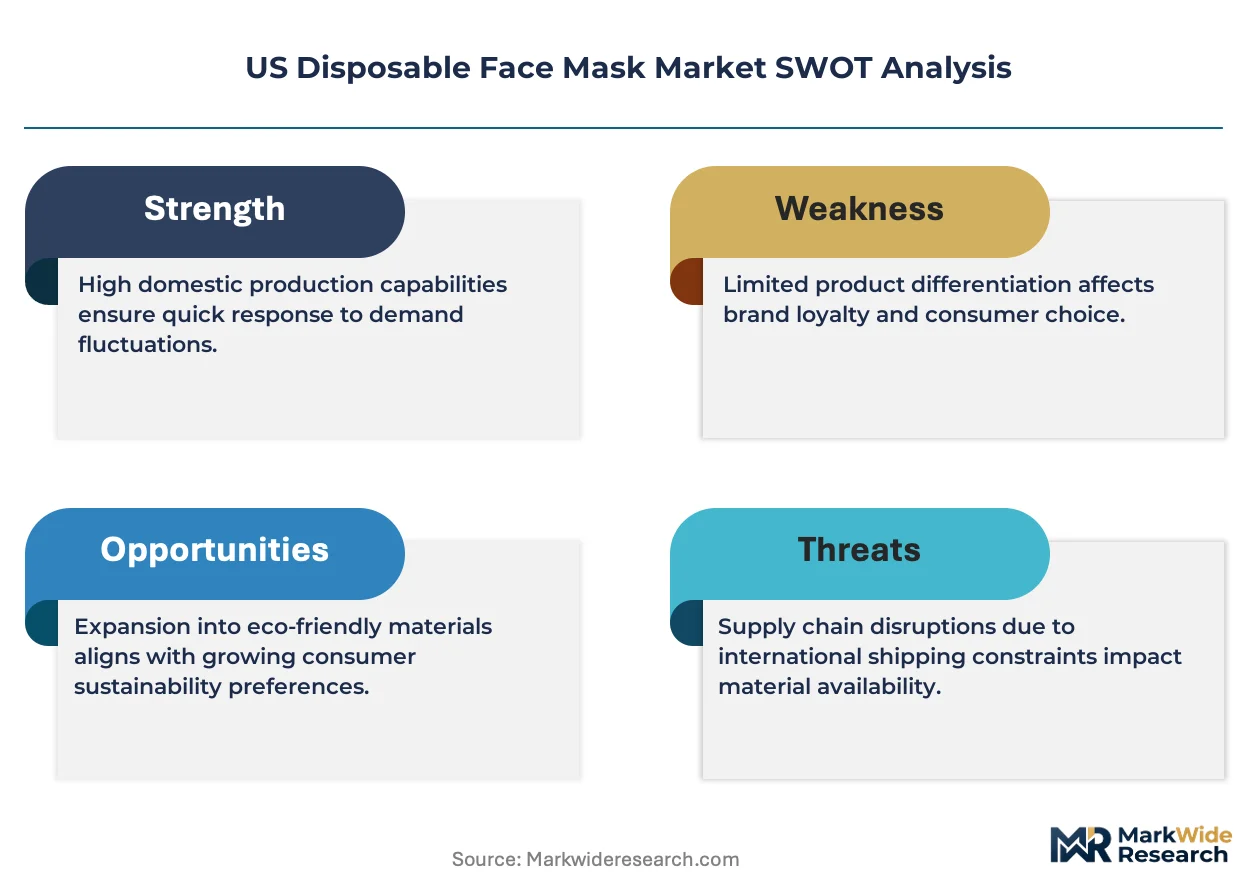
Advanced melt-blown polypropylene filtration technology is reconfiguring manufacturing throughput and particle capture consistency across the US disposable face mask supply base. 3M leverages deep materials science expertise to sustain premium positioning in N95 respirator segments. Kimberly-Clark Corporation anchors institutional contracts with acute-care hospital networks through direct distribution agreements. Moldex-Metric, Inc. specializes in domestically produced respirators, competing on shorter lead times versus offshore alternatives.
A US disposable face mask constitutes a single-use respiratory protective device constructed from nonwoven polypropylene layers, typically featuring melt-blown middle filtration media with bacterial filtration efficiency ratings exceeding 95 percent, designed to block particulate matter and limit pathogen transmission in occupational and clinical environments. Surgical masks dominate hospital procurement volumes as standard precaution equipment, while N95 respirators command concentrated margin pools in industrial and laboratory settings where OSHA-mandated fit-testing protocols apply. Personal use applications have matured post-pandemic, with retail channels now absorbing excess polypropylene-based inventory that shifted from healthcare allocation.
FDA oversight of surgical masks as Class II medical devices, combined with NIOSH certification requirements for N95 respirators and OSHA respiratory protection standards, creates a multi-layered compliance architecture that filters market entrants by testing capacity and quality system documentation. The CDC's periodic updates to infection control guidance in healthcare settings directly trigger restocking cycles across hospital and clinic end users. Stakeholders must monitor whether OSHA advances permanent aerosol transmission standards beyond current COVID-19-specific frameworks, as this would structurally expand respirator mandate coverage into previously unregulated workplace categories.
Market Dynamics
Post-pandemic infection control protocols have institutionalized elevated procurement volumes across US healthcare facilities, permanently embedding disposable face masks into standard precaution workflows rather than episodic emergency stockpiling.
Growth Catalysts
- OSHA Respiratory Protection Standards:Mandatory fit-testing protocols in industrial and laboratory settings sustain N95 respirator demand beyond healthcare applications, creating dual-market pull for certified manufacturers.
- Melt-blown polypropylene filtration:Advanced nonwoven manufacturing technology improves bacterial filtration efficiency consistency, enabling domestic producers to compete on performance parity with offshore suppliers.
- Texas and Florida hospital systems:Large integrated delivery networks in these states standardize bulk purchasing agreements, concentrating procurement volume and stabilizing manufacturer revenue predictability.
Market Restraints
- Polypropylene feedstock volatility:Petrochemical input cost fluctuations compress margin stability for domestic manufacturers dependent on Gulf Coast resin supply chains.
- Offshore supply concentration:Asian producers dominate economy-tier surgical mask segments, limiting pricing power for US-based manufacturers without NIOSH certification differentiation.
- FDA Class II device pathways:Extended 510(k) clearance timelines for novel filtration media create regulatory friction against rapid product iteration cycles.
Strategic Opportunities
- California occupational safety expansion:State-level aerosol transmission standards beyond federal minimums create mandate coverage in agricultural processing and warehouse logistics previously unregulated.
- Direct-to-institution distribution:Bypassing traditional medical supply distributors through hospital system GPO contracts captures margin previously absorbed by intermediaries.
- Antimicrobial coating convergence:Integration of copper-infused or silver-ion surface treatments with standard melt-blown substrates commands premium positioning in surgical suites.
Industry Challenges
- NIOSH certification backlog:Extended approval timelines for new respirator designs delay market entry and tie up capital in pre-revenue inventory.
- Polypropylene supply chain reconfiguration:Domestic resin capacity constraints force manufacturers to maintain dual-sourcing relationships across Gulf Coast and imported feedstock channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Disposable Face Mask Market |
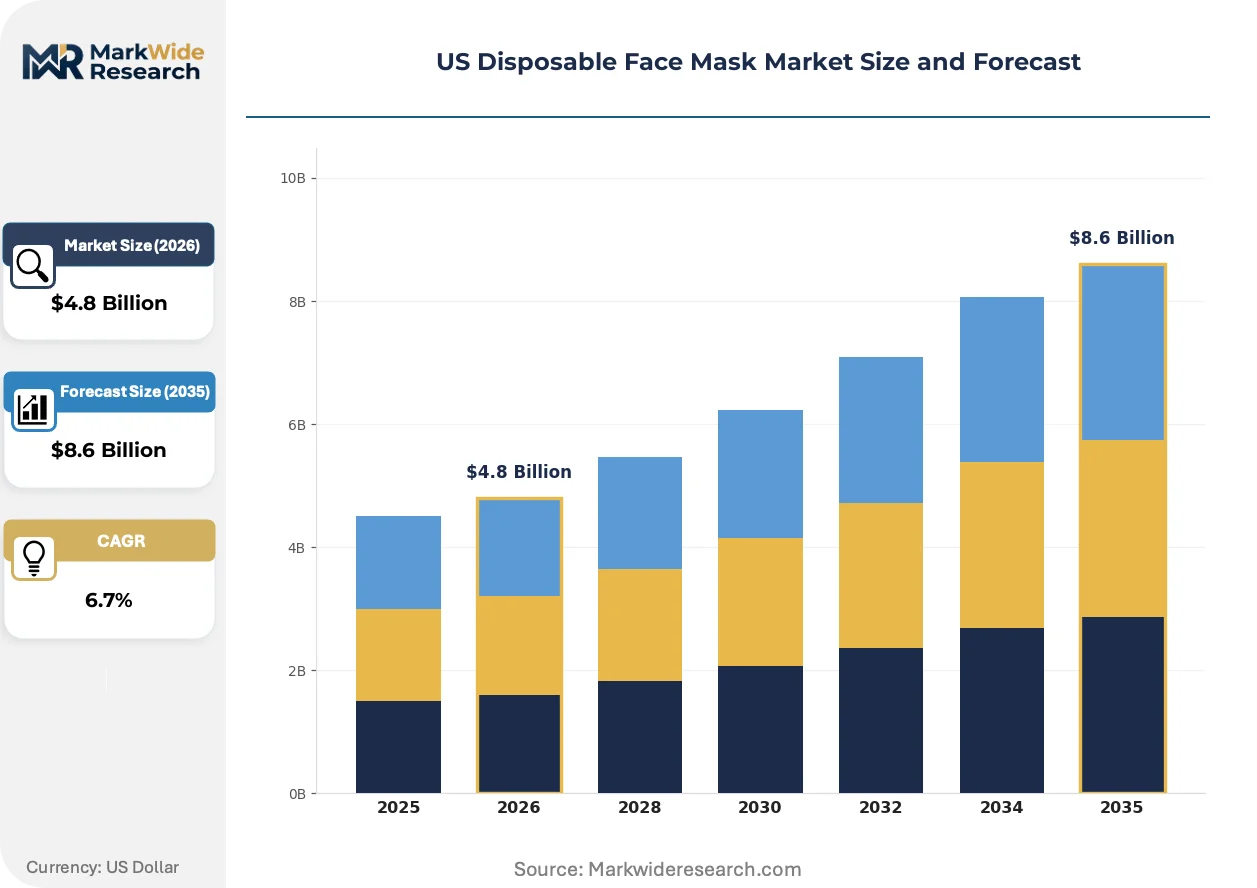
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Masks, N95 Respirators, Cloth Masks, Face Shields Application: Healthcare, Industrial, Retail, Personal Use Material: Polypropylene, Cotton, Polyester, Foam End User: Hospitals, Clinics, Laboratories, Consumers |
| Companies Covered | 3M, Honeywell International Inc., Moldex-Metric, Inc., Kimberly-Clark Corporation, Medline Industries, LP, Owens & Minor, Inc., Cardinal Health, SAS Safety Corp., The Gerson Companies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Disposable Face Mask Market Emerging Trajectories
Filtration media engineering and regulatory clarity are compressing product lifecycles while reshaping how manufacturers compete on certification tier rather than commodity volume alone.
Electrostatic charging of melt-blown polypropylene is virtualizing particle capture efficiency without denser material construction, enabling lighter-weight respirators that reduce wearer fatigue during extended shifts. Industrial employers in construction and manufacturing are adopting these designs at accelerated replacement cycles compared to legacy N95 models. This technology is virtualizing the tradeoff between comfort and protection that previously limited respirator compliance rates in non-healthcare occupational settings.
FDA's updated enforcement discretion policies for face masks during public health emergencies continue refining manufacturer compliance obligations, particularly around quality system documentation and post-market surveillance requirements. The agency's shifting posture between emergency use pathways and standard 510(k) clearance creates planning uncertainty for product development pipelines. Surgical mask producers with established quality management systems are responding by bifurcating product lines into emergency-stockpile and standard-commercial tiers to maintain regulatory optionality.
Hospital procurement departments now consolidate respiratory protection purchasing through system-wide standardization committees rather than allowing individual facility autonomy, compressing vendor counts and extending contract durations. This concentration transfers negotiation leverage from distributed clinical staff to centralized supply chain executives who prioritize total cost of ownership over unit price. The shift is most visible in multi-state health systems across the Southeast and Midwest, where standardized formularies now specify single-manufacturer respirator lines to simplify fit-testing protocols and reduce SKU complexity.
US Disposable Face Mask Market Segmentation
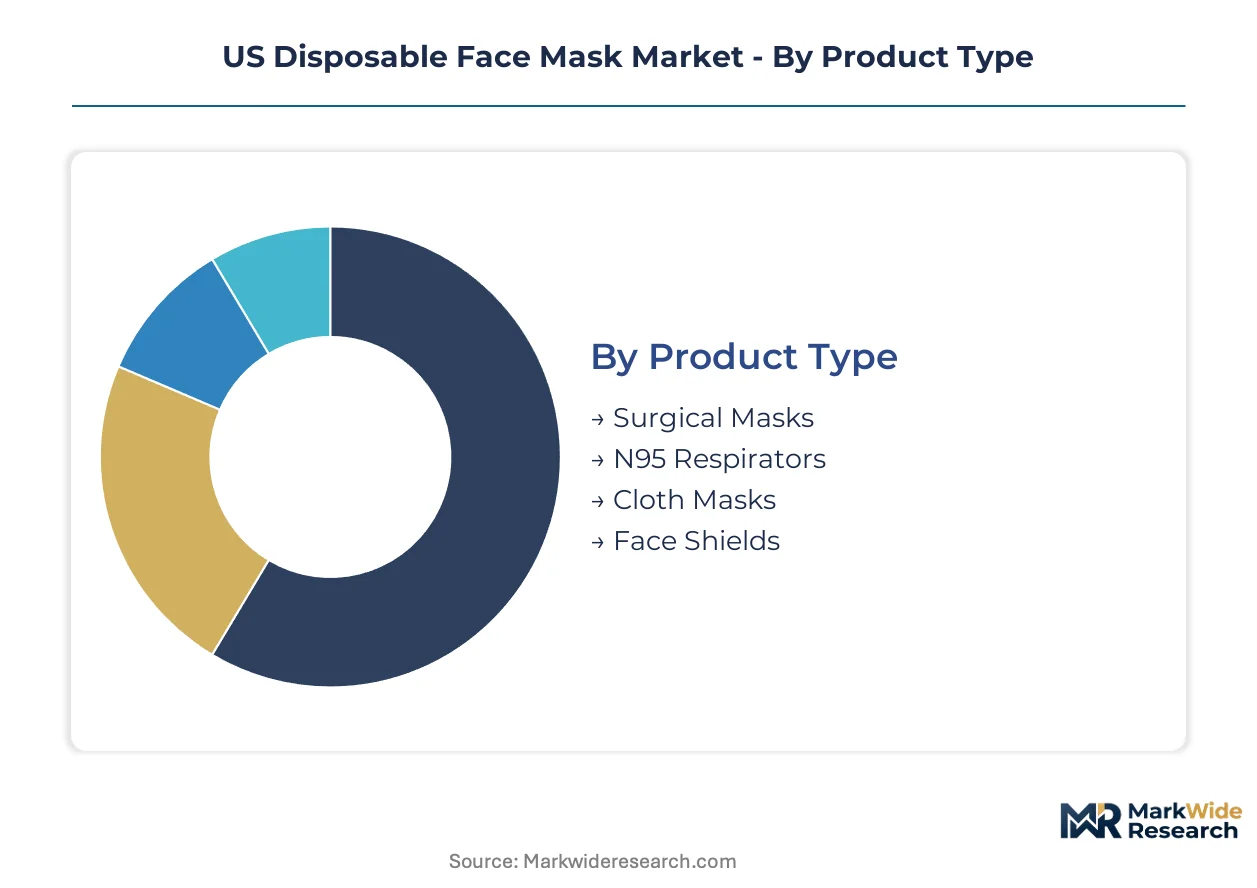
US disposable face mask demand fragments across four distinct taxonomies that govern procurement logic, regulatory pathways, and margin architecture. Product type determines certification burden and pricing tier. Application and end-user concentration shape volume predictability and contract structures.
Product Type:
Mature filtration technologies dominate hospital procurement, while emerging designs target comfort-driven replacement cycles in extended-wear environments.
- Surgical Masks:Three-layer nonwoven construction with melt-blown polypropylene middle filtration media and bacterial filtration efficiency ratings exceeding 95 percent. Hospital systems across Texas, California, and Florida standardize bulk purchasing agreements around these devices, embedding them into institutional infection control protocols as standard precaution equipment.
- N95 Respirators:NIOSH-certified tight-fitting respirators utilizing electrostatically charged polypropylene filtration media to achieve 95 percent particle capture at 0.3 microns. OSHA-mandated fit-testing protocols in industrial and laboratory settings sustain dual-market demand beyond healthcare applications, creating concentrated margin pools for certified domestic manufacturers.
- Cloth Masks:Reusable woven fabric barriers with variable filtration performance, primarily absorbed by retail channels and personal use segments post-pandemic.
- Face Shields:Polycarbonate or PET splash barriers designed as adjunctive protection rather than primary respiratory devices, deployed in dental and surgical settings for fluid exposure control.
Surgical masks handle the majority of throughput; N95 respirators are expanding most quickly on share as OSHA coverage extends into previously unregulated workplace categories.
Application:
Volume concentration follows regulatory mandate intensity, with cost tier separating institutional contracts from discretionary consumer purchases.
- Healthcare:Acute-care hospitals, ambulatory surgery centers, and long-term care facilities sustain elevated procurement volumes through institutionalized post-pandemic infection control protocols. CDC guidance updates directly trigger restocking cycles.
- Industrial:Manufacturing, construction, and agricultural processing employers face OSHA respiratory protection standards requiring fit-tested N95 or equivalent protection for aerosol exposure.
- Retail:Pharmacies, big-box stores, and e-commerce channels absorbed excess polypropylene-based inventory shifted from healthcare allocation as pandemic emergency demand subsided.
- Personal Use:Discretionary consumer purchases driven by seasonal illness patterns and individual risk tolerance rather than regulatory mandate.
Healthcare commands absolute volume scale; industrial applications are climbing the fastest as state-level occupational safety expansions broaden mandate coverage.
Material:
Supply concentration in Gulf Coast petrochemical corridors determines feedstock cost volatility and domestic manufacturing competitiveness.
- Polypropylene:Dominant melt-blown nonwoven feedstock enabling bacterial filtration efficiency consistency. Domestic resin capacity constraints force manufacturers to maintain dual-sourcing relationships across Gulf Coast and imported channels.
- Cotton:Natural fiber alternative for reusable cloth mask constructions, limited by moisture retention and variable filtration performance compared to synthetic nonwovens.
- Polyester:Synthetic woven or nonwoven option for economy-tier disposable and reusable designs, offering lower raw material cost but reduced electrostatic charge retention.
- Foam:Polyurethane or polyethylene cushioning materials for respirator face seals and comfort layers, critical for fit integrity in NIOSH-certified devices.
Polypropylene underpins the vast majority of medical-grade production; polyester is gaining share fastest in economy-tier consumer segments.
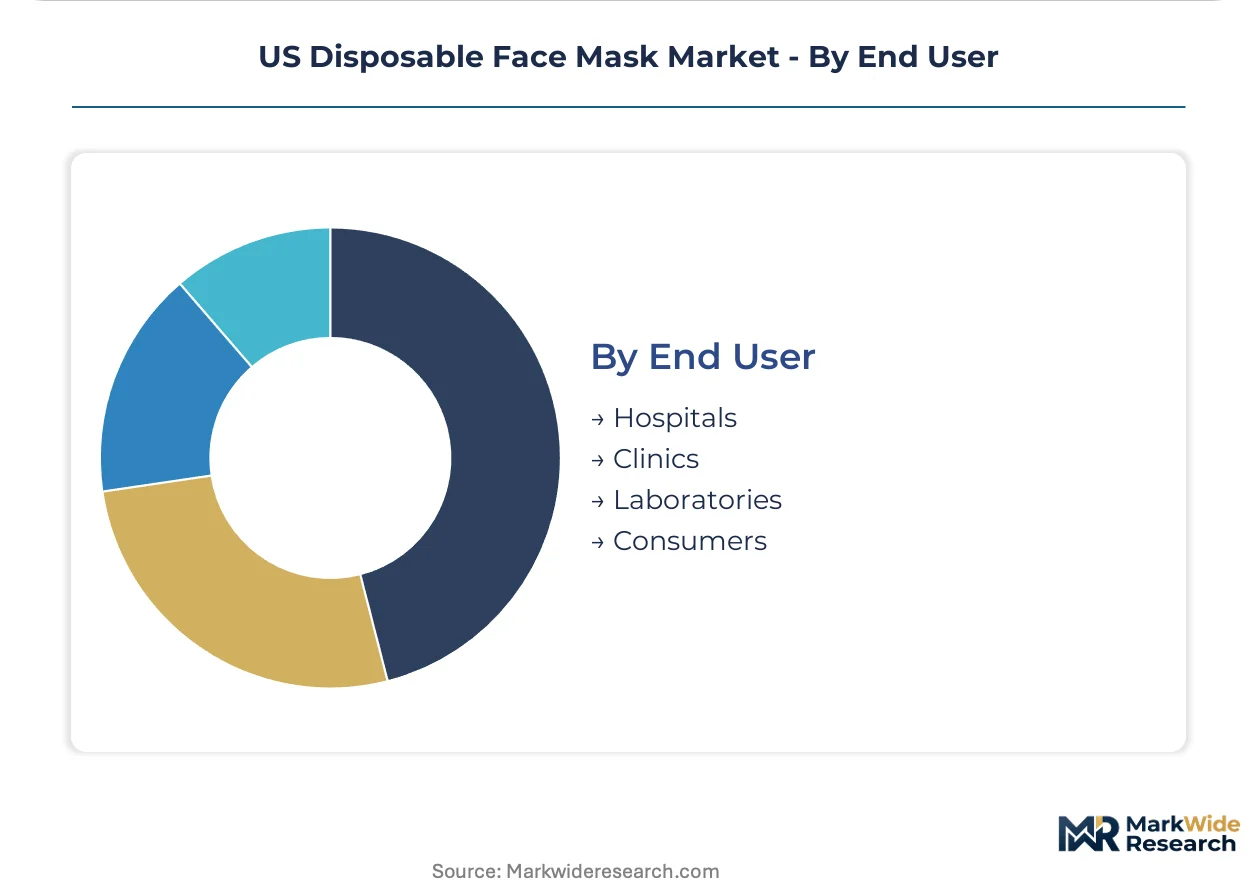
End User:
Customer type determines contract structure, with centralized purchasing committees compressing vendor counts and extending agreement durations.
- Hospitals:Large integrated delivery networks standardize formularies through system-wide committees, prioritizing total cost of ownership and fit-testing protocol simplification over unit price.
- Clinics:Outpatient and specialty practices with lower volume but similar regulatory requirements, often purchasing through group purchasing organizations or regional distributors.
- Laboratories:Research and diagnostic facilities requiring N95 or higher protection under OSHA standards, with concentrated demand in biotechnology clusters.
- Consumers:Individual purchasers through retail and e-commerce channels, price-sensitive and driven by seasonal demand fluctuations without institutional contract stability.
Hospitals concentrate procurement volume through multi-year agreements; laboratories are expanding most quickly as biotechnology manufacturing capacity scales domestically.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US disposable face mask market operates with net import reliance in economy-tier surgical segments offset by domestic production concentration in NIOSH-certified respirators, creating distinct regional supply-demand balances across manufacturing clusters and consumption centers.
Texas
Large integrated delivery networks including Houston Methodist and Baylor Scott & White standardize bulk purchasing agreements that concentrate procurement volume. OSHA maintains active enforcement of respiratory protection standards across Gulf Coast petrochemical facilities and energy infrastructure projects. The Houston medical center corridor anchors hospital system demand while Dallas-Fort Worth distribution hubs coordinate regional supply chain logistics.
California
State-level aerosol transmission standards exceed federal OSHA minimums, expanding mandate coverage into agricultural processing in the Central Valley and warehouse logistics across the Inland Empire. Cal/OSHA's permanent infectious disease prevention regulations sustain elevated institutional procurement beyond federal baseline requirements. The Los Angeles-Long Beach port complex handles substantial polypropylene resin imports feeding West Coast manufacturing operations.
Florida
Retirement-age demographic concentration drives sustained demand in long-term care facilities and hospital systems across the Tampa Bay and South Florida corridors. Florida Agency for Health Care Administration licensing requirements embed infection control protocols into facility operations. The Miami-Dade medical device distribution cluster coordinates supply chain flows throughout the Southeast and Caribbean markets.
Illinois and Michigan
Manufacturing and automotive production facilities in Detroit-Warren and Chicago-Naperville sustain industrial N95 respirator demand under OSHA respiratory protection mandates. Michigan Occupational Safety and Health Administration maintains active inspection programs in metal fabrication and assembly operations. The Chicago regional distribution network serves as a consolidation point for Midwest hospital system group purchasing organizations.
New York and New Jersey
Acute-care hospital density in the New York City metropolitan area generates concentrated procurement volume through multi-hospital system standardization committees. New York State Department of Health regulations require specific filtration efficiency documentation for surgical mask procurement in state-licensed facilities. The Port of Newark-Elizabeth handles substantial East Coast import volumes of nonwoven polypropylene materials.
US Disposable Face Mask Market Vendor Landscape
On the supply side, the industry is bifurcated between premium-tier NIOSH-certified respirator producers and economy-tier surgical mask fabricators facing offshore price competition. Domestic manufacturers cluster around Gulf Coast petrochemical corridors for polypropylene feedstock access, while distribution relationships with hospital group purchasing organizations determine volume capture. Three strategic archetypes dominate: diversified materials science conglomerates with deep filtration expertise, specialized respiratory protection manufacturers with domestic production assets, and institutional supply distributors with embedded hospital system contracts. Capacity expansion and direct-to-institution distribution partnerships represent the dominant competitive moves reshaping channel economics.
Within the diversified materials science tier, 3M and Honeywell International Inc. occupy positions anchored by decades of NIOSH certification expertise and multi-industry distribution infrastructure. Moldex-Metric, Inc. exemplifies the specialized domestic manufacturer archetype, competing on shorter lead times versus offshore alternatives. Kimberly-Clark Corporation represents the institutional hygiene conglomerate model, leveraging direct distribution agreements with acute-care hospital networks to secure recurring procurement volumes.
| Leading Market Players |
|---|
| 3M |
| Honeywell International Inc. |
| Moldex-Metric, Inc. |
| Kimberly-Clark Corporation |
| Medline Industries, LP |
| Owens & Minor, Inc. |
| Cardinal Health |
| SAS Safety Corp. |
| The Gerson Companies |
| Others |
Supply Flow & Price Mechanics
The Houston Ship Channel freight corridor anchors resin cost dynamics that cascade through domestic melt-blown polypropylene supply, compressing margin pools for manufacturers without NIOSH certification while amplifying price differentiation between emergency-stockpile and standard-commercial tiers.
Pricing Analysis
Electrostatic-charging technology-generation pricing gaps separate legacy melt-blown constructions from next-generation lighter-weight respirators, with prior-generation surgical masks facing steepest erosion. Three-tier pricing structure across premium N95, standard surgical, and economy non-certified levels stratifies by FDA Class II pathway completion and NIOSH approval status. Cost compression in economy-tier segments intensifies because Asian offshore producers flood retail channels with non-medical-grade inventory. Hospital systems demonstrate lowest price sensitivity through multi-year GPO contracts, while personal-use consumers exhibit highest elasticity to unit cost fluctuations.
Supply Chain Analysis
Domestic contract-manufacturing concentration centers on Gulf Coast petrochemical corridors where Braskem and ExxonMobil resin operations feed nonwoven converters, supplemented by Asian fabricators in China and Vietnam handling economy-tier surgical mask assembly. Polypropylene pellet, melt-blown fabric, and NIOSH testing capacity constitute critical input dependencies. Single-source vulnerability concentrates in electrostatic charging equipment where European suppliers dominate. Distribution runs through hospital GPO contracts, industrial safety distributors, and retail pharmacy chains in descending volume priority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reusable elastomeric respirator substitution threatens disposable N95 volume pools as OSHA fit-testing cost burdens push industrial employers toward extended-use alternatives. Incumbents must navigate this technology displacement while defending institutional contract positions.
For Market Incumbents: Insulate hospital system relationships through direct distribution agreements that bypass Medline and Cardinal Health margin absorption, while accelerating NIOSH certification for electrostatically charged next-generation designs to outpace reusable respirator substitution. Backward integration into Gulf Coast polypropylene resin sourcing defends against petrochemical feedstock volatility that compresses margin stability for contract-dependent manufacturers.
For New Entrants and Emerging Players: California agricultural processing and warehouse logistics facilities represent the most penetrable entry point, as Cal/OSHA aerosol transmission mandates exceed federal coverage without incumbent respirator line standardization. NIOSH-certified domestic production with sub-90-day lead times versus offshore alternatives offers the strongest go-to-market angle against established hospital GPO lock-in.
For Investors and Strategic Acquirers: Specialized respiratory protection manufacturers with captive melt-blown capacity and established NIOSH approval pipelines present acquisition targets with durable moats. Long-term viability hinges on OSHA permanent aerosol standard expansion beyond COVID-specific frameworks. Quarterly review of NIOSH certification backlog duration and Cal/OSHA enforcement intensity is advised to detect inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| NIOSH Certification Investment | Accelerated approval pipelines capture OSHA-mandated industrial demand before reusable respirator substitution advances. |
| Direct-to-Institution Distribution | Bypassing Medline and Cardinal Health GPO intermediaries recaptures margin previously absorbed by supply chain layers. |
| Antimicrobial Coating Integration | Copper-ion surface treatments command premium positioning in surgical suites where infection control committees specify enhanced barriers. |
| Backward Resin Integration | Gulf Coast polypropylene sourcing hedges against petrochemical volatility that destabilizes domestic manufacturing cost structures. |
| California Market Expansion | Cal/OSHA permanent infectious disease regulations extend mandate coverage into agricultural and logistics sectors previously unregulated. |
Methodological Framework
Operator-level perspectives from hospital procurement directors, GPO contract managers, biomedical engineers, and industrial safety officers anchored the qualitative base, cross-referenced with FDA 510(k) filings, NIOSH certification databases, OSHA enforcement records, and hospital supply chain disclosures. Bottom-up volume estimates from state-level health facility licensing data and top-down resin consumption figures from Gulf Coast petrochemical reporting were triangulated to constrain forecast ranges.
Scenario-bracketing across conservative, baseline, and expansion cases shaped the analytical framework across the analysis window, with segmentation modeling across product type, application, material, and end-user dimensions. CAGRs were derived from fitted trend extrapolation against historical procurement cycle data and regulatory trigger event analysis, incorporating CDC guidance update frequency and OSHA standard revision timelines as industry-specific forecast inputs.
Stress conditions across polypropylene feedstock cost bands, NIOSH approval timeline extensions, and Cal/OSHA enforcement intensity variations were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about institutional infection control protocol permanence and industrial mandate expansion trajectories. Quarterly review of NIOSH certification queue length and state-level occupational safety regulatory filings is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Suture Wire Market
Medical Supplies
Bleeding Control Kit Market
Medical Supplies
North America Nasal Spray Market
Medical Supplies
Medical Gas Market
Medical Supplies
Global Disposable Urinary Drainage Bag Market
Medical Supplies
Europe Insulin Syringe Market
Medical Supplies
Bile Collection Bags Market
Medical Supplies
Global Sterilization Container Systems Market
Medical Supplies
Push-In Plug Vials Market
Medical Supplies
Global Urinary Drainage Bags Market
Medical Supplies
Super Absorbent Dressings Market
Medical Supplies
UAE Hospital Supplies Market
Medical Supplies
Centrifuge Bottles Market
Medical Supplies
Global Contact Lens Solution Market
Medical Supplies
Global Surgical Pledgets Market
Medical Supplies
Medical Plastics Market