
 Asia Pacific Wound Care Biologics Market | 2026-2036
Asia Pacific Wound Care Biologics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Wound Care Biologics Market Insights
Outcome-based service contracts for wound closure monitoring is rebalancing how biologics vendors capture recurring value across Asia Pacific hospital networks. Smith & Nephew Plc anchors its regional position through dedicated wound care specialist teams in Australian and Japanese metropolitan markets. MiMedx leverages amniotic tissue processing capabilities to differentiate within cellular therapy supply chains serving South Korean burn centers. Organogenesis Inc. competes on manufactured skin substitute scale, sustaining cost advantages for chronic wound protocols in Indian multi-specialty hospitals.
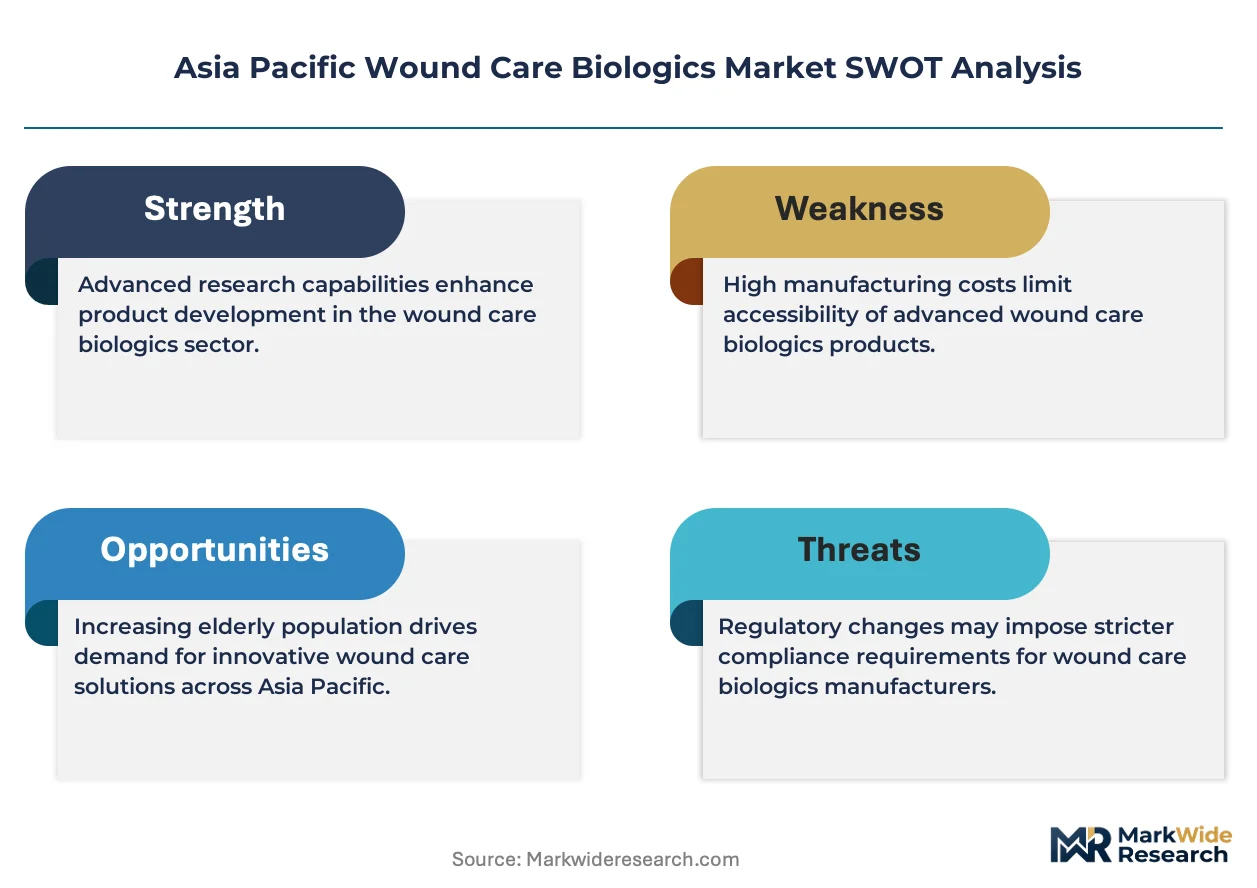
Asia Pacific wound care biologics comprise engineered living tissues, extracellular matrix derivatives, and growth factor formulations applied to dermal regeneration, typically requiring cryopreservation or sterile hydration with defined shelf-life parameters. These products serve to accelerate granulation tissue formation and re-epithelialization in wounds that stall under standard moist wound healing protocols. Collagen-based matrices command mature volume pools across Australian and Japanese outpatient clinics, while cellular therapy segments capture premium positioning in South Korean and Singaporean tertiary settings where reimbursement favors autologous and allogeneic skin substitutes. Growth factor therapy occupies a narrowing mid-tier as hospitals weigh cost-per-closure against advanced dressing alternatives for surgical wound prophylaxis.
PMDA's regenerative medicine framework and Australia's TGA biologicals designation create divergent approval cost structures that filter which developers enter each national market. India's CDSCO biologic licensing requirements for imported wound products add testing layers that favor local contract manufacturing partnerships over direct import models. China's NMPA innovation priority review channels are compressing timelines for domestically manufactured hydrogel and alginate variants. Stakeholders must monitor how reimbursement harmonization across ASEAN national health insurance schemes reshapes cross-border product registration strategies and distribution investment priorities.
Market Dynamics
Hospital procurement of advanced biologic dressings is rebalancing toward outcome-based service contracts, compressing traditional product-centric sales cycles and forcing vendors to embed monitoring capabilities into chronic wound protocols across tertiary care networks.
Growth Catalysts
- PMDA Accelerated Pathways:Japan's regenerative medicine framework shortens approval timelines for cellular therapy products, enabling faster market entry for skin substitute developers targeting burn and diabetic foot ulcer segments.
- Diabetic Foot Ulcer Incidence:China's tier-one cities are witnessing specialized wound center expansion driven by rising diabetes prevalence, creating concentrated demand pools for extracellular matrix and growth factor formulations.
- Amniotic Tissue Processing:South Korean burn centers are integrating advanced cellular therapy supply chains, with allogeneic skin substitutes capturing premium positioning through superior granulation tissue formation outcomes.
Market Restraints
- Cryopreservation Infrastructure:Cold chain requirements for living tissue products limit distribution reach to tier-two and tier-three cities in India and Southeast Asia, constraining addressable market expansion.
- CDSCO Import Testing Layers:India's biologic licensing requirements for imported wound products add validation costs that favor local contract manufacturing partnerships over direct import models.
- Growth Factor Cost Compression:Hospitals are substituting recombinant growth factor therapy with advanced moist dressings for surgical wound prophylaxis, narrowing the mid-tier product segment.
Strategic Opportunities
- ASEAN Reimbursement Harmonization:Cross-border alignment of national health insurance schemes across Southeast Asia is reshaping product registration strategies, enabling centralized distribution hubs serving multiple markets.
- Domestic Hydrogel Manufacturing:China's NMPA innovation priority review channels favor domestically produced alginate variants, creating regulatory tailwinds for local production scale-up.
- Outpatient Clinic Expansion:Australian and Japanese metropolitan markets are seeing collagen-based matrix volume pools shift toward ambulatory settings, opening channel diversification beyond inpatient procurement.
Industry Challenges
- Reimbursement Code Fragmentation:Wound care biologics face inconsistent coverage determination across Australian private insurers and Japanese statutory health insurance, complicating pricing strategy and revenue predictability.
- Specialist Workforce Scarcity:Tertiary wound center expansion in India and China outpaces training pipelines for certified wound care nurses and tissue viability specialists, creating treatment protocol standardization gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Wound Care Biologics Market |
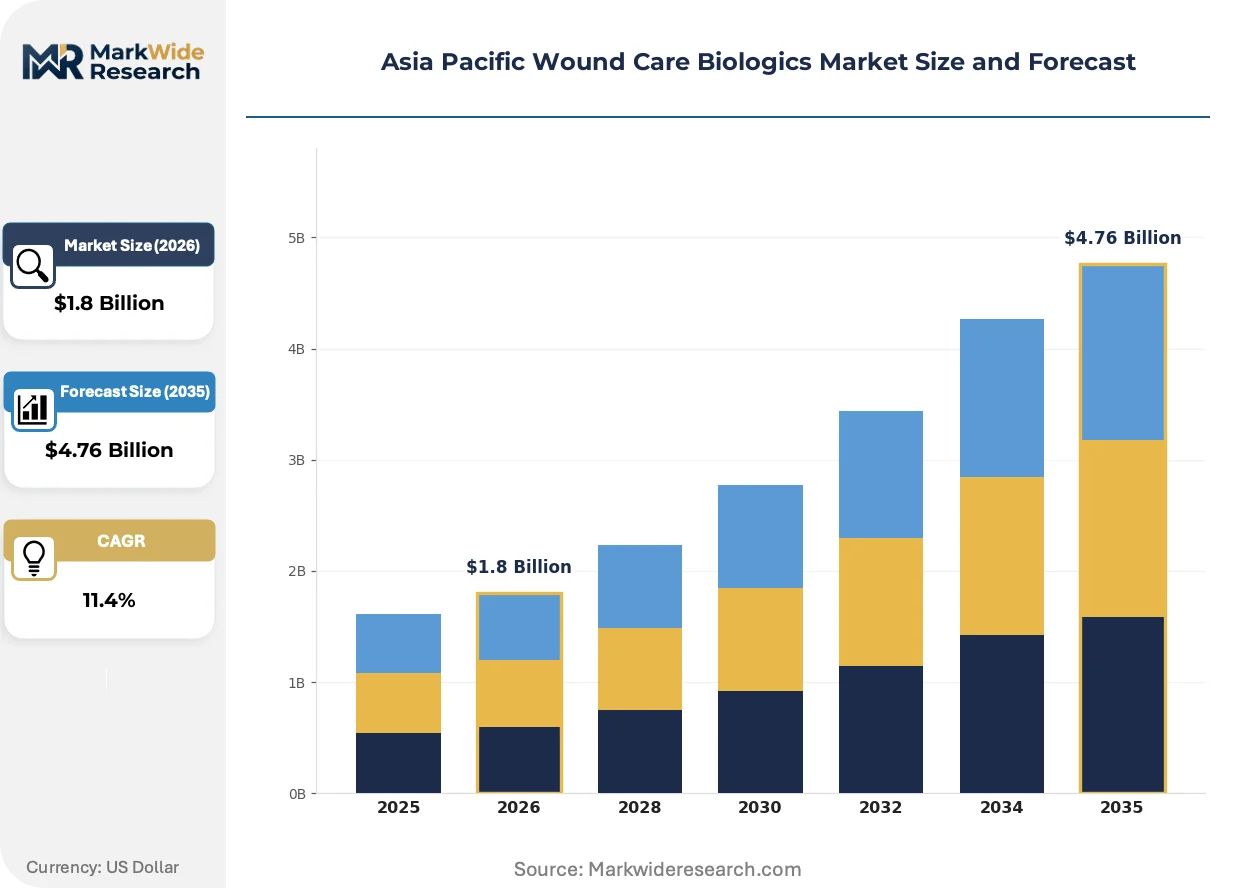
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collagen, Hydrogel, Foam Dressings, Alginate End User: Hospitals, Home Care, Long-term Care Facilities, Outpatient Clinics Application: Chronic Wounds, Surgical Wounds, Burns, Traumatic Wounds Technology: Advanced Dressings, Growth Factor Therapy, Cellular Therapy, Skin Substitutes |
| Companies Covered | Skye Biologics, Vericel Corporation, Smith & Nephew Plc, GC Cell, MiMedx, Integra LifeSciences Holdings Corporation, Kerecis, Osiris Therapeutics Inc., Organogenesis Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Wound Care Biologics Market Trends and Innovations
Digital wound measurement and remote monitoring capabilities are embedding into biologics service contracts, compressing the feedback loop between product application and clinical outcome verification across Asia Pacific hospital procurement frameworks.
3D bioprinting of dermal scaffolds is automating the customization of skin substitute architecture to patient-specific wound geometries. South Korean research hospitals are piloting these systems for complex burn reconstruction cases. The technology is automating manual cell seeding processes that previously limited production throughput and consistency in allogeneic tissue manufacturing.
PMDA's regenerative medicine framework and Australia's TGA biologicals designation are creating divergent approval cost structures that filter market entry decisions. Developers face distinct clinical evidence requirements and post-market surveillance obligations in each jurisdiction. Cellular therapy segments in Japan are responding with dedicated regulatory affairs capabilities, while Australian sponsors leverage TGA's priority review vouchers for breakthrough designations.
Specialized wound center networks in China are consolidating purchasing authority previously dispersed across departmental procurement committees. Hospital groups in Shanghai and Beijing are centralizing biologics selection through formulary committees that evaluate cost-per-closure metrics against standard of care. This concentration is most visible in diabetic foot ulcer protocols where tertiary centers now drive volume allocation decisions for advanced dressing categories.
Asia Pacific Wound Care Biologics Market Segmentation
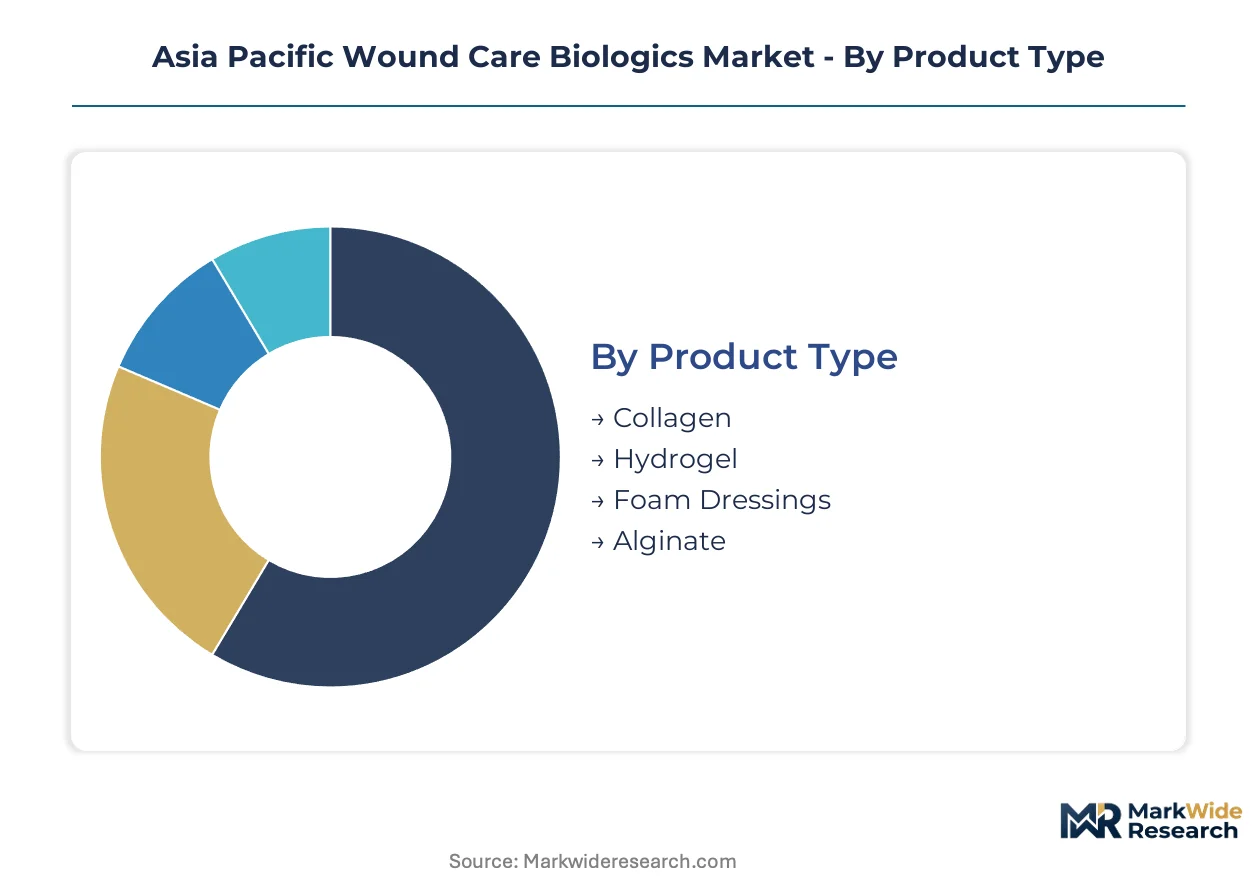
Product differentiation across the Asia Pacific wound care biologics market follows distinct upgrade cycles tied to reimbursement evolution and clinical evidence accumulation. Procurement committees evaluate segment transitions based on cost-per-closure metrics rather than unit pricing alone.
Product Type:
Replacement cycles for primary dressings accelerate as hospitals migrate from passive moisture management toward active biological intervention.
- Collagen:Extracellular matrix proteins derived from bovine or porcine sources provide scaffold architecture for cellular migration and granulation tissue formation. Australian and Japanese outpatient clinics command mature volume pools for these matrices, though reimbursement compression is narrowing margin expansion.
- Hydrogel:Cross-linked polymer networks maintain moist wound environments while enabling autolytic debridement of necrotic tissue. China's NMPA innovation priority review channels favor domestically manufactured variants, compressing approval timelines for local producers against imported alternatives.
- Foam Dressings:Hydrophilic polyurethane structures absorb exudate while maintaining peri-wound skin integrity.
- Alginate:Calcium-sodium salt fibers derived from brown seaweed form gel matrices upon contact with wound exudate.
Collagen sits at the top of the volume ranking, with hydrogel climbing the fastest.
End User:
Site-of-care migration is redistributing procurement authority from centralized hospital pharmacies toward distributed channel partners.
- Hospitals:Tertiary care networks in India and Southeast Asia anchor advanced biologic dressing procurement through formulary committees evaluating outcome-based service contracts. Centralized purchasing authority is consolidating previously dispersed departmental decision-making.
- Home Care:Post-acute wound management shifts toward skilled nursing visits with portable biologic delivery systems. Cold chain limitations constrain cellular therapy penetration to metropolitan corridors with reliable logistics infrastructure.
- Long-term Care Facilities:Pressure injury protocols in aged care settings drive standardized dressing selection.
- Outpatient Clinics:Ambulatory wound centers in Australian and Japanese metropolitan markets capture shifting volume from inpatient settings.
Hospitals retain dominant procurement volume, while home care expands most quickly.
Application:
Clinical indication severity determines product selection tier, with complex chronic cases justifying premium biologic intervention.
- Chronic Wounds:Diabetic foot ulcers and venous leg ulcers that stall under standard moist wound healing protocols require extracellular matrix or growth factor intervention. China's tier-one cities are witnessing specialized wound center expansion targeting this indication pool.
- Surgical Wounds:Prophylactic biologic application for high-risk closure sites competes against advanced moist dressings on cost-per-case metrics. Growth factor therapy faces substitution pressure in this segment.
- Burns:Partial-thickness and full-thickness thermal injuries drive demand for cellular therapy and skin substitutes. South Korean burn centers integrate advanced allogeneic tissue supply chains.
- Traumatic Wounds:Acute mechanical injury with tissue loss requires rapid granulation tissue formation.
Chronic wounds command the largest addressable patient pool, with burns gaining share fastest.
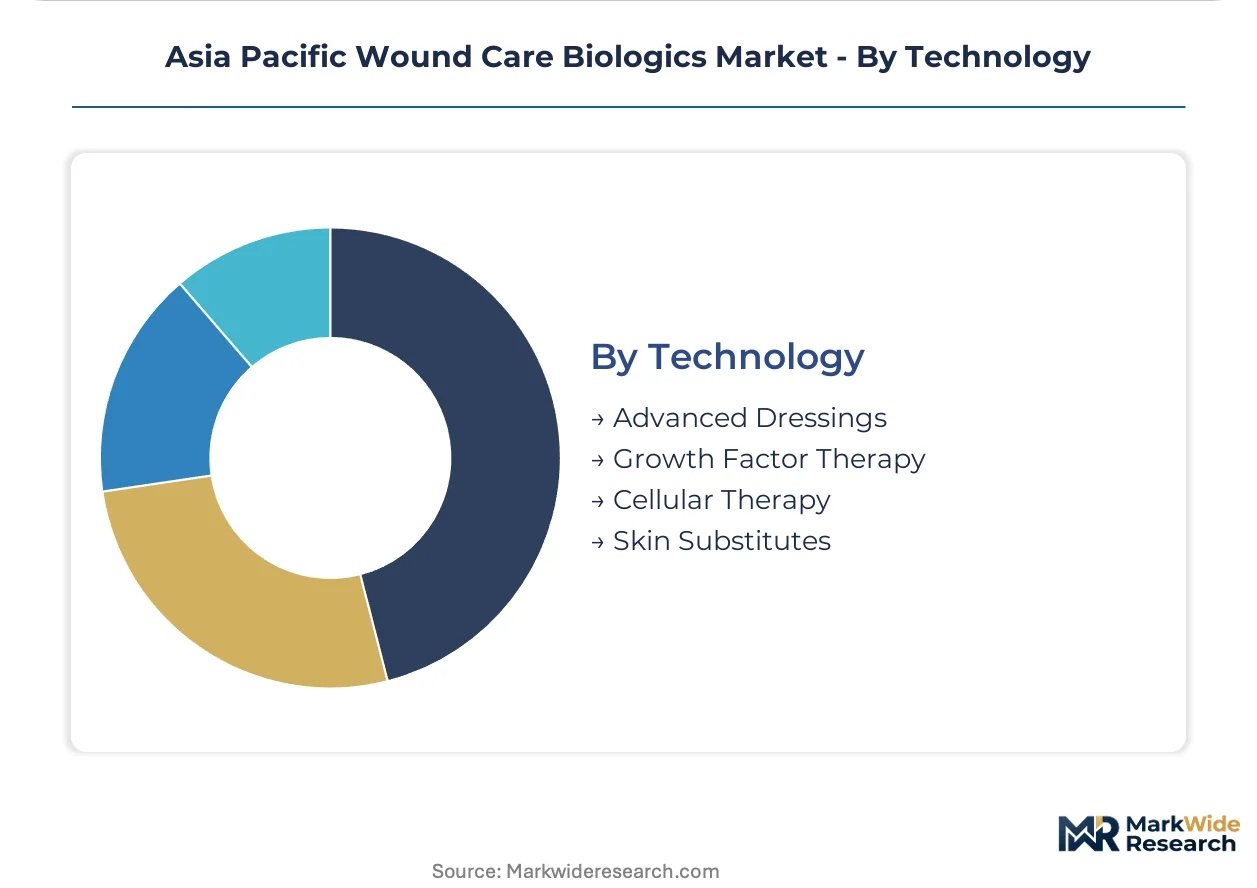
Technology:
Platform maturity separates established dressing categories from emerging cellular interventions requiring specialized manufacturing and distribution.
- Advanced Dressings:Engineered materials including antimicrobial silver, honey-based formulations, and interactive moisture-responsive polymers occupy the standard-of-care tier. These products compete on unit economics against passive alternatives.
- Cellular Therapy:Living allogeneic or autologous cell populations seeded onto scaffold substrates deliver active wound healing intervention. Japan's PMDA accelerated pathways enable faster market entry for developers targeting this premium tier.
- Growth Factor Therapy:Recombinant protein formulations stimulate cellular proliferation and angiogenesis.
- Skin Substitutes:Manufactured or processed tissue products replace full-thickness dermal defects.
Advanced dressings dominate current volume, with cellular therapy showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting manufacturing investment toward jurisdictions with streamlined biologics pathways, as developers weigh Japan's PMDA acceleration against India's CDSCO localization incentives and China's NMPA domestic preference mechanisms.
China
Diabetic foot ulcer incidence in Shanghai and Beijing is driving specialized wound center expansion, with tertiary hospitals consolidating procurement through formulary committees. NMPA innovation priority review channels compress timelines for domestically manufactured hydrogel variants. The Yangtze River Delta anchors production scale-up for alginate and collagen matrix manufacturing serving tier-one city demand.
Japan
PMDA's regenerative medicine framework accelerates approval timelines for cellular therapy products targeting burn and diabetic foot ulcer segments. Tokyo and Osaka metropolitan markets host dedicated wound care specialist teams from multinational vendors. Kanto region hospitals capture mature volume pools for collagen-based matrices amid reimbursement compression pressures.
India
CDSCO biologic licensing requirements for imported wound products add validation costs that favor local contract manufacturing partnerships over direct import models. Tertiary care networks in Maharashtra and Karnataka are expanding advanced biologic dressing procurement through outcome-based service contracts. Mumbai and Bangalore clusters concentrate cold chain infrastructure for cellular therapy distribution.
South Korea
MFDS oversight of regenerative medical products shapes market entry strategies for allogeneic skin substitute developers. Seoul Capital Area burn centers integrate advanced cellular therapy supply chains with premium positioning for amniotic tissue processing capabilities. Busan-Ulsan corridor supports manufacturing scale for extracellular matrix derivatives serving regional export demand.
Australia
TGA biologicals designation creates distinct approval cost structures that filter developer entry decisions compared to Asian regulators. Sydney and Melbourne metropolitan markets shift collagen-based matrix volume pools toward ambulatory outpatient settings. Victoria and New South Wales concentrate specialist wound care nursing workforce training pipelines.
Asia Pacific Wound Care Biologics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational developers anchoring premium cellular therapy tiers while regional fabricators capture standardized dressing categories through cost-optimized production. Market structure exhibits moderate consolidation at the top tier alongside fragmentation among mid-scale domestic suppliers. Three archetypes dominate: integrated wound care platform operators, amniotic tissue processing specialists, and manufactured skin substitute scale players. Competitive dynamics center on regulatory pathway optimization and localized manufacturing partnerships rather than pure price competition.
Within the integrated platform tier, Smith & Nephew Plc and Organogenesis Inc. exemplify divergent geographic anchoring strategies, with the former representing European-headquartered wound care specialization and the latter occupying North American manufactured tissue scale positioning. MiMedx sits within the cellular therapy supply chain specialist archetype, reflecting amniotic tissue processing capabilities that differentiate service to burn center networks. These three entities collectively illustrate how regulatory compliance infrastructure and tissue sourcing relationships determine sustainable regional presence.
| Leading Market Players |
|---|
| Skye Biologics |
| Vericel Corporation |
| Smith & Nephew Plc |
| GC Cell |
| MiMedx |
| Integra LifeSciences Holdings Corporation |
| Kerecis |
| Osiris Therapeutics Inc. |
| Organogenesis Inc. |
| Others |
Pricing and Supply Chain Analysis
Bovine collagen spot prices in Australian agricultural commodity indices cascade through tiered manufacturing cost structures, compressing margins for extracellular matrix producers while amplifying pricing power for vertically integrated processors serving Japanese and South Korean hospital networks.
Pricing Analysis
Distributor margins of 18-25% for cellular therapy products separate premium skin substitute tiers from standard advanced dressings across Asia Pacific procurement channels. Price differentiation hinges on cryopreservation certification grade and PMDA/MFDS regulatory pathway completion, with Japanese tertiary centers least sensitive to unit cost and Indian multi-specialty hospitals most responsive to volume discounts. Pricing pressure stems from CDSCO localization mandates favoring domestic hydrogel manufacturers, eroding import premium capture.
Supply Chain Analysis
Dual-sourcing requirements from Australian TGA biologicals designation compel amniotic tissue processors to qualify secondary suppliers across South Korea and Japan, fragmenting procurement leverage. Raw material dependencies center on bovine dermal harvests from New South Wales, porcine intestinal submucosa from Victorian abattoirs, and seaweed alginate from Busan coastal processing zones. Tariff exposure on cross-border tissue shipments between ASEAN members concentrates supply chain risk. Distribution runs through hospital GPO contracts and specialized wound center direct agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's PMDA accelerated approval pathways create a 12-18 month regulatory cost advantage versus India's CDSCO import testing layers, positioning cellular therapy developers for geographic arbitrage by anchoring manufacturing in Kanto region facilities.
For Market Incumbents: Deploy outcome-based contracting capabilities to lock in formulary committee relationships at Shanghai and Beijing tertiary wound centers. Incorporate remote monitoring sensors into service bundles to defend against advanced moist dressing substitution. Add cryopreservation capacity in Maharashtra to circumvent CDSCO localization pressure on imported living tissue products. For New Entrants and Emerging Players: Enter via domestic hydrogel manufacturing partnerships with Yangtze River Delta chemical processors, leveraging NMPA innovation priority review channels against slower-import competitors. Target tier-two Chinese cities where diabetic foot ulcer incidence outpaces specialized wound center supply. Lead with cost-per-closure analytics to displace growth factor therapy in surgical wound prophylaxis protocols. For Investors and Strategic Acquirers: Asymmetric upside sits with amniotic tissue processing specialists holding MFDS-approved South Korean manufacturing infrastructure and established burn center relationships. Five-to-ten year viability favors platforms with backward integration into tissue sourcing rather than contract-dependent supply models. Monitor PMDA breakthrough therapy designation announcements as inflection signals for premium segment allocation shifts.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Breakthrough Therapy Designation | Accelerates cellular therapy market entry by 12-18 months in Japanese burn and diabetic foot ulcer segments. |
| Domestic Hydrogel Manufacturing Scale-Up | NMPA priority review channels compress approval timelines for Yangtze River Delta producers against import competitors. |
| Outcome-Based Service Contracting | Hospital formulary committees in tier-one Chinese cities now evaluate cost-per-closure metrics over unit pricing. |
| Cold Chain Infrastructure Expansion | Mumbai and Bangalore clusters enable cellular therapy penetration beyond metropolitan corridors into Indian tier-two cities. |
| Amniotic Tissue Sourcing Integration | Busan-Ulsan corridor manufacturing secures premium positioning in South Korean burn center supply chains. |
Research Methodology
Multiple input streams — primary interviews with wound care specialists and hospital procurement managers, regulatory pathway documentation from PMDA and NMPA filings, and customs trade data for collagen matrix imports — were reconciled through bottom-up demand modeling and top-down market sizing validation. Secondary sources encompassed tertiary hospital formulary databases, GPO contract repositories, and MFDS regenerative medical product registries. Cross-referencing clinician utilization patterns against manufacturer shipment records identified channel inventory dynamics.
Historical volume trajectories were cross-referenced against expert panel assessments of reimbursement evolution and wound center expansion timelines across the analysis window. Segmentation modeling incorporated product type transitions, end-user site-of-care migration, application severity tiers, and technology platform maturity curves. CAGRs were derived from spline interpolation between anchor-year observations and terminal-year demand projections, calibrated against diabetes prevalence forecasts and surgical procedure volume trends.
Inputs from PMDA approval databases and Australian TGA biologicals registers were available through the study window; gaps in real-time hospital procurement transaction data introduce uncertainty bands around quarterly volume estimates. Forecasts reflect assumptions regarding reimbursement harmonization progress across ASEAN national health insurance schemes and cold chain infrastructure buildout in Indian tier-two cities. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Wound Debridement Products Market
Wound Care
Bioactive Wound Care Market
Wound Care
Advanced Wound Care Market
Wound Care
Infectious Wound Care Management Market
Wound Care
North America Wound Care Management Market
Wound Care
Italy Wound Care Market
Wound Care
Wound Healing Market
Wound Care
South Korea Wound Care Management Market
Wound Care
Global Active Wound Care Market
Wound Care
Gauze Bandage Rolls Market
Wound Care
Europe Advanced Wound Care Market
Wound Care
Global Traditional Wound Management Market
Wound Care
Pressure Bandages Market
Wound Care
Advanced Wound Care Management Market
Wound Care
Global Compression Bandages Market
Wound Care
Chronic Wound Care Market