
 Bladder Cancer Diagnostics Market | 2026-2036
Bladder Cancer Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Bladder Cancer Diagnostics Market Analysis
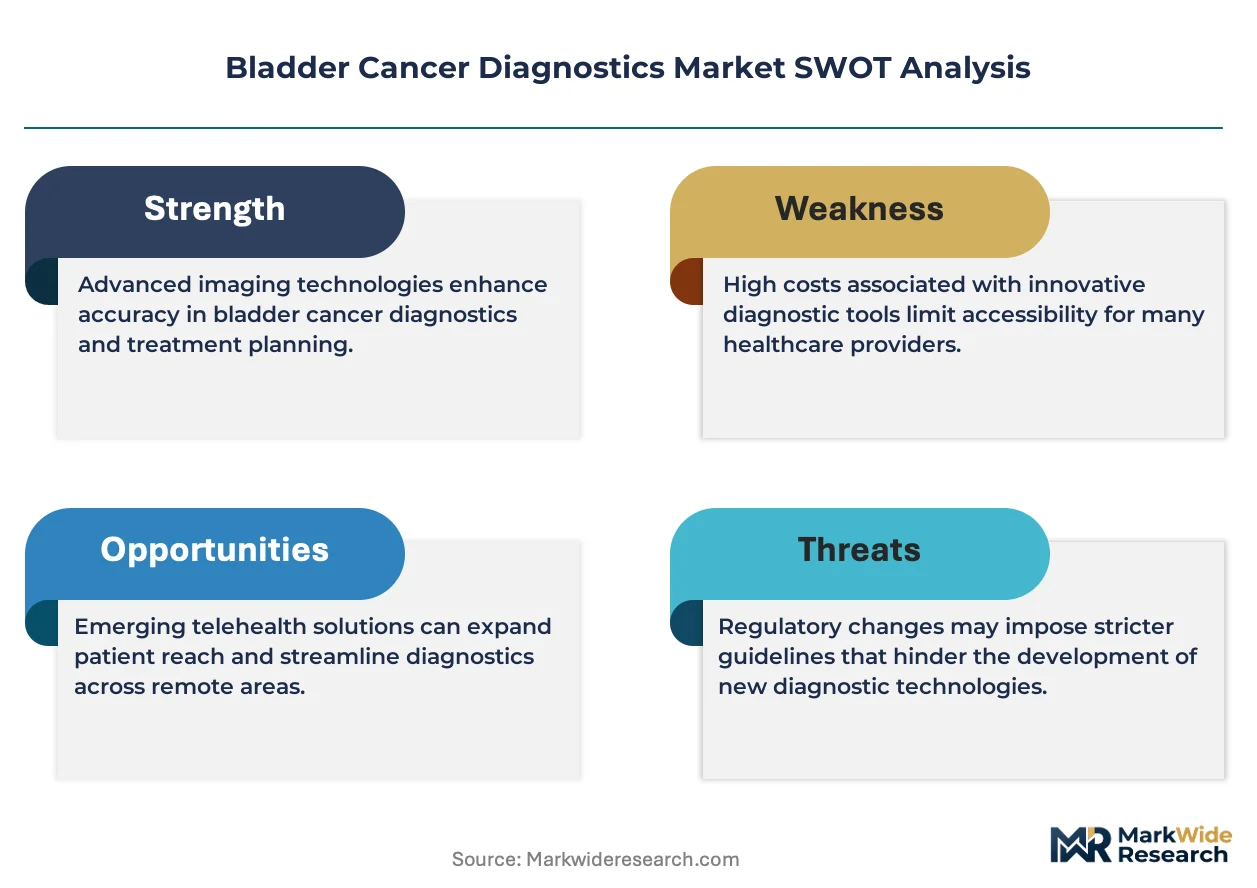
The EU In Vitro Diagnostic Regulation is rebalancing compliance costs toward larger manufacturers with dedicated regulatory affairs teams. Roche Diagnostics leverages its established CE-marked portfolio to sustain market presence across European urology networks. Photocure ASA anchors its position through proprietary photodynamic diagnostic technology. Abbott Laboratories competes by extending its installed base of automated analyzers into oncology workflows.
Bladder cancer diagnostics encompasses cystoscopic visualization, urinary biomarker detection, imaging modalities, and molecular assays used to identify, stage, and monitor urothelial malignancies. Cystoscopy remains the structural backbone of hematuria workups due to its direct tissue visualization capability, though urinary biomarker panels are gaining traction as first-line triage tools to reduce unnecessary invasive procedures. Next-generation sequencing applications in prognosis are expanding fastest among technology segments as clinicians seek genomic stratification for BCG response prediction. Diagnostic laboratories capture the deepest margin pools through high-throughput processing of multiplexed urinary assays.
The FDA and EMA jointly shape product development pathways through parallel scientific advice programs for novel diagnostic biomarkers, while the EU MDR extends clinical evidence requirements for legacy IVD devices. Japan's PMDA accelerates review timelines for oncology diagnostics through its Sakigake designation system. Stakeholders must monitor evolving reimbursement thresholds for liquid biopsy tests across national health technology assessment bodies.
Market Dynamics
The bladder cancer diagnostics sector is absorbing pressure from the FDA's accelerated approval pathway for companion diagnostics, which compresses development timelines while demanding simultaneous clinical evidence generation for immunotherapy stratification tools.
Growth Catalysts
- IVDR Compliance Consolidation:The EU In Vitro Diagnostic Regulation is filtering out smaller manufacturers, creating shelf space for scaled players with dedicated regulatory infrastructure across German and French laboratory networks.
- Liquid Biopsy Validation:Urinary cfDNA and CTC detection platforms are gaining traction as first-line triage instruments, reducing cystoscopy dependency in hematuria workups.
- Precision Oncology Reimbursement:Japan's PMDA Sakigake designation is compressing review timelines for genomic assays, accelerating commercialization of BCG response predictors.
Market Restraints
- Clinical Validation Burden:The EU MDR's extended clinical evidence requirements for legacy IVD devices impose retrospective study costs that disproportionately burden mid-tier manufacturers.
- Biomarker Specificity Limitations:Current urinary NMP22 and BTA tests exhibit false-positive rates in benign urologic conditions, constraining adoption for population screening.
- Pathologist Workflow Friction:Molecular assay interpretation demands specialized genomic training that outpaces current fellowship curricula in community hospital settings.
Strategic Opportunities
- Home-Based Sample Collection:At-home urine stabilization kits paired with telemedicine platforms could unlock rural and elderly patient segments currently underserved by cystoscopy access.
- AI-Augmented Cystoscopy:Computer vision integration with white-light and narrow-band imaging systems offers real-time lesion characterization, reducing inter-operator variability.
- Pharma-Diagnostic Codevelopment:Parallel scientific advice programs between FDA and EMA create streamlined pathways for immunotherapy companion diagnostics.
Industry Challenges
- Multi-Omics Integration Complexity:Combining genomic, transcriptomic, and proteomic data streams requires bioinformatics infrastructure that exceeds capabilities of most community pathology laboratories.
- Reimbursement Code Fragmentation:Liquid biopsy tests face heterogeneous coverage determinations across Medicare Administrative Contractors, creating patchwork access patterns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bladder Cancer Diagnostics Market |
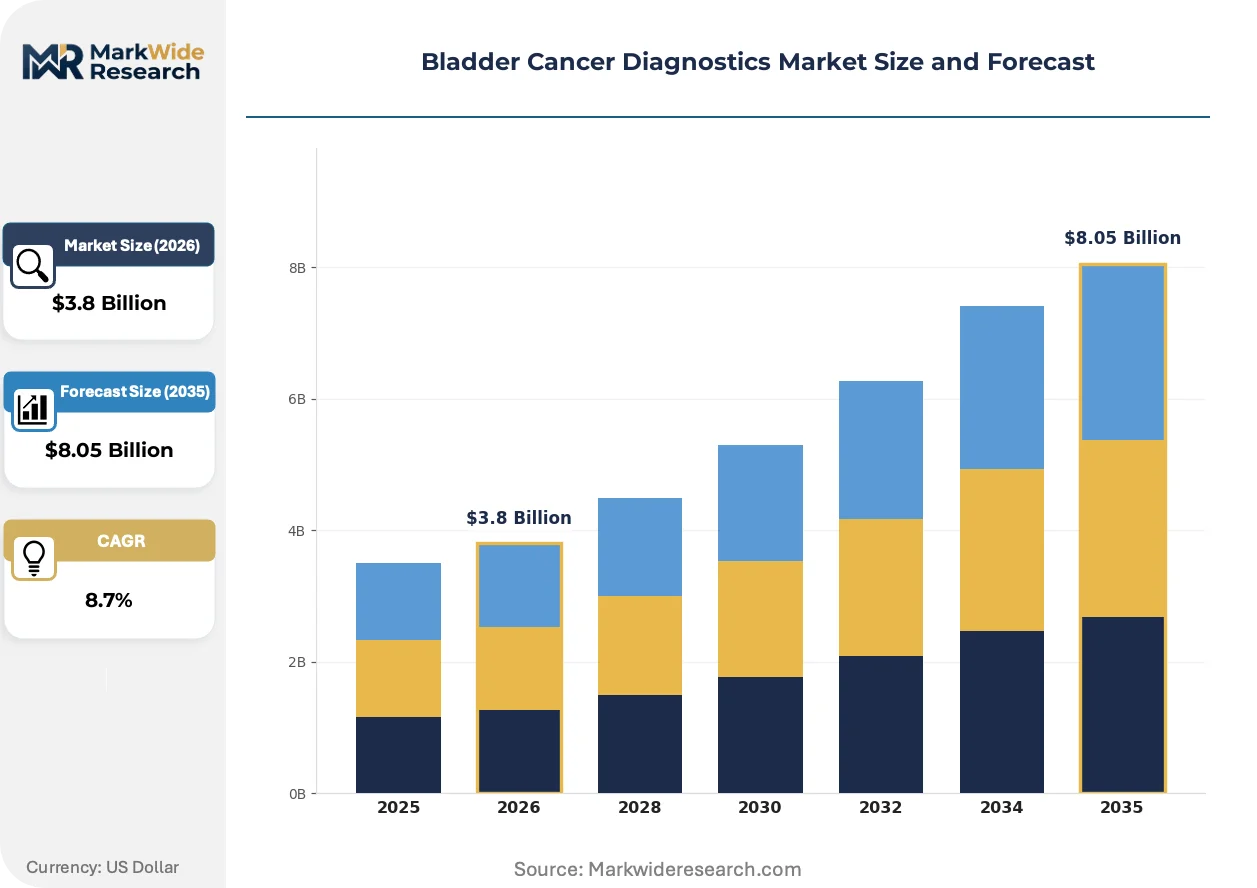
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cystoscopy, Urinary Biomarkers, Imaging Techniques, Urinalysis Technology: Fluorescence In Situ Hybridization, Next-Generation Sequencing, PCR, Cytology End User: Hospitals, Diagnostic Laboratories, Research Centers, Clinics Application: Screening, Diagnosis, Prognosis, Monitoring |
| Companies Covered | Beckman Coulter, Olympus Corporation, Roche Diagnostics, Cellens, Karl Storz, Abbott Laboratories, Photocure ASA, Freenome, Sysmex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bladder Cancer Diagnostics Market Emerging Trajectories
Diagnostic modality convergence is compressing the traditional cystoscopy-first workflow, with molecular stratification tools embedding earlier in the clinical decision tree.
Next-generation sequencing panels for FGFR3, PIK3CA, and ERBB2 mutations are absorbing market share from single-analyte immunohistochemistry in tertiary care centers. Urology practices in the United States and Germany are adopting these platforms for BCG-unresponsive patient identification. The technology is absorbing revenue from repeat cystoscopy schedules by enabling risk-adapted surveillance intervals.
The EU MDR's clinical evidence requirements are forcing retrospective performance studies for legacy urinary biomarker devices. Manufacturers with pre-2022 CE markings must compile real-world outcome data or withdraw from European markets. High-volume German and French laboratories are consolidating supplier relationships toward vendors with completed MDR technical documentation.
Academic medical centers are unbundling diagnostic service contracts, procuring cystoscopy, pathology, and molecular testing from separate specialty providers. This fragmentation pressures integrated health systems to defend volume through captive laboratory buildouts. The pattern is most pronounced in United States metropolitan markets with concentrated urology group practices.
Bladder Cancer Diagnostics Market Segmentation
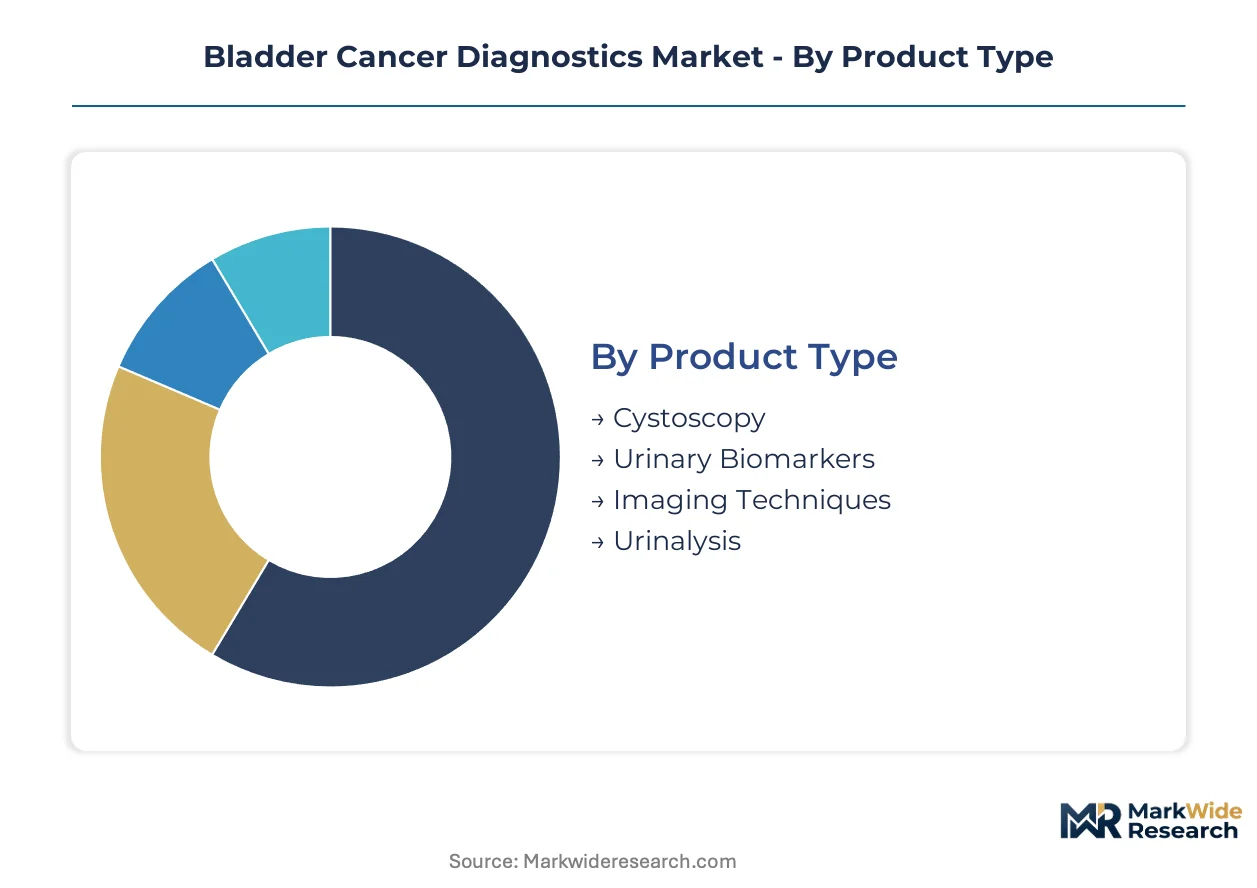
Bladder cancer diagnostics segments along four intersecting dimensions that determine procurement patterns and margin capture. Product type and technology choices drive capital allocation, while end-user concentration and application workflows shape commercial access strategies.
Product Type:
Supply concentration clusters around manufacturers with integrated visualization and molecular platforms.
- Cystoscopy:White-light and narrow-band imaging systems deliver direct urothelial visualization with optical biopsy capability. Demand concentrates in tertiary hospital networks across the United States, Germany, and Japan where surgical volume justifies capital equipment investment and maintenance contracts.
- Urinary Biomarkers:NMP22, BTA, and emerging multi-analyte panels detect shed tumor antigens in voided specimens. German and French diagnostic laboratories are expanding high-throughput processing capacity for these assays as the EU IVDR filters out smaller kit suppliers.
- Imaging Techniques:CT urography and MRI provide cross-sectional staging assessment for muscle-invasive disease detection.
- Urinalysis:Automated sediment analysis and dipstick microscopy serve initial hematuria triage in high-volume primary care settings.
Today's leader: Cystoscopy. Tomorrow's challenger: Urinary Biomarkers.
Technology:
Cost tier separation distinguishes premium molecular platforms from commoditized cytology workflows.
- Next-Generation Sequencing:Comprehensive genomic profiling for FGFR3, PIK3CA, and ERBB2 mutations enables BCG response prediction and immunotherapy stratification. Academic medical centers in the United States absorb the highest per-test reimbursement for these panels.
- Fluorescence In Situ Hybridization:Chromosomal enumeration probes for chromosomes 3, 7, 17, and 9p21 detect urothelial carcinoma in equivocal cytology cases. Community hospital laboratories favor FISH for its moderate complexity classification and established Medicare coverage.
- PCR:Targeted amplification methods support point mutation detection with faster turnaround than sequencing workflows.
- Cytology:Conventional Papanicolaou-stained urine cytology remains the lowest-cost screening modality despite sensitivity limitations for low-grade lesions.
NGS platforms command premium pricing. FISH maintains volume leadership in community settings.
End User:
Customer type determines contract structure, with integrated health systems negotiating enterprise pricing distinct from independent laboratory procurement.
- Diagnostic Laboratories:Centralized processing hubs achieve scale economies through automated sample handling and multiplexed assay menus. Large reference laboratories in the United States and Germany are consolidating molecular testing for urology group practices.
- Hospitals:In-house pathology departments retain cystoscopy and surgical pathology services while outsourcing complex molecular profiling.
- Research Centers:Academic institutions drive biomarker discovery and companion diagnostic codevelopment with pharmaceutical sponsors.
- Clinics:Urology ambulatory surgery centers perform office-based cystoscopy with point-of-care urine testing for immediate triage decisions.
Laboratories capture the deepest margin pools. Hospital consolidation is compressing vendor counts.
Application:
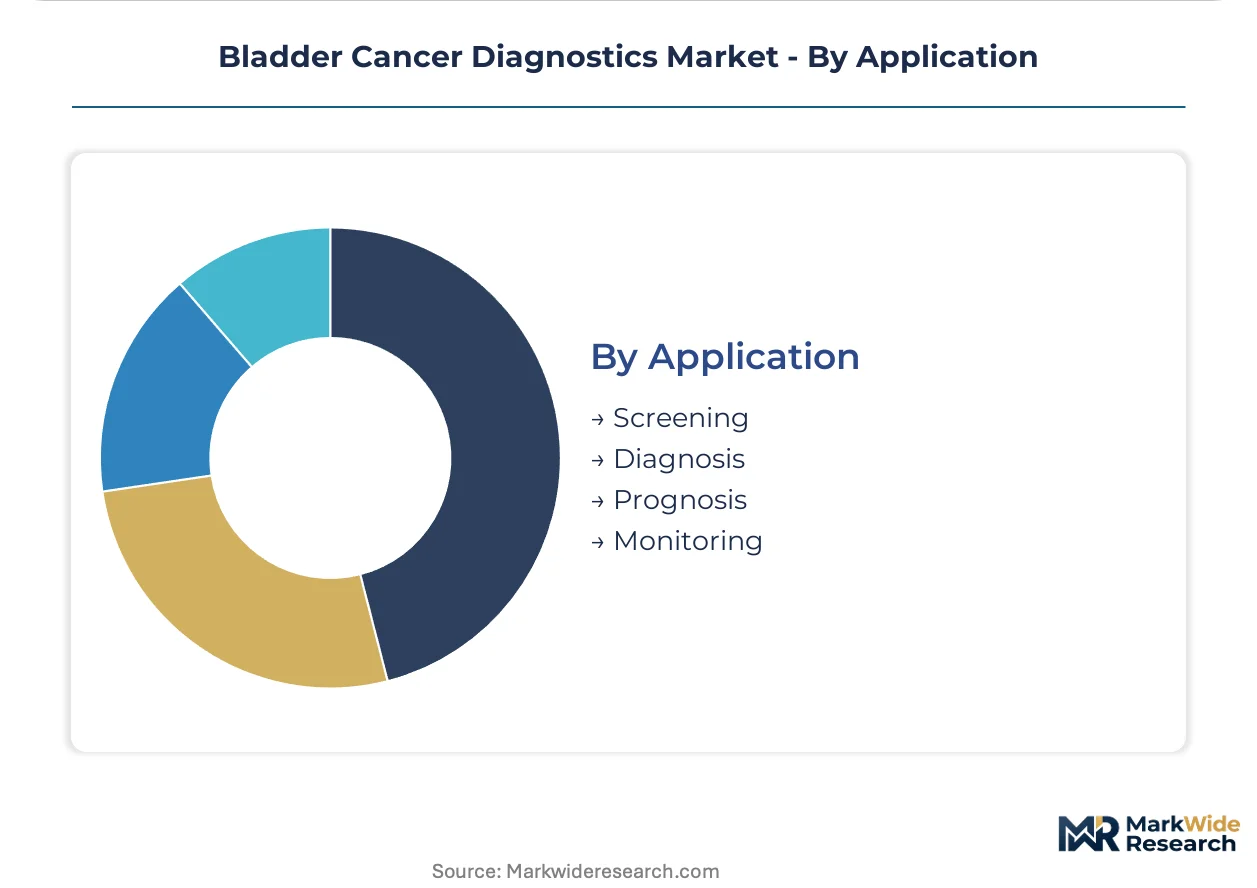
Volume distribution follows the cancer care continuum, with surveillance monitoring representing the highest test frequency segment.
- Monitoring:Post-treatment surveillance protocols mandate periodic cystoscopy and urine testing for recurrence detection. The United States and Japan maintain the most intensive surveillance intervals, driving recurring revenue for device and assay suppliers.
- Diagnosis:Initial hematuria workup combines cystoscopy with upper tract imaging and urine cytology. German urology networks are adopting urinary biomarker triage to reduce unnecessary cystoscopy referrals.
- Screening:Population-level detection remains limited by biomarker specificity constraints in benign urologic conditions.
- Prognosis:Genomic risk stratification guides BCG therapy selection and intensity in high-risk non-muscle invasive disease.
Monitoring sustains recurring revenue. Diagnosis offers the steepest expansion trajectory for molecular platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized uropathologists and molecular diagnosticians concentrate in metropolitan hospital clusters across the United States, Germany, and Japan. These talent pools anchor the highest diagnostic test volumes for bladder cancer surveillance and precision oncology selection.
United States
Academic medical centers in Boston, New York, and Houston drive adoption of next-generation sequencing panels for BCG response prediction. The FDA's accelerated approval pathway for companion diagnostics compresses development timelines for immunotherapy stratification tools. Mayo Clinic and MD Anderson anchor multi-site laboratory networks processing multiplexed urinary assays for urology group practices.
Germany
Diagnostic laboratories in Berlin and Munich expand high-throughput processing capacity for urinary biomarker panels as the EU IVDR filters out smaller kit suppliers. The country's national pharmaceutical regulator enforces extended clinical evidence requirements for legacy IVD devices under EU MDR. The Rhine-Ruhr metropolitan region concentrates reference laboratory capacity serving urology networks across Western Europe.
Japan
Aging demographics in Tokyo and Osaka sustain intensive cystoscopy surveillance protocols with recurring revenue for device suppliers. PMDA's Sakigake designation system compresses review timelines for genomic assays enabling BCG response predictors. The Kanto region anchors commercialization partnerships between diagnostic manufacturers and pharmaceutical sponsors developing immunotherapy companion diagnostics.
United Kingdom
NHS England's specialized commissioning frameworks concentrate molecular testing capacity in London and Manchester academic centers. The country's national pharmaceutical regulator aligns with EMA parallel scientific advice programs for novel diagnostic biomarkers. The Oxford-Cambridge corridor anchors biomarker discovery collaborations between research institutions and IVD manufacturers.
France
Hospital networks in Paris and Lyon consolidate supplier relationships toward vendors with completed MDR technical documentation for urinary cytology platforms. ANSM enforces post-market surveillance requirements for legacy CE-marked devices. The Île-de-France region anchors photodynamic diagnostic technology adoption for fluorescence-guided cystoscopy procedures.
Bladder Cancer Diagnostics Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the bladder cancer diagnostics sector. The vendor base stratifies into three tiers: multinational conglomerates with integrated visualization and molecular platforms, mid-scale IVD manufacturers with dedicated oncology menus, and emerging liquid biopsy specialists with single-assay focus. Dominant competitive moves include portfolio diversification into companion diagnostics and geographic expansion through laboratory service contracts.
Among diversified diagnostic conglomerates, Roche Diagnostics and Abbott Laboratories occupy positions spanning cystoscopy, urinary biomarkers, and molecular testing workflows. Beckman Coulter exemplifies the mid-scale IVD archetype with automated analyzer penetration into hospital laboratory networks. Photocure ASA anchors the specialized photodynamic diagnostics tier with proprietary technology for fluorescence-guided lesion detection.
| Leading Market Players |
|---|
| Beckman Coulter |
| Olympus Corporation |
| Roche Diagnostics |
| Cellens |
| Karl Storz |
| Abbott Laboratories |
| Photocure ASA |
| Freenome |
| Sysmex Corporation |
| Others |
Supply Flow & Price Mechanics
Specialized molecular pathologists in Boston, New York, and Houston anchor the highest-value diagnostic workflows, with labor-cost differentials between academic medical centers and community hospitals driving three-tier spreads across NGS panel pricing.
Pricing Analysis
Bundled service contracts encompassing cystoscopy, pathology, and molecular testing command premium positioning against unbundled procurement patterns spreading through United States metropolitan markets. Three-tier pricing structure across premium, standard, and economy levels separates comprehensive genomic profiling from FISH-based triage and conventional cytology workflows. Pricing pressure stems from Medicare Administrative Contractor heterogeneity in liquid biopsy coverage determinations. Community hospital laboratories exhibit highest price sensitivity due to capital constraints on bioinformatics infrastructure.
Supply Chain Analysis
Dual-sourcing requirements from United States diagnostic laboratories mandate multi-supplier qualification for critical reagents and optical components. Manufacturing concentration clusters in Germany, Japan, and the United States for endoscopic visualization systems and automated analyzers. Supply chains draw from specialized optical glass, monoclonal antibody reagents, and semiconductor-based imaging sensors. Single-source vulnerability concentrates in photodynamic diagnostic dye production. Distribution runs through GPO-negotiated contracts with integrated health systems and direct laboratory service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bladder cancer diagnostics market functions as a regulatory compounder, with the FDA's accelerated approval pathway for companion diagnostics generating recurring demand inflections for immunotherapy stratification tools.
For Market Incumbents: Cement market position through captive laboratory buildouts in United States metropolitan corridors where urology group practice consolidation is accelerating. Defend against liquid biopsy specialists by securing exclusive service contracts with integrated health systems. Prioritize MDR technical documentation completion to capture shelf space vacated by smaller European kit suppliers.
For New Entrants and Emerging Players: Japan's PMDA Sakigake designation in oncology diagnostics opens a window for genomic assay commercialization with compressed review timelines. Target home-based urine collection kits paired with telemedicine platforms in rural United States segments currently underserved by cystoscopy access. Pursue pharma-diagnostic codevelopment partnerships as the primary go-to-market channel.
For Investors and Strategic Acquirers: Pharmaceutical sponsors developing immunotherapy agents are the most active acquirer in this space, seeking companion diagnostic capabilities for trial stratification. The five-to-ten year viability window favors platforms with FDA-cleared or CE-marked status in liquid biopsy or AI-augmented cystoscopy. Acquisition target archetype: emerging liquid biopsy specialists with single-assay focus and completed analytical validation. Watch for reimbursement code consolidation signals as inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU IVDR compliance secures access to German and French laboratory networks. |
| Hospital System Partnership | Exclusive service contracts with Mayo Clinic and MD Anderson anchor volume. |
| Reimbursement Strategy | Medicare coverage determination unlocks United States community hospital adoption. |
| Software Companion Development | AI-augmented cystoscopy integration reduces inter-operator variability in lesion detection. |
| Pharma-Diagnostic Codevelopment | FDA-EMA parallel scientific advice streamlines immunotherapy stratification tool pathways. |
Methodological Framework
Multiple input streams — primary interviews with urology practice administrators, molecular pathologists, and GPO contracts managers; secondary validation through FDA 510(k) filings, CMS Medicare coverage determinations, and EU MDR technical documentation databases; and hospital procurement database analysis — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across the projection horizon modeled segmentation dimensions including technology tier, end-user concentration, application workflow, and regional regulatory cluster. CAGRs were derived from installed base expansion rates and assay menu adoption curves. Forecast inputs incorporated immunotherapy pipeline progression and liquid biopsy analytical validation milestones.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA companion diagnostic approval delays or EU MDR enforcement acceleration. Deviation in Medicare Administrative Contractor liquid biopsy coverage determinations would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology Diagnostics
Asia-Pacific Lung Cancer Diagnostics Market
Oncology Diagnostics
Europe Non-Small Cell Lung Cancer Diagnostics Market
Oncology Diagnostics
US Colorectal Cancer Screening Market
Oncology Diagnostics
Asia Pacific Multi-Cancer Early Detection Market
Oncology Diagnostics
Asia-Pacific Lung Cancer Screening Software Market
Oncology Diagnostics
Glioma Diagnosis and Treatment Market
Oncology Diagnostics
AI in Cancer Diagnostics Market
Oncology Diagnostics
Cancer Diagnostics Market
Oncology Diagnostics
Cancer Biopsy Market
Oncology Diagnostics
Early-Stage Lung Cancer Diagnostics Market
Oncology Diagnostics
Europe Liver Cancer Diagnostics Market
Oncology Diagnostics
Pancreatic Cancer Diagnostics Market
Oncology Diagnostics
Europe Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
South America Ovarian Cancer Diagnostics and Therapeutics Market
Oncology Diagnostics
Non-Hodgkin Lymphoma Diagnostics Market
Oncology Diagnostics
Global Clinical Oncology NGS Market