
 Electronics Ceramics and Electrical Ceramics Market | 2026-2036
Electronics Ceramics and Electrical Ceramics Market Size, Share, and Industry Trends Forecast 2026-2036
Electronics Ceramics and Electrical Ceramics Market Intelligence
The European Union's RoHS directive, alongside similar substance restrictions in China, is decoupling material selection from traditional cost metrics for many electronic components. Kyocera Corporation specializes in high-performance ceramic packages and substrates for advanced electronics. Murata Manufacturing Co., Ltd. sustains its leadership in the multilayer ceramic capacitor segment through massive production scale and continuous R&D investment. TDK Corporation competes with a diverse portfolio focused on magnetic and piezoelectric ceramic components.
Electronics and electrical ceramics are advanced inorganic, non-metallic materials engineered for specific electrical properties such as insulation, semiconduction, or piezoelectricity. Compositions like alumina, zirconia, and barium titanate are processed to achieve precise functional characteristics. Their primary purpose is to serve as critical passive components, including capacitors, insulators, substrates, and sensors within electronic circuits and systems. Dielectric ceramics for multilayer ceramic capacitors constitute the market's largest segment by volume, while demand for piezoelectric ceramics is accelerating due to new sensor applications in automotive electronics.
Compliance with the EU's REACH regulation and US EPA guidelines on hazardous materials governs chemical composition and end-of-life management. Concurrently, ISO 9001 certification is a baseline requirement for suppliers targeting automotive and aerospace customers. These frameworks mandate stringent quality control and supply chain transparency. Future competitiveness for material suppliers depends on developing lead-free and high-performance materials that meet both evolving device requirements and divergent international environmental standards.
Market Dynamics
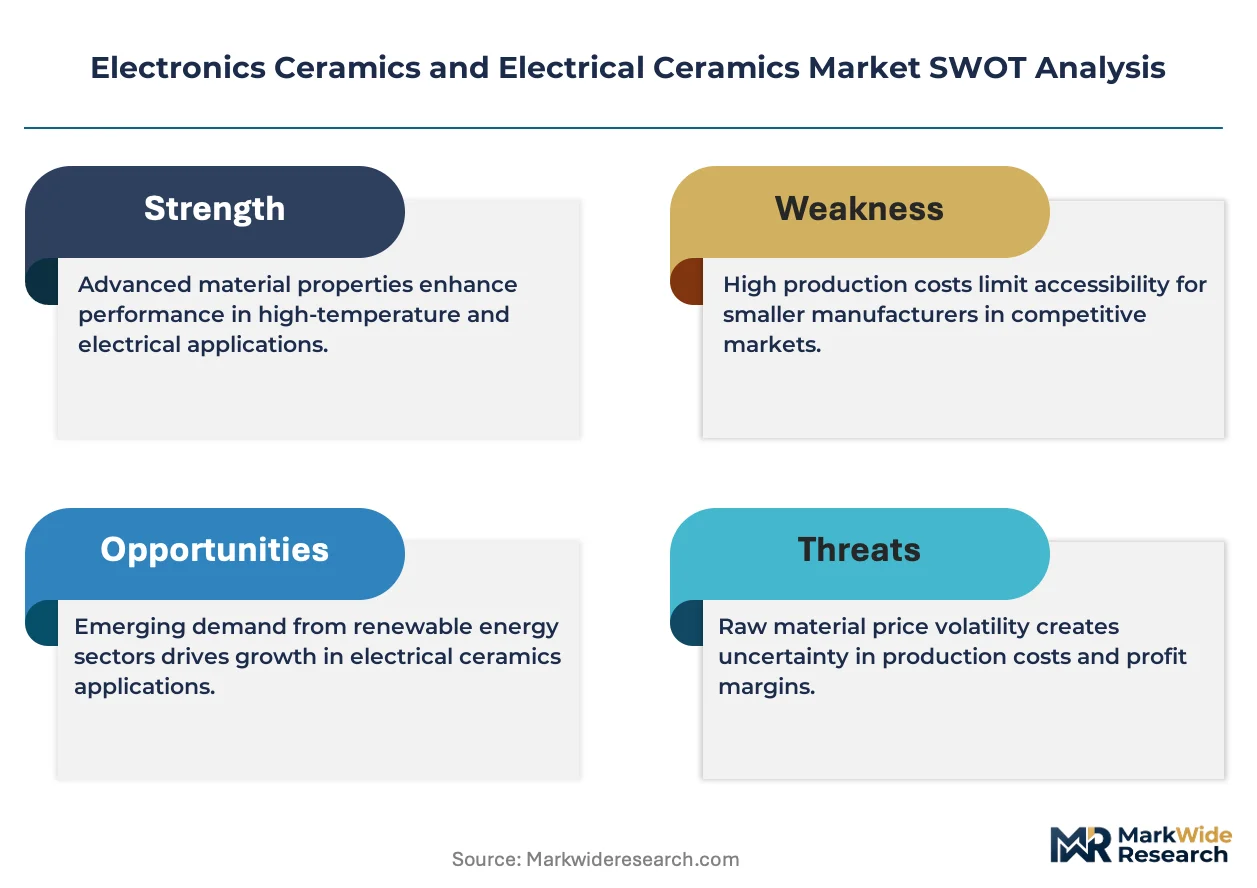
The market's central dynamic is the tension between escalating performance requirements for high-frequency electronics and tightening substance-of-concern regulations. This conflict forces material innovation away from legacy lead-based formulations toward more complex, higher-cost lead-free piezoelectric and dielectric compounds to serve automotive and telecommunications sectors.
Growth Catalysts
- 5G Infrastructure Expansion:The deployment of 5G base stations and devices requires high-frequency dielectric ceramics for filters and substrates, driving volume demand for materials with low signal loss characteristics.
- Automotive Electrification:The shift to electric vehicles and advanced driver-assistance systems boosts demand for multilayer ceramic capacitors, piezoelectric sensors, and high-voltage insulators for power management.
- Data Center Growth:Hyperscale data centers require vast quantities of ceramic components, including substrates for high-density interconnects and capacitors for power management in servers and networking equipment.
Market Restraints
- Raw Material Volatility:Price fluctuations for key inputs like high-purity alumina and barium titanate create cost pressure and margin instability for ceramic component manufacturers.
- Technical Miniaturization Limits:Pushing component dimensions smaller introduces challenges like dielectric breakdown and thermal management, increasing process complexity and impacting manufacturing yields.
- Processing Concentration:Heavy reliance on specialized firing facilities in China and South Korea creates supply chain vulnerabilities and geopolitical risk for global electronics production.
Strategic Opportunities
- Biocompatible Medical Ceramics:Developing zirconia and alumina ceramics for implantable medical devices like pacemakers opens a high-margin application with stringent qualification requirements.
- Substrates for Wide-Bandgap Devices:The adoption of SiC and GaN power electronics creates demand for specialized ceramic substrates with high thermal conductivity.
- Regional Supply Chain Initiatives:Policies like the EU Chips Act create opportunities for new ceramic substrate facilities in Europe to support local semiconductor manufacturing.
Industry Challenges
- Divergent Environmental Regulations:Manufacturers must manage complex formulations to comply simultaneously with the EU's REACH and RoHS directives, US EPA rules, and China's GB standards.
- High Capital Intensity:Building and qualifying state-of-the-art ceramic processing facilities, including high-temperature kilns and cleanrooms, requires substantial, long-term capital investment with delayed returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronics Ceramics and Electrical Ceramics Market |
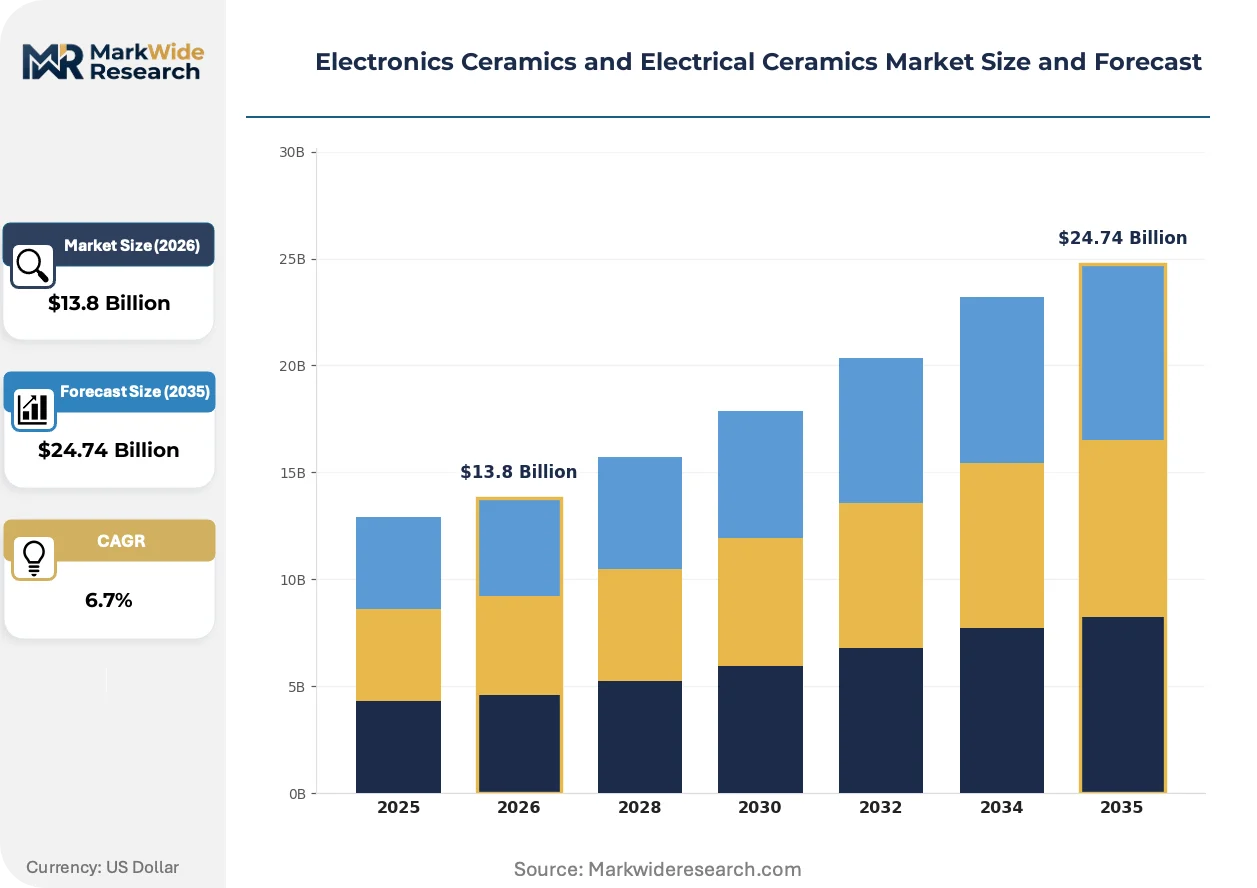
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.74 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dielectric Ceramics, Piezoelectric Ceramics, Magnetic Ceramics, Electroceramics Technology: Multilayer Ceramic Capacitors, Thick Film Technology, Thin Film Technology, Sintering, Tape Casting Application: Consumer Electronics, Telecommunications Equipment, Industrial Automation, Automotive Electronics, Aerospace Systems End User: Electronics Manufacturers, OEM Suppliers, Research Laboratories, Defense Contractors |
| Companies Covered | Murata Manufacturing Co., Ltd., Kyocera Corporation, CeramTec GmbH, Morgan Advanced Materials, CoorsTek Inc., TDK Corporation, NGK Insulators, Ltd., Maruwa Co., Ltd., APC International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronics Ceramics and Electrical Ceramics Market Strategic Shifts & Innovations
Material science advancements are converging with the dual pressures of device miniaturization and global environmental compliance. This intersection drives innovation toward lead-free compositions and novel structures that support higher performance in smaller, more energy-efficient electronic systems.
Lead-free piezoelectric ceramics, such as bismuth sodium titanate, provide an alternative to lead zirconate titanate. These materials are being adopted by automotive and consumer electronics manufacturers to meet environmental regulations. This shift to lead-free formulations is overtaking traditional PZT in new designs for sensors and actuators, despite performance trade-offs.
The European Union's RoHS directive continues to restrict hazardous substances like lead and cadmium in electronic equipment. This regulation forces a continuous redesign of ceramic material formulations, affecting everything from capacitors to substrates. The dielectric ceramics segment is most impacted, investing heavily in R&D to find compliant materials without sacrificing electrical performance.
A shift toward early-stage design collaboration is replacing transactional component procurement. End-users in automotive and aerospace now demand deep material data and supply chain transparency to meet stringent quality standards like ISO 9001. This collaborative model is most visible in North America and Europe, where system reliability and traceability are paramount.
Electronics Ceramics and Electrical Ceramics Market Segmentation
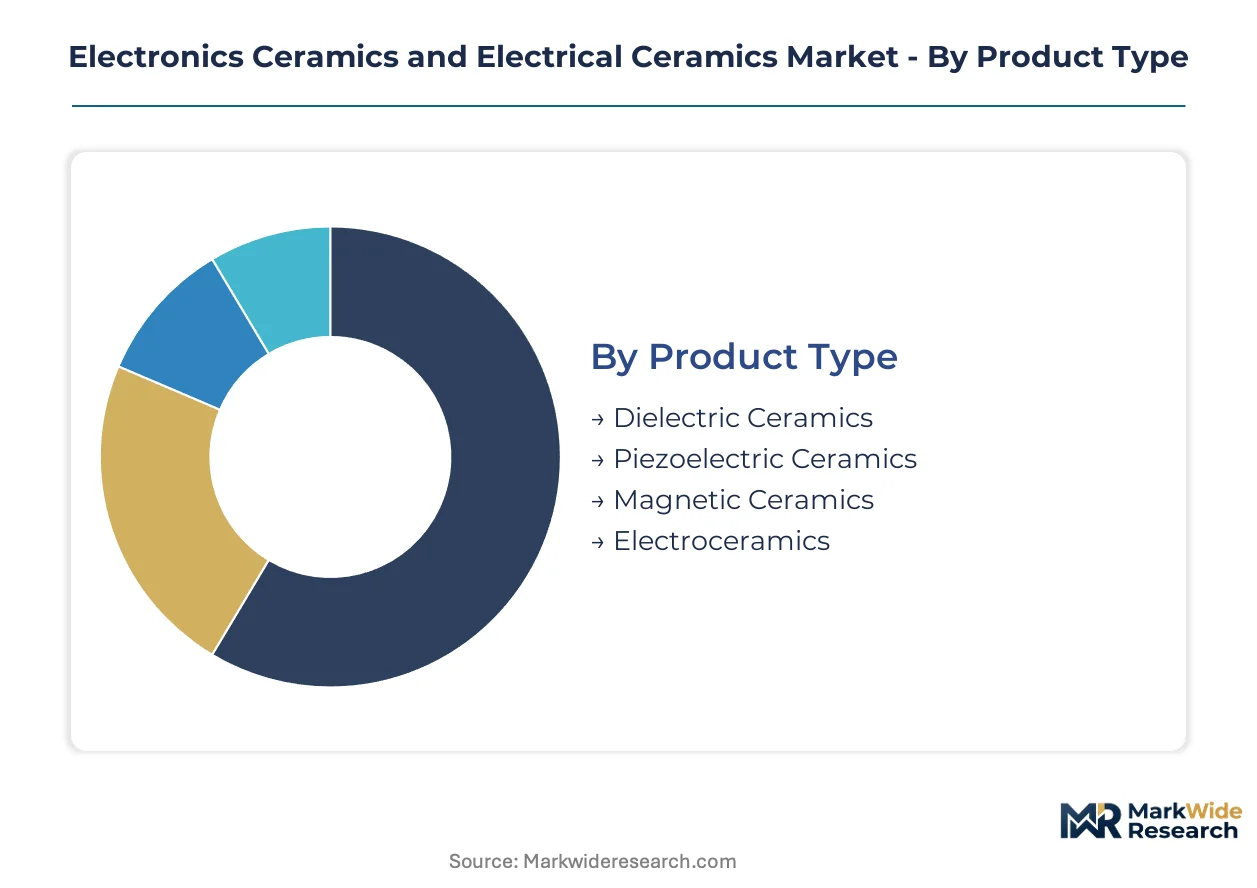
The electronics ceramics and electrical ceramics market exhibits diverse segmentation, reflecting the broad array of material compositions, processing techniques, and end-use environments. Understanding these distinct segments provides clarity on demand drivers, technological imperatives, and competitive dynamics across the value chain.
Product Type:
The integration depth of ceramic materials varies significantly across product types, reflecting their functional roles from fundamental components to advanced sensor elements.
- Dielectric Ceramics:These materials possess high electrical resistivity and low dielectric loss, making them essential for energy storage and insulation in electronic circuits. Demand concentrates in multilayer ceramic capacitors for automotive electrification and data center power management applications.
- Piezoelectric Ceramics:These ceramics convert mechanical energy into electrical energy and vice-versa, making them critical for sensors, actuators, and transducers. Demand accelerates in advanced driver-assistance systems and medical ultrasound devices due to new sensor applications.
- Magnetic Ceramics:Comprising ferrites and garnets, these materials are used in inductors, transformers, and magnetic recording heads. Their applications include high-frequency communication systems and power conversion units.
- Electroceramics:This broad category encompasses materials engineered for specific electrical properties beyond just dielectric or piezoelectric functions, including thermistors and varistors.
Volume placements concentrate in Dielectric Ceramics; the faster expansion belongs to Piezoelectric Ceramics.
Technology:
The volume of production for electrical ceramics is heavily influenced by the chosen manufacturing technology, dictating throughput and precision.
- Multilayer Ceramic Capacitors:This technology involves stacking multiple thin ceramic layers with interleaved electrodes, forming compact, high-capacitance devices. Automotive electronics and 5G infrastructure drive demand for miniaturized, high-performance capacitors.
- Sintering:This fundamental thermal process compacts ceramic powder into a solid mass, enhancing mechanical strength and electrical properties. Sintering is crucial for nearly all ceramic component manufacturing, impacting final material density.
- Thick Film Technology:This method applies conductive, resistive, or dielectric pastes onto a substrate, followed by firing, creating robust hybrid circuits and sensors. Industrial automation systems frequently utilize thick film circuits for harsh environments.
- Thin Film Technology:This advanced deposition technique creates extremely thin layers of ceramic materials with precise control over composition and structure. High-frequency filters and specialized sensors leverage thin film technology.
- Tape Casting:A method for producing thin, flexible ceramic sheets, which are then cut, stacked, and sintered to create complex multilayer structures. This process is vital for manufacturing ceramic substrates and packages.
Multilayer Ceramic Capacitors technology dominates high-volume production, while Thin Film Technology offers specialized capabilities for niche applications.
Application:
Different customer types drive ceramic application requirements, with each sector demanding specific performance characteristics and reliability standards.
- Automotive Electronics:Ceramics are indispensable for advanced driver-assistance systems, electric vehicle power electronics, and engine management units. Stringent reliability standards and high-temperature performance are critical for automotive applications.
- Telecommunications Equipment:This sector utilizes ceramics for 5G base station filters, antenna substrates, and high-frequency circuit components. Low signal loss and high thermal stability are paramount for telecommunications infrastructure.
- Consumer Electronics:Capacitors, sensors, and substrates are integral to smartphones, laptops, and smart home devices. Miniaturization and cost-effectiveness are key considerations for consumer electronics applications.
- Industrial Automation:Ceramics serve in sensors, actuators, and power control modules for robotics, process control, and manufacturing equipment. Durability and long-term stability are highly valued in industrial settings.
- Aerospace Systems:High-reliability ceramic components are used in avionics, satellite communication, and navigation systems. Extreme temperature tolerance and radiation hardness are essential for aerospace applications.
Automotive Electronics applications are experiencing substantial demand, with Telecommunications Equipment also showing strong material consumption.
End User:
The margin profiles for electronics ceramics suppliers vary significantly based on the end-user segment's qualification processes and volume procurement patterns.
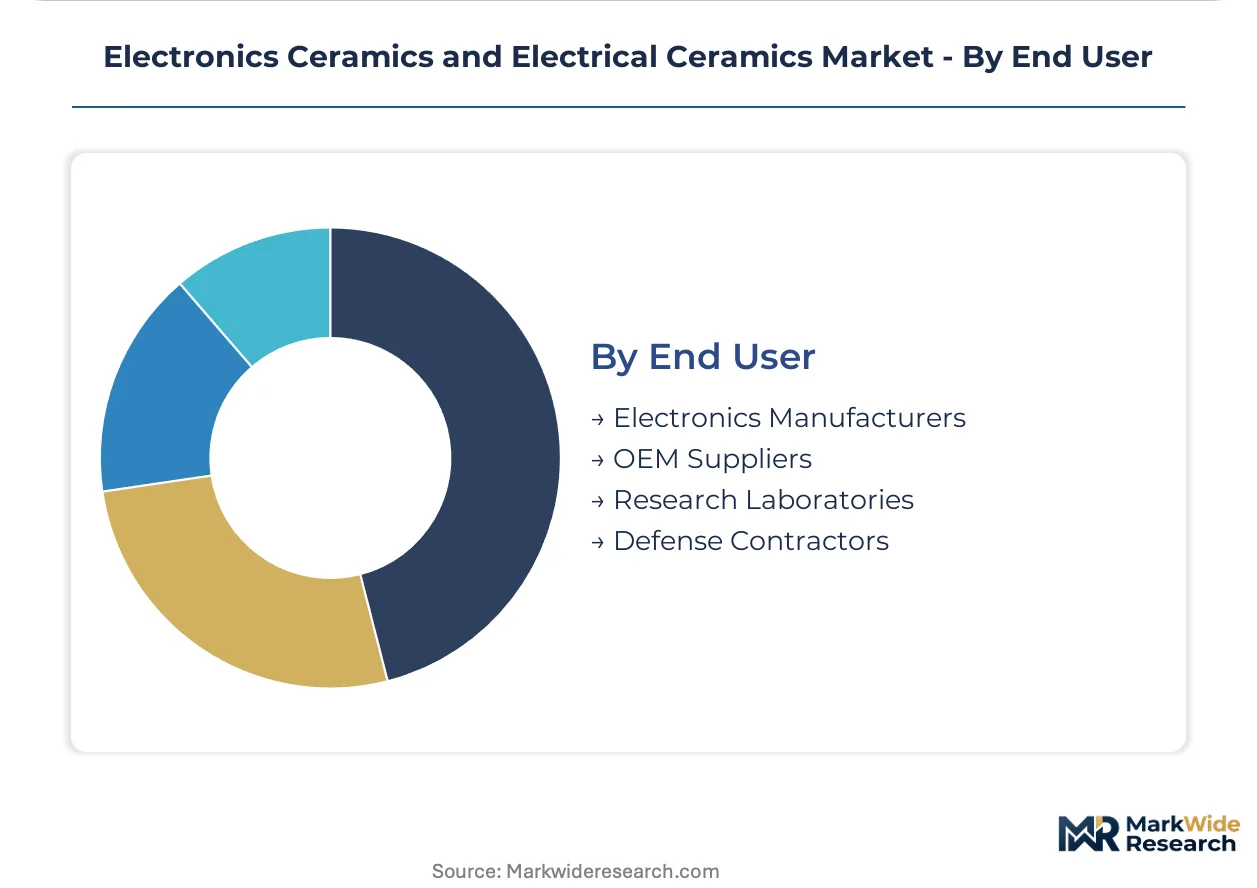
- Electronics Manufacturers:These companies directly procure ceramic components for integration into their final products, such as circuit boards, modules, and devices. Their procurement often involves high volumes and specific technical requirements.
- OEM Suppliers:Original equipment manufacturers integrate ceramic components into sub-assemblies or systems supplied to larger product manufacturers. OEM suppliers require consistent quality and robust supply chain support.
- Research Laboratories:Academic and industrial research institutions utilize specialized ceramic materials for developing new technologies and conducting material science studies. Procurement in this segment often focuses on novel materials and small batch quantities.
- Defense Contractors:These entities require high-reliability, ruggedized ceramic components for military electronics, communication systems, and aerospace applications. Stringent specifications and secure supply chains are critical for defense procurement.
Electronics Manufacturers represent the largest direct procurement channel, with OEM Suppliers driving substantial indirect material acquisition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for electronics ceramics is notably high in regions with advanced manufacturing capabilities and significant electronics production. The global market for these specialized materials is heavily influenced by technological advancements and regulatory frameworks in key industrial nations.
China
China's robust consumer electronics and automotive electrification sectors drive substantial demand for dielectric and piezoelectric ceramics. The country's GB standards influence material selection and manufacturing processes for local and international suppliers. Industrial clusters in the Yangtze River Delta and Pearl River Delta remain central to high-volume ceramic component production.
United States
The United States experiences strong demand for advanced ceramic components from its aerospace, defense, and automotive electronics industries. US EPA guidelines and ISO 9001 certifications govern material composition and quality control for critical applications. Silicon Valley and other tech hubs continue to innovate new device architectures requiring specialized ceramic substrates.
Germany
Germany's automotive and industrial automation sectors are major consumers of high-performance electrical ceramics, particularly for sensors and power electronics. The EU's RoHS directive and REACH regulation mandate lead-free formulations and stringent material declarations. The Bavaria region, with its strong engineering base, supports significant research and manufacturing in advanced ceramics.
South Korea
South Korea's leading position in semiconductor manufacturing and 5G infrastructure development fuels consistent demand for multilayer ceramic capacitors and specialized substrates. The country's national standards and strong R&D investment drive continuous material innovation. The Seoul Capital Area and surrounding industrial zones house major electronics manufacturers and ceramic component suppliers.
Japan
Japan's long-standing leadership in electronics and precision manufacturing ensures sustained demand for high-quality electronics ceramics. METI initiatives support advanced material development for next-generation devices and automotive applications. The Kanto region, including Tokyo, serves as a hub for ceramic material research and component fabrication.
Electronics Ceramics and Electrical Ceramics Market Key Industry Players
Japanese and South Korean producers anchor one tier of the market, focusing on high-volume, precision ceramic components; European and North American specialists hold another, concentrating on high-performance and niche applications. The market structure exhibits a tiered consolidation, with a few large integrated players dominating core segments while numerous specialized firms serve specific industrial needs. Key competitive moves include strategic partnerships for technology co-development and continuous investment in R&D for lead-free material formulations.
Within the high-volume, integrated manufacturing tier, Murata Manufacturing Co., Ltd. and Kyocera Corporation exemplify extensive production capabilities across diverse ceramic product types. TDK Corporation also occupies a significant position, particularly in magnetic and piezoelectric ceramic components. These companies leverage their scale and technical expertise to maintain leadership in segments like multilayer ceramic capacitors and advanced substrates, driven by global demand in automotive and consumer electronics.
| Leading Market Players |
|---|
| Murata Manufacturing Co., Ltd. |
| Kyocera Corporation |
| CeramTec GmbH |
| Morgan Advanced Materials |
| CoorsTek Inc. |
| TDK Corporation |
| NGK Insulators, Ltd. |
| Maruwa Co., Ltd. |
| APC International |
| Others |
Cost & Logistics Intelligence
Lead-free material innovation simultaneously reshapes cost economics and concentrates global supply chains for electronics ceramics. This shift necessitates higher R&D investment and specialized processing capabilities, impacting both component pricing and material sourcing strategies.
Pricing Analysis
Volume-driven segments in electronics ceramics prioritize cost efficiency, while high-performance niche applications command premium margins. The dominant pricing model is per-unit transactional, heavily influenced by raw material costs and manufacturing scale. Price differentiation stems from quality grade, ISO 9001 certification level, and customization requirements for specific end-user applications. Pricing softness reflects raw material price volatility for inputs like barium titanate. Consumer electronics manufacturers exhibit the highest price sensitivity, whereas aerospace systems buyers prioritize performance and reliability over cost.
Supply Chain Analysis
Skilled workforce availability in China and South Korea underpins the high-volume production of electronics ceramics. Geographic supply concentration for ceramic components centers on China, South Korea, and Japan. The industry draws from key inputs such as high-purity alumina and barium titanate. Geopolitical risk associated with processing concentration in Asia presents a structural supply chain vulnerability. Distribution runs through a dual model, with Electronics Manufacturers directly procuring components and OEM Suppliers integrating ceramics into sub-assemblies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electronics ceramics market is becoming a vertical integration race, with companies seeking upstream control over specialized raw material processing to mitigate supply chain risks.
For Market Incumbents: To counter tightening substance-of-concern regulations, incumbent manufacturers must accelerate R&D investments in lead-free piezoelectric and dielectric compounds. Strategic partnerships for technology co-development can share the burden of high capital intensity for new processing facilities. Expanding regional manufacturing capacity in Europe, driven by initiatives like the EU Chips Act, enhances supply chain resilience. Investing in advanced material characterization and ISO 9001 certification maintains a competitive edge in automotive and aerospace segments.
For New Entrants and Emerging Players: Price-point gaps exist between highly specialized, high-performance ceramics and commodity volume products, creating entry opportunities for focused players. Target underpenetrated segments like biocompatible medical ceramics or specialized substrates for wide-bandgap devices. A go-to-market angle focusing on niche applications with stringent performance requirements, such as those for SiC and GaN power electronics, allows for premium pricing. Emphasize deep material data and supply chain transparency to win over automotive and aerospace customers.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized material science firms and regional fabrication facilities for electronics ceramics. Long-term viability over the next 5-10 years is strong, driven by sustained demand from automotive electrification, 5G infrastructure, and data center expansion. Acquisition targets should include companies with patented lead-free formulations or unique processing technologies. The signal to watch for inflection points is successful qualification of novel lead-free materials in high-volume automotive electronics applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Accelerate Lead-Free Material R&D | Ensures compliance with evolving regulations and enables new device performance. |
| Expand Regional Manufacturing Capacity | Mitigates geopolitical risks and strengthens localized supply chains. |
| Develop Advanced Substrates for GaN/SiC | Captures growth in high-power, high-frequency electronics applications. |
| Invest in Automotive Electronics Qualification | Unlocks access to a high-growth, high-reliability end-use market. |
| Form Strategic Partnerships for 5G Components | Facilitates co-development of high-frequency dielectric ceramics and filters. |
Research Approach
Independent corroboration across industry association reports, regulatory body publications, and corporate financial disclosures underwrites the qualitative findings of this study. Primary interviews with R&D directors, procurement leads at electronics manufacturers, automotive engineers, and material scientists provided granular insights. This approach integrated bottom-up data from component suppliers with top-down market perspectives from major end-users, ensuring comprehensive data validation.
Rate-of-change decomposition models market evolution by segmenting historical data and projecting future growth drivers across the analysis window. The analytical framework incorporated segmentation dimensions such as product type, technology, application, end user, and regional regulatory compliance. Compound annual growth rates were derived from a blend of historical trends and anticipated shifts in key demand drivers. Forecast inputs included 5G network deployment rates and electric vehicle production volumes.
Underlying measurement precision varies by segment; established dielectric ceramics and automotive electronics applications carry tighter precision than emerging medical ceramics. Forecasts reflect assumptions regarding technological advancements and regulatory stability. Material deviation in raw material supply or regulatory enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Ceramic Additives Market
Ceramics
Polymer-Derived Ceramics Market
Ceramics
Active Calcium Silicate Market
Ceramics
Ceramic Substrate Market
Ceramics
Ceramic Frit Glass Market
Ceramics
US Kaolin Market
Ceramics
Thailand Ceramic Tiles Market
Ceramics
Ceramic Binders Market
Ceramics
Low Temperature Co-Fired Ceramic (LTCC) Market
Ceramics
Cerium Carbonate Market
Ceramics
Taiwan Ceramic Tiles Market
Ceramics
Graphite Crucibles Market
Ceramics
Porous Ceramic Market
Ceramics
Global Thermal Ceramics Market
Ceramics
East Africa Ceramic Tiles Market
Ceramics
High Purity Mullite Powder Market