
 Low Temperature Co-Fired Ceramic (LTCC) Market | 2026-2036
Low Temperature Co-Fired Ceramic (LTCC) Market Size, Share, and Industry Trends Forecast 2026-2036
Low Temperature Co-Fired Ceramic (LTCC) Market Foresight
A shift from single-source ceramic powder procurement to multi-source qualification is realigning supplier relationships across the LTCC value chain. Murata Manufacturing sustains captive material streams through backward integration into dielectric formulations. TDK Corporation leverages its thin-film deposition expertise to dominate high-frequency component segments for 5G base stations. Kyocera Corporation anchors production scale across automotive-qualified LTCC substrates, competing on thermal cycling reliability metrics.
Low Temperature Co-Fired Ceramic denotes a multilayer ceramic technology fired below 1,000°C, enabling co-firing of silver or copper conductors with glass-ceramic dielectrics to produce dense, hermetic electronic packages. The process yields low-loss, high-thermal-conductivity substrates essential for microwave and millimeter-wave circuits in telecommunications and radar modules. LTCC Components command the largest revenue pool due to recurring demand for filters, couplers, and antennas in base station rollouts. Multi-Layer Technology represents the fastest-growing process category as stack counts rise above twenty layers for compact RF front-end modules. Hybrid Technology occupies niche margin pools where LTCC integrates with semiconductor dies in medical imaging and aerospace sensor applications.
FCC spectrum allocation rules in the United States and EU Radio Equipment Directive compliance requirements in Europe shape product certification timelines and performance benchmarks for LTCC-based RF components. Japan's METI energy-efficiency standards and China's GB/T electromagnetic compatibility regulations further constrain design parameters for automotive and industrial deployments. Stakeholders must monitor evolving mmWave spectrum policy across telecommunications regulators and assess qualification burdens before committing to regional manufacturing footprints.
Market Dynamics
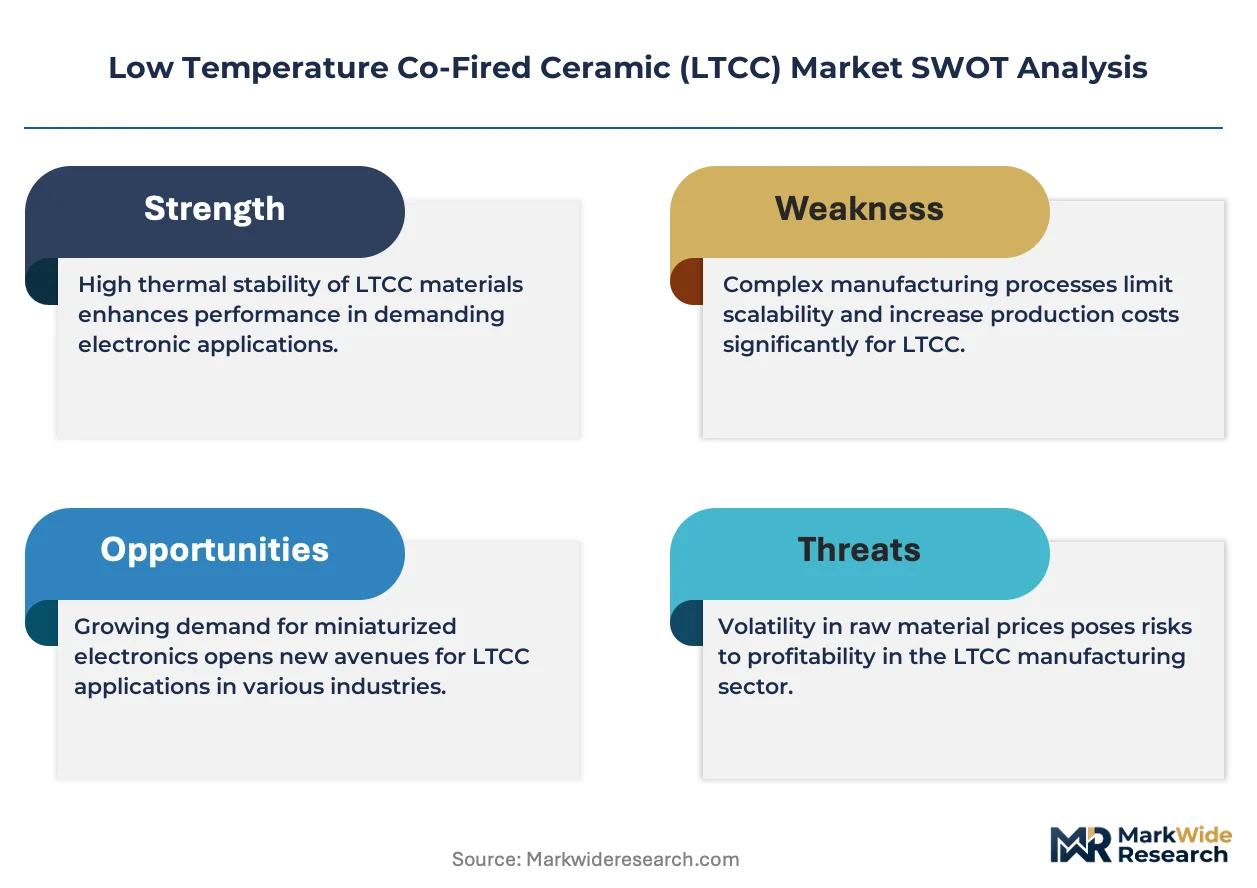
Silver paste cost volatility and multi-layer stack complexity are compressing margins for LTCC fabricators while telecommunications infrastructure rollouts accelerate substrate consumption.
Growth Catalysts
- 5G Base Station Deployment:Millimeter-wave spectrum allocation by the FCC is driving filter and antenna module demand for telecommunications infrastructure expansion.
- REACH Compliance:European ECHA substance restrictions are forcing reformulation of glass-ceramic dielectrics toward lead-free compositions, opening qualified supplier positions.
- Automotive Radar Integration:77-81 GHz sensor modules for advanced driver-assistance systems are consuming hermetic LTCC packages for thermal cycling reliability.
Market Restraints
- Silver Price Volatility:Precious metal conductor pastes represent 35-45% of material costs, exposing fabricators to London Bullion Market Association spot price swings.
- East Asian Supply Concentration:Ceramic powder synthesis and tape casting capacity clusters in Japan, China, and South Korea, creating single-source qualification risks.
- Firing Temperature Floor:Glass-ceramic densification chemistry limits further temperature reduction below 850°C, constraining copper conductor adoption versus silver.
Strategic Opportunities
- India Telecommunications:TRAI spectrum auctions and domestic manufacturing incentives under the PLI scheme are opening substrate demand from indigenous base station vendors.
- Medical Implant Hermeticity:ISO 10993 biocompatibility certification pathways enable LTCC feedthroughs for implantable neurostimulator and pacemaker enclosures.
- Photonics Hybrid Integration:Co-firing of glass-ceramic with silicon photonics interposers enables optical transceiver modules for data center interconnects.
Industry Challenges
- Multi-Layer Registration Tolerance:Stack counts exceeding twenty layers demand sub-micron via alignment across sequential lamination steps, straining dimensional metrology capabilities.
- RoHS Recast Compliance:EU delegated directive updates on restricted substance thresholds require continuous supply chain documentation and third-party testing expenditure.
- RF Simulation Talent Scarcity:Electromagnetic field solver expertise for millimeter-wave design combines ceramic material science with computational physics, limiting qualified engineering pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Temperature Co-Fired Ceramic (LTCC) Market |
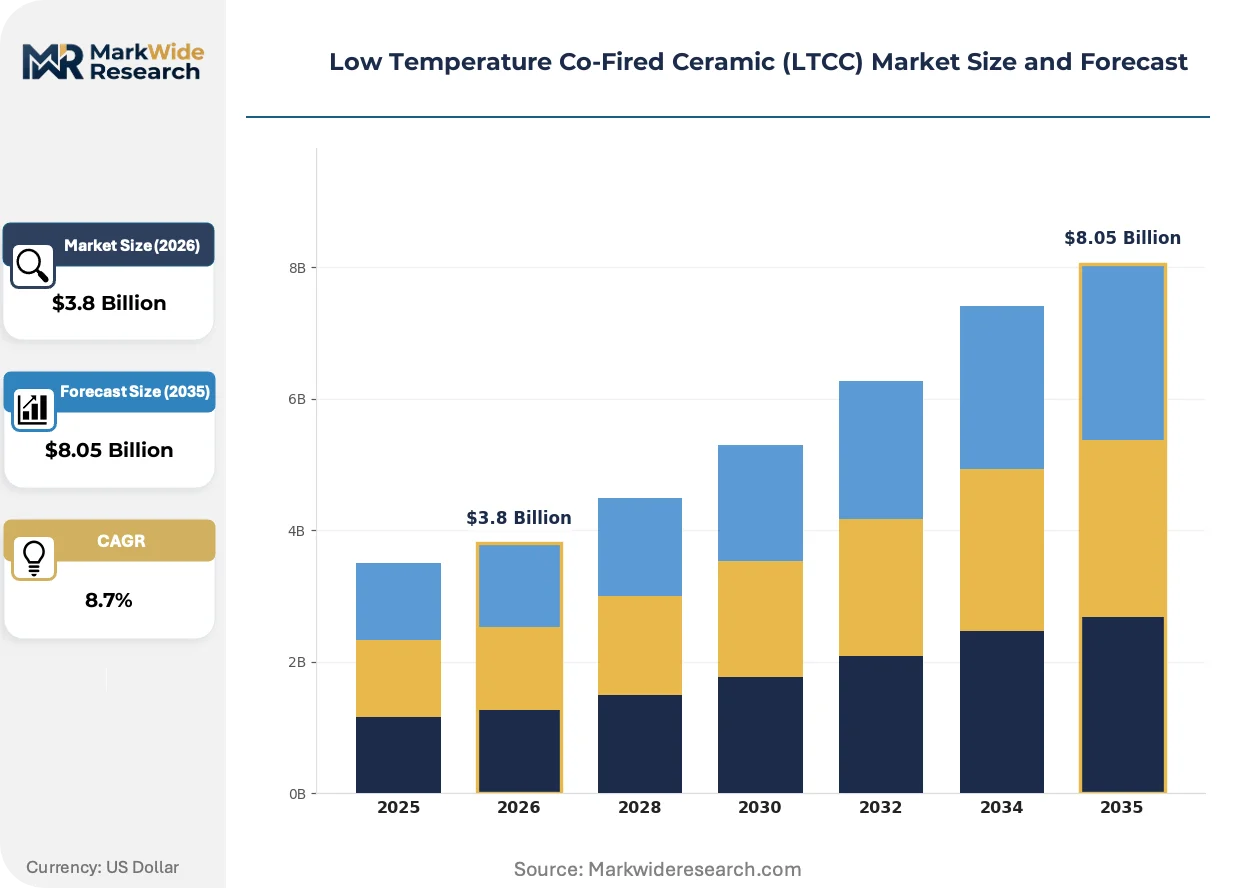
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LTCC Substrates, LTCC Components, LTCC Assemblies, LTCC Devices Application: Telecommunications, Automotive Electronics, Medical Devices, Consumer Electronics End User: OEMs, Contract Manufacturers, Research Institutions, Component Suppliers Technology: Thin-Film Technology, Multi-Layer Technology, Hybrid Technology, Printed Circuit Technology |
| Companies Covered | KOA Corporation, Yokowo Co., Ltd., Murata Manufacturing Co., Ltd., Selmic Oy, DuPont, Kyocera Corporation, NGK Spark Plug Co., Ltd., Adamant Namiki Precision Jewel Co., Ltd., TDK Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Temperature Co-Fired Ceramic (LTCC) Market Shifts & Advancements
Material formulation advances and co-firing process control are enabling denser interconnect integration while regulatory chemical restrictions reshape supplier qualification protocols.
Ultra-low-loss glass-ceramic compositions with dielectric constants below 4.0 are expanding into 28 GHz and 39 GHz 5G new radio bands. Base station original equipment manufacturers in South Korea and Japan are qualifying these substrates for massive MIMO antenna arrays. The technology is expanding into module footprints previously served by organic laminates, compressing bill-of-material costs for high-frequency channels.
EU REACH Annex XVII restrictions on lead and cadmium compounds are forcing reformulation of traditional borosilicate glass-ceramic systems. ECHA authorization timelines are extending material qualification cycles by 12-18 months for European automotive and medical device suppliers. Dielectric material vendors with pre-registered substance portfolios are capturing preferred supplier status ahead of 2027 sunset dates.
Consolidated procurement functions at telecommunications equipment manufacturers are unbundling substrate supply from module assembly, creating direct material qualification relationships. Tier-one base station vendors in China and Sweden are establishing dedicated LTCC technical sourcing teams with ceramic engineering expertise. This pattern is most visible in Shenzhen and Stockholm, where supplier development programs now include joint firing process optimization.
Low Temperature Co-Fired Ceramic (LTCC) Market Segmentation
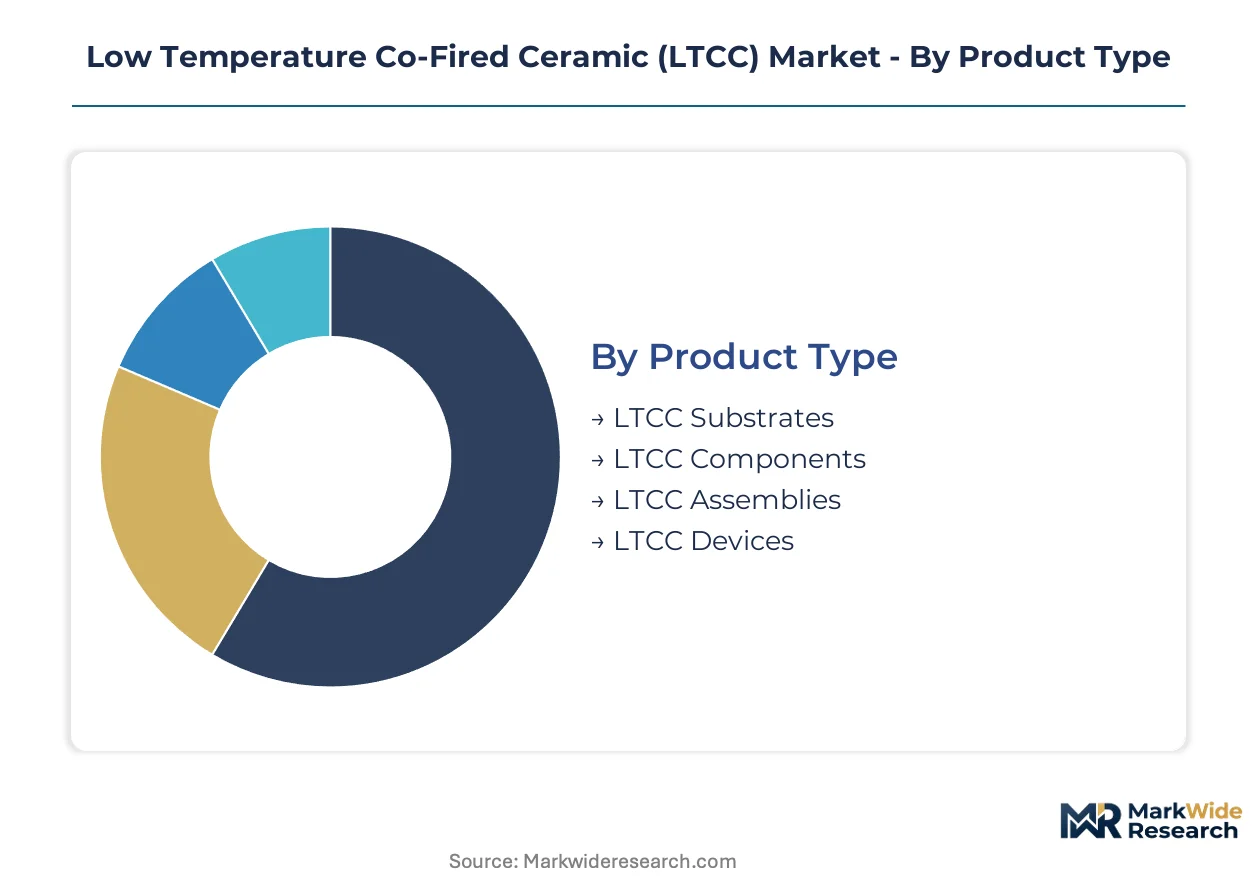
LTCC market segmentation reveals distinct certification pathways and performance thresholds across product hierarchies. Each category carries specific regulatory burdens that determine supplier qualification timelines and manufacturing location decisions.
Product Type:
EU REACH Annex XVII substance restrictions and RoHS delegated directive updates impose differentiated compliance burdens across product tiers, with medical-grade assemblies requiring ISO 10993 biocompatibility certification.
- LTCC Components:Filters, couplers, and antenna modules dominate telecommunications infrastructure consumption. Base station rollouts in South Korea and Japan concentrate demand for 28 GHz and 39 GHz qualified devices.
- LTCC Substrates:Glass-ceramic tape systems fired below 1,000°C enable silver or copper conductor co-firing for hermetic electronic packages. Automotive radar modules in Germany and Japan specify thermal cycling reliability metrics that constrain supplier pools.
- LTCC Assemblies:Integrated module solutions for RF front-ends require FCC Part 15 certification in the United States and EU Radio Equipment Directive compliance.
- LTCC Devices:Packaged sensor and actuator units for industrial automation carry IEC 61000 electromagnetic compatibility requirements.
Leading the category by volume: LTCC Components. Growing fastest: LTCC Substrates.
Application:
Cost tier stratification separates premium-certified medical and aerospace applications from high-volume telecommunications and automotive electronics.
- Telecommunications:Millimeter-wave spectrum deployment by the FCC and TRAI spectrum auctions in India drive filter and antenna module consumption. Massive MIMO arrays in South Korea specify ultra-low-loss dielectric constants below 4.0.
- Automotive Electronics:77-81 GHz radar sensors for advanced driver-assistance systems require hermetic packaging with thermal cycling endurance. NHTSA safety standards and Japan's METI energy-efficiency regulations shape design parameters.
- Medical Devices:Implantable neurostimulator and pacemaker enclosures demand ISO 10993 biocompatibility certification and hermetic feedthrough integrity.
- Consumer Electronics:High-frequency RF modules for smartphones and wearables compete on bill-of-material cost compression against organic laminate alternatives.
Telecommunications generates the largest revenue pool. Medical Devices carries the steepest expansion trajectory due to certification-constrained supply.
End User:
Procurement authority concentration varies sharply across customer types, with OEMs establishing direct material qualification relationships and contract manufacturers competing on process yield.
- OEMs:Base station original equipment manufacturers in China and Sweden unbundle substrate supply from module assembly, creating dedicated LTCC technical sourcing teams with ceramic engineering expertise.
- Contract Manufacturers:Electronics manufacturing services providers compete on firing process yield and multi-layer registration tolerance for stack counts exceeding twenty layers.
- Research Institutions:University and national laboratory programs drive photonics hybrid integration and silicon photonics interposer development for optical transceiver modules.
- Component Suppliers:Tier-two and tier-three vendors supply standardized filters and couplers to distributors serving industrial and automotive aftermarket channels.
OEMs command the largest procurement volume. Research Institutions are climbing the fastest as government funding expands for advanced packaging R&D.
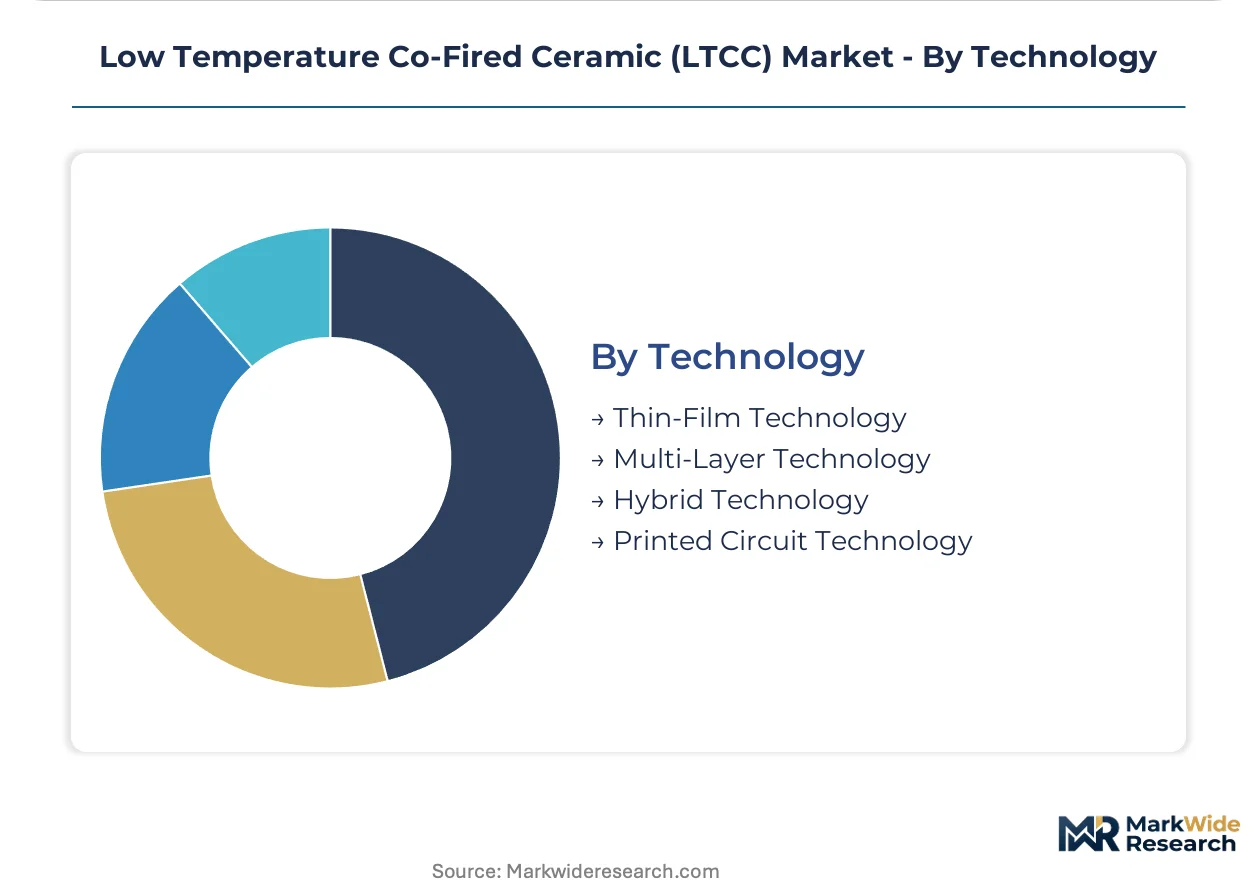
Technology:
Process maturity separates established multi-layer and thin-film methods from emerging hybrid integration approaches that combine ceramic and semiconductor fabrication.
- Multi-Layer Technology:Sequential lamination of twenty-plus layer stacks demands sub-micron via alignment and dimensional metrology capabilities. Telecommunications infrastructure rollouts accelerate substrate consumption for compact RF front-end modules.
- Thin-Film Technology:Sputtered and evaporated conductor deposition enables fine-line geometries for millimeter-wave circuits. TDK Corporation leverages this expertise for 5G base station high-frequency component segments.
- Hybrid Technology:Co-firing of glass-ceramic with semiconductor dies serves medical imaging and aerospace sensor applications in niche margin pools.
- Printed Circuit Technology:Screen-printed conductor patterns on ceramic tape support cost-sensitive industrial and consumer electronics applications.
Multi-Layer Technology leads by production volume. Hybrid Technology is expanding most quickly as photonics integration requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for LTCC substrates clusters in East Asian telecommunications infrastructure hubs, with regulatory compliance requirements in Europe and North America reshaping material qualification pathways for suppliers seeking cross-regional market access.
China
Domestic 5G base station rollouts and massive MIMO antenna array deployments drive substrate consumption for millimeter-wave RF modules. MIIT spectrum allocation policies and GB/T electromagnetic compatibility standards constrain design parameters for telecommunications equipment. Shenzhen hosts concentrated procurement teams from tier-one base station vendors establishing direct material qualification relationships with dielectric suppliers.
Japan
Automotive radar sensor integration for advanced driver-assistance systems and high-frequency telecommunications components anchor domestic fabrication capacity. METI energy-efficiency standards shape thermal cycling reliability specifications for automotive-qualified substrates. Kyoto and Nagoya industrial corridors concentrate multi-layer ceramic device fabrication with backward-integrated material streams.
South Korea
28 GHz and 39 GHz 5G new radio band deployments accelerate filter and antenna module demand for telecommunications infrastructure. National spectrum policy under the Ministry of Science and ICT governs millimeter-wave equipment certification timelines. Seoul metropolitan area vendors qualify ultra-low-loss dielectric compositions for massive MIMO arrays.
Germany
Automotive electronics suppliers specify hermetic LTCC packages for 77-81 GHz radar modules in advanced driver-assistance systems. ECHA REACH Annex XVII restrictions on lead compounds extend material qualification cycles for glass-ceramic dielectric reformulation. Bavaria and Baden-Württemberg host automotive tier-one engineering centers driving thermal cycling reliability standards.
United States
FCC millimeter-wave spectrum allocation rules shape RF component certification timelines for telecommunications infrastructure. NHTSA safety standards influence automotive radar module packaging requirements. Greater Boston and Silicon Valley clusters concentrate RF simulation expertise for electromagnetic field solver development in millimeter-wave design.
Low Temperature Co-Fired Ceramic (LTCC) Market Competitive Landscape
Backward integration into dielectric formulations dominates the current landscape as fabricators seek captive material streams amid silver paste cost volatility and multi-layer stack complexity pressures. The vendor base stratifies across three tiers: integrated material-to-module conglomerates with in-house powder synthesis, specialized substrate fabricators competing on firing process yield, and regional component suppliers serving aftermarket industrial channels. Two competitive vectors define positioning: vertical control over glass-ceramic compositions versus multi-source qualification agility, and scale-driven cost compression versus premium-tier certification specialization.
Among Japanese fabricators, Murata Manufacturing Co., Ltd., TDK Corporation, and Kyocera Corporation exemplify divergent strategic archetypes within the integrated tier. Murata Manufacturing Co., Ltd. occupies a position anchored in backward-integrated material streams through captive dielectric formulation capabilities. TDK Corporation sits within the thin-film deposition specialization vector, leveraging sputtered conductor expertise for high-frequency segment positioning. Kyocera Corporation represents the production-scale archetype competing on automotive-qualified substrate reliability metrics and thermal cycling endurance specifications.
| Leading Market Players |
|---|
| KOA Corporation |
| Yokowo Co., Ltd. |
| Murata Manufacturing Co., Ltd. |
| Selmic Oy |
| DuPont |
| Kyocera Corporation |
| NGK Spark Plug Co., Ltd. |
| Adamant Namiki Precision Jewel Co., Ltd. |
| TDK Corporation |
| Others |
Supply & Pricing Matrix
Multi-layer stack counts exceeding twenty layers are compressing fabrication yields while simultaneously concentrating procurement leverage among telecommunications OEMs with dedicated ceramic engineering teams. This process intensification redraws cost economics across silver paste consumption, firing cycle throughput, and dimensional metrology investment.
Pricing Analysis
Service bundling separates qualified material supply with joint firing process optimization from unbundled substrate-only transactions. Three-tier pricing structure across automotive-qualified, telecommunications-standard, and industrial-economy levels reflects certification burden and thermal cycling reliability specifications. Pricing pressure stems from silver spot volatility on the London Bullion Market Association, with precious metal pastes representing the dominant material cost component. Contract manufacturers exhibit highest price sensitivity due to yield-driven margin compression, while medical device OEMs accept premium positioning for ISO 10993 biocompatibility pathways.
Supply Chain Analysis
Freight cost exposure runs through ceramic powder synthesis clusters in Japan, China, and South Korea, where tape casting capacity concentrates near downstream module assembly. Raw material dependencies center on borosilicate glass precursors, silver and copper conductor pastes, and alumina filler systems. Single-source qualification risk dominates structural vulnerability as ECHA REACH authorization timelines extend material approval cycles. Distribution feeds from captive material streams at integrated conglomerates through specialized substrate fabricators to regional component suppliers serving aftermarket industrial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LTCC sector occupies a technology-transition phase as ultra-low-loss dielectric compositions below 4.0 displace legacy borosilicate systems in millimeter-wave 5G infrastructure.
For Market Incumbents: Anchor backward integration into dielectric formulations to defend against silver paste cost volatility and multi-source qualification disruption. Consolidate firing process yield advantages through dimensional metrology investment for twenty-plus layer stacks. Prioritize captive material streams as procurement functions at telecommunications OEMs unbundle substrate supply from module assembly.
For New Entrants and Emerging Players: Photonics hybrid integration with silicon photonics interposers offers unclaimed positioning in data center optical transceiver modules. Target medical implant hermeticity segments constrained by ISO 10993 certification scarcity and limited qualified supplier pools. Pursue joint development agreements with research institutions advancing glass-ceramic co-firing process control.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized substrate fabricators possessing automotive thermal cycling qualifications given NHTSA safety standard expansion and METI energy-efficiency adoption. Long-term viability hinges on material formulation IP and regional regulatory pre-registration portfolios. Monitor ECHA REACH Annex XVII sunset date progression as inflection indicator for preferred supplier status capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dielectric Formulations | Murata Manufacturing sustains captive material streams against silver volatility. |
| Multi-Source Qualification Agility | European automotive suppliers reduce single-source risk through ECHA-registered portfolios. |
| Photonics Hybrid Integration | Glass-ceramic co-firing with silicon interposers enables data center optical modules. |
| Automotive Thermal Cycling Certification | Kyocera Corporation anchors production scale through NHTSA-qualified substrate reliability. |
| Joint Firing Process Optimization | Shenzhen procurement teams establish direct technical sourcing with dielectric vendors. |
Research Methodology
Independent corroboration across primary interviews with RF design engineers, ceramic process technologists, telecommunications procurement directors, and automotive tier-one substrate specifiers underwrites the qualitative findings. Secondary validation draws from FCC spectrum allocation filings, ECHA REACH substance registration databases, MIIT electromagnetic compatibility standards, and SEC 10-K disclosures from integrated material-to-module conglomerates. Bottom-up fabrication capacity modeling and top-down telecommunications infrastructure deployment tracking triangulate volume estimates.
Comparable historical reference periods spanning pre-5G substrate demand and millimeter-wave spectrum allocation waves anchor the projection framework. Segmentation dimensions span product type, application, end user, and technology process category, with dielectric constant tiers and layer count stratification as industry-specific modeling inputs. CAGRs derive from regression analysis against telecommunications capital expenditure cycles and automotive radar sensor penetration curves.
Several conditions sit outside the modeled scope, including unannounced regulatory substance restrictions, breakthrough low-temperature co-firing chemistries below 850°C, and geopolitical trade measures affecting ceramic powder cross-border flows. Forecasts reflect assumptions about spectrum auction timing and OEM qualification cycle durations. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Thailand Ceramic Tiles Market
Ceramics
Traditional Ceramic Market
Ceramics
Engineering Ceramics Market
Ceramics
Construction Ceramics Market
Ceramics
Advanced Ceramic Additives Market
Ceramics
Hot-Pressed Aluminum Titanate Ceramics Market
Ceramics
Global Thermal Ceramics Market
Ceramics
Calcined Kaolin Market
Ceramics
Boiler Refractory Material Market
Ceramics
Saudi Arabia Ceramic Tiles Market
Ceramics
Controlled Pore Metal Oxide Market
Ceramics
Ceramics Packaging Market
Ceramics
Ceramic Proppant Market
Ceramics
Colloidal Alumina Market
Ceramics
Global Ceramic Foams Market
Ceramics
Mexico Ceramic Tiles Market