
 Ceramic Binders Market | 2026-2036
Ceramic Binders Market Size, Share, and Industry Trends Forecast 2026-2036
Ceramic Binders Market Outlook
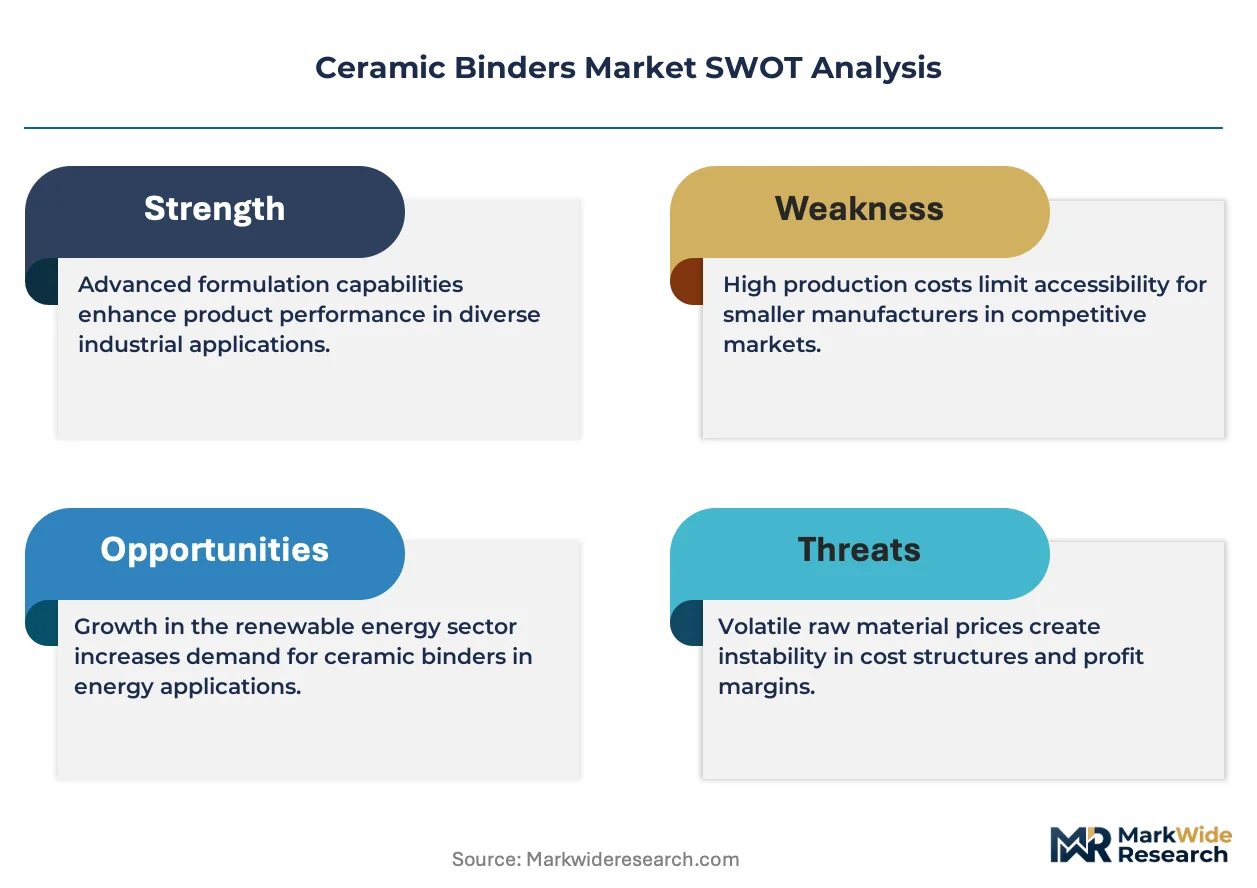
Specialist polymer chemist availability is bifurcating the competitive landscape into R&D-intensive multinationals and regionally focused compounders. BASF SE leverages its Ludwigshafen integrated site to sustain captive alumina-silicate supply chains. Evonik Industries AG differentiates through high-purity organosilicon binder platforms for turbine blade casting. DuPont de Nemours anchors North American aerospace qualification programs with ceramic matrix composite precursors.
Ceramic binders comprise film-forming agents—typically colloidal alumina, silica sols, or synthetic polymers—that suspend and adhere ceramic particulates during green-body shaping before burnout or sintering, with viscosity specifications often ranging from 500 to 5000 mPa·s at application temperature. Organic Binders dominate formulation volumes in tape casting and injection molding where thermoplastic behavior enables complex near-net shaping. Inorganic Binders capture margin pools in refractory linings for steel and glass furnaces where sodium silicate and phosphate systems withstand temperatures exceeding 1500°C without carbonaceous residue. Hybrid Binders represent the fastest-growing structural category as formulators blend temporary organic strength with permanent inorganic bonding to reduce defect rates in additive manufacturing of technical ceramics.
EPA hazardous air pollutant standards under Maximum Achievable Control Technology constrain solvent-based organic binder formulations in U.S. ceramics plants, while REACH registration requirements in Europe force substitution of formaldehyde-releasing phenolic resins. China's GB standards for building materials and industrial ceramics, administered by SAMR, mandate low-emission binders in construction-grade products. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple jurisdictions, as fluoropolymer binders face prospective phase-outs that would redirect R&D spending toward silicone and bio-derived alternatives.
Market Dynamics
Hybrid binder architectures are restructuring competitive advantage as aerospace propulsion OEMs demand defect-free additive manufacturing of ceramic matrix composites, forcing formulators to merge temporary organic strength with permanent inorganic bonding in single systems.
Growth Catalysts
- Turbine blade casting demand:Aerospace propulsion manufacturers in the United States and Germany are qualifying high-purity organosilicon binders for single-crystal superalloy investment casting, creating specification pull-through across the supply base.
- REACH formaldehyde restrictions:ECHA's tightening controls on phenolic resin emissions are accelerating substitution toward low-emission silicone and bio-derived binder platforms in European technical ceramics.
- Refractory furnace rebuild cycles:Steel and glass producers in China are specifying phosphate and sodium silicate inorganic binders for linings exceeding 1500°C, eliminating carbonaceous residue concerns in high-purity melts.
Market Restraints
- Specialty polymer chemist scarcity:The limited pool of formulation scientists capable of hybrid binder design concentrates R&D capability within integrated multinationals, raising barriers for regional compounders.
- Alumina-silicate supply concentration:Captive production of colloidal alumina at Ludwigshafen-scale integrated sites creates dependency risks for non-integrated formulators seeking qualified raw material streams.
- Fluoropolymer phase-out trajectory:Prospective PFAS restrictions across multiple jurisdictions threaten binder segments reliant on fluoropolymer chemistries, forcing premature R&D redirection before technically mature alternatives exist.
Strategic Opportunities
- Additive manufacturing qualification:Technical ceramics producers in Japan are pioneering binder jetting systems that blend organic burnout behavior with inorganic green strength, opening near-net shaping applications previously limited to injection molding.
- India refractory expansion:BIS standards alignment with international furnace lining specifications creates entry pathways for phosphate-bonded systems in the country's growing steel capacity.
- US EPA MACT compliance services:Hazardous air pollutant standards for solvent-based formulations are generating consultative revenue streams around water-based organic binder transitions and thermal oxidizer optimization.
Industry Challenges
- Green body defect prediction:The nonlinear interaction between organic burnout kinetics and inorganic sintering shrinkage requires computational modeling capabilities that exceed legacy empirical formulation approaches.
- Multi-jurisdiction PFAS monitoring:Tracking evolving state-level restrictions in the United States alongside EU REACH candidate list updates consumes regulatory affairs bandwidth without clear harmonization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceramic Binders Market |
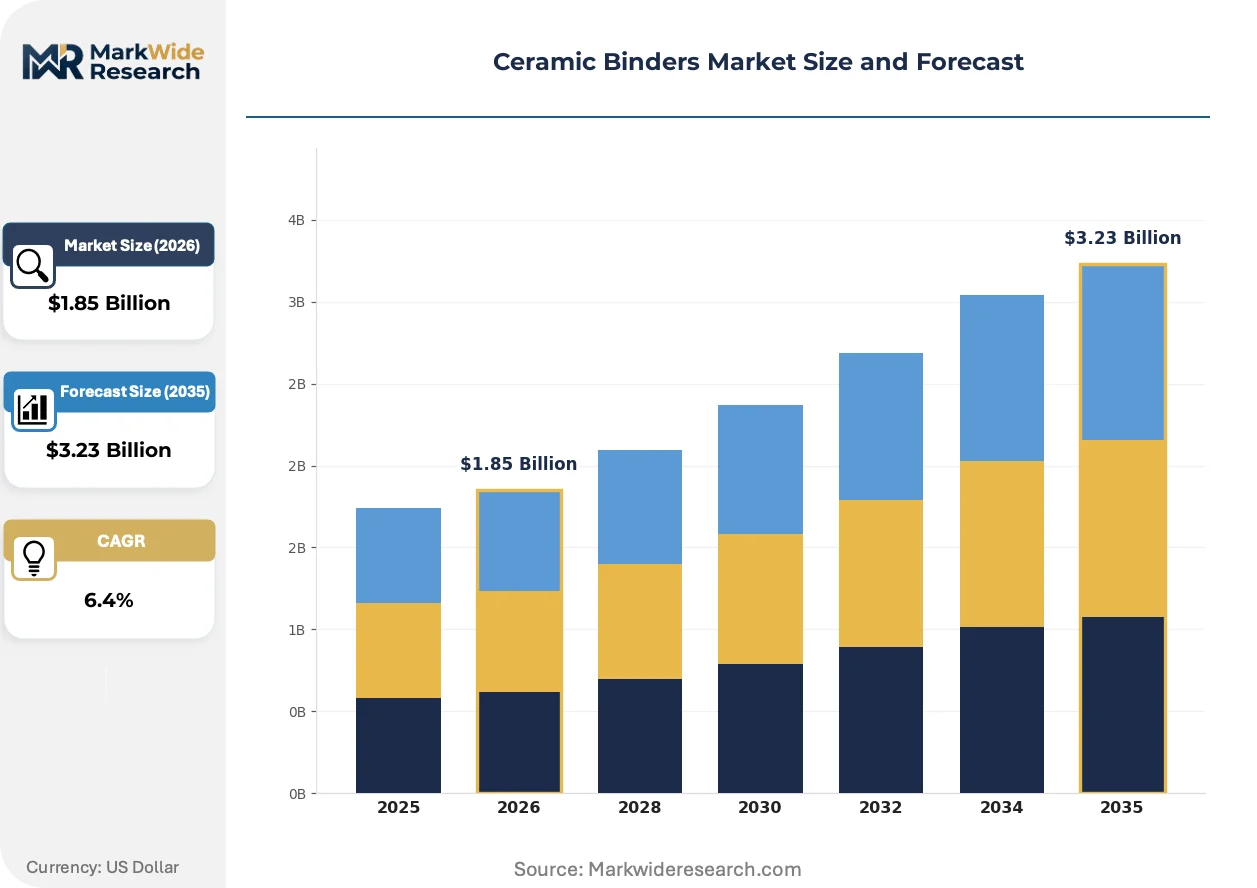
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Binders, Inorganic Binders, Hybrid Binders, Additive Binders Application: Ceramics Production, Refractories, Pottery, Construction Materials End Use Industry: Aerospace, Automotive Components, Electrical Insulators, Consumer Goods Form: Paste, Powder, Liquid, Granular |
| Companies Covered | DuPont de Nemours, KYOEISHA CHEMICAL Co. Ltd, 3M Company, Huntsman Corporation, Zircar Ceramics, BASF SE, Evonik Industries AG, Ferro Corporation, Almatis GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceramic Binders Market Strategic Shifts
Binder chemistry is converging with digital process control as real-time viscosity monitoring and predictive burnout modeling displace empirical batch testing in high-value ceramic manufacturing.
Water-based colloidal silica systems with tailored particle size distributions are fragmenting the solvent-based organic binder installed base in tape casting operations. Aerospace substrate manufacturers in Germany and Japan are adopting these platforms to eliminate thermal oxidizer capital while maintaining green body handling strength. The shift is compressing margins for incumbent solvent-based suppliers unable to match the environmental compliance profile.
REACH registration requirements for formaldehyde-releasing phenolic resins are forcing systematic substitution in European investment casting foundries. ECHA's restriction roadmap is eliminating cost-competitive thermoset options for complex ceramic core applications. Foundries are responding by qualifying acrylate and silicone-modified temporary binders despite higher per-kilogram raw material costs.
Buyer concentration among aerospace propulsion OEMs is consolidating specification authority over binder qualification programs. Tier-2 ceramic component suppliers now face direct auditing of binder source chemistry and burnout residue characterization. This pattern is most pronounced in the United States, where FAA engine certification requirements cascade backward through ceramic matrix composite precursor supply chains.
Ceramic Binders Market Segmentation
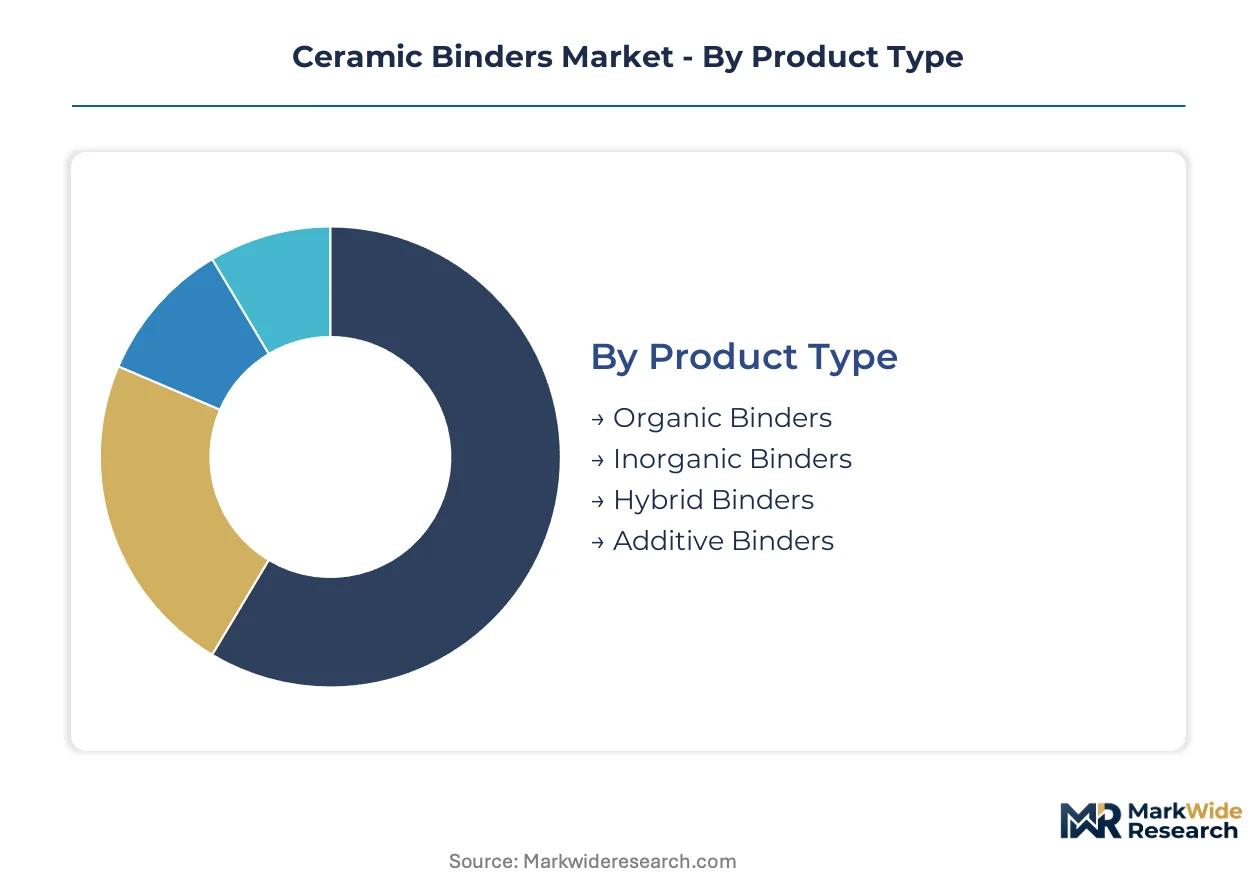
Segmentation in ceramic binders reveals how formulation chemistry, application requirements, and processing constraints create distinct margin architectures. Understanding these divisions exposes where technical differentiation commands premium positioning versus where commoditization pressures dominate.
Product Type:
Highest margin capture concentrates in systems that bridge temporary processing aid with permanent structural contribution, rewarding R&D-intensive formulators.
- Organic Binders:Thermoplastic polymers and thermoset resins enable complex near-net shaping through tape casting and injection molding. Aerospace substrate manufacturers in Germany and Japan specify these for green body handling strength before burnout cycles. Demand concentrates in turbine blade casting foundries where thermoplastic behavior supports intricate core geometries.
- Inorganic Binders:Colloidal alumina, silica sols, and phosphate systems provide permanent bonding without carbonaceous residue. Steel and glass furnace operators in China specify sodium silicate and phosphate binders for refractory linings exceeding 1500°C, eliminating purity concerns in high-temperature melts.
- Hybrid Binders:Blended organic-inorganic architectures merge temporary green strength with permanent ceramic bonding. Additive manufacturing of technical ceramics is driving qualification programs for these systems.
- Additive Binders:Specialized rheology modifiers and dispersants optimize particle suspension in precision casting applications. Investment casting foundries use these for ceramic shell building.
The dominant share belongs to Organic Binders, while Hybrid Binders are closing the gap fastest.
Application:
Volume-weighted demand tracks industrial rebuild cycles and construction activity, while value-weighted demand follows aerospace qualification timelines.
- Ceramics Production:Technical ceramic manufacturers employ binders for structural components, electronic substrates, and wear-resistant parts. Binder jetting systems in Japan blend organic burnout behavior with inorganic green strength for near-net shaping.
- Refractories:Furnace lining applications demand thermal stability without residual carbon. China's steel capacity expansion is specifying phosphate-bonded systems for new installations.
- Pottery:Traditional ceramic ware production uses lower-specification binders for green body integrity. Artisan and industrial producers balance cost against firing characteristics.
- Construction Materials:Building-grade ceramics under SAMR-administered GB standards mandate low-emission binder formulations for tiles and sanitary ware.
Ceramics Production holds the largest volume position, though Refractories demonstrates the steepest expansion trajectory tied to industrial furnace rebuild cycles.
End Use Industry:
Customer concentration and qualification barriers create tiered pricing power, with aerospace propulsion OEMs exercising disproportionate specification authority.
- Aerospace:Propulsion system manufacturers qualify high-purity organosilicon binders for single-crystal superalloy investment casting. FAA engine certification requirements cascade backward through ceramic matrix composite precursor supply chains, forcing direct auditing of binder chemistry.
- Automotive Components:Catalytic converter substrates and sensor housings require thermal shock-resistant ceramic bonding. Emissions control specifications drive binder purity requirements.
- Electrical Insulators:High-voltage ceramic components demand binders that burnout cleanly without conductive residue. Power transmission infrastructure expansion supports steady demand.
- Consumer Goods:Tableware, decorative ceramics, and sanitary fixtures utilize cost-optimized binder systems. Price sensitivity limits formulation complexity.
Aerospace commands the premium tier by margin, while Automotive Components is gaining share fastest on electrification-driven sensor and substrate demand.
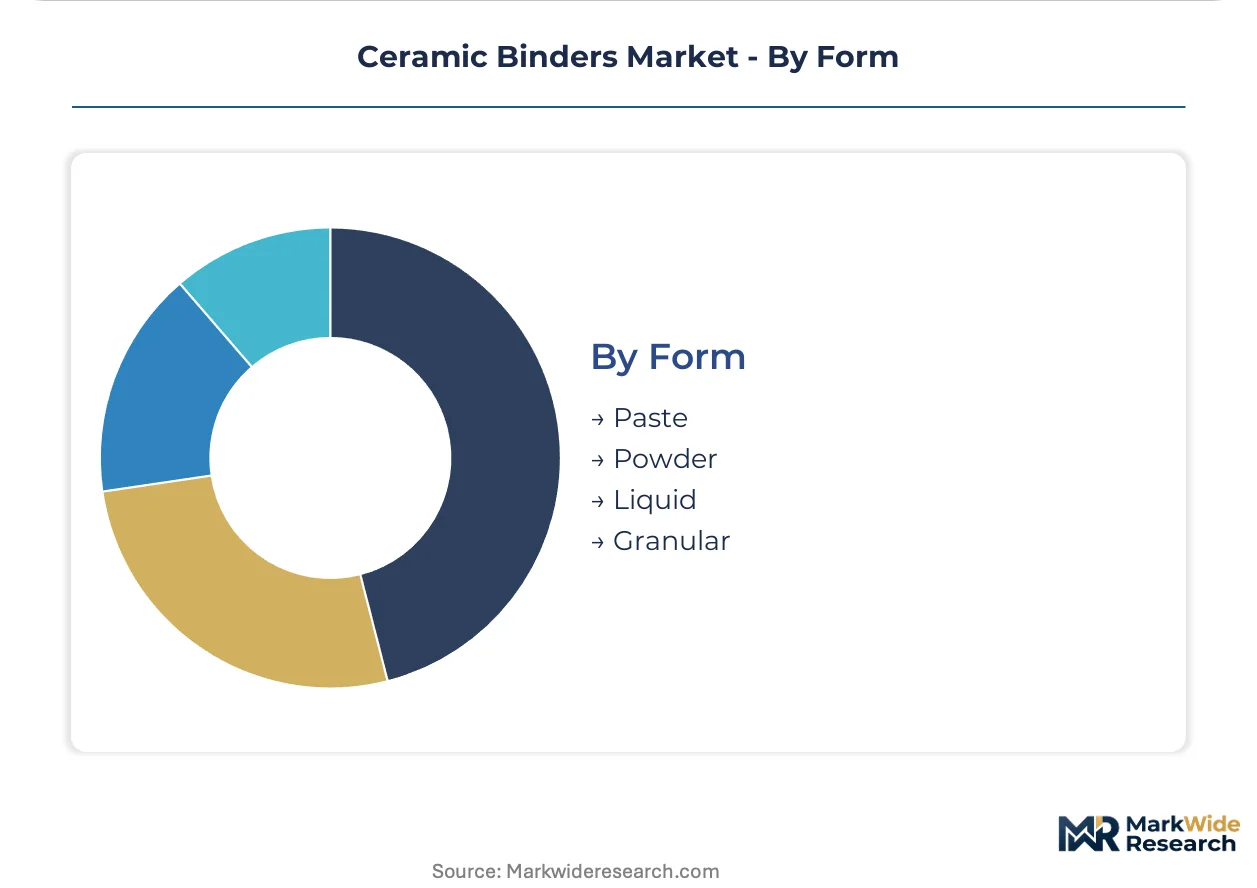
Form:
Processing equipment compatibility and logistics economics determine form selection, with liquid systems capturing value in automated production lines.
- Liquid:Colloidal suspensions and solutions enable precise viscosity control in continuous processing. Water-based silica systems are displacing solvent-based organics in tape casting to eliminate thermal oxidizer capital.
- Paste:High-viscosity formulations suit extrusion and molding operations where shape retention is critical. Thick-film electronics and structural ceramics favor this form.
- Powder:Dry blends facilitate long-distance shipping and custom on-site formulation. Refractory installers prefer powder binders for furnace lining applications.
- Granular:Free-flowing particles support automated dosing in large-scale ceramic tile and brick production. Handling efficiency drives adoption in construction materials.
Liquid forms dominate value capture, while Powder forms are expanding most quickly in refractory applications favoring field-mixed formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR-administered GB standards in China anchor the dominant geography for ceramic binders, with the country's advanced ceramics corridor driving formulation volume. REACH compliance in Europe and EPA MACT standards in the United States reshape competitive positioning across secondary markets. Industrial clusters in Germany, Japan, and India concentrate specialized demand for aerospace and refractory applications.
China
Steel and glass furnace rebuild cycles are accelerating phosphate-bonded inorganic binder consumption for linings exceeding 1500°C. SAMR's GB standards for building materials mandate low-emission formulations in construction-grade ceramics. The Yangtze River Delta concentrates technical ceramics manufacturing where hybrid binder qualification programs are expanding.
United States
Aerospace propulsion OEMs are qualifying high-purity organosilicon binders for single-crystal superalloy investment casting under FAA engine certification requirements. EPA hazardous air pollutant standards under MACT constrain solvent-based organic formulations, forcing water-based transitions. Greater Cincinnati and the Ohio River Valley host turbine blade casting foundries with direct auditing of binder chemistry.
Germany
ECHA's tightening REACH controls on formaldehyde-releasing phenolic resins are accelerating substitution toward silicone and bio-derived platforms. The Ludwigshafen integrated site sustains captive alumina-silicate supply chains for R&D-intensive multinationals. Bavaria's aerospace substrate manufacturers are adopting water-based colloidal silica systems to eliminate thermal oxidizer capital.
Japan
Technical ceramics producers are pioneering binder jetting systems that blend organic burnout behavior with inorganic green strength for near-net shaping. METI industrial standards support additive manufacturing qualification programs. The Nagoya-Chubu corridor concentrates precision casting operations driving acrylate and silicone-modified temporary binder adoption.
India
BIS standards alignment with international furnace lining specifications is creating entry pathways for phosphate-bonded refractory systems. The country's steel capacity expansion is specifying inorganic binders for new installations. Gujarat and Maharashtra host growing refractory manufacturing clusters where field-mixed powder binder formulations are gaining preference.
Ceramic Binders Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the ceramic binders market. Integrated multinationals with captive raw material supply chains command premium positioning in aerospace qualification programs, while regional compounders compete on formulation flexibility and local service. Three archetypes dominate: R&D-intensive integrated chemical conglomerates, specialized ceramic materials specialists, and regional toll compounders. Competitive moves concentrate on backward integration into colloidal alumina production and strategic partnerships for hybrid binder co-development.
Within the integrated chemical conglomerate tier, BASF SE and Evonik Industries AG exemplify technology-forward positioning through Ludwigshafen-scale manufacturing and high-purity organosilicon platforms respectively. DuPont de Nemours anchors North American aerospace qualification programs. These three entities represent the R&D-capable archetype capable of hybrid binder design and direct OEM specification authority.
| Leading Market Players |
|---|
| DuPont de Nemours |
| KYOEISHA CHEMICAL Co. Ltd |
| 3M Company |
| Huntsman Corporation |
| Zircar Ceramics |
| BASF SE |
| Evonik Industries AG |
| Ferro Corporation |
| Almatis GmbH |
| Others |
Value Chain & Pricing Dynamics
FAA engine certification requirements gate both supply qualification and price differentiation simultaneously, as aerospace propulsion OEMs demand direct auditing of binder chemistry and burnout residue characterization before authorizing tier-2 ceramic component suppliers into specification programs.
Pricing Analysis
Geographic price spreads widen between German and Chinese supply bases as ECHA REACH registration costs for formaldehyde-releasing phenolic resins compound European formulation premiums against SAMR-administered GB standard compliance in Asia. Three-tier pricing structure across aerospace-qualified, industrial-grade, and construction-economy levels separates specification authority from commodity spot purchasing. Cost compression in construction-grade binders intensifies because SAMR mandates low-emission formulations without corresponding price elasticity in tile and sanitary ware markets. Refractory furnace operators exhibit lowest price sensitivity given rebuild cycle criticality, while pottery artisans face acute margin pressure from raw material volatility.
Supply Chain Analysis
Inbound logistics costs from Yangtze River Delta ports to European tape casting operations fluctuate with container availability on Asia-North Europe trade lanes, compressing margins for non-integrated formulators lacking Ludwigshafen-scale captive alumina-silicate production. Supply concentrates in Germany, China, and Japan for colloidal alumina, high-purity organosilicon platforms, and binder jetting system integration respectively. Raw material dependencies rest on phosphate rock for refractory binders, synthetic polymer feedstocks for organic systems, and rare earth stabilizers for high-temperature performance grades. Single-source vulnerability permeates aerospace qualification programs where FAA certification locks in specific binder chemistries for engine component supply chains. Distribution runs through direct technical service relationships for aerospace tiers and regional toll compounders for construction materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial furnace rebuild cycles signal cyclical recovery as steel and glass producers in China accelerate phosphate-bonded refractory specifications following deferred maintenance during prior capacity overhang periods.
For Market Incumbents: Compound specification authority by deepening captive colloidal alumina production at integrated sites and accelerating hybrid binder co-development partnerships with additive manufacturing equipment OEMs. Defend against regional toll compounders by embedding computational burnout modeling capabilities that exceed legacy empirical formulation approaches. Prioritize certification investment for REACH-compliant silicone platforms before ECHA restriction roadmaps eliminate phenolic resin alternatives. For New Entrants and Emerging Players: Lead with water-based colloidal silica systems targeting German and Japanese aerospace substrate manufacturers seeking thermal oxidizer elimination without green body handling strength degradation. Target India's refractory expansion where BIS standards alignment creates entry pathways for phosphate-bonded systems in steel capacity buildout. Pursue consultative go-to-market positioning around EPA MACT compliance services for solvent-based organic binder transitions in U.S. ceramics plants. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hybrid binder R&D programs as additive manufacturing qualification demands merge organic burnout behavior with inorganic green strength in single systems. Long-term viability favors integrated chemical conglomerates with captive raw material supply chains and direct OEM specification authority. Monitor PFAS restriction harmonization timelines across U.S. state-level actions and EU REACH candidate list updates as inflection indicators for fluoropolymer binder segment viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Colloidal Alumina | BASF SE's Ludwigshafen captive supply secures qualified raw material streams for aerospace qualification programs. |
| Hybrid Binder Co-Development Partnership | Additive manufacturing OEMs in Japan demand merged organic-inorganic architectures for technical ceramics near-net shaping. |
| REACH-Compliant Silicone Platform Certification | ECHA formaldehyde restrictions eliminate phenolic resin cost advantages in European investment casting foundries. |
| Water-Based Colloidal Silica System Launch | German aerospace substrate manufacturers adopt these platforms to eliminate thermal oxidizer capital expenditure. |
| EPA MACT Compliance Service Expansion | U.S. ceramics plants face hazardous air pollutant standards forcing solvent-based organic binder transitions. |
Study Parameters
Operator-level perspectives from ceramic formulation chemists, refractory procurement managers at steel producers, aerospace propulsion OEM specification engineers, and SAMR regulatory affairs specialists anchored the qualitative base for this study. Primary interview findings triangulated against secondary validation from ECHA restriction roadmap documentation, FAA engine certification requirement circulars, SEC 10-K filings of integrated chemical conglomerates, and Chinese customs data on alumina-silicate trade flows. Bottom-up segment sizing across organic, inorganic, hybrid, and additive binder categories reconciled with top-down market envelope checks.
Sensitivity analysis tested forecast robustness across regulatory acceleration scenarios, raw material price volatility bands, and aerospace qualification timeline compression. The analytical framework modeled volume and value trajectories across the projection horizon by product type, application, end-use industry, and form factor, with additional dimensioning by regional production hub concentration. CAGRs derived from segment-level growth rate synthesis applied to base year market sizing. Industry-specific forecast inputs incorporated steel furnace rebuild cycle phasing, additive manufacturing equipment installation rates, and REACH registration cost pass-through elasticity.
Forecasts assume regulatory continuity in FAA certification requirements, ECHA REACH implementation timelines, and SAMR GB standard enforcement; material policy shifts would require re-modeling. Specific risk factors that could revise projections include premature PFAS phase-out acceleration, aerospace propulsion OEM consolidation reducing specification authority dispersion, and colloidal alumina supply disruption at integrated chemical sites. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Advanced Ceramic Additives Market
Ceramics
Asia-Pacific Activated Alumina Market
Ceramics
Europe Activated Alumina Market
Ceramics
Barium Carbonate Powder Market
Ceramics
Glazed Ceramic Tile Market
Ceramics
Global Ceramic Tube Market
Ceramics
Liquid Sodium Silicate Market
Ceramics
Ceramic Armor Materials Market
Ceramics
South Korea Ceramic Sanitaryware Market
Ceramics
Magnesia Carbon Bricks Market
Ceramics
China Ceramic Tiles Market
Ceramics
Calcite Market
Ceramics
Global Wollastonite Powder Market
Ceramics
Ceramic Proppant Market
Ceramics
Philippines Ceramic Tiles Market
Ceramics
Iran Ceramic Tiles Market