
 South Korea Ceramic Tiles Market | 2026-2036
South Korea Ceramic Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Ceramic Tiles Market Analytics
MFDS building material safety standards is repositioning compliance costs for domestic manufacturers. KCC Corporation leverages captive raw material sourcing to sustain margin stability against certification overhead. Hanyoung Ceramic Co., Ltd. anchors its position through specialized porcelain formulations for high-rise residential towers. Kukdong Ceramics Co., Ltd. competes via channel control across Gyeonggi-do distributor networks.
South Korea ceramic tiles are sintered clay-based or porcelain slabs, typically measuring 300x300 mm to 800x800 mm, fired at 1,000–1,250°C for dimensional stability and abrasion resistance, serving primarily as surfacing materials for interior and exterior built environments. Floor tiles dominate volume throughput in the residential application segment as multi-family housing complexes standardize hard-surface specifications. Porcelain tiles represent the fastest-growing product type due to superior water absorption rates below 0.5% that satisfy MFDS durability benchmarks for commercial installations. The distributor channel segment captures the deepest margin pools through project bundling for contractor end users in Seoul's reconstruction market.
Korea Institute of Ceramic Engineering and Technology (KICET) testing protocols and Korean Industrial Standards (KS) classifications shape product differentiation thresholds, while Ministry of Land, Infrastructure and Transport (MOLIT) green building certification criteria steer specification trends toward low-emission glaze formulations. Stakeholders must monitor whether KICET accelerates digital printing quality standards before committing capital to next-generation production lines.
Market Dynamics
Digital inkjet printing technology is compressing production batch sizes and accelerating design refresh cycles across South Korean manufacturing facilities, forcing capital reallocation toward flexible production systems.
Growth Catalysts
- MFDS Durability Benchmarks:Commercial building codes in Seoul now mandate water absorption rates below 0.5% for exterior cladding, pulling porcelain specifications into high-rise residential towers.
- Gyeonggi-do Urban Corridors:New town development in Hwaseong and Gwangmyeong generates sustained volume demand for standardized 600x600 mm floor tiles across multi-family housing complexes.
- Digital Decoration:Single-pass inkjet systems enable micro-batch production with sub-24-hour design turnaround, allowing contractors to match reconstruction project aesthetics without inventory risk.
Market Restraints
- Kaolin Supply Concentration:Domestic manufacturers depend on imported refined clay from specific Southeast Asian deposits, exposing margin stability to shipping route volatility.
- KICET Testing Timelines:Extended certification protocols for new glaze formulations delay product launches by four to six months, compressing effective selling seasons.
- Engineered Stone Substitution:Quartz surfacing materials capture premium kitchen and bath specifications previously held by large-format porcelain slabs.
Strategic Opportunities
- Busan Commercial Reconstruction:Aging office stock in the city's central business district requires full-surface renovation, creating demand for slip-resistant porcelain with recycled content.
- MOLIT Green Building Incentives:Low-emission glaze formulations qualify for accelerated permitting and tax credits under updated certification criteria.
- Direct Contractor Platforms:Digital procurement channels bypass traditional distributor markups for mid-size renovation projects in Seoul's satellite cities.
Industry Challenges
- Digital Print Technician Scarcity:The shift to inkjet systems outpaces vocational training programs, creating bottlenecks for quality control and color matching.
- Legacy Kiln Retrofit Costs:Converting traditional roller hearth furnaces for rapid design changeover requires capital outlays that strain mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Ceramic Tiles Market |
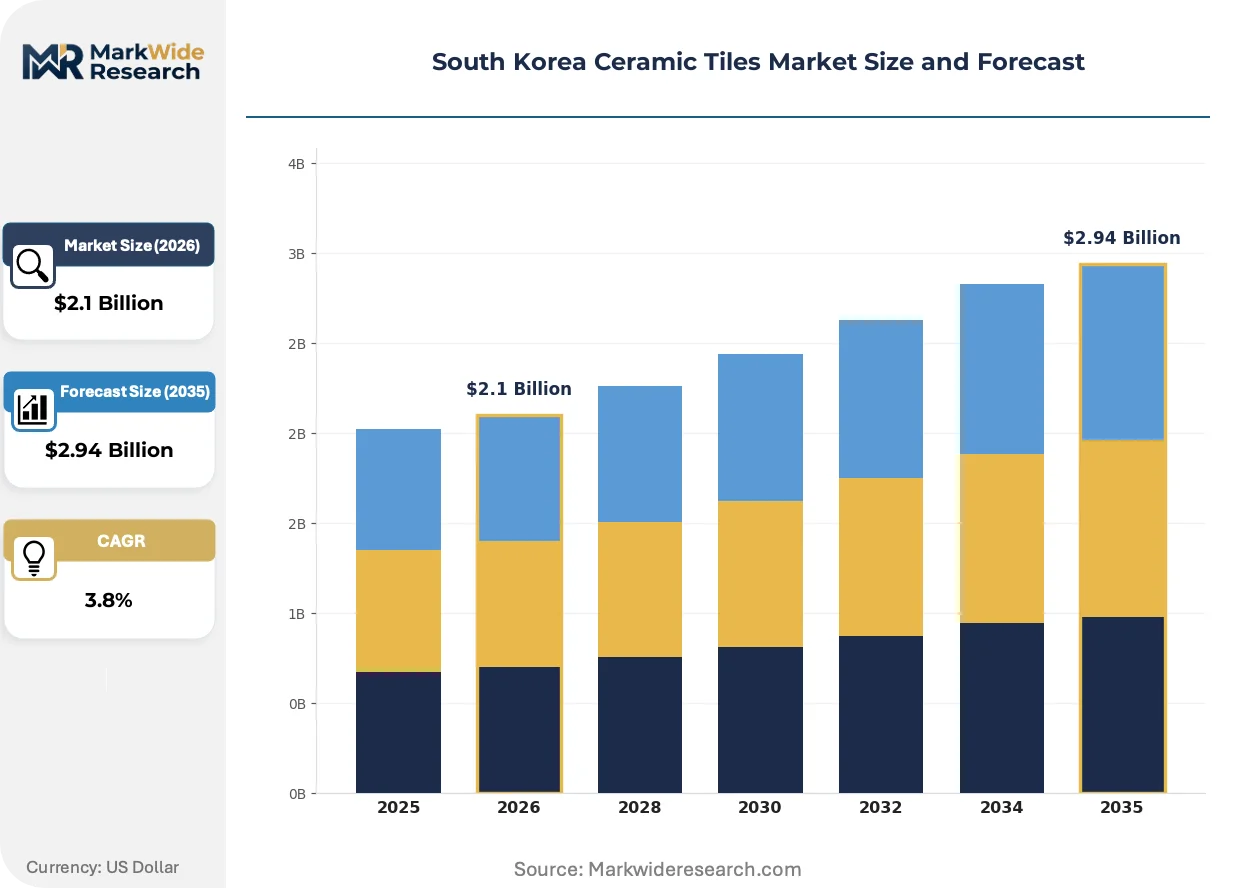
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall Tiles, Floor Tiles, Outdoor Tiles, Porcelain Tiles Application: Residential, Commercial, Industrial, Institutional Distribution Channel: Retail Stores, Online Stores, Direct Sales, Distributors End User: Homeowners, Contractors, Designers, Architects |
| Companies Covered | Hanyoung Ceramic Co., Ltd., Kukdong Ceramics Co., Ltd., KCC Corporation, Samyoung Chemical, Woongjin Ceramics, IS DONGSEO Co., Ltd., Korea Fine Ceramic Co., Ltd., Donghwa Entec, Sungil Ceramics Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Ceramic Tiles Market Evolving Landscape
Production flexibility and compliance automation are converging to reshape how South Korean manufacturers compete on speed and specification breadth rather than scale alone.
Single-pass digital inkjet decoration is integrating nano-particle glaze deposition with real-time color correction software. Boutique residential developers in Seoul's Gangnam and Seocho districts specify these systems for custom pattern matching across multi-unit projects. The technology is compressing minimum order quantities from container-load to pallet-load without unit cost penalties.
MFDS building material safety standards now incorporate volatile organic compound emission thresholds for interior-grade tiles. Manufacturers reformulating lead-free frit compositions face temporary yield losses during process stabilization. Commercial specification teams in Busan and Incheon now require third-party emission test reports before bid qualification.
Project bundling through contractor consortia is displacing single-product distributor relationships. Mid-size renovation firms in Gyeonggi-do now aggregate flooring, wall, and exterior cladding purchases to extract volume discounts previously reserved for national developers. This consolidation concentrates negotiation leverage with five to seven purchasing cooperatives covering the Seoul metropolitan area.
South Korea Ceramic Tiles Market Segmentation
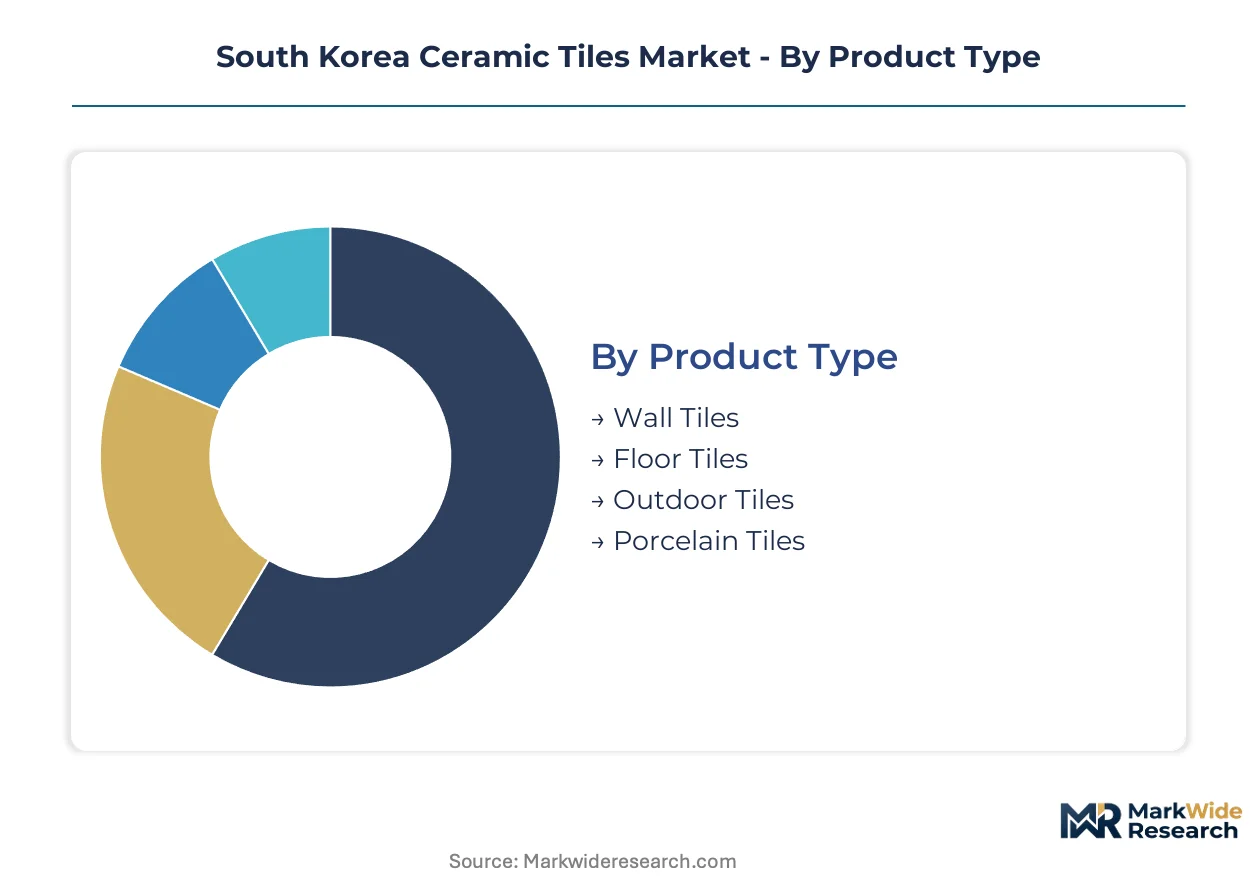
Segmentation in the South Korea ceramic tiles market reveals how procurement patterns split between standardized bulk contracts and specification-driven custom orders. Each dimension exposes different margin pools and compliance burdens that manufacturers must navigate.
Product Type:
Standardization dominates high-volume segments while digital printing enables customization in premium tiers.
- Floor Tiles:Sintered clay slabs fired at 1,000–1,200°C with abrasion resistance ratings for heavy foot traffic. Demand concentrates in Gyeonggi-do's multi-family housing complexes where developers specify standardized 600x600 mm formats for cost efficiency.
- Porcelain Tiles:Ultra-low water absorption below 0.5% through higher firing temperatures and refined kaolin compositions. Commercial towers in Seoul's reconstruction zones specify these for MFDS compliance on exterior cladding durability benchmarks.
- Wall Tiles:Lighter body compositions with glazed surfaces for moisture resistance in interior vertical applications.
- Outdoor Tiles:Frost-resistant formulations with textured surfaces for slip resistance in Busan's commercial reconstruction projects.
Leading the category by volume: Floor Tiles. Growing fastest: Porcelain Tiles.
Application:
Volume scales inversely with specification complexity across end-use environments.
- Residential:Multi-family housing in Seoul's satellite cities drives standardized procurement through developer bulk contracts.
- Commercial:Office and retail reconstruction in Busan generates demand for slip-resistant porcelain with recycled content and accelerated MFDS certification.
- Industrial:Manufacturing facilities require chemical-resistant heavy-duty tiles with minimal aesthetic variation.
- Institutional:Schools and hospitals prioritize low-emission glazes qualifying for MOLIT green building incentives.
Residential commands absolute volume. Commercial delivers the steepest expansion trajectory.
Distribution Channel:
Channel selection determines margin capture versus market access trade-offs.
- Distributors:Project bundling through Gyeonggi-do networks captures the deepest margin pools for contractor end users in Seoul's reconstruction market.
- Direct Sales:Digital procurement platforms bypass traditional markups for mid-size renovation projects in satellite cities.
- Retail Stores:Homeowner-driven replacement demand with higher per-unit margins but fragmented order sizes.
- Online Stores:Emerging channel for sample ordering and small-batch custom digital prints.
Distributors dominate project volume. Direct Sales channels are gaining share fastest.
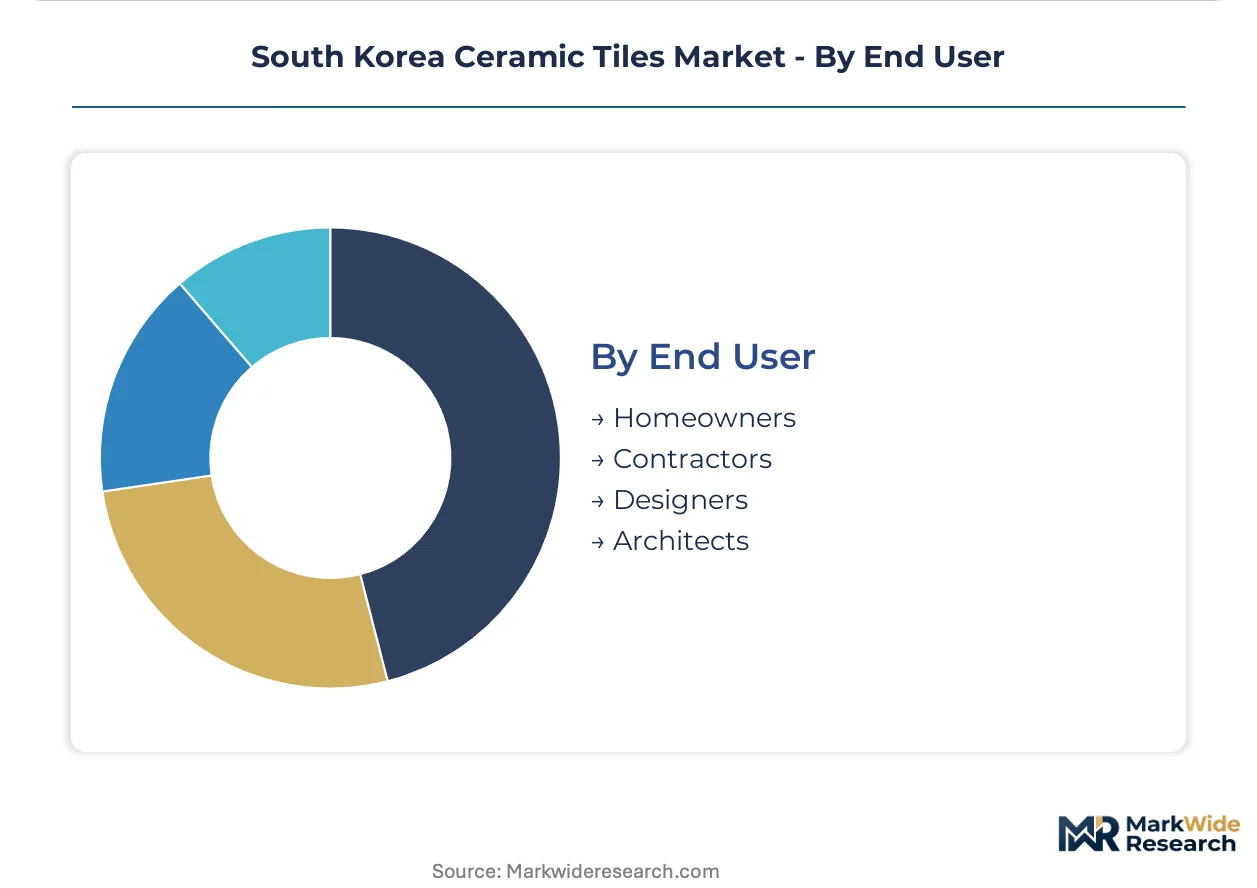
End User:
Technical sophistication and procurement scale separate user categories.
- Contractors:Aggregate flooring, wall, and exterior cladding purchases through purchasing cooperatives covering the Seoul metropolitan area.
- Architects:Specify custom digital inkjet patterns for boutique residential developments in Gangnam and Seocho districts.
- Homeowners:Replacement and renovation demand with sensitivity to visible design variation.
- Designers:Bridge aesthetic specification with technical compliance for emission and durability standards.
Contractors drive aggregate volume. Architects command the highest value per project.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gyeonggi-do's free economic zones and Sejong City's special development districts concentrate tile procurement for public housing and commercial reconstruction projects.
Seoul Capital Area
Multi-family housing complexes in Gwangmyeong and Hwaseong generate standardized demand for 600x600 mm floor tiles. MFDS building material certifications now mandate water absorption below 0.5% for exterior applications in high-rise towers. Gangnam and Seocho districts drive premium porcelain specifications for boutique residential developments.
Busan-Ulsan
Aging office stock in Busan's central business district requires slip-resistant porcelain with recycled content for full-surface renovation. MOLIT green building certification criteria steer procurement toward low-emission glaze formulations. The city's commercial reconstruction zones concentrate contractor purchasing cooperatives aggregating flooring and cladding bundles.
Daegu-Gyeongbuk
Industrial facility modernization creates demand for chemical-resistant heavy-duty tiles with minimal aesthetic variation. Regional distributors maintain inventory pools for contractor consortia covering the southeastern manufacturing belt. KICET testing protocols shape local manufacturer compliance investments for institutional specifications.
Daejeon-Sejong
Government complex expansion and administrative city construction generate institutional demand for low-emission interior-grade tiles. Public procurement frameworks prioritize MFDS-certified suppliers with established emission test documentation. The Sejong special development district channels volume through designated contractor panels.
Gwangju-Honam
Smaller-scale residential renovation projects in the southwestern region rely on distributor networks for mid-tier product access. Digital procurement platforms are gaining traction among mid-size renovation firms bypassing traditional markups. Regional manufacturers compete on batch flexibility for custom digital inkjet patterns.
South Korea Ceramic Tiles Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: integrated chemical-materials conglomerates with captive raw material sourcing, specialized porcelain formulators serving high-rise residential specifications, and regional distributors controlling Gyeonggi-do channel access. Dominant competitive moves include backward integration into refined clay supply chains and rapid kiln retrofitting for digital inkjet flexibility.
Within the conglomerate tier, KCC Corporation anchors positions through upstream control over raw material inputs. Hanyoung Ceramic Co., Ltd. and Kukdong Ceramics Co., Ltd. occupy specialist positions, with the former exemplifying porcelain formulation expertise and the latter representing channel-centric competitive strategies. These three entities collectively illustrate how scale, specialization, and distribution control segment competitive terrain.
| Leading Market Players |
|---|
| Hanyoung Ceramic Co., Ltd. |
| Kukdong Ceramics Co., Ltd. |
| KCC Corporation |
| Samyoung Chemical |
| Woongjin Ceramics |
| IS DONGSEO Co., Ltd. |
| Korea Fine Ceramic Co., Ltd. |
| Donghwa Entec |
| Sungil Ceramics Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Kaolin import costs from Southeast Asian deposits cascade through three pricing tiers before reaching Seoul metropolitan contractors. Refined clay procurement absorbs shipping route volatility, compressing margins for mid-tier manufacturers while integrated conglomerates sustain stability through captive sourcing.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent separate spot inventory transactions from contract-scheduled deliveries in Gyeonggi-do distributor networks. Pricing stratifies across MFDS-certified premium grades, standard KS-compliant formats, and economy-tier unglazed products. Cost compression in the economy tier intensifies because Indonesian kaolin suppliers are consolidating export quotas. National developer consortia exhibit lowest price sensitivity, while mid-size renovation firms in satellite cities negotiate aggressively on pallet-load minimums.
Supply Chain Analysis
Freight cost spikes on Southeast Asian shipping lanes are forcing inventory pre-positioning at Busan port warehousing facilities. Raw material sourcing draws from Indonesian refined kaolin deposits, Vietnamese clay processors, and domestic limestone quarries in Gangwon-do. Single-source vulnerability concentrates in the Surabaya-Jakarta shipping corridor where container availability fluctuates seasonally. Distribution runs through Gyeonggi-do contractor purchasing cooperatives that aggregate flooring and cladding bundles for Seoul reconstruction projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital inkjet printing technology is displacing traditional roller hearth production systems, compressing design refresh cycles from months to hours and rewarding capital flexibility over scale.
For Market Incumbents: Cement market position through backward integration into refined clay supply chains and rapid kiln retrofitting for micro-batch flexibility. Engineered stone substitution in premium kitchen specifications threatens porcelain slab margins. MFDS emission certification investments create defensive moats against mid-tier competitors facing yield losses during lead-free frit reformulation.
For New Entrants and Emerging Players: Boutique residential developers in Gangnam and Seocho districts represent the most penetrable buyer archetype for custom digital pattern matching. White-space targets include direct contractor platforms bypassing traditional distributor markups in Seoul satellite cities and slip-resistant recycled-content porcelain for Busan commercial reconstruction. A sample-to-installation digital workflow with sub-72-hour turnaround anchors the go-to-market angle.
For Investors and Strategic Acquirers: KICET acceleration of digital printing quality standards is the leading indicator that capital allocation toward next-generation production lines will separate winners from stranded assets. The five-to-ten year viability window favors acquisition targets with existing MFDS emission certifications and flexible kiln infrastructure over scale-heavy legacy operators. Monitor whether vocational training programs for inkjet technician skills expand sufficiently to resolve quality control bottlenecks.
| Strategic Initiative | Industry Significance |
|---|---|
| Kiln Retrofit for Digital Flexibility | Enables micro-batch production without unit cost penalties for Seoul boutique developers. |
| Backward Integration into Kaolin Supply | Insulates margin stability from Indonesian shipping route volatility affecting mid-tier competitors. |
| MFDS Emission Certification Investment | Qualifies products for MOLIT green building tax credits accelerating permitting timelines. |
| Direct Contractor Platform Launch | Bypasses Gyeonggi-do distributor markups capturing margin pools in mid-size renovation segments. |
| Vocational Training Partnership | Addresses digital print technician scarcity constraining quality control for inkjet color matching. |
Research Methodology
Document review covered KICET testing protocol documentation, MOLIT green building certification criteria, and MFDS building material safety standards, complemented by interviews with plant managers at porcelain manufacturing facilities, procurement leads at Gyeonggi-do distributor networks, technical R&D directors specializing in glaze formulation, and contractor purchasing cooperative coordinators across the Seoul metropolitan area. Secondary validation drew from Korea Industrial Standards classifications, customs import records for Southeast Asian kaolin, and SEC filings of integrated chemical-materials conglomerates. Bottom-up volume estimates from facility utilization rates were triangulated against top-down construction permit data.
Historical production capacity trends were cross-referenced against panel input from industry stakeholders to construct the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application environment, distribution channel structure, and end-user procurement sophistication. CAGRs were derived from regression analysis of construction activity indices and specification trend trajectories. Forecast inputs incorporated digital inkjet adoption curves and MFDS certification timeline delays.
Revisions become necessary when KICET accelerates quality standards, kaolin export quotas tighten, or engineered stone substitution rates exceed baseline assumptions. Forecasts reflect documented assumptions about technology transition speeds and regulatory enforcement intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Yttria-Stabilized Zirconia (YSZ) Market
Ceramics
Heat-Resistant Ceramic Tableware Market
Ceramics
Vaterite Market
Ceramics
Stoneware Market
Ceramics
Tetramethyl Orthosilicate Market
Ceramics
Zirconia Ceramics Market
Ceramics
Boiler Refractory Material Market
Ceramics
Activated Alumina Market
Ceramics
Iran Ceramic Tiles Market
Ceramics
Calcium Silicate Boards Market
Ceramics
Ceramics Packaging Market
Ceramics
Ceramic Additives Market
Ceramics
Global Alumina Market
Ceramics
Fire Clay Market
Ceramics
ME K-Feldspar Market
Ceramics
Refractories Market