
 High Temperature Plastic Market | 2026-2036
High Temperature Plastic Market Size, Share, and Industry Trends Forecast 2026-2036
High Temperature Plastic Market Analysis
The gap between premium high-performance grades and commodity-engineered polymers is expanding as aerospace and automotive electrification demand specialized thermal and chemical resistance. Solvay S.A. leverages its integrated fluoropolymer and polyimide chains to serve aircraft OEMs with certified material lots. Victrex PLC anchors the polyetheretherketone segment through captive polymerization capacity and medical-grade qualifications. BASF SE competes across polyphenylene sulfide and polyimide formulations for industrial machinery and electronics cooling applications.
High temperature plastics are thermally stable polymer formulations, typically with continuous service temperatures exceeding 150 degrees Celsius, produced through step-growth polymerization or electrophilic substitution processes to yield aromatic backbone structures for load-bearing components in aggressive thermal and chemical environments. Polyetheretherketone leads in revenue contribution due to its bone-like modulus and sterilization compatibility, while fluoropolymer captures margin pools in semiconductor fabrication and wire insulation where purity thresholds are extreme. Polyphenylene sulfide grows fastest in automotive underhood applications as OEMs replace metal with injection-molded housings to cut weight.
EPA emissions standards and REACH substance restrictions in Europe constrain halogenated additive use, compelling reformulation toward inherently flame-retardant aromatic polymers. FDA biocompatibility requirements and FAA flammability protocols shape qualification timelines and barrier costs for new resin entrants. Stakeholders must monitor regulatory divergence between EU F-Gas phase-downs and US IRA clean-energy procurement rules, as these will redirect investment toward bio-based polyimide precursors and recycled-content polyphenylene sulfide streams.
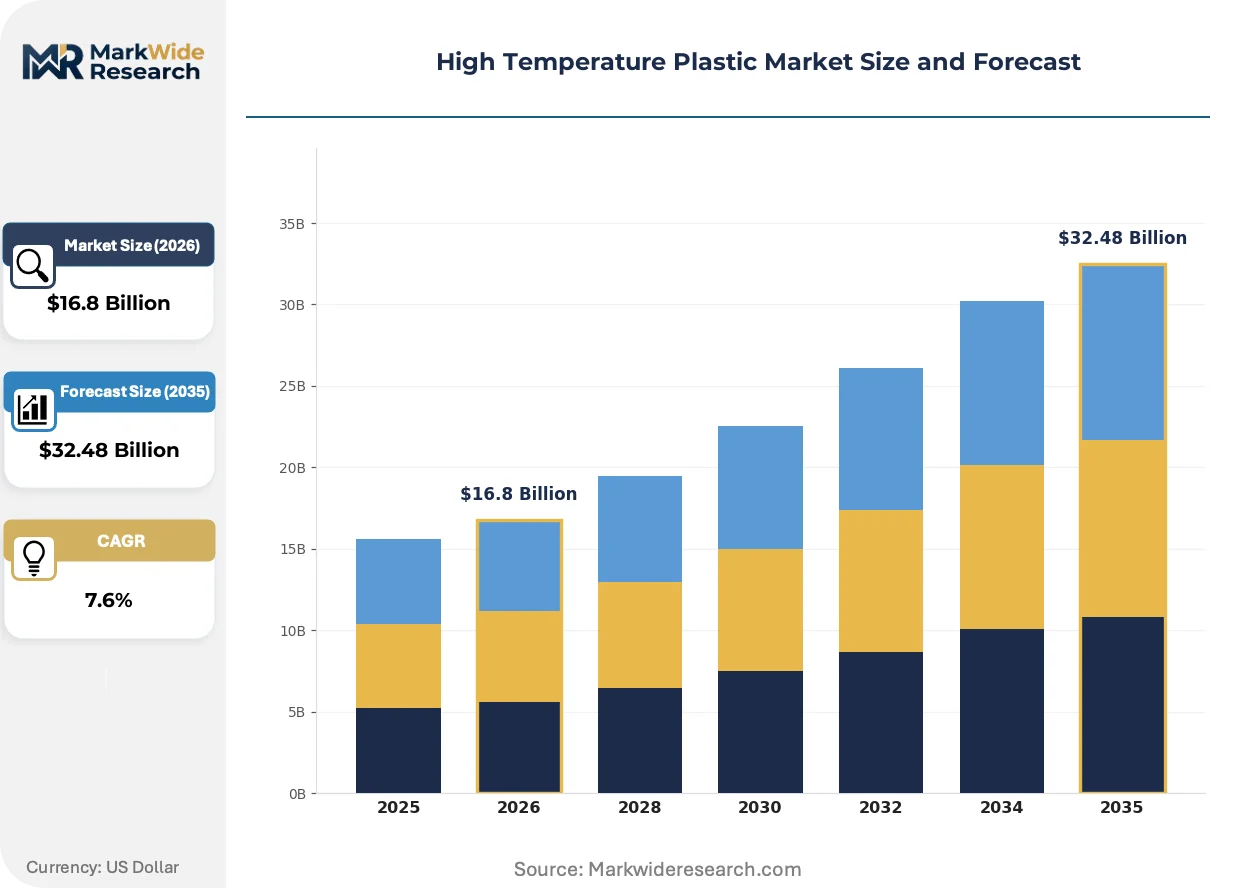
Market Dynamics
Automotive electrification is compressing thermal management requirements into tighter spatial envelopes, forcing resin suppliers to certify aromatic polymers for continuous service above 180°C while maintaining dielectric stability. This thermal-density imperative now governs formulation roadmaps and qualification investments across the value chain.
Growth Catalysts
- EPA emissions standards:Underhood component downsizing mandates in the United States are accelerating metal-to-polymer substitution in charge air coolers and exhaust gas recirculation housings.
- Semiconductor fabrication:Fluoropolymer demand for wafer handling equipment and cleanroom infrastructure is expanding as foundries in Taiwan and South Korea add advanced node capacity.
- Battery thermal barriers:Electric vehicle OEMs are specifying polyimide films and PPS composites for cell-to-cell isolation and module encapsulation to contain thermal runaway propagation.
Market Restraints
- Monomer supply concentration:Bisphenol A and hydroquinone feedstocks for PEEK and PPS polymerization concentrate among Chinese and Middle Eastern petrochemical complexes, exposing processors to freight-driven volatility.
- REACH authorization timelines:ECHA substance evaluation delays for novel aromatic monomers extend qualification cycles by 18-24 months, freezing formulation investments.
- High-performance metal alloys:Titanium aluminide and nickel superalloys retain cost-performance advantages above 300°C in aerospace turbine applications, capping polymer penetration.
Strategic Opportunities
- India automotive manufacturing:PLI scheme incentives for electric vehicle component localization are creating first-mover windows for heat-resistant polymer compounders establishing technical centers near Chennai and Pune.
- EU F-Gas phase-down:Refrigeration system OEMs are redesigning compressor housings and valve plates around PPS and PA46 to eliminate hydrofluorocarbon working fluids and their associated seals.
- Medical device sterilization:Gamma and autoclave-resistant PEEK grades for surgical instrument handles and endoscope components are penetrating ambulatory surgery centers replacing metal instruments.
Industry Challenges
- Polymerization technician scarcity:Step-growth reactor operation and molecular weight control expertise concentrates among retiring cohorts at established European and Japanese resin houses, constraining capacity expansion.
- FAA flammability certification:Aircraft interior applications require 16g seat and cargo liner testing protocols that extend development timelines and demand dedicated burn-test facilities.
- Legacy injection molding infrastructure:Tooling designed for commodity nylons and polyesters requires barrel, screw, and hot-runner modifications to process high-viscosity aromatic polymers without degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Temperature Plastic Market |
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $32.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyetheretherketone, Polyimide, Polyphenylene Sulfide, Fluoropolymer Application: Aerospace, Automotive Components, Electronics, Industrial Machinery End User: Manufacturers, OEMs, Engineering Firms, Contractors Distribution Channel: Online Retail, Distributors, Wholesalers, Direct Sales |
| Companies Covered | Solvay S.A., Victrex PLC, BASF SE, DIC Corporation, Arkema S.A., Celanese Corporation, DuPont de Nemours, Evonik Industries AG, SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Temperature Plastic Market Emerging Trajectories
Formulation science is pivoting from incremental thermal ceiling improvements toward multifunctional performance bundles that combine flame retardance, electrical insulation, and chemical resistance in single resin platforms. This convergence is compressing the traditional trade-off space between property sets.
Carbon-fiber-reinforced PEEK composites are absorbing structural loads in commercial aircraft primary brackets and satellite bus frames, displacing aluminum and thermoset alternatives. Boeing and Airbus procurement teams are qualifying these grades for A350 and 787 successor programs. The material is absorbing certification momentum that previously favored metal solutions, forcing tier suppliers to retool autoclave and press capacity.
REACH restrictions on per- and polyfluoroalkyl substances are compelling fluoropolymer processors to validate fluorine-free alternatives for food-contact and medical tubing. ECHA's 2023 PFAS restriction proposal has triggered reformulation investments at compounders serving European dairy equipment and pharmaceutical fluid handling. Industrial machinery OEMs in Germany are piloting PEEK and PPS-lined pumps and valves to maintain chemical resistance without fluorinated polymer barriers.
Consolidated procurement by automotive Tier 1s is compressing supplier bases and demanding resin suppliers provide compounded grades rather than virgin polymer. Bosch, Continental, and Denso are reducing their approved material lists and requiring compounders to hold safety stock and provide VMI programs. This concentration is most visible in Germany and Japan, where powertrain electrification has synchronized thermal management component sourcing decisions across hybrid and battery-electric platforms.
High Temperature Plastic Market Segmentation
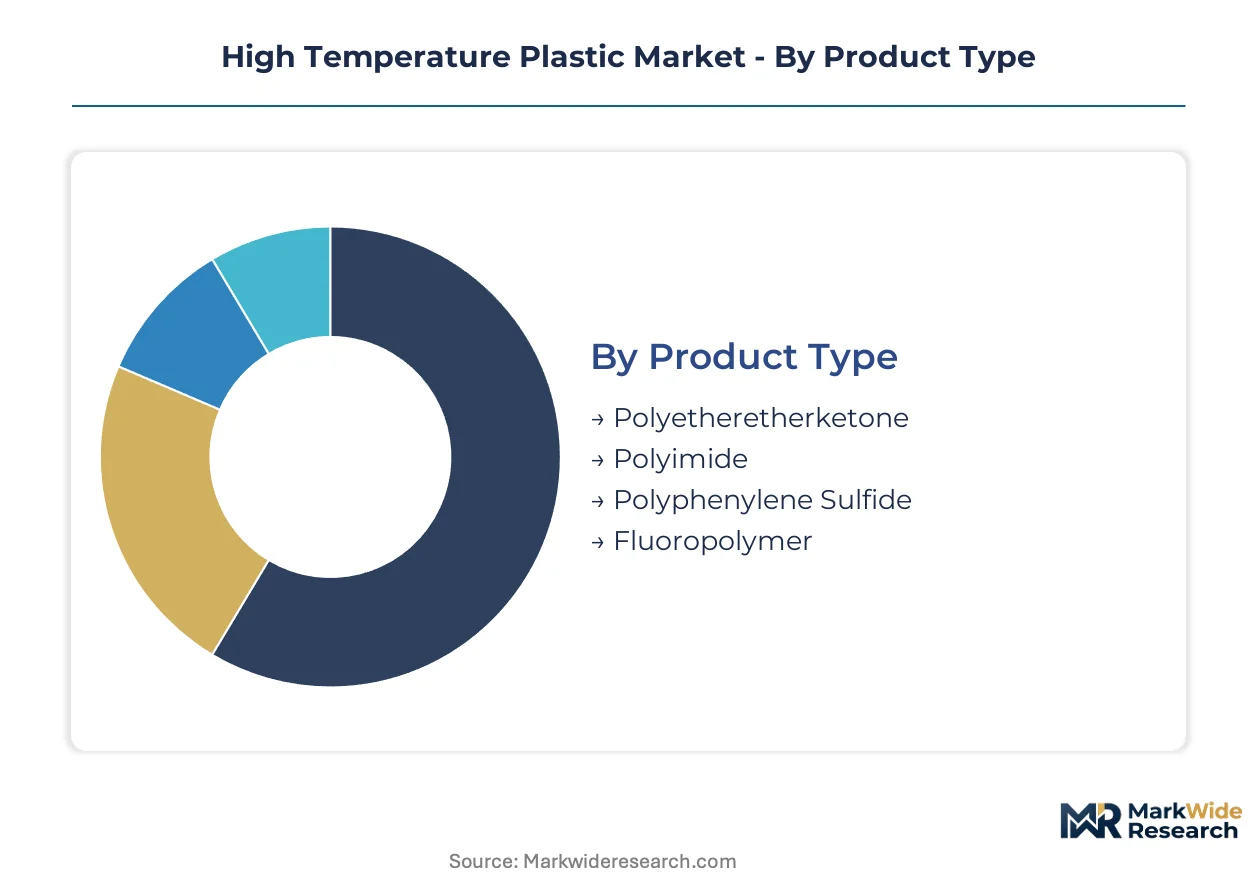
High temperature plastics fragment across thermal performance thresholds, regulatory certification requirements, and processing method compatibility. Each segment carries distinct qualification barriers and margin structures that reshape supplier positioning.
Product Type:
Customization intensity spans from commodity-competitive fluoropolymer grades to application-specific polyimide formulations requiring dedicated polymerization campaigns.
- Polyetheretherketone:Semi-crystalline aromatic polymer with bone-matching modulus and gamma sterilization compatibility. Aircraft OEMs in Germany and the United States specify carbon-fiber-reinforced grades for primary structural brackets as Boeing and Airbus expand thermoplastic composite airframes.
- Polyimide:Amorphous imide-ring backbone delivering the highest continuous service temperatures among melt-processable polymers. Semiconductor foundries in Taiwan and South Korea drive consumption for wafer handling films and probe card substrates where dimensional stability exceeds 300°C.
- Polyphenylene Sulfide:Semi-crystalline thioether polymer with inherent flame retardance and chemical resistance. Automotive underhood applications in China and Germany absorb volume as charge air cooler housings convert from aluminum.
- Fluoropolymer:Fully fluorinated carbon backbone providing extreme chemical inertness and dielectric performance. Wire insulation and cleanroom infrastructure in the United States and Japan concentrate demand despite REACH-driven reformulation pressures.
Leading the category by volume: Polyetheretherketone. Growing fastest: Polyphenylene Sulfide.
Application:
Application selection maps directly to thermal envelope requirements and regulatory exposure severity, with aerospace and automotive commanding the most stringent qualification protocols.
- Aerospace:Structural brackets, thermal shields, and interior components requiring FAA flammability certification and 16g seat testing. Airbus and Boeing procurement teams in Toulouse and Seattle drive specification tightening for PEEK composite primary structures.
- Automotive Components:Underhood thermal management, battery module housings, and electric motor insulation. OEMs in Germany and China specify PPS and PA46 for charge air systems as EPA emissions standards compress packaging space.
- Electronics:Connector housings, circuit substrates, and semiconductor fabrication equipment. Foundry expansion in Taiwan and South Korea pulls fluoropolymer and polyimide grades for cleanroom purity thresholds.
- Industrial Machinery:Pump housings, valve components, and bearing surfaces in chemical processing. German machinery OEMs pilot PEEK-lined equipment to eliminate PFAS barriers under ECHA restrictions.
Aerospace commands premium pricing through certification barriers. Electronics expands most quickly on semiconductor capital expenditure cycles.
End User:
End user type determines technical service intensity, with engineering firms demanding formulation support and OEMs consolidating approved material lists.
- Manufacturers:Compounders and converters purchasing virgin resin for compounding or direct molding. Tier 1 automotive suppliers in Germany and Japan reduce approved vendor lists and require VMI programs.
- OEMs:Original equipment manufacturers specifying certified material lots for internal production or supplier mandates. Aircraft OEMs in Seattle and Toulouse audit polymerization batch records for traceability.
- Engineering Firms:Design consultancies selecting materials for client projects and qualification support. Firms in Munich and Detroit specify PEEK for medical device and automotive applications.
- Contractors:Installation and maintenance operations purchasing finished components. Industrial contractors in the US Gulf Coast specify fluoropolymer-lined piping for chemical resistance.
OEMs dominate procurement volume. Engineering firms gain share fastest on design-in complexity.
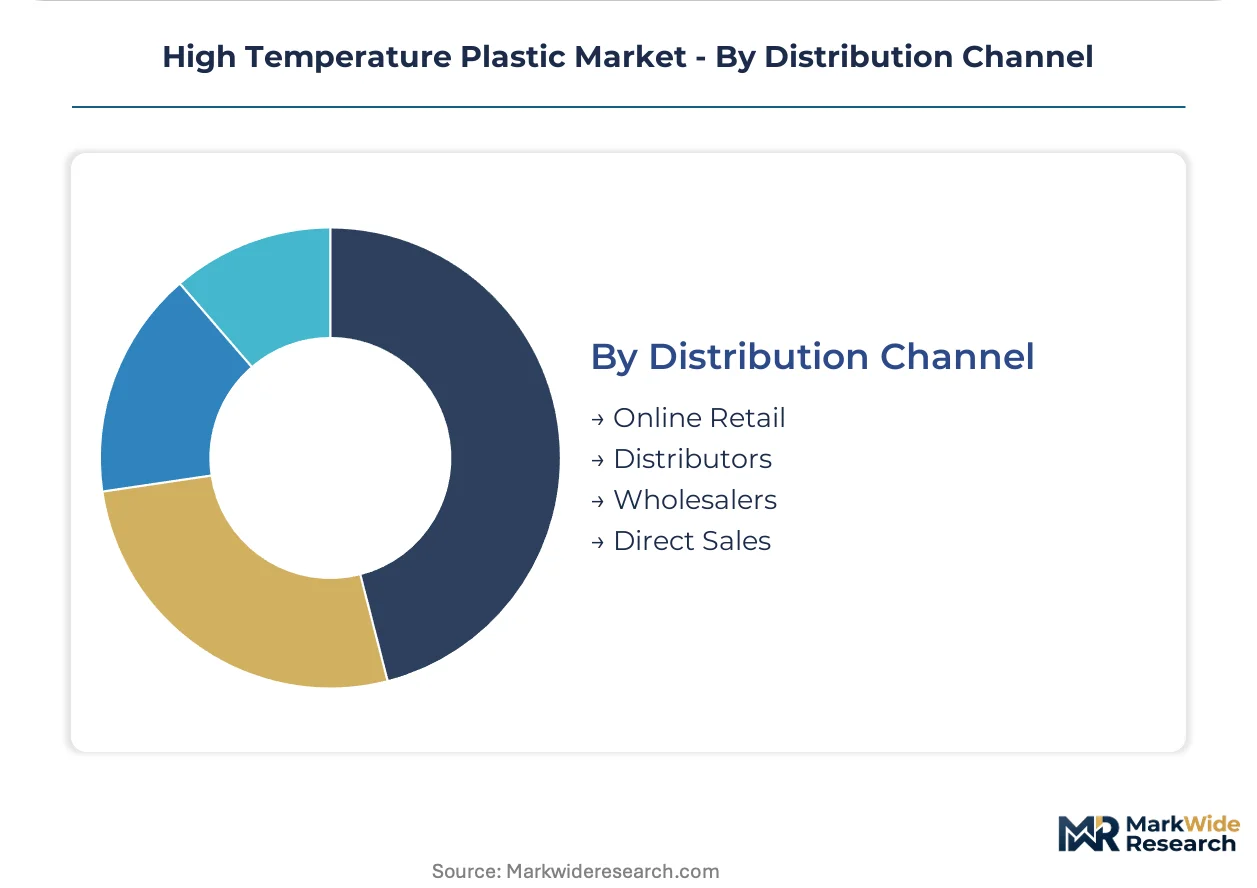
Distribution Channel:
Channel selection reflects order fragmentation, technical support requirements, and geographic coverage needs across regional manufacturing clusters.
- Distributors:Regional stocking points providing technical service and just-in-time delivery. Avient and PolyOne networks in Germany and the United States hold compounded grades for automotive Tier 1s.
- Direct Sales:Virgin polymer supplied directly from resin houses to large compounders or OEMs. Solvay and Victrex sell PEEK and polyimide direct to aerospace manufacturers in Toulouse and Seattle.
- Online Retail:E-commerce platforms serving prototype quantities and small-lot researchers. Specialized resin distributors in China and the United States list standard grades for 3D printing filament.
- Wholesalers:Bulk handlers moving standard grades to secondary converters. Regional plastics wholesalers in India stock PPS for automotive component suppliers near Chennai.
Distributors capture the largest volume share. Direct sales expands fastest on OEM consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors automotive demand for polyphenylene sulfide charge air coolers as German OEMs compress underhood packaging to meet emissions targets. The city's supplier ecosystem draws compounders from across Europe seeking proximity to Bosch and Continental procurement teams.
United States
EPA emissions standards drive metal-to-polymer substitution in exhaust gas recirculation housings. FAA flammability protocols in Washington govern aircraft interior qualification timelines. Seattle-Tacoma aerospace clusters specify carbon-fiber-reinforced PEEK for 787 successor programs.
Germany
REACH substance restrictions accelerate reformulation away from halogenated additives toward inherently flame-retardant aromatic polymers. ECHA authorization delays for novel monomers extend qualification cycles. Munich engineering firms specify PEEK for medical device sterilization compatibility.
China
Automotive electrification concentrates thermal management demand in Shanghai and Guangzhou battery module production. Dual carbon goals redirect investment toward recycled-content polymer streams. Yangtze River Delta foundries absorb PPS volumes for electric motor insulation.
Japan
METI industrial standards shape polyimide qualification for semiconductor wafer handling equipment. Tokyo-Osaka machinery OEMs pilot PEEK-lined pumps to eliminate PFAS barriers under ECHA-aligned supply chain pressures. Nagoya automotive suppliers consolidate approved material lists.
India
PLI scheme incentives for electric vehicle component localization create first-mover windows for heat-resistant polymer compounders. Chennai and Pune technical centers serve Bosch and Denso procurement consolidation. BIS standards adoption accelerates qualification for export markets.
High Temperature Plastic Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification-grade and application-specialization dimensions. The market structure consolidates around resin houses with captive polymerization capacity and compounders serving consolidated automotive Tier 1 procurement. Three archetypes dominate: integrated resin producers with aerospace qualifications, regional compounders holding VMI programs, and specialized medical-grade processors. Capacity expansion and strategic partnerships represent the dominant competitive vectors as OEMs reduce approved vendor lists.
Among European-integrated resin houses, Solvay S.A. and Victrex PLC occupy positions exemplifying the premium-certification archetype, while BASF SE sits within the diversified industrial formulation tier. These companies represent the competitive anchors around which qualification timelines and batch-traceability standards consolidate, with direct sales channels to Toulouse and Seattle aerospace clusters reinforcing their structural positioning.
| Leading Market Players |
|---|
| Solvay S.A. |
| Victrex PLC |
| BASF SE |
| DIC Corporation |
| Arkema S.A. |
| Celanese Corporation |
| DuPont de Nemours |
| Evonik Industries AG |
| SABIC |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap resin houses in Germany and Japan anchor supply discipline through captive polymerization capacity, converting feedstock volatility into premium pricing power for certified aerospace lots. This ownership structure reinforces long-term offtake contracts with Boeing and Airbus procurement teams while insulating margin pools from spot-market bisphenol A fluctuations.
Pricing Analysis
Yield-based pricing anchors the market, with resin suppliers charging premiums tied to aircraft OEM uptime guarantees and semiconductor foundry throughput rates. Three-tier pricing structure across aerospace-certified, industrial-grade, and prototype-research tiers separates batch-traceable PEEK lots from standard polyphenylene sulfide compounds. Cost compression in industrial-grade fluoropolymers is intensifying because REACH-driven reformulation investments are spreading fixed compliance costs across smaller volumes. Automotive Tier 1s exhibit highest price sensitivity due to consolidated procurement mandates, while medical device OEMs absorb premiums for gamma-sterilization compatibility.
Supply Chain Analysis
Freight costs from Chinese and Middle Eastern petrochemical complexes to European compounding facilities are amplifying margin pressure on PEEK and PPS processors. Bisphenol A, hydroquinone, and difluorobenzophenone feedstocks concentrate among Yangtze River Delta and Gulf Coast producers, exposing resin houses to ocean freight volatility and tariff exposure on aromatic monomer imports. Distribution runs through authorized distributor networks holding safety stock for automotive VMI programs rather than spot-market wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Step-growth reactor capacity scarcity among retiring European and Japanese technician cohorts is propping pricing for qualified polymerization batches. This bottleneck favors incumbents with captive technical training pipelines.
For Market Incumbents: To counter emerging compounder competition from India and Southeast Asia, Solvay and Victrex should deepen backward integration into difluorobenzophenone precursors while expanding carbon-fiber PEEK autoclave capacity near Seattle-Tacoma aerospace clusters. Certification investment in FAA 16g flammability protocols for next-generation aircraft interiors remains the critical defensive lever. For New Entrants and Emerging Players: Bio-based polyimide precursor technology offers entry traction into EU F-Gas phase-down compliance markets where incumbents face stranded fluoropolymer assets. Target battery thermal barrier applications in Chennai and Pune automotive corridors, leveraging PLI scheme localization requirements. Go-to-market positioning should emphasize recycled-content PPS streams for Chinese dual carbon procurement mandates. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional compounders with VMI relationships to Bosch and Continental in Germany, where automotive electrification is synchronizing thermal management sourcing decisions. Long-term viability hinges on five-to-ten year aerospace qualification momentum for thermoplastic composites displacing aluminum primary structures. Watch for ECHA authorization delays on novel aromatic monomers as inflection signals for incumbent pricing power restoration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Precursors | Captive supply of difluorobenzophenone insulates Solvay and Victrex from Chinese freight volatility. |
| Carbon-Fiber PEEK Autoclave Capacity Expansion | Seattle-Tacoma proximity captures Boeing 787 successor program qualification timelines. |
| Bio-Based Polyimide Precursor Development | EU F-Gas phase-down compliance opens substitution windows for fluorine-free alternatives. |
| Recycled-Content PPS Stream Certification | Chinese dual carbon procurement rules redirect automotive module housing specifications. |
| Technical Training Pipeline Investment | Step-growth reactor expertise scarcity among retiring cohorts creates captive talent moats. |
Methodological Framework
SEC 10-K filings, customs and trade data from Germany and China, and ECHA substance registration databases formed the secondary backbone for resin production and feedstock flow analysis. Primary interviews with polymerization plant managers at European resin houses, procurement leads at automotive Tier 1 suppliers in Stuttgart and Nagoya, and technical R&D directors at semiconductor foundries in Taiwan validated batch-traceability standards and qualification timeline assumptions. Bottom-up modeling of polymerization capacity by grade tier combined with top-down triangulation against aerospace and automotive production forecasts.
Bottom-up volume modeling segmented by product type, application thermal envelope, and regional regulatory cluster anchored the analytical lens, cross-checked against top-down macro indicators. The forecast framework tracked polyetheretherketone, polyimide, polyphenylene sulfide, and fluoropolymer segments across aerospace, automotive, electronics, and industrial machinery end uses. CAGRs were derived from elasticity-adjusted demand curves incorporating EPA emissions standards, REACH authorization timelines, and semiconductor capital expenditure cycles.
Several conditions sit outside the modeled scope, including sudden ECHA PFAS restriction enforcement, FAA flammability protocol revisions, and geopolitical disruption to Chinese bisphenol A supply. Forecasts reflect assumptions about technician training pipeline replenishment and automotive electrification penetration rates. Stakeholders should weight assumptions against their own operating context and polymerization batch qualification backlogs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
High-Value Chemicals
Ammonium Metavanadate Market
High-Value Chemicals
Hydroxyethyl Urea Market
High-Value Chemicals
High-Purity Boehmite Market
High-Value Chemicals
Global High Potency Apis /HPAPI Market
High-Value Chemicals
High Purity Lignin Market
High-Value Chemicals
High Purity Aluminum Hydroxide Market
High-Value Chemicals
Global Hyaluronidase Market
High-Value Chemicals
P-Hydroxybenzoates (PHB) Market
High-Value Chemicals
High Purity Benzenethiol Market
High-Value Chemicals
High Molecular Ammonium Polyphosphate Market
High-Value Chemicals
Potassium Hydroxide Market
High-Value Chemicals
Barium Hydroxide Monohydrate Market
High-Value Chemicals
Phenanthroline Monohydrate Market
High-Value Chemicals
Ultra-High Purity Materials Market
High-Value Chemicals
High Performance Fluoropolymers Market
High-Value Chemicals
High Performance Mercury Sorbent Market