
 Electromagnetic and Radio Frequency Interference Coating for Electric Vehicles Market | 2026-2036
Electromagnetic and Radio Frequency Interference Coating for Electric Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Electromagnetic and Radio Frequency Interference Coating for Electric Vehicles Market Intelligence
Graphene-enhanced formulations is repositioning cost-performance tradeoffs across the EMI coating stack. Parker Hannifin leverages its fluid systems expertise to integrate conductive coatings into thermal management assemblies. Henkel AG anchors its position through adhesive-conductive hybrid chemistries that bond and shield simultaneously. DuPont (Laird Performance Materials) specializes in multi-layer laminate structures that absorb broadband interference across EV frequency ranges.
Electromagnetic and radio frequency interference coating for electric vehicles comprises thin-film or spray-applied barrier materials—typically silver-, nickel-, or carbon-based composites with thicknesses from 25 to 200 microns—that attenuate electromagnetic emissions from 30 MHz to 6 GHz. These coatings prevent crosstalk between high-voltage inverters, battery management systems, and wireless communication modules. Conductive coatings currently dominate value capture due to their established supply chains and proven attenuation performance above 60 dB. Battery enclosure applications are expanding fastest as cell-to-pack architectures expose larger conductive surfaces to radiated emissions. OEMs represent the most concentrated end-user margin pool, with fleet operators emerging as a secondary growth channel through retrofit programs.
FCC Part 15 in the United States and ECE R10 in Europe mandate radiated emission limits that directly determine coating thickness and conductivity specifications for type-approved EVs. China's GB standards for electromagnetic compatibility, enforced by MIIT, require domestic manufacturers to meet shielding effectiveness thresholds that exceed baseline UN ECE requirements. REACH and RoHS constraints in Europe restrict certain heavy-metal fillers, pushing formulators toward polymer-ceramic composites. Stakeholders must monitor how 800V and silicon-carbide inverter architectures shift interference spectra upward, demanding coatings with validated performance in the 2-6 GHz range where current formulations show degradation.
Market Dynamics
Silicon-carbide inverter architectures operating at 800V are shifting electromagnetic interference spectra upward into the 2-6 GHz range, forcing coating formulators to validate attenuation performance beyond legacy specifications. This voltage transition compresses product development cycles while expanding addressable coating thickness requirements across battery enclosure and power electronics applications.
Growth Catalysts
- ECE R10 Type Approval:Europe's tightening radiated emission limits for electric powertrains mandate shielding effectiveness above 60 dB, directly expanding coating thickness specifications for German and French OEM supply chains.
- Cell-to-Pack Battery Architectures:Elimination of module housings exposes larger conductive surfaces to radiated emissions, creating new surface area demand for spray-applied barrier coatings across high-voltage battery systems.
- Conductive Polymer-Ceramic Composites:REACH and RoHS constraints on heavy-metal fillers are accelerating substitution toward nickel-free formulations that maintain broadband absorption from 30 MHz to 6 GHz.
Market Restraints
- Silver Price Volatility:Conductive filler costs comprising 40-60% of raw material inputs expose formulators to commodity swings that compress margin structures at contract-renewal cycles.
- Application Equipment Concentration:Precision spray systems for 25-200 micron thickness control remain concentrated among German and Japanese equipment suppliers, creating capacity bottlenecks for coating service providers.
- Attenuation Degradation Above 4 GHz:Carbon-based composites exhibit measurable performance decay in the upper Wi-Fi and cellular bands, limiting their deployment in vehicles with integrated V2X communication modules.
Strategic Opportunities
- Retrofit Fleet Programs:Commercial vehicle operators in California and Germany are funding aftermarket shielding upgrades for first-generation electric buses and delivery vans to meet updated local EMC ordinances.
- Adhesive-Conductive Hybrid Chemistries:Bonding-and-shielding formulations reduce assembly steps in battery pack manufacturing, creating value capture for coating suppliers that integrate structural adhesive functionality.
- MIIT GB Standard Alignment:China's electromagnetic compatibility thresholds exceeding baseline UN ECE requirements are pulling multinational formulators toward dual-certified product platforms that access domestic EV production.
Industry Challenges
- Multi-Physics Simulation Talent:Electromagnetic modeling expertise spanning RF engineering and polymer rheology remains scarce, extending formulation validation timelines for 800V-compatible coatings.
- Cross-Functional Certification Delays:Coatings must simultaneously satisfy automotive OEM material specifications, ECE R10 type approval, and REACH substance restrictions, creating sequential testing bottlenecks.
- Thermal-Shielding Co-Design:Battery enclosures require coatings that attenuate interference while conducting or insulating heat, forcing formulators to coordinate with thermal management subsystem suppliers on conflicting performance targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electromagnetic and Radio Frequency Interference Coating for Electric Vehicles Market |
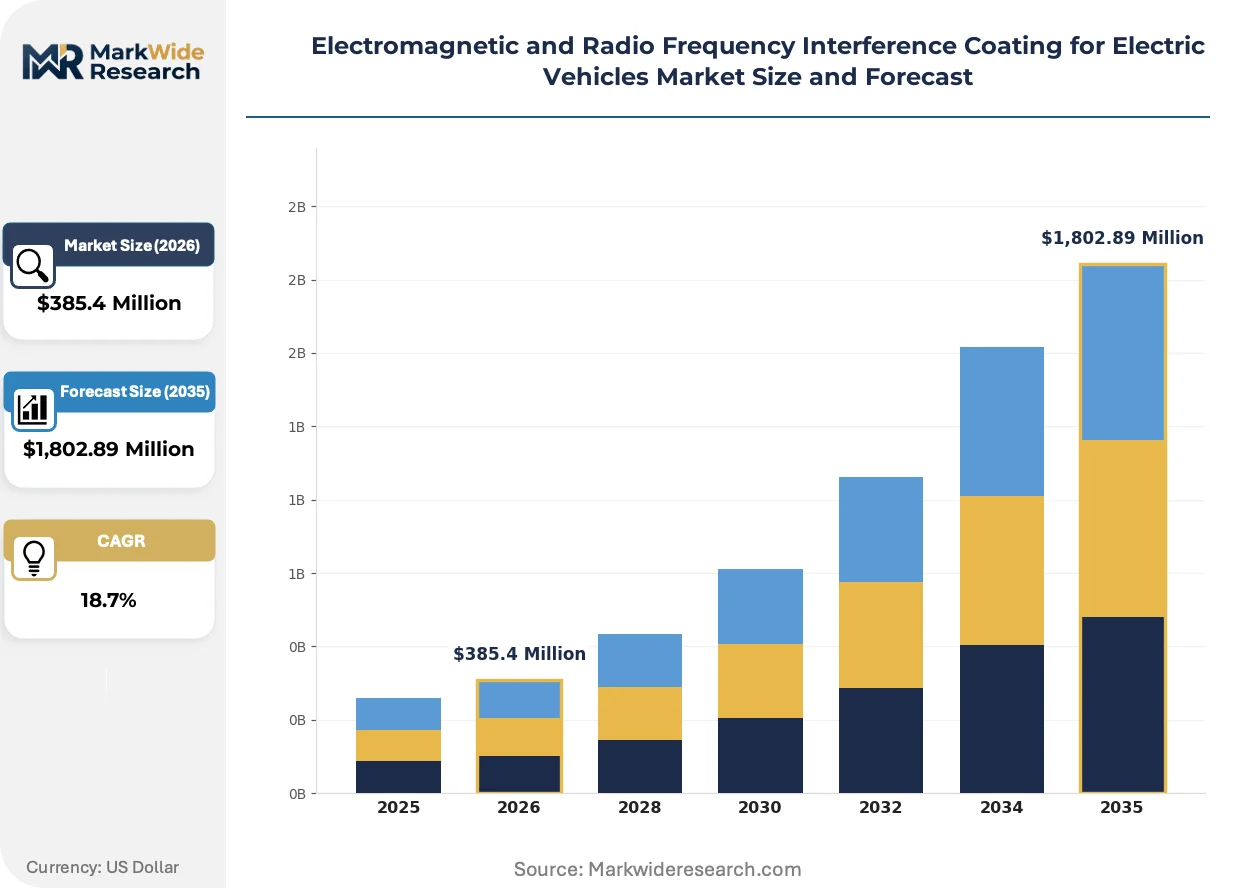
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,802.89 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coating Type: Conductive, Non-Conductive, Hybrid, Insulative Application: Chassis, Battery Enclosure, Electronic Housing, Sensors End User: OEMs, Aftermarket Providers, Fleet Operators, Research Institutions Material: Metals, Polymers, Composites, Ceramics |
| Companies Covered | Parker Hannifin, PPG Industries, Henkel AG, DuPont (Laird Performance Materials), MG Chemicals, Nanotech Energy, Electroninks, Sono-Tek, AFT Fluorotec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electromagnetic and Radio Frequency Interference Coating for Electric Vehicles Market Strategic Shifts & Innovations
Graphene-enhanced formulations are repositioning technical and economic tradeoffs across the EMI coating stack, compressing the performance gap between silver-based and carbon-based alternatives while opening new application methods.
Spray-deposited graphene-polymer composites is decentralizing coating application from centralized OEM paint shops toward tier supplier and even cell manufacturing facilities. Battery producers in South Korea and Germany are installing in-line spray booths at cell-to-pack assembly lines, reducing logistics costs and enabling just-in-time shielding application. This geographic diffusion of coating capability is compressing the traditional OEM-dominated value chain.
China's MIIT enforcement of GB/T electromagnetic compatibility standards for domestic EV certification is tightening shielding effectiveness thresholds that exceed UN ECE baselines. Foreign suppliers must establish local testing partnerships or joint ventures to access type approval documentation. Domestic manufacturers are responding by accelerating qualification of locally produced polymer-ceramic formulations that satisfy both GB and export-market requirements.
Fleet procurement of shielding retrofits is fragmenting historical OEM-captive demand toward independent service providers and aftermarket coating applicators. Municipal transit authorities in California and commercial logistics operators in Germany are issuing direct contracts for battery enclosure re-coating programs, bypassing traditional vehicle OEM service networks. This channel disintermediation is most visible in high-mileage electric bus and delivery van segments where electromagnetic compliance audits have become standard fleet management practice.
Electromagnetic and Radio Frequency Interference Coating for Electric Vehicles Market Segmentation
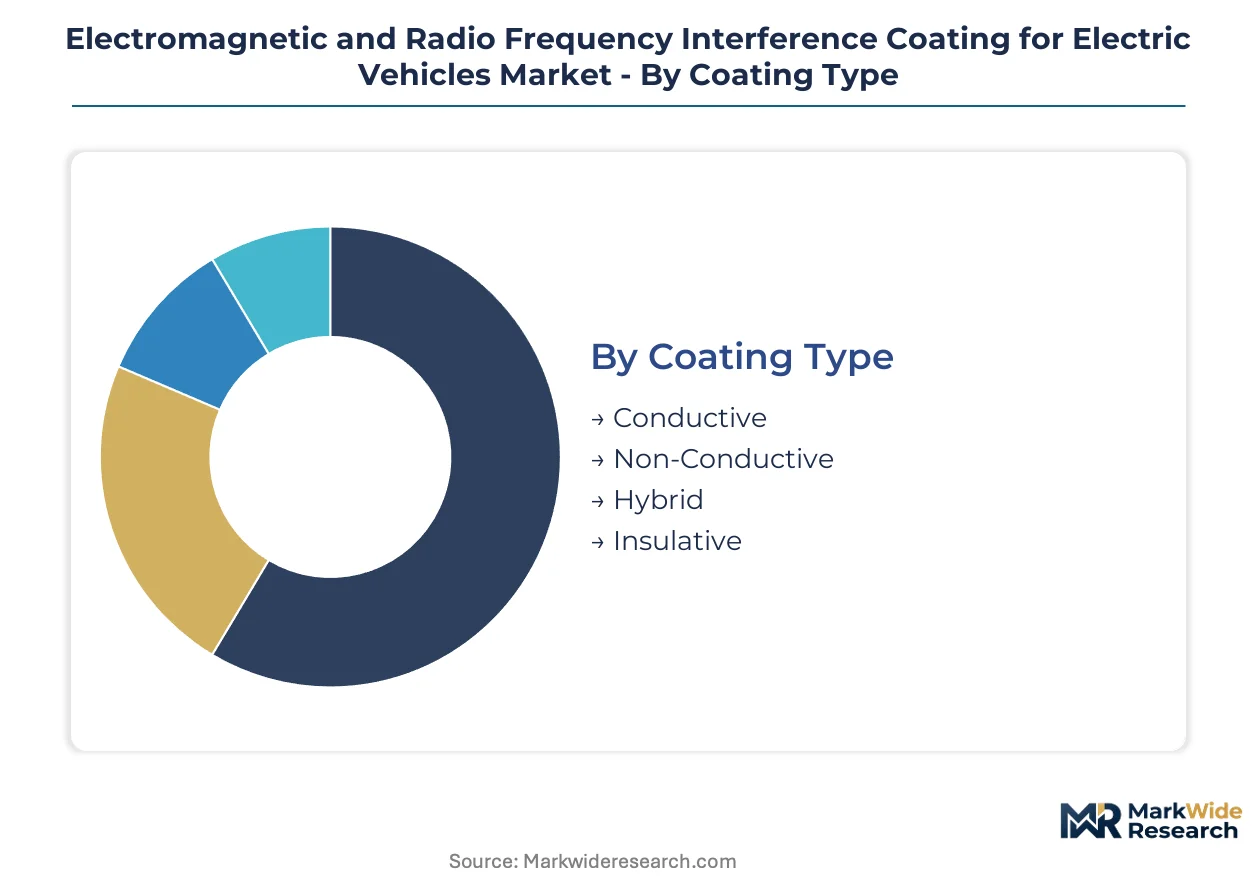
Coating specifications diverge sharply based on whether shielding operates as a standalone barrier or integrates with structural assemblies. Integration depth determines formulation chemistry, application equipment, and margin capture across the value chain.
Coating Type:
Standalone spray-applied films dominate high-volume battery production, while embedded conductive layers penetrate integrated thermal-electronic subsystems.
- Conductive:Silver-, nickel-, and carbon-based composites deliver attenuation above 60 dB across 30 MHz to 6 GHz. German OEM supply chains specify these for ECE R10 type-approved battery enclosures where shielding effectiveness is non-negotiable.
- Hybrid:Adhesive-conductive chemistries bond structural joints while attenuating interference, eliminating separate assembly steps in cell-to-pack architectures. South Korean battery manufacturers are qualifying these for in-line spray application at cell assembly facilities.
- Non-Conductive:Polymer-ceramic composites absorb rather than reflect electromagnetic energy, deployed where galvanic corrosion risks prohibit metal fillers.
- Insulative:Dielectric barrier coatings isolate high-voltage traces from conductive housings in power electronics modules.
Volume placements concentrate in Conductive; the faster expansion belongs to Hybrid.
Application:
Surface area exposure and voltage proximity dictate coating thickness specifications and reapplication frequency.
- Battery Enclosure:Cell-to-pack architectures expose 40-60% more conductive surface area than module-based designs, driving spray-applied barrier demand across 25-200 micron thickness ranges. Fleet operators in California are funding retrofit programs for first-generation electric buses.
- Electronic Housing:Inverter and DC-DC converter enclosures require multi-layer laminates that absorb broadband interference across 2-6 GHz where silicon-carbide switching generates elevated emissions.
- Chassis:Ground plane coatings manage conducted emissions from high-voltage cabling routed through vehicle underbodies.
- Sensors:Thin-film shielding protects lidar and radar modules from self-interference in advanced driver-assistance systems.
Revenue pools concentrate in Battery Enclosure; Electronic Housing is climbing the fastest as 800V architectures proliferate.
End User:
Procurement authority is fragmenting from OEM-captive specifications toward direct fleet and aftermarket contracting.
- OEMs:German and French automakers dominate material specification authority, qualifying coatings for 10-15 year vehicle lifecycles through combined ECE R10 and REACH compliance testing.
- Fleet Operators:Municipal transit authorities and commercial logistics providers are issuing direct retrofit contracts for electromagnetic compliance audits, bypassing traditional OEM service networks in high-mileage segments.
- Aftermarket Providers:Independent coating applicators are capturing battery enclosure re-coating programs as first-generation EVs age out of warranty coverage.
- Research Institutions:National laboratories and university consortia validate next-generation formulations for 800V and silicon-carbide compatibility.
Contract value concentrates in OEMs; Fleet Operators are gaining share fastest through disintermediated procurement channels.
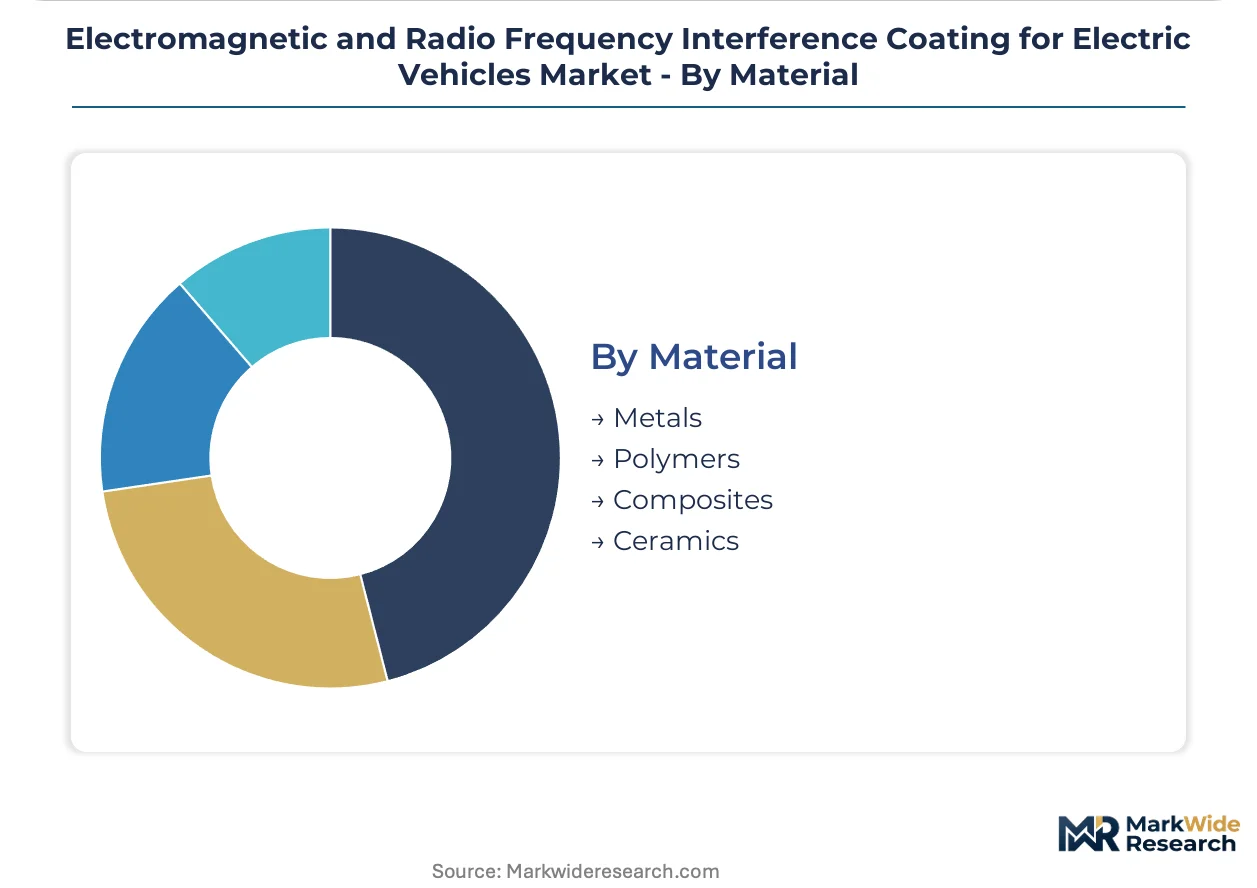
Material:
REACH and RoHS constraints are accelerating substitution patterns across the filler portfolio.
- Metals:Silver and nickel flakes deliver highest conductivity but face price volatility and regulatory restrictions on heavy-metal content.
- Composites:Graphene-polymer formulations are compressing the performance gap between silver-based and carbon-based alternatives while enabling decentralized application.
- Polymers:Intrinsically conductive polymers process at lower temperatures, expanding substrate compatibility to thermally sensitive battery components.
- Ceramics:Ferrite and barium titanate fillers absorb magnetic field components in the lower frequency ranges below 100 MHz.
Formulation activity concentrates in Composites; Polymers show the steepest expansion trajectory as processing temperatures drop.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs and tier suppliers operate the densest manufacturing clusters for electric powertrains, creating concentrated demand for ECE R10-compliant shielding solutions. Battery producers in South Korea and China are installing in-line spray capabilities at cell-to-pack assembly lines. Fleet operators in California and Germany are funding direct retrofit contracts for electromagnetic compliance audits.
Germany
BMW, Mercedes-Benz, and Volkswagen qualify coatings for 10-15 year vehicle lifecycles through combined ECE R10 type approval and REACH compliance testing. KBA enforcement of radiated emission limits for electric powertrains mandates shielding effectiveness above 60 dB. Stuttgart and Munich host tier supplier clusters where Henkel AG and Parker Hannifin anchor conductive formulation development for high-voltage battery systems.
United States
Silicon-carbide inverter production for 800V architectures is shifting interference spectra upward, forcing coating validation beyond legacy FCC Part 15 specifications. California Air Resources Board audits of municipal electric bus fleets are creating aftermarket demand for battery enclosure re-coating. Detroit and Silicon Valley house competing development tracks for OEM-captive specifications versus fleet-operator retrofit programs.
China
CATL and BYD are accelerating cell-to-pack production lines with integrated spray booths for just-in-time shielding application. MIIT enforcement of GB/T electromagnetic compatibility standards exceeds baseline UN ECE requirements, pulling multinational formulators toward dual-certified product platforms. Shenzhen and Shanghai battery producers are qualifying locally produced polymer-ceramic formulations for domestic and export-market requirements.
South Korea
LG Energy Solution and Samsung SDI are installing in-line spray capabilities at cell assembly facilities, reducing logistics costs through decentralized coating application. KATS adoption of international EMC standards creates alignment pressure for export-bound production. Gyeonggi-do and Ulsan manufacturing complexes concentrate qualification activity for adhesive-conductive hybrid chemistries that bond and shield simultaneously.
France
Renault and Stellantis operations require REACH-compliant nickel-free formulations as heavy-metal restrictions tighten across EU supply chains. ANSM oversight of substance restrictions pushes formulators toward polymer-ceramic composites for galvanic-sensitive applications. Paris-Saclay research clusters validate next-generation graphene-polymer formulations for 800V-compatible attenuation performance.
Electromagnetic and Radio Frequency Interference Coating for Electric Vehicles Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with formulation developers capturing margin in OEM-captive supply chains while equipment providers concentrate in precision spray system supply. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with fluid systems expertise, adhesive-chemical specialists with conductive hybrid platforms, and materials-science pure-plays with multi-layer laminate structures. Competitive moves center on backward integration into raw material supply and geographic expansion through local testing partnerships for MIIT GB standard alignment.
Within the diversified industrial tier, Parker Hannifin exemplifies fluid systems integration into thermal management assemblies. Henkel AG anchors the adhesive-chemical specialist archetype through hybrid bonding-and-shielding formulations. DuPont occupies a position representing materials-science depth via multi-layer laminate structures for broadband interference absorption.
| Leading Market Players |
|---|
| Parker Hannifin |
| PPG Industries |
| Henkel AG |
| DuPont (Laird Performance Materials) |
| MG Chemicals |
| Nanotech Energy |
| Electroninks |
| Sono-Tek |
| AFT Fluorotec |
| Others |
Cost & Logistics Intelligence
Backward integration into conductive filler supply anchors pricing power for German and Japanese formulators serving ECE R10-compliant OEM specifications, while outsourced raw material procurement exposes tier suppliers to silver and nickel commodity swings that compress margins at contract renewal. This structural split between captive and merchant supply positions separates premium coating developers from price-competitive service providers.
Pricing Analysis
Volume placements in conductive coatings generate thin margins on high-tonnage battery enclosure contracts, while hybrid adhesive-conductive formulations capture premium pricing through reduced assembly step value. Price differentiation hinges on ECE R10 certification tier and volume scale, with REACH-compliant nickel-free formulations commanding structural premiums over legacy metal-filled alternatives. Cost compression in standard conductive grades is intensifying because South Korean battery producers are qualifying locally produced polymer-ceramic composites for in-line spray application. Fleet operators exhibit highest price sensitivity through disintermediated retrofit procurement, whereas German OEM captive specifications tolerate premium pricing for 10-15 year lifecycle validation.
Supply Chain Analysis
Reverse-logistics flows for first-generation EV battery enclosures are creating aftermarket coating demand as municipal transit authorities in California and Germany audit electromagnetic compliance on out-of-warranty electric bus fleets. Raw material supply concentrates in China for graphene feedstock, Germany for precision spray equipment, and South Korea for conductive polymer resins. Formulation draws from silver flake, nickel powder, and carbon nanotube inputs that face REACH and RoHS restriction risks on heavy-metal content. Single-source vulnerability runs through German and Japanese precision spray system suppliers that control 25-200 micron thickness calibration. Distribution runs through OEM-captive tier supplier networks, with direct fleet contracting fragmenting historical channel concentration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ECE R10 type approval functions as a cost-of-compliance moat that protects qualified formulators from unvalidated competitors, with KBA enforcement of shielding effectiveness thresholds above 60 dB creating multi-year certification barriers for new market participants.
For Market Incumbents: Anticipate graphene-polymer substitution patterns that threaten silver-based formulation margins by accelerating qualification of nickel-free composites for 800V architectures. Prioritize backward integration into conductive filler supply to offset commodity price volatility exposure. Defend channel position through exclusive testing partnerships with MIIT-authorized laboratories for dual GB-ECE certification platforms. For New Entrants and Emerging Players: The price-point gap between premium OEM-captive specifications and economy-tier aftermarket retrofits opens white-space targeting of independent fleet operators in California and Germany seeking direct electromagnetic compliance contracts. Focus initial penetration on battery enclosure re-coating programs for first-generation electric buses and delivery vans. Pursue qualification partnerships with South Korean cell-to-pack manufacturers installing decentralized in-line spray capabilities. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified industrial conglomerates seeking fluid systems integration capabilities. Long-term viability favors formulators with validated 2-6 GHz attenuation performance for silicon-carbide inverter architectures. Monitor MIIT enforcement actions against non-compliant domestic EV manufacturers as inflection signal for dual-certified product platform demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Conductive Filler Supply | Captive silver and nickel flake sourcing insulates Henkel AG and Parker Hannifin from commodity volatility compressing tier supplier margins. |
| Dual GB-ECE Certification Platform Development | Joint testing partnerships with MIIT-authorized laboratories unlock CATL and BYD supply chains exceeding baseline UN ECE shielding thresholds. |
| In-Line Spray Capability Installation | Decentralized coating application at LG Energy Solution cell assembly facilities reduces logistics costs and enables just-in-time shielding. |
| Adhesive-Conductive Hybrid Formulation Launch | Bonding-and-shielding chemistries eliminate separate assembly steps in Samsung SDI cell-to-pack manufacturing lines. |
| Aftermarket Fleet Retrofit Program Expansion | Direct contracting with California municipal transit authorities bypasses OEM service networks in high-mileage electric bus segments. |
Research Approach
SEC 10-K filings, ECE R10 type approval documentation, and IHS Markit vehicle production databases formed the secondary backbone, cross-referenced with primary interviews across OEM platform engineers, tier supplier procurement leads, coating formulator R&D directors, and fleet operator maintenance managers. Bottom-up and top-down triangulation validated volume estimates against customs trade data for conductive filler imports and MIIT GB standard certification records.
Bottom-up modeling segmented the market by coating type, application surface, end-user procurement authority, and conductive filler chemistry across the analysis window. Top-down validation referenced electric powertrain production forecasts and cell-to-pack architecture penetration rates. CAGRs derived from regression analysis of historical coating content per vehicle against 800V platform rollout timelines and silicon-carbide inverter adoption curves.
Inputs from ECE R10 certification databases and fleet operator procurement records were available through the study window; gaps in real-time silver price volatility data introduce uncertainty bands around raw material cost projections. Practitioners should monitor MIIT enforcement actions, KBA type approval backlog durations, and graphene-polymer formulation qualification timelines for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle (EV) Ball Bearings Market
Electric Vehicles
Norway Electric Vehicle Market
Electric Vehicles
Electric Scooters and Mopeds Market
Electric Vehicles
Vietnam Electric Vehicle Market
Electric Vehicles
Asia-Pacific Electric Bus Battery Pack Market
Electric Vehicles
India Electric Bus Market
Electric Vehicles
Asia Pacific Electric Commercial Vehicles Market
Electric Vehicles
India Solar E-Bike Market
Electric Vehicles
Electric Skateboard Market
Electric Vehicles
Latin America Automotive High Performance Electric Vehicle Market
Electric Vehicles
Agricultural Electric Vehicles Market
Electric Vehicles
Mexico E-Bike Market
Electric Vehicles
Germany Electric Bus Battery Pack Market
Electric Vehicles
UK Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Self Balancing Electric Scooter Market
Electric Vehicles
Golf Cart Battery Market