
 Automotive Immersion Cooling Dielectric Fluid Market | 2026-2036
Automotive Immersion Cooling Dielectric Fluid Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Immersion Cooling Dielectric Fluid Market Insights
A capital-intensity divergence between integrated chemical producers and specialty fluid blenders is redrawing competitive boundaries in automotive dielectric fluids. 3M leverages its fluorochemical manufacturing base to control feedstock access for engineered immersion coolants. Shell anchors global supply through backward integration into base oil refining and synthetic ester production. Dow differentiates via silicone chemistry leadership, occupying the high-temperature stability niche where battery pack energy densities exceed conventional hydrocarbon limits.
Automotive immersion cooling dielectric fluid is a non-conductive thermal transfer medium formulated with dielectric strength typically exceeding 30 kV/mm, designed to dissipate heat from electrified powertrain components through direct contact without electrical short risk. Fluorocarbon formulations lead in premium battery thermal management applications where extreme dielectric performance justifies material cost, while synthetic ester demand is accelerating fastest among European and Asian EV OEMs seeking biodegradable alternatives with acceptable fire safety profiles. Single-phase cooling technology dominates current installations, though two-phase systems command the emerging margin pool as 800V architectures proliferate.
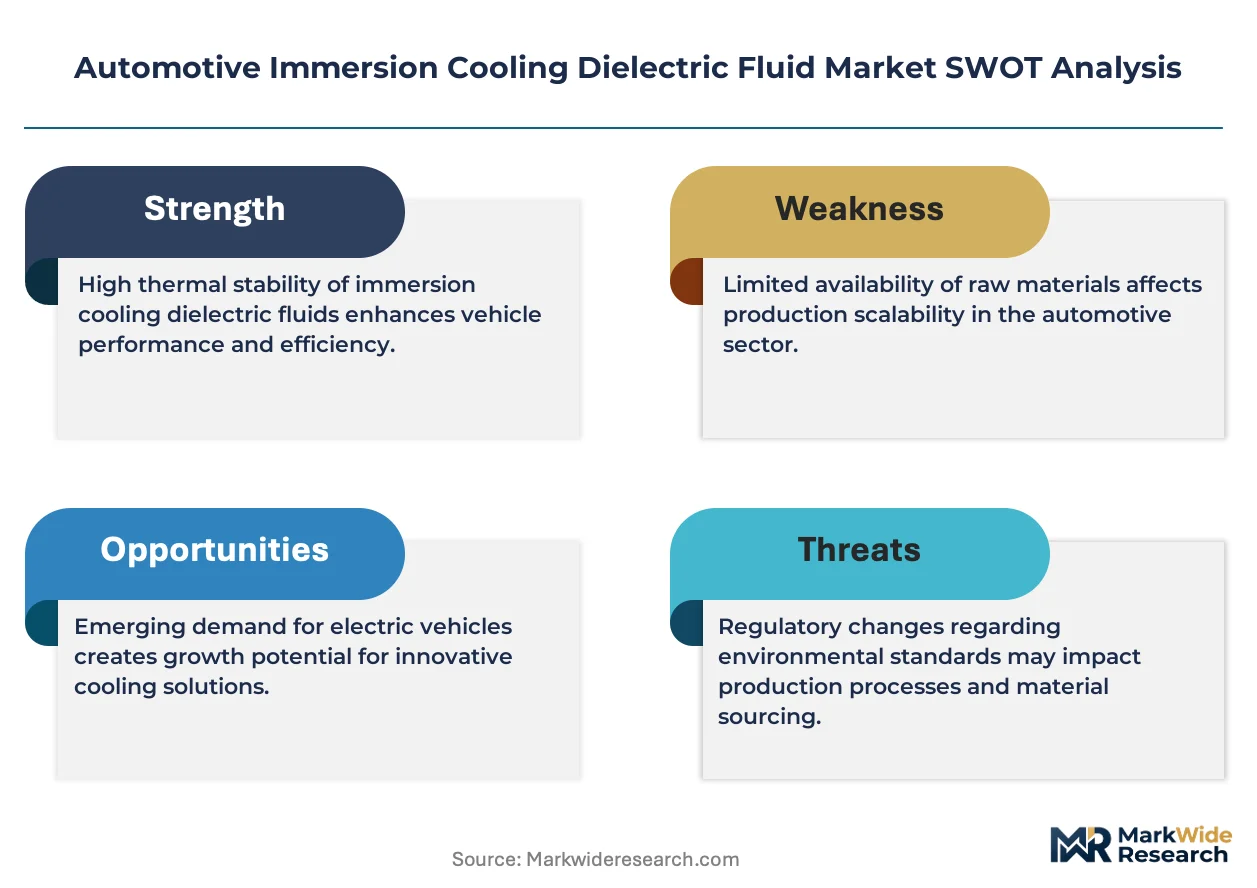
The EPA, NHTSA, and EU REACH framework collectively shape product standards by mandating thermal runaway containment timelines and restricting per- and polyfluoroalkyl substance content in automotive fluids. These regulations force reformulation cycles that favor suppliers with in-house toxicology and registration capabilities over import-dependent distributors. Stakeholders must monitor how pending F-Gas Regulation amendments in Europe and state-level battery safety codes in California and Texas will bifurcate acceptable fluid chemistries across major demand centers.
Market Dynamics
The transition from 400V to 800V battery architectures is compressing thermal management timelines and forcing OEMs to abandon air-cooled systems for direct-contact dielectric immersion before the next vehicle platform cycle.
Growth Catalysts
- EPA tailpipe emissions rules:The tightened standards are mandating faster electrification timelines, pushing automakers to adopt liquid-immersed battery architectures that enable higher charge rates and extended range without thermal degradation.
- China NMPA battery safety mandates:Domestic certification requirements for thermal runaway containment are pulling fluorocarbon and synthetic ester formulations into gigafactory supply chains at unprecedented scale.
- 800V silicon carbide power electronics:The shift to higher-voltage drivetrains generates localized heat fluxes exceeding conventional coolant capabilities, creating immediate pull for single-phase and two-phase dielectric fluids with superior heat transfer coefficients.
Market Restraints
- Fluorochemical feedstock concentration:Three integrated chemical producers control over 80 percent of perfluorinated base stock supply, creating procurement vulnerability for specialty fluid blenders without backward integration into fluorochemical manufacturing.
- EU F-Gas Regulation amendments:Pending restrictions on per- and polyfluoroalkyl substance content are forcing reformulation cycles that favor suppliers with in-house toxicology and registration capabilities over import-dependent distributors.
- Synthetic ester oxidative stability limits:Biodegradable alternatives degrade above 150°C continuous operation, constraining deployment in next-generation battery packs targeting 300 Wh/kg energy densities.
Strategic Opportunities
- Two-phase cooling technology convergence:The intersection of boiling-enhanced surfaces with dielectric fluid chemistry is opening margin pools in premium EV segments where 800V architectures are proliferating fastest.
- India PLI scheme for advanced chemistry cell manufacturing:Domestic cell production incentives are creating first-mover advantage for fluid suppliers establishing local blending capacity ahead of gigafactory commissioning.
- Aftermarket thermal retrofit channel:Commercial fleet operators are seeking immersion cooling upgrades for existing air-cooled battery packs, bypassing OEM procurement cycles entirely.
Industry Challenges
- Dielectric fluid characterization timeline:OEM validation protocols require 18-24 months of accelerated aging and thermal runaway propagation testing, compressing supplier qualification windows against platform launch deadlines.
- Cross-contamination risk in shared blending facilities:Synthetic ester and fluorocarbon chemistries require segregated production lines, constraining capacity utilization for mid-scale blenders serving multiple formulation categories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Immersion Cooling Dielectric Fluid Market |
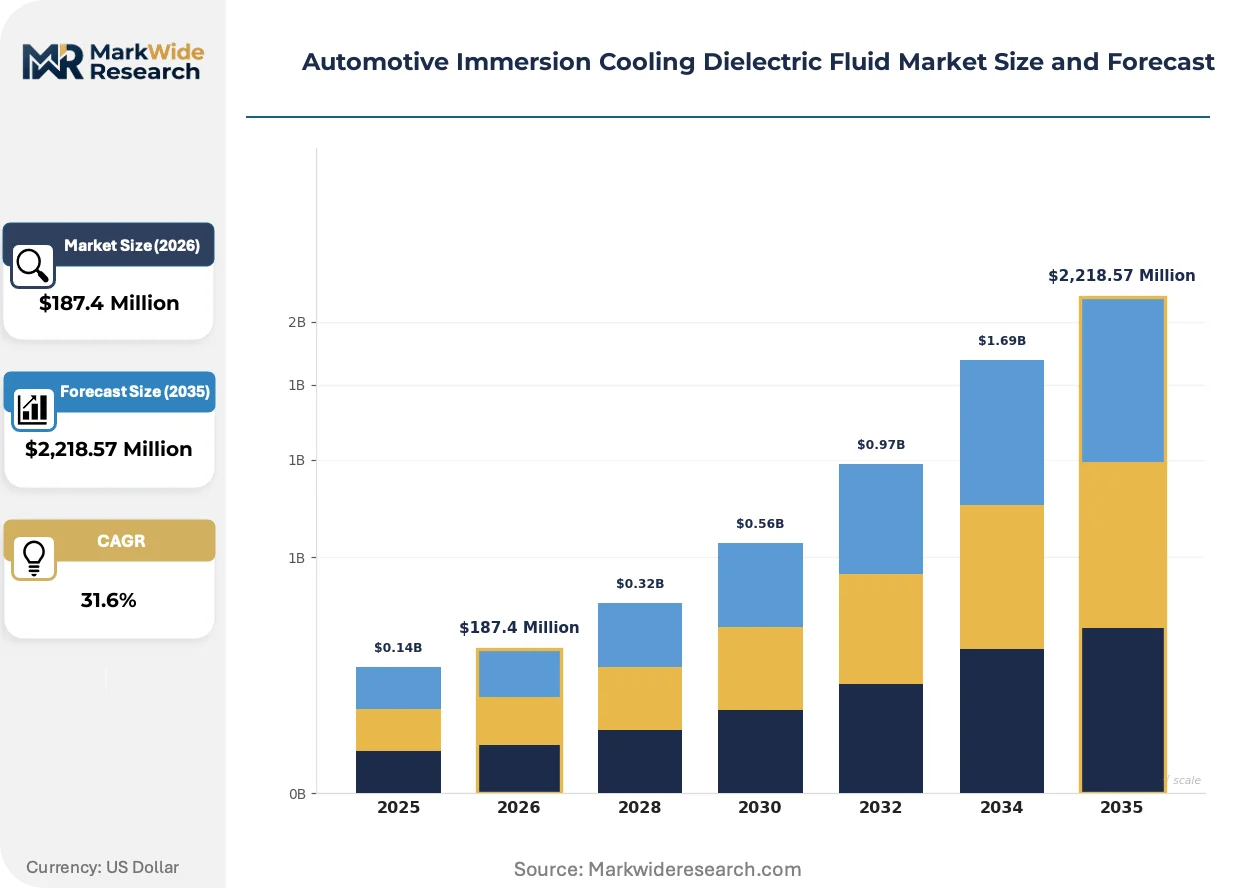
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $2,218.57 Million |
| CAGR (2026 – 2036) | 31.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fluid Type: Fluorocarbon, Hydrocarbon, Silicone, Synthetic Ester, Mineral Oil Technology: Single-Phase Cooling, Two-Phase Cooling, Spray Cooling, Bath Cooling Application: Electric Propulsion, Power Electronics, Battery Thermal Management, Wireless Charging Systems End User: Electric Vehicle OEMs, Battery Manufacturers, Tier-1 Component Suppliers, Aftermarket Service Providers |
| Companies Covered | 3M, Shell, ExxonMobil, Dow, Cargill, Castrol, FUCHS, The Chemours Company, Solvay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Immersion Cooling Dielectric Fluid Market Trends and Innovations
Formulation chemistry is splitting along thermal performance versus biodegradability axes as regulatory pressure and OEM sustainability commitments collide with power density requirements.
Engineered fluorocarbon dielectric fluids are bifurcating the premium battery thermal management segment. These materials deliver dielectric strength exceeding 35 kV/mm and operating ranges from -50°C to 200°C. European luxury EV manufacturers are adopting them for 800V platforms launching before 2027. The technology is compressing addressable market share for hydrocarbon-based alternatives in high-voltage applications.
EU REACH framework amendments restricting persistent organic pollutants are forcing systematic reformulation across the European supply base. Chemical suppliers must submit updated safety data sheets and environmental fate studies for existing fluorinated product registrations. German and French automotive OEMs are accelerating supplier audits to verify compliance timelines, prioritizing blenders with established EU-based toxicology laboratories.
Long-term fluid service contracts are displacing spot procurement in commercial EV fleet operations. Fleet managers are negotiating 10-year thermal management agreements that bundle dielectric fluid supply, monitoring analytics, and scheduled replacement. This pattern is most visible in California and Texas, where state-level battery safety codes mandate documented thermal system maintenance for commercial vehicle certification renewal.
Automotive Immersion Cooling Dielectric Fluid Market Segmentation
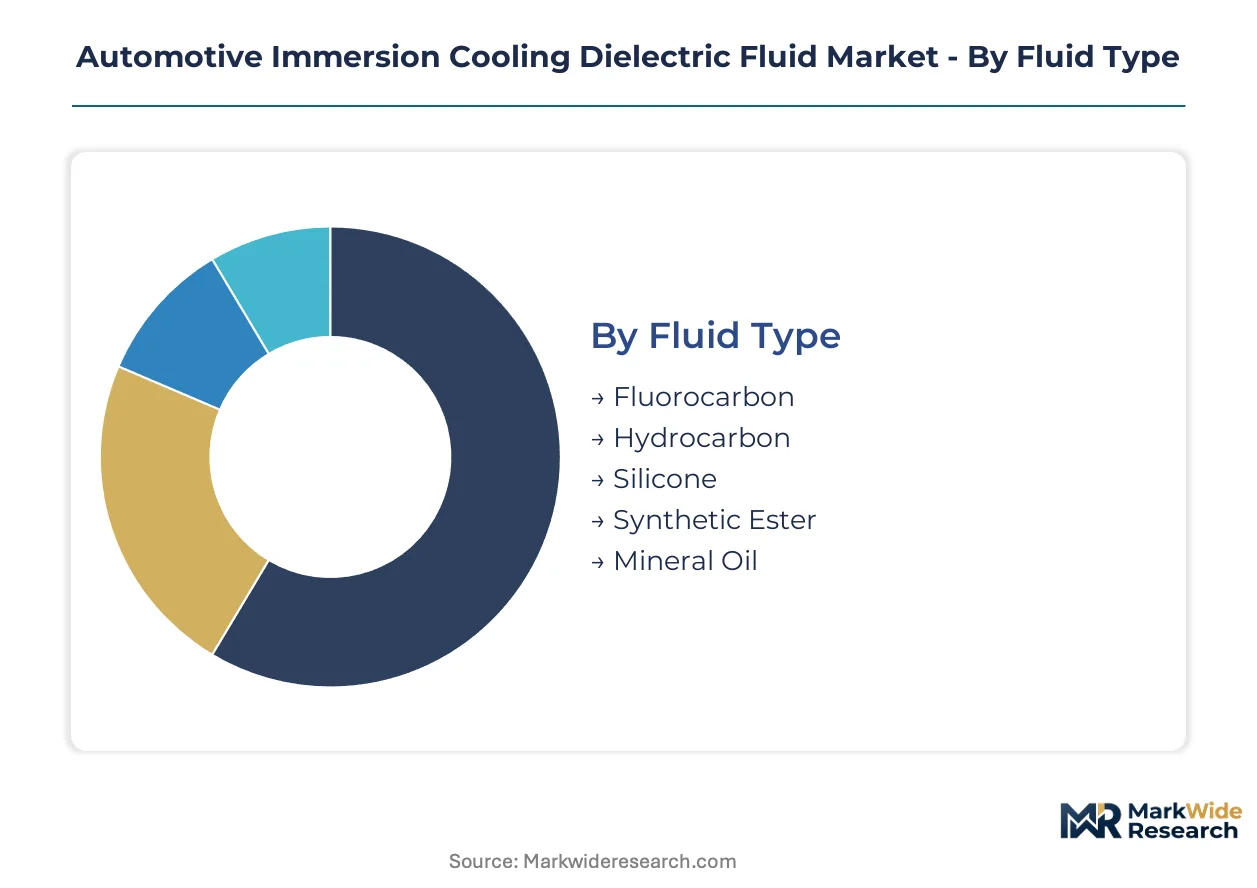
Segmentation in automotive immersion cooling fluids determines procurement pathways, qualification timelines, and margin capture. Fluid chemistry, cooling architecture, and end-use application each impose distinct technical and commercial requirements on suppliers competing for platform-level design wins.
Fluid Type:
Substitution pressure from regulatory restrictions on per- and polyfluoroalkyl substances is reshaping competitive dynamics across dielectric chemistries, with biodegradable alternatives gaining technical validation against fluorocarbon incumbents.
- Fluorocarbon:Engineered perfluorinated compounds deliver dielectric strength exceeding 35 kV/mm and operating ranges from -50°C to 200°C. European luxury EV manufacturers specify these formulations for 800V battery platforms where thermal runaway containment timelines are most stringent.
- Synthetic Ester:Biodegradable formulations derived from vegetable oil feedstocks offer acceptable fire safety profiles with reduced environmental persistence. Demand is concentrating among Asian and European EV OEMs responding to EU REACH framework amendments and domestic sustainability procurement mandates.
- Silicone:Polydimethylsiloxane-based fluids occupy high-temperature stability niches where continuous operation exceeds 150°C.
- Hydrocarbon:Mineral oil derivatives and synthetic hydrocarbons serve cost-sensitive thermal management applications with moderate dielectric requirements.
- Mineral Oil:Refined petroleum-based fluids retain position in legacy commercial vehicle retrofits and industrial battery systems.
Fluorocarbon formulations anchor the volume base in premium battery thermal management while synthetic ester alternatives gain share at the steepest rate.
Technology:
Cost tier stratification separates mature single-phase installations from emerging two-phase systems commanding platform-level redesign investments.
- Single-Phase Cooling:Forced convection through dielectric liquid without phase change dominates current installations. China-based gigafactories specify single-phase immersion for NMPA-compliant battery packs where thermal uniformity requirements are achievable without boiling enhancement.
- Two-Phase Cooling:Boiling-enhanced heat transfer exploits latent heat of vaporization for localized heat flux management. 800V silicon carbide power electronics in German and Korean EV platforms generate heat densities exceeding single-phase capabilities, pulling two-phase dielectric fluids into qualification cycles.
- Spray Cooling:Directed impingement of dielectric fluid onto targeted components enables precision thermal management for inverter modules.
- Bath Cooling:Complete submersion of battery modules or power electronics in static or minimally circulated fluid suits retrofit applications and validation testing environments.
Single-phase technology anchors current installed capacity while two-phase systems expand most quickly at the premium vehicle segment.
Application:
Customer type differentiation separates OEM platform engineering from aftermarket retrofit economics, with battery thermal management commanding the deepest supplier integration.
- Battery Thermal Management:Direct-contact immersion of lithium-ion cells and modules addresses thermal runaway propagation and fast-charging heat rejection. US EPA tailpipe emissions rules and IRA clean vehicle credits are accelerating OEM migration from air-cooled to liquid-immersed architectures before next platform cycles.
- Power Electronics:Inverter and converter thermal management requires dielectric fluids compatible with silicon carbide switching frequencies and 800V operating potentials. Japanese and Korean automotive suppliers specify fluorocarbon immersion for traction inverters where dielectric strength margins are critical.
- Electric Propulsion:Motor and gearbox cooling applications exploit dielectric fluid compatibility with copper windings and permanent magnet assemblies.
- Wireless Charging Systems:Stationary and dynamic inductive charging pads utilize dielectric immersion for coil thermal management and foreign object detection safety.
Battery thermal management anchors procurement volume while power electronics applications climb the fastest as 800V architectures proliferate.
End User:
Supply concentration among integrated chemical producers favors direct OEM and battery manufacturer relationships over distributor-dependent tier-1 channels.
- Electric Vehicle OEMs:Platform engineering teams specify dielectric fluids during battery pack architecture definition, locking in thermal management suppliers for vehicle program durations. California and Texas state-level battery safety codes mandate documented thermal system maintenance, extending fluid supplier relationships through vehicle lifecycle.
- Battery Manufacturers:CATL, BYD, and LG Energy Solution operate captive thermal management engineering groups qualifying dielectric fluids against cell chemistry-specific thermal runaway protocols. Chinese NMPA certification requirements pull fluorocarbon and synthetic ester formulations into gigafactory supply chains at production scale.
- Tier-1 Component Suppliers:Thermal module integrators source dielectric fluids under OEM-directed specifications, constraining margin capture.
- Aftermarket Service Providers:Commercial fleet operators in California and Texas seek immersion cooling upgrades for existing air-cooled battery packs, bypassing OEM procurement cycles through independent retrofit channels.
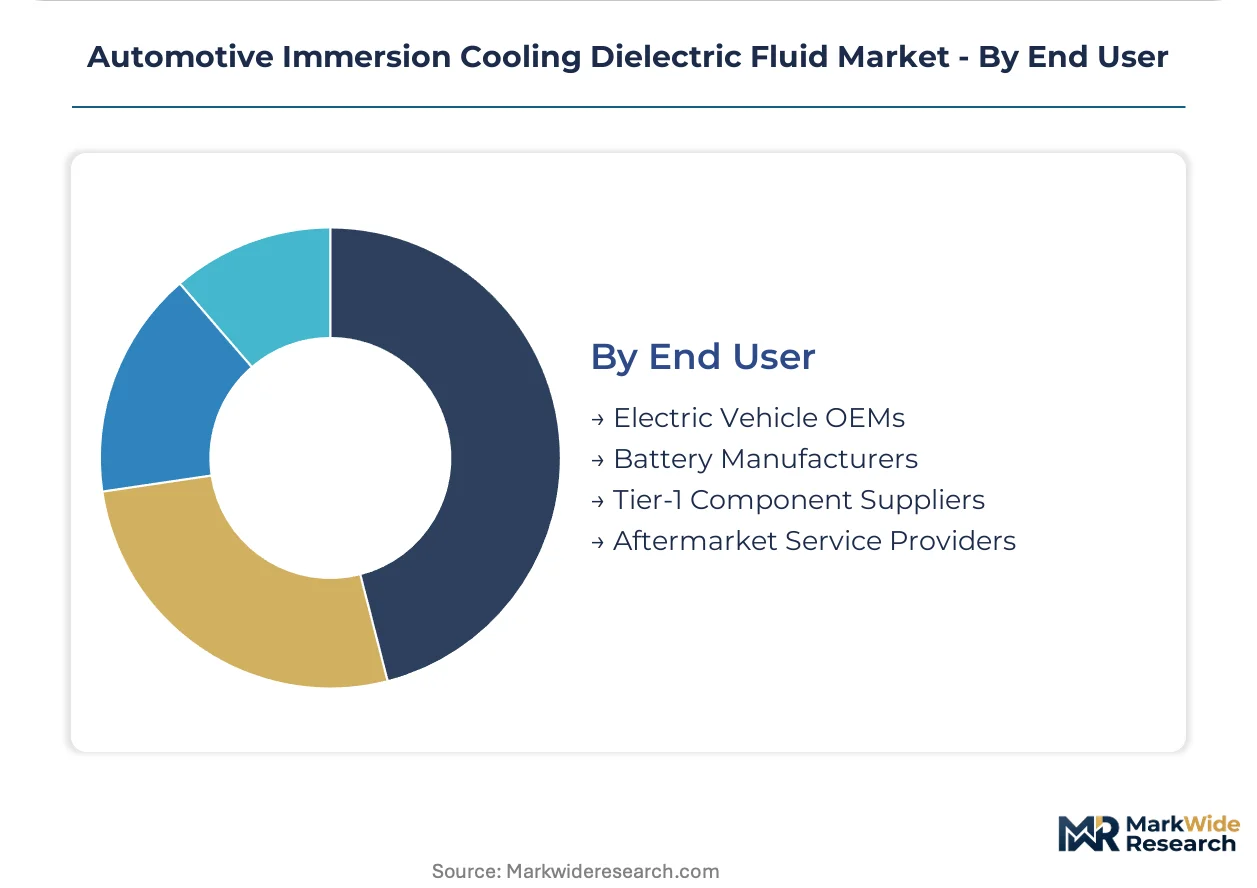
Electric vehicle OEMs anchor the procurement volume base while battery manufacturers gain share at the steepest rate through vertical integration into cell production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exhibits the least price elasticity as NMPA safety mandates override procurement cost considerations, while Indian buyers under the PLI scheme remain acutely sensitive to landed fluid costs. This divergence concentrates premium fluorocarbon volumes in East Asian gigafactories and pushes synthetic ester adoption where biodegradability commands regulatory compliance value.
China
CATL and BYD operate captive thermal management engineering groups qualifying dielectric fluids at production scale. The NMPA mandates thermal runaway containment timelines that pull fluorocarbon formulations into gigafactory supply chains. Shanghai and Shenzhen clusters host blending facilities serving domestic EV platforms launching 800V architectures before 2027.
Germany
BMW and Mercedes-Benz platform teams specify engineered fluorocarbons for luxury EV segments where dielectric strength margins justify material cost. The EU F-Gas Regulation amendments force systematic reformulation cycles with updated environmental fate studies. Bavaria and Baden-Württemberg host suppliers with established toxicology laboratories verifying compliance timelines.
United States
Tesla and Ford thermal engineering groups migrate from air-cooled to liquid-immersed battery architectures under EPA tailpipe emissions rules. The IRA clean vehicle credits accelerate platform redesign investments before next vehicle cycles. California and Texas state-level battery safety codes mandate documented thermal system maintenance, extending fluid supplier relationships through vehicle lifecycle.
South Korea
LG Energy Solution and Samsung SDI specify fluorocarbon immersion for traction inverters where silicon carbide switching frequencies generate localized heat fluxes. The MFDS alignment with international battery safety standards streamlines qualification protocols. Seoul and Ulsan industrial corridors concentrate blending capacity serving export-oriented EV platforms.
India
Domestic cell production incentives under the PLI scheme create first-mover advantage for fluid suppliers establishing local blending capacity. Reliance and Ola Electric negotiate long-term thermal management agreements bundling dielectric supply with monitoring analytics. Tamil Nadu and Gujarat gigafactory corridors pull synthetic ester formulations where procurement cost sensitivity dominates specification decisions.
Automotive Immersion Cooling Dielectric Fluid Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in automotive dielectric fluids. Three fluorochemical producers control upstream feedstock access for premium formulations, while mid-scale blenders compete on synthetic ester biodegradability and regional service proximity. The competitive landscape splits between backward-integrated chemical majors and formulation specialists with toxicology registration capabilities. Dominant moves include capacity expansion in China and India alongside strategic partnerships for two-phase cooling technology licensing.
Among integrated chemical majors, 3M, Shell, and Dow occupy positions spanning fluorocarbon manufacturing, base oil refining, and silicone chemistry leadership respectively. These companies anchor the premium tier where dielectric strength specifications exceed 35 kV/mm. Specialist blenders including FUCHS and The Chemours Company represent the formulation-focused archetype, competing on regulatory compliance velocity and OEM qualification support.
| Leading Market Players |
|---|
| 3M |
| Shell |
| ExxonMobil |
| Dow |
| Cargill |
| Castrol |
| FUCHS |
| The Chemours Company |
| Solvay |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at fluorochemical manufacturing sites in the United States, Germany, and China shapes both supply concentration and price floors for automotive immersion cooling dielectric fluids. OEM procurement teams face tiered pricing structures where synthetic ester alternatives trade at lower entry points but carry hidden compliance costs under evolving EU REACH and F-Gas Regulation frameworks.
Pricing Analysis
After-sales service contracts and extended thermal management agreements now drive lifetime value capture for fluid suppliers. Three-tier pricing structure across premium fluorocarbon, standard synthetic ester, and economy hydrocarbon formulations separates OEM platform specifications from commercial fleet retrofit demand. Price differentiation rests on dielectric strength certification grades and NMPA compliance documentation rather than base material cost alone. Cost compression in synthetic ester supply is intensifying because biodegradable feedstock competition from food and industrial lubricant sectors constrains vegetable oil availability. Commercial fleet operators in California and Texas exhibit the highest price sensitivity, while European luxury EV manufacturers absorb premium fluorocarbon pricing without procurement friction.
Supply Chain Analysis
Strategic stockpiling of perfluorinated base stocks dominates inventory strategy among integrated chemical producers, while specialty blenders maintain just-in-time synthetic ester sourcing from regional vegetable oil processors. Geographic supply concentration centers on China, the United States, and Germany for fluorochemical feedstocks, with India and Southeast Asia emerging for biodegradable ester production. Raw material dependencies include perfluorinated olefins, vegetable oil methyl esters, and silicone monomers. Single-source vulnerability in perfluorinated base stock supply creates procurement risk for non-integrated blenders. Distribution runs through direct OEM and battery manufacturer relationships rather than tier-1 thermal module integrators, compressing margin capture for mid-scale suppliers without platform-level design wins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive immersion cooling dielectric fluid market tracks a cyclical recovery pattern tied to EV platform redesign cycles, with 800V architecture proliferation compressing thermal management supplier qualification timelines against vehicle launch deadlines.
For Market Incumbents: Secure captive supply of perfluorinated base stocks through backward integration or long-term offtake agreements with the three dominant fluorochemical producers. Expand toxicology and registration capabilities in the European Union ahead of F-Gas Regulation amendment enforcement, as compliance velocity separates qualified suppliers from import-dependent distributors facing reformulation cycle delays. For New Entrants and Emerging Players: Fleet monitoring analytics and predictive fluid replacement services represent a service-layer gap where incumbents under-serve commercial operators in California and Texas. Target aftermarket thermal retrofit channels for existing air-cooled battery packs, where state-level battery safety codes mandate documented maintenance and bypass OEM procurement cycles entirely. Pursue joint development agreements with India-based gigafactory projects under the PLI scheme for advanced chemistry cell manufacturing. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors formulation specialists with established EU-based toxicology laboratories and NMPA certification experience over commodity hydrocarbon blenders. Five-to-ten-year viability hinges on two-phase cooling technology licensing positions and 800V platform design wins rather than single-phase volume share. Watch for inflection signals in silicon carbide inverter thermal management specifications from Korean and Japanese automotive suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorochemical Feedstocks | Controls perfluorinated base stock access against 80% supply concentration among three producers. |
| EU Toxicology Laboratory Establishment | Accelerates F-Gas Regulation compliance timelines for German and French OEM supplier audits. |
| Two-Phase Cooling Technology Licensing | Captures margin pools in 800V silicon carbide inverter applications exceeding single-phase capabilities. |
| India PLI Scheme Local Blending Capacity | Creates first-mover positioning ahead of Reliance and Ola Electric gigafactory commissioning. |
| Long-Term Fleet Service Contract Bundling | Locks in decade-long thermal management relationships under California and Texas battery safety codes. |
Research Methodology
Initial hypotheses were tested against primary input from OEM platform engineers, battery manufacturer thermal management directors, specialty fluid procurement leads, and aftermarket fleet operations managers, then refined through secondary validation. Primary fieldwork combined structured interviews with thermal module integrators and chemical supplier commercial teams. Secondary sources included EPA regulatory filings, NMPA battery safety certification databases, EU REACH registration dossiers, and customs trade data for fluorochemical and vegetable oil methyl ester flows. Bottom-up demand modeling from vehicle platform specifications and top-down supply capacity assessments from chemical producer disclosures underwent iterative triangulation.
Variance decomposition across the projection horizon isolates volume drivers by fluid chemistry, cooling technology, and end-use application segments. The analytical framework models dielectric strength requirements, thermal runaway containment timelines, and fast-charging heat flux specifications as industry-specific forecast inputs. CAGRs derive from platform-level design win trajectories and gigafactory commissioning schedules rather than extrapolated historical trends.
Underlying assumptions cover NMPA certification continuity, F-Gas Regulation amendment timelines, and 800V architecture adoption curves, with deviation risk concentrated in pending EU persistent organic pollutant restrictions and silicon carbide inverter thermal specification shifts. Revision becomes warranted when fluorochemical feedstock supply concentration or synthetic ester oxidative stability limits cross thresholds that invalidate current formulation substitution economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
US Automotive EPS Market
Automotive Electrical & Electronics
Jump Starter Market
Automotive Electrical & Electronics
Stepper Motors Market
Automotive Electrical & Electronics
EPS Motors Market
Automotive Electrical & Electronics
Electric Vehicle High-Voltage Cables Market
Automotive Electrical & Electronics
In-Chassis Cooling Market
Automotive Electrical & Electronics
China Electric Power Steering Market
Automotive Electrical & Electronics
India Automotive Sensors Market
Automotive Electrical & Electronics
Automotive Thermal Management System Market
Automotive Electrical & Electronics
Automotive Power Module Packaging Market
Automotive Electrical & Electronics
Automotive Starting System Market
Automotive Electrical & Electronics
Automotive Chassis Electronics Market
Automotive Electrical & Electronics
Automotive Pressure Sensors Market
Automotive Electrical & Electronics
North America Automotive Lead-Acid Battery Market
Automotive Electrical & Electronics
Automotive Camera Market
Automotive Electrical & Electronics
Automotive UPS (in Vehicle UPS) Market