
 Electric Vehicle (EV) Ball Bearings Market | 2026-2036
Electric Vehicle (EV) Ball Bearings Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle (EV) Ball Bearings Market Insights
The direct-to-Tier-1 supply channel is fragmenting as EV OEMs bring bearing specification authority in-house. SKF leverages its European R&D footprint to sustain technical leadership in ceramic hybrid designs. Schaeffler anchors its position through backward integration into heat-treatment and rolling-element production. NSK competes aggressively in the Chinese OEM segment with localized manufacturing scale.
Electric vehicle ball bearings are precision rotary components manufactured from vacuum-degassed steel or silicon nitride ceramic, engineered to withstand rotational speeds exceeding 20,000 rpm in motor assemblies while maintaining noise thresholds below 40 dB. Their primary commercial purpose is to reduce friction and extend service life in drivetrain systems where thermal cycling and electrical corrosion pose accelerated wear risks. Deep groove configurations currently occupy the largest share of OEM procurement volumes due to their versatility across motor and hub applications. Angular contact bearings represent the fastest-growing product category as axial-load motor architectures proliferate in performance EV platforms. The specialty size tier commands disproportionate margin pools where custom tolerances align with premium drivetrain programs.
The EPA tailpipe standards and NHTSA fuel economy rules in the United States compel bearing suppliers to demonstrate friction-reduction credentials that translate into extended EV range claims. The EU's REACH chemicals framework and F-Gas Regulation restrict lubricant formulations and manufacturing byproducts, reshaping material selection across European supply chains. China's GB standards and MIIT new-energy vehicle catalog requirements enforce localization thresholds that condition market access. Stakeholders must monitor how battery platform standardization versus modular drivetrain diversity reshapes volume concentration and specification fragmentation across procurement channels.
Market Dynamics
China's NEV mandate and the EU's CO2 fleet standards are forcing bearing suppliers to reengineer friction coefficients and electrical insulation properties at unprecedented speed. OEMs now specify ceramic hybrid bearings directly, bypassing traditional Tier-1 intermediaries.
Growth Catalysts
- China's MIIT new-energy vehicle catalog:Localization thresholds enforce domestic procurement quotas that accelerate capacity buildout in Jiangsu and Zhejiang manufacturing corridors.
- Silicon nitride ceramic rolling elements:These materials eliminate electrical pitting in high-frequency motor applications, extending service intervals beyond 300,000 kilometers.
- Angular contact bearing architectures:Axial-load motor designs in performance EV platforms are pulling procurement volumes away from deep groove configurations.
Market Restraints
- Specialty steel input volatility:Vacuum-degassed bearing steel pricing fluctuates with scrap metal markets and energy-intensive refining costs in European mills.
- Heat-treatment capacity concentration:Controlled atmosphere furnaces for precision bearing hardening cluster in Germany and Japan, creating single-source vulnerability.
- REACH chemical restrictions:The EU's lubricant formulation limits constrain fluoropolymer coatings that currently prevent electrical corrosion in hybrid bearings.
Strategic Opportunities
- India's PLI scheme for automotive components:Production-linked incentives for advanced manufacturing could attract bearing facilities serving domestic EV assembly.
- Solid-state battery thermal management:Next-generation cell architectures will require bearings rated for wider temperature cycling ranges than current liquid-cooled systems.
- Direct OEM specification channels:EV manufacturers building in-house drivetrain engineering teams create bypass routes around entrenched Tier-1 distributor networks.
Industry Challenges
- Ceramic rolling-element grinding expertise:Silicon nitride ball sphericity tolerances below 0.05 micrometers require specialized workforce training that outpaces vocational pipeline output.
- ISO 26262 functional safety certification:Automotive-grade bearing qualification timelines extend 18-24 months, compressing product refresh cycles against platform launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle (EV) Ball Bearings Market |
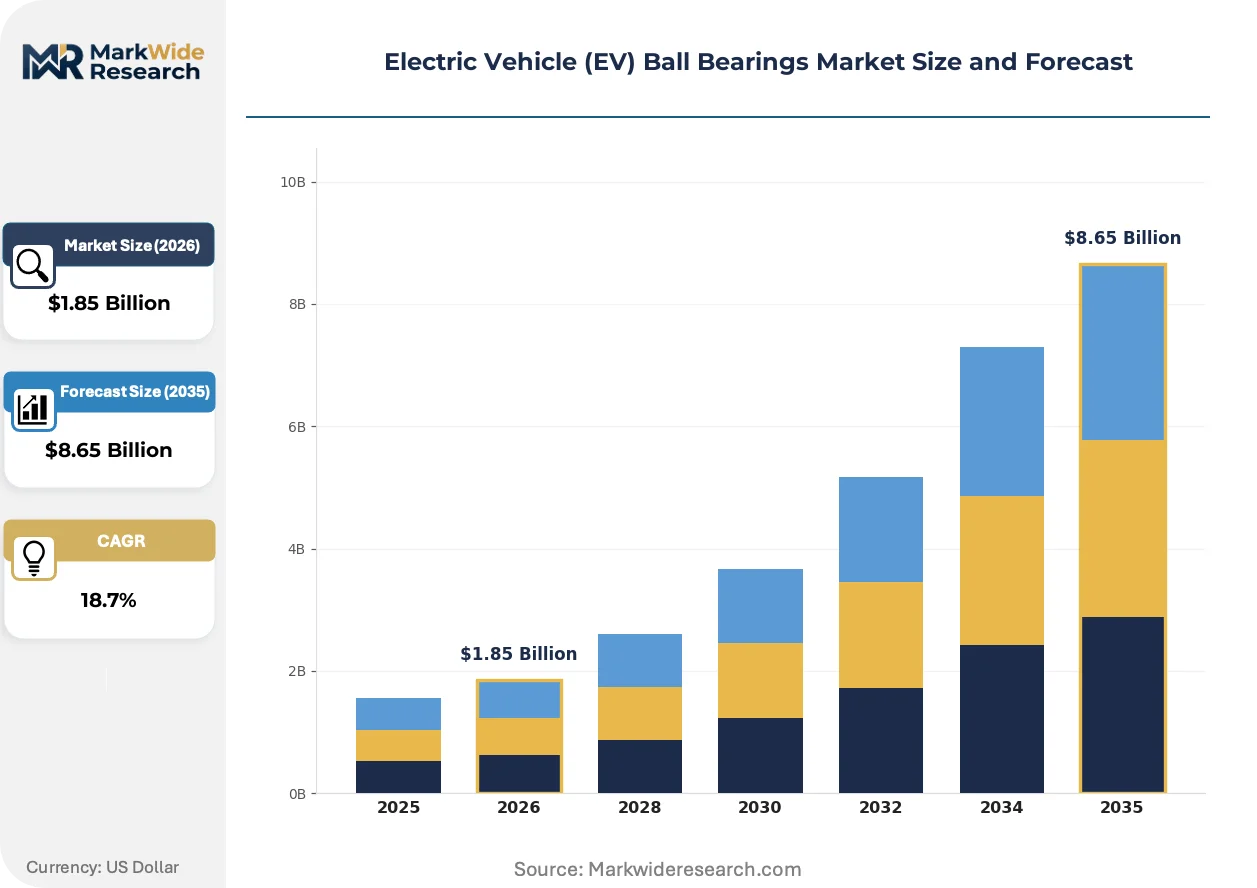
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $8.65 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Deep Groove, Angular Contact, Self-Aligning, Thrust End User: OEMs, Aftermarket, Tier-1 Suppliers, Vehicle Assemblers Size: Standard, Miniature, Specialty, Custom Application: Motor Assemblies, Wheel Hubs, Suspension Systems, Steering |
| Companies Covered | SKF, Schaeffler, NSK, NTN, JTEKT, Timken, C&U GROUP, NACHI, Rexnord, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle (EV) Ball Bearings Market Trends and Innovations
Ceramic hybrid bearing architectures are rendering obsolete conventional steel designs across high-performance motor applications. Three interconnected developments are compressing supplier response windows and rewiring specification authority.
Silicon nitride ceramic rolling elements deliver dielectric insulation exceeding 10^15 ohm-cm, eliminating electrical discharge machining pits that plague steel bearings in 800-volt architectures. Premium EV motor programs in Germany and South Korea have adopted these configurations as baseline specifications. The technology is rendering obsolete grease-lubricated steel bearings in axial-load motor designs above 150 kW.
The EU's F-Gas Regulation restricts perfluorinated lubricant chemistries that currently enable extended service intervals in sealed bearing cartridges. Bearing suppliers must reformulate with polyether or synthetic ester bases that degrade faster under thermal cycling. European OEM procurement teams are now requiring lubricant migration roadmaps as contract preconditions.
Direct technical collaboration between bearing engineers and OEM motor design teams is displacing traditional Tier-1 specification intermediaries. SKF and NSK now station application engineers inside customer R&D centers in Stuttgart and Shanghai. This channel restructuring concentrates volume with suppliers capable of co-development rather than catalog distribution.
Electric Vehicle (EV) Ball Bearings Market Segmentation
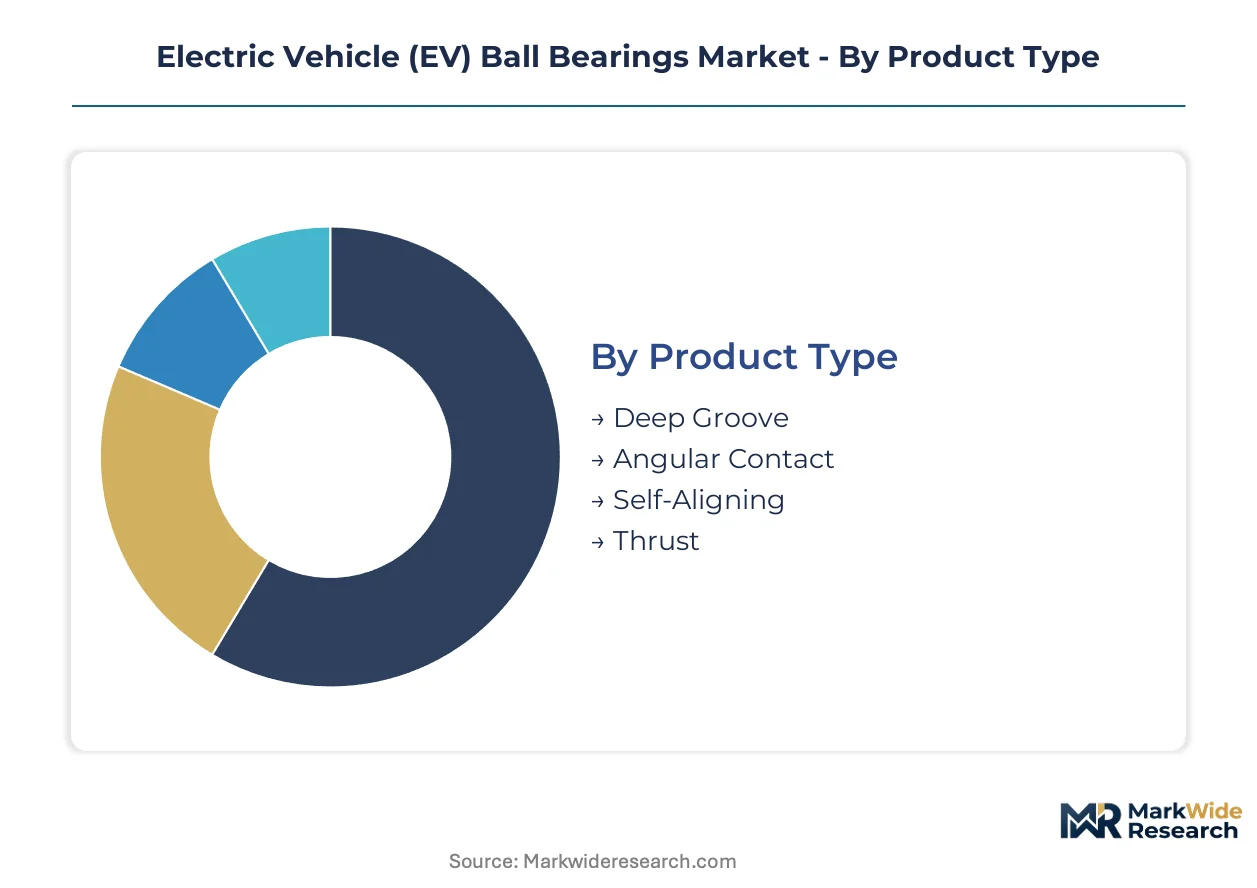
Segmentation in the EV ball bearing market reveals how procurement authority, technical specifications, and margin pools distribute across divergent supply channels. Understanding these divisions exposes where specification power concentrates and where suppliers must build differentiated capabilities to capture value.
Product Type:
The use-case spectrum spans from versatile general-purpose designs to precision axial-load architectures in high-performance drivetrains.
- Deep Groove:These bearings handle combined radial and axial loads through a continuous raceway geometry, making them deployable across motor and hub applications with minimal customization. Procurement volumes concentrate with Chinese OEMs building cost-optimized BEV platforms in Jiangsu province, where standardization drives economies of scale.
- Angular Contact:Designed with raceway offsets that create contact angles for pure axial load handling, these configurations serve 800-volt motor architectures above 150 kW. German and South Korean OEMs specify these as baseline for performance platforms, displacing deep groove alternatives in premium drivetrain programs.
- Self-Aligning:Spherical outer ring raceways accommodate shaft misalignment in suspension linkages and steering columns. Demand clusters with vehicle assemblers prioritizing assembly tolerance relaxation.
- Thrust:Single-direction axial load capacity serves limited applications in gearbox selector mechanisms and parking brake actuators. Procurement remains fragmented across Tier-1 transmission suppliers.
The dominant share belongs to Deep Groove, while Angular Contact is closing the gap fastest.
End User:
Cost tier stratification separates specification authority from fulfillment execution across the supply pyramid.
- OEMs:Direct technical collaboration with bearing engineers now bypasses traditional intermediaries. Stuttgart and Shanghai R&D centers host embedded supplier teams co-developing motor-integrated bearing solutions.
- Tier-1 Suppliers:These intermediaries retain residual volume in legacy platform carryovers and modular drivetrain sourcing. Margin compression accelerates as OEMs internalize specification authority.
- Aftermarket:Service interval extension beyond 300,000 kilometers from ceramic hybrid designs constrains replacement demand. Channel participants pivot toward diagnostic tooling and remanufacturing services.
- Vehicle Assemblers:Contract manufacturers and joint-venture production facilities procure through OEM-directed supply agreements with limited independent sourcing discretion.
OEMs command the specification high ground, though Tier-1 Suppliers retain operational leverage in legacy fulfillment.
Size:
Volume concentration versus margin extraction splits across dimensional categories with divergent manufacturing economics.
- Specialty:Custom tolerances below 0.05 micrometers sphericity and non-standard envelope dimensions serve low-volume premium drivetrain programs. SKF and Schaeffler dominate through captive heat-treatment and grinding expertise concentrated in Germany and Japan.
- Standard:ISO dimension series bearings move through high-volume automated production lines serving mass-market BEV platforms. Chinese manufacturing corridors in Zhejiang absorb the majority of global procurement tonnage.
- Miniature:Sub-10mm bore diameters support auxiliary motor applications in thermal management and active aerodynamics systems. Demand scales with multi-motor platform proliferation.
- Custom:Application-specific envelope modifications and integrated sensor features command project-based pricing with extended qualification timelines.
Specialty dimensions capture disproportionate margin pools, while Standard sizes absorb the volume base.
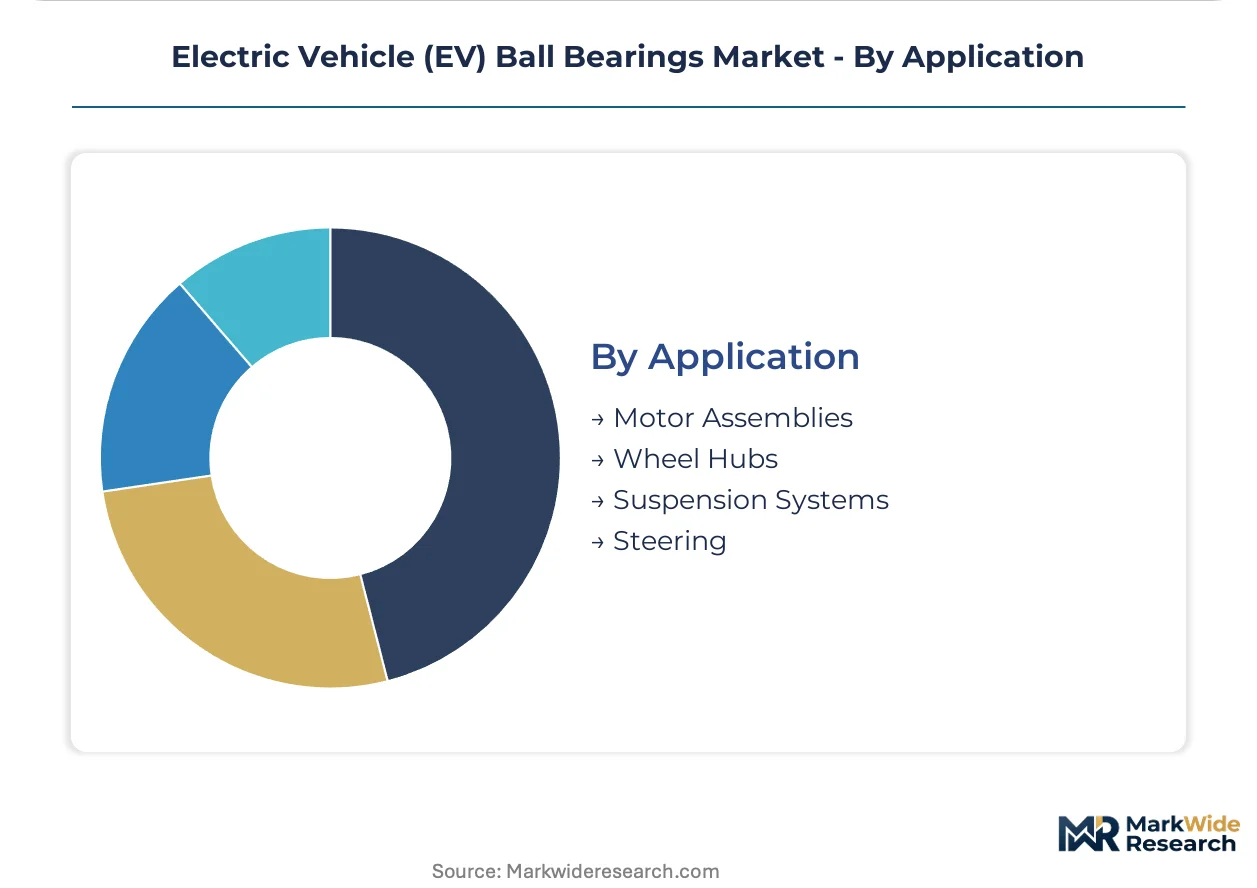
Application:
Customer type segmentation maps bearing performance requirements to thermal, electrical, and mechanical stress profiles across vehicle systems.
- Motor Assemblies:Rotational speeds exceeding 20,000 rpm and electrical insulation demands above 10^15 ohm-cm define specifications. Ceramic hybrid architectures eliminate discharge pitting in 800-volt inverter-fed motors.
- Wheel Hubs:Sealed cartridge designs face extended service interval requirements and contamination resistance priorities. Load ratings center on vehicle mass distribution and regenerative braking torque reversal.
- Suspension Systems:Multi-axis load cases and corrosion exposure from road salt and debris drive material selection toward sealed stainless variants.
- Steering:Rack-and-pinion and column-mounted applications prioritize noise thresholds below 40 dB and backlash minimization for haptic feedback preservation.
Motor Assemblies anchor procurement value, with Wheel Hubs following as electrification extends platform content per vehicle.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai-Ningbo-Zhoushan port complex anchors Asia-Pacific bearing logistics, handling vacuum-degassed steel imports and ceramic hybrid exports for motor assembly programs across three continents. This maritime infrastructure underwrites China's dominance in precision component manufacturing.
China
Jiangsu and Zhejiang manufacturing corridors absorb the majority of global EV bearing procurement tonnage. MIIT catalog requirements enforce localization thresholds that condition market access for foreign suppliers. Changzhou and Ningbo host concentrated heat-treatment and grinding operations serving domestic OEMs.
Germany
Stuttgart and Munich R&D centers host embedded bearing application engineers co-developing 800-volt motor solutions. The F-Gas Regulation restricts perfluorinated lubricant formulations, forcing reformulation with polyether bases. Schweinfurt maintains captive heat-treatment expertise for specialty tolerance programs.
United States
EPA tailpipe standards and NHTSA fuel economy rules compel friction-reduction credentials that translate into extended EV range claims. The Inflation Reduction Act's domestic content incentives reshape procurement patterns for battery platform assemblies. Michigan and Ohio manufacturing zones attract bearing facilities serving Detroit Three electrification programs.
Japan
Meti industrial policy prioritizes ceramic rolling-element grinding expertise for silicon nitride sphericity below 0.05 micrometers. JIS standards enforce qualification protocols that extend automotive-grade bearing timelines to 18-24 months. Kansai and Chubu regions concentrate precision grinding workforce training pipelines.
South Korea
Seoul-based OEMs specify ceramic hybrid bearings as baseline for performance platforms above 150 kW. MFDS chemical oversight parallels REACH restrictions on fluoropolymer coatings. Busan-Ulsan industrial belt hosts motor-integrated bearing development for export-oriented drivetrain programs.
Electric Vehicle (EV) Ball Bearings Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in material and process domains. The vendor base concentrates around three strategic archetypes: European R&D-centric designers with captive heat-treatment, Asian scale manufacturers with localized supply chains, and mid-cap specialists with ceramic grinding expertise. Consolidation pressure intensifies as OEMs internalize specification authority. Dominant competitive moves include backward integration into rolling-element production and direct technical collaboration contracts that bypass traditional distribution channels.
Within the European R&D-centric tier, SKF and Schaeffler occupy positions defined by captive heat-treatment infrastructure and ceramic hybrid design leadership. NSK anchors the Asian scale manufacturer archetype through localized production corridors. These three entities exemplify how specification authority migrates toward suppliers capable of co-development rather than catalog distribution.
| Leading Market Players |
|---|
| SKF |
| Schaeffler |
| NSK |
| NTN |
| JTEKT |
| Timken |
| C&U GROUP |
| NACHI |
| Rexnord |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Ningbo-Zhoushan port complex channels vacuum-degassed steel imports and ceramic hybrid exports at freight rates that compress margin structures for European heat-treatment specialists while amplifying price differentiation between Jiangsu mass-market producers and German captive-technology suppliers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ceramic hybrid bearings with sub-0.05-micrometer sphericity tolerances from ISO-dimension standard grades and unbranded Chinese catalog offerings. Price differentiation hinges on ISO 26262 functional safety certification tier and backward integration into silicon nitride rolling-element production. Pricing pressure stems from OEMs internalizing specification authority and demanding direct technical collaboration contracts that bypass traditional Tier-1 distributor markups. Chinese OEMs in the Jiangsu corridor exhibit highest price sensitivity, while German and South Korean performance platform programs absorb premium tiers with minimal negotiation leverage.
Supply Chain Analysis
Contract manufacturing concentration resides with captive heat-treatment operations at SKF and Schaeffler facilities in Germany and Japan, supplemented by NSK's localized Zhejiang production corridors. Geographic supply concentration centers on China for standard-grade volume, Germany for specialty tolerance programs, and Japan for ceramic grinding expertise. Raw material dependencies include vacuum-degassed bearing steel from European scrap-fed mills, silicon nitride powder from Japanese ceramic suppliers, and polyether-based lubricants reformulated under EU F-Gas Regulation constraints. Single-source vulnerability concentrates in controlled-atmosphere furnace capacity for precision hardening. Distribution runs through direct OEM technical collaboration channels that displace traditional Tier-1 intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EV ball bearing market sits in early-cycle expansion as 800-volt platform proliferation pulls ceramic hybrid specifications into baseline procurement for performance drivetrains.
For Market Incumbents: Build captive ceramic rolling-element grinding moats through workforce pipeline investments in Kansai and Chubu training centers. Defensive moves require securing direct OEM co-development contracts in Stuttgart and Shanghai R&D centers while expanding heat-treatment furnace capacity ahead of platform launch windows. The threat of Chinese scale manufacturers capturing specification authority through MIIT localization mandates demands preemptive joint-venture structures in Jiangsu corridors.
For New Entrants and Emerging Players: India's underpenetrated PLI scheme for automotive components offers white-space access as domestic EV assembly scales. Target solid-state battery thermal management bearing applications requiring wider temperature cycling ranges than incumbent liquid-cooled designs permit. Go-to-market leverage rests on ceramic grinding expertise partnerships with Japanese equipment suppliers rather than greenfield furnace investment.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with stranded bearing divisions lacking EV-specific ceramic hybrid capabilities. Long-term viability favors suppliers with demonstrated 800-volt motor program qualifications and embedded application engineering relationships. Monitor NHTSA fuel economy rule stringency adjustments as inflection signal for friction-reduction specification acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Hybrid Bearing Platform Standardization | SKF and NSK embed engineers in Stuttgart R&D centers to co-develop 800-volt motor solutions. |
| Backward Integration into Silicon Nitride Production | Schaeffler's captive rolling-element capacity insulates margin structures from raw material volatility. |
| Direct OEM Specification Channel Bypass | Bypass routes around Tier-1 distributors concentrate volume with co-development-capable suppliers. |
| Localized Manufacturing Scale in Jiangsu Corridors | MIIT catalog thresholds enforce domestic procurement quotas that condition foreign supplier market access. |
| Polyether-Based Lubricant Reformulation | EU F-Gas Regulation restrictions on fluoropolymer coatings force faster-degrading synthetic ester alternatives. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with OEM platform engineers, Tier-1 supplier procurement leads, ceramic grinding equipment specialists, and heat-treatment furnace operators; and secondary validation against MIIT new-energy vehicle catalog filings, EPA fuel economy compliance databases, EU REACH chemical restriction updates, and customs trade records for vacuum-degassed bearing steel flows. Bottom-up triangulation across Jiangsu and Zhejiang production tonnage estimates converged with top-down market sizing from drivetrain content-per-vehicle assumptions.
Forecast inputs incorporated vehicle class stratification, propulsion architecture differentiation between BEV and PHEV platforms, bearing content per motor configuration, OEM tier segmentation, and regional production cluster concentration across the analysis window. CAGRs derived from segment-level volume projections weighted by premium-standard-economy pricing tier mix. Industry-specific inputs included 800-volt platform penetration curves and ceramic hybrid adoption thresholds above 150 kW motor ratings.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese state-supported manufacturers or accelerated REACH chemical restrictions would shift outcomes beyond modeled bounds. Quarterly review of MIIT catalog localization enforcement intensity and NHTSA rulemaking timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Vehicle Solar Panel Market
Electric Vehicles
Bus Pantograph Charger Market
Electric Vehicles
North America Electric Bus Market
Electric Vehicles
Electric Vehicle Skateboard Chassis Market
Electric Vehicles
Preassembled Harness Modules for Skateboard EV Platforms Market
Electric Vehicles
Electric Vehicle Speed Reducer Market
Electric Vehicles
Hybrid EV Conversion Kit Market
Electric Vehicles
Global Vehicle to Grid Technology Market
Electric Vehicles
China Electric Truck Market
Electric Vehicles
Global Electric All Wheel Drive (AWD) Market
Electric Vehicles
Europe Electric Car Market
Electric Vehicles
Electric Unicycle Market
Electric Vehicles
Electric Loader Rickshaw Market
Electric Vehicles
Electric Vehicle Extruded Aluminum Battery Trays Market
Electric Vehicles
48V Mild Hybrid Electric Vehicle (MHEV) Market
Electric Vehicles
Indian E-Bike Rental Market