
 India Solar E-Bike Market | 2026-2036
India Solar E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
India Solar E-Bike Market Insights
Photovoltaic integration with lightweight lithium-ion battery packs is reconfiguring powertrain architecture for Indian electric two-wheelers. EMotorad leverages its direct-to-consumer platform to control pricing across Tier 2 and Tier 3 cities. Hero Lectro E-Cycles anchors its position through Hero Cycles' vast dealership network spanning 400 plus Indian towns. Toutche Electric differentiates with proprietary solar charge controllers optimized for tropical insolation patterns.
India solar e-bikes combine brushless DC or hub motors with rooftop or detachable photovoltaic panels rated 20-50 watts, storing energy in lithium-ion or lead-acid packs to extend range 15-30 kilometers beyond grid charging alone. The commuter segment dominates unit volume due to fuel cost sensitivity among urban office workers, while delivery services represent the fastest-expanding category as Swiggy and Zomato franchisees seek zero-fuel-cost fleet options. Lithium-ion batteries command premium positioning against lead-acid alternatives due to superior cycle life and energy density in high-temperature Indian climates.
BIS certification requirements for electric vehicle batteries and CEA grid-interconnection standards for AC charging infrastructure shape product compliance costs and market access timelines. State transport authorities in Maharashtra and Karnataka enforce distinct subsidy documentation requirements that fragment go-to-market execution. Stakeholders must monitor PLI scheme disbursement velocity and state EV policy renewal cycles to calibrate capacity investments and distribution expansion timing.
Market Dynamics
The PLI scheme for advanced chemistry cell batteries is compressing domestic battery costs and reconfiguring powertrain economics for solar-assisted electric two-wheelers across Indian manufacturing clusters.
Growth Catalysts
- State EV Policies:Maharashtra, Karnataka, and Tamil Nadu offer registration fee waivers and road tax exemptions that reduce total cost of ownership for fleet operators and individual commuters.
- Last-Mile Delivery Expansion:Swiggy and Zomato franchisees in Mumbai and Bangalore are scaling procurement of solar-assisted electric two-wheelers to eliminate fuel expenditure from unit economics.
- Photovoltaic Integration:Rooftop and detachable solar panels rated 20-50 watts are extending single-charge range by 15-30 kilometers beyond grid-dependent alternatives.
Market Restraints
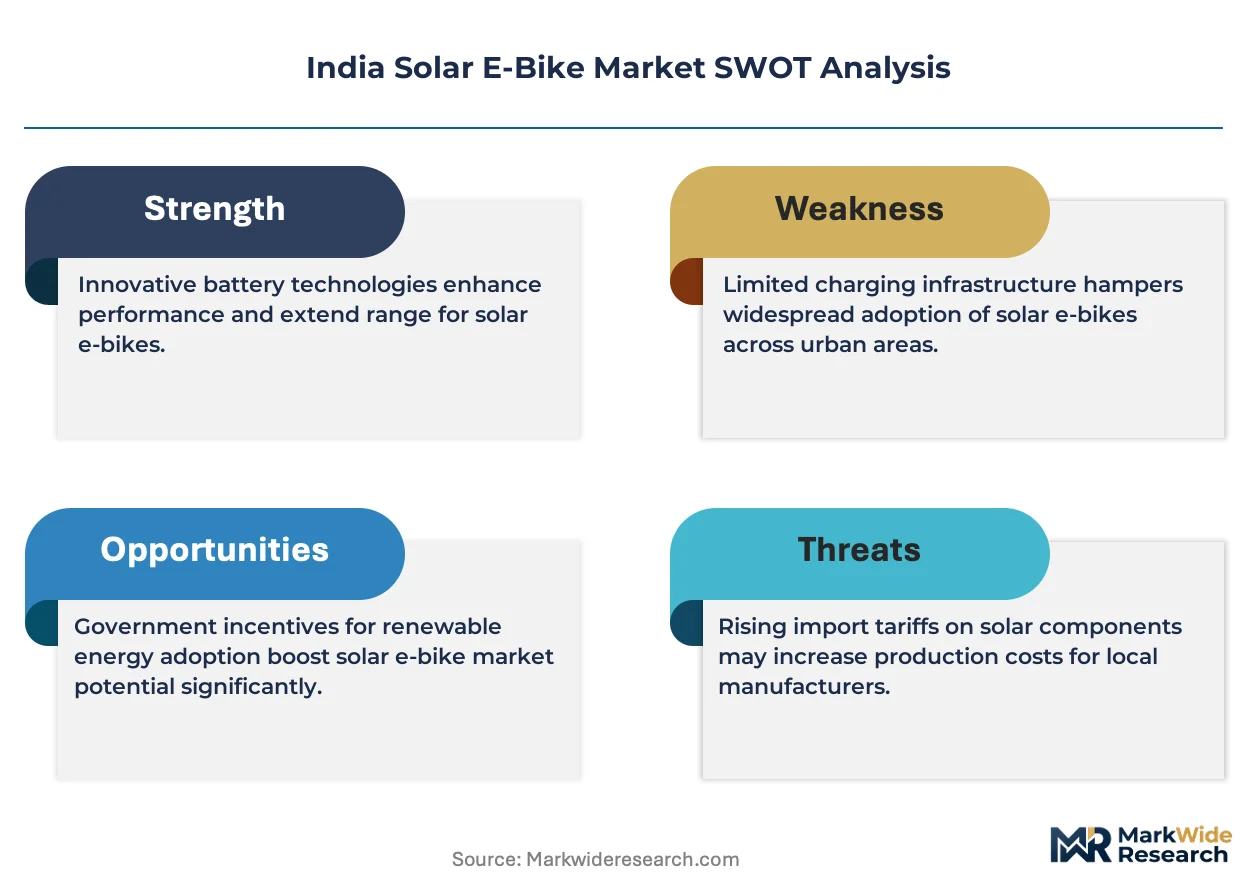
- Battery Input Cost Volatility:Lithium carbonate and cobalt price fluctuations from concentrated South American and African supply corridors compress margin predictability for domestic pack assemblers.
- Technical Limitation:Tropical high-temperature climates degrade lead-acid cycle life, forcing premium lithium-ion positioning that prices out rural mass-market segments.
- Regulatory Friction:BIS certification requirements for electric vehicle batteries and CEA grid-interconnection standards for AC charging infrastructure extend product launch timelines by 8-14 months.
Strategic Opportunities
- Tier 2 and Tier 3 Urban Penetration:Direct-to-consumer platforms are opening distribution white space in cities like Indore, Lucknow, and Kochi where dealership networks remain underdeveloped.
- Delivery Fleet Electrification Mandates:Municipal zero-emission zone proposals in Delhi NCR and Hyderabad are creating regulatory pull for solar-assisted fleet procurement by logistics aggregators.
- Technology Convergence:Integration of brushless DC hub motors with proprietary solar charge controllers optimized for tropical insolation patterns is enabling all-weather reliability claims.
Industry Challenges
- Certification Timeline Compression:State transport authorities in Maharashtra and Karnataka enforce distinct subsidy documentation requirements that fragment go-to-market execution and strain compliance teams.
- Technical Talent Scarcity:Shortage of power electronics engineers with photovoltaic-battery hybrid system expertise constrains R&D velocity for domestic original equipment manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Solar E-Bike Market |
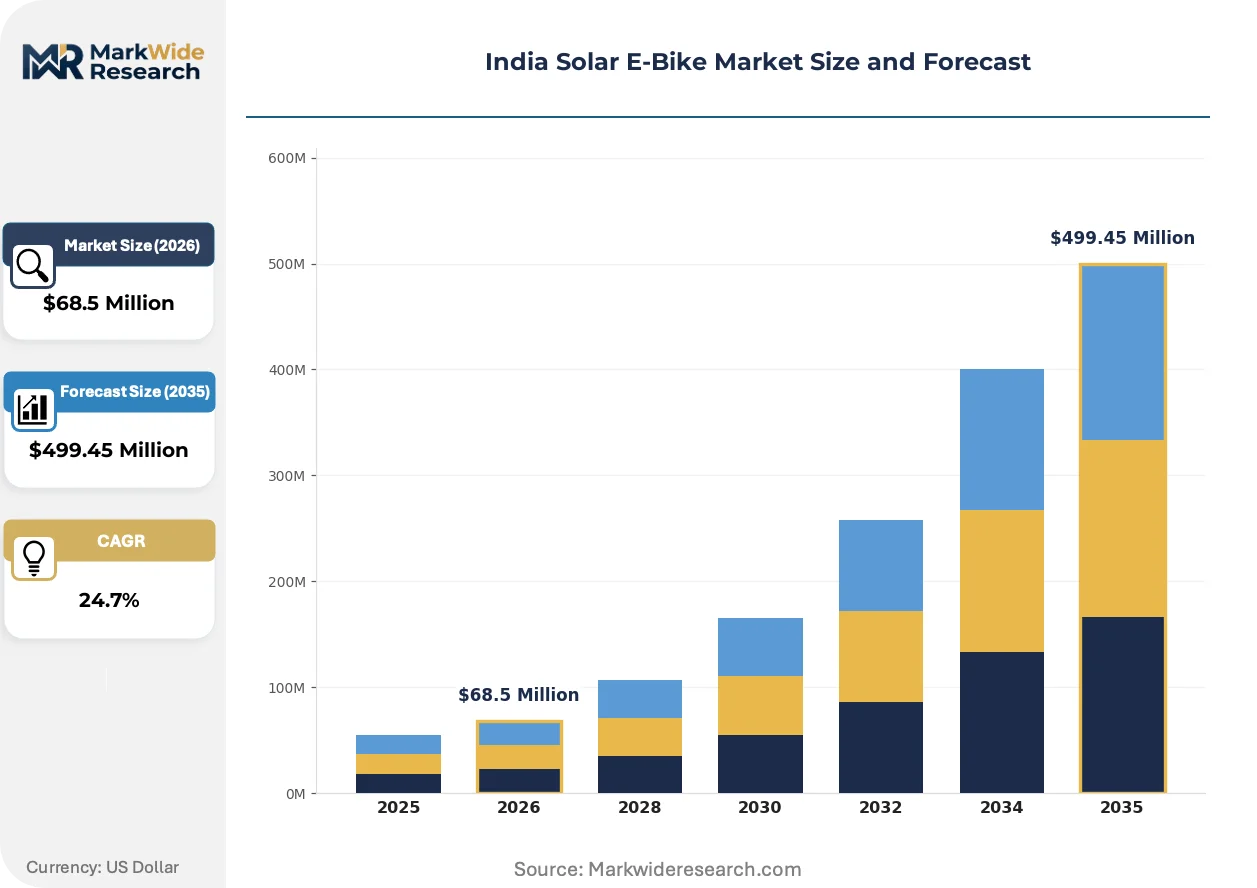
| Market Size in 2026 | $68.5 Million |
| Market Size in 2035 | $499.45 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-ion, Lead-acid, Nickel Metal Hydride, Solid State Motor Type: Brushless DC, Hub Motor, Mid-drive, Gear Motor End User: Commuters, Delivery Services, Leisure Riders, Fleet Operators Charging Method: Solar Panel Charging, AC Charging, Regenerative Charging, Standard Charging |
| Companies Covered | EMotorad, Hero Lectro E-Cycles, Elecson, Ninety One Cycles, Lekeamp, SK Ebicycle, Stryder Cycle, Toutche Electric, Virtus Motors, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Solar E-Bike Market Trends and Innovations
Photovoltaic-battery hybrid architectures are digitizing powertrain control systems and enabling real-time energy flow optimization that was previously mechanically governed.
Solar charge controller firmware is digitizing energy harvesting decisions across brushless DC powertrains, allowing hub motors to switch seamlessly between photovoltaic, battery, and regenerative inputs. Fleet operators in Bangalore are adopting these systems fastest, drawn by fuel cost elimination. The technology is digitizing maintenance scheduling by enabling predictive diagnostics on motor controller health.
The PLI scheme disbursement velocity is accelerating domestic cell manufacturing scale-up, reducing import dependency for lithium-ion cathode materials. Cell producers must now align with BIS safety standards and CEA grid codes to qualify for incentive tranches. Maharashtra-based pack assemblers are responding by consolidating testing partnerships with accredited laboratories to compress certification cycles.
Direct fleet procurement by delivery aggregators is compressing traditional dealership intermediation, unbundling after-sales service from initial hardware margins. Zomato and Swiggy franchisees in Mumbai now negotiate volume contracts directly with assemblers, bypassing Hero Cycles' 400-town network. This channel shift is most visible in Karnataka, where state EV policy registration waivers reduce paperwork friction for bulk fleet registration.
India Solar E-Bike Market Segmentation
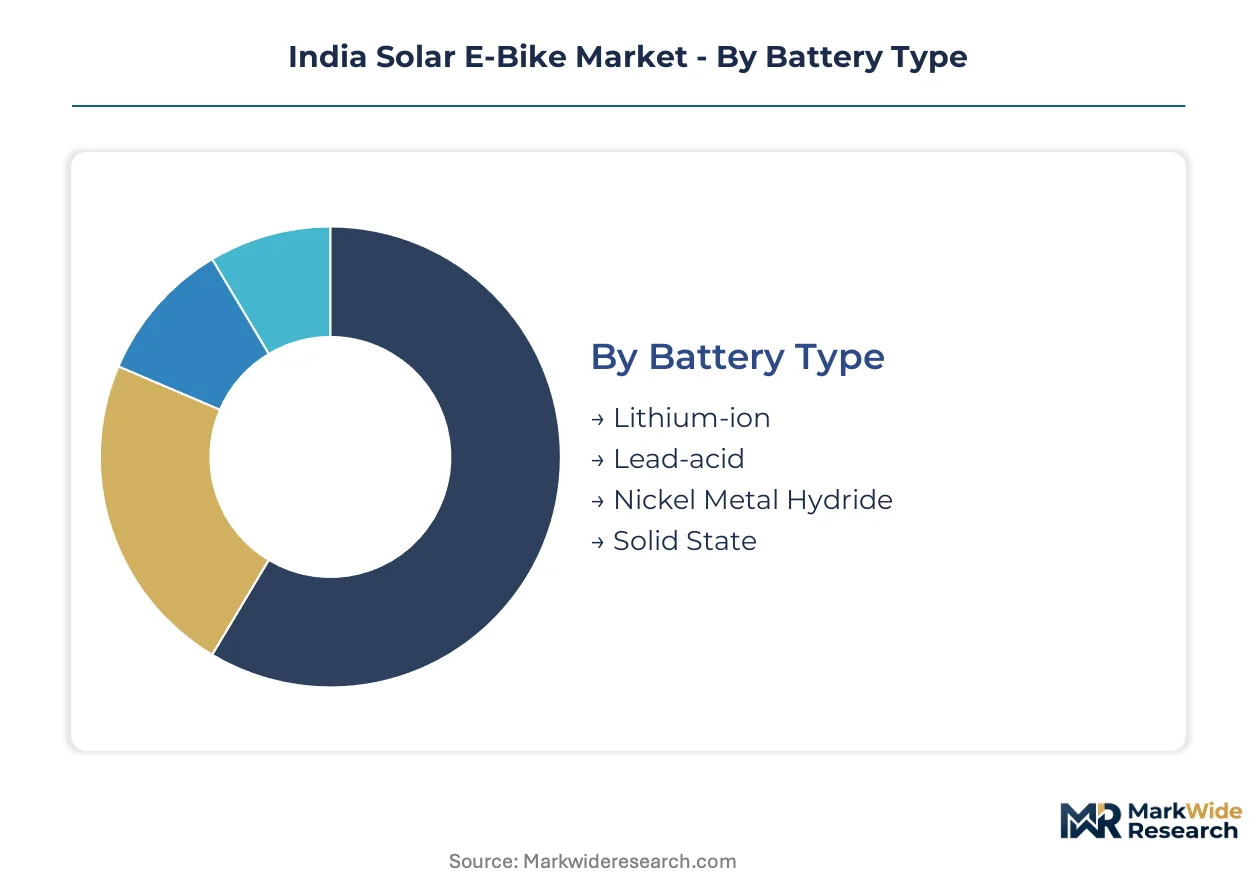
Segmentation in the India solar e-bike market reveals how powertrain configuration and end-use application determine pricing tiers, distribution channels, and regulatory compliance pathways across Maharashtra, Karnataka, and Tamil Nadu. Battery chemistry and motor architecture choices directly influence total cost of ownership calculations for fleet operators versus individual commuters.
Battery Type:
The use-case spectrum spans from premium lithium-ion packs for high-utilization delivery fleets to cost-optimized lead-acid alternatives for occasional rural commuters.
- Lithium-ion:Superior energy density and extended cycle life in tropical climates support 15-30 kilometer range extensions from integrated solar panels. Demand concentrates among Swiggy and Zomato franchisees in Bangalore and Mumbai where daily utilization rates exceed 100 kilometers and downtime minimization justifies premium pack costs.
- Lead-acid:Lower upfront acquisition costs attract price-sensitive individual commuters in Tier 2 cities, though high-temperature degradation accelerates replacement cycles and elevates lifetime costs. Maharashtra state EV subsidies partially offset this penalty through registration fee waivers.
- Nickel Metal Hydride:Intermediate positioning offers moderate temperature tolerance for leisure riders in coastal Tamil Nadu where humidity corrosion risks complicate lithium-ion storage.
- Solid State:Emerging chemistry promises enhanced safety profiles for future fleet deployments, with PLI scheme disbursements accelerating domestic cell manufacturing scale-up to reduce import dependency.
Established volume favors Lithium-ion; emerging adoption favors Solid State.
Motor Type:
Powertrain architecture selection tracks directly against terrain demands and load-carrying requirements across India's diverse urban and semi-urban environments.
- Brushless DC:Electronic commutation eliminates mechanical wear, reducing maintenance burden for high-mileage delivery operators in Hyderabad's expanding zero-emission zones. Integration with proprietary solar charge controllers enables seamless switching between photovoltaic and battery inputs.
- Hub Motor:Direct wheel integration simplifies drivetrain complexity for commuter-focused models distributed through EMotorad's direct-to-consumer platform in Indore and Lucknow. Compact packaging preserves frame geometry for rooftop panel mounting.
- Mid-drive:Centralized mass distribution improves handling stability for loaded cargo applications in Kerala's hilly terrain where torque multiplication through the drivetrain offsets motor weight penalties.
- Gear Motor:Mechanical advantage systems address steep gradient challenges in Pune's Sahyadri foothill suburbs, though added friction reduces solar-assisted range extension efficiency.
Hub Motor dominates unit shipments; Brushless DC is climbing the fastest on fleet electrification momentum.
End User:
Customer archetype segmentation determines channel strategy, with direct procurement compressing traditional dealership intermediation for high-volume accounts.
- Commuters:Fuel cost sensitivity among urban office workers in Delhi NCR drives demand for solar-assisted range extension to eliminate workplace charging dependency. Individual purchasers respond to state-level road tax exemptions.
- Delivery Services:Swiggy and Zomato franchisees negotiate volume contracts directly with assemblers, bypassing Hero Cycles' 400-town network to capture zero-fuel-cost unit economics in Mumbai and Bangalore.
- Leisure Riders:Weekend recreational use in Goa and Kerala hill stations prioritizes aesthetic integration of detachable solar panels over maximum range specifications.
- Fleet Operators:Municipal logistics contracts in Chennai and Hyderabad require standardized maintenance protocols and predictive diagnostics enabled by digitized motor controller health monitoring.
Commuters anchor current installed base; Delivery Services represent the steepest expansion trajectory.
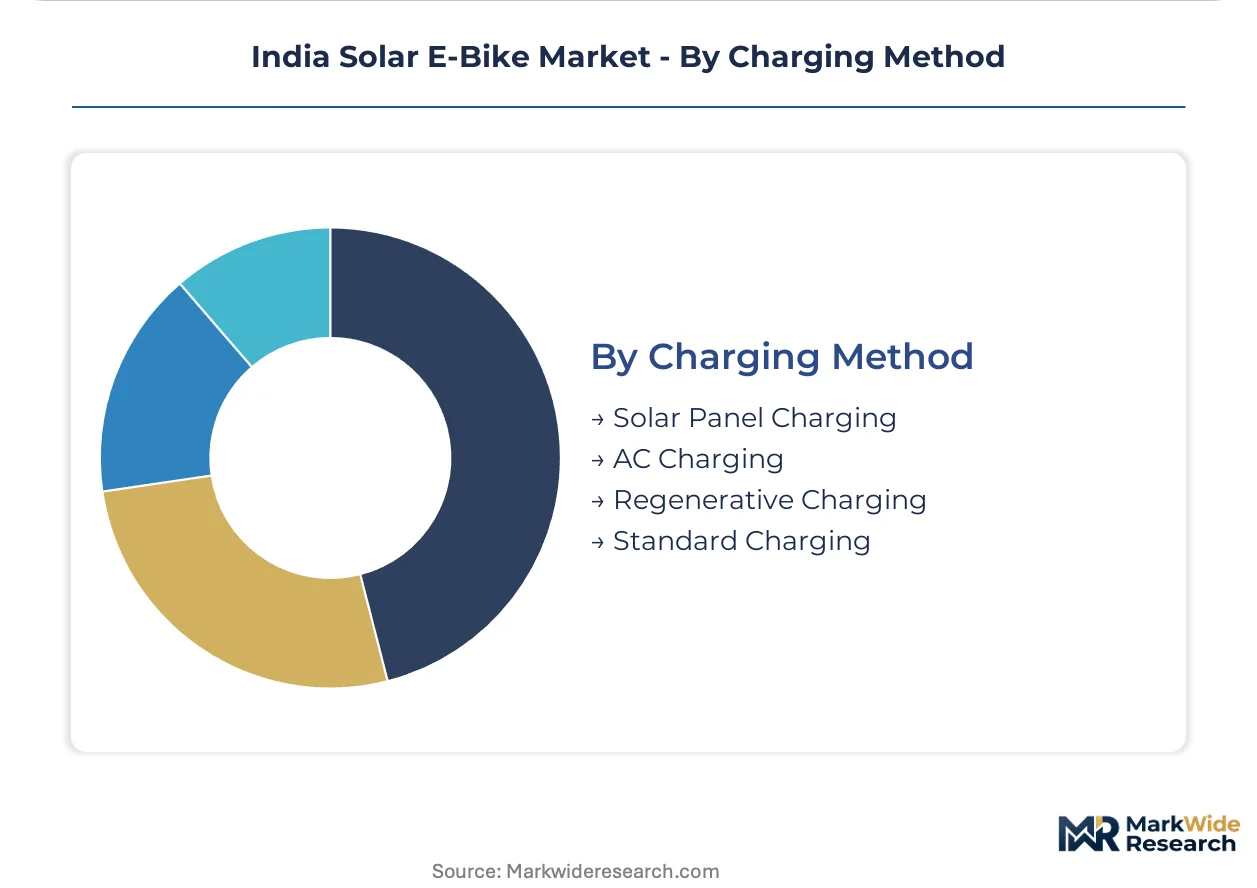
Charging Method:
Energy input modality selection reflects infrastructure availability constraints and operational flexibility requirements across India's uneven grid reliability landscape.
- Solar Panel Charging:Rooftop and detachable 20-50 watt photovoltaic arrays extend single-charge range 15-30 kilometers beyond grid-dependent alternatives, critical for riders in Tamil Nadu's semi-urban periphery where power outages disrupt AC charging schedules.
- AC Charging:Grid-connected overnight charging dominates urban apartment dweller behavior in Pune and Ahmedabad, though CEA interconnection standards extend product launch timelines 8-14 months.
- Regenerative Charging:Kinetic energy recovery during braking complements solar input in stop-and-go Bangalore traffic, though efficiency gains remain modest on flat terrain.
- Standard Charging:Basic plug-in alternatives persist in rural markets where solar panel acquisition costs exceed household willingness-to-pay despite BIS certification requirements for battery safety.
AC Charging maintains volume leadership; Solar Panel Charging is gaining share fastest on last-mile delivery fleet procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian solar e-bike manufacturers supply domestic demand concentrated across western and southern state clusters where state EV policies compress total cost of ownership for fleet operators and individual commuters.
Maharashtra
Last-mile delivery aggregators in Mumbai and Pune anchor procurement volumes as Swiggy and Zomato franchisees eliminate fuel expenditure from unit economics. The state transport authority enforces distinct subsidy documentation requirements that extend registration processing timelines. Nashik-based pack assemblers consolidate testing partnerships with BIS-accredited laboratories to compress certification cycles for lithium-ion battery systems.
Karnataka
Bangalore's expanding zero-emission zone proposals create regulatory pull for solar-assisted fleet procurement by logistics operators. State EV policy registration fee waivers reduce paperwork friction for bulk fleet registration compared to neighboring jurisdictions. Hubli-Dharwad corridor manufacturers leverage the state's electronics manufacturing cluster density to source brushless DC motor controllers.
Tamil Nadu
Semi-urban periphery riders prioritize solar panel charging to circumvent grid reliability disruptions that interrupt AC charging schedules. The state road tax exemption structure favors individual commuters over fleet operators, skewing demand toward leisure and office-worker segments. Coimbatore's precision engineering ecosystem supports mid-drive motor fabrication for hilly terrain applications in Kerala-border districts.
Telangana
Hyderabad municipal logistics contracts require standardized maintenance protocols that favor digitized motor controller health monitoring systems. State transport authorities coordinate with CEA on grid-interconnection standards for AC charging infrastructure deployment across apartment complexes. Warangal-based assemblers target Tier 2 city penetration through direct-to-consumer platforms bypassing traditional dealership networks.
Delhi-NCR
Urban office workers in Delhi and Gurugram drive commuter segment demand for solar-assisted range extension to eliminate workplace charging dependency. The National Capital Region's air quality mandates accelerate fleet electrification timelines for delivery services operating across Noida and Faridabad. Ghaziabad pack integrators face compressed margin predictability from lithium carbonate price volatility originating in South American supply corridors.
India Solar E-Bike Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a fragmented vendor base where no single entity commands dominant share. The market structure tiers between established cycle manufacturers leveraging vast dealership networks and direct-to-consumer platforms opening distribution white space in underserved cities. Two strategic archetypes dominate: legacy bicycle brands with manufacturing scale advantages, and technology-focused entrants with proprietary solar charge controller firmware. Competitive moves concentrate on geographic expansion into Tier 2 and Tier 3 urban centers and technology licensing partnerships to accelerate photovoltaic-battery hybrid system development.
Within the legacy manufacturer tier, Hero Lectro E-Cycles occupies a position exemplifying established cycle brand extension into electrified product lines. Among technology-specialist entrants, EMotorad and Toutche Electric represent direct-to-consumer platform strategies that bypass traditional intermediation. These three entities anchor the competitive spectrum between scale-driven distribution control and innovation-focused product differentiation in the Indian solar e-bike market.
| Leading Market Players |
|---|
| EMotorad |
| Hero Lectro E-Cycles |
| Elecson |
| Ninety One Cycles |
| Lekeamp |
| SK Ebicycle |
| Stryder Cycle |
| Toutche Electric |
| Virtus Motors |
| Others |
Pricing and Supply Chain Analysis
The Mumbai-JNPT freight corridor's volatile container rates compress landed costs for lithium-ion cathode materials while simultaneously amplifying price differentiation between domestically assembled and fully imported solar e-bike systems. This logistics chokepoint concentrates procurement power among Maharashtra-based pack integrators who negotiate volume contracts with Bangalore fleet operators.
Pricing Analysis
Lead-acid to lithium-ion to solid-state battery generations command widening price spreads as thermal degradation risks and cycle life advantages stratify positioning. Three-tier pricing structure across premium lithium-ion, standard lead-acid, and economy refurbished tiers reflects BIS certification grade and volume procurement scale. Pricing pressure stems from lithium carbonate volatility originating in South American supply corridors. Individual commuters in Tier 2 cities exhibit highest price sensitivity, while Swiggy franchisees prioritize total cost of ownership over upfront acquisition.
Supply Chain Analysis
Tariff exposure between China and India dominates supply chain risk calculations for photovoltaic panel imports and brushless DC motor controllers. Manufacturing concentrates in China for solar cells, South Korea for lithium-ion cells, and domestic Maharashtra-Karnataka corridors for final assembly. Raw material dependencies span lithium carbonate, cobalt, and polysilicon wafers. Single-source vulnerability for advanced chemistry cells threatens production continuity. Distribution runs through direct-to-consumer platforms and Hero Cycles' 400-town dealership network.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Power electronics engineers with photovoltaic-battery hybrid expertise remain scarce across Indian manufacturing clusters, constraining R&D velocity and compressing product development timelines for domestic original equipment manufacturers.
For Market Incumbents: Harden certification capabilities by consolidating BIS-accredited laboratory partnerships in Nashik and Pune to compress battery safety testing cycles. Defend against direct-to-consumer platform encroachment by locking exclusive service agreements with Zomato franchisees in Mumbai. Vertical integration into solar charge controller firmware development protects margin structure from technology licensing costs. For New Entrants and Emerging Players: Tier 3 cities in Madhya Pradesh and Uttar Pradesh present underpenetrated distribution white space where EMotorad's direct-to-consumer model has established proof points. Target Indore and Lucknow commuter segments with detachable solar panel configurations optimized for workplace parking exposure. Deploy mobile service vans to bypass dealership infrastructure gaps. For Investors and Strategic Acquirers: Carve-out targets emerge from Hero Cycles' non-core electrification assets and regional battery pack assemblers seeking scale capital. Long-term viability hinges on PLI scheme disbursement velocity and state EV policy renewal continuity. Monitor CEA grid-interconnection standard revisions as inflection signals for AC charging infrastructure investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Solar Charge Controller Development | Toutche Electric's firmware optimization for tropical insolation patterns enables all-weather reliability claims. |
| Direct Fleet Procurement Contracts | Volume negotiations with Swiggy and Zomato franchisees bypass traditional dealership intermediation in Bangalore. |
| BIS Certification Consolidation | Maharashtra-based pack assemblers compress testing timelines through accredited laboratory partnerships. |
| Tier 2 and Tier 3 Distribution Expansion | EMotorad's platform opens white space in Indore, Lucknow, and Kochi beyond Hero Cycles' network. |
| PLI Scheme Alignment for Cell Manufacturing | Domestic advanced chemistry cell scale-up reduces import dependency for lithium-ion cathode materials. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of BIS certification databases, CEA grid-interconnection standards, and state EV policy documentation. Primary interviews engaged product managers at EMotorad and Hero Lectro E-Cycles, procurement leads at Swiggy and Zomato franchisee operations, BIS-accredited laboratory directors in Maharashtra, and state transport authority officials in Karnataka and Tamil Nadu. Secondary sources included PLI scheme disbursement records, customs import data for lithium-ion cells, and vehicle registration statistics from regional transport offices. Bottom-up unit shipment estimates triangulate against top-down market value calculations.
Forecast inputs span battery chemistry adoption curves, motor architecture preferences across terrain types, and end-user segment growth rates over the projection horizon. Segmentation dimensions modeled include battery type, motor configuration, end-user archetype, and charging method alongside regional policy incentive intensity. CAGRs derive from logistic diffusion curves fitted to historical EV adoption patterns and fleet electrification mandate timelines. Industry-specific inputs incorporate tropical climate degradation coefficients for lead-acid cycle life and solar insolation variability across monsoon regions.
Practitioners should monitor lithium carbonate price volatility, state EV subsidy renewal cycles, and municipal zero-emission zone implementation for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
North America E-Bike Market
Electric Vehicles
Wireless Electric Vehicle Charging Market
Electric Vehicles
Speed Pedelec E-Bike Market
Electric Vehicles
Electric Van Market
Electric Vehicles
Asia-Pacific Electric Bus Battery Pack Market
Electric Vehicles
Electric Vehicle Regenerative Braking System Market
Electric Vehicles
Self Balancing Electric Scooter Market
Electric Vehicles
Germany Automotive High Performance Electric Vehicles Market
Electric Vehicles
Asia Pacific Electric Scooter Market
Electric Vehicles
Hybrid EV Conversion Kit Market
Electric Vehicles
One Wheel Electric Scooter Market
Electric Vehicles
EV Condenser Market
Electric Vehicles
Japan Solar E-Bike Market
Electric Vehicles
Two-Wheeled Electric Vehicle Battery Market
Electric Vehicles
E-Bike Lithium-Ion Battery Market
Electric Vehicles
India E-Bike Market