
 UK Electric Commercial Vehicle Battery Pack Market | 2026-2036
UK Electric Commercial Vehicle Battery Pack Market Size, Share, and Industry Trends Forecast 2026-2036
UK Electric Commercial Vehicle Battery Pack Market Insights
Cell-to-pack architecture is reshaping how battery systems integrate thermal management and structural support into commercial vehicle chassis. Contemporary Amperex Technology Co. Ltd. leverages its cylindrical cell expertise to anchor supply relationships with UK-based van assemblers. LG Energy Solution Ltd. competes through pouch-format specialization optimized for double-deck electric bus configurations. Hyperbat navigates domestic content requirements by operating a UK manufacturing footprint that sustains local assembly credibility.
The UK Electric Commercial Vehicle Battery Pack comprises electrochemical cells assembled into modules with battery management systems, thermal regulation hardware, and structural enclosures rated for commercial duty cycles exceeding 150,000 kilometres. These systems power zero-emission propulsion for freight haulage, urban distribution, and passenger transport where payload capacity and route predictability define pack sizing. LFP chemistry dominates light-duty van applications where cost sensitivity and cycle longevity outweigh energy density requirements. Heavy-duty segments favor NMC formulations that maximize range for regional freight corridors. Fast charging infrastructure deployment concentrates margin pools around depot-based fleet operators rather than opportunistic public network users.
The UK's Office for Product Safety and Standards enforces battery safety certification under retained EU framework adaptations, while the Environment Agency governs end-of-life cell recovery obligations that shape pack design-for-recycling mandates. The Department for Transport's vehicle type approval process filters non-compliant suppliers from accessing fleet procurement channels. Stakeholders must monitor how post-Brexit regulatory divergence on carbon intensity benchmarking affects cross-border supplier qualification and domestic manufacturing subsidy eligibility.
Market Dynamics
Cell-to-pack architecture is compressing module assembly steps and redistributing thermal management responsibility to chassis integrators, forcing pack suppliers to renegotiate value capture with vehicle assemblers across England's logistics corridors.
Growth Catalysts
- Zero Emission Vehicle mandate:The UK's Department for Transport enforces escalating sales quotas for van and truck manufacturers, compelling fleet operators to accelerate diesel replacement programs in Greater London clean air zones.
- Depot charging infrastructure clusters:Warehouse operators in the Midlands logistics corridor are installing megawatt-scale charging arrays that enable heavy-duty battery pack sizing without range anxiety penalties.
- LFP chemistry maturation:Iron phosphate cell formulations now deliver cycle life exceeding commercial duty requirements at cost points that displace NMC in light-duty van applications.
Market Restraints
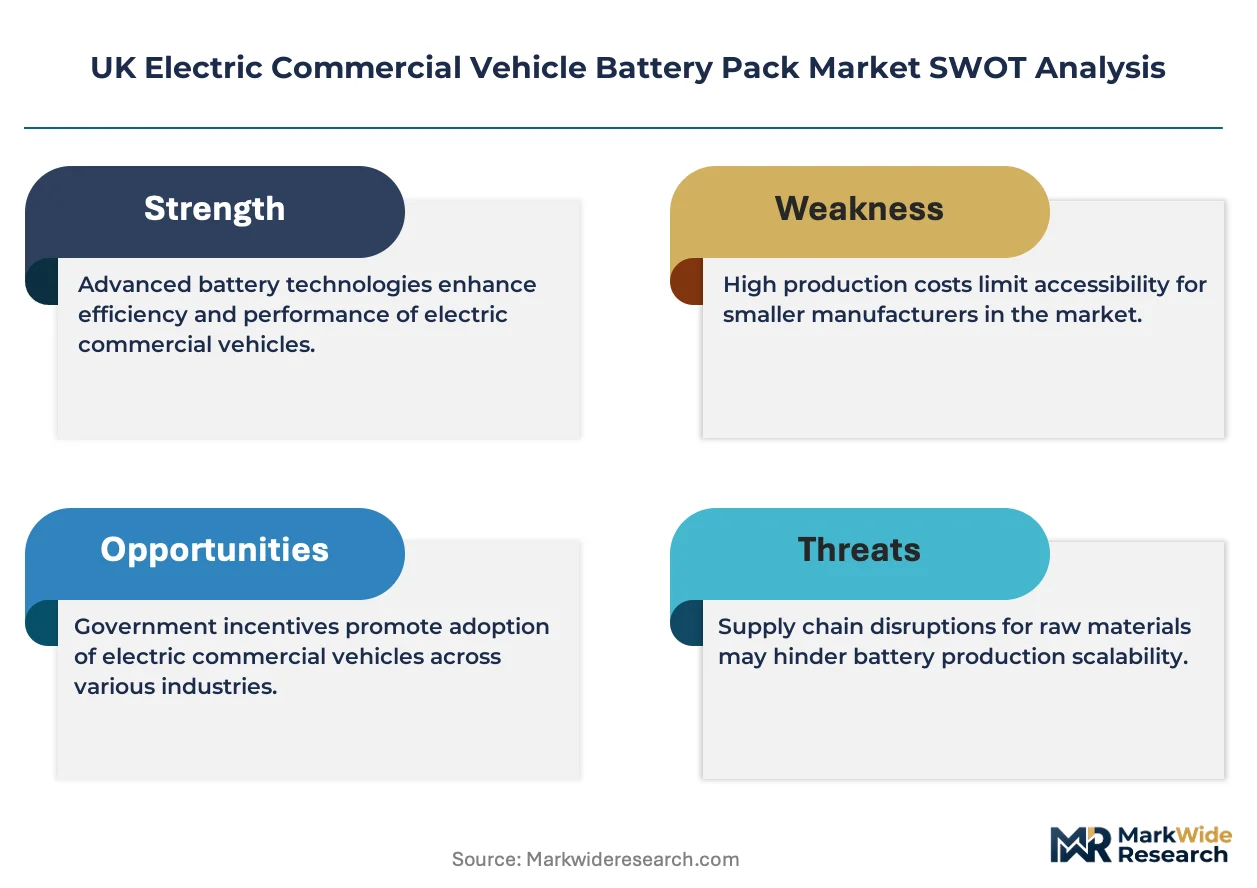
- Lithium carbonate volatility:Cathode active material costs swing with spot market pricing, compressing pack assembler margins and forcing indexed contract renegotiations with fleet buyers.
- Cell supply concentration:Cylindrical and prismatic cell production concentrates in East Asian manufacturing bases, exposing UK pack assemblers to shipping disruptions and currency fluctuation risks.
- Battery Passport compliance friction:EU-UK alignment protocols demand granular supply chain traceability that legacy ERP systems cannot populate without expensive middleware retrofits.
Strategic Opportunities
- Scottish freight corridors:Aberdeen and Inverness distribution networks remain underpenetrated by electric truck deployments, offering first-mover positioning for pack suppliers with cold-weather thermal management expertise.
- Second-life stationary storage:Retired commercial vehicle packs retain residual capacity suitable for grid balancing applications, creating circular revenue streams through utility partnerships.
- Wireless inductive charging:Dynamic charging embedded in roadway infrastructure is hybridizing with static depot systems to enable smaller pack sizing without compromising route flexibility.
Industry Challenges
- Battery management system firmware certification:The UK's Vehicle Certification Agency requires extensive validation cycles for safety-critical software updates, delaying pack variant launches by quarters.
- Thermal engineer scarcity:Pack suppliers compete with aerospace and data center cooling sectors for specialists capable of integrating liquid-cooled architectures into commercial vehicle chassis.
- End-of-life disassembly automation:The Environment Agency's recovery mandates demand pack designs compatible with robotic cell extraction, yet current adhesive bonding methods resist economical separation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Electric Commercial Vehicle Battery Pack Market |
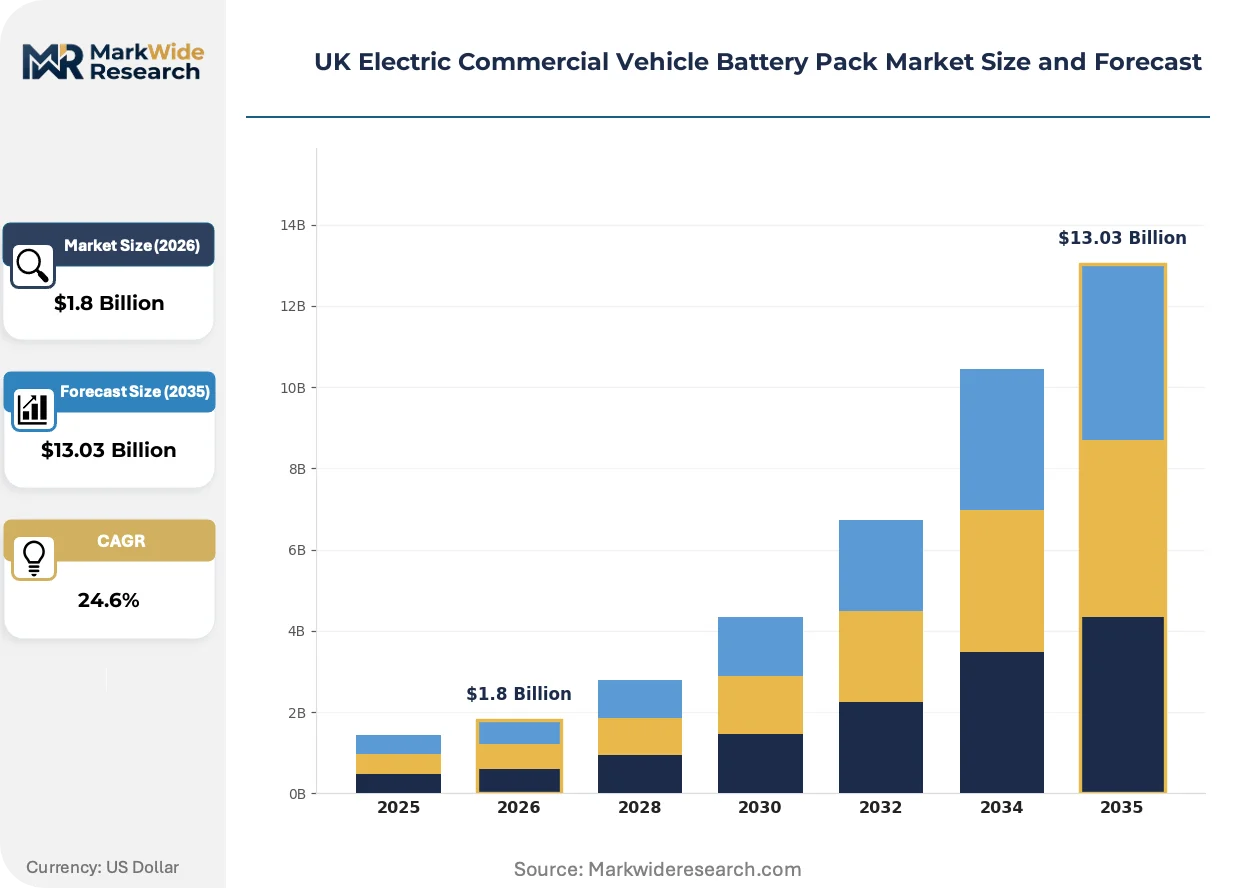
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $13.03 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: LFP, NMC, NCA, LTO Vehicle Type: Light Duty, Medium Duty, Heavy Duty, Bus Application: Urban Transport, Freight, Construction, Emergency Services Charging Infrastructure: Fast Charging, Standard Charging, Wireless Charging, Home Charging |
| Companies Covered | BYD Company Ltd., Contemporary Amperex Technology Co. Ltd., LG Energy Solution Ltd., Samsung SDI Co. Ltd., SK Innovation Co. Ltd., LEAPENERGY, Envision AESC, Hyperbat, Britishvolt, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Electric Commercial Vehicle Battery Pack Market Trends and Innovations
Electrification of commercial fleets is forcing convergence between automotive battery engineering and heavy-duty industrial power systems, dissolving traditional boundaries between passenger vehicle and commercial vehicle pack architectures.
Solid-state electrolyte research is hybridizing with conventional liquid cell manufacturing lines as pack suppliers pilot semi-solid hybrid formats that retain existing electrode coating equipment while improving energy density. Regional freight operators in England's East Midlands are trialing these transitional chemistries for double-shift routes where current NMC packs require midday charging interruptions. The structural consequence is a compression of the technology roadmap, with mid-decade pack refresh cycles now targeting full solid-state replacement rather than incremental NMC improvements.
The UK's retained EU battery safety framework, enforced by the Office for Product Safety and Standards, mandates thermal runaway propagation testing that exceeds UN ECE R100 requirements for commercial vehicle categories. This regulatory overlay is diverting engineering resources toward passive fire suppression systems and venting channel optimization rather than pure energy density gains. Heavy-duty truck assemblers serving cross-Channel routes are responding by specifying packs with ceramic separator layers and redundant cell monitoring circuits that anticipate future regulatory tightening.
Fleet procurement departments are consolidating battery pack sourcing through multi-year total-cost-of-ownership agreements that bundle charging infrastructure, maintenance, and residual value guarantees. This model is displacing transactional pack purchases and concentrating contract negotiation leverage with national logistics operators rather than regional fleet managers. The shift is most visible among grocery and parcel delivery consolidators operating from England's Midlands distribution hubs, where standardized pack specifications across van and truck categories enable volume-based supplier commitments.
UK Electric Commercial Vehicle Battery Pack Market Segmentation
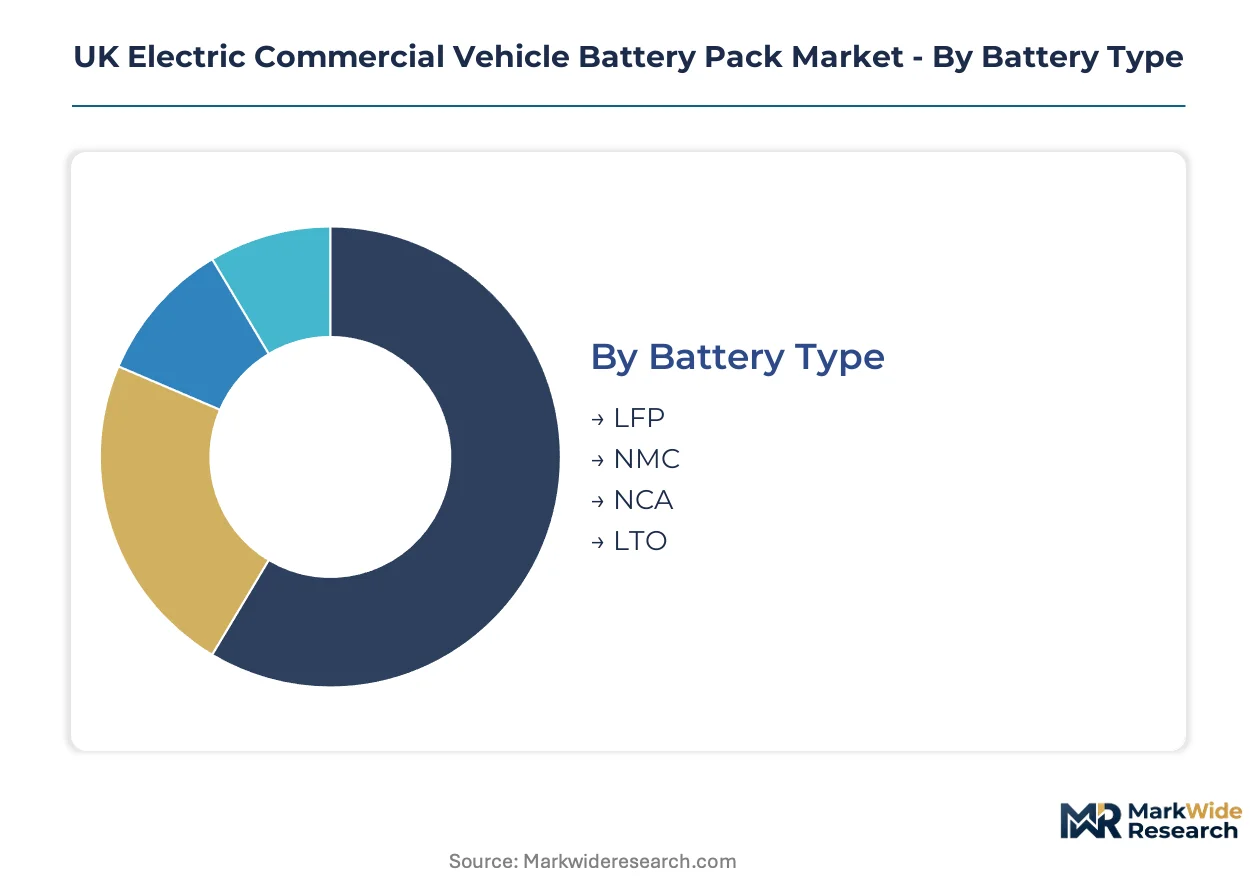
Segmentation in the UK Electric Commercial Vehicle Battery Pack Market reveals how duty cycles, depot infrastructure, and regulatory pressure differentially shape pack specifications across fleet categories. Understanding these divisions exposes where procurement leverage concentrates and which technology trajectories face compression from divergent cost and performance requirements.
Battery Type:
Cycle times for chemistry transitions vary sharply: LFP packs refresh every 5-7 years under standard van duty, while NMC architectures in heavy freight turn over faster as energy density improvements accelerate obsolescence.
- LFP:Iron phosphate cathodes deliver cycle life exceeding 4,000 charge events with thermal stability that reduces fire suppression hardware requirements. England's Midlands grocery delivery fleets specify these packs for predictable urban routes where depot charging eliminates range anxiety constraints.
- NMC:Nickel-manganese-cobalt formulations maximize gravimetric energy density for regional freight corridors spanning Greater London to Manchester logistics hubs, though cathode active material costs force indexed pricing clauses in fleet procurement contracts.
- NCA:Nickel-cobalt-aluminum cells occupy niche performance applications where specific energy prioritization outweighs cycle longevity trade-offs in premium express delivery segments.
- LTO:Lithium-titanate oxide anodes enable extreme fast-charging acceptance for bus rapid transit systems in Birmingham and Glasgow where dwell-time minimization dictates pack specification.
LFP dominates installed base through light-duty van penetration. NMC is where expansion concentrates as heavy-duty electrification accelerates.
Vehicle Type:
Cost tier separation runs deepest here: light-duty packs compete on total ownership cost against diesel equivalents, while heavy-duty systems command premium positioning through payload preservation engineering.
- Light Duty:Van-class packs under 100 kWh capacity integrate beneath cargo floors without intrusion into load space, with Greater London clean air zone enforcement driving replacement demand among final-mile parcel operators.
- Medium Duty:Rigid truck configurations serving regional distribution from Midlands hubs require 150-250 kWh systems balancing weight against 200-kilometre daily range requirements.
- Heavy Duty:Articulated tractor units for cross-Channel freight corridors demand 350+ kWh packs with liquid cooling architectures that maintain cell temperature across Alpine gradients.
- Bus:Double-deck and single-deck configurations in Transport for London fleets standardize on roof-mounted packs with opportunity charging compatibility at terminal stations.
Light Duty captures volume concentration through van fleet electrification mandates. Heavy Duty represents the steepest expansion trajectory as zero-emission truck regulations tighten.
Application:
Margin structure diverges by utilization intensity: continuous-duty freight applications amortize pack costs across higher annual mileage, while intermittent emergency services usage demands extreme reliability premiums.
- Urban Transport:Bus and coach electrification in English metropolitan areas operates on fixed-route predictability that enables precise pack sizing without overengineering for range buffers.
- Freight:Haulage operators along the M6 and M1 corridors negotiate multi-year pack-service bundles that integrate megawatt-scale depot charging infrastructure with residual value guarantees.
- Construction:Site vehicles and mixers in Scotland's infrastructure projects require ruggedized enclosures rated for vibration exposure and unimproved surface operation.
- Emergency Services:Police and ambulance fleets specify redundant cell monitoring and fault-tolerant architectures where propulsion failure carries operational-critical consequences.
Freight commands procurement scale through consolidated national logistics operator contracts. Urban Transport is where standardization pressure from municipal tendering concentrates supplier selection.
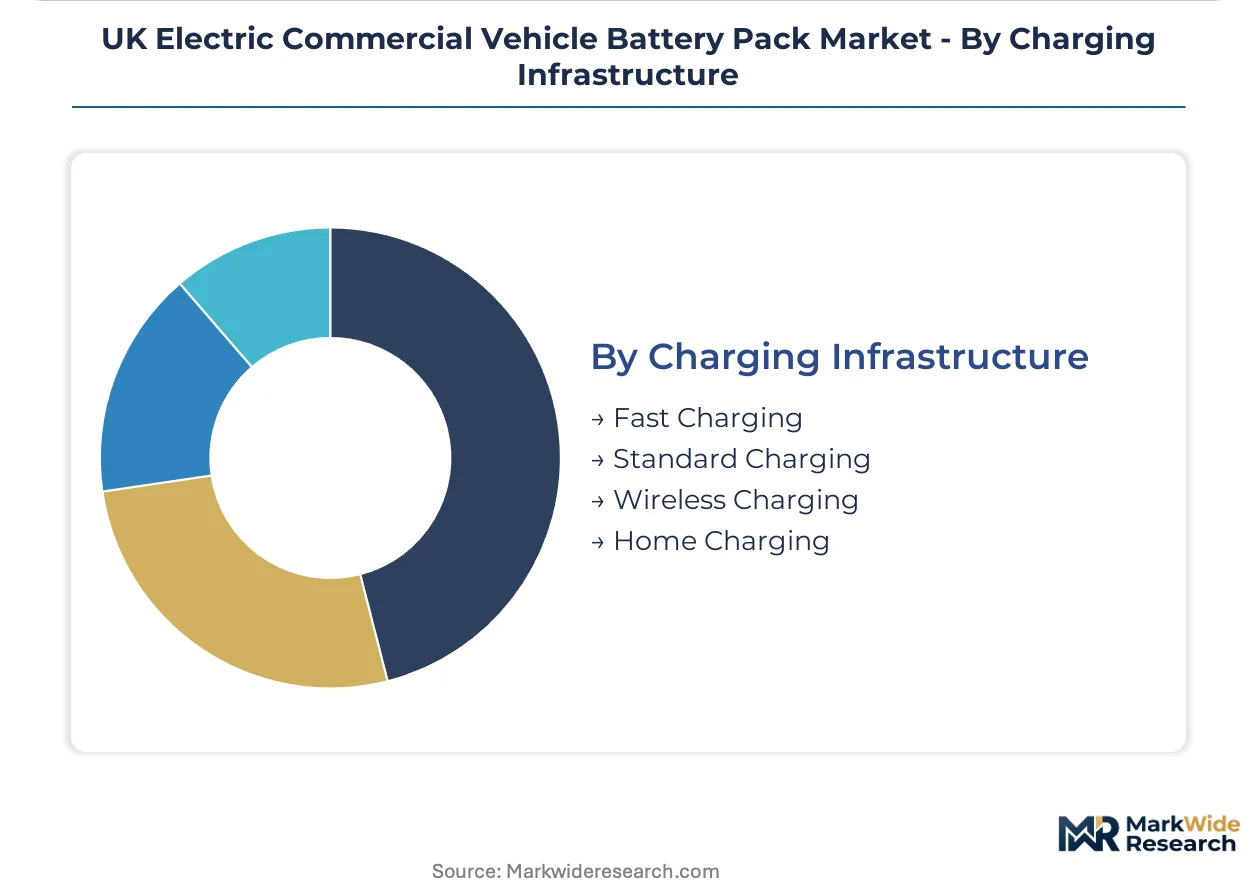
Charging Infrastructure:
Supply concentration for charging hardware reshapes pack design requirements: fast-charging network availability determines acceptable pack downsizing, while wireless pilot programs enable alternative range-extension strategies.
- Fast Charging:150+ kW DC infrastructure at Midlands distribution hubs permits smaller pack sizing for regional routes, though cell chemistry must tolerate elevated C-rates without accelerated degradation.
- Standard Charging:Overnight AC depot charging remains the dominant paradigm for van fleets with predictable return-to-base patterns, preserving battery longevity through gentle charge profiles.
- Wireless Charging:Inductive pads embedded in Birmingham bus station approaches and Manchester airport logistics roads enable opportunity charging that reduces required pack capacity.
- Home Charging:Single-phase AC limitations constrain this segment to sole-operator van businesses without depot access, representing a marginal addressable market.
Standard Charging anchors installed base through existing depot infrastructure. Fast Charging is gaining share fastest as fleet operators optimize asset utilization against charging downtime.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UK pack assemblers source cylindrical and prismatic cells from East Asian suppliers, creating trade-flow dependency through Rotterdam and Felixstowe ports. Domestic manufacturing capacity concentrates in England's industrial heartlands where vehicle assembly clusters anchor demand. Scotland and Wales present expansion corridors with distinct thermal and infrastructure requirements.
London and the Southeast
Transport for London's bus electrification mandate and Ultra Low Emission Zone enforcement drive pack demand for double-deck configurations. The Department for Transport's Zero Emission Vehicle mandate escalates van sales quotas that compress diesel replacement timelines. Depot charging infrastructure clusters around Dartford and Thurrock distribution hubs where grocery and parcel operators standardize on LFP architectures.
Midlands Logistics Corridor
Megawatt-scale charging arrays at Birmingham and Coventry distribution centers enable heavy-duty battery pack sizing without range penalties. The Office for Product Safety and Standards enforces retained EU battery safety certifications that filter non-compliant suppliers from fleet procurement channels. Cell-to-pack architecture adoption accelerates among van assemblers in the West Midlands automotive cluster.
North England Freight Networks
Manchester and Leeds distribution hubs negotiate multi-year pack-service bundles integrating charging infrastructure with residual value guarantees. The Environment Agency's end-of-life recovery obligations shape pack design-for-recycling mandates among suppliers serving cross-Pennine haulage routes. Heavy-duty electrification concentrates along the M62 corridor where regional freight operators trial NMC formulations for 200-kilometre daily ranges.
Scottish Distribution Corridors
Aberdeen and Inverness freight networks remain underpenetrated by electric truck deployments, offering positioning for suppliers with cold-weather thermal management expertise. Scotland's net-zero emissions target accelerates public procurement of electric buses in Glasgow and Edinburgh. Highland logistics operators specify packs with enhanced thermal insulation for sub-zero operating conditions.
UK Electric Commercial Vehicle Battery Pack Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: East Asian cell manufacturers with cylindrical and prismatic expertise, European specialists in pouch-format systems, and domestic pack assemblers navigating local content requirements. Market structure reflects tiered competition between scale-driven chemistry providers and chassis-integrated pack designers. Dominant competitive moves include strategic partnerships with vehicle assemblers and geographic expansion through co-located manufacturing footprints.
Among East Asian cell suppliers, Contemporary Amperex Technology Co. Ltd. and LG Energy Solution Ltd. exemplify the chemistry-specialist archetype, while Hyperbat occupies a position within the domestic integration tier. These anchors represent divergent approaches to value capture: cylindrical cell expertise versus pouch-format optimization versus UK manufacturing credibility. The competitive dynamic forces renegotiation of thermal management responsibility between pack suppliers and vehicle assemblers.
| Leading Market Players |
|---|
| BYD Company Ltd. |
| Contemporary Amperex Technology Co. Ltd. |
| LG Energy Solution Ltd. |
| Samsung SDI Co. Ltd. |
| SK Innovation Co. Ltd. |
| LEAPENERGY |
| Envision AESC |
| Hyperbat |
| Britishvolt |
| Others |
Pricing and Supply Chain Analysis
Lithium carbonate spot volatility compresses pack assembler margins and forces indexed contract renegotiations with fleet buyers, determining both the spread between LFP and NMC pricing tiers and the geographic sourcing strategies UK assemblers deploy to hedge currency and shipping risks.
Pricing Analysis
The technology-generation pricing gap separates mature LFP architectures from next-generation semi-solid and solid-state formats under pilot deployment. Three-tier pricing structure across premium, standard, and economy levels stratifies by cell chemistry, thermal management complexity, and after-sales service bundling. Cost compression in light-duty van segments is intensifying because fleet procurement departments consolidate sourcing through multi-year total-cost-of-ownership agreements. Grocery and parcel delivery operators in England's Midlands exhibit highest price sensitivity, while emergency services fleets prioritize fault-tolerant architectures over unit economics.
Supply Chain Analysis
Upstream feedstock concentration in lithium spodumene mining and cathode active material refining centers on Australia, Chile, and China. UK pack assemblers draw from cylindrical and prismatic cell production anchored in South Korea, Japan, and China, with Rotterdam and Felixstowe ports serving as logistics chokepoints. Single-source vulnerability concentrates around East Asian cell supply, exposing assemblers to shipping disruptions and tariff exposure under post-Brexit trade protocols. Distribution runs through Tier 1 supplier relationships with West Midlands van assemblers and direct OEM contracts for heavy-duty truck configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK Electric Commercial Vehicle Battery Pack Market sits in a cyclical recovery phase as fleet electrification mandates compress diesel replacement timelines and depot charging infrastructure buildouts accelerate pack refresh cycles.
For Market Incumbents: Harden supply relationships with East Asian cell manufacturers through long-term offtake agreements indexed to lithium carbonate futures. Deepen backward integration into thermal management hardware production to capture value migrating from module assembly to chassis integration. The Department for Transport's Zero Emission Vehicle mandate escalation and Battery Passport compliance requirements threaten margin erosion for suppliers lacking ERP middleware capabilities. For New Entrants and Emerging Players: Establish a beachhead in Scotland's Aberdeen and Inverness freight corridors where cold-weather thermal management expertise remains scarce among incumbent suppliers. Target construction site vehicle applications in Highland infrastructure projects requiring ruggedized enclosures rated for vibration exposure and unimproved surface operation. Partner with Scottish public procurement channels for electric bus deployments in Glasgow and Edinburgh to secure reference installations. For Investors and Strategic Acquirers: The UK's Battery Passport requirements under EU-UK alignment protocols reshape the acquisition landscape by elevating traceability infrastructure from compliance cost to competitive moat. Five-to-ten-year viability hinges on pack assemblers demonstrating design-for-recycling compatibility with the Environment Agency's robotic cell extraction mandates. Target acquisition archetypes include domestic pack integrators with UK manufacturing footprints and established Vehicle Certification Agency validation histories. The signal to monitor is Environment Agency enforcement intensity on end-of-life recovery obligations as a proxy for regulatory tightening trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Cell-to-Pack Architecture Adoption | Compresses module assembly steps and redistributes thermal management responsibility to West Midlands chassis integrators. |
| Scottish Freight Corridor Expansion | Captures first-mover positioning in Aberdeen and Inverness distribution networks with cold-weather thermal management expertise. |
| Battery Passport Compliance Investment | Enables granular supply chain traceability that legacy ERP systems cannot populate without expensive middleware retrofits. |
| Second-Life Stationary Storage Partnerships | Creates circular revenue streams through utility partnerships for retired commercial vehicle packs with residual capacity. |
| Megawatt-Scale Depot Charging Integration | Enables heavy-duty battery pack sizing without range anxiety penalties for Midlands logistics corridor operators. |
Research Methodology
Cross-validation between fleet operator procurement directors and cell manufacturer supply chain executives anchors the qualitative findings. Primary interviews with vehicle certification engineers, thermal management specialists, depot charging infrastructure planners, and Environment Agency compliance officers combined with secondary validation against Department for Transport vehicle type approval records, Office for Product Safety and Standards certification databases, and customs trade flow data through Rotterdam and Felixstowe. Bottom-up pack shipment tallies triangulate against top-down fleet electrification mandate compliance trajectories.
Calibration against historical LFP and NMC chemistry transition cycles and van versus heavy-duty truck electrification penetration rates informs the analytical framework across the projection horizon. Segmentation dimensions modeled include battery chemistry, vehicle duty class, charging infrastructure type, and regional regulatory cluster. CAGRs derive from weighted average of technology adoption curves and fleet replacement cycle compression. Industry-specific forecast inputs incorporate Zero Emission Vehicle mandate quota trajectories and Battery Passport implementation timelines.
Sensitivities concentrate around lithium carbonate spot price volatility, post-Brexit regulatory divergence on carbon intensity benchmarking, and East Asian cell supply disruption scenarios. Forecasts reflect assumptions on depot charging infrastructure deployment pace and fleet operator consolidation patterns. Quarterly review of Vehicle Certification Agency validation queue lengths and Environment Agency recovery mandate enforcement intensity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle Relay Market
Electric Vehicles
Solar E-Bike Market
Electric Vehicles
Global Vehicle to Grid Technology Market
Electric Vehicles
Automotive EV HUB Market
Electric Vehicles
Electric Vehicle Insulation Market
Electric Vehicles
Mexico E-Bike Market
Electric Vehicles
Asia-Pacific Electric Vehicle Thermal Management System Market
Electric Vehicles
Battery-Swapping for Electric Two-Wheeler Market
Electric Vehicles
Spain Solar E-Bike Market
Electric Vehicles
North America Electric Truck Market
Electric Vehicles
Asia-Pacific Electric Bus Battery Pack Market
Electric Vehicles
Commercial Vehicle Traction Battery Systems Market
Electric Vehicles
Solar Golf Cart Market
Electric Vehicles
Oman EV Market
Electric Vehicles
Solar Car Market
Electric Vehicles
E-Bike Lithium-Ion Battery Market