
 Golf Cart Battery Market | 2026-2036
Golf Cart Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Golf Cart Battery Market Outlook
ISO 9001 quality management certification is reorganizing supplier eligibility for OEM contracts, pushing smaller assemblers toward third-party auditing. Trojan Battery Company leverages its deep-cycle expertise to sustain dominance in flooded lead-acid replacements. RELION Battery anchors its growth on lithium-ion chemistry for weight-sensitive retrofit applications.
Golf cart batteries are deep-cycle energy storage devices engineered for repeated discharge-recharge cycles at low current draw over extended periods, typically constructed with thick lead-antimony or lithium iron phosphate plates to withstand 50-80 percent depth of discharge without capacity degradation. Their primary commercial purpose is to power low-speed electric vehicles across golf courses, planned residential communities, and light industrial campuses where silent operation and minimal emissions outweigh highway performance requirements. Lithium-ion chemistry captures the fastest expansion as fleet operators prioritize reduced watering maintenance and longer cycle life, while lead-acid retains volume leadership in price-sensitive replacement channels. The voltage dimension shows 48V and 72V configurations gaining share as manufacturers design higher-torque drivetrains for hilly terrain and street-legal conversions.
The US EPA governs lead-acid battery recycling through the Battery Act, while OSHA mandates workplace ventilation standards during installation and maintenance procedures. These frameworks elevate compliance costs for distributors but simultaneously create barriers against uncertified imports. Stakeholders must track state-level low-speed vehicle classification rules, as reclassification would immediately expand addressable fleet populations beyond traditional golf course boundaries.
Market Dynamics
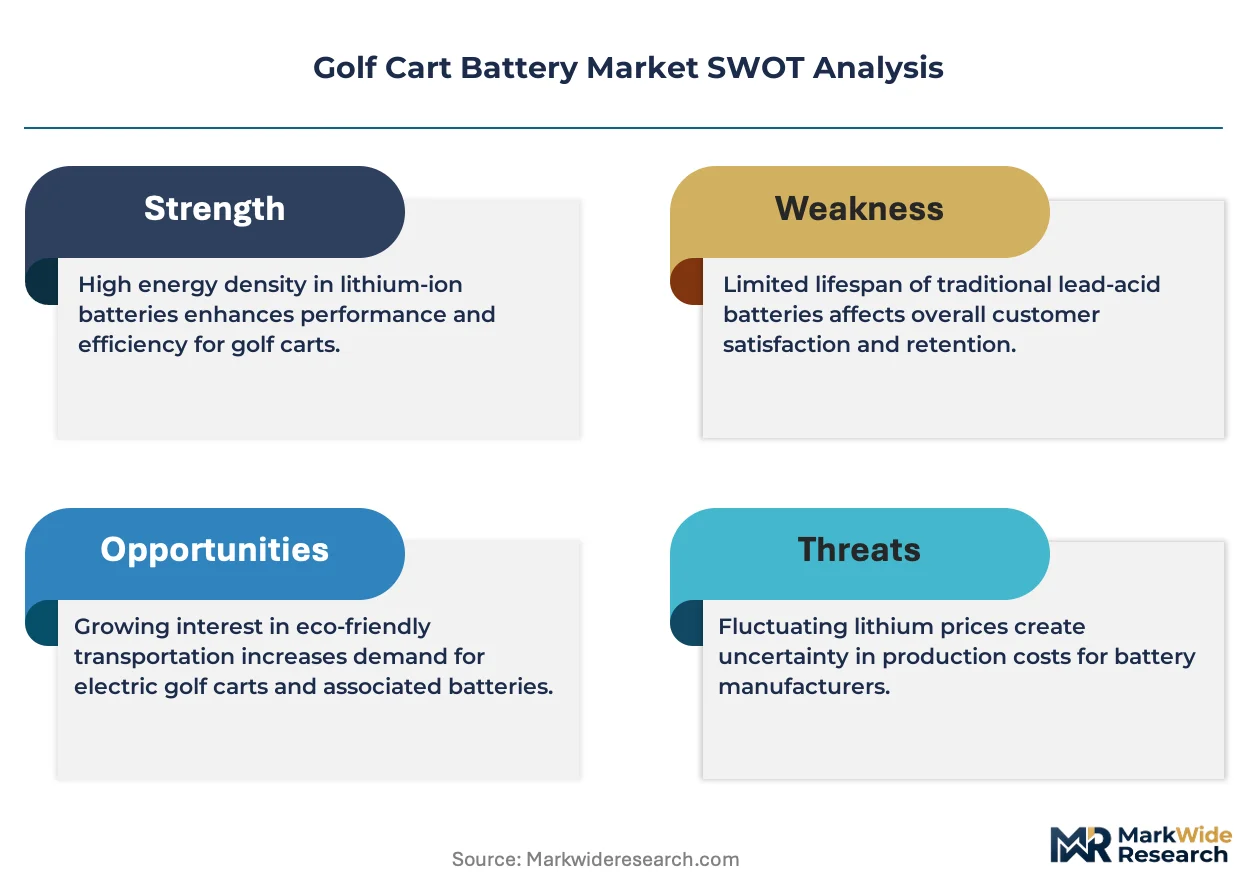
Fleet operators in Florida's planned communities and Arizona's retirement corridors are accelerating lithium-ion retrofits as watering maintenance costs compound and cycle-life economics invert the total-cost-of-ownership equation against flooded lead-acid.
Growth Catalysts
- Low-Speed Vehicle Reclassification:State transportation departments expanding street-legal access classifications multiply addressable fleet populations beyond golf course perimeters into neighborhood electric vehicle applications.
- OSHA Workplace Ventilation Mandates:Installation and maintenance procedure standards elevate compliance barriers against uncertified imports while favoring audited distributors with documented safety protocols.
- Lithium Iron Phosphate Chemistry:Superior depth-of-discharge tolerance and thermal stability enable weight-sensitive retrofit applications in hilly terrain configurations previously dominated by lead-acid.
Market Restraints
- Lead Price Volatility:Antimony and lead oxide input costs swing replacement channel pricing unpredictably, compressing margins for distributors serving price-sensitive aftermarket segments.
- Supply Concentration in East Asian Cell Production:Cylindrical and prismatic lithium cell manufacturing clusters create single-source vulnerability for North American pack assemblers lacking captive cathode supply.
- US EPA Battery Act Recycling Burden:Lead-acid end-of-life compliance costs and documentation requirements deter small-scale distributors from carrying legacy chemistry inventories.
Strategic Opportunities
- India Planned Community Electrification:Emerging golf resort developments and retirement township projects present first-mover positioning for lithium pack suppliers establishing local assembly partnerships.
- 48V and 72V High-Torque Drivetrains:Voltage architecture upgrades for street-legal conversions and hillside residential communities open premium retrofit pricing tiers.
- ISO 9001 Certification Arbitrage:Third-party auditing services capture value from smaller assemblers excluded from OEM contract eligibility under reorganized supplier qualification frameworks.
Industry Challenges
- Deep-Cycle Battery Technician Shortage:Specialized diagnostic and balancing expertise for lithium pack management systems outpaces vocational training program output in key retirement corridor markets.
- Multi-Chemistry Inventory Complexity:Distributors must simultaneously stock flooded, AGM, gel, and lithium variants across voltage configurations, straining working capital and warehouse space.
- State-by-State LSV Classification Fragmentation:Inconsistent safety equipment mandates and registration requirements force pack assemblers to maintain jurisdiction-specific product variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Golf Cart Battery Market |
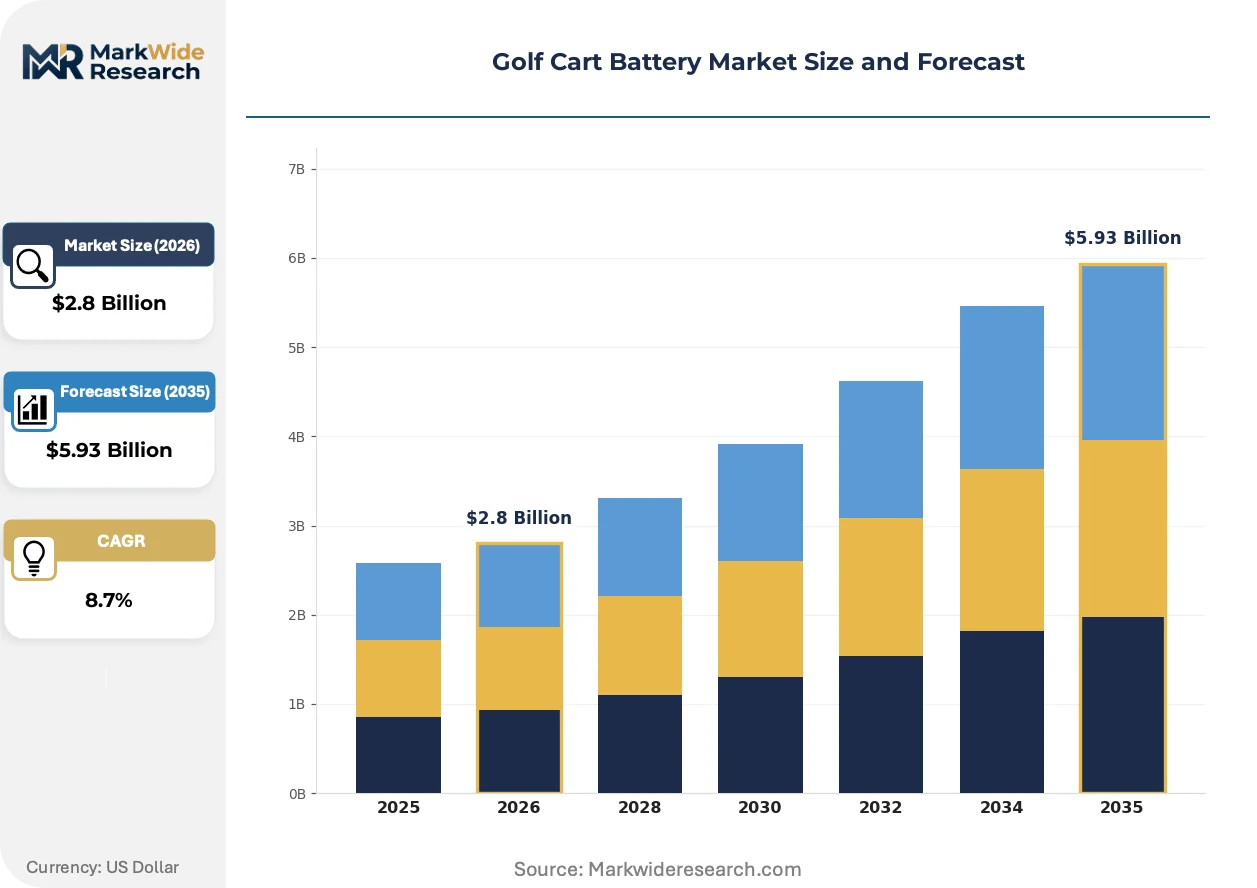
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lead-Acid, Lithium-Ion, Gel, AGM Application: Golf Courses, Residential Use, Commercial Use, Industrial Use Voltage: 6V, 8V, 12V, 36V Size: Small, Medium, Large, Custom |
| Companies Covered | Trojan Battery Company, Exide Technologies, Crown Battery Manufacturing, U.S. Battery, Interstate Batteries, Allied Battery, East Penn Manufacturing, RELION Battery, RoyPow Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Golf Cart Battery Market Strategic Shifts
Electrification of low-speed vehicle fleets is compressing technology replacement cycles and rewiring competitive advantage around chemistry selection and voltage architecture design capabilities.
Lithium iron phosphate cell technology is supplanting thick-plate lead-antimony constructions in deep-cycle applications requiring 50-80 percent depth-of-discharge tolerance. Resort fleet managers and retirement community operators are completing chemistry conversions within 18-24 month windows as watering labor costs accumulate. This transition is compressing aftermarket revenue pools for flooded lead-acid distributors while expanding service-contract attach rates for integrated battery management system providers.
REACH substance restrictions and RoHS compliance deadlines in Europe are tightening heavy metal content thresholds for battery imports and manufacturing residues. Industrial consequence includes accelerated phase-out of certain lead-acide formulations and reformulation investments by chemistry suppliers. Pack assemblers serving EU export markets are responding with dedicated product lines and enhanced material declaration documentation.
Buyer preference is consolidating around bundled energy-service contracts that unbundle battery asset ownership from vehicle procurement. Fleet operators in Florida's planned communities are replacing capital expenditure models with per-mile or per-cycle operating agreements. This restructuring is most visible in retirement corridor markets where predictable utilization patterns enable accurate residual value forecasting.
Golf Cart Battery Market Segmentation
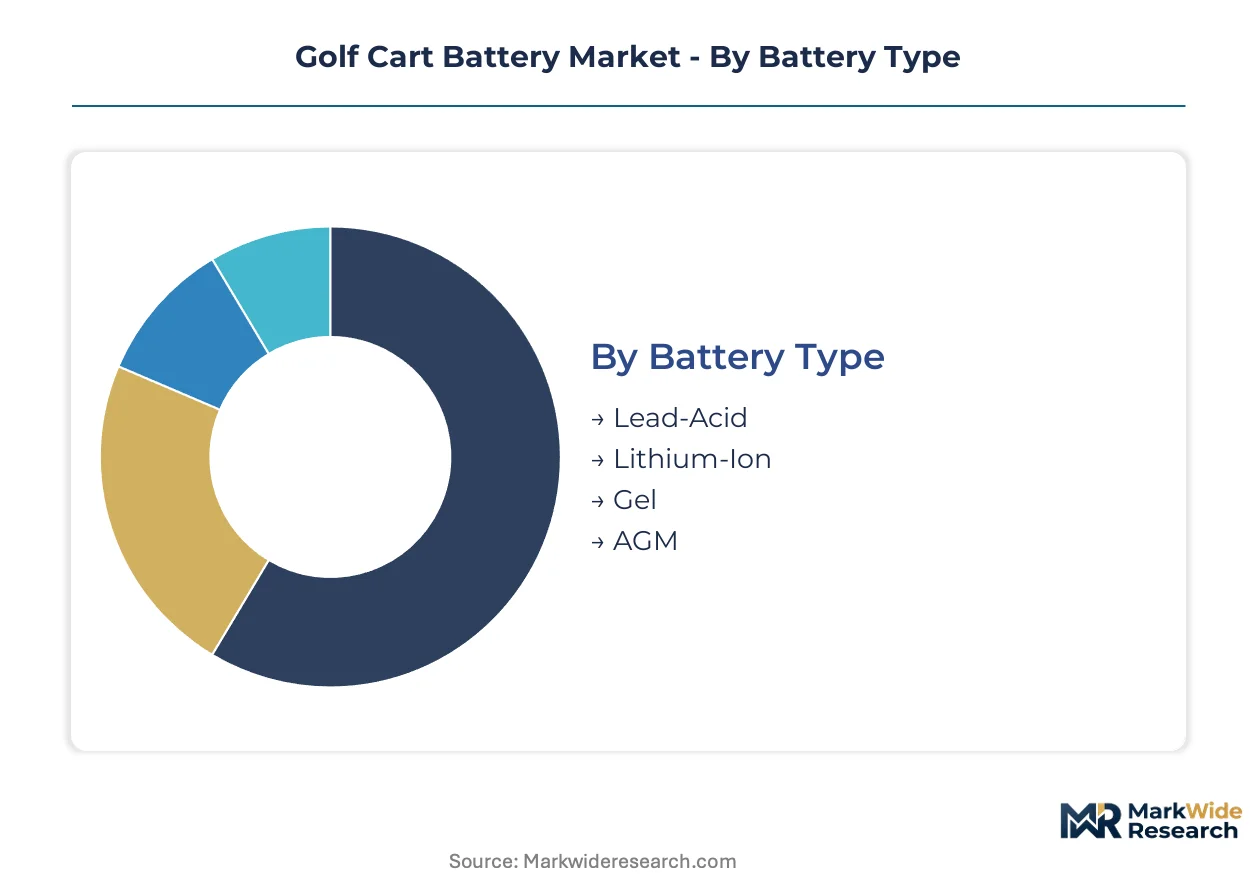
Golf cart battery procurement decisions split across chemistry durability, voltage architecture, and fleet duty cycles. Each segmentation axis carries distinct compliance footprints and total-cost-of-ownership profiles that reshape supplier qualification requirements.
Battery Type:
US EPA Battery Act recycling mandates and OSHA ventilation standards create divergent compliance burdens across electrochemical formulations, favoring distributors with documented safety protocols.
- Lithium-Ion:Lithium iron phosphate cells deliver 50-80 percent depth-of-discharge tolerance without capacity degradation. Fleet operators in Florida's planned communities and Arizona's retirement corridors accelerate retrofits as watering labor costs compound and cycle-life economics invert ownership calculations.
- Lead-Acid:Flooded lead-antimony constructions with thick plates dominate price-sensitive replacement channels. Antimony and lead oxide input cost volatility compresses margins for aftermarket distributors serving legacy fleet segments.
- Gel:Silica-thickened electrolyte formulations eliminate spillage risks for hillside terrain and street-legal conversions. Maintenance-free operation appeals to retirement community operators with limited technical staff.
- AGM:Absorbed glass mat separators enable vibration resistance and faster recharge rates. Industrial campus fleets prioritize AGM for multi-shift duty cycles requiring minimal downtime.
Established volume favors Lead-Acid; emerging adoption favors Lithium-Ion.
Application:
End-use concentration determines pack configuration complexity and service-contract attach rates.
- Residential Use:Planned community fleet operators in Florida and Arizona retirement corridors drive lithium-ion demand through predictable utilization patterns that enable accurate residual value forecasting. Per-mile operating agreements replace capital expenditure models.
- Golf Courses:Traditional 18-hole and resort course fleets balance replacement cost sensitivity against watering maintenance burdens. Deep-cycle diagnostic expertise shortages constrain lithium pack deployment timelines.
- Commercial Use:Resort hospitality and tourism shuttle applications prioritize silent operation and minimal emissions. Bundled energy-service contracts consolidate procurement around integrated battery management system providers.
- Industrial Use:Light manufacturing campuses and warehouse complexes demand multi-chemistry inventory across voltage configurations. Working capital strain from simultaneous flooded, AGM, gel, and lithium stocking challenges smaller distributors.
Procurement concentration sits with Residential Use; service innovation targets Commercial Use.
Voltage:
Voltage architecture selection governs drivetrain torque output and street-legal conversion eligibility.
- 48V:Higher-torque configurations for hilly terrain and neighborhood electric vehicle applications command premium retrofit pricing. State transportation department reclassification efforts expand addressable fleet populations beyond golf course boundaries.
- 36V:Legacy fleet replacement maintains volume leadership in flat-terrain golf course applications. Price-sensitive operators defer voltage upgrades until drivetrain end-of-life.
- 6V:Individual cell replacements for flooded lead-acid banks sustain aftermarket parts revenue. Specialized diagnostic and balancing expertise requirements outpace vocational training program output.
- 8V:Intermediate voltage tiers bridge replacement cost and performance upgrade decisions. Distributors stock 8V configurations to capture split-bank retrofit scenarios.
- 12V:Standard automotive voltage compatibility simplifies auxiliary power integration. Street-legal conversion mandates for lighting and signaling systems drive 12V accessory demand.
Replacement volume anchors 36V; expansion trajectory favors 48V.
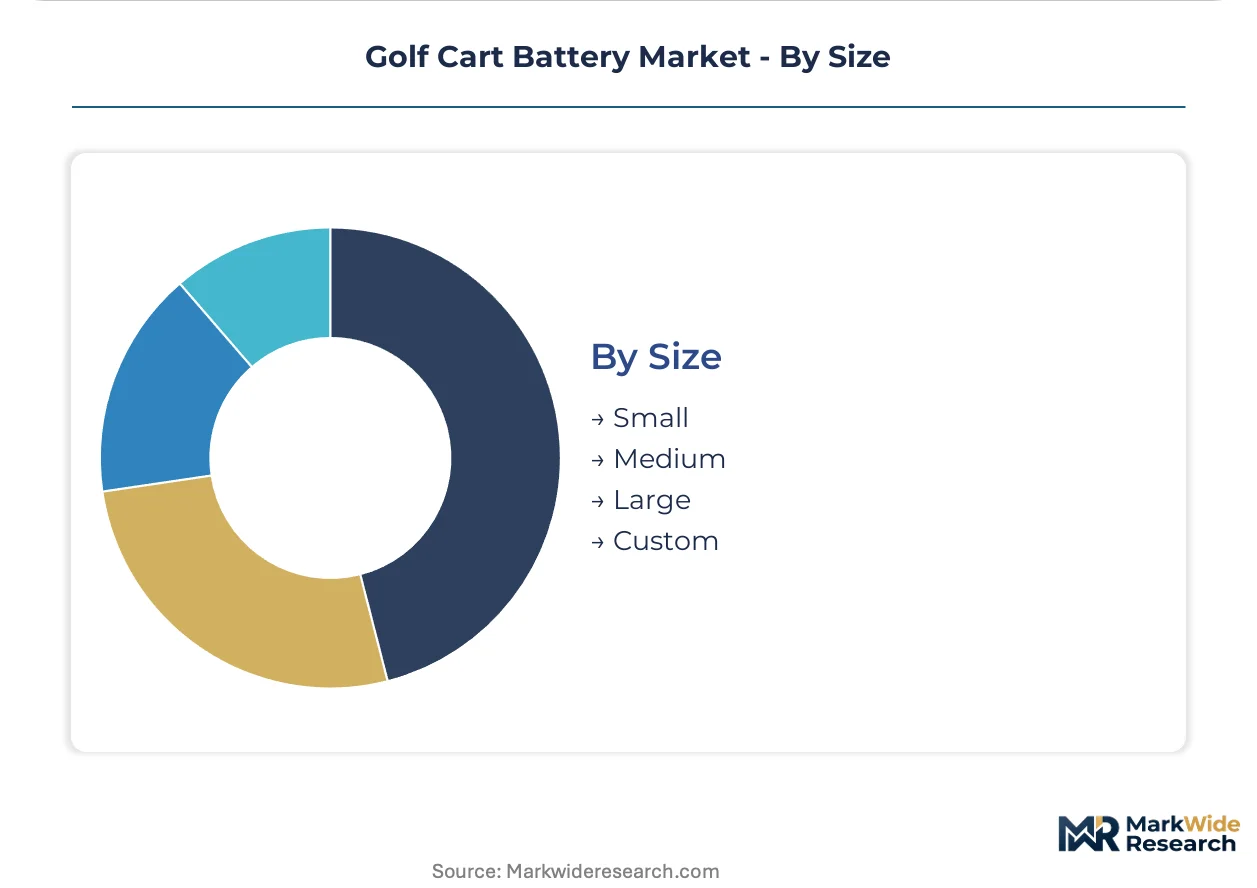
Size:
Physical form factor determines pack integration complexity and custom engineering attach rates.
- Custom:Non-standard dimensions for vintage fleet retrofits and specialized industrial chassis command engineering service premiums. ISO 9001-certified assemblers capture value from third-party auditing requirements.
- Large:High-capacity configurations for multi-passenger shuttles and extended-range street-legal vehicles strain warehouse space and working capital for distributors.
- Medium:Standard golf cart form factors dominate replacement channel volume. REACH substance restrictions and RoHS compliance deadlines accelerate phase-out of certain legacy formulations.
- Small:Compact packs for personal mobility devices and utility carts concentrate in price-sensitive segments. East Asian cell production clusters create single-source vulnerability for North American pack assemblers.
Standardization benefits Medium; margin capture favors Custom.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-level low-speed vehicle reclassification programs are expanding addressable fleet populations beyond traditional golf course boundaries. The US Department of Transportation's tightening safety standards for street-legal certification are reshaping procurement requirements across multiple jurisdictions. Regional demand concentrates in planned community developments and retirement corridor infrastructure investments.
United States
Florida's planned communities and Arizona's retirement corridors drive lithium-ion retrofit demand as watering maintenance costs accumulate. The US Department of Transportation's low-speed vehicle safety standards tighten certification requirements for street-legal conversions. Fleet electrification accelerates in The Villages, Florida and Sun City, Arizona where predictable utilization patterns enable per-mile operating agreements.
China
Domestic golf resort developments and retirement township projects in Hainan and Yunnan provinces create first-mover opportunities for lithium pack suppliers. MIIT dual carbon goals accelerate electrification mandates for low-speed vehicle fleets in planned community developments. Manufacturing clusters in Guangdong and Jiangsu provinces supply cylindrical and prismatic lithium cells to North American pack assemblers.
Germany
REACH substance restrictions and RoHS compliance deadlines tighten heavy metal content thresholds for battery imports and manufacturing residues. The KBA regulates low-speed vehicle classifications and safety equipment mandates for neighborhood electric vehicle applications. Industrial battery distributors in Baden-Württemberg and Bavaria reformulate product lines to meet enhanced material declaration documentation requirements.
India
Emerging golf resort developments in Goa and Karnataka alongside retirement township projects near Pune present expansion opportunities for lithium pack suppliers. BIS quality certification requirements reorganize supplier eligibility for OEM contracts in the planned community electrification segment. Local assembly partnerships in Tamil Nadu and Gujarat are capturing value from third-party auditing demand among smaller assemblers.
Japan
MetI industrial standards govern deep-cycle battery performance specifications for light industrial campus applications. Aging demographic concentration in planned communities outside Tokyo and Osaka drives demand for maintenance-free gel and lithium configurations. Specialized diagnostic expertise for lithium pack management systems remains concentrated in the Kanto and Kansai industrial corridors.
Golf Cart Battery Market Competitive Environment
Player mix skews toward established deep-cycle specialists with flooded lead-acid heritage and emerging lithium-ion chemistry providers. Market structure shows moderate consolidation around legacy battery manufacturers with distribution network density advantages. Two strategic archetypes dominate: traditional lead-acid assemblers defending replacement channel volume, and lithium-ion specialists capturing retrofit premium pricing. Competitive moves center on chemistry portfolio diversification and ISO 9001 certification acquisition for OEM contract eligibility.
Within the established chemistry tier, Trojan Battery Company and Exide Technologies occupy positions representing deep-cycle expertise and manufacturing scale respectively. RELION Battery exemplifies the lithium-ion specialist archetype targeting weight-sensitive retrofit applications. Crown Battery Manufacturing and U.S. Battery sit within the mid-tier distributor-served segment where price-sensitive replacement channel dynamics persist. Interstate Batteries anchors the independent distributor network model, while East Penn Manufacturing represents vertically integrated production capabilities spanning multiple electrochemical formulations.
| Leading Market Players |
|---|
| Trojan Battery Company |
| Exide Technologies |
| Crown Battery Manufacturing |
| U.S. Battery |
| Interstate Batteries |
| Allied Battery |
| East Penn Manufacturing |
| RELION Battery |
| RoyPow Technology |
| Others |
Value Chain & Pricing Dynamics
ISO 9001 certification gates both OEM contract eligibility and premium pricing tiers simultaneously, compressing uncertified assemblers into commoditized replacement channels while audited distributors capture service-contract attach premiums. Chemistry selection and voltage architecture complexity fragment procurement decisions across multiple cost-plus contract structures indexed to lead and lithium carbonate input volatility.
Pricing Analysis
Cost-plus contracts with lead and lithium carbonate indexation dominate fleet procurement, with pricing stratifying across ISO-certified premium tiers, standard audited distributor levels, and uncertified economy channels. Price differentiation rests on certification grade and after-sales service bundling, with battery management system integration commanding attach premiums. Cost compression in flooded lead-acid replacement channels is intensifying because antimony input volatility compresses distributor margins. Golf course operators exhibit highest price sensitivity, while retirement community fleet managers prioritize total-cost-of-ownership over upfront capital outlay.
Supply Chain Analysis
China and South Korea anchor cylindrical and prismatic lithium cell fabrication, while domestic US and Mexican facilities concentrate lead-acid assembly and pack integration. Raw material flows draw from Australian spodumene concentrates, Chilean lithium brine operations, and domestic lead smelter output. Single-source vulnerability in East Asian cathode precursor supply creates procurement risk for North American pack assemblers lacking captive upstream control. Distribution runs through independent battery distributor networks serving aftermarket replacement channels, with direct OEM supply agreements capturing fleet retrofit volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bundled energy-service contracts with per-mile or per-cycle operating structures are expanding faster than hardware-only transactions, repositioning competitive advantage around residual value forecasting and battery management system integration capabilities.
For Market Incumbents: Consolidate distributor network density in Florida and Arizona retirement corridors to defend replacement channel volume against lithium-ion specialist encroachment. Deepen backward integration into lead smelting or lithium cell supply to offset East Asian cathode precursor vulnerability. ISO 9001 certification investment remains essential for OEM contract eligibility as supplier qualification frameworks tighten. For New Entrants and Emerging Players: Differentiate on lithium iron phosphate chemistry expertise for weight-sensitive hillside terrain retrofits previously dominated by lead-acid. India's emerging golf resort developments and retirement township projects near Pune and Goa represent the most penetrable geography, with local assembly partnerships capturing BIS certification arbitrage value. Target per-mile operating agreement structures to bypass capital expenditure barriers among retirement community fleet operators. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial battery manufacturers with underutilized deep-cycle production lines and established distributor relationships. Long-term viability favors chemistry-agnostic assemblers with ISO 9001 certification and battery management system software capabilities. The signal to watch is state-level low-speed vehicle reclassification momentum, which would immediately expand addressable fleet populations beyond traditional golf course boundaries.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 9001 Certification Investment | Third-party auditing unlocks OEM contract eligibility and premium pricing tiers for pack assemblers. |
| Lithium Iron Phosphate Chemistry Transition | Superior depth-of-discharge tolerance captures retrofit demand from Florida and Arizona fleet operators. |
| Local Assembly Partnership Formation | India and China manufacturing presence satisfies BIS and MIIT compliance for planned community electrification. |
| Battery Management System Integration | Software-enabled service contracts generate recurring revenue beyond hardware-only transactions. |
| Multi-Chemistry Inventory Rationalization | SKU consolidation reduces working capital strain for distributors serving diverse fleet duty cycles. |
Study Parameters
A standing panel of fleet operations managers, battery distributor principals, OEM procurement leads, and deep-cycle technician training program directors provided ongoing calibration throughout the primary research phase. Triangulation combined structured interviews with secondary validation against US EPA Battery Act filings, OSHA workplace safety documentation, state-level low-speed vehicle classification registers, and customs trade data for lead and lithium cell imports. Bottom-up voltage configuration demand modeling and top-down chemistry adoption rate analysis were cross-checked for consistency.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. The analytical framework modeled segmentation dimensions including battery chemistry, voltage architecture, application end-use, and fleet duty cycle intensity. CAGRs were derived from chemistry-specific replacement cycle compression rates and street-legal conversion penetration assumptions. Forecast inputs incorporated lead price volatility indices and lithium carbonate contract pricing trends without year-specific anchoring.
The analysis sits within stated boundaries; outcomes outside sustained lithium iron phosphate cost parity or accelerated state-level LSV reclassification would require recalibration. Forecasts reflect documented assumptions regarding fleet electrification timelines and watering labor cost accumulation patterns. Recalibration cycles align with material shifts in low-speed vehicle safety standards and REACH substance restriction enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Europe Electric Vehicle Thermal Management System Market
Electric Vehicles
Bus Pantograph Charger Market
Electric Vehicles
Vietnam Solar E-Bike Market
Electric Vehicles
Electric Car Rental Market
Electric Vehicles
Electric Tuk-Tuks Market
Electric Vehicles
Automotive Battery Thermal Management System Market
Electric Vehicles
Global Smart Electric Drive Market
Electric Vehicles
Electric Vehicle (EV) Ball Bearings Market
Electric Vehicles
Automotive Electric Vehicle Power System Market
Electric Vehicles
China Electric Truck Market
Electric Vehicles
Global EV on-Board Chargers Market
Electric Vehicles
Automotive Energy Harvesting and Regeneration Market
Electric Vehicles
North America Electric Vehicle Market
Electric Vehicles
Norway Electric Vehicle Market
Electric Vehicles
Electric Vehicle HVAC Market
Electric Vehicles
BEV On-Board Charger Market