
 Global Automotive on Board Power Inverter Market | 2026-2036
Global Automotive on Board Power Inverter Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive on Board Power Inverter Market Intelligence
The transition to pure sine wave inverters for sensitive electronics is reorganizing the value proposition away from basic power conversion. Continental Engineering Services leverages its system integration expertise to offer complete power solutions for passenger vehicles. STMicroelectronics specializes in high-efficiency power semiconductors that are critical for compact inverter designs. Robert Bosch GmbH sustains its market position through extensive R&D in automotive electronics and a global manufacturing footprint.
An automotive on-board power inverter is an electrical device that converts direct current (DC) from a vehicle's battery into alternating current (AC). This enables the operation of standard consumer electronics and tools, typically providing 120V or 230V AC power from a 12V or 24V DC source. The electric vehicle (EV) and hybrid vehicle segments represent the fastest-growing end-user categories, demanding integrated power solutions. Pure sine wave models command higher price points due to their ability to power sensitive electronics, displacing older modified sine wave units.
Product design and market access are shaped by regulations like the US National Highway Traffic Safety Administration (NHTSA) safety standards and Europe's CE marking requirements for electromagnetic compatibility. In China, compliance with GB standards for automotive components is mandatory for all vehicles. Stakeholder success will depend on navigating the divergent power requirements and form factors between aftermarket installations and OEM-integrated systems.
Market Dynamics
The imperative for electrification across all vehicle classes, from passenger cars to commercial fleets, is the central force shaping the automotive on-board power inverter market. This transition drives demand for both high-voltage powertrain inverters and auxiliary low-voltage DC-AC converters.
Growth Catalysts
- Wide-Bandgap Semiconductors:The adoption of materials like silicon carbide (SiC) and gallium nitride (GaN) improves inverter efficiency, power density, and thermal performance, enabling more compact and powerful designs for electric vehicles.
- Commercial Fleet Electrification:The proliferation of consumer electronics, mobile office equipment, and specialized tools within commercial vans and trucks creates sustained demand for reliable on-board AC power sources independent of the main powertrain.
- EV Mandates:Government policies in China and Europe mandating transitions to electric vehicles directly accelerate the need for integrated, high-reliability power conversion systems as standard equipment in new cars.
Market Restraints
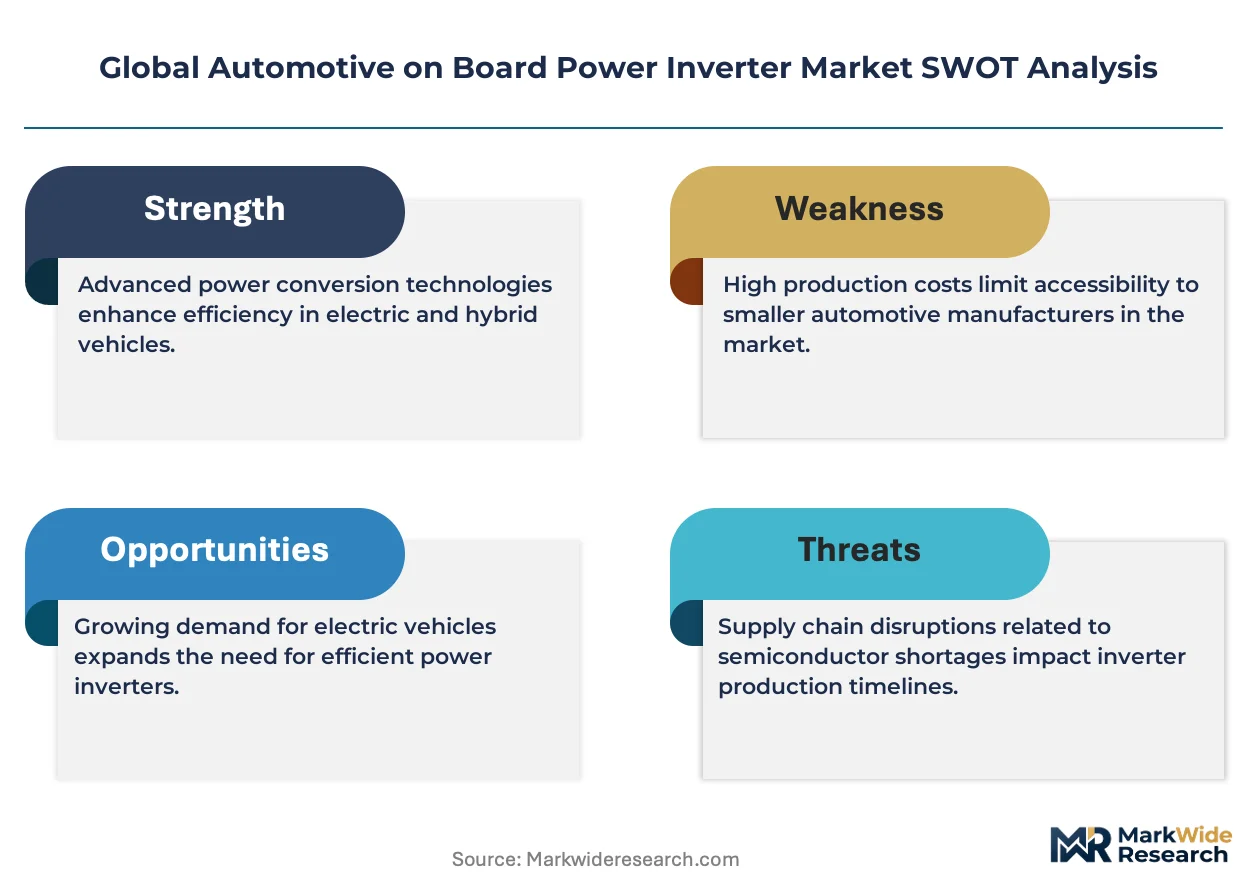
- Component Cost:The higher material and fabrication costs associated with pure sine wave inverters and advanced SiC semiconductors create a price premium, limiting adoption in cost-sensitive vehicle segments and aftermarket applications.
- Thermal Management Complexity:Increasing power density in smaller form factors generates significant waste heat, requiring sophisticated and costly thermal management solutions like liquid cooling to ensure reliability and safety.
- Supply Chain Concentration:The manufacturing of high-performance power semiconductors is concentrated in a few foundries, primarily in Asia, creating potential supply chain vulnerabilities and pricing power for component suppliers.
Strategic Opportunities
- Vehicle-to-Grid (V2G) Integration:The development of bidirectional inverters that allow EVs to supply power back to the grid or a home presents a significant opportunity, creating new value streams for vehicle owners and utility providers.
- Emerging Commercial Markets:Expanding logistics and service fleets in developing economies like India and Brazil offer underpenetrated markets for robust, high-capacity inverters to power auxiliary equipment.
- Power Module Consolidation:Integrating the on-board inverter with other power electronics, such as the on-board charger (OBC) and DC-DC converter, into a single, compact unit offers a path to reduce cost, weight, and complexity for OEMs.
Industry Challenges
- System Integration Hurdles:Ensuring seamless compatibility and communication between the inverter and a vehicle's diverse electrical systems and battery management software poses a significant engineering challenge, particularly for aftermarket suppliers.
- Divergent Regulatory Standards:Manufacturers must navigate a complex and fragmented landscape of safety and electromagnetic compatibility regulations, including NHTSA standards in the US, CE marking in Europe, and GB standards in China.
- Power Electronics Talent Gap:A shortage of engineers with specialized expertise in high-frequency power electronics, wide-bandgap semiconductor design, and automotive system integration constrains R&D and product development capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive on Board Power Inverter Market |
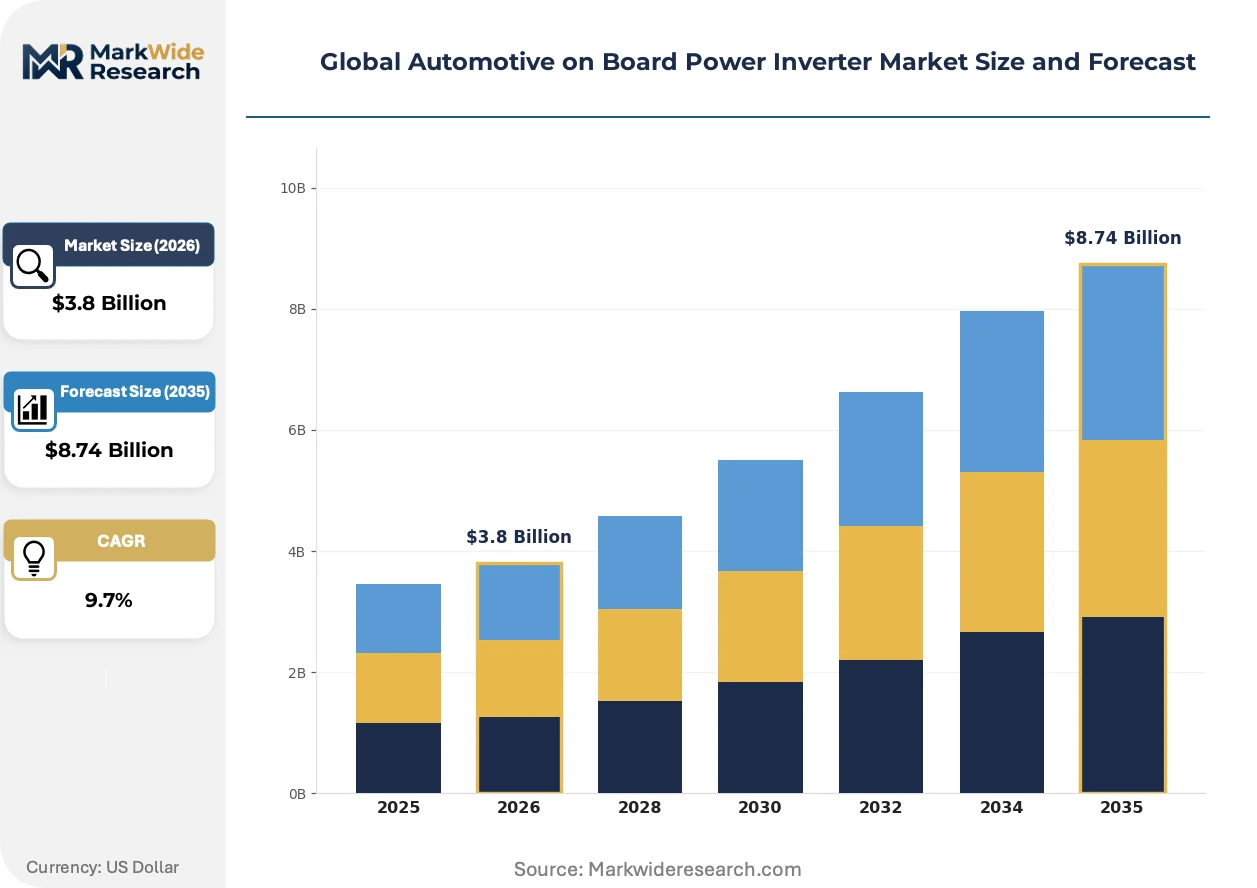
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modified Sine Wave, Pure Sine Wave, High-Frequency, Low-Frequency End User: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Hybrid Vehicles Capacity: 500W, 1000W, 2000W, 3000W Installation: Integrated, Standalone, OEM Installation, Aftermarket Installation |
| Companies Covered | Sensata Technologies, Continental Engineering Services, Infineon Technologies, STMicroelectronics, Marelli Holdings, Robert Bosch GmbH, Analog Devices, Hitachi Ltd., ON Semiconductor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive on Board Power Inverter Market Strategic Shifts & Innovations
The market's evolution is defined by the dual pressures of electrification and consumer demand for ubiquitous power. This drives innovation toward higher efficiency, smaller form factors, and deeper integration into the vehicle's core electrical architecture, moving beyond simple power conversion.
Wide-bandgap semiconductors like Silicon Carbide (SiC) provide a fundamental advantage in power conversion by enabling higher switching frequencies and operating temperatures. Electric vehicle manufacturers are the primary adopters for improving powertrain efficiency, with the technology now migrating to auxiliary power systems. This technological shift is decomposing the traditional trade-off between power density and thermal management, allowing for smaller inverters that do not compromise on output or reliability.
European Union directives promoting smart grid integration and vehicle electrification are directly influencing inverter functionality. These policies incentivize the development of bidirectional power flow capabilities, enabling Vehicle-to-Grid (V2G) and Vehicle-to-Home (V2H) applications. The passenger EV segment is most affected, as automakers respond by designing on-board power systems that can serve as mobile energy storage assets, contributing to grid stability.
A notable behavioral change is the consumer preference shift away from aftermarket, user-installed inverters toward solutions fully integrated by the original equipment manufacturer (OEM). This trend diminishes the role of traditional automotive parts retailers for this product category, strengthening direct B2B supply channels between inverter specialists and automakers. This is most pronounced in the North American recreational vehicle (RV) and premium SUV segments, where built-in 120V outlets are becoming a standard feature.
Global Automotive on Board Power Inverter Market Segmentation
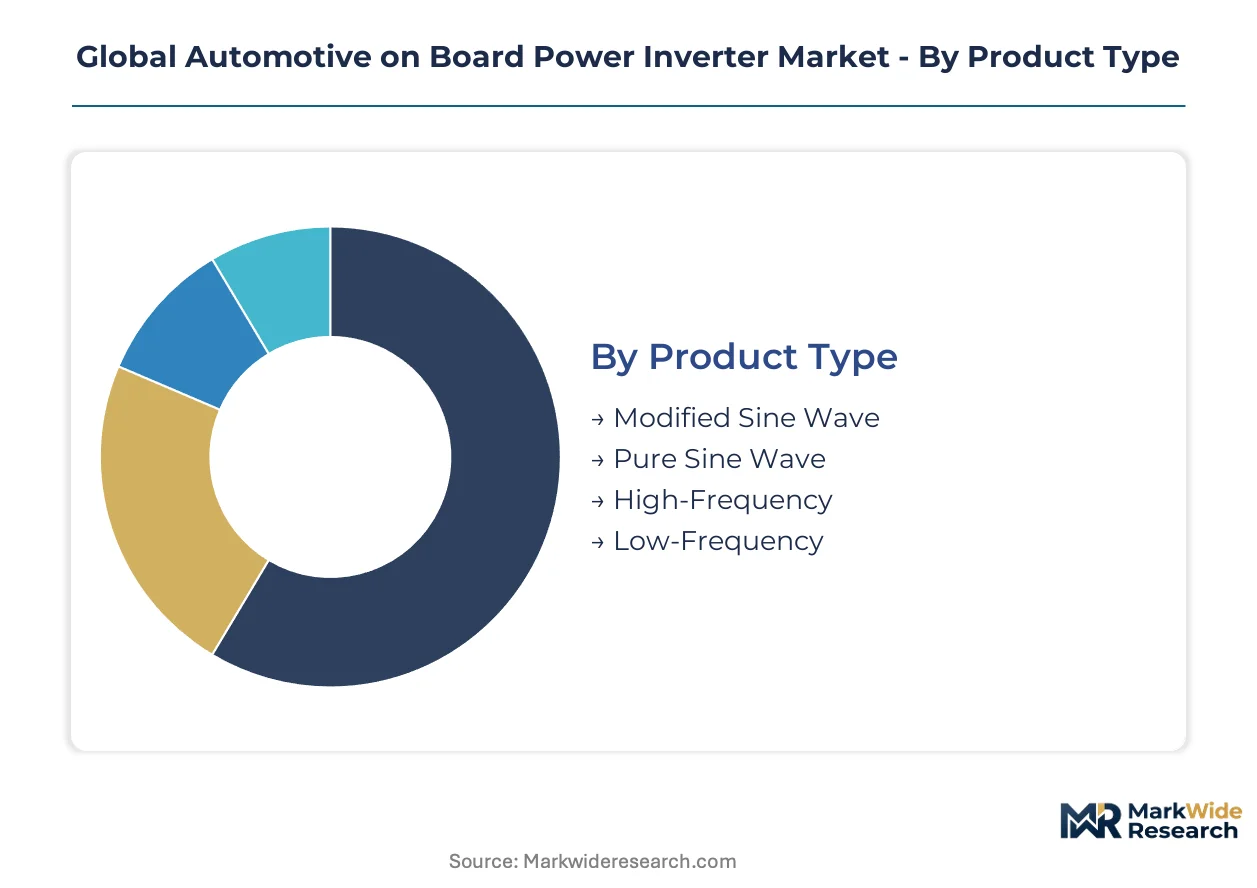
The segmentation of the global automotive on-board power inverter market provides a granular view of distinct product characteristics and end-user demands. Understanding these categories is crucial for identifying areas of growth, technological shifts, and competitive differentiation within the industry.
Product Type:
The market for automotive on-board power inverters faces significant substitution pressure, particularly as advanced technologies displace older, less efficient solutions.
- Pure Sine Wave:This product type converts direct current (DC) into alternating current (AC) with a smooth, continuous waveform, mirroring utility power. Passenger electric vehicles demand these for sensitive electronics, driven by the need for stable power quality.
- High-Frequency:High-frequency inverters utilize smaller magnetic components for lightweight and compact designs, operating at elevated switching speeds. Electric vehicle powertrains increasingly integrate these for improved power density, spurred by space constraints.
- Modified Sine Wave:Modified sine wave inverters provide a stepped approximation of an AC sine wave, suitable for less sensitive electronic devices.
- Low-Frequency:Low-frequency inverters feature larger transformers for robust power delivery and are often found in heavy-duty commercial applications.
Modified Sine Wave retains volume leadership; Pure Sine Wave holds the steepest expansion curve.
End User:
Different end-user segments exhibit distinct power conversion requirements, shaping the design and integration of on-board inverters.
- Electric Vehicles:These vehicles require high-voltage inverters for powertrain management and auxiliary DC-AC conversion for consumer electronics. China's electric vehicle manufacturing leadership drives significant demand for integrated power solutions.
- Commercial Vehicles:Commercial fleets utilize on-board inverters to power mobile office equipment and specialized tools from 12V or 24V DC sources. Logistics and service fleets in India and Brazil present underpenetrated markets for robust AC power.
- Passenger Vehicles:Passenger vehicles incorporate inverters for convenience features, enabling the operation of small electronics and charging devices.
- Hybrid Vehicles:Hybrid vehicles integrate power inverters to manage energy flow between the internal combustion engine and electric motor systems.
Electric Vehicles are expanding most quickly, while Passenger Vehicles represent a foundational segment.
Capacity:
Capacity segmentation reflects the varied power demands of on-board applications, from basic charging to heavy-duty tool operation.
- 1000W:This capacity provides sufficient power for a range of consumer electronics and light-duty tools within vehicles. Recreational vehicles and premium SUVs often feature this capacity for built-in 120V outlets.
- 2000W:The 2000W capacity offers higher power output suitable for larger appliances or multiple devices simultaneously, common in commercial settings. Commercial vans and trucks increasingly adopt this capacity to support mobile office equipment.
- 500W:The 500W segment is primarily used for charging small personal devices and powering low-wattage electronics.
- 3000W:This capacity is designed for high-demand applications, such as power tools or specialized equipment in heavy commercial vehicles.
The 1000W segment maintains significant market presence, and the 2000W capacity is gaining share fastest.
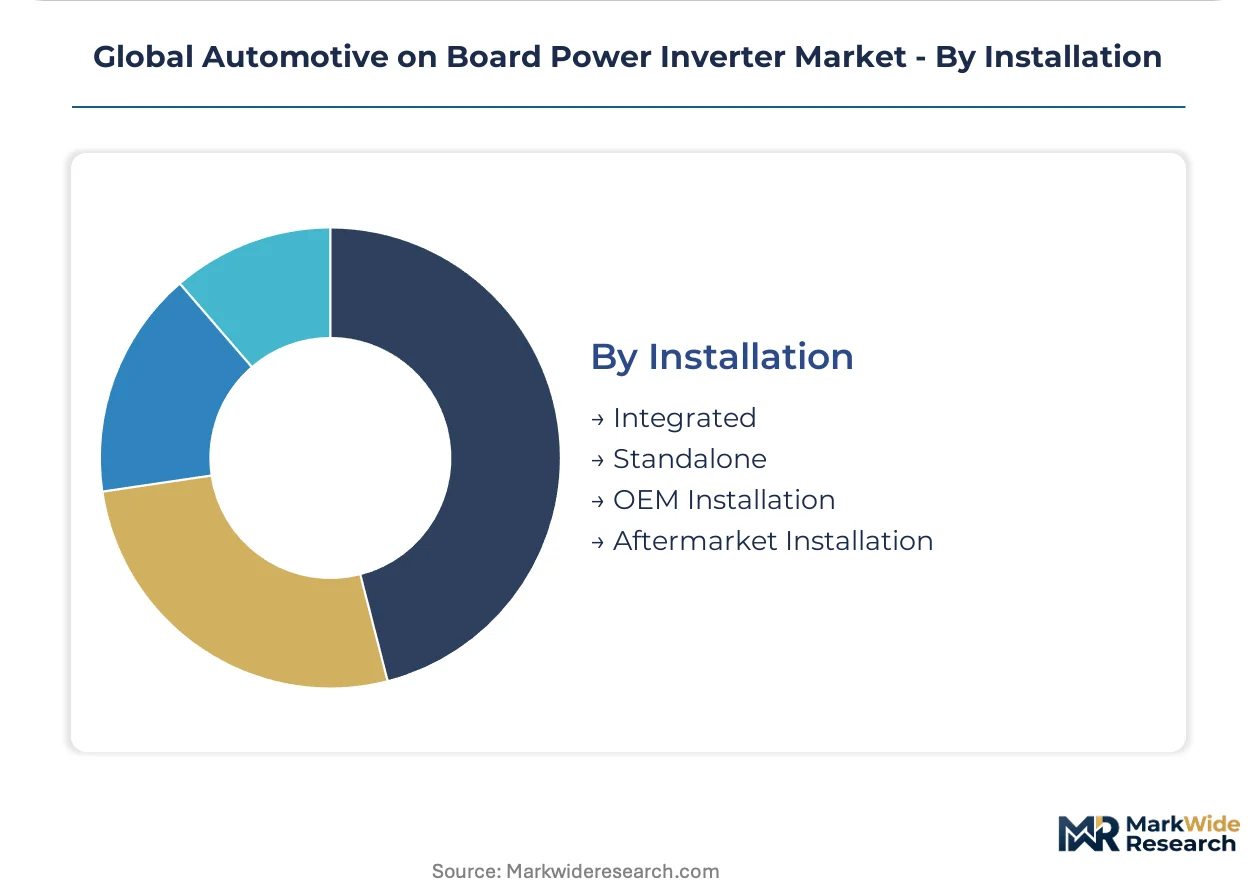
Installation:
Different installation methods cater to distinct customer preferences and vehicle integration strategies, influencing market access.
- OEM Installation:Inverters are factory-installed as standard equipment, ensuring seamless integration with the vehicle's electrical architecture. New electric vehicle models frequently offer OEM-integrated power solutions, driven by government mandates.
- Integrated:These systems combine the inverter with other power electronics, such as on-board chargers, into a single, compact module. Automakers seek integrated solutions to reduce cost, weight, and complexity in vehicle design.
- Standalone:Standalone units are individual inverter devices purchased separately and connected to the vehicle's battery.
- Aftermarket Installation:Aftermarket inverters are added to vehicles post-purchase, often by users or third-party installers.
Aftermarket Installation still accounts for notable volume, but OEM Installation is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for automotive on-board power inverters exhibits varying price elasticity across segments. Premium electric vehicles prioritize pure sine wave models for sensitive electronics, accepting higher costs. Conversely, aftermarket installations in cost-sensitive applications often favor more economical modified sine wave units.
China
China's electric vehicle manufacturing leadership creates substantial demand for integrated power solutions. Compliance with GB standards for automotive components is mandatory for all vehicles. The Yangtze River Delta region, including Shanghai, drives EV production and power electronics innovation.
Germany
German automotive manufacturers integrate advanced on-board inverters for premium passenger vehicles. CE marking requirements ensure electromagnetic compatibility for these systems. The Stuttgart region, a hub for automotive OEMs, spearheads research into high-efficiency power conversion.
United States
The United States market sees significant demand from recreational vehicles and commercial fleet electrification. NHTSA safety standards govern the design and installation of on-board power systems. Michigan's automotive corridor, alongside Silicon Valley, drives advancements in EV power electronics integration.
India
India's expanding logistics and service fleets offer underpenetrated markets for robust on-board inverters. The PLI scheme incentivizes domestic manufacturing of advanced automotive components. Chennai and Pune automotive clusters are developing local capabilities for high-capacity power conversion solutions.
Japan
Japanese automakers prioritize integrated power solutions for hybrid vehicles and advanced passenger electronics. JIS standards ensure the quality and reliability of automotive power components. The Nagoya region, a key automotive innovation hub, focuses on compact, high-efficiency inverter designs.
Global Automotive on Board Power Inverter Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the automotive on-board power inverter market. The industry exhibits a tiered structure, with specialized power electronics firms focusing on high-efficiency, compact designs for OEM integration. Conversely, other manufacturers prioritize cost-effective solutions for aftermarket and less sensitive applications. Strategic partnerships between semiconductor suppliers and automotive Tier 1s are common, alongside portfolio diversification into bidirectional V2G capabilities.
Within the high-performance semiconductor segment, STMicroelectronics, a Swiss-Dutch multinational, exemplifies specialized expertise in high-efficiency power devices critical for compact inverter designs. Robert Bosch GmbH, a German multinational engineering and technology company, anchors its market position through extensive automotive electronics R&D and a global manufacturing footprint. Sensata Technologies, a US-based industrial technology company, represents a key supplier of advanced sensing and electrical protection solutions, often integrated into power conversion systems. These firms collectively illustrate the diverse technological and geographical strengths driving the market.
| Leading Market Players |
|---|
| Sensata Technologies |
| Continental Engineering Services |
| Infineon Technologies |
| STMicroelectronics |
| Marelli Holdings |
| Robert Bosch GmbH |
| Analog Devices |
| Hitachi Ltd. |
| ON Semiconductor |
| Others |
Cost & Logistics Intelligence
CE marking requirements not only gate market access for automotive power inverters in Europe but also influence pricing tiers by demanding specific quality and compliance investments across the supply chain. This regulatory framework shapes both product qualification and cost structures.
Pricing Analysis
Extended warranty and service contracts for integrated power solutions drive lifetime value for OEMs and Tier 1 suppliers. The dominant pricing structure remains per-unit transactional, with price differentiation stemming from certification levels like CE marking compliance and the integration of advanced features such as bidirectional V2G capabilities. Cost compression in aftermarket segments is intensifying due to competition from basic modified sine wave units. Commercial fleet operators exhibit high price sensitivity, while premium EV manufacturers prioritize performance over cost.
Supply Chain Analysis
Managing inventory levels for critical power semiconductor components remains a significant supply chain challenge, impacting production lead times for advanced inverter modules. Geographic supply concentration for high-performance power semiconductors largely resides in Asia, particularly Taiwan and South Korea, with China also playing a key role in manufacturing. The supply chain sources heavily from specialized silicon carbide (SiC) wafers and microcontrollers. Single-source vulnerability for advanced components presents a structural risk. Distribution runs through direct B2B channels to automotive OEMs and Tier 1s, alongside a fragmented aftermarket network.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive on-board power inverter market presents a capability scarcity, particularly in the specialized engineering expertise required for high-frequency power electronics and wide-bandgap semiconductor integration. This gap influences innovation and market entry strategies.
For Market Incumbents:Compound existing R&D investments in wide-bandgap semiconductors and advanced thermal management to maintain a technological edge against emerging specialized firms. Reinforce market position by deepening vertical integration into power module manufacturing, ensuring a robust supply of critical components. The threat of new entrants offering highly efficient, compact designs necessitates continuous innovation in system integration.
For New Entrants and Emerging Players:Lead with modular, cost-effective solutions targeting underpenetrated markets like commercial fleet auxiliary power in developing economies such as India and Brazil. Focus on providing robust, high-capacity inverters for specialized tools and mobile office equipment, leveraging a go-to-market angle centered on durability and ease of aftermarket installation. The passenger vehicle aftermarket for basic power conversion also offers white space.
For Investors and Strategic Acquirers:EU directives promoting smart grid integration reshapes the acquisition landscape, favoring firms with proven bidirectional inverter technology and V2G capabilities. Over a 5-10 year window, the market's long-term viability is strong, driven by global EV mandates and increasing demand for integrated power solutions. Specialized power electronics firms with expertise in SiC and GaN technologies represent an attractive acquisition archetype. The signal to watch is the widespread adoption rate of V2G charging infrastructure and compatible vehicle models.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in SiC/GaN R&D | Enables higher efficiency and power density for next-generation EV powertrains. |
| Develop Bidirectional Inverters | Unlocks Vehicle-to-Grid (V2G) and Vehicle-to-Home (V2H) revenue streams. |
| Consolidate Power Modules | Reduces cost, weight, and complexity for automotive OEM integration. |
| Expand Commercial Fleet Solutions | Captures sustained demand for auxiliary power in logistics and service sectors. |
| Enhance Thermal Management | Ensures reliability and safety for compact, high-power inverter designs. |
Research Approach
A spread of perspectives from OEM platform engineers, Tier 1 procurement specialists, and semiconductor R&D leads converged on the working assumptions for the automotive on-board power inverter market. Primary interviews were combined with validation against secondary data from vehicle production databases, regulatory filings (e.g., NHTSA, CE marking documentation), and industry association reports. Both bottom-up and top-down triangulation methods ensured data accuracy.
The product type, end-user, capacity, installation method, and semiconductor material were the primary segmentation dimensions modeled for the automotive on-board power inverter market. The analytical framework projected market growth across the analysis window, with compound annual growth rates derived from historical trends and anticipated technological shifts. Key industry-specific forecast inputs included electric vehicle production forecasts and commercial fleet electrification rates.
The analysis sits within stated boundaries; outcomes outside significant shifts in global trade policy or unforeseen battery technology breakthroughs would require recalibration. Forecasts reflect assumptions regarding current regulatory trajectories and technological adoption rates. Revision becomes warranted when major macroeconomic downturns or supply chain disruptions cross critical thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
High Voltage DC Relay for Vehicle Market
Automotive Electrical & Electronics
Automotive UPS (in Vehicle UPS) Market
Automotive Electrical & Electronics
Personal Mobility Devices Market
Automotive Electrical & Electronics
China Automotive Electric Power Steering (EPS) Market
Automotive Electrical & Electronics
Automotive E-Axle Disconnect Actuator Market
Automotive Electrical & Electronics
Argentina Automotive EPS Market
Automotive Electrical & Electronics
Electric Vehicle High-Voltage Cables Market
Automotive Electrical & Electronics
Automotive Airbag Electronic Control Unit Market
Automotive Electrical & Electronics
In-Chassis Cooling Market
Automotive Electrical & Electronics
Car Satellite Antenna Market
Automotive Electrical & Electronics
North America Automotive Lead-Acid Battery Market
Automotive Electrical & Electronics
Jump Starter Market
Automotive Electrical & Electronics
US Automotive E-Axle Market
Automotive Electrical & Electronics
Automotive Magnetic Sensor Market
Automotive Electrical & Electronics
Automotive Zonal Gateway ECU Market
Automotive Electrical & Electronics
Electric Motor Horn Market