
 Asia Pacific Electric Commercial Vehicles Market | 2026-2036
Asia Pacific Electric Commercial Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Electric Commercial Vehicles Market Outlook
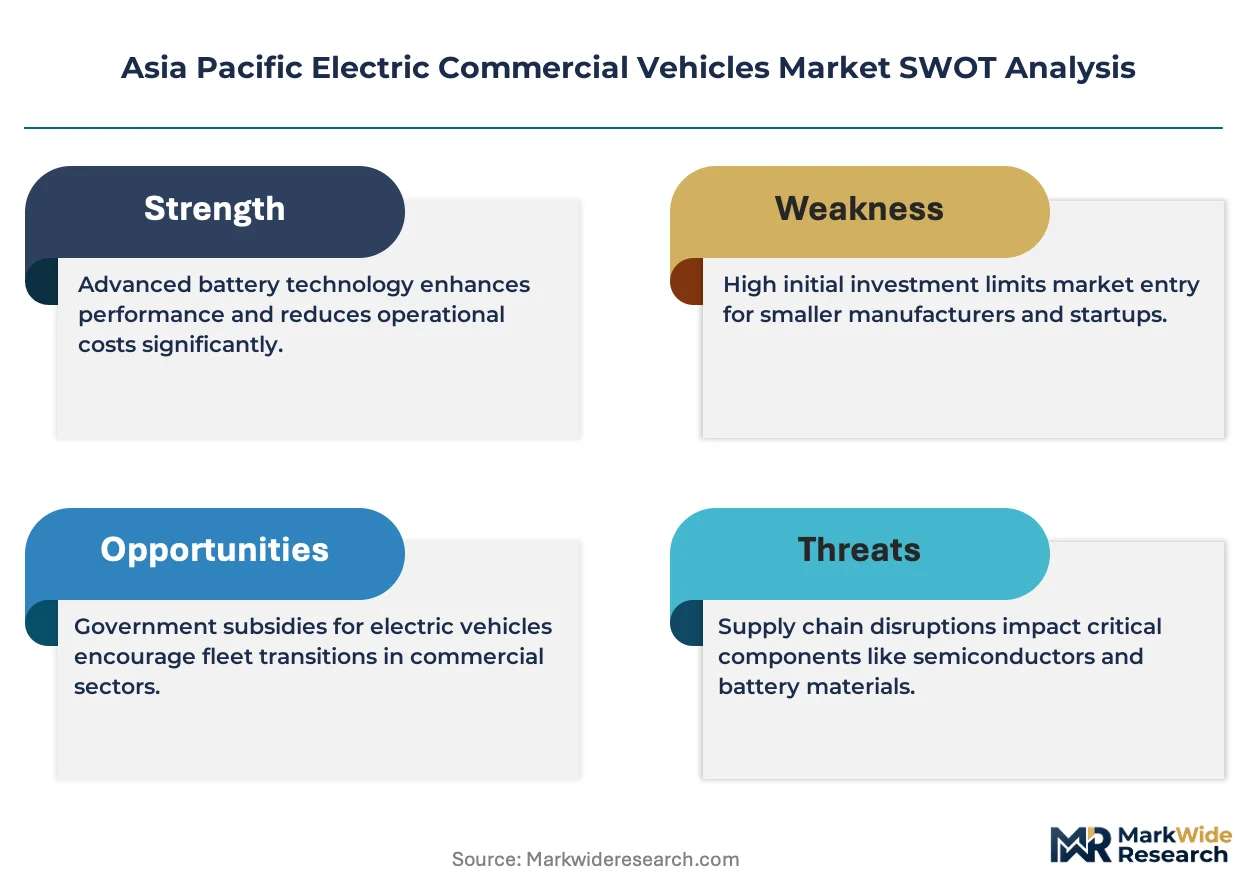
Commercial vehicle technician shortages across Southeast Asian service networks is unwinding fleet electrification timelines in Indonesia and Vietnam. BYD Company leverages integrated battery manufacturing to sustain cost leadership across light-duty and bus segments. Tata Motors anchors Indian market penetration through localized powertrain engineering and government fleet contracts. Dongfeng Motor competes aggressively in medium-duty distribution trucks through state-backed charging corridor partnerships.
Asia Pacific electric commercial vehicles comprise battery-dominant, hybrid, and fuel-cell powertrains installed in trucks and buses exceeding 3.5 tonnes gross vehicle weight, with lithium iron phosphate and nickel manganese cobalt chemistries dominating energy density specifications above 150 kWh for heavy-duty routes. Battery electric configurations occupy the dominant share of new registrations as cell costs decline and energy density improves, while plug-in hybrid variants retain structural relevance in archipelago nations with intermittent grid reliability. DC fast charging infrastructure captures the fastest expansion trajectory among charging categories, driven by depot-based fleet scheduling and opportunity charging at logistics hubs.
China's MIIT enforces GB standards for commercial EV safety and battery thermal management, while India's CEA mandates interoperability protocols for public charging networks. Japan's METI coordinates hydrogen fuel cell truck demonstrations through designated highway corridors. Stakeholders must weigh powertrain technology commitments against evolving subsidy phase-out schedules and charging infrastructure readiness across divergent national regulatory frameworks.
Market Dynamics
China's dual carbon goals and India's PLI scheme for advanced chemistry cell manufacturing are compressing total cost of ownership calculations across urban logistics fleets, accelerating procurement timelines for battery-electric trucks and buses.
Growth Catalysts
- Port electrification mandates:China's Yangtze River Delta megacity cluster enforces zero-emission freight zones at major container terminals, forcing fleet operators to electrify drayage and short-haul distribution vehicles.
- CEA interoperability protocols:India's Central Electricity Authority mandates standardized payment and connector systems for public charging networks, reducing range anxiety and enabling cross-fleet charging access.
- Lithium iron phosphate chemistry:Energy density improvements above 150 kWh for heavy-duty routes are eliminating payload penalties that previously constrained electric truck adoption in long-haul applications.
Market Restraints
- Technician scarcity:Commercial vehicle technician shortages across Southeast Asian service networks in Indonesia and Vietnam are unwinding fleet electrification timelines and extending vehicle downtime.
- Grid reliability gaps:Intermittent electricity supply in archipelago nations limits pure battery-electric deployment, forcing retention of plug-in hybrid variants with higher total cost of ownership.
- Charging infrastructure concentration:DC fast charging corridors remain concentrated in coastal Chinese provinces and Indian metropolitan corridors, leaving interior logistics routes underserved.
Strategic Opportunities
- Vietnamese urban freight:Underpenetrated last-mile delivery electrification in Ho Chi Minh City and Hanoi offers first-mover positioning as e-commerce fulfillment networks expand.
- Hydrogen fuel cell corridors:Japan's METI-coordinated highway demonstrations for heavy-duty fuel cell trucks create regulatory tailwinds for zero-emission long-haul routes exceeding battery-electric range limits.
- Depot charging integration:Fleet operators are converging solar generation with overnight DC fast charging at logistics hubs, reducing grid dependency and peak demand charges.
Industry Challenges
- Battery thermal management certification:China's MIIT enforcement of GB standards for commercial EV safety requires extensive validation timelines, delaying new model launches by 8-14 months.
- Powertrain integration complexity:Retrofitting existing diesel service depots for high-voltage electric truck maintenance demands capital reconfiguration of lifts, fire suppression, and technician training facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Electric Commercial Vehicles Market |
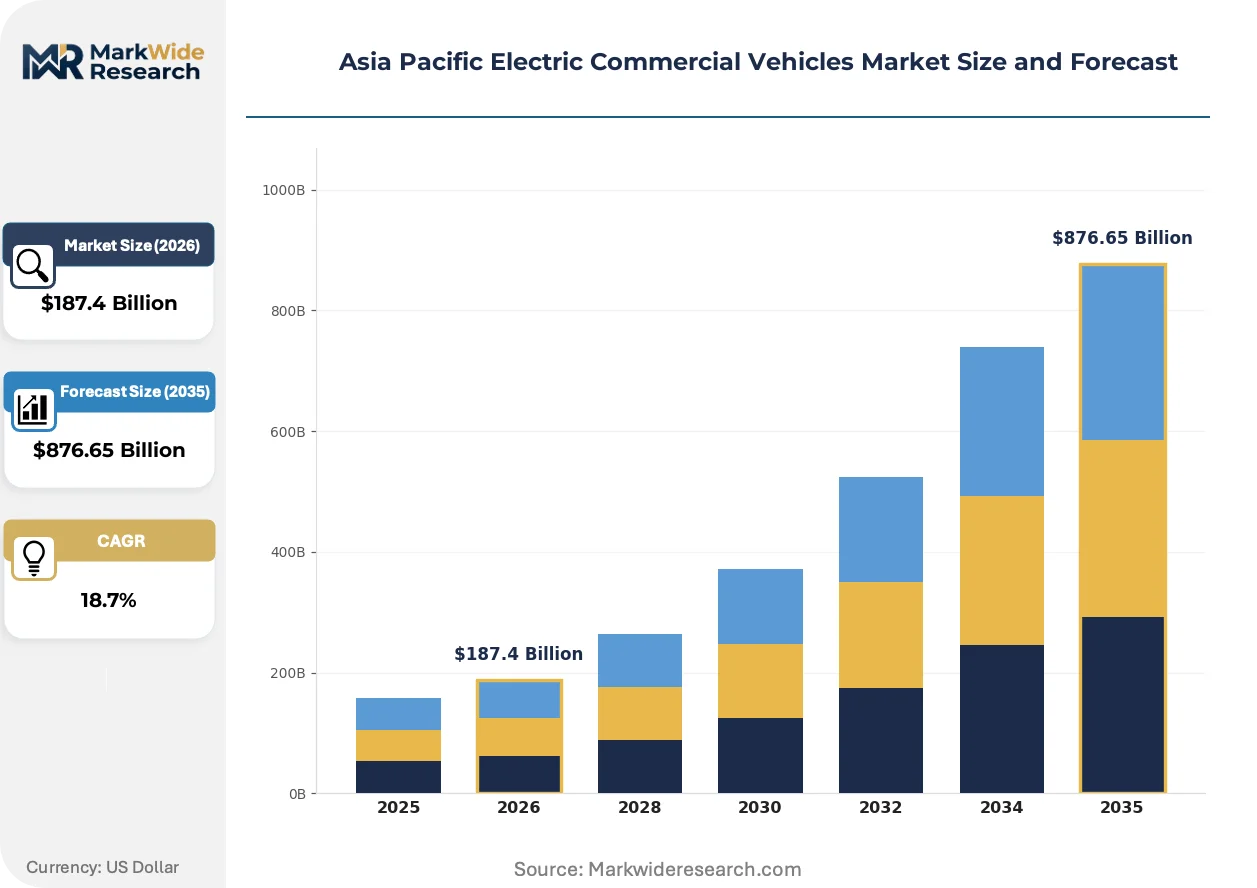
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $876.65 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Light-Duty Trucks, Medium-Duty Trucks, Heavy-Duty Trucks, Buses Powertrain Technology: Battery Electric, Plug-in Hybrid, Fuel Cell, Others Application: Logistics, Public Transportation, Freight Delivery, Waste Management Charging Infrastructure: DC Fast Charging, AC Charging Stations, Wireless Charging, Others |
| Companies Covered | BYD Company, Yutong Bus, Dongfeng Motor, Tata Motors, Daimler Trucks, Mitsubishi Motors, Wuling Motors, General Motors, Ford Motor Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Electric Commercial Vehicles Market Strategic Shifts
Powertrain technology commitments are diverging across national subsidy phase-out schedules and charging infrastructure readiness, creating divergent fleet procurement strategies within the same regional market.
Silicon-anode battery chemistries are fragmenting the energy density landscape for heavy-duty commercial vehicles. Fleet operators in Australia's mining logistics and New Zealand's alpine freight routes are piloting these configurations to achieve 800+ kilometer ranges without mid-route charging. This technology is fragmenting the traditional segmentation between battery-electric and fuel-cell powertrains for extreme-duty cycles.
India's CEA interoperability protocols are mandating open-network access for all public charging stations above 50 kW capacity. This regulatory shift is dismantling proprietary charging networks operated by individual OEMs, forcing hardware standardization and payment system consolidation. Light-duty delivery fleets across Maharashtra and Karnataka are responding by consolidating procurement around vehicles compatible with universal charging access.
Fleet operators are unbundling after-sales service contracts from vehicle procurement, selecting third-party maintenance providers based on technician certification rather than OEM affiliation. This behavioral shift is disrupting traditional dealer networks in Thailand and Malaysia. Large logistics consolidators in Bangkok's port corridor are most visible in this transition, signing multi-year service agreements with independent high-voltage specialists.
Asia Pacific Electric Commercial Vehicles Market Segmentation
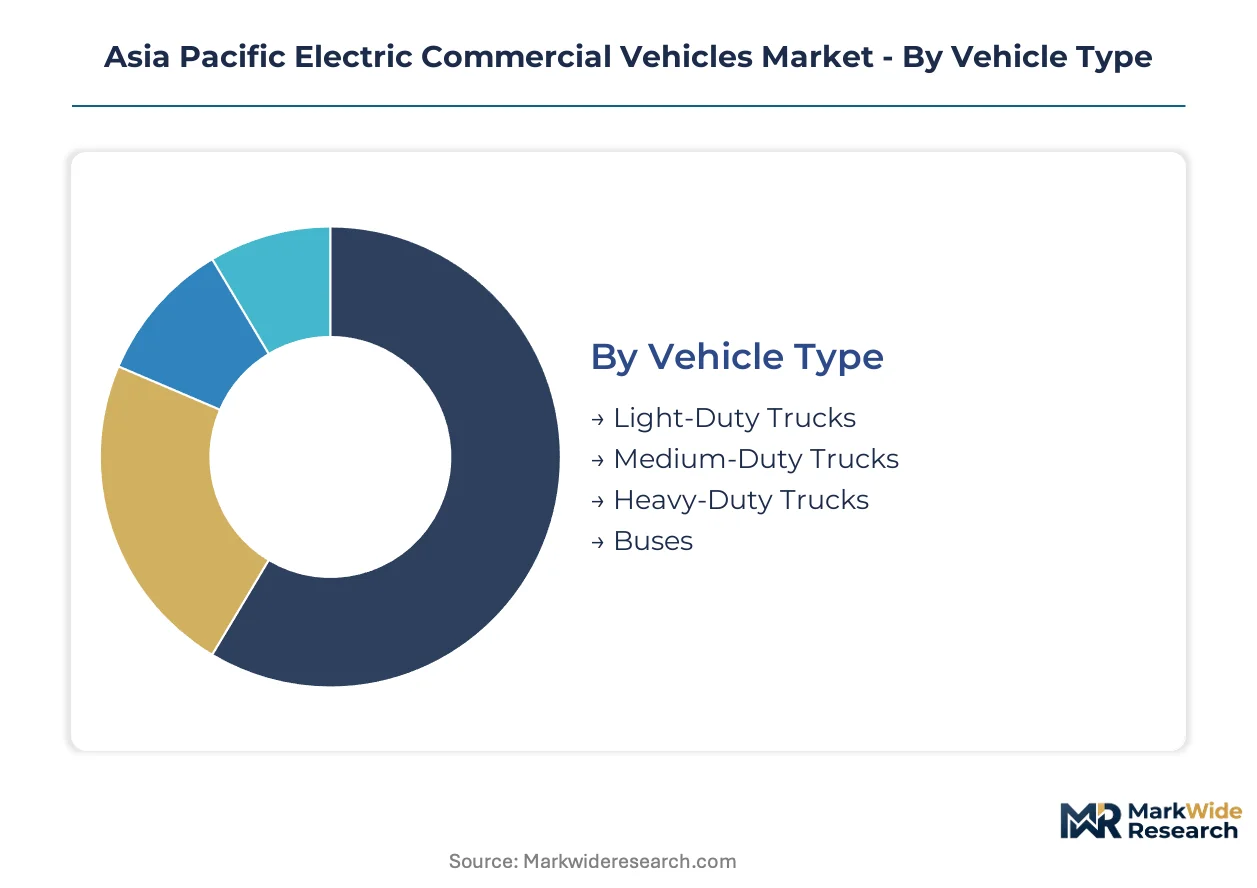
Segmentation in Asia Pacific electric commercial vehicles reveals how powertrain economics and infrastructure readiness diverge across fleet operator budgets and route profiles. Procurement patterns cluster sharply around vehicle duty cycles and charging accessibility rather than brand loyalty.
Vehicle Type:
Substitution pressure from electrification varies dramatically by payload class, with light-duty segments facing imminent displacement from diesel while heavy-duty applications confront persistent range and charging constraints.
- Light-Duty Trucks:Gross vehicle weights below 3.5 tonnes dominate urban last-mile logistics across China's Yangtze River Delta and India's Maharashtra corridor. E-commerce fulfillment networks in Ho Chi Minh City and Jakarta are consolidating procurement around these configurations as battery pack costs compress total cost of ownership calculations below diesel equivalents.
- Buses:Fixed-route scheduling and depot-based overnight charging eliminate range anxiety that plagues variable-route freight applications. State-owned transport corporations in China's megacity clusters and India's metropolitan bus undertakings are mandating 100% electric procurement for new fleet additions, creating guaranteed demand visibility unmatched by commercial trucking segments.
- Medium-Duty Trucks:Distribution applications between 3.5 and 12 tonnes serve intercity freight corridors with moderate daily distances.
- Heavy-Duty Trucks:Long-haul routes exceeding 500 kilometers daily face persistent payload penalties from battery mass and charging downtime economics.
Light-Duty Trucks anchors the volume base while Buses gains share at the steepest rate.
Powertrain Technology:
Cost tier stratification separates premium battery-electric configurations from transitional hybrid architectures as cell chemistry improvements compress the viable use-case overlap.
- Battery Electric:Lithium iron phosphate and nickel manganese cobalt chemistries above 150 kWh enable continuous-duty operations in China's port electrification zones. India's PLI scheme for advanced chemistry cell manufacturing is localizing pack assembly and reducing import dependency for fleet operators in Karnataka and Tamil Nadu.
- Plug-in Hybrid:Archipelago nations including Indonesia and the Philippines retain structural relevance for this configuration where grid reliability gaps and inter-island ferry logistics preclude pure electric deployment.
- Fuel Cell:Japan's METI coordinates highway corridor demonstrations targeting heavy-duty routes beyond battery-electric range limits.
- Others:Emerging powertrain architectures including range-extended electric and swappable battery systems pilot in niche applications.
Battery Electric captures the dominant procurement share while Fuel Cell climbs the fastest among emerging configurations.
Application:
Application-specific duty cycles determine charging infrastructure investment viability and thus electrification feasibility across fleet operator categories.
- Logistics:Scheduled depot returns and predictable daily distances enable overnight charging optimization. Third-party logistics consolidators in Bangkok's port corridor and Singapore's container terminals are unbundling after-sales service contracts to select maintenance providers based on high-voltage technician certification rather than OEM affiliation.
- Public Transportation:Government fleet contracts provide procurement certainty and charging infrastructure co-investment that commercial operators cannot replicate.
- Freight Delivery:Variable route patterns and customer-dictated scheduling create charging coordination complexity absent in fixed-route applications.
- Waste Management:Stop-start urban collection routes with low average speeds minimize energy consumption and maximize regenerative braking recovery.
Logistics anchors the volume base while Public Transportation gains share at the steepest rate.
Charging Infrastructure:
Geographic concentration of charging asset deployment creates divergent fleet procurement strategies between coastal corridor operators and interior logistics providers.
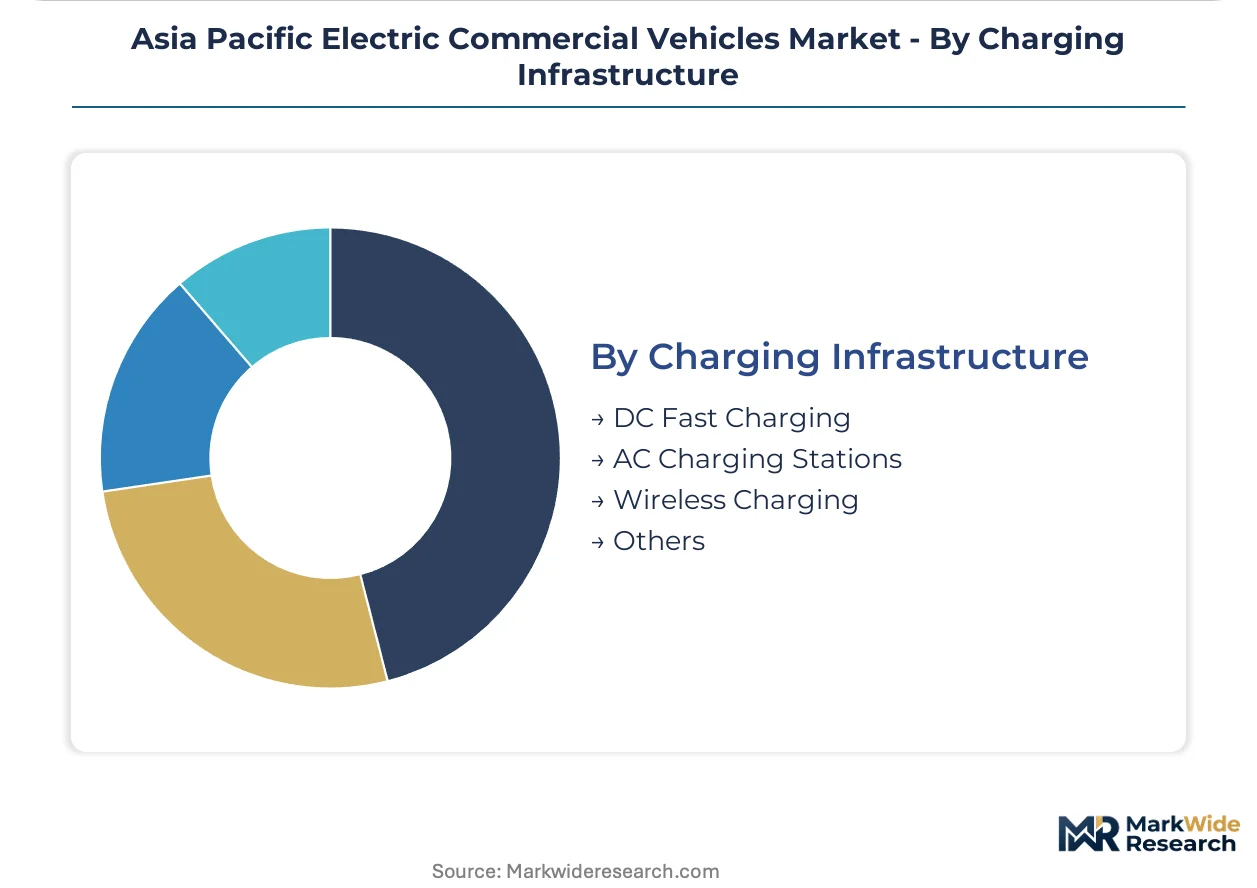
- DC Fast Charging:Depot-based fleet scheduling and opportunity charging at logistics hubs drive the fastest infrastructure expansion trajectory. India's CEA interoperability protocols mandate standardized payment and connector systems above 50 kW capacity, dismantling proprietary OEM networks and enabling cross-fleet access.
- AC Charging Stations:Overnight depot charging dominates light-duty fleet operations where dwell times exceed eight hours.
- Wireless Charging:Inductive systems pilot at bus terminals and automated logistics facilities in Japan and South Korea.
- Others:Battery swapping stations and overhead catenary systems serve niche applications in Chinese mining logistics and port drayage operations.
DC Fast Charging anchors the volume base while Wireless Charging gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT's GB standards enforcement anchors procurement patterns across the region's dominant geography. India's CEA interoperability protocols and Japan's METI corridor demonstrations create divergent regulatory frameworks that reshape fleet operator strategies.
China
Yangtze River Delta megacity clusters drive battery-electric truck demand through port electrification mandates at Shanghai and Ningbo-Zhoushan terminals. MIIT enforces GB standards for commercial EV safety and battery thermal management, compressing new model launch timelines. Dense charging networks in Jiangsu and Zhejiang provinces enable continuous-duty freight operations for urban logistics fleets.
India
Maharashtra and Karnataka corridors concentrate light-duty electric truck procurement as e-commerce fulfillment networks expand. CEA mandates interoperability protocols for public charging networks above 50 kW capacity, dismantling proprietary OEM networks. Tamil Nadu's advanced chemistry cell manufacturing clusters under the PLI scheme localize battery pack assembly for fleet operators.
Japan
METI coordinates hydrogen fuel cell truck demonstrations through designated highway corridors targeting heavy-duty routes beyond battery-electric range limits. Kanto and Kansai industrial belts pilot wireless inductive charging at bus terminals and automated logistics facilities. Regulatory tailwinds favor zero-emission long-haul configurations for alpine freight routes.
South Korea
Seoul Capital Area logistics operators consolidate depot-based overnight charging with solar generation integration to reduce grid dependency. Busan-Ulsan port complexes enforce emission reduction timelines for container drayage fleets. Government fleet contracts for metropolitan bus undertakings mandate electric procurement for new additions.
Vietnam
Ho Chi Minh City and Hanoi present underpenetrated last-mile delivery electrification opportunities as urban freight demand accelerates. Grid reliability gaps in secondary cities constrain pure battery-electric deployment, preserving plug-in hybrid relevance. Technician scarcity across Southeast Asian service networks extends vehicle downtime and unwinds fleet electrification timelines.
Asia Pacific Electric Commercial Vehicles Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Asia Pacific electric commercial vehicles landscape. The market structure consolidates around integrated battery manufacturers, state-affiliated automotive groups, and multinational truck manufacturers with localized engineering capabilities. Three strategic archetypes dominate: vertically integrated cell-to-vehicle producers, government fleet contract specialists, and charging corridor partnership builders. Competitive intensity centers on capacity expansion for lithium iron phosphate pack assembly and strategic partnerships for DC fast charging network deployment.
Within the integrated manufacturing tier, BYD Company and Yutong Bus occupy positions exemplifying cost leadership through captive battery supply chains. Dongfeng Motor and Tata Motors represent state-affiliated and nationally anchored archetypes respectively, securing government fleet contracts through localized powertrain engineering. Daimler Trucks anchors the multinational premium segment, competing through established service networks and heavy-duty platform expertise.
| Leading Market Players |
|---|
| BYD Company |
| Yutong Bus |
| Dongfeng Motor |
| Tata Motors |
| Daimler Trucks |
| Mitsubishi Motors |
| Wuling Motors |
| General Motors |
| Ford Motor Company |
| Others |
Value Chain & Pricing Dynamics
Cell manufacturing scale economies in China's Yangtze River Delta and India's Tamil Nadu corridor compress pack assembly costs and establish regional price floors that undercut imported alternatives. This geographic concentration of lithium iron phosphate capacity grants domestic fleet operators procurement leverage while forcing multinational OEMs to localize or surrender margin.
Pricing Analysis
Price spreads between coastal Chinese provinces and interior Southeast Asian markets exceed twenty percent due to logistics premiums and import duties on battery packs. Pricing stratifies across premium heavy-duty platforms with nickel manganese cobalt chemistries, standard medium-duty configurations using lithium iron phosphate, and economy light-duty variants with reduced energy density. Cost compression in standard tiers is intensifying because India's PLI scheme subsidizes local cell assembly. Third-party logistics consolidators exhibit highest price sensitivity, while government bus undertakings prioritize total cost of ownership over upfront capital outlay.
Supply Chain Analysis
China and South Korea anchor cathode active material production and cell assembly capacity for commercial vehicle battery packs. Raw material procurement draws from Indonesian nickel processing, Australian lithium spodumene, and Chilean carbonate refining. Single-source vulnerability concentrates in separator films and electrolyte salts where Japanese and Chinese suppliers dominate. Distribution runs through OEM-captive depot networks for fleet operators and independent charging hub operators for fragmented commercial buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation across Asia Pacific logistics corridors is shifting procurement leverage toward volume buyers capable of dictating powertrain specifications and charging infrastructure co-investment terms.
For Market Incumbents: Secure captive battery supply through joint ventures with cell manufacturers in India and Vietnam before PLI scheme benefits expire. Defend service network density by certifying independent high-voltage technicians to offset technician scarcity that extends vehicle downtime. Prioritize software-defined vehicle architectures that enable over-the-air thermal management updates, reducing recall exposure under MIIT's evolving GB standards. For New Entrants and Emerging Players: Differentiate on depot charging integration by bundling solar generation and overnight DC fast charging hardware with vehicle sales. Target Vietnamese urban freight corridors where e-commerce fulfillment networks lack established OEM relationships and grid reliability gaps preserve plug-in hybrid viability. Pursue white-label manufacturing partnerships with state-affiliated automotive groups to bypass lengthy GB standard certification timelines. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among charging infrastructure operators with fleet management software platforms that lock in multi-year service agreements. Long-term viability favors asset-light technology licensors over capital-intensive vehicle manufacturers given subsidy phase-out trajectories. Monitor Japan's METI hydrogen corridor demonstration outcomes as the inflection signal for fuel cell powertrain relevance in heavy-duty applications.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium iron phosphate capacity from Tamil Nadu PLI beneficiaries for medium-duty truck platforms. |
| Charging Infrastructure Partnership | Deploys interoperable DC fast charging corridors along Maharashtra logistics routes per CEA mandates. |
| Software-Defined Vehicle Investment | Enables remote thermal management calibration to accelerate MIIT GB standard compliance validation. |
| Geographic Manufacturing Footprint | Localizes pack assembly in Indonesia to circumvent technician scarcity and import duty exposure. |
| Platform Standardization | Consolidates light-duty architectures across ASEAN markets to achieve component scale economies. |
Study Parameters
Cross-validation between fleet operator procurement directors and charging infrastructure developers anchors the qualitative findings on electrification timeline compression. Primary interviews with OEM platform engineers, commercial vehicle fleet managers, battery cell procurement leads, and regulatory affairs specialists at MIIT and CEA inform technology adoption assumptions. Secondary validation incorporates vehicle production databases, customs trade records for lithium-ion cell imports, and public charging network registration filings. Bottom-up fleet operator demand modeling triangulates against top-down powertrain production capacity estimates.
Sensitivity analysis on cell cost decline trajectories and subsidy phase-out schedules shapes the projection framework across vehicle class, powertrain architecture, and regional regulatory cluster dimensions. CAGRs derive from installed base turnover rates and replacement demand elasticities modeled through the forecast period. Industry-specific inputs include GB standard certification timelines, PLI scheme disbursement schedules, and depot charging utilization curves from logistics hub operators.
Material uncertainties — battery chemistry disruption, grid reliability deterioration, trade restriction escalation — sit outside the modeled envelope. Forecasts reflect assumptions on policy continuity and infrastructure buildout pace that industry participants have disclosed. Recalibration cycles align with material shifts in national subsidy schedules and charging network deployment milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Automotive Intelligent Battery Sensor Market
Electric Vehicles
Oman Electric Vehicle (EV) Market
Electric Vehicles
Europe Wireless Electric Vehicle Charging Market
Electric Vehicles
Electric Transporters Market
Electric Vehicles
Pedelec Market
Electric Vehicles
Automotive Battery Thermal Management System Market
Electric Vehicles
Electric Vehicle Control Unit Market
Electric Vehicles
Canada Solar E-Bike Market
Electric Vehicles
North America Automotive High Performance Electric Vehicle Market
Electric Vehicles
Automotive EV HUB Market
Electric Vehicles
Electric Vehicle on Board Charger Market
Electric Vehicles
Electric Vehicle Reducer Market
Electric Vehicles
Electric Vehicle NVH Material Market
Electric Vehicles
Electric Axle Drive Systems Market
Electric Vehicles
Automotive Electric Vehicle Power System Market
Electric Vehicles
Used EV Market