
 Automotive EMI Shielding Market | 2026-2036
Automotive EMI Shielding Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive EMI Shielding Market Analysis
IATF 16949 qualification is reorganizing supplier tiers across the automotive EMI shielding landscape. Henkel AG & Co. KGaA leverages its adhesive-conductive coating portfolio to anchor European OEM supply chains. TE Connectivity sustains leadership in shielded cable architectures for high-voltage electric platforms. Parker Hannifin Corp competes through integrated gasket and sealing solutions that address thermal-EMI convergence.
Automotive EMI shielding encompasses conductive materials and engineered barriers that attenuate electromagnetic interference across frequencies from kilohertz to gigahertz, typically achieving 40–100 dB suppression through metallic deposition, particle-filled composites, or woven mesh architectures. Its primary purpose is ensuring functional coexistence of densely packed electronic control units, radar modules, and telematics hardware without signal degradation or safety-critical failure. Conductive coatings command established volume positions due to compatibility with complex geometries and plastic substrates, while shielded cables capture premium value as 800V architectures proliferate. EMI gaskets face margin compression from material cost volatility in copper and nickel feedstocks, though conductive elastomer formulations are gaining specification share for vibration-damped sealing joints.
The U.S. FCC Part 15 emissions framework and Europe's ECE R10 directive collectively mandate electromagnetic compatibility validation before vehicle type approval, directly shaping test protocol investments and material qualification timelines. China's GB/T standards for automotive electromagnetic environments add a third compliance layer for suppliers serving domestic EV manufacturers. OEMs and Tier-1 suppliers must monitor regulatory divergence between these jurisdictions when selecting shielding architectures, as regional test method differences can invalidate cross-certified designs.
Market Dynamics
Electric vehicle powertrain electrification is compressing electromagnetic compatibility margins as 800V architectures multiply high-frequency switching noise sources across densely packaged control modules.
Growth Catalysts
- High-Voltage Platform Proliferation:Battery electric vehicle architectures above 400V are mandating upgraded shielding specifications for inverter and DC-DC converter housings to prevent capacitive coupling failures.
- ECE R10 Compliance Intensification:Europe's tightened electromagnetic compatibility type-approval requirements are forcing recertification cycles that expand material qualification volumes for shielding suppliers.
- ADAS Sensor Density:Radar and lidar module clustering in front-end assemblies is creating localized interference zones that demand site-specific shielding engineering rather than blanket solutions.
Market Restraints
- Copper-Nickel Feedstock Volatility:Conductive particle costs in EMI gasket formulations fluctuate with London Metal Exchange pricing, compressing margin stability for compounders serving Tier-2 contracts.
- Regional Certification Fragmentation:Divergent test protocols between FCC Part 15, ECE R10, and China's GB/T standards force redundant validation investments that delay cross-regional product launches.
- Thin-Film Conductive Coating Limits:Sputtered metal layers below 5 microns struggle to maintain shielding effectiveness above 6 GHz, constraining 5G telematics integration without thicker, costlier deposition.
Strategic Opportunities
- India EV Manufacturing Localization:Domestic production incentives under the country's automotive PLI scheme are attracting shielding suppliers to establish captive coating and gasket operations near Chennai and Pune assembly corridors.
- Thermal-EMI Convergence Products:Integrated phase-change materials with conductive fillers address simultaneous heat dissipation and electromagnetic attenuation needs in power-dense motor controllers.
- Recyclable Conductive Polymers:Bio-based filler matrices compatible with existing injection molding infrastructure open specification pathways as OEM sustainability scorecards weight circular material content.
Industry Challenges
- Multi-Physics Simulation Talent Scarcity:Electromagnetic, thermal, and mechanical co-design capabilities remain concentrated among a narrow pool of specialized CAE engineers, elongating product development timelines.
- IATF 16949 Audit Backlogs:Certification body capacity constraints are extending supplier qualification periods, delaying new market entrants from securing approved vendor status with established OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive EMI Shielding Market |
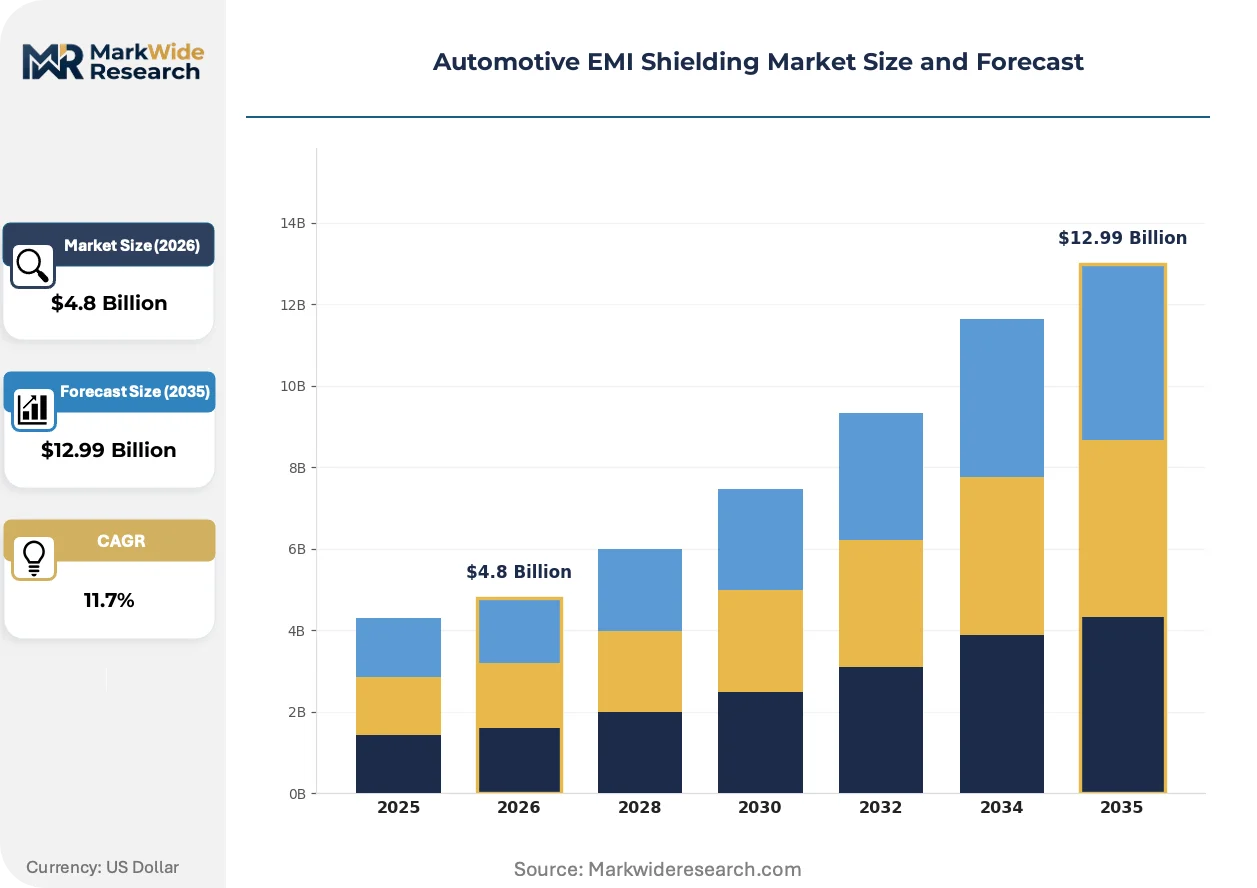
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conductive Coatings, EMI Gaskets, Metal Mesh, Shielded Cables Material: Copper, Aluminum, Conductive Elastomers, Nickel Application: Powertrain Electronics, Infotainment Systems, Safety Systems, Body Control Modules End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Henkel AG & Co. KGaA, Leader Tech Inc., Parker Hannifin Corp, Nolato AB, TE Connectivity, PPG Industries Inc, Laird Technologies, RTP Company, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive EMI Shielding Market Emerging Trajectories
Material architectures are converging with thermal management functions while deposition techniques adapt to complex polymer geometries. Three developments are restructuring competitive positioning.
Printed conductive ink systems are replacing conventional metal deposition for antenna housing and sensor enclosure applications. Tier-1 electronics suppliers are qualifying aerosol-jet and screen-printed silver formulations for mid-volume electric vehicle programs. This approach is miniaturizing shielding layer thicknesses while maintaining 60–80 dB attenuation across targeted frequency bands.
Europe's ECE R10 directive revision is tightening radiated emission limits for vehicle categories M and N, effective for type approvals submitted after regulatory transition periods. Test houses in Germany and the Czech Republic are expanding chamber capacity to accommodate combined immunity and emissions validation. Shielded cable assemblies for high-voltage traction systems face the steepest retesting burden as voltage classes climb.
Automotive electronics buyers are consolidating supplier panels around vertically integrated coating-to-assembly providers capable of delivering validated subsystem solutions. This pattern displaces discrete component sourcing for multi-layer shielding stacks. German and Japanese OEM procurement organizations are most advanced in this transition, specifying functional performance guarantees rather than material specifications.
Automotive EMI Shielding Market Segmentation
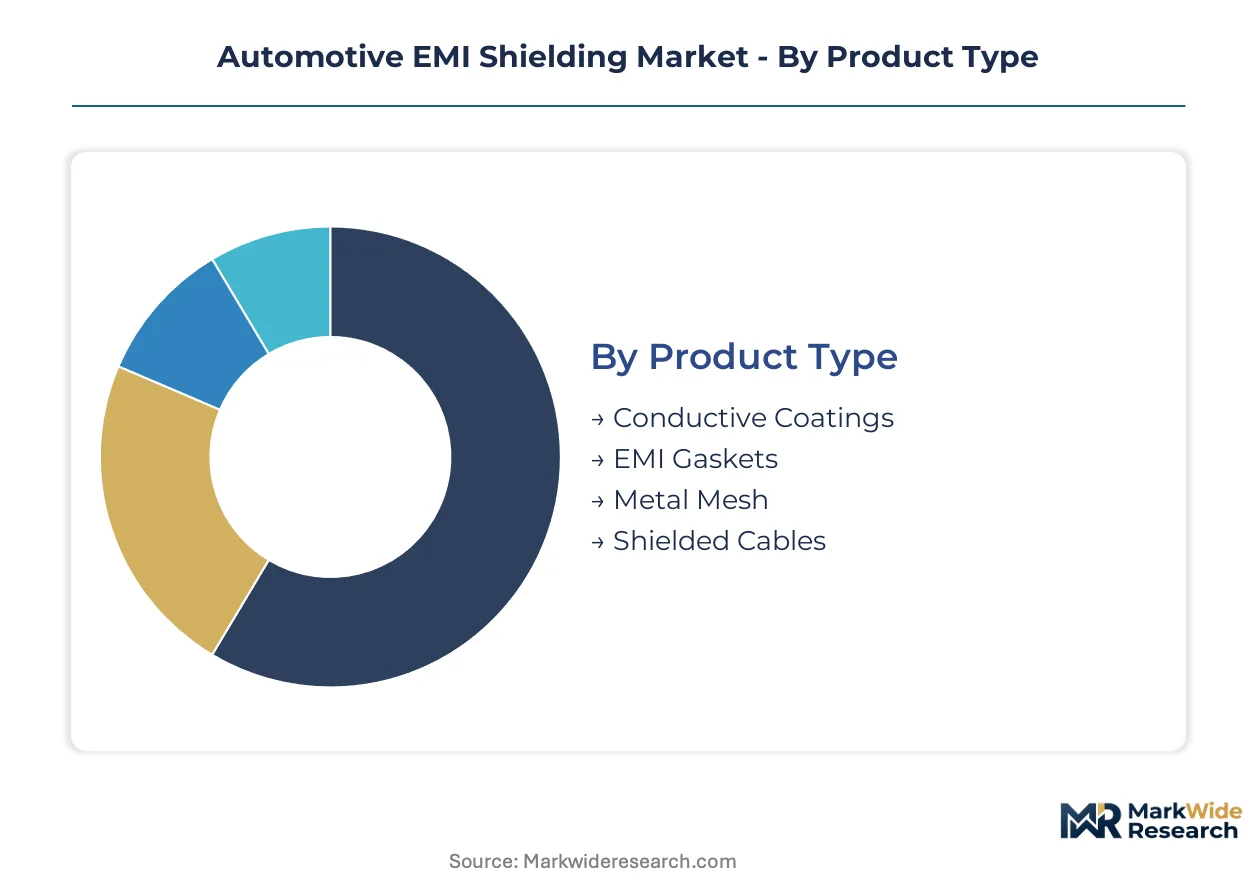
Automotive EMI shielding segmentation reveals divergent supply chain configurations across product categories. Material selection and application targeting determine whether suppliers serve domestic assembly plants or export-oriented manufacturing corridors.
Product Type:
Conductive coatings and shielded cables concentrate in Germany's automotive manufacturing corridor for European OEM supply, while EMI gaskets and metal mesh serve broader export markets from Asian production bases.
- Conductive Coatings:Sputtered or sprayed metallic layers—typically silver, copper, or nickel—achieve 40–80 dB attenuation on plastic housings for radar modules and telematics units. Demand clusters around Stuttgart and Munich assembly corridors serving BMW, Mercedes-Benz, and Volkswagen electric platforms, driven by 800V architecture proliferation requiring upgraded housing specifications.
- Shielded Cables:Multi-layer constructions with braided copper or aluminum shields protect high-voltage traction system signaling from capacitive coupling failures. European ECE R10 recertification cycles are expanding qualification volumes for cable assemblies above 400V, particularly for inverter-to-motor connections in battery electric vehicles.
- EMI Gaskets:Conductive particle-filled elastomers provide vibration-damped sealing for control module enclosures. Copper-nickel feedstock volatility from London Metal Exchange pricing compresses margin stability for compounders.
- Metal Mesh:Woven or expanded metal screens deliver broadband shielding for large apertures and ventilation panels. Specifications favor aluminum variants for weight-sensitive applications.
Conductive coatings command the established base. The steepest expansion runs through shielded cables.
Material:
Cost tier stratification separates premium copper and nickel formulations from standard aluminum and economy conductive elastomer grades, with pricing gaps widening based on conductivity requirements and corrosion resistance specifications.
- Copper:Highest conductivity material achieving superior shielding effectiveness across kilohertz to gigahertz ranges, specified for safety-critical ADAS modules where signal integrity failures carry liability exposure. Premium positioning reflects London Metal Exchange price linkage and limited substitution options for 5G telematics frequencies above 6 GHz.
- Aluminum:Lightweight alternative with 60% conductivity of copper, dominant in volume applications where 40–60 dB attenuation suffices. German and Czech test houses specify aluminum-cored cables for combined immunity and emissions validation under tightened ECE R10 radiated emission limits.
- Conductive Elastomers:Silicone or fluorocarbon matrices loaded with silver-plated glass spheres or carbon particles. Injection molding compatibility enables complex gasket geometries for power-dense motor controllers.
- Nickel:Corrosion-resistant plating material for coastal market vehicles and underbody applications. Magnetic properties extend shielding effectiveness to lower frequency ranges.
Copper retains premium specification share. Aluminum gains volume fastest through high-voltage platform standardization.
Application:
Application targeting separates suppliers serving thermal-EMI convergence needs in powertrain electronics from those addressing infotainment frequency management and safety system functional coexistence requirements.
- Powertrain Electronics:Inverter housings, DC-DC converters, and onboard chargers generate the highest switching noise densities, demanding integrated phase-change materials with conductive fillers. India's PLI scheme incentives are attracting coating and gasket operations near Chennai and Pune to serve domestic EV manufacturing localization.
- Safety Systems:Airbag control modules, anti-lock braking systems, and steering angle sensors require fail-operational electromagnetic compatibility under ISO 11452 immunity test protocols. China's GB/T standards add domestic compliance layers for suppliers serving BYD and NIO platforms.
- Infotainment Systems:5G telematics, V2X communication modules, and center stack displays face thin-film conductive coating limits below 6 GHz without thicker, costlier deposition layers.
- Body Control Modules:Door control units, lighting controllers, and climate management systems represent established specification volumes with slower technology turnover.
Powertrain electronics anchor material demand. Safety systems are climbing the fastest on regulatory compliance intensification.
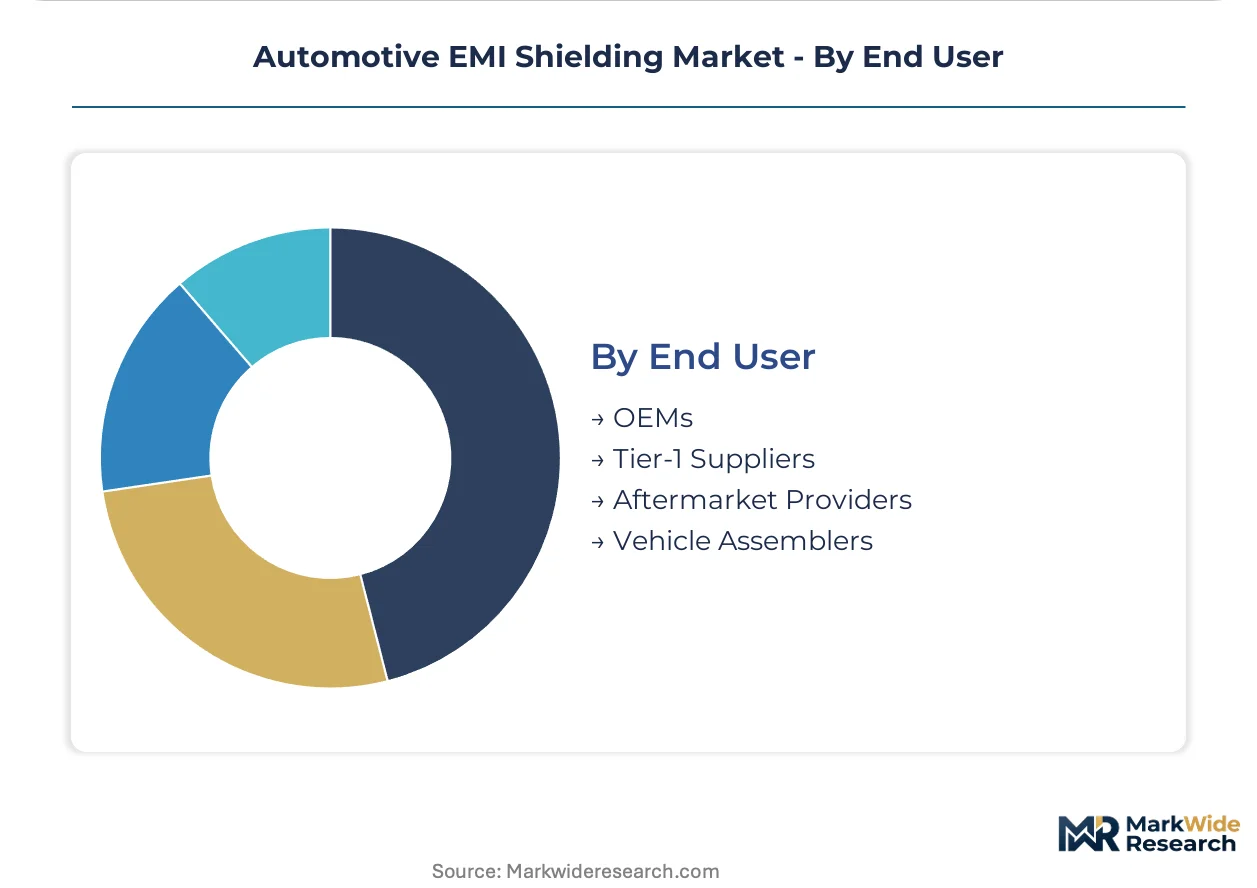
End User:
Customer type determines procurement pattern complexity, with OEM direct relationships demanding IATF 16949 certification and Tier-1 suppliers consolidating around vertically integrated coating-to-assembly providers.
- OEMs:Volkswagen, BMW, Mercedes-Benz, and Stellantis procurement organizations specify functional performance guarantees rather than material specifications, displacing discrete component sourcing for multi-layer shielding stacks. German and Japanese OEMs lead this transition.
- Tier-1 Suppliers:Continental, Bosch, and ZF Friedrichshafen aggregate shielding into validated subsystem solutions, consolidating supplier panels around providers with captive coating, gasket, and cable assembly capabilities.
- Vehicle Assemblers:Contract manufacturers and joint venture operations in emerging EV production corridors source qualified components from approved vendor lists without direct material specification authority.
- Aftermarket Providers:Repair and retrofit channels for collision replacement and classic vehicle electromagnetic upgrades represent fragmented demand with limited standardization.
OEMs and Tier-1 suppliers concentrate procurement authority. Aftermarket channels expand most quickly on vehicle electrification retrofit demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive EMI shielding procurement concentrates among German OEMs, Chinese EV manufacturers, and U.S. Tier-1 electronics suppliers, with each buyer archetype driving distinct material qualification timelines and certification requirements.
Germany
Stuttgart and Munich assembly corridors anchor European demand for conductive coatings on 800V inverter housings. ECE R10 recertification cycles are expanding test chamber capacity at German and Czech validation facilities. Henkel AG & Co. KGaA leverages its adhesive-conductive portfolio to secure multi-year supply agreements with BMW and Mercedes-Benz procurement organizations.
United States
Detroit-area OEMs and Silicon Valley EV startups are consolidating supplier panels around vertically integrated coating-to-assembly providers. FCC Part 15 emissions frameworks mandate pre-market electromagnetic compatibility validation. TE Connectivity sustains specification leadership for shielded cable architectures serving high-voltage traction systems.
China
BYD and NIO platforms are driving domestic qualification volumes under GB/T automotive electromagnetic environment standards. MIIT regulations add compliance layers for suppliers serving battery electric vehicle programs. Shanghai and Shenzhen manufacturing corridors concentrate conductive elastomer compounding capacity for power-dense motor controllers.
India
Chennai and Pune assembly corridors are attracting captive coating and gasket operations under the automotive PLI scheme. Domestic EV production incentives compress supplier establishment timelines. BIS standards for electromagnetic compatibility are converging with ECE R10 test protocols to streamline export qualification.
Japan
Kanto and Kansai electronics clusters specify fail-operational shielding for ISO 11452 immunity protocols on safety-critical modules. METI guidelines for automotive electromagnetic environments shape material selection for radar and lidar integration. Toyota and Honda procurement organizations are consolidating multi-layer shielding stack sourcing.
Automotive EMI Shielding Market Vendor Landscape
Player mix skews toward diversified materials conglomerates with adhesive and coating heritage, creating tiered competition between full-stack subsystem providers and discrete component specialists. Strategic archetypes separate vertically integrated coating-to-assembly operators from conductive particle compounders and specialized cable fabricators. Dominant competitive moves include IATF 16949 qualification investments and captive supply chain establishment near emerging EV production corridors.
Among diversified materials conglomerates, Henkel AG & Co. KGaA and 3M occupy positions anchored by adhesive-conductive technology portfolios, while TE Connectivity exemplifies the cable-centric archetype serving high-voltage platform proliferation. These three entities represent distinct competitive vectors: European chemical heritage, U.S. multi-industrial scale, and connectivity-focused subsystem integration. Each anchors supplier tier consolidation patterns visible across German, Japanese, and North American OEM procurement organizations.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Leader Tech Inc. |
| Parker Hannifin Corp |
| Nolato AB |
| TE Connectivity |
| PPG Industries Inc |
| Laird Technologies |
| RTP Company |
| 3M |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at German and Czech test houses shapes both supply concentration and price floors for shielding materials, as ECE R10 recertification cycles compress lead times for validated components. OEM procurement consolidation around vertically integrated coating-to-assembly providers concentrates pricing power among IATF 16949-qualified suppliers while squeezing Tier-2 compounders serving spot-market gasket demand.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate conductive elastomer and metal-plated component sourcing, tying Tier-2 supplier margins to copper-nickel feedstock volatility. Three-tier pricing structure across premium, standard, and economy levels separates fail-operational ADAS specifications from volume body control module applications, with certification grade and volume scale as primary differentiation drivers. Cost compression in EMI gasket formulations is intensifying because OEMs are consolidating supplier panels around subsystem providers. Aftermarket channels exhibit highest price sensitivity due to fragmented demand and limited standardization, while safety system specifications show lowest sensitivity given liability exposure from signal integrity failures.
Supply Chain Analysis
Inventory buffers for conductive particle feedstocks stretch to 12-16 weeks at compounders serving European OEMs, reflecting just-in-sequence delivery requirements for Stuttgart and Munich assembly corridors. Supply concentrates in Germany for conductive coatings, China for conductive elastomer compounding, and the United States for shielded cable architectures. Raw material dependencies center on copper and nickel from London Metal Exchange-linked sources, silver-plated glass spheres from specialized chemical processors, and aluminum for weight-sensitive mesh applications. Single-source vulnerability around IATF 16949-qualified coating operations poses structural risk as certification body backlogs extend qualification timelines. Distribution runs through Tier-1 electronics aggregators that validate subsystem solutions before OEM platform integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among German and Japanese OEM procurement organizations that specify functional performance guarantees rather than material specifications, displacing discrete component sourcing and compressing margins for non-integrated suppliers.
For Market Incumbents: Secure IATF 16949 certification body relationships ahead of audit queue expansion, as backlogs are extending supplier qualification periods and delaying approved vendor status. Deepen backward integration into conductive particle compounding to defend against London Metal Exchange price volatility eroding gasket margins. Capacity addition near Chennai and Pune corridors captures India's PLI scheme incentives before domestic coating operations saturate. For New Entrants and Emerging Players: Anchor in India's automotive PLI scheme corridors where domestic EV production incentives compress supplier establishment timelines and BIS standards convergence with ECE R10 streamlines export qualification. Target thermal-EMI convergence products for power-dense motor controllers as the most penetrable application segment, where integrated phase-change materials with conductive fillers address simultaneous heat dissipation and electromagnetic attenuation needs. Pursue qualification partnerships with established Tier-1 electronics aggregators rather than direct OEM engagement. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated coating-to-assembly providers with captive conductive particle operations and validated subsystem capabilities. Long-term viability hinges on 800V platform proliferation sustaining premium shielding specifications through the electrification transition. Acquisition target archetype: mid-cap specialists with IATF 16949 qualification and thermal-EMI convergence R&D pipelines. Monitor ECE R10 test chamber capacity expansion as inflection indicator for recertification cycle intensity and material qualification volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| IATF 16949 Certification Investment | Secures approved vendor status with BMW, Mercedes-Benz, and Volkswagen procurement organizations. |
| Backward Integration into Conductive Particle Compounding | Insulates margin stability from London Metal Exchange copper-nickel price volatility. |
| Captive Coating Operation Establishment in India | Captures PLI scheme incentives near Chennai and Pune EV assembly corridors. |
| Thermal-EMI Convergence Product Development | Addresses simultaneous heat dissipation and electromagnetic attenuation in 800V motor controllers. |
| ECE R10 Test Chamber Capacity Expansion | Accommodates tightened radiated emission limits and combined immunity validation cycles. |
Methodological Framework
Operator-level perspectives from Tier-1 supplier procurement managers, OEM platform engineers, conductive particle compounders, and ECE R10 test house directors anchored the qualitative base for this analysis. Primary interview insights combined with secondary validation from vehicle production databases, IHS Markit registration data, SEC filings of diversified materials conglomerates, and London Metal Exchange price series. Bottom-up segment sizing triangulated against top-down OEM electrification roadmap analysis.
Sensitivity analysis around 800V platform adoption rates, IATF 16949 certification timeline assumptions, and copper-nickel feedstock price trajectories informed forecast robustness across the projection horizon. Segmentation dimensions modeled include product type, material grade tier, application targeting, and end-user procurement pattern. CAGRs derived from vehicle electrification content-per-vehicle scaling and regional production cluster growth trajectories, with specific inputs from ECE R10 regulatory transition schedules and PLI scheme incentive disbursement patterns.
Decision-makers should treat outputs as directional under base assumptions of sustained OEM procurement consolidation and 800V architecture proliferation; material deviation in electrification adoption rates or regulatory harmonization progress would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Europe Automotive LED Lighting Market
Automotive Electrical & Electronics
Europe Electric Power Steering Market
Automotive Electrical & Electronics
Automotive Digital Key Market
Automotive Electrical & Electronics
Automotive Pressure Sensors Market
Automotive Electrical & Electronics
China Automotive Electric Power Steering (EPS) Market
Automotive Electrical & Electronics
Automotive Ultracapacitor Market
Automotive Electrical & Electronics
Automotive UPS (in Vehicle UPS) Market
Automotive Electrical & Electronics
Automotive Thermal Management System Market
Automotive Electrical & Electronics
Electric Vehicle HV Cables Market
Automotive Electrical & Electronics
Automotive E-Axle Disconnect Actuator Market
Automotive Electrical & Electronics
E-Bike Lights Market
Automotive Electrical & Electronics
Automotive Electronic Logging Device (ELD/E-Log) Market
Automotive Electrical & Electronics
On-Board Fuse Box Market
Automotive Electrical & Electronics
Automotive Ecall Market
Automotive Electrical & Electronics
Europe Automotive Steering Sensor Market
Automotive Electrical & Electronics
Global Automotive DC-DC Converters Market