
 Vietnam Electric Vehicle Market | 2026-2036
Vietnam Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Electric Vehicle Market Insights
Market Context with Strategic Players
Dealer networks and direct-to-consumer platforms are reconfiguring how Vietnamese buyers access electric vehicles. VinFast Motor Ltd. leverages its captive retail footprint and domestic battery manufacturing to control pricing and delivery timelines. Hyundai Motor Company competes through hybrid-to-full-EV transition programs tailored to Vietnamese urban commutes. BYD Auto Co. Ltd anchors its position in the commercial bus segment with municipal procurement contracts in Da Nang and Hai Phong.
Technical Definition and Structural Segments
Vietnam electric vehicles encompass battery-electric and plug-in hybrid road vehicles engineered with lithium-ion or solid-state battery packs, typically delivering 150-500 km range per charge for passenger applications. These vehicles serve industrial logistics, urban mobility services, and private transportation while reducing petroleum import dependency in a country where crude oil constitutes a major trade deficit item. Passenger cars and two-wheelers dominate volume, with two-wheelers commanding the largest installed base due to Vietnam's status as one of the world's highest per-capita motorcycle markets. Fast chargers and battery swapping stations represent the fastest-expanding charging infrastructure category, though home chargers still capture the majority of overnight replenishment demand. Solid-state battery technology remains nascent in Vietnam, with lithium-ion chemistry sustaining near-total market share and margin concentration flowing to integrated cell-pack-vehicle producers.
Regulatory Frame and Forward-Looking Close
Vietnam's Ministry of Transport, the Vietnam Register under the Ministry of Transport, and the Ministry of Industry and Trade collectively shape EV policy through registration fee exemptions, import tariff schedules, and charging infrastructure standards. The country's national power development plan and EV manufacturing incentives are compressing payback periods for fleet operators while mandating local content thresholds that protect domestic assembly. Stakeholders must monitor how Vietnam's evolving grid capacity commitments and renewable energy purchase obligations interact with charging load profiles across the northern, central, and southern economic zones.
Market Dynamics
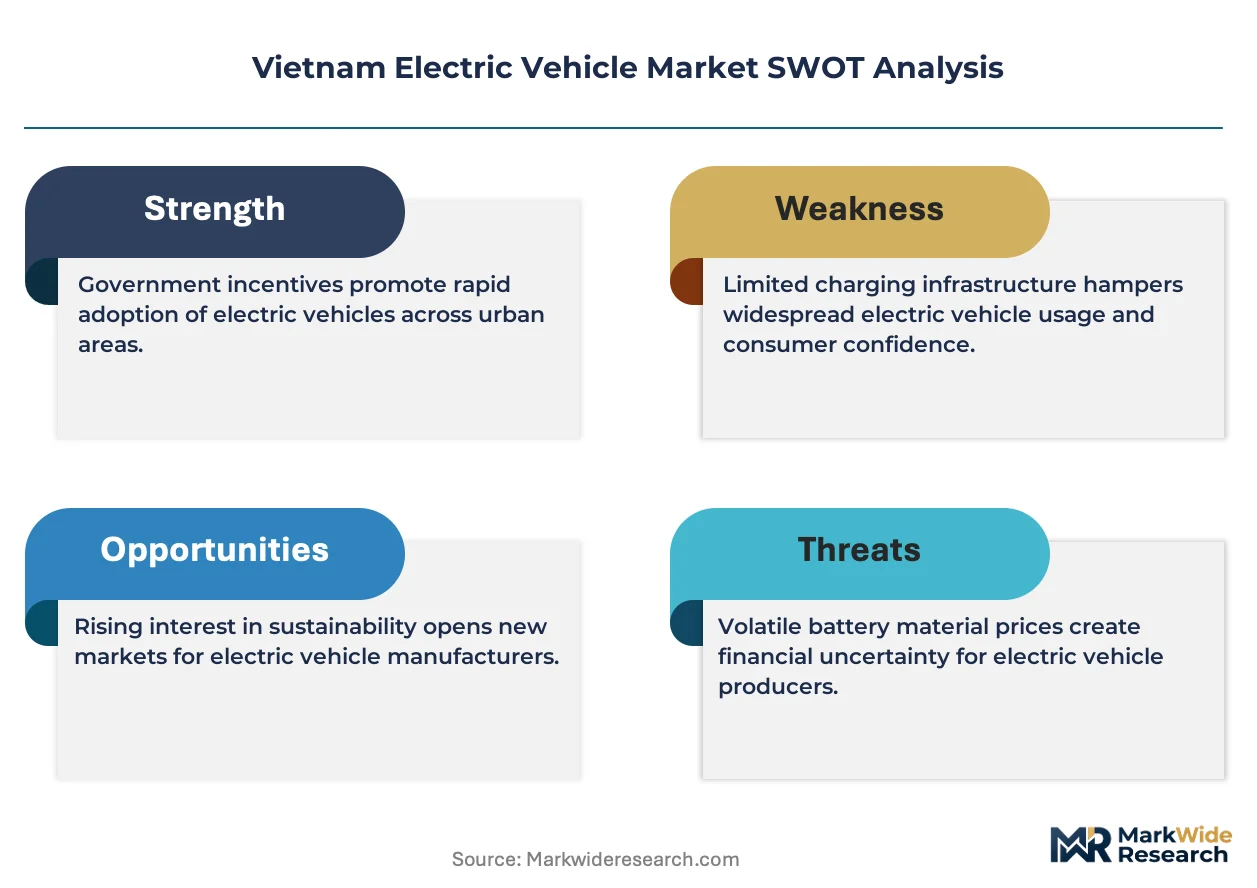
Fleet electrification commitments from ride-hailing operators in Ho Chi Minh City and Hanoi are compressing payback periods and forcing charging infrastructure buildouts ahead of consumer adoption curves.
Growth Catalysts
- Decree 103/2021/ND-CP:Vietnam's Ministry of Transport vehicle registration fee reductions for domestically manufactured EVs narrow total cost of ownership gaps against internal combustion alternatives.
- Battery swapping networks:Infrastructure deployment concentrated around the Red River Delta industrial corridor is eliminating range anxiety for two-wheeler commercial operators.
- Ride-hailing fleet mandates:Urban mobility service electrification targets in Vietnam's two largest cities are generating predictable demand volumes for OEMs.
Market Restraints
- Lithium supply concentration:Vietnam's dependence on imported battery cell materials exposes assemblers to upstream pricing volatility and geopolitical supply disruptions.
- Grid capacity constraints:Northern economic zone power infrastructure limitations restrict simultaneous fast-charging deployment density in industrial corridors.
- Local content thresholds:Domestic assembly mandates under Ministry of Industry and Trade rules extend production timelines for foreign manufacturers lacking Vietnamese component suppliers.
Strategic Opportunities
- Central Highlands logistics electrification:Agricultural and plantation transport fleets in Vietnam's coffee and tea regions remain underpenetrated by commercial EV offerings.
- Renewable energy purchase obligations:Vietnam's national power development plan creates green charging branding opportunities for operators sourcing from solar and wind assets.
- Two-wheeler battery-as-a-service:Subscription-based energy models are displacing upfront battery ownership in Hanoi and Ho Chi Minh City urban delivery segments.
Industry Challenges
- Power electronics engineering shortage:Vietnam's technical education pipeline produces insufficient motor control and battery management system specialists for scaling domestic R&D.
- Homologation timeline compression:Vietnam Register certification procedures for new EV platforms create launch delays that misalign with fleet procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Electric Vehicle Market |
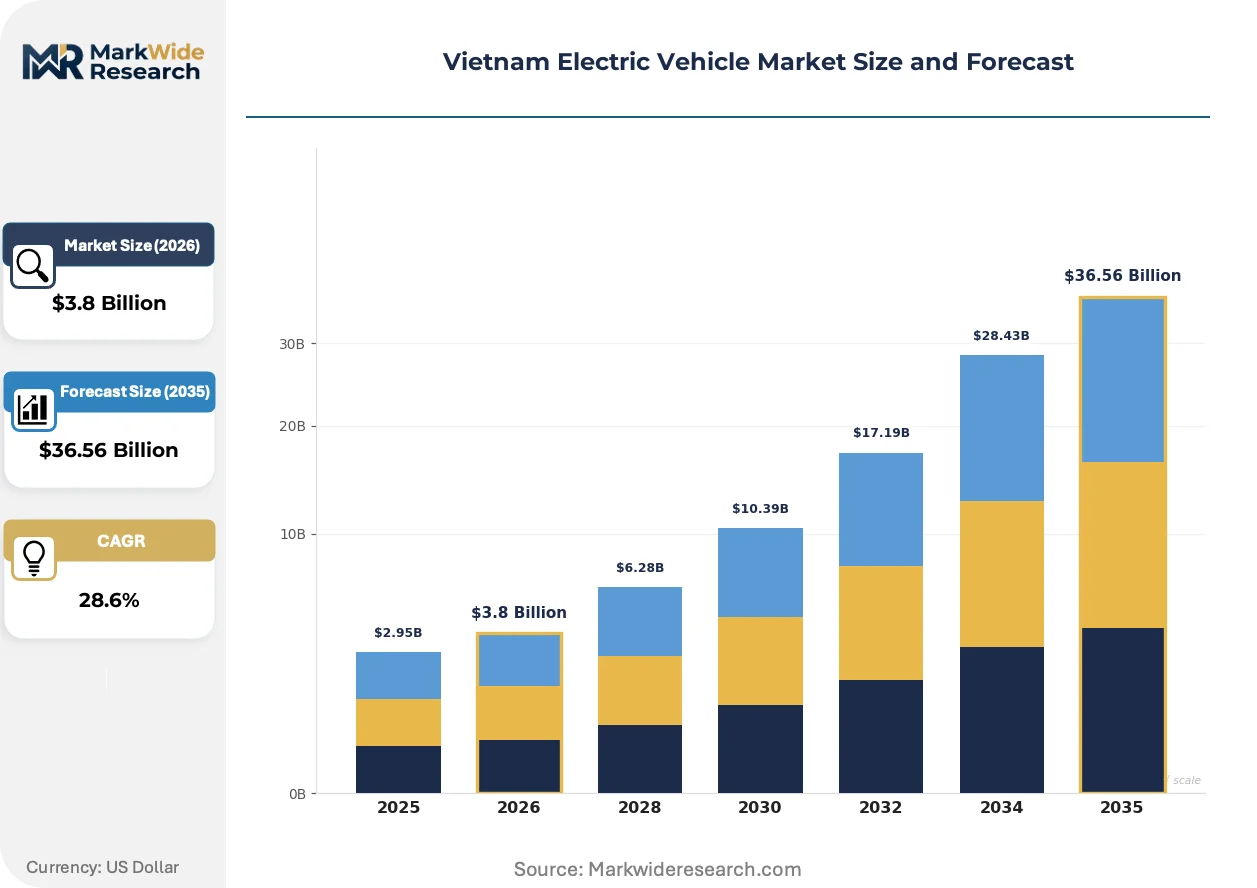
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $36.56 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger Car, Two-Wheeler, Bus, Truck Charging Infrastructure: Public Charging Stations, Home Chargers, Fast Chargers, Wireless Chargers Battery Technology: Lithium-Ion, Solid-State, Lead-Acid, Nickel-Metal Hydride Government Incentives: Tax Rebates, Subsidies, Grants, Loan Programs |
| Companies Covered | VinFast Motor Ltd., Hyundai Motor Company, Toyota Motor Corporation, BYD Auto Co. Ltd, SAIC-GM-Wuling Automobile Co., Ltd., Tesla Inc., Kia Corporation, Nissan Motor Co. Ltd, Honda Motor Co. Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Electric Vehicle Market Trends and Innovations
Powertrain architecture decisions are bifurcating around range requirements and charging access, with commercial and consumer segments diverging on battery size and chemistry preferences.
Lithium iron phosphate chemistry is hybridizing with nickel-manganese-cobalt configurations in Vietnamese passenger EV offerings. Domestic manufacturers prioritize LFP for fleet vehicles prioritizing cycle life, while premium consumer segments demand NMC energy density. This chemistry stratification is enabling price tiering without sacrificing thermal safety margins in tropical operating conditions.
Decree 103/2021/ND-CP registration fee structures are redirecting foreign manufacturer investment toward domestic assembly partnerships. Industrial consequence includes accelerated localization of battery pack production to qualify for fee exemptions. Passenger car segments with local assembly operations capture disproportionate policy benefit versus fully imported alternatives.
Fleet procurement is consolidating around total cost of ownership guarantees rather than vehicle sticker price. Logistics operators in the Red River Delta now demand battery performance warranties and energy cost predictability as primary selection criteria. This specification shift is most visible among express delivery companies operating high-utilization two-wheeler fleets in Hanoi metropolitan zones.
Vietnam Electric Vehicle Market Segmentation
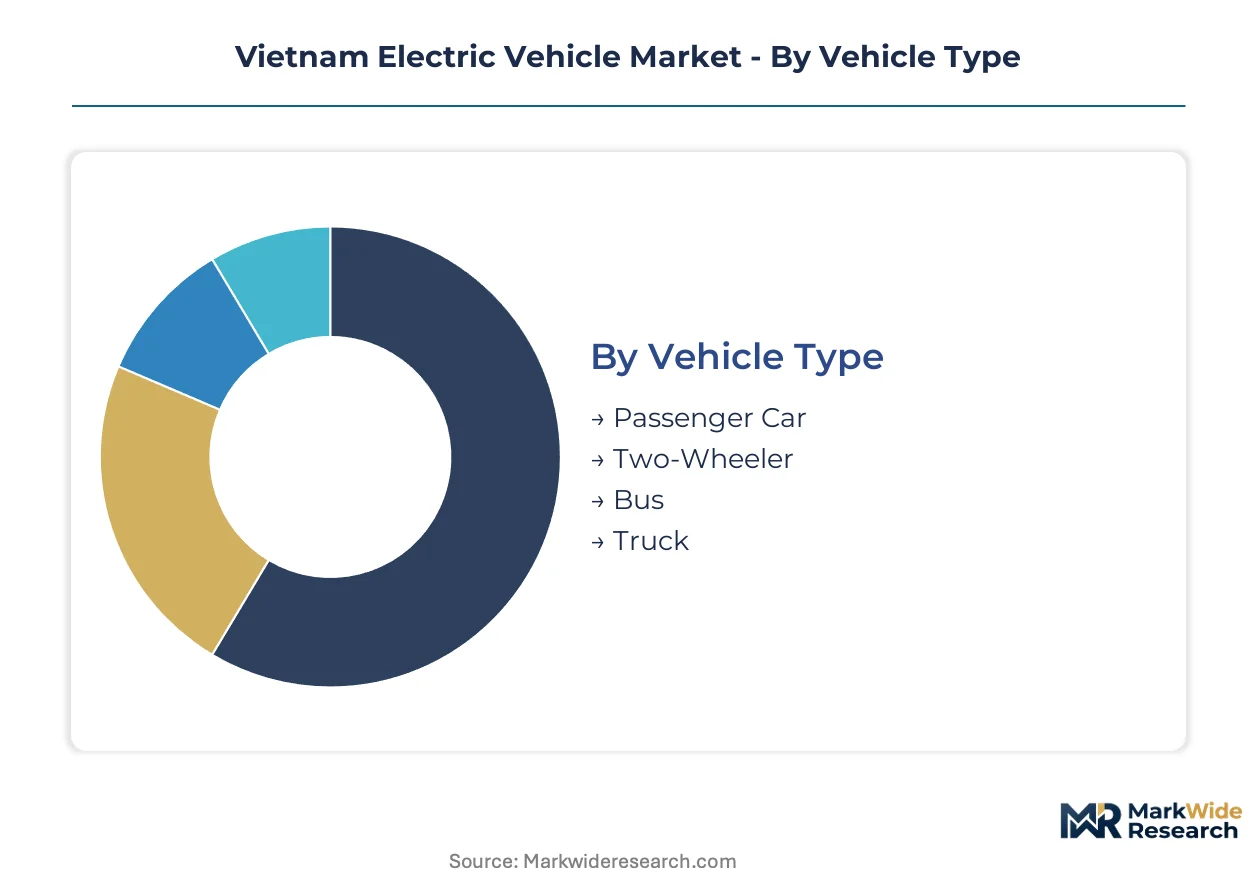
Vietnam's EV segmentation reveals distinct after-sales service intensity profiles across vehicle categories. Battery swapping networks and fast-charging infrastructure demand continuous technical support, while passenger cars require lower-touch maintenance models. Understanding these service dynamics shapes go-to-market economics for manufacturers and infrastructure operators.
Vehicle Type:
After-sales service intensity varies dramatically across vehicle categories, with commercial fleets demanding 24-hour technical response capabilities and private vehicles tolerating scheduled maintenance windows.
- Passenger Car:Battery-electric and plug-in hybrid sedans, SUVs, and hatchbacks engineered for 150-500 km range. Demand concentrates in Hanoi and Ho Chi Minh City private ownership segments, where Decree 103/2021/ND-CP registration fee exemptions compress total cost of ownership gaps against internal combustion alternatives.
- Two-Wheeler:Battery-powered motorcycles and scooters dominating Vietnam's per-capita motorcycle market. Demand clusters around Red River Delta urban delivery fleets and Hanoi express logistics operators, where battery-as-a-service subscriptions displace upfront battery ownership and eliminate range anxiety through swapping networks.
- Bus:Electric municipal and intercity buses serving public transit authorities. Da Nang and Hai Phong municipal procurement contracts anchor commercial deployment.
- Truck:Battery-electric and hybrid commercial vehicles for industrial logistics. Central Highlands agricultural transport corridors remain underpenetrated.
Two-wheelers hold the largest share; momentum sits with passenger cars.
Charging Infrastructure:
Cost tier stratification separates capital-intensive fast-charging deployments from distributed home charging economics.
- Public Charging Stations:Grid-connected charging points in commercial parking, retail centers, and highway corridors. Ho Chi Minh City and Hanoi ride-hailing fleet electrification mandates are forcing buildouts ahead of consumer adoption curves, though northern economic zone grid capacity constraints restrict deployment density.
- Home Chargers:Level 1 and Level 2 residential charging equipment capturing majority of overnight replenishment demand. Urban apartment dwellers in Vietnamese cities face installation barriers due to building electrical infrastructure limitations.
- Fast Chargers:DC rapid charging infrastructure delivering 80% capacity in 30-60 minutes. Red River Delta industrial corridor concentration supports commercial fleet utilization patterns.
- Wireless Chargers:Inductive charging systems eliminating cable connection requirements. Deployment remains nascent in Vietnam with limited pilot programs.
Home chargers dominate installed base; fast chargers are gaining share fastest.
Battery Technology:
Application-specific requirements drive chemistry selection across thermal safety, cycle life, and energy density trade-offs.
- Lithium-Ion:Dominant battery chemistry encompassing lithium iron phosphate and nickel-manganese-cobalt variants. Vietnamese manufacturers prioritize LFP for fleet vehicles prioritizing cycle life, while premium consumer segments demand NMC energy density for tropical operating conditions.
- Solid-State:Next-generation battery technology with solid electrolyte replacing liquid components. Remains nascent in Vietnam with no commercial deployment.
- Lead-Acid:Mature battery technology with lower energy density and shorter cycle life. Limited to low-speed electric vehicles and backup power applications.
- Nickel-Metal Hydride:Hybrid-electric vehicle battery chemistry with moderate energy density. Declining relevance as lithium-ion costs compress.
Lithium-ion holds the largest share; solid-state represents the steepest expansion trajectory.
Government Incentives:
Customer type differentiation separates fleet operators accessing structured programs from individual buyers navigating retail incentive channels.
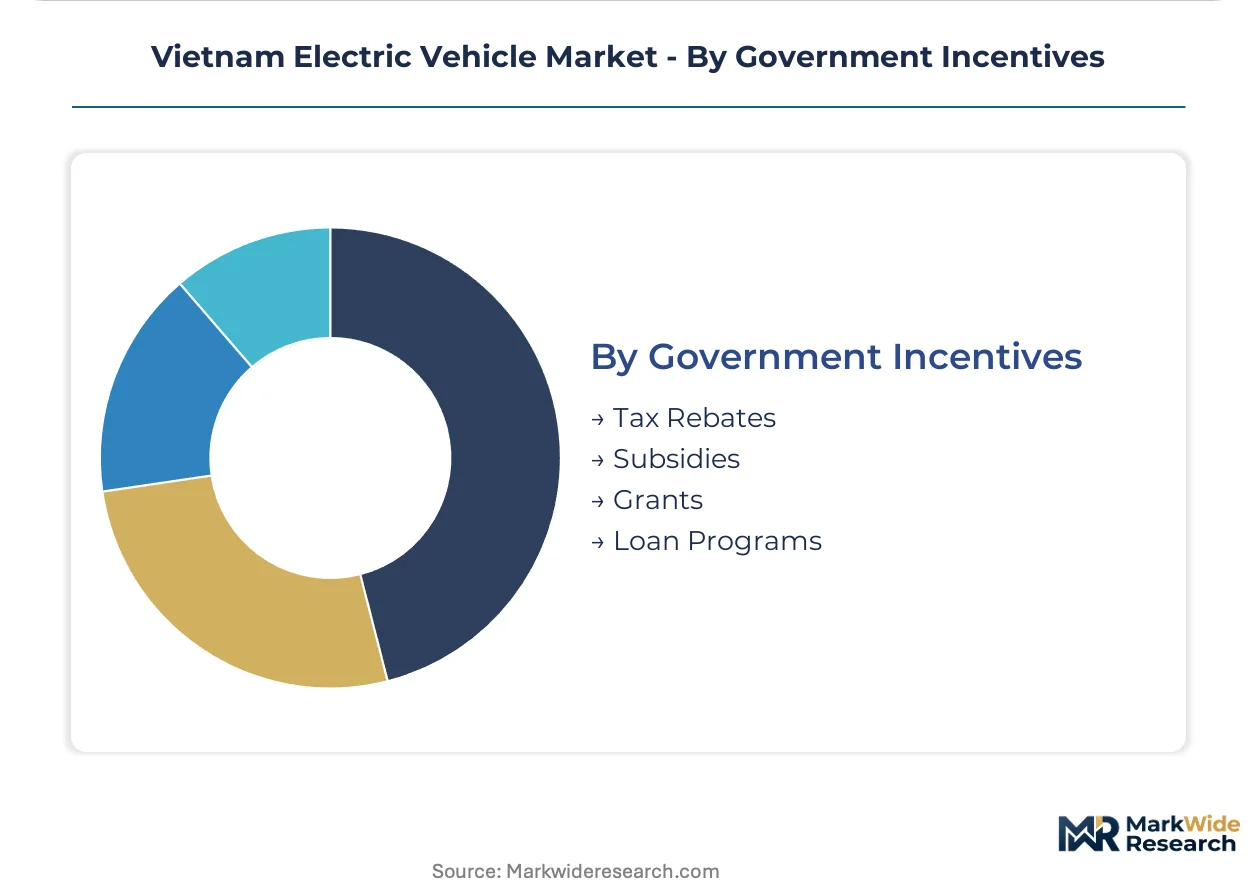
- Tax Rebates:Registration fee reductions and import duty modifications under Ministry of Transport Decree 103/2021/ND-CP. Domestic assembly operations capture disproportionate policy benefit versus fully imported alternatives.
- Subsidies:Direct purchase price reductions for qualifying electric vehicle categories. Ministry of Industry and Trade local content thresholds protect domestic assembly.
- Grants:Non-repayable funding for charging infrastructure deployment and fleet conversion. Municipal programs in Ho Chi Minh City and Hanoi accelerate urban electrification.
- Loan Programs:Preferential financing terms through state-linked banking channels. Compress payback periods for commercial fleet operators.
Tax rebates hold the largest share; grants show strongest momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Decree 103/2021/ND-CP registration fee reductions are compressing total cost of ownership gaps across Vietnam's northern, central, and southern economic zones. The Ministry of Transport policy framework channels investment toward domestically assembled vehicles. Sub-regional electrification momentum diverges based on grid capacity, industrial density, and fleet operator concentration.
Red River Delta
Battery swapping networks for two-wheeler delivery fleets dominate infrastructure deployment in Hanoi and surrounding industrial provinces. The Ministry of Industry and Trade local content thresholds protect domestic assembly operations in this northern corridor. Hai Phong municipal procurement contracts for electric buses anchor commercial vehicle adoption in the delta's port-centric manufacturing zones.
Southeast Region
Ho Chi Minh City ride-hailing fleet electrification mandates generate predictable demand volumes for passenger EVs and charging infrastructure. Grid capacity constraints in the northern economic zone do not bind here, enabling denser fast-charging deployment. Binh Duong and Dong Nai industrial provinces host logistics fleet conversion programs targeting warehouse-to-port container movements.
Central Coast
Da Nang municipal authorities anchor electric bus procurement in the central region's primary urban center. Tourism-dependent transport operators in Quang Nam and Thua Thien-Hue provinces pilot electric shuttle services for coastal resort corridors. The Vietnam Register maintains homologation facilities in Da Nang, compressing certification timelines for platforms targeting this zone.
Central Highlands
Agricultural and plantation transport fleets in Dak Lak and Lam Dong coffee regions remain underpenetrated by commercial EV offerings. Agricultural cooperatives lack structured financing channels available to urban fleet operators. Pleiku and Buon Ma Thuot logistics hubs show nascent interest in electrified cold-chain vehicles for perishable crop transport.
Mekong Delta
Can Tho and An Giang provinces experiment with electric riverine cargo vessels complementary to road electrification. Rice milling and aquaculture processing clusters generate distributed freight demand poorly served by existing charging infrastructure. Provincial governments lack the fiscal capacity of Hanoi or Ho Chi Minh City for direct fleet subsidies.
Vietnam Electric Vehicle Market Competitive Landscape
On the supply side, the industry is consolidating around domestic assembly operations and captive battery manufacturing capabilities. Tiered competitive positioning separates integrated cell-pack-vehicle producers from import-dependent assemblers. Three archetypes dominate: domestic champions with vertical manufacturing control, regional Asian exporters leveraging scale economics, and Western premium brands targeting private ownership segments. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with local content compliance driving joint venture formation.
Among domestic champions, VinFast Motor Ltd. anchors the integrated manufacturing archetype through captive battery cell production and controlled retail distribution. Hyundai Motor Company and BYD Auto Co. Ltd. represent the regional Asian exporter tier, with the former emphasizing hybrid-to-full-EV transition programs and the latter securing municipal bus procurement contracts. These three entities occupy positions that exemplify the policy-incentivized shift toward domestic assembly partnerships required for Decree 103/2021/ND-CP registration fee exemptions.
| Leading Market Players |
|---|
| VinFast Motor Ltd. |
| Hyundai Motor Company |
| Toyota Motor Corporation |
| BYD Auto Co. Ltd |
| SAIC-GM-Wuling Automobile Co., Ltd. |
| Tesla Inc. |
| Kia Corporation |
| Nissan Motor Co. Ltd |
| Honda Motor Co. Ltd |
| Others |
Pricing and Supply Chain Analysis
The Red River Delta industrial corridor's freight cost dynamics concentrate supply power among integrated cell-pack-vehicle producers while forcing three-tier pricing stratification across premium, standard, and economy vehicle tiers. Decree 103/2021/ND-CP registration fee exemptions amplify price spreads between domestically assembled and fully imported alternatives.
Pricing Analysis
Local content thresholds under Ministry of Industry and Trade rules create the primary price spread, with domestic assembly operations capturing disproportionate policy benefit versus import-dependent competitors. Subscription-based battery-as-a-service models for two-wheelers displace upfront ownership costs while compressing margins for pure hardware vendors. Pricing pressure stems from lithium supply volatility and grid capacity constraints in northern economic zones. Fleet operators in Hanoi and Ho Chi Minh City demonstrate highest price sensitivity, while private passenger car buyers absorb premium positioning for VinFast's vertically integrated offerings.
Supply Chain Analysis
Contract manufacturing for battery pack assembly concentrates in Vietnamese industrial zones around Hai Phong and Binh Duong, with VinFast's captive facilities anchoring domestic capacity. Cell production draws from China, South Korea, and Japan, while lithium carbonate and nickel sulfate feedstocks rest on Australian and Indonesian mining operations. Single-source vulnerability in semiconductor power electronics creates procurement risk for motor control systems. Distribution runs through captive retail networks for domestic champions and dealer partnerships for regional exporters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through Decree 103/2021/ND-CP local content thresholds constructs defensive moats for integrated manufacturers, with switching costs rising for fleet operators locked into battery swapping network ecosystems.
For Market Incumbents:Pre-empt emerging two-wheeler battery-as-a-service competitors by accelerating captive swapping station deployment in Central Highlands agricultural corridors before regional logistics operators consolidate around rival networks. Secure nickel and lithium offtake agreements with Indonesian and Australian suppliers to insulate against upstream price volatility threatening margin compression in fleet segments.
For New Entrants and Emerging Players:Pursue underpenetrated Central Highlands cold-chain logistics for perishable coffee and tea transport, where agricultural cooperatives lack structured financing channels available to urban fleet operators. Target Can Tho and An Giang provinces in the Mekong Delta for electric riverine cargo vessel pilots, leveraging provincial appetite for infrastructure differentiation against Hanoi and Ho Chi Minh City dominance.
For Investors and Strategic Acquirers:Integrated swapping network operators with proprietary battery management software present acquisition targets with embedded customer lock-in and recurring revenue visibility. Long-term viability hinges on renewable energy purchase obligation alignment with grid capacity expansion timelines. Monitor Ministry of Transport homologation timeline compression for new EV platforms as inflection signal for domestic manufacturing competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium iron phosphate cell volumes from Chinese or Korean suppliers for Hanoi fleet deployment. |
| Charging Infrastructure Partnership | Aligns Red River Delta swapping network density with express delivery operator route optimization. |
| Backward Integration into Cell Production | Qualifies VinFast and domestic assemblers for Decree 103/2021/ND-CP registration fee exemptions. |
| Platform Standardization | Enables battery interoperability across two-wheeler fleets serving Ho Chi Minh City ride-hailing mandates. |
| Software-Defined Vehicle Investment | Differentiates premium passenger offerings through over-the-air battery management optimization in tropical conditions. |
Research Methodology
Operator-level perspectives from fleet procurement managers at express delivery companies, ride-hailing platform executives, Vietnam Register homologation officials, and Ministry of Industry and Trade policy leads anchored the qualitative base. Secondary validation drew from Vietnam customs import records, Ministry of Transport regulatory filings, national power development plan documents, and IHS Markit vehicle registration databases. Bottom-up fleet deployment modeling triangulated against top-down market sizing across passenger car, two-wheeler, bus, and truck segments.
Scenario-bracketing around grid capacity expansion timelines and lithium supply disruption probabilities framed the analytical approach across the projection horizon. Segmentation dimensions modeled encompassed vehicle type, charging infrastructure category, battery chemistry variant, and government incentive mechanism. CAGRs derived from logistic diffusion curves fitted to fleet electrification commitment schedules and consumer adoption elasticity estimates. Forecast inputs incorporated Decree 103/2021/ND-CP policy persistence assumptions and Red River Delta industrial corridor infrastructure buildout rates.
Macroeconomic conditions sit as an overlay; deviation in Vietnamese dong exchange rates, crude oil import dependency costs, or central bank monetary tightening would shift the trajectory. Forecasts reflect documented assumptions about local content threshold enforcement and battery swapping network deployment cadence. Quarterly review of Ministry of Transport regulatory amendments and VinFast production capacity announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Busbar for EV Market
Electric Vehicles
South America Electric Vehicles Market
Electric Vehicles
UK Electric Bus Battery Pack Market
Electric Vehicles
North America Electric Vehicle (EV) Fluids Market
Electric Vehicles
Electric Vehicle HVAC Market
Electric Vehicles
High-Performance Electric Sports Cars Market
Electric Vehicles
Electric Vehicle Electric Heating Film Market
Electric Vehicles
BEV Electric Drive Unit Market
Electric Vehicles
Electric Vehicle (EV) Fluids Market
Electric Vehicles
Mexico Automotive High Performance Electric Vehicle Market
Electric Vehicles
Electric Vehicle Reducer Market
Electric Vehicles
Europe Automotive High Performance Electric Vehicle Market
Electric Vehicles
France Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
EV Taxi Market
Electric Vehicles
EV Transmission System Market
Electric Vehicles
Pedelec Market