
 India Electric Bus Market | 2026-2036
India Electric Bus Market Size, Share, and Industry Trends Forecast 2026-2036
India Electric Bus Market Outlook
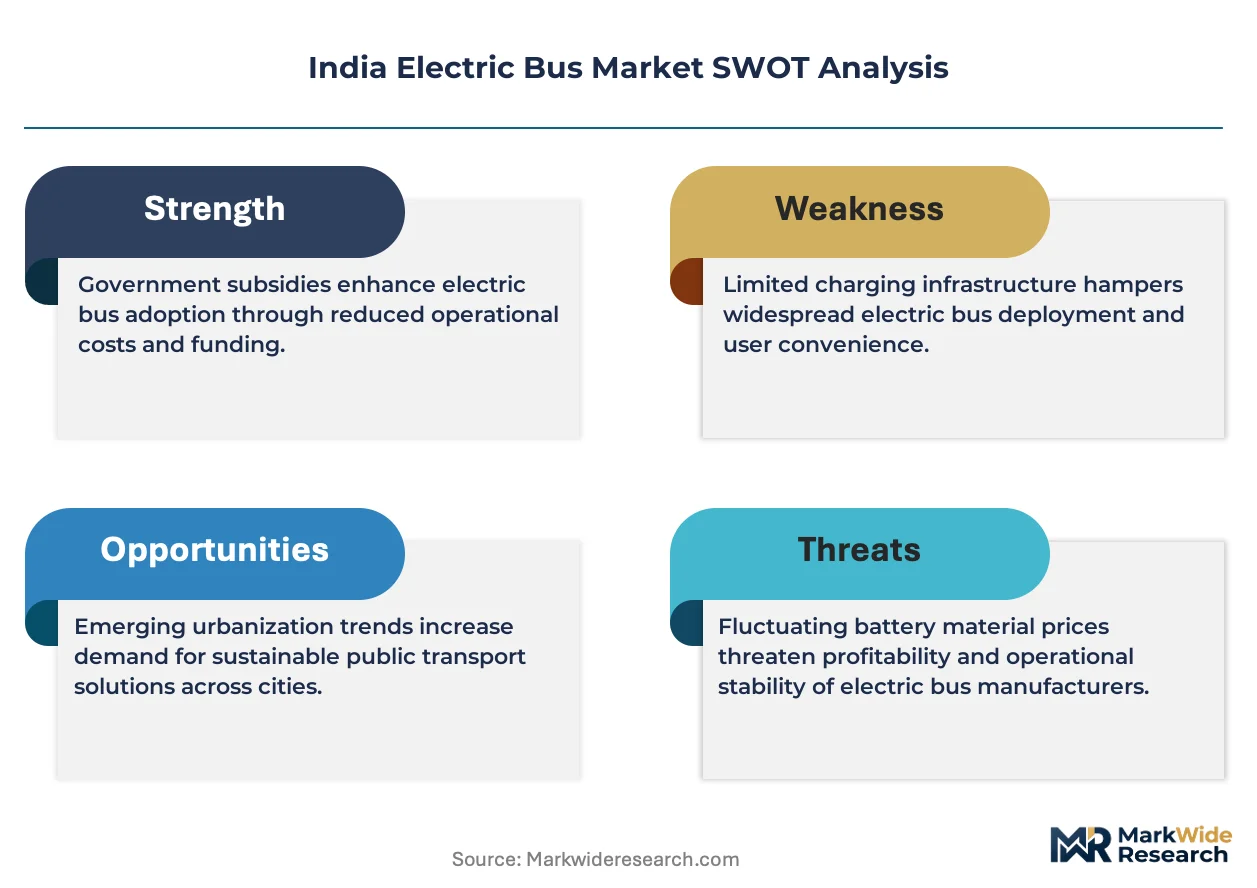
FAME III is consolidating procurement economics for OEMs and state transport undertakings alike. Tata Motors leverages its integrated powertrain manufacturing to anchor large-volume tenders across multiple states. Ashok Leyland sustains competitive positioning through dedicated electric bus platforms and extensive service networks. Olectra Greentech specializes in long-range intercity configurations with advanced thermal management systems.
An electric bus is a commercial passenger vehicle propelled by electric motors drawing energy from onboard battery packs, typically lithium-ion configurations ranging from 200 kWh to 600 kWh, with regenerative braking systems that recover kinetic energy during deceleration. These vehicles serve urban mass transit and intercity routes, eliminating tailpipe emissions while reducing noise pollution in dense corridors. Battery Electric Buses dominate tender allocations due to zero-emission compliance and falling battery costs, while the 400-600 kWh capacity band captures the fastest growth as operators demand extended range without midday charging interruptions. Public Transport Operators represent the deepest demand pool, though Private Fleet Operators are expanding faster as corporate employee transportation electrifies.
BIS certification mandates, CEA grid-integration guidelines, and state-level EV policies from Maharashtra and Gujarat shape product specifications and charging infrastructure rollouts. The PLI scheme for advanced chemistry cell manufacturing is localizing battery supply chains and reshaping OEM sourcing strategies. Stakeholders must monitor state-level tender design, subsidy disbursement velocity, and charging infrastructure build-out to calibrate capacity planning and partnership priorities.
Market Dynamics
FAME III subsidy disbursement velocity and indigenous lithium-ion cell manufacturing under the PLI scheme are compressing total cost of ownership curves faster than battery pack prices alone would predict.
Growth Catalysts
- FAME III Framework:Central subsidy allocation covering 40-60% of vehicle cost accelerates state transport undertaking fleet replacement cycles in Maharashtra, Delhi, and Karnataka.
- Indigenous Cell Manufacturing:PLI scheme incentives for advanced chemistry cell production localize battery supply chains and reduce import dependency for OEMs.
- Metropolitan Depot Electrification:Grid-connected charging hubs at bus depots in tier-one cities enable overnight fleet charging without midday range interruptions.
Market Restraints
- Lithium Carbonate Volatility:Raw material price swings for cathode precursors transmit directly to battery pack costs, squeezing OEM margins on fixed-price tenders.
- Charging Infrastructure Gaps:Intercity corridors lack standardized fast-charging stations, limiting deployment to urban depot-centric routes.
- CEA Grid Integration Delays:Distribution company approval timelines for high-capacity depot connections extend project commissioning by 6-12 months.
Strategic Opportunities
- Tier-Two City Penetration:State capitals including Jaipur, Lucknow, and Bhopal present untapped demand pools as FAME III eligibility expands beyond metros.
- Corporate Employee Transportation:Private fleet operators serving IT parks and manufacturing campuses represent faster contract velocity than public tenders.
- Battery Swapping Convergence:Interoperable swap stations combined with standardized pack geometries could eliminate range anxiety without depot charging.
Industry Challenges
- High-Voltage Technician Scarcity:Bus depots lack certified personnel for 600V+ battery maintenance, forcing OEMs to embed service teams at customer sites.
- BIS Certification Timelines:Type approval testing for new battery chemistries extends product launch windows by 8-10 months.
- Legacy Fleet Integration:Mixed diesel-electric depot operations require dual maintenance protocols and retraining of existing workshop staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Electric Bus Market |
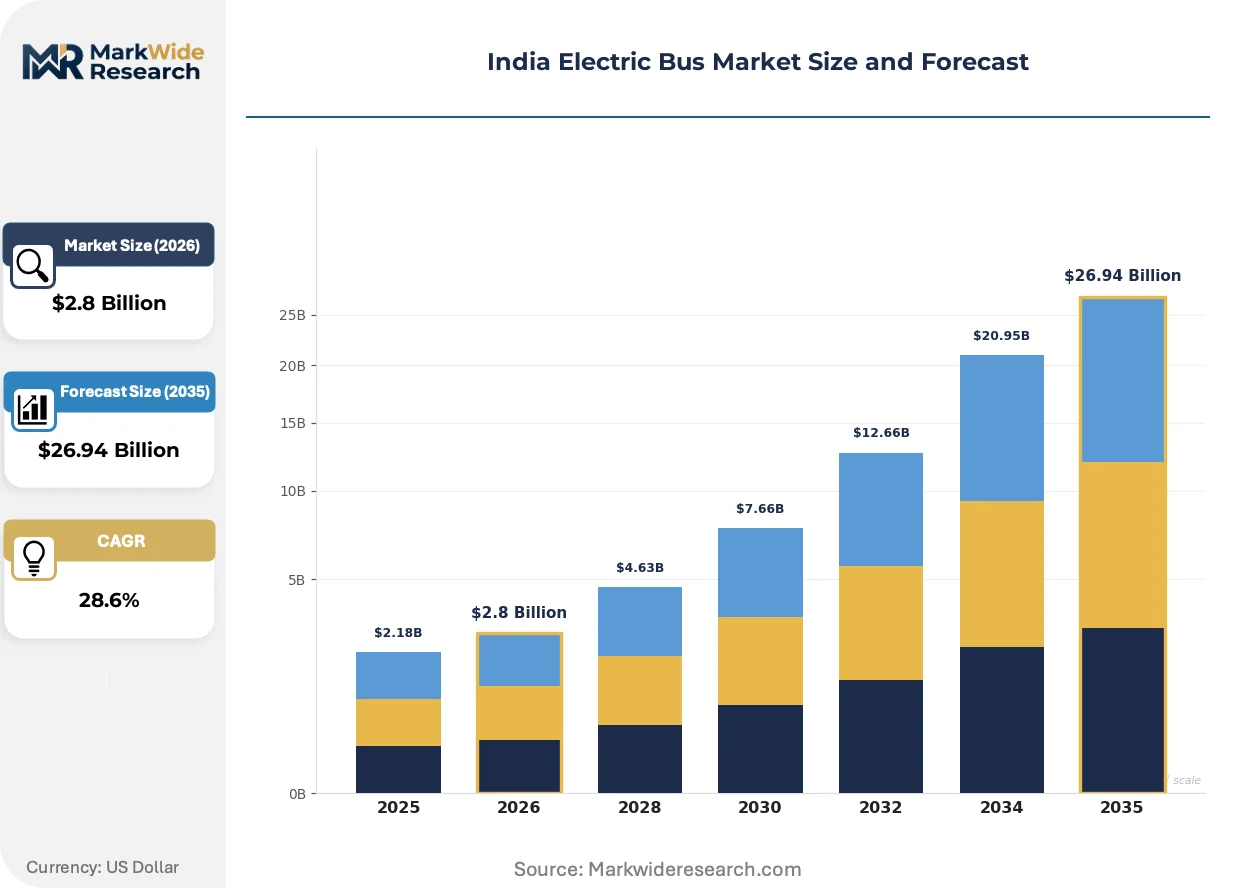
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $26.94 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Electric Buses, Hybrid Electric Buses, Plug-in Hybrids, Fuel Cell Buses End User: Public Transport Operators, Private Fleet Operators, Ride-Sharing Services, Logistics Providers Battery Capacity: Below 200 kWh, 200-400 kWh, 400-600 kWh, Above 600 kWh Charging Infrastructure: Depo Charging, Fast Charging Stations, On-route Charging, Wireless Charging |
| Companies Covered | JBM Auto, Ashok Leyland, Tata Motors, Eka Mobility, Mahindra Electric, Olectra Greentech, Switch Mobility, Volvo Buses India, PMI Electro Mobility, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Electric Bus Market Strategic Shifts
Thermal management architectures and procurement contract structures are undergoing parallel transformation as operators demand all-weather reliability and predictable lifecycle costs.
Liquid-cooled battery packs with active thermal management are absorbing the performance degradation risks that previously limited electric bus deployment in India's high-ambient-temperature corridors. State transport undertakings in Rajasthan and Gujarat are specifying these systems as mandatory tender requirements. The technology is absorbing market share from air-cooled alternatives by extending cycle life beyond 4,000 full equivalent cycles.
CEA technical standards for grid-connected electric vehicle supply equipment mandate smart charging protocols and demand response compatibility for all new depot installations. Distribution companies must now provision dedicated transformers and time-of-use tariffs for bus charging loads. The regulation most affects intercity corridor planning, where operators are clustering charging points at highway nodes to minimize grid upgrade costs.
Lease-to-own financing structures are displacing outright purchase models for private fleet operators serving corporate campuses. Asset finance providers assume residual value risk while operators pay per-kilometer fees covering energy, maintenance, and depreciation. The shift is most visible in Bengaluru and Hyderabad, where IT park shuttle contracts now specify total mobility cost rather than vehicle procurement price.
India Electric Bus Market Segmentation
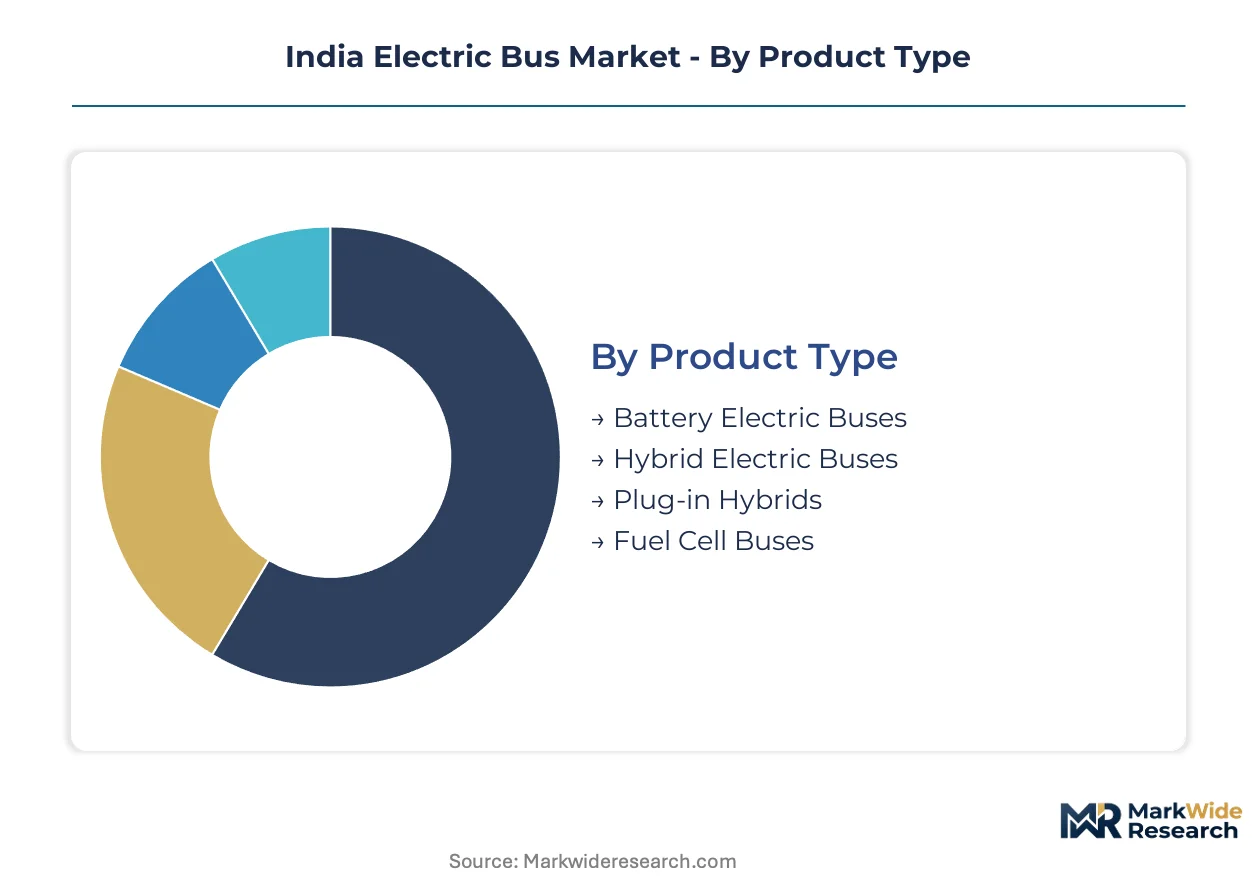
Electric bus procurement in India fragments across propulsion architectures, operational models, energy storage scales, and charging topologies. Each segmentation axis carries distinct BIS certification requirements, subsidy eligibility thresholds, and infrastructure dependencies that shape OEM product strategies and state transport tender designs.
Product Type:
Standalone zero-emission platforms dominate tender allocations, while hybrid configurations serve transitional corridors where charging infrastructure remains incomplete.
- Battery Electric Buses:These vehicles draw propulsion energy exclusively from onboard lithium-ion battery packs ranging from 200 kWh to 600 kWh, with permanent magnet synchronous motors delivering torque directly to drive axles. Maharashtra State Road Transport Corporation and Delhi Transport Corporation have standardized these configurations for urban depot operations, driven by FAME III eligibility that excludes hybrid architectures from maximum subsidy tiers.
- Hybrid Electric Buses:Parallel hybrid systems combine downsized diesel engines with electric traction motors, enabling operation in zero-emission zones while eliminating range anxiety on intercity stretches. Karnataka State Road Transport Corporation deploys these on Bangalore-Mysore corridors where fast-charging station density remains insufficient for pure battery-electric operation.
- Plug-in Hybrids:Larger battery packs than conventional hybrids allow 30-50 km electric-only range before combustion activation, appealing to operators serving mixed urban-suburban routes.
- Fuel Cell Buses:Proton exchange membrane fuel cells generate electricity from onboard hydrogen storage, eliminating battery weight penalties for extended-range intercity service.
Volume placements concentrate in Battery Electric Buses; the faster expansion belongs to Fuel Cell Buses as green hydrogen corridors emerge under the National Hydrogen Mission.
End User:
Public procurement frameworks and private capital deployment follow diverging contract structures, risk allocation models, and residual value assumptions.
- Public Transport Operators:State transport undertakings in Delhi, Maharashtra, and Karnataka issue multi-year tenders with 10-15 year operational leases, transferring residual value risk to OEMs or fleet aggregators. These entities anchor demand volume through FAME III consolidated subsidy claims.
- Private Fleet Operators:Corporate campus shuttles and employee transportation contracts in Bengaluru and Hyderabad specify per-kilometer mobility fees rather than asset ownership, accelerating contract velocity through lease-to-own structures.
- Ride-Sharing Services:App-based mobility platforms pilot electric bus deployments on high-frequency airport and intercity routes, optimizing utilization through dynamic routing algorithms.
- Logistics Providers:E-commerce fulfillment networks test electric mid-mile shuttles for warehouse-to-hub distribution, constrained by payload-range tradeoffs in battery-electric configurations.
Public Transport Operators absorb the deepest procurement volume; Private Fleet Operators are climbing the fastest as IT park electrification mandates harden.
Battery Capacity:
Energy storage scale determines route eligibility, charging frequency, and thermal management complexity across India's climatic zones.
- 200-400 kWh:Nickel-manganese-cobalt or lithium-iron-phosphate cell configurations deliver 150-250 km daily range, sufficient for intra-city depot-charged operations with overnight replenishment. This band captures maximum FAME III subsidy efficiency by minimizing capital cost per passenger-kilometer.
- 400-600 kWh:Liquid-cooled thermal architectures sustain performance in Rajasthan and Gujarat ambient conditions above 45°C, enabling 300+ km range without midday charging interruptions. State transport undertakings specify these systems as mandatory for intercity tender eligibility.
- Below 200 kWh:Compact packs serve last-mile feeder services and airport shuttle loops with predictable low-speed duty cycles.
- Above 600 kWh:Extended-range configurations target overnight intercity routes where depot charging infrastructure spans 400+ km corridors.
Volume placements concentrate in 200-400 kWh; 400-600 kWh is gaining share fastest as all-weather reliability specifications harden in western and northern state tenders.
Charging Infrastructure:
Charging topology selection locks operators into specific grid integration requirements, land use patterns, and vehicle downtime profiles.
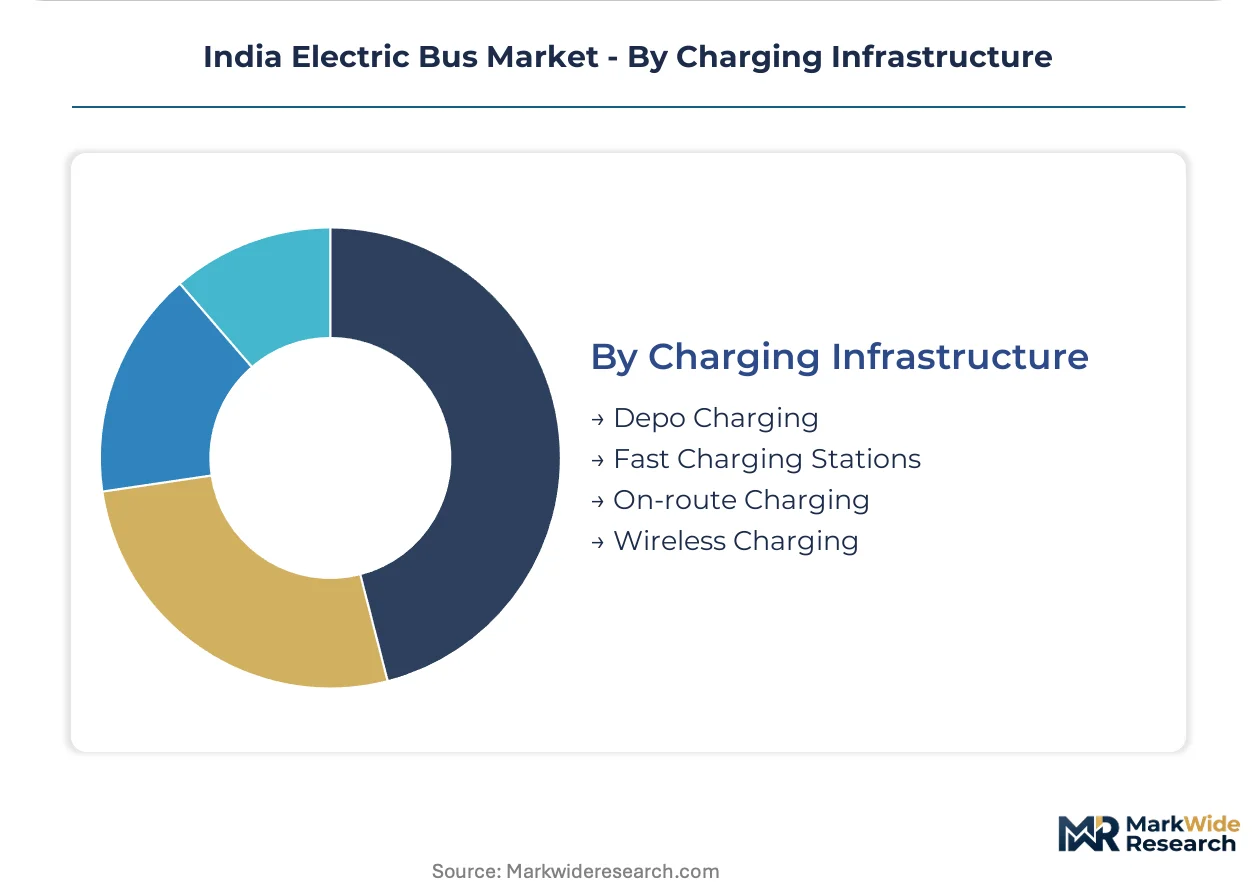
- Depo Charging:Overnight slow-charging at 30-60 kW AC or 120-150 kW DC within bus depot boundaries minimizes grid upgrade costs and aligns with CEA time-of-use tariff structures. Delhi and Mumbai transport corporations have standardized this model for fleet electrification.
- Fast Charging Stations:350 kW+ DC installations at highway nodes and city terminals enable opportunity charging during layover windows, extending effective daily range without battery capacity penalties.
- On-route Charging:Pantograph or inverted pantograph systems at bus stops allow 3-5 minute top-ups during passenger boarding, reducing required battery size for fixed-route operations.
- Wireless Charging:Inductive pads embedded at terminus stations eliminate connector wear and enable automated charging sequences for autonomous shuttle pilots.
Volume placements concentrate in Depo Charging; Fast Charging Stations are expanding most quickly as intercity corridor electrification accelerates under state highway development programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State transport undertakings in Maharashtra, Delhi, and Karnataka concentrate procurement volume under FAME III, while Gujarat and Tamil Nadu emerge as manufacturing clusters for indigenous battery assembly and vehicle integration.
Maharashtra
Mumbai and Pune metropolitan depots drive fleet electrification through Maharashtra State Road Transport Corporation tenders specifying 400-600 kWh liquid-cooled configurations. The state EV policy mandates 25% electric bus procurement for urban routes by 2027. Nashik and Nagpur industrial corridors host powertrain component suppliers serving western India demand.
Delhi-NCR
Delhi Transport Corporation operates India's largest electric bus depot network with overnight charging infrastructure across 12 locations. The Delhi EV Policy 2020 mandates complete bus fleet electrification by 2030. Gurugram and Faridabad manufacturing units supply battery management systems to OEMs serving the capital region.
Karnataka
Bangalore Metropolitan Transport Corporation anchors southern India demand with intercity corridor pilots to Mysore and Chennai. The Karnataka Electric Vehicle and Energy Storage Policy offers capital subsidies for charging infrastructure deployment. Tumakuru and Hoskote industrial zones concentrate electric motor and controller manufacturing.
Gujarat
Ahmedabad and Surat municipal corporations issue tenders emphasizing all-weather thermal management for 45°C+ ambient operations. Gujarat's EV policy exempts electric buses from motor vehicle tax and registration fees. Sanand and Halol automotive clusters integrate PLI scheme battery cell production into bus supply chains.
Tamil Nadu
Chennai Metropolitan Transport Corporation expands depot electrification with CEA-mandated smart charging protocols. The Tamil Nadu EV Policy provides land allocation priority for charging infrastructure at bus terminals. Sriperumbudur and Oragadam industrial corridors host foreign OEM joint ventures for electric commercial vehicle assembly.
India Electric Bus Market Competitive Environment
Domestic automotive conglomerates anchor volume supply; dedicated electric vehicle specialists hold technology differentiation positions. The market structures around three tiers: integrated OEMs with captive powertrain manufacturing, platform-focused specialists with thermal management expertise, and emerging challengers leveraging PLI scheme incentives for component localization. Consolidation pressures intensify through state tender bundling and long-term operational lease requirements.
Among established domestic producers, Tata Motors, Ashok Leyland, and Olectra Greentech occupy distinct competitive positions. Tata Motors represents the integrated conglomerate archetype with backward control over critical powertrain components. Ashok Leyland exemplifies the dedicated commercial vehicle platform approach with extensive service network coverage. Olectra Greentech anchors the specialist tier through intercity configuration expertise and advanced thermal system integration.
| Leading Market Players |
|---|
| JBM Auto |
| Ashok Leyland |
| Tata Motors |
| Eka Mobility |
| Mahindra Electric |
| Olectra Greentech |
| Switch Mobility |
| Volvo Buses India |
| PMI Electro Mobility |
| Others |
Value Chain & Pricing Dynamics
Indigenous lithium-ion cell manufacturing under the PLI scheme is compressing battery pack costs while redistributing procurement power toward domestic suppliers. This production-method transition simultaneously erodes import-dependent cost structures and concentrates supplier leverage in Gujarat and Tamil Nadu manufacturing clusters.
Pricing Analysis
Volume placements concentrate in 200-400 kWh configurations where FAME III subsidy efficiency maximizes passenger-kilometer economics, while 400-600 kWh liquid-cooled systems command premium positioning through all-weather reliability specifications. Price differentiation hinges on thermal management certification grade and after-sales service bundling duration. Cost compression in the standard tier is intensifying because fixed-price state tenders expose OEMs to lithium carbonate volatility. Public transport undertakings exhibit highest price sensitivity due to consolidated subsidy dependency, whereas private fleet operators absorb premium positioning for lease-to-own flexibility.
Supply Chain Analysis
Lithium carbonate and cathode precursor supply rests on Chilean mining operations, Chinese refining capacity, and Australian spodumene concentrate. Battery management system controllers draw from Taiwanese semiconductor foundries and South Korean memory suppliers. Single-source vulnerability concentrates in electrolyte salt production where Japanese specialty chemical producers dominate global output. Distribution runs through state transport undertaking tender aggregators and corporate fleet management companies serving IT park contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India electric bus market sits in a technology-transition phase where liquid-cooled battery architectures displace air-cooled legacy systems. This thermal management shift redefines competitive differentiation beyond propulsion hardware toward integrated energy system reliability.
For Market Incumbents: Anchor fleet aggregation capabilities through long-term operational lease structures that transfer residual value risk from state transport undertakings. Deepen backward integration into battery management system firmware and thermal control algorithms to defend against emerging platform specialists. Secure CEA grid-connection approval capabilities in-house to compress commissioning timelines that currently extend 6-12 months. For New Entrants and Emerging Players: FAME III eligibility expansion into tier-two state capitals opens a window for regional depot electrification contracts with faster procurement cycles than metropolitan tenders. Target Jaipur, Lucknow, and Bhopal municipal corporations where incumbent service networks remain underdeveloped. Pursue corporate employee transportation mandates through per-kilometer mobility fee structures rather than asset-sale competition. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated automotive conglomerates seeking thermal management technology and state-level tender relationships. Long-term viability favors specialists with captive battery assembly capacity and CEA-certified grid integration expertise. Monitor PLI scheme disbursement velocity as the inflection indicator for indigenous cell manufacturing scale and cost competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cell Assembly | PLI scheme incentives localize supply chains and reduce lithium carbonate import dependency for OEMs. |
| CEA Grid-Connection Certification Investment | Accelerated approval timelines compress project commissioning from 12 months to under 6 months. |
| Liquid-Cooled Thermal Management Platform Launch | Rajasthan and Gujarat tenders now mandate all-weather reliability specifications above 45°C ambient. |
| Lease-to-Own Financing Structure Development | Corporate campus contracts in Bengaluru and Hyderabad specify total mobility cost rather than vehicle price. |
| Tier-Two City Service Network Expansion | State capitals beyond metros present untapped demand pools as FAME III eligibility broadens. |
Study Parameters
Ministry of Heavy Industries FAME III disbursement records, Central Electricity Authority grid-integration filings, and state transport undertaking tender documents formed the secondary backbone for market sizing. Primary interviews with OEM platform engineers, state transport procurement officers, battery management system suppliers, and corporate fleet operators combined with secondary validation through bottom-up and top-down triangulation. Analysis incorporated PLI scheme beneficiary disclosures and BIS certification timelines to calibrate supply-side capacity assumptions.
Historical trendline analysis of state-level electric bus deployment tracked tender award velocity, fleet commissioning rates, and charging infrastructure build-out across the analysis window. Segmentation modeling incorporated propulsion architecture, battery capacity tier, end-user category, and charging topology dimensions. CAGRs derived from volume-weighted average of state transport undertaking procurement pipelines and private fleet operator contract announcements. Forecast inputs included lithium carbonate price trajectory assumptions and CEA distribution company approval rate projections.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter the outlook for liquid-cooled thermal management investment cycles. Forecasts reflect documented assumptions regarding FAME III subsidy continuity and PLI scheme disbursement schedules. Policy discontinuity, raw material price spikes, or grid-integration approval bottlenecks warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle Battery Cases Market
Electric Vehicles
Electric Passenger Cars Market
Electric Vehicles
Agricultural Electric Vehicles Market
Electric Vehicles
Electric Vehicle Reducer Market
Electric Vehicles
BEV On-Board Charger Market
Electric Vehicles
Mexico Automotive Electric Bus Market
Electric Vehicles
48V Mild Hybrid Electric Vehicle (MHEV) Market
Electric Vehicles
High-Performance Electric Sports Cars Market
Electric Vehicles
US Electric Mobility Market
Electric Vehicles
Peer-To-Peer Electric Vehicle Charging Market
Electric Vehicles
New Energy Vehicle (NEV) Taxi Market
Electric Vehicles
Europe Fuel Cell Electric Vehicle Market
Electric Vehicles
48V Mild Hybrid Battery Pack Systems Market
Electric Vehicles
Germany Electric Bus Battery Pack Market
Electric Vehicles
North America Electric Bus Market
Electric Vehicles
Battery Electric Vehicle (BEV) Market