
 Asia-Pacific Electric Bus Battery Pack Market | 2026-2036
Asia-Pacific Electric Bus Battery Pack Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Electric Bus Battery Pack Market Insights
China is reshaping regional supply dynamics through massive cell manufacturing expansion in Fujian and Jiangsu provinces. CATL leverages vertical integration into cathode material refining to sustain cost leadership across 300kWh and 400kWh pack configurations. BYD Company Ltd anchors domestic bus electrification through in-house production of lithium iron phosphate cells. Samsung SDI Co Ltd competes in South Korea's premium transit segment with high-nickel chemistry expertise.
An electric bus battery pack comprises interconnected lithium-ion cells housed in thermal-managed enclosures delivering 100kWh to 400kWh for propulsion and auxiliary loads. These systems integrate battery management systems, cooling circuits, and high-voltage junction boxes to ensure cycle life exceeding 3,000 charge events under depot and opportunity charging regimes. Lithium-ion chemistry dominates installed capacity due to mature supply chains and declining cell costs, while solid-state technology attracts R&D investment for future energy density gains. Public transit end users represent the primary demand pool as municipal operators replace diesel fleets with zero-emission alternatives. Fast charging infrastructure deployment is accelerating in Chinese megacities where 400kWh packs enable extended route coverage without midday depot returns.
China's MIIT enforces GB standards for cell safety and pack thermal runaway containment, while South Korea's KATS administers KC certification for battery system electromagnetic compatibility. Japan's METI coordinates national hydrogen and battery roadmaps that influence procurement criteria for next-generation electric bus platforms. India's CEA and BIS are developing localized testing protocols under the Faster Adoption and Manufacturing of Electric Vehicles scheme to reduce import dependency. Stakeholders must monitor how subsidy phase-out timelines in China interact with cell cost curves to determine margin sustainability across the value chain.
Market Dynamics
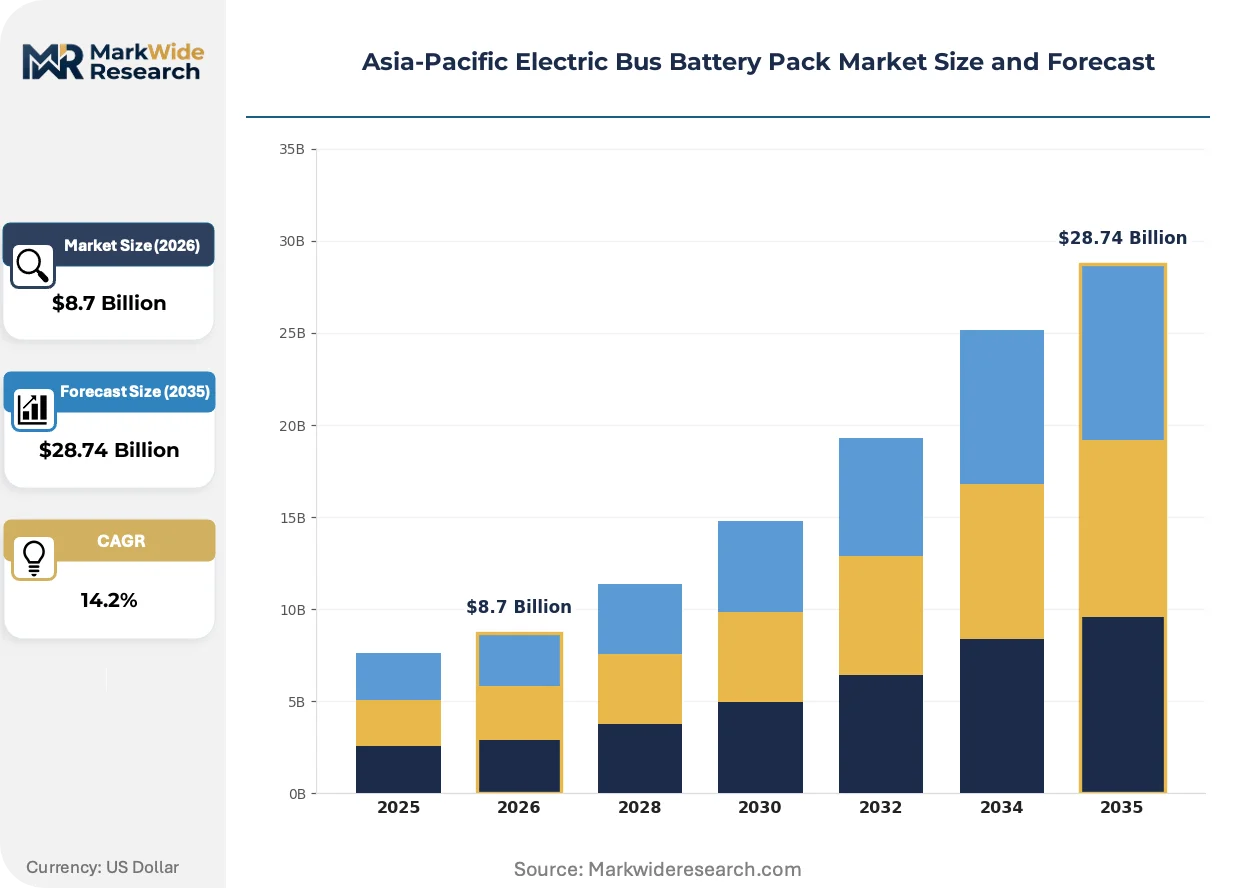
China's dual carbon goals are compressing procurement timelines for zero-emission transit fleets, forcing battery pack suppliers to scale thermal management and fast-charging compatibility faster than cell cost curves alone would dictate.
Growth Catalysts
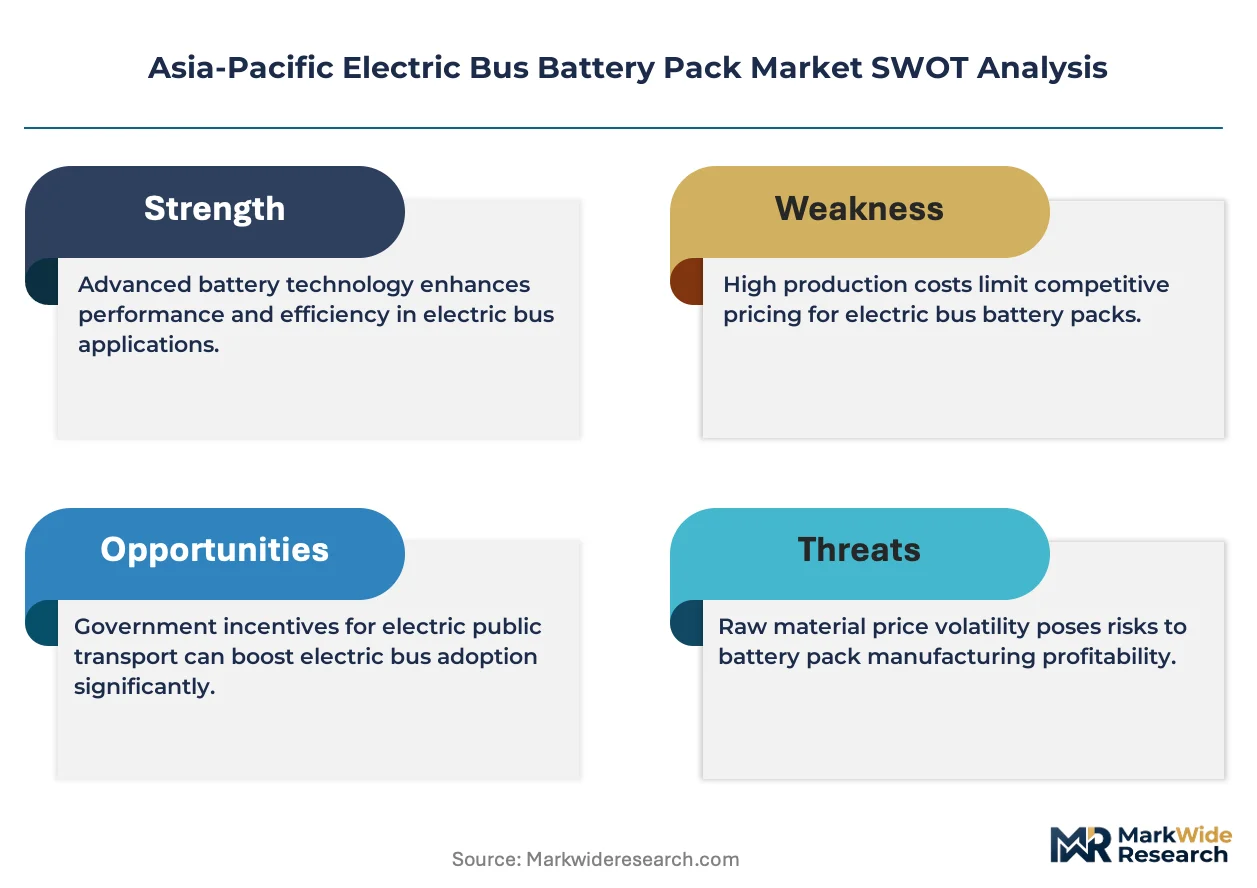
- MIIT GB Standards:China's mandatory cell safety and thermal runaway containment rules are eliminating subscale pack assemblers, concentrating orders among certified tier-one suppliers.
- Depot charging infrastructure:Municipal operators in Chinese megacities are expanding overnight charging facilities, anchoring demand for 300kWh and 400kWh configurations with extended cycle life.
- Fujian-Jiangsu cell clusters:Cathode material refining and cell finishing capacity is concentrating in these provinces, shortening lead times for integrated pack production.
Market Restraints
- Lithium carbonate volatility:Raw material input swings compress margin buffers for pack integrators lacking captive mining or refining positions.
- KATS KC certification:South Korea's electromagnetic compatibility testing creates friction for Chinese suppliers seeking premium transit segment entry.
- Solid-state substitution timeline:Laboratory-stage solid-state chemistry threatens long-term lithium-ion pack relevance, freezing some R&D capital allocation decisions.
Strategic Opportunities
- India's FAME scheme:Localized testing protocols under CEA and BIS jurisdiction are opening import-substitution pathways for domestic pack assembly.
- Opportunity charging corridors:Pantograph and inductive fast-charging installations along Japanese trunk routes enable smaller pack sizes with higher cycle frequency.
- Battery management system convergence:Integration of predictive analytics with thermal control circuits is creating service revenue layers beyond hardware shipment.
Industry Challenges
- High-voltage safety engineering:Scarce talent pools for 800V system architecture and arc containment are extending product development cycles.
- GB-to-KC-to-JIS multi-certification:Divergent national testing regimes force parallel validation tracks, inflating qualification costs for regional suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Electric Bus Battery Pack Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Nickel-Metal Hydride, Solid-State, Lead-Acid End User: Public Transit, Private Operators, Schools, Logistics Capacity: 100kWh, 200kWh, 300kWh, 400kWh Technology: Fast Charging, Wireless Charging, Regenerative Braking, Battery Management Systems |
| Companies Covered | Samsung SDI Co Ltd, EVE Energy Co Ltd, BYD Company Ltd, GS Yuasa International Ltd, Gotion High-Tech Co Ltd, Contemporary Amperex Technology Co Ltd (CATL), Panasonic Holdings Corporation, Ameperex Technology Limited (ATL), LG Energy Solution Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Electric Bus Battery Pack Market Trends and Innovations
Digital twin technology is virtualizing pack design validation, compressing prototype-to-production timelines while regulatory pressure on thermal safety intensifies across Northeast Asian transit authorities.
Cell-to-pack architectures are eliminating modular housings and busbar complexity, reducing mass and volume overhead by integrating cooling channels directly into cell arrays. Chinese OEMs are adopting these designs for 400kWh depot-charged configurations, trading service accessibility for energy density gains. This structural simplification is virtualizing traditional tiered supplier relationships, as cell manufacturers assume pack integration responsibilities previously held by independent system integrators.
METI's national battery roadmap is coordinating hydrogen fuel cell and solid-state lithium-ion development priorities, creating procurement criteria that favor dual-platform bus chassis designs. Japanese transit operators are responding with technology-neutral tender specifications, preserving optionality against chemistry uncertainty. This policy framing most directly affects premium intercity routes where range anxiety and charging downtime carry highest penalty costs.
Lifecycle service contracts are unbundling pack hardware from performance guarantees, with operators paying per-kilometer fees covering cell degradation and thermal management maintenance. Chinese municipal fleets are piloting these arrangements for 300kWh configurations, transferring residual value risk to suppliers. South Korean operators in Seoul and Busan are resisting this shift, preferring capital ownership with extended warranty coverage.
Asia-Pacific Electric Bus Battery Pack Market Segmentation
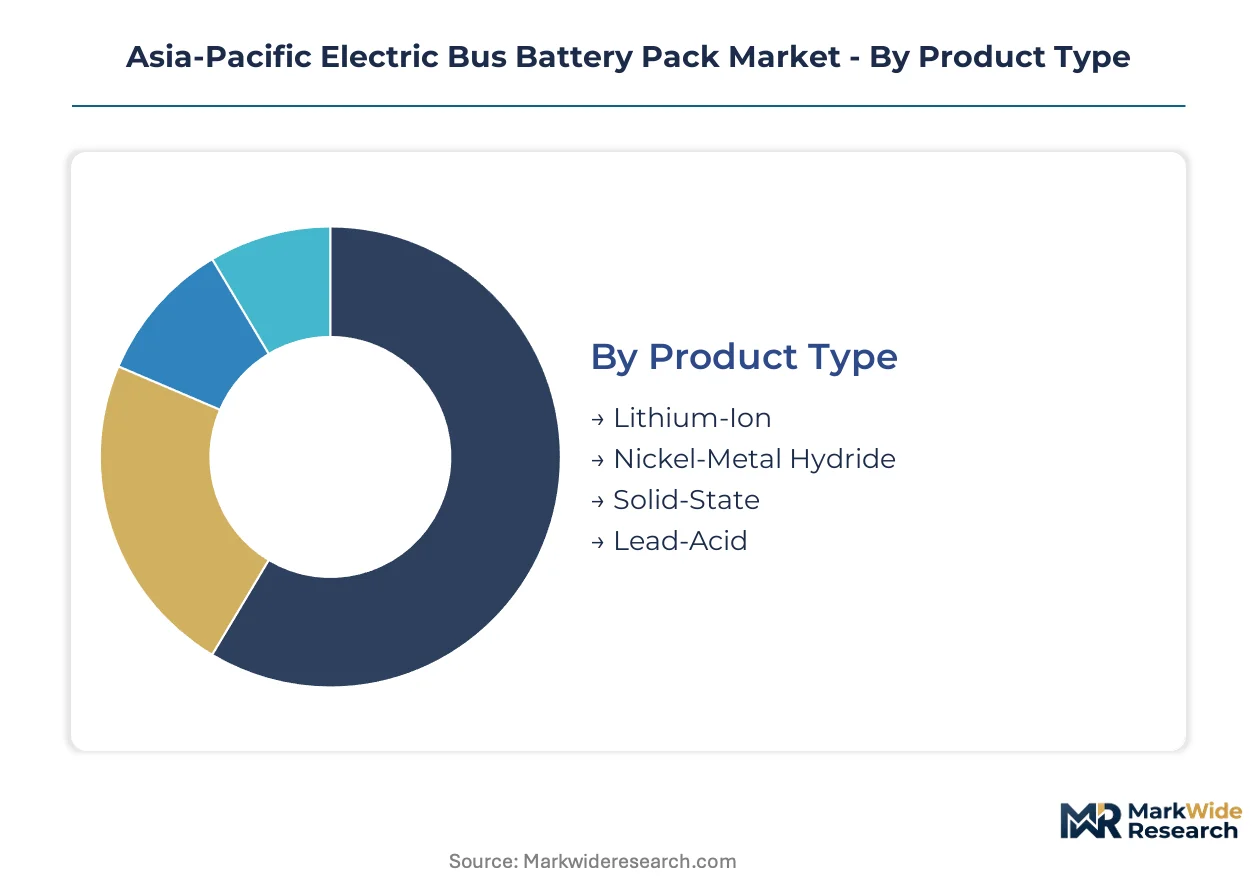
Segmentation in the Asia-Pacific electric bus battery pack market reveals how chemistry choices, fleet ownership models, and charging infrastructure interact to determine procurement specifications. Pack suppliers must align thermal management designs and cycle life guarantees with distinct operational regimes across municipal, commercial, and institutional buyers.
Product Type:
Cycle times vary sharply by chemistry maturity, with established lithium-ion formats turning inventory fastest while solid-state prototypes remain in extended qualification phases.
- Lithium-Ion:Dominant cell format utilizing nickel-manganese-cobalt or lithium iron phosphate cathodes housed in modular packs. Chinese megacity procurement under MIIT GB standards concentrates demand for 300kWh and 400kWh configurations with depot charging compatibility.
- Solid-State:Laboratory-stage cells with ceramic or polymer electrolytes promising energy density gains above 400 Wh/kg. Japanese METI roadmap coordination is channeling R&D investment toward intercity bus platforms where range extension carries premium value.
- Nickel-Metal Hydride:Mature chemistry retained in legacy hybrid conversions and cost-sensitive retrofits.
- Lead-Acid:Declining format limited to auxiliary power units in budget fleet segments.
Lithium-ion anchors the volume base while solid-state gains share at the steepest rate.
End User:
Cost tier stratification separates capital-rich municipal buyers from margin-constrained commercial operators.
- Public Transit:Municipal fleet operators deploying zero-emission buses under national dual carbon mandates. Chinese provincial governments in Fujian and Jiangsu are consolidating procurement through state-owned transport bureaus, demanding 15-year service life guarantees.
- Private Operators:Commercial bus companies and airport shuttle services with utilization-driven degradation profiles. South Korean premium transit segments under KATS KC certification requirements are prioritizing electromagnetic compatibility in high-voltage architectures.
- Schools:Institutional buyers with predictable route patterns and overnight charging windows.
- Logistics:Warehouse shuttle and depot feeder operators with high-frequency duty cycles.
Public transit commands the procurement volume while private operators are expanding most quickly as subsidy structures mature.
Capacity:
Application requirements dictate pack sizing, with route length and charging availability determining optimal energy storage.
- 400kWh:Extended-range configuration enabling single-shift operation without midday charging. Chinese megacities deploying opportunity charging corridors along trunk routes are specifying these packs for 18-meter articulated buses.
- 300kWh:Standard depot-charged format balancing capital cost against daily range requirements. Indian FAME scheme incentives are accelerating adoption in state transport undertakings across Maharashtra and Karnataka.
- 200kWh:Mid-size packs for feeder routes and smaller chassis formats.
- 100kWh:Compact configuration for shuttle services and last-mile connectivity.
300kWh configurations anchor current fleet deployment while 400kWh packs are climbing the fastest as fast-charging infrastructure spreads.
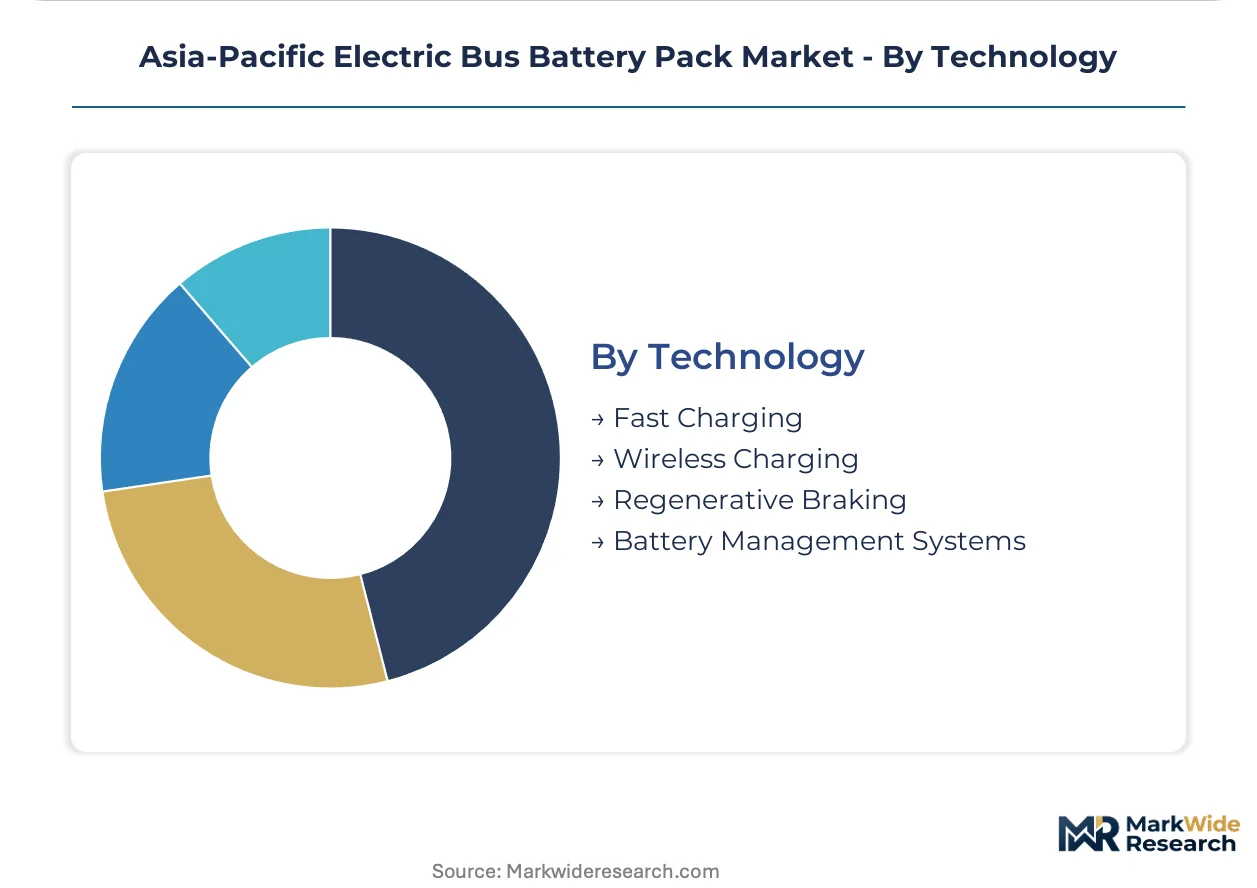
Technology:
Customer type influences technology prioritization, with public fleets emphasizing predictability and private operators seeking utilization maximization.
- Fast Charging:Pantograph and plug-in systems delivering 350kW+ power transfer for opportunity charging. Japanese transit authorities along Tokyo-Osaka corridor routes are standardizing roof-mounted pantograph interfaces.
- Battery Management Systems:Integrated control electronics monitoring cell balancing, thermal state, and state-of-charge estimation. South Korean suppliers are converging predictive analytics with active cooling circuits to create service revenue layers.
- Wireless Charging:Inductive power transfer for automated depot operations.
- Regenerative Braking:Kinetic energy recovery systems reducing net energy consumption in stop-start urban duty cycles.
Battery management systems anchor the technology stack while fast charging is gaining share at the steepest rate as infrastructure deployment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell finishing capacity clusters in Fujian and Jiangsu provinces are compressing lead times for integrated pack production across the region. MIIT GB standards are eliminating subscale assemblers and concentrating procurement among certified tier-one suppliers.
China
Provincial governments in Fujian and Jiangsu are consolidating procurement through state-owned transport bureaus demanding 15-year service life guarantees. MIIT enforces mandatory cell safety and thermal runaway containment rules under GB standards. The Yangtze River Delta and Pearl River Delta house cathode material refining operations that shorten lead times for 300kWh and 400kWh pack configurations.
South Korea
Seoul and Busan municipal operators are prioritizing electromagnetic compatibility in high-voltage architectures for premium transit segments. KATS administers KC certification requirements that create friction for foreign suppliers seeking market entry. The Seoul Capital Area concentrates battery management system integration expertise with predictive analytics capabilities.
Japan
Transit authorities along the Tokyo-Osaka corridor are standardizing roof-mounted pantograph interfaces for opportunity charging. METI coordinates national hydrogen and battery roadmaps that influence procurement criteria for next-generation platforms. Kansai region operators are deploying technology-neutral tender specifications that preserve optionality against chemistry uncertainty.
India
State transport undertakings across Maharashtra and Karnataka are accelerating adoption of 300kWh configurations under FAME scheme incentives. CEA and BIS are developing localized testing protocols to reduce import dependency. The Delhi-NCR cluster is emerging as a hub for domestic pack assembly operations targeting import substitution.
Australia
New South Wales and Victoria state governments are expanding zero-emission transit commitments with depot charging infrastructure investments. The national Clean Energy Finance Corporation is backing municipal fleet electrification programs. Sydney and Melbourne metropolitan operators are specifying extended-range configurations for interurban route coverage.
Asia-Pacific Electric Bus Battery Pack Market Competitive Landscape
Vertically integrated cell manufacturers and independent pack integrators split the market along chemistry control and thermal engineering lines. The structure concentrates orders among entities with captive cathode refining or certified system integration capabilities. Three archetypes dominate: conglomerate-affiliated battery divisions with upstream material control, independent specialists focusing on thermal management and battery management system software, and bus OEMs with in-house cell production. Capacity expansion in Fujian-Jiangsu corridors and strategic partnerships for fast-charging compatibility represent the dominant competitive moves.
Within the conglomerate-affiliated tier, Contemporary Amperex Technology Co Ltd and BYD Company Ltd exemplify upstream-integrated positions spanning cell chemistry through pack assembly. Samsung SDI Co Ltd anchors the premium-tier vector for South Korean metropolitan operators. These three entities occupy positions that reflect divergent strategic bets on LFP versus high-nickel chemistry dominance across 300kWh and 400kWh transit configurations.
| Leading Market Players |
|---|
| Samsung SDI Co Ltd |
| EVE Energy Co Ltd |
| BYD Company Ltd |
| GS Yuasa International Ltd |
| Gotion High-Tech Co Ltd |
| Contemporary Amperex Technology Co Ltd (CATL) |
| Panasonic Holdings Corporation |
| Ameperex Technology Limited (ATL) |
| LG Energy Solution Ltd |
| Others |
Pricing and Supply Chain Analysis
Fujian-Jiangsu cathode refining clusters concentrate upstream capacity, translating into asymmetric pricing power for cell manufacturers over independent pack integrators. MIIT GB certification requirements segment the market into certified tier-one suppliers commanding premium positioning and subscale assemblers facing margin compression.
Pricing Analysis
MIIT GB standards dictate the pricing tier structure by eliminating uncertified pack assemblers and concentrating procurement among qualified suppliers. Three-tier pricing structure across premium, standard, and economy levels separates KATS KC-certified systems for South Korean metropolitan fleets from standard depot-charged configurations and budget auxiliary units. Cost compression in standard-tier packs is intensifying because lithium carbonate volatility erodes margin buffers for non-integrated assemblers. Municipal transport bureaus in Chinese provinces exhibit lowest price sensitivity due to dual carbon procurement mandates, while private airport shuttle operators in Southeast Asia demonstrate highest sensitivity to upfront capital costs.
Supply Chain Analysis
Tariff exposure between China and South Korea dominates supply chain risk calculations for battery management system components and high-voltage junction boxes. Cell finishing capacity concentrates in China, South Korea, and Japan, with cathode material refining anchored in Fujian-Jiangsu corridors. Raw material supply draws from lithium carbonate processors, nickel sulfate refiners, and separator membrane producers concentrated in East Asian chemical clusters. Single-source vulnerability in ceramic-coated separator supply threatens production continuity for high-nickel chemistry packs. Distribution runs through state-owned transport bureau procurement channels in China and OEM-direct relationships in Japan and South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific electric bus battery pack procurement is shifting toward platform-economics logic as cell-to-pack architectures virtualize traditional tiered supplier relationships and METI's dual-platform roadmaps force interoperability investments.
For Market Incumbents: Harden thermal engineering capabilities against solid-state substitution threats by deepening in-house production of battery management system software and predictive analytics layers. Defend margin position through captive cathode refining in Fujian-Jiangsu corridors rather than spot-market sourcing. Accelerate KC certification investment to penetrate South Korean premium transit segments before Chinese competitors consolidate. For New Entrants and Emerging Players: India's state transport undertakings under FAME scheme localization mandates represent the most penetrable white-space target, with Maharashtra and Karnataka offering import-substitution pathways for domestic pack assembly. Australian metropolitan operators in Sydney and Melbourne present secondary opportunity for extended-range configurations backed by Clean Energy Finance Corporation capital. Partner with established cell manufacturers for cathode supply rather than attempting backward integration into refining. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because cell-to-pack architecture shifts are displacing independent system integrators and concentrating value in vertically integrated cell manufacturers or specialized thermal engineering boutiques. Target acquisition archetypes include battery management system software specialists with predictive maintenance platforms and certified pack assemblers holding KC or GB tier-one status. Watch for inflection when METI finalizes solid-state procurement criteria and Japanese operators shift tender specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Cell-to-Pack Architecture Adoption | Eliminates modular housings and compresses assembly margins for independent integrators. |
| GB-to-KC Multi-Certification Investment | Unlocks premium transit segments in Seoul and Busan for qualified Chinese suppliers. |
| Fujian-Jiangsu Capacity Expansion | Shortens lead times for 300kWh and 400kWh configurations serving Chinese megacity fleets. |
| Battery Management System Convergence | Creates recurring service revenue through predictive analytics integration with thermal control. |
| FAME Scheme Localization Partnership | Positions suppliers for Indian state transport procurement under CEA-BIS testing protocols. |
Research Methodology
Desk research of customs trade databases, MIIT regulatory filings, and METI roadmap documentation preceded structured interviews with battery pack engineering directors, municipal fleet procurement managers, thermal management specialists, and cathode material sourcing leads. Primary fieldwork captured operational specifications for 300kWh and 400kWh depot-charged configurations across Chinese provincial transport bureaus, South Korean KC certification consultants, and Indian FAME scheme implementation officers. Secondary validation drew from SEC filings of listed battery manufacturers, IHS Markit vehicle production data, and IEA clean transport deployment statistics. Bottom-up capacity and demand estimates were triangulated against top-down market sizing from national electrification targets.
Forecasts assume MIIT GB standards remain enforced across the projection horizon, lithium carbonate price volatility follows observed historical bands, and solid-state chemistry remains pre-commercial for transit applications. Segmentation modeling incorporated chemistry type, pack capacity tier, end-user ownership structure, and charging technology compatibility. CAGRs were derived from installed base growth trajectories and replacement cycle analysis rather than simple extrapolation. Key inputs included municipal fleet electrification timelines under dual carbon goals, fast-charging infrastructure deployment curves in Chinese megacities, and FAME scheme subsidy phase-out assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by solid-state technology developers or unexpected lithium supply disruptions would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Asia-Pacific Solar E-Bike Market
Electric Vehicles
France Automotive High Performance Electric Vehicles Market
Electric Vehicles
Asia Pacific Electric Scooter Market
Electric Vehicles
Global Industrial Electric Vehicle Market
Electric Vehicles
BEV Electric Drive Unit Market
Electric Vehicles
South America Electric Bus Battery Pack Market
Electric Vehicles
Vehicle Solar Panel Market
Electric Vehicles
Netherlands Solar E-Bike Market
Electric Vehicles
Mexico Electric Car Market
Electric Vehicles
France Electric Bus Battery Pack Market
Electric Vehicles
Busbar for EV Market
Electric Vehicles
New Energy Vehicle (NEV) Market
Electric Vehicles
Electric Vehicle NVH Material Market
Electric Vehicles
RV SLI Battery Market
Electric Vehicles
Automotive Battery Powered Propulsion System Market
Electric Vehicles
India E-Bike Market