
 Zinc Sulfate Market | 2026-2036
Zinc Sulfate Market Size, Share, and Industry Trends Forecast 2026-2036
Zinc Sulfate Market Intelligence
Agricultural fertilizer demand is hardening as the dominant pull factor for zinc sulfate consumption. Zinc Nacional S.A. leverages its integrated mining-to-chemical processing footprint across Latin America. Old Bridge Chemicals anchors North American supply through captive sulfuric acid integration and regional distribution density. Bohigh Group competes on crystallization technology leadership that yields pharmaceutical-grade heptahydrate with low heavy-metal residuals.
Zinc sulfate denotes a colorless crystalline salt with formula ZnSO₄, typically manufactured through the reaction of zinc oxide or zinc dust with sulfuric acid followed by crystallization, evaporation, and drying to specified hydration states. The compound functions primarily as a micronutrient carrier in agriculture, a dietary supplement precursor in animal nutrition, and a coagulant aid in water treatment chemistry. Monohydrate grades command margin concentration due to stability advantages in bulk fertilizer blending and lower freight moisture penalties. Heptahydrate crystals retain dominance in pharmaceutical and laboratory applications where solubility precision matters. Granular forms are gaining formulation share in mechanized broadcasting equipment across large-scale farming operations.
EPA regulates zinc sulfate as a pesticide inert ingredient and fertilizer constituent under FIFRA, while REACH mandates registration and hazard communication for imports into the European Union. China MIIT enforces GB standards on industrial-grade purity thresholds that directly shape export qualification criteria. India's FSSAI and CDSCO impose parallel constraints on food-grade and pharmaceutical applications, creating a multi-jurisdictional compliance burden. Stakeholders must monitor evolving micronutrient fortification mandates in national food security programs and fertilizer subsidy schemes that redirect volume allocation across end-use segments.
Market Dynamics
Soil amendment programs across Brazil, India, and China are tightening specification requirements for zinc sulfate purity, forcing crystallization technology upgrades and redirecting volume toward monohydrate grades optimized for bulk fertilizer blending.
Growth Catalysts
- Micronutrient fortification mandates:India's FSSAI and CDSCO are expanding zinc fortification requirements in national food security programs, pulling additional pharmaceutical-grade heptahydrate volume into dietary supplement applications.
- Mechanized broadcasting adoption:Large-scale farming operations across Brazil's Cerrado region are specifying granular zinc sulfate formulations compatible with precision agriculture equipment, creating specification premiums for specialized particle-size distributions.
- REACH registration completion:European ECHA compliance deadlines for zinc sulfate intermediates have locked in supplier qualification barriers that favor established registrants with existing dossier infrastructure.
Market Restraints
- Sulfuric acid cost volatility:Captive sulfuric acid integration determines regional cost competitiveness, with merchant acid exposure compressing margins for non-integrated processors during energy price spikes.
- Substitution by zinc oxide and zinc chelates:Organic zinc complexes in animal nutrition are displacing inorganic sulfate in premium feed formulations, particularly in EU and North American markets with stringent heavy-metal thresholds.
- China MIIT export qualification barriers:GB standard purity thresholds for industrial-grade material create batch rejection risks that concentrate exportable supply among certified producers with laboratory infrastructure.
Strategic Opportunities
- Water treatment coagulant expansion:Municipal utilities in secondary Indian cities are adopting zinc sulfate as an alternative coagulant aid where aluminum-based chemistry faces residual toxicity scrutiny.
- Pharmaceutical-grade heptahydrate white space:Low heavy-metal residual specifications for parenteral applications remain undersupplied relative to oral-grade capacity, creating margin concentration for crystallization technology leaders.
- Brazilian fertilizer subsidy alignment:Federal micronutrient inclusion mandates in subsidized NPK formulations are redirecting import flows toward Atlantic port infrastructure with blending terminal access.
Industry Challenges
- Crystallization process engineering talent scarcity:Pharmaceutical-grade heptahydrate production requires specialized expertise in controlled nucleation and heavy-metal precipitation that concentrates among aging technical workforces in traditional chemical processing regions.
- Multi-jurisdictional certification timelines:Simultaneous FSSAI, CDSCO, and EPA FIFRA registration processes for food-grade and pesticide-inert applications create 18-36 month commercialization delays that freeze formulation development budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zinc Sulfate Market |
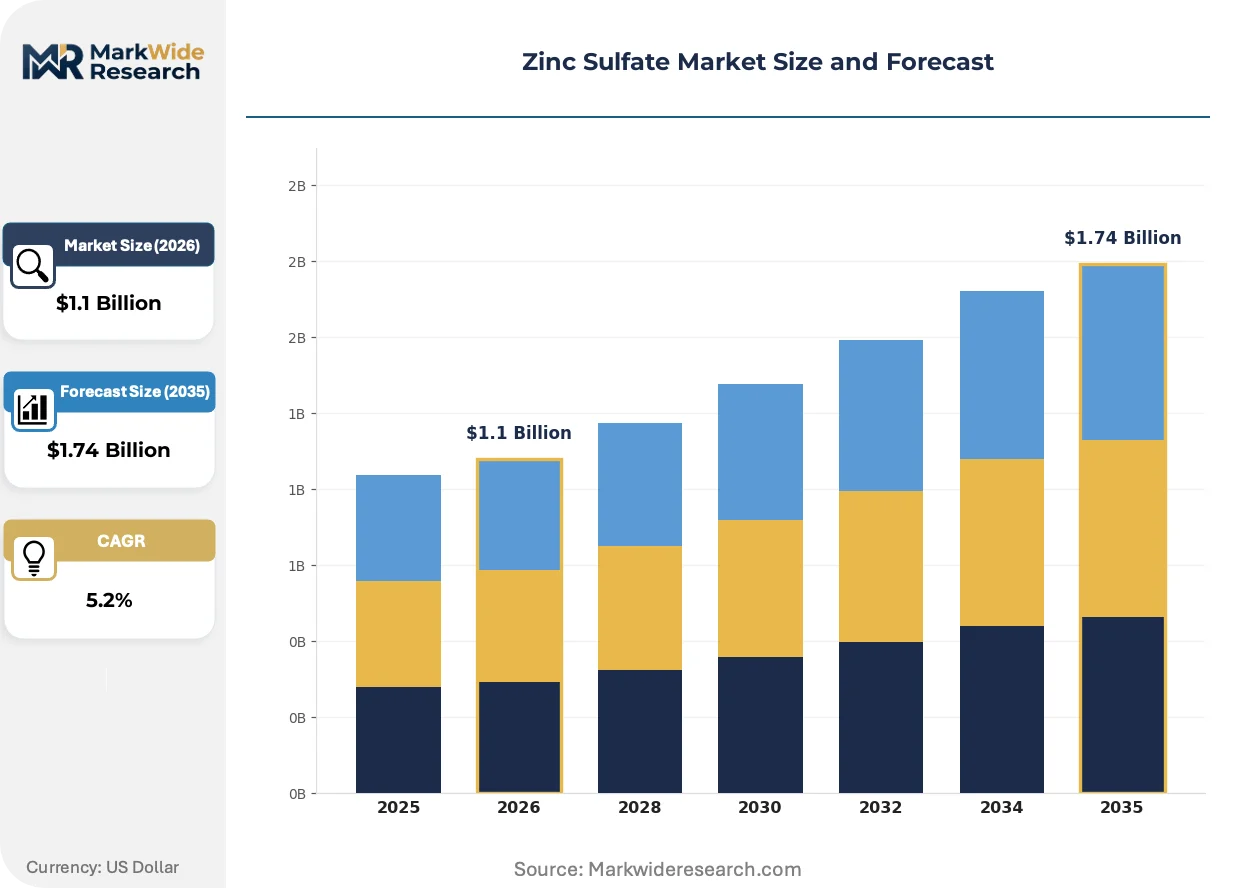
| Market Size in 2026 | $1.1 Billion |
| Market Size in 2035 | $1.74 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monohydrate, Heptahydrate, Anhydrous, Granular Application: Agricultural Fertilizers, Animal Feed, Pharmaceuticals, Water Treatment End User Industry: Crops Cultivation, Livestock Nutrition, Nutraceuticals, Municipal Water Facilities Form: Powder, Crystals, Solution, Pellets |
| Companies Covered | Zinc Nacional S.A., Old Bridge Chemicals, Bohigh Group, Balaji Industries, Changsha Haolin Chemicals Co. Ltd., Rech Chemical Co. Ltd., Sulfozyme Agro India Pvt. Ltd., Grillo Werke AG, Tianjin Xinxin Chemical Factory, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zinc Sulfate Market Strategic Shifts & Innovations
Process intensification and regulatory precision are compressing batch-cycle economics while fragmenting grade specifications across agricultural, pharmaceutical, and industrial end-uses.
Continuous crystallization systems with inline particle-size monitoring are modularizing production economics for mid-scale processors. Brazilian and Indian fertilizer blenders are adopting these units to bypass centralized refinery dependence. The technology is modularizing regional supply architectures by enabling distributed production nodes with freight-cost advantages over bulk import-reliant competitors.
REACH F-Gas Regulation and parallel EPA SNAP program restrictions on fluorinated greenhouse gases are tightening energy-efficiency requirements for crystallization drying stages. Process heat integration and mechanical vapor recompression are becoming qualification criteria for European pharmaceutical-grade supply contracts. Heptahydrate producers with legacy steam-drying infrastructure face retrofit capex burdens that favor greenfield investments with integrated heat recovery.
Specification-driven procurement is compressing supplier qualification cycles for zinc sulfate used in precision agriculture formulations. Brazilian cooperatives and Indian state procurement agencies are consolidating purchase volumes around certified producers with documented heavy-metal batch testing. This concentration is most visible in Mato Grosso soybean regions and Punjab wheat belts where soil zinc deficiency maps drive variable-rate application adoption.
Zinc Sulfate Market Segmentation
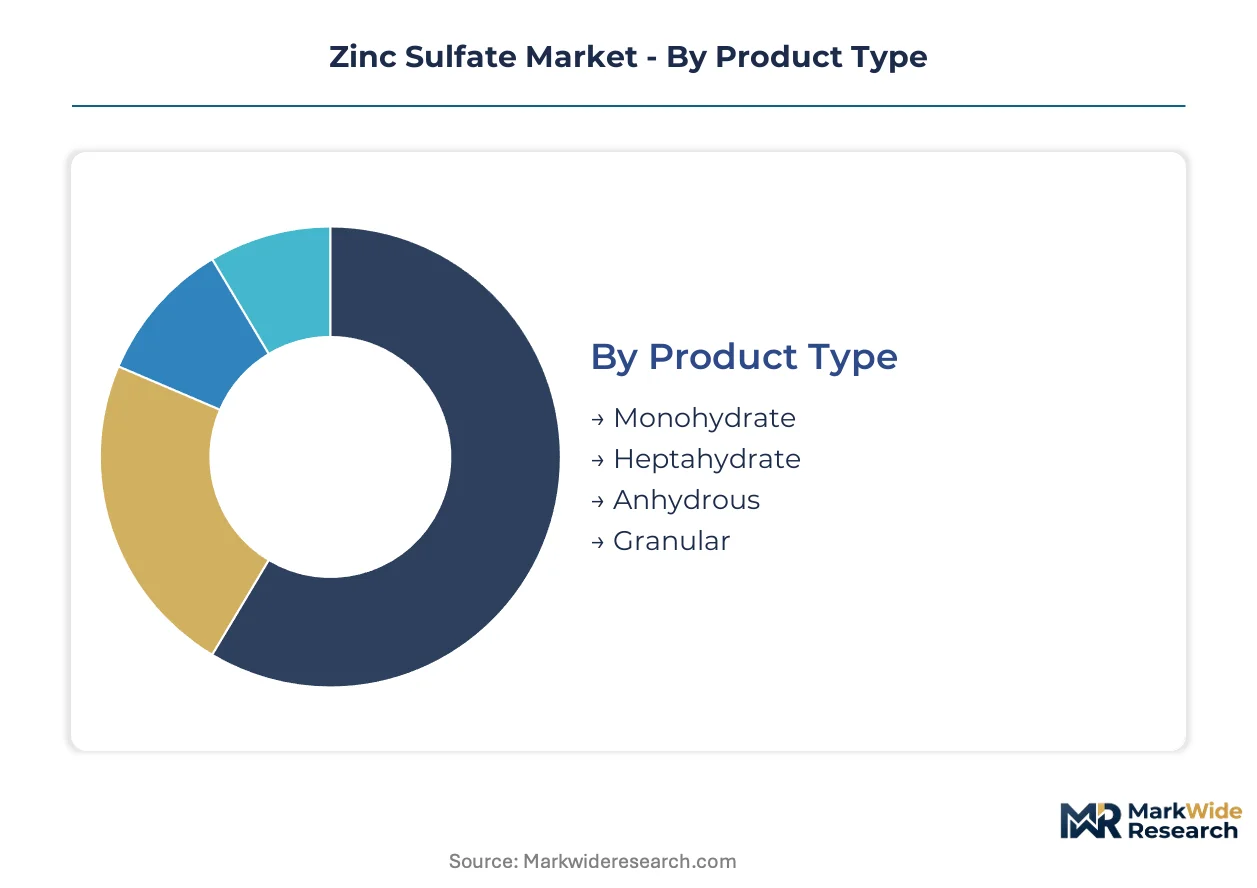
Zinc sulfate specifications fragment sharply across end-use requirements. Agricultural buyers prioritize moisture stability and freight economics. Pharmaceutical and nutraceutical procurement demands heavy-metal traceability and crystallization precision that command manufacturing premiums.
Product Type:
Volume concentration favors monohydrate grades with superior storage stability, while heptahydrate production captures margin through purity-intensive crystallization cycles.
- Monohydrate:The ZnSO₄·H₂O composition delivers 35-36% zinc content with minimal hygroscopic risk. Bulk fertilizer blenders across Brazil's Mato Grosso and India's Punjab specify monohydrate to avoid caking during monsoon-season storage and ocean freight. Mechanized broadcasting equipment compatibility reinforces specification lock-in.
- Heptahydrate:Pharmaceutical-grade ZnSO₄·7H₂O requires controlled nucleation to achieve parenteral-grade heavy-metal thresholds below 10 ppm lead. CDSCO and FSSAI registration dossiers for dietary supplement applications concentrate demand among crystallization technology leaders with inline particle monitoring. Solubility precision drives laboratory and clinical chemistry procurement.
- Anhydrous:Desiccant and specialty chemical applications in electronics manufacturing consume limited volumes through direct contracts with zinc smelter affiliates.
- Granular:Sized particle distributions for precision agriculture equipment are gaining formulation share in Brazilian Cerrado cooperatives with variable-rate application infrastructure.
Mature deployment sits with monohydrate grades in bulk fertilizer channels. Newer deployment is concentrated in pharmaceutical-grade heptahydrate with parenteral specifications.
Application:
Cost tier stratification separates commodity agricultural consumption from certified pharmaceutical and nutraceutical procurement with 18-36 month registration timelines.
- Agricultural Fertilizers:Micronutrient deficiency maps across China's North China Plain, India's Indo-Gangetic belt, and Brazil's Cerrado drive soil amendment program procurement. Federal subsidy schemes in Brazil and state-level procurement in India consolidate volume around certified producers with documented batch testing.
- Animal Feed:Organic zinc complexes are displacing inorganic sulfate in EU and North American premium formulations, though cost-sensitive poultry and swine operations in Southeast Asia sustain sulfate demand.
- Pharmaceuticals:Parenteral-grade specifications for intravenous formulations remain undersupplied relative to oral-grade capacity, creating margin concentration for producers with heavy-metal precipitation expertise.
- Water Treatment:Municipal utilities in secondary Indian cities are adopting zinc sulfate as alternative coagulant aid where aluminum residual toxicity faces regulatory scrutiny.
Steepest expansion trajectory is visible in water treatment coagulant applications. Agricultural fertilizer consumption maintains volume dominance.
End User Industry:
Customer type fragmentation separates state procurement agencies, private fertilizer cooperatives, pharmaceutical manufacturers, and municipal utility operators with divergent certification requirements.
- Crops Cultivation:Soybean, wheat, and maize operations with soil zinc deficiency diagnoses drive variable-rate application adoption. Brazilian cooperatives in Mato Grosso and Goiás consolidate purchase volumes around Atlantic port blending terminals.
- Livestock Nutrition:Integrated poultry and swine operations in Vietnam, Indonesia, and Thailand specify feed-grade sulfate for cost-optimized premix formulations.
- Nutraceuticals:Dietary supplement manufacturers in India and China face FSSAI and CDSCO zinc fortification mandates expanding pharmaceutical-grade heptahydrate pull-through.
- Municipal Water Facilities:Secondary city utilities in India's Uttar Pradesh and Maharashtra states are piloting zinc sulfate coagulation as aluminum alternative.
Procurement maturity concentrates in crops cultivation with decade-long subsidy program relationships. Municipal water facility adoption represents emerging demand formation.
Form:
Supply concentration in crystalline heptahydrate contrasts with distributed powder processing for agricultural blending and emerging pellet formulations for mechanized application.
- Powder:Fine-ground monohydrate serves bulk fertilizer blenders with immediate dissolution requirements in NPK formulation.
- Crystals:Heptahydrate crystallization from controlled evaporation yields pharmaceutical-grade material with documented nucleation parameters for regulatory dossiers.
- Solution:Liquid zinc sulfate eliminates dust handling in automated fertigation systems across Israeli and Spanish greenhouse operations.
- Pellets:Sized cylindrical forms are gaining share in Brazilian precision agriculture equipment with pneumatic broadcasting specifications.
Established supply sits with crystalline heptahydrate for pharmaceutical certification. Pellet form production is scaling fastest for mechanized agricultural deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate zinc sulfate refining capacity near sulfuric acid pipeline networks and zinc smelter complexes. Tax incentives for chemical process intensification anchor production gravity in Jiangsu and Zhejiang provinces.
China
MIIT-enforced GB standards on industrial-grade purity thresholds reshape export qualification criteria for zinc sulfate processors. Dual carbon goals accelerate mechanical vapor recompression retrofits in crystallization drying stages. Jiangsu province chemical clusters near Nanjing deploy continuous crystallization systems with inline particle monitoring.
Brazil
Federal micronutrient inclusion mandates in subsidized NPK formulations redirect import flows toward Atlantic port infrastructure. ANVISA registration requirements for pharmaceutical-grade material create compliance barriers for non-certified exporters. Mato Grosso soybean cooperatives consolidate purchase volumes around blending terminals in Santos port corridor.
India
FSSAI and CDSCO zinc fortification mandates in national food security programs expand pharmaceutical-grade heptahydrate demand. State-level procurement agencies in Punjab and Haryana specify documented heavy-metal batch testing for agricultural monohydrate. Secondary municipal utilities in Uttar Pradesh pilot zinc sulfate coagulation as aluminum alternative.
United States
EPA FIFRA registration for pesticide inert ingredient applications imposes 18-36 month commercialization timelines on new entrants. Captive sulfuric acid integration determines regional cost competitiveness for fertilizer-grade production. Gulf Coast chemical processors leverage merchant acid exposure during energy price volatility.
Germany
REACH F-Gas Regulation tightens energy-efficiency requirements for crystallization drying stages in pharmaceutical-grade supply contracts. ECHA compliance deadlines for zinc sulfate intermediates lock in supplier qualification barriers. Baden-Württemberg chemical engineering clusters concentrate process heat integration expertise for heptahydrate production.
Zinc Sulfate Market Key Industry Players
Top-tier vendors anchor crystallization technology leadership, while mid-scale regional processors compete on freight-cost positioning and subsidy program alignment. The supplier base fragments across mining-integrated Latin American operators, North American sulfuric acid-captive refiners, and Chinese crystallization specialists. Three archetypes dominate: integrated mining-to-chemical processors, captive acid fertilizer blenders, and pharmaceutical-grade crystallization technology leaders. Capacity expansion in Brazilian Atlantic port infrastructure and technology licensing for continuous crystallization systems represent the dominant competitive moves.
Within the pharmaceutical-grade tier, Bohigh Group and Old Bridge Chemicals exemplify divergent strategic positions. Bohigh Group occupies a position as a crystallization technology specialist with documented low heavy-metal residual capabilities. Old Bridge Chemicals represents North American supply anchoring through regional distribution density and captive sulfuric acid integration. Zinc Nacional S.A. sits within the mining-integrated archetype, leveraging upstream zinc smelter control across Latin American markets.
| Leading Market Players |
|---|
| Zinc Nacional S.A. |
| Old Bridge Chemicals |
| Bohigh Group |
| Balaji Industries |
| Changsha Haolin Chemicals Co. Ltd. |
| Rech Chemical Co. Ltd. |
| Sulfozyme Agro India Pvt. Ltd. |
| Grillo Werke AG |
| Tianjin Xinxin Chemical Factory |
| Others |
Cost & Logistics Intelligence
Continuous crystallization systems with inline particle monitoring are compressing batch-cycle economics while fragmenting grade specifications across end-use segments. This technology transition simultaneously reduces unit production costs for mid-scale processors and concentrates supply qualification barriers among crystallization technology leaders with pharmaceutical-grade certification infrastructure.
Pricing Analysis
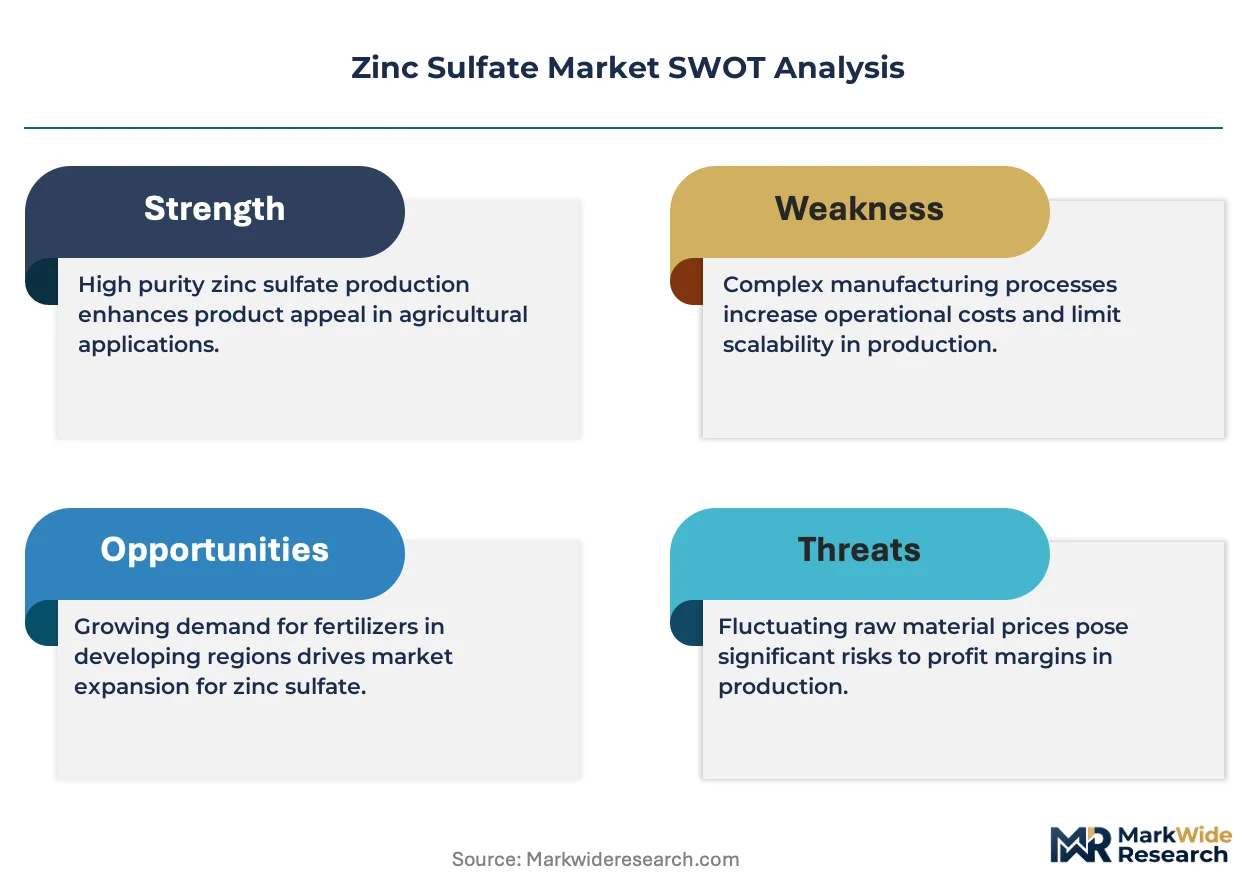
Short lead-time premiums for pharmaceutical-grade heptahydrate command substantial markups over contract-based agricultural monohydrate procurement. Three-tier pricing structure across parenteral-grade, oral-grade, and feed-grade certification levels reflects heavy-metal traceability investments and registration dossier costs. Cost compression in agricultural monohydrate runs through sulfuric acid merchant exposure during energy price volatility. State procurement agencies in India and Brazil exhibit highest price sensitivity, while parenteral-grade pharmaceutical buyers prioritize batch consistency over unit cost.
Supply Chain Analysis
Direct-to-fertilizer-blender channels handle bulk agricultural demand across Brazil's Mato Grosso cooperatives and India's Punjab procurement agencies. Production gravity centers on China's Jiangsu and Zhejiang chemical clusters, Brazil's Atlantic port corridor, and India's Gujarat industrial belt. Raw material dependencies draw from zinc smelter output, captive or merchant sulfuric acid, and crystallization energy inputs. Single-source vulnerability concentrates in pharmaceutical-grade heptahydrate where heavy-metal precipitation expertise concentrates among aging technical workforces. Distribution runs through Atlantic port blending terminals for Brazilian subsidy-aligned volumes and state procurement depots for Indian agricultural programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechanical vapor recompression retrofits in crystallization drying stages are displacing legacy steam-drying infrastructure, creating capital allocation inflection points across producer tiers.
For Market Incumbents: Anticipate displacement pressure from organic zinc chelates in EU and North American animal nutrition by securing backward integration into zinc smelter feedstock and expanding parenteral-grade heptahydrate capacity. Prioritize certification investment for CDSCO and FSSAI registration dossiers to capture Indian dietary supplement fortification mandates. Channel control through Atlantic port blending terminal partnerships defends position against freight-cost-optimized regional entrants. For New Entrants and Emerging Players: The price-point gap between pharmaceutical-grade heptahydrate and feed-grade monohydrate creates entry space for oral-grade crystallization specialists with moderate heavy-metal control capabilities. Target water treatment coagulant applications in secondary Indian cities where aluminum residual toxicity scrutiny drives specification transitions. Go-to-market leverage rests on municipal utility pilot program partnerships with documented efficacy data against aluminum-based alternatives. For Investors and Strategic Acquirers: Exit pathways concentrate in crystallization technology specialists with documented low heavy-metal residual capabilities and established regulatory dossier infrastructure. Long-term viability favors producers with integrated heat recovery systems and REACH F-Gas Regulation compliance positioning. Watch for inflection in Brazilian federal micronutrient inclusion mandate enforcement as subsidy program volume allocation signal.| Strategic Initiative | Industry Significance |
|---|---|
| Mechanical Vapor Recompression Retrofit | REACH F-Gas Regulation compliance locks in European pharmaceutical-grade supply contract eligibility. |
| Atlantic Port Blending Terminal Partnership | Brazilian federal subsidy alignment redirects import flows toward Santos corridor infrastructure. |
| CDSCO/FSSAI Registration Dossier Investment | Indian zinc fortification mandates in national food security programs expand addressable market. |
| Continuous Crystallization System Licensing | Modular production economics enable distributed regional nodes with freight-cost advantages. |
| Captive Sulfuric Acid Integration | Merchant acid exposure compression during energy price spikes determines margin resilience. |
Research Approach
Trade databases, chemical industry association reports, and regulatory filing repositories formed the secondary backbone for supply-side capacity and trade flow estimation. Primary interviews with zinc sulfate plant managers, procurement leads at fertilizer blenders, pharmaceutical formulation scientists, and municipal water treatment engineers validated production cost structures and specification requirements. Bottom-up triangulation against top-down demand modeling from micronutrient deficiency maps and fortification mandate scopes anchored volume estimates.
Bottom-up modeling segmented demand across monohydrate, heptahydrate, anhydrous, and granular grades, then cross-referenced against agricultural, pharmaceutical, animal feed, and water treatment end-use intensities. Top-down validation applied macroeconomic drivers from fertilizer subsidy program budgets and dietary supplement market expansion. CAGRs were derived from regression analysis of historical trade volumes against explanatory variables including sulfuric acid pricing, regulatory registration timelines, and mechanized broadcasting equipment adoption curves across the projection horizon.
Inputs from customs records and producer capacity disclosures were available through the study window; gaps in real-time inventory positioning at Brazilian cooperatives introduce uncertainty bands around quarterly volume allocation estimates. Forecasts reflect assumptions on subsidy program continuity, REACH registration enforcement intensity, and crystallization technology diffusion rates. Periodic stress-testing of base assumptions against sulfuric acid price volatility and organic zinc complex substitution trajectories is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Rare Earth Elements Recycling Market
Metals & Minerals
Lithium Ingots Market
Metals & Minerals
Nickel Nano Powder Market
Metals & Minerals
Global Magnesium Market
Metals & Minerals
Bauxite Mining Market
Metals & Minerals
Global Fabricated Metal Products Market
Metals & Minerals
North America and EMEA Ferrosilicon Market
Metals & Minerals
Testing Inspection and Certification TIC for the Metals and Minerals Market
Metals & Minerals
Dolomite Market
Metals & Minerals
US Coated Steel Market
Metals & Minerals
Boron Ore Market
Metals & Minerals
Global Antimony Market
Metals & Minerals
Cobalt Nitrate Market
Metals & Minerals
Recycled Copper Market
Metals & Minerals
Middle-East and Africa Lithium Market
Metals & Minerals
Middle-East and Africa Sodium Sulfide Market